
 Middle East and Africa Ready to Drink Beverages Market | 2026-2036
Middle East and Africa Ready to Drink Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Ready to Drink Beverages Market Foresight
Asset-light franchising and third-party co-manufacturing arrangements is reconfiguring competitive entry barriers across the Middle East and Africa Ready to Drink Beverages landscape. Danone SA leverages its dairy-based beverage expertise to anchor premium positioning in North African markets. PepsiCo competes through extensive cold-chain partnerships that sustain distribution reach into smaller urban centers. Almarai controls vertically integrated dairy supply networks that differentiate its juice and flavored milk portfolios in Gulf markets.
Ready to drink beverages comprise commercially prepared, shelf-stable or refrigerated drinks packaged in cans, bottles, or cartons for immediate consumption without further preparation, typically preserved through pasteurization, aseptic filling, or carbonation to achieve ambient or chilled stability. These products serve retail and foodservice channels seeking convenience, portion control, and consistent flavor profiles for on-the-go consumption. Sodas and iced tea categories occupy mature volume positions with established margin structures, while coffee and functional juice segments attract faster growth from health-conscious adult consumers. Distribution through supermarkets and e-commerce channels concentrates in metropolitan zones, though vending machines and convenience stores extend penetration into transit hubs and workplace locations where immediate purchase occasions dominate.
Saudi Arabia's SFDA enforces nutritional labeling and ingredient disclosure standards that elevate compliance costs for imported formulations, while Egypt's EOS and South Africa's NRCS administer local quality certifications affecting market access timelines. The EU Green Deal's extraterritorial packaging sustainability requirements increasingly shape supplier specifications for brands exporting into European-adjacent North African trade zones. Stakeholders must monitor evolving sugar taxation proposals across Gulf Cooperation Council jurisdictions and assess co-packer capacity constraints in Ethiopia and Kenya as regional manufacturing hubs mature.
Market Dynamics
Sugar-reduction mandates from Saudi Arabia's SFDA are compressing formulation cycles across Gulf Cooperation Council markets, forcing manufacturers to rebuild taste profiles around alternative sweeteners while maintaining shelf stability in harsh desert climates.
Growth Catalysts
- Functional beverage demand:Young adult consumers in urban Nigeria and South Africa are pulling protein-fortified RTD coffee and energy drinks into daily consumption routines, expanding the addressable base beyond traditional soda drinkers.
- SFDA labeling standards:Saudi Arabia's nutritional disclosure requirements are harmonizing ingredient transparency across Gulf markets, reducing regulatory fragmentation that previously delayed multi-country launches.
- Cold-chain partnerships:PepsiCo's refrigerated distribution networks are penetrating smaller urban centers in Egypt and Morocco, extending chilled RTD availability beyond Cairo-Alexandria and Casablanca corridors.
Market Restraints
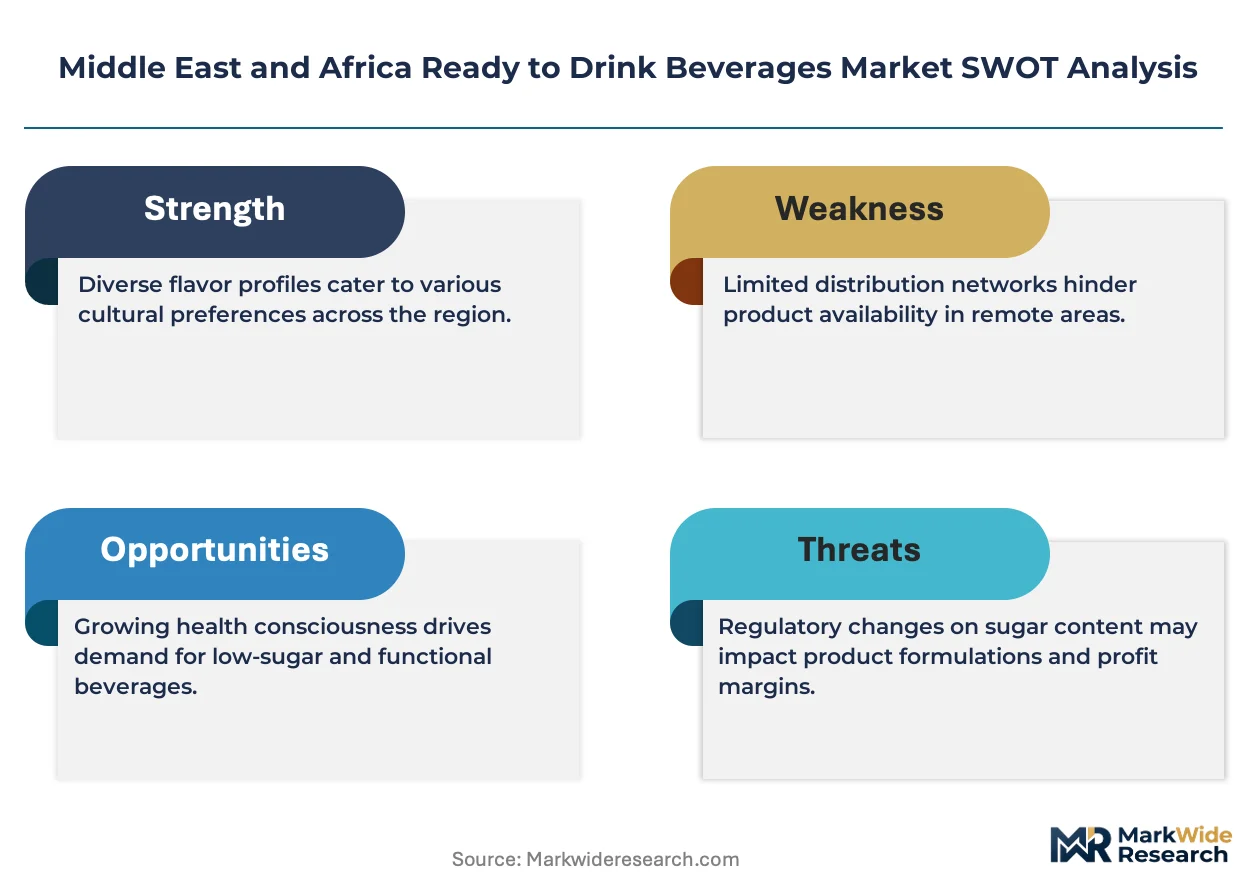
- Aluminum can supply concentration:Primary metal sourcing clusters in the Gulf states create input cost volatility for can-dependent RTD categories when regional smelter output fluctuates.
- Aseptic filling equipment scarcity:Limited installed base of high-speed aseptic lines in Ethiopia and Kenya constrains local manufacturing scale-up for shelf-stable dairy and juice formulations.
- Sugar taxation proposals:Draft excise frameworks under review in UAE and Bahrain threaten margin compression for full-sugar carbonated and juice portfolios already facing reformulation costs.
Strategic Opportunities
- Kenyan manufacturing hub maturation:Co-packer capacity expansion in Nairobi and Mombasa offers regional production bases serving East African Community markets with reduced import duty exposure.
- EU Green Deal packaging alignment:North African exporters to European-adjacent trade zones can capture premium positioning by certifying recyclable or biodegradable packaging formats ahead of mandatory compliance dates.
- Vending machine channel penetration:Workplace and transit hub installations in Johannesburg, Lagos, and Dubai Metro systems capture immediate-consumption occasions outside traditional retail hours.
Industry Challenges
- Food technologist scarcity:Formulation expertise for sugar-reduced taste engineering and natural preservative systems remains concentrated in South Africa and Egypt, creating recruitment bottlenecks for Gulf-based innovation centers.
- Multi-jurisdiction certification timelines:Parallel approvals required from Saudi SFDA, Egypt EOS, and South Africa NRCS extend product launch windows by 8-14 months for regional portfolio rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Ready to Drink Beverages Market |
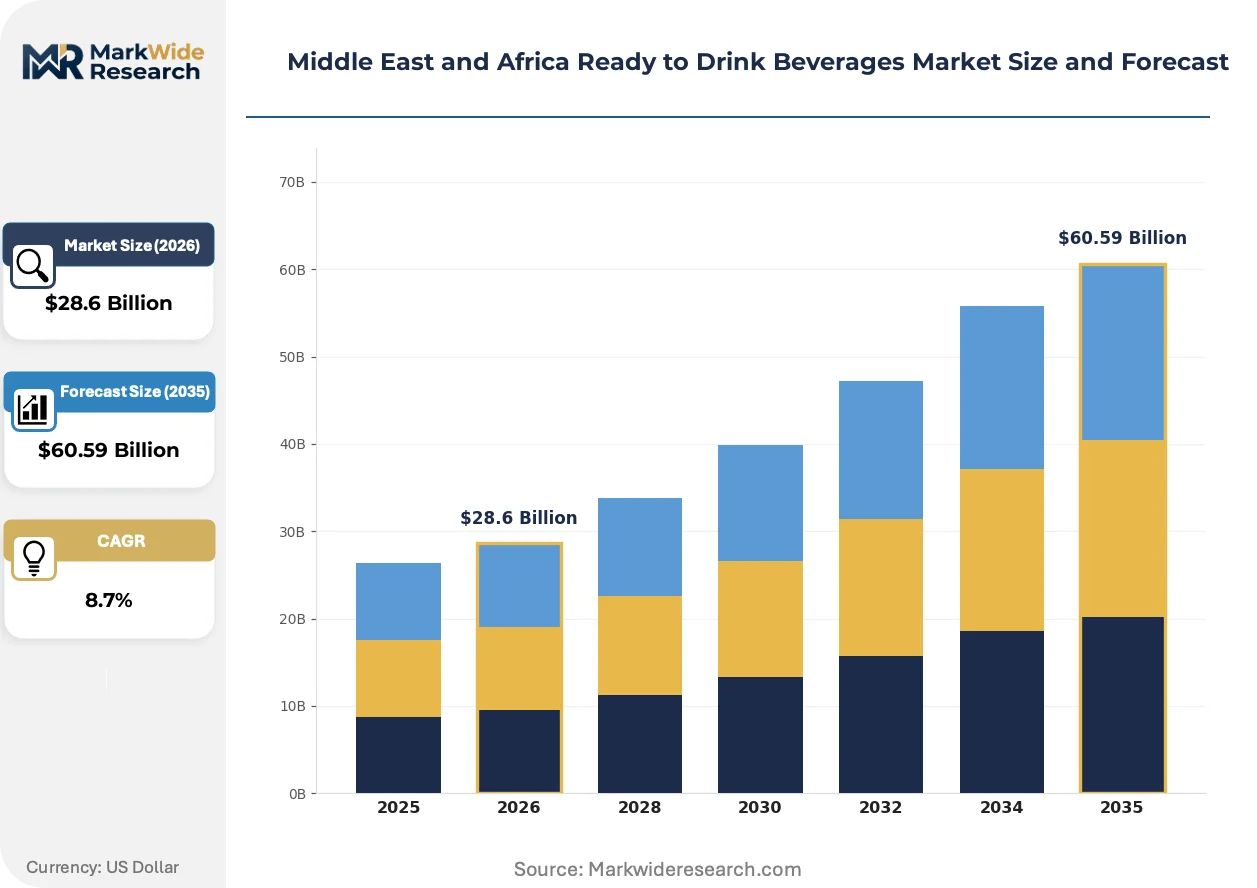
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodas, Juices, Iced Tea, Coffee Consumer Segment: Adults, Teens, Children, Seniors Distribution Channel: Supermarkets, Convenience Stores, E-commerce, Vending Machines Flavor Profile: Citrus, Berry, Tropical, Herbal |
| Companies Covered | Danone SA, Red Bull GmbH, Nestle SA, Alokozay Group, Monster Energy, PepsiCo, Almarai, Glanbia PLC, The Coca-Cola Company, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Ready to Drink Beverages Market Shifts & Advancements
Digital traceability systems and reformulation science are converging to reshape how RTD beverages demonstrate provenance and health credentials to skeptical Middle Eastern and African consumers.
Aseptic carton packaging integrated with blockchain serialization is digitizing supply chain transparency for dairy and juice products. Almarai and regional dairy leaders are adopting these systems to verify cold-chain integrity from processing plant to retail shelf. This technology is digitizing consumer trust mechanisms, compressing the advantage window for brands lacking verifiable freshness credentials.
Saudi Arabia's SFDA sugar-reduction mandates are cascading into formulation standards across Gulf Cooperation Council jurisdictions. Manufacturers now face compressed timelines to rebuild taste profiles using stevia, monk fruit, and fiber-based bulking agents while maintaining microbial stability. RTD coffee and flavored milk segments are most affected, with brands accelerating pilot programs in Riyadh and Jeddah to secure early compliance positioning.
Subscription-based replenishment models are displacing traditional supermarket stock-up behavior among affluent households in Dubai, Cape Town, and Nairobi. Direct-to-consumer platforms and app-integrated delivery services are capturing recurring revenue from health-conscious buyers seeking personalized functional beverage assortments. This shift is most visible in the UAE, where cold-chain logistics maturity enables same-day delivery of refrigerated protein coffees and kombucha variants previously confined to specialty retail.
Middle East and Africa Ready to Drink Beverages Market Segmentation
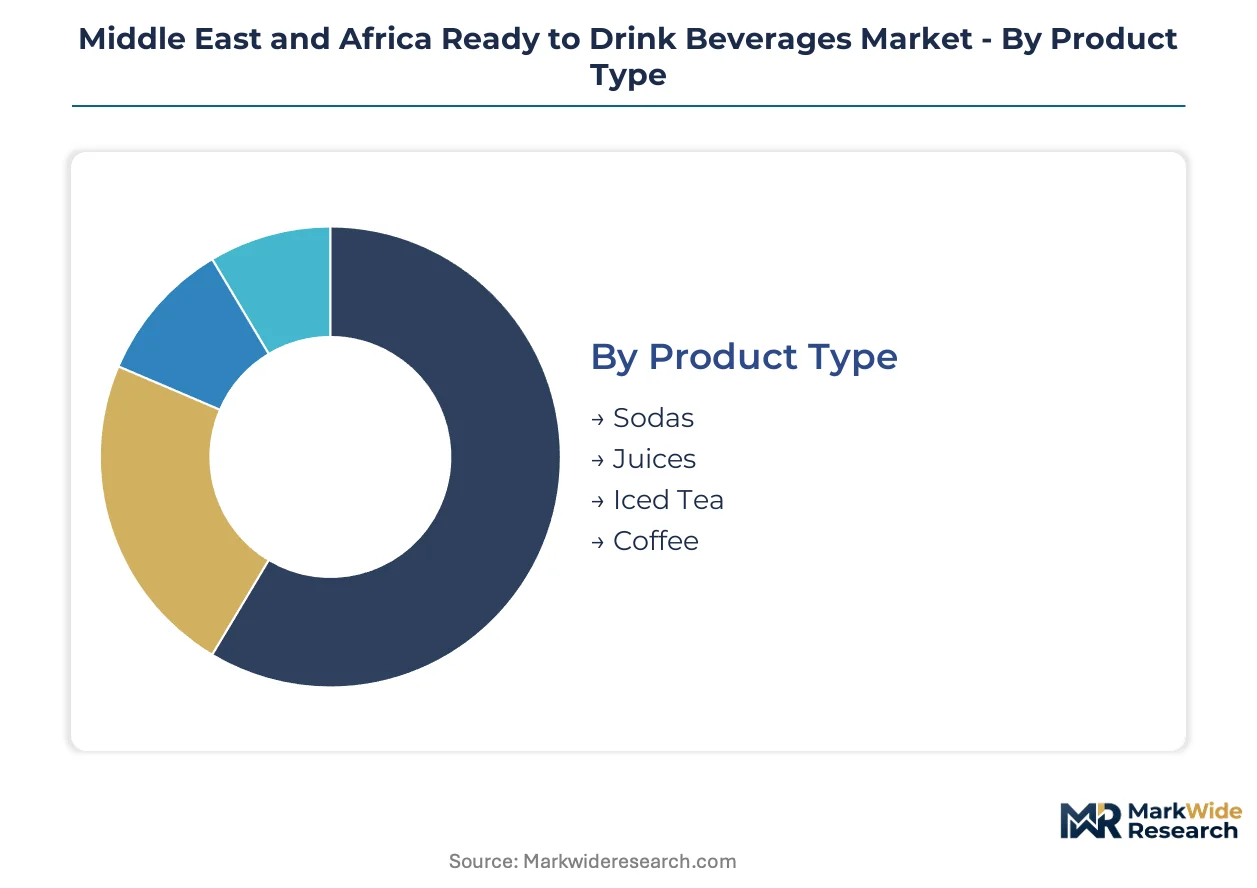
Segmentation in the Middle East and Africa RTD beverages market reveals distinct service intensity patterns across product lifecycles. Refrigerated categories demand cold-chain maintenance and frequent replenishment, while ambient-stable formats prioritize shelf-life monitoring and retail execution.
Product Type:
After-sales service intensity varies sharply across product categories, with dairy-based and refrigerated beverages requiring temperature-controlled logistics and shorter rotation cycles than shelf-stable alternatives.
- Sodas:Carbonated formulations in aluminum and PET formats dominate volume through established fountain and retail networks. Egyptian and Nigerian bottlers concentrate production in Cairo-Alexandria and Lagos corridors where sugar-tax debates are forcing rapid reformulation. Ambient distribution minimizes cold-chain service costs but intensifies price competition.
- Juices:Aseptic and chilled variants span premium NFC segments to value-added concentrates. Almarai's Gulf dairy networks anchor premium juice distribution, while Ethiopian and Kenyan co-packers struggle with aseptic line scarcity for shelf-stable expansion. Fruit sourcing transparency is becoming a service differentiator.
- Iced Tea:RTD tea blends occupy mature positions in South African and Moroccan retail, with formulation stability requiring less technical support than dairy alternatives.
- Coffee:Protein-fortified and cold-brew variants attract the highest service intensity through refrigerated last-mile delivery and subscription replenishment models in Dubai and Cape Town.
Sodas holds the largest share; momentum sits with Coffee.
Consumer Segment:
Pricing stratification across consumer tiers reflects divergent channel access and functional benefit expectations rather than pure income segmentation.
- Adults:Functional benefit seekers drive protein coffee, energy drink, and low-sugar juice adoption. Urban Nigerian and South African professionals pull premium RTD into daily routines, while Saudi SFDA sugar mandates reshape adult-oriented formulation standards across Gulf markets.
- Teens:Flavor novelty and social consumption occasions dominate, with convenience store and vending penetration highest in Johannesburg, Lagos, and Dubai Metro transit systems.
- Children:School-channel restrictions and parental sugar concerns compress this segment in regulated Gulf markets, though North African volume remains substantial.
- Seniors:Fortified dairy and digestive health formulations attract emerging attention from Egyptian and Moroccan dairy processors seeking portfolio extension.
Adults commands current value; Teens is climbing the fastest.
Distribution Channel:
Channel selection determines working capital intensity and margin structure, with direct-to-consumer platforms capturing recurring revenue at the cost of logistics complexity.
- Supermarkets:Modern retail concentration in Cairo-Alexandria, Casablanca, and Johannesburg corridors sustains volume for planned purchase occasions. PepsiCo's cold-chain partnerships extend chilled RTD penetration into secondary urban centers beyond flagship metros.
- Convenience Stores:Extended hours and transit-adjacent locations capture immediate consumption with higher per-unit margins but fragmented inventory management.
- E-commerce:Subscription models displace stock-up behavior in affluent Dubai, Cape Town, and Nairobi households. Same-day cold-chain delivery capability separates premium functional beverage contenders from commodity players.
- Vending Machines:Workplace and transit installations in Johannesburg, Lagos, and Dubai Metro extend purchase occasions outside retail hours with minimal labor overhead.
Supermarkets retains volume leadership; E-commerce shows steepest expansion trajectory.
Flavor Profile:
Flavor preference mapping tracks regional agricultural availability and import dependency, with local citrus and tropical sourcing advantaged in North African and East African markets.
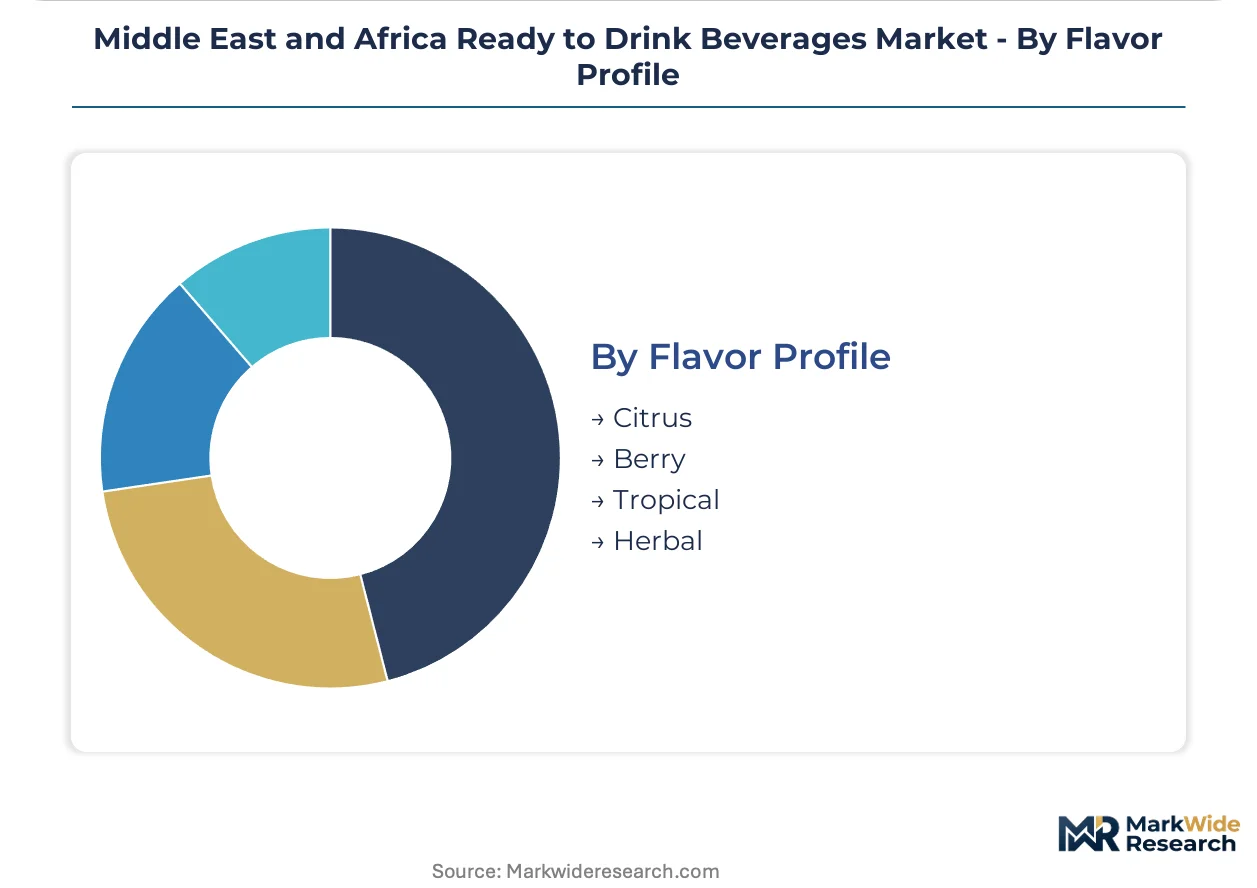
- Citrus:Orange and lemon variants leverage Egyptian and Moroccan domestic fruit processing, reducing import exposure for North African formulators.
- Berry:Import-dependent formulations concentrate in premium Gulf and South African segments where cold-chain maturity permits frozen concentrate sourcing.
- Tropical:Mango and pineapple profiles align with Nigerian and Kenyan consumer preference, with local puree processing emerging in Nairobi manufacturing hubs.
- Herbal:Traditional botanical infusions attract niche positioning in Moroccan and Egyptian markets with established tea cultures.
Citrus dominates regional volume; Tropical is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sugar-reduction mandates and cold-chain infrastructure investments are reconfiguring RTD beverage distribution patterns across Middle East and Africa markets. National regulators in Saudi Arabia, South Africa, Egypt, UAE, and Nigeria are imposing distinct compliance frameworks that fragment market access timelines.
Saudi Arabia
Young urban professionals in Riyadh and Jeddah drive protein-fortified RTD coffee adoption through subscription delivery platforms. The SFDA enforces nutritional labeling and sugar-reduction standards that compress formulation cycles for dairy and juice portfolios. Concentrated demand clusters along the Riyadh-Jeddah corridor reflect modern retail expansion and rising disposable incomes among middle-class households.
South Africa
Energy drink and functional beverage consumption concentrates among young adults in Johannesburg and Cape Town urban centers. The NRCS administers local quality certifications affecting imported formulation market access timelines. Cold-chain partnerships extend chilled RTD penetration into secondary urban centers beyond flagship metros.
Egypt
The Cairo-Alexandria corridor anchors volume demand through expanding modern retail infrastructure and rising middle-class purchasing power. EOS quality certifications create regulatory gatekeeping for shelf-stable juice and dairy entrants. Domestic bottlers concentrate production capacity in Greater Cairo where sugar-tax debates force rapid reformulation of carbonated portfolios.
United Arab Emirates
MOHAP and municipal health authorities shape labeling standards that harmonize with Saudi SFDA requirements while maintaining distinct compliance pathways. Dubai's cold-chain logistics maturity enables same-day delivery of refrigerated protein coffees and kombucha variants previously confined to specialty retail. Transit-hub vending installations across Dubai Metro capture immediate-consumption occasions outside traditional retail hours.
Nigeria
Lagos and Abuja urban corridors pull RTD coffee and energy drinks into daily consumption routines among professional demographics. Import duty structures and foreign exchange volatility create working capital intensity for brands relying on offshore formulation sourcing. Local manufacturing scale-up remains constrained by aseptic filling equipment scarcity and power infrastructure reliability gaps.
Middle East and Africa Ready to Drink Beverages Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions defined by cold-chain reach and formulation expertise. The vendor base clusters around three strategic archetypes: dairy-integrated beverage conglomerates, global refreshment multinationals with extensive distribution partnerships, and energy drink specialists with premium positioning. Consolidation pressure concentrates among Gulf-based dairy networks and North African bottling alliances. Dominant competitive moves include co-manufacturing arrangements that reduce capital intensity and portfolio diversification into functional benefit categories.
Among dairy-integrated beverage conglomerates, Danone SA and Almarai exemplify vertical supply chain control spanning raw milk sourcing through retail shelf placement. PepsiCo and The Coca-Cola Company anchor the global refreshment multinational archetype through refrigerated distribution networks penetrating secondary urban centers. Red Bull GmbH and Monster Energy occupy the energy drink specialist tier with premium positioning sustained by brand equity rather than manufacturing scale. These named entities represent distinct competitive approaches rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Danone SA |
| Red Bull GmbH |
| Nestle SA |
| Alokozay Group |
| Monster Energy |
| PepsiCo |
| Almarai |
| Glanbia PLC |
| The Coca-Cola Company |
| Others |
Supply & Pricing Matrix
Overcapacity in Egyptian aseptic filling plants compresses supplier pricing power while forcing Gulf-based brands to absorb premium logistics costs for cross-border formulation sourcing. This utilization asymmetry between North African manufacturing and Gulf demand centers reshapes procurement negotiations across the Cairo-Alexandria corridor.
Pricing Analysis
Certification level creates the primary spread between Egyptian EOS-certified formulations and premium Saudi SFDA-grade products commanding shelf-space premiums in Riyadh-Jeddah retail. Three-tier pricing structure across premium chilled functional beverages, standard ambient juices, and economy soda formats stratifies margin pools. Pricing pressure stems from draft sugar taxation frameworks under UAE and Bahrain review threatening full-sugar portfolio margins. Price-sensitive teens in Lagos and Johannesburg convenience channels contrast with least-sensitive Dubai professionals subscribing to cold-chain protein coffee deliveries.
Supply Chain Analysis
Contract-manufacturing concentration sits with Almarai's vertically integrated dairy networks and PepsiCo's cold-chain partnerships anchoring Gulf and North African capacity respectively. Geographic supply clusters in Egypt, Saudi Arabia, and South Africa feed regional formulation while Ethiopian and Kenyan hubs mature. Raw material dependencies center on Gulf aluminum smelter output for can formats, Egyptian citrus processing for juice bases, and imported stevia extracts for sugar-reduced lines. Single-source vulnerability runs through concentrated Gulf aluminum supply when regional smelter output fluctuates. Distribution runs through supermarket and e-commerce channels in metropolitan corridors, with vending machines extending into transit-adjacent micro-fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa RTD beverages market sits in a cyclical recovery phase as post-pandemic on-premise consumption normalizes and sugar-reduction mandates force portfolio reinvestment. Cold-chain infrastructure buildout and functional beverage premiumization drive the current upswing.
For Market Incumbents: Pre-empt margin erosion by locking in multi-year co-manufacturing agreements with Nairobi and Mombasa capacity before East African Community import duty advantages attract competitor manufacturing relocation. Accelerate SFDA-compliant sugar-reduced formulation pipelines to defend shelf positioning against regulatory enforcement timelines. Channel control through Dubai Metro vending exclusivity represents a defensible lever against e-commerce subscription displacement.
For New Entrants and Emerging Players: Pursue white-space opportunity in Ethiopian and Kenyan aseptic dairy and juice manufacturing where equipment scarcity constrains incumbent scale-up. Target Nigerian professional corridors for protein-fortified RTD coffee penetration where import duty structures disadvantage offshore brands. Direct-to-consumer subscription platforms with same-day cold-chain capability offer the most penetrable go-to-market angle in affluent Dubai and Cape Town households.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across third-party co-manufacturing arrangements as asset-light franchising displaces vertical integration. Long-term viability favors platforms controlling cold-chain last-mile networks rather than commodity formulation assets. Acquisition targets should demonstrate regional regulatory certification across multiple Gulf Cooperation Council jurisdictions. The signal to watch is co-packer utilization rates in Nairobi and Mombasa as leading indicators of East African manufacturing hub maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Sugar-Reduced Formulation Pipeline | SFDA compliance positioning secures shelf access in Saudi Arabia's modern retail expansion. |
| Co-Manufacturing Partnership Expansion | Nairobi and Mombasa capacity locks in East African Community tariff advantages ahead of competitor entry. |
| Cold-Chain Logistics Investment | Same-day delivery capability separates premium functional contenders from ambient-stable commodity players. |
| Vending Machine Channel Penetration | Dubai Metro and Johannesburg transit installations capture immediate-consumption occasions outside retail hours. |
| Blockchain Traceability Integration | Almarai-style serialization verifies cold-chain integrity for dairy and juice provenance marketing. |
Research Methodology
A spread of perspectives from beverage brand managers, supermarket category buyers, cold-chain logistics operators, and regulatory affairs specialists converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with Egyptian bottler executives, Saudi SFDA compliance officers, and South African NRCS certification leads alongside secondary validation through customs trade records, retail audit databases, and SEC filings from listed beverage multinationals. Bottom-up volume builds from country-level consumption patterns triangulated against top-down category spend estimates across the analysis window.
Demand-supply balance modeling anchored the projection framework, with consumption growth trajectories tested against manufacturing capacity expansion timelines in Egypt, Saudi Arabia, and Kenya. Segmentation dimensions spanned product type, consumer demographic, distribution channel, and flavor profile, with regulatory cluster tiering capturing SFDA, EOS, and NRCS compliance pathways. CAGRs derived from trend extrapolation adjusted for sugar taxation probability weights and cold-chain infrastructure maturity indices.
Sensitivities concentrate around sugar taxation enactment timelines in UAE and Bahrain, aluminum input cost volatility from Gulf smelter output fluctuations, and aseptic line installation delays in Ethiopian and Kenyan manufacturing hubs. Cross-checking against regional customs import data and modern retail square footage expansion rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Freezer & Beverage and Wine Cooler Market
Beverages
Chocolate Malt Drink Market
Beverages
Soft Serve Premix Market
Beverages
South America Energy Drink Market
Beverages
US and Canada Tonic Water Market
Beverages
Solid Beverages Market
Beverages
Grape Juice Concentrate for Wine Making Market
Beverages
Cold Pressed Juice Market
Beverages
Popping Bobas Market
Beverages
Hydrogen Water Dispenser Market
Beverages
Direct Piping Water Dispenser Market
Beverages
Enzyme-Enabled Cold-Brew Concentrates Market
Beverages
United States Recovery Drinks Market
Beverages
Hydrogen Water Bottle Market
Beverages
Caffeinated Beverage Market
Beverages
Blenders Market