
 Soy Lecithin Market | 2026-2036
Soy Lecithin Market Size, Share, and Industry Trends Forecast 2026-2036
Soy Lecithin Market Intelligence
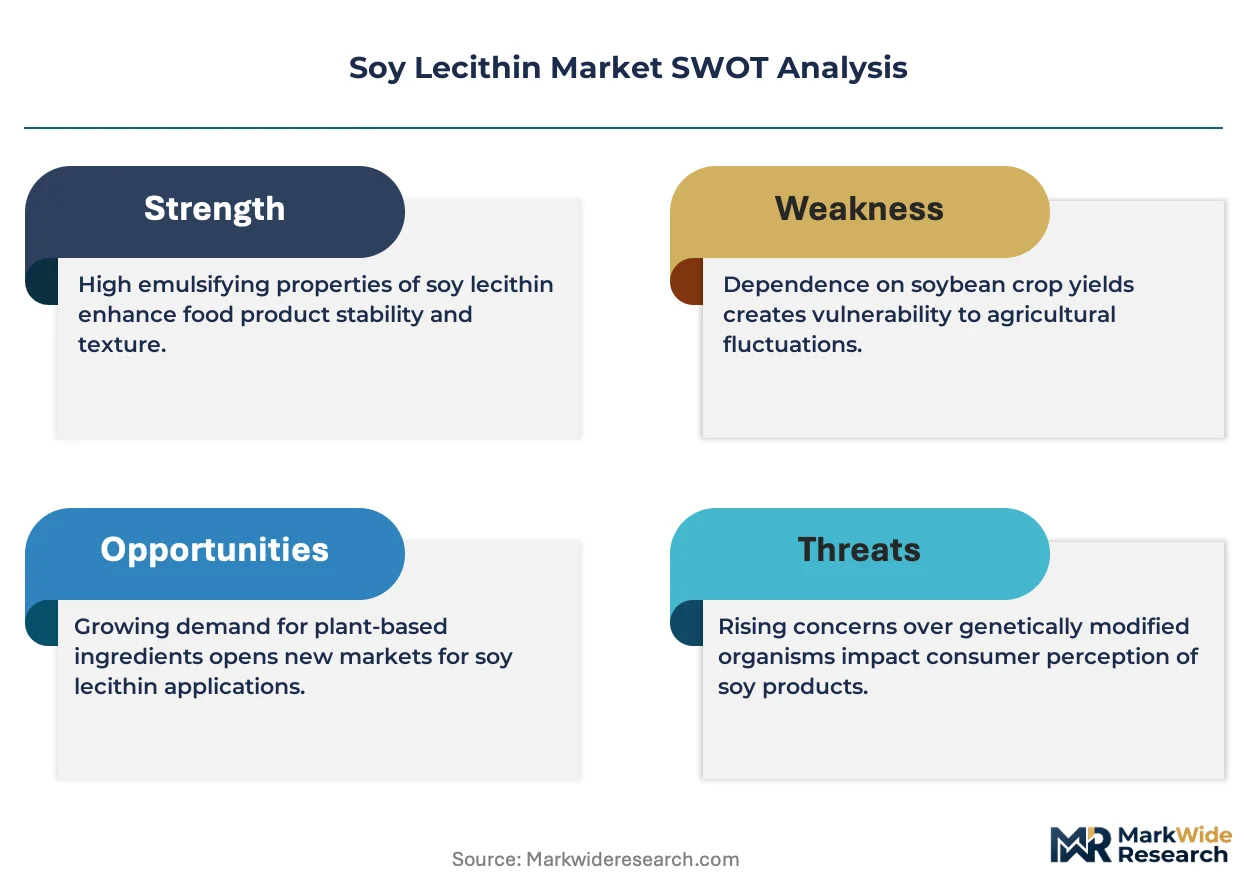
ISO 22000 certification is unwinding competitive access across the soy lecithin supply base, filtering out smaller processors lacking integrated food safety management systems. Archer Daniels Midland Company leverages its crushing network to sustain backward integration into crude lecithin streams. Cargill, Incorporated anchors North American supply through its soybean origination dominance. Lipoid GmbH specializes in high-purity pharmaceutical grades that command premium positioning in European markets.
Soy lecithin comprises a mixture of phospholipids—primarily phosphatidylcholine, phosphatidylethanolamine, and phosphatidylinositol—extracted from soybean oil through degumming and hydration processes, functioning as a natural emulsifier, wetting agent, and dispersant across food, pharmaceutical, and industrial applications. Liquid lecithin retains the largest volume footprint due to its cost efficiency in bulk food processing, while de-oiled powdered lecithin captures expanding share in nutraceutical encapsulation where flowability and concentrated phospholipid content matter. The food industry end-user segment generates the deepest margin pools, though pharmaceutical applications are tightening purity specifications and shortening supplier qualification timelines.
The FDA's food additive regulations and GRAS affirmations shape US market entry pathways, while the EU's REACH framework and EFSA purity standards govern phospholipid specifications for food and pharmaceutical applications in Europe. India's FSSAI mandates increasingly scrutinize lecithin labeling and origin declarations for imported soy derivatives. Stakeholders must monitor evolving allergen disclosure requirements and phosphatidylcholine concentration thresholds as formulation science advances in functional foods and lipid-based drug delivery systems.
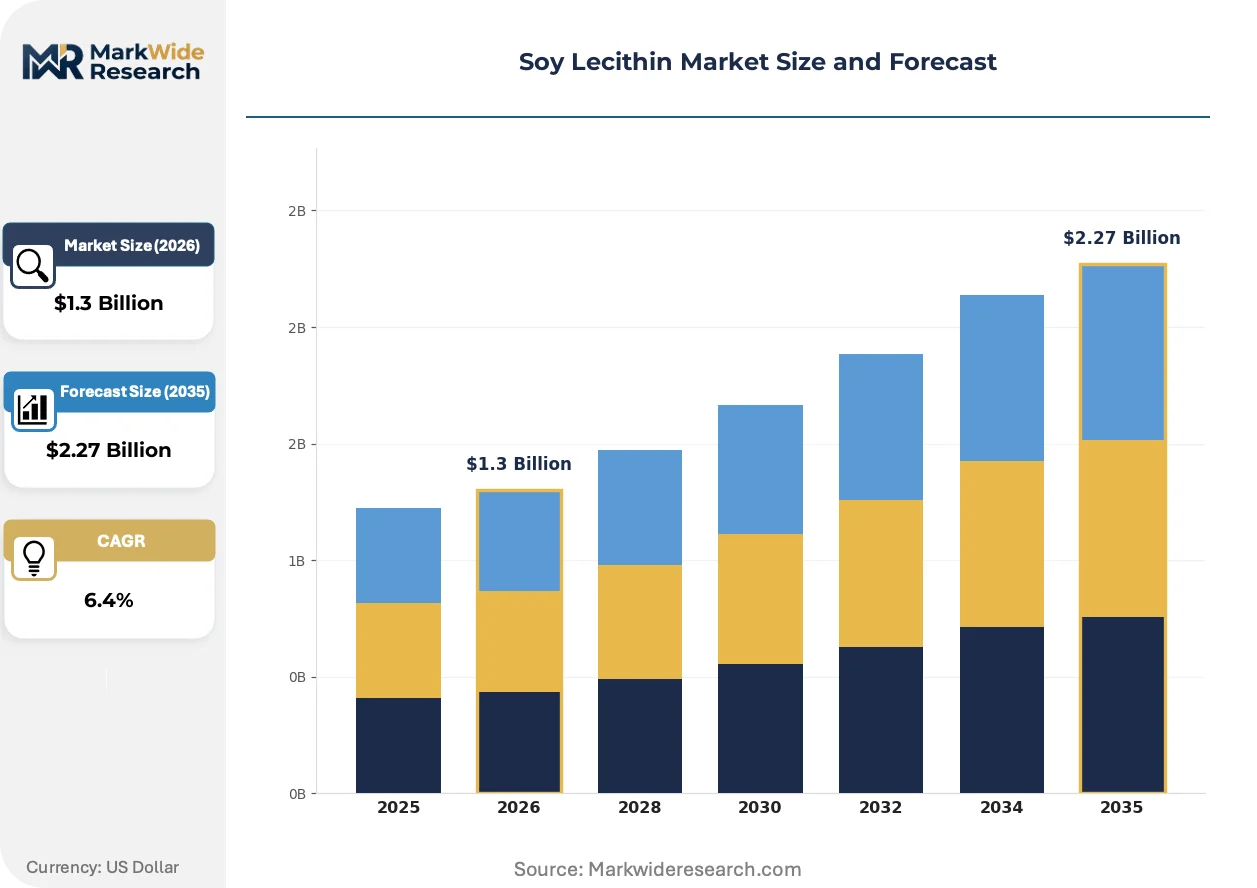
Market Dynamics
Clean-label formulation mandates from EU Novel Food Regulation and FDA allergen disclosure rules are compressing supplier qualification timelines while concentrating procurement among ISO 22000-certified processors capable of integrated traceability systems.
Growth Catalysts
- Pharmaceutical-grade phospholipid specifications:Tightening purity thresholds for lipid-based drug delivery systems in EFSA-governed markets are pulling de-oiled lecithin into nutraceutical encapsulation.
- India's FSSAI labeling mandates:Origin declaration requirements for imported soy derivatives are formalizing documentation standards that favor established crushing networks with integrated supply chain visibility.
- Midwest soybean belt concentration:Proximity of processing infrastructure to origination points in Iowa, Illinois, and Indiana sustains cost-efficient crude lecithin stream access for North American food manufacturers.
Market Restraints
- Crude soybean oil price volatility:Input cost swings tied to commodity futures in Chicago and Dalian exchanges compress margin predictability for non-integrated processors lacking captive crushing assets.
- EU REACH registration burdens:Phospholipid specification compliance costs and ECHA documentation requirements create asymmetric barriers for smaller exporters without dedicated regulatory affairs functions.
- Sunflower and rapeseed lecithin substitution:Non-allergenic alternatives are capturing share in premium infant nutrition and hypoallergenic formulations where soybean allergen labeling creates formulation friction.
Strategic Opportunities
- Brazilian ANVISA pharmaceutical pathways:Underdeveloped high-purity lecithin infrastructure in Latin America's largest pharma market creates first-mover positioning for certified exporters.
- CSRD-aligned sustainability reporting:EU corporate sustainability disclosure requirements are incentivizing traceable, deforestation-free soybean sourcing as a procurement differentiator.
- Precision fermentation convergence:Synthetic biology approaches to phospholipid production are opening non-agricultural supply routes for specialty pharmaceutical applications.
Industry Challenges
- ISO 22000 auditor scarcity:Limited third-party certification capacity in Eastern European and Southeast Asian processing hubs extends supplier qualification timelines for multinational food manufacturers.
- Legacy ERP integration with blockchain traceability:Food safety management system upgrades required for EU digital product passport compliance demand capital deployment that mid-scale processors struggle to sequence.
- Phosphatidylcholine assay standardization:Inconsistent analytical methods across USP, EP, and JP pharmacopeias create batch release disputes between suppliers and pharmaceutical customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soy Lecithin Market |
| Market Size in 2026 | $1.3 Billion |
| Market Size in 2035 | $2.27 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Lecithin, Powdered Lecithin, Granulated Lecithin, Soya Phospholipids Application: Beverages, Bakery, Confectionery, Feed Additives End User: Food Industry, Pharmaceuticals, Nutraceuticals, Cosmetics Distribution Channel: Direct Sales, Online Retail, Supermarkets, Specialty Stores |
| Companies Covered | DuPont de Nemours, Inc., Lipoid GmbH, Archer Daniels Midland Company, Ruchi Soya Industries, Lasenor Emul SL, Cargill, Incorporated, Wilmar International, American Lecithin Company, Bunge Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soy Lecithin Market Strategic Shifts & Innovations
Enzymatic modification and membrane filtration technologies are restructuring how phospholipid fractions are isolated, enabling functional specificity that commodity extraction cannot achieve.
Membrane filtration technology is decomposing the traditional solvent-based degumming hierarchy by enabling cold-pressed phospholipid recovery without hexane residues. Nutraceutical manufacturers in Germany and Switzerland are adopting these systems at pilot scale. This capability is compressing the premium gap between crude and refined lecithin grades by allowing mid-tier processors to achieve pharmaceutical-adjacent purity profiles.
REACH Annex XVII updates on residual solvent limits are tightening extraction process documentation requirements for EU market access. Industrial consequence includes accelerated capital redeployment toward supercritical CO2 and enzyme-assisted systems. Food-grade lecithin destined for infant formula applications faces the most stringent scrutiny, with suppliers building dedicated solvent-free production lines.
Direct procurement from crushing cooperatives is displacing layered distributor networks for large-scale bakery and confectionery manufacturers. This channel compression is most visible in the US Midwest and Northern Germany, where processor-procurement teams are establishing long-term offtake agreements with origination-adjacent facilities to secure volume certainty and traceability documentation.
Soy Lecithin Market Segmentation
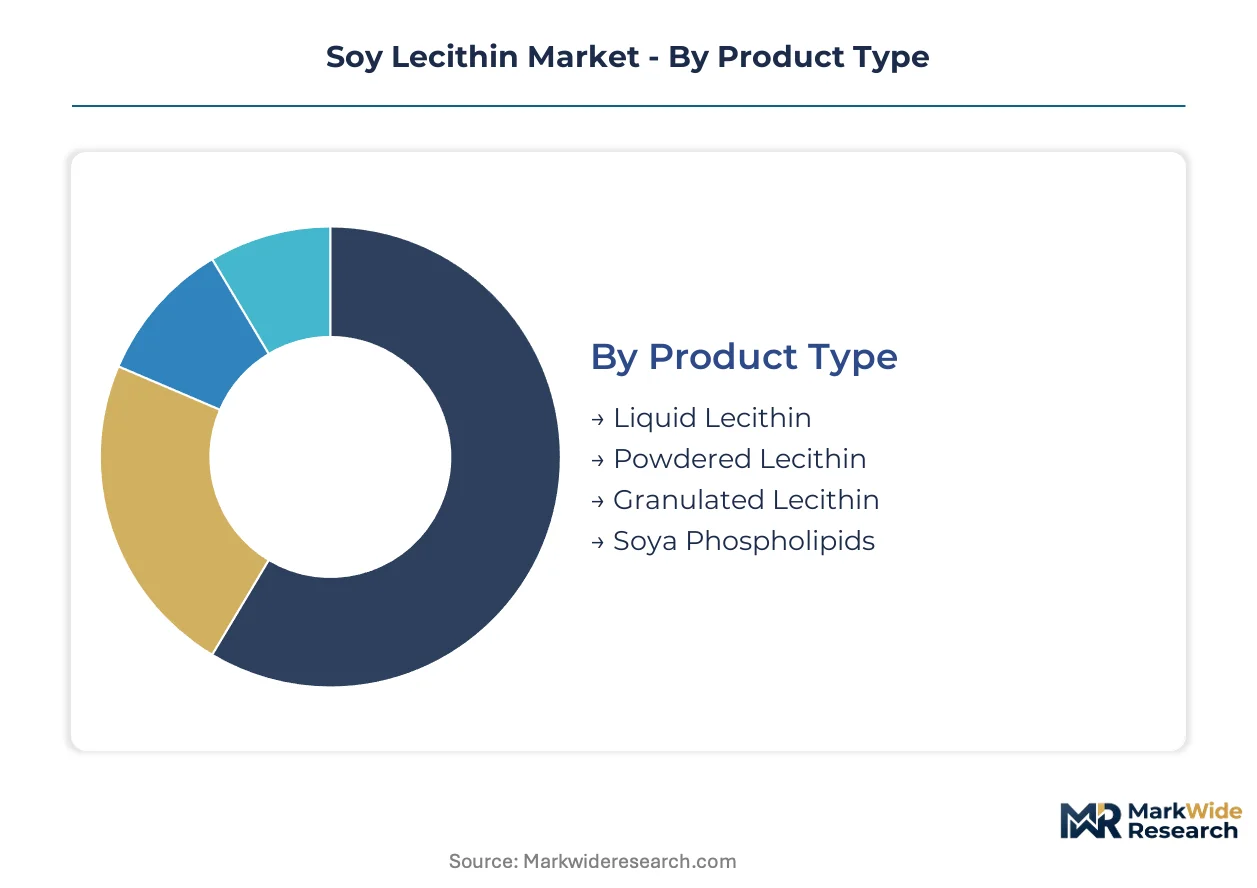
Soy lecithin segmentation reflects divergent purity specifications across regulatory jurisdictions and end-use applications. Product form, application intensity, and channel economics create distinct margin architectures that suppliers must navigate simultaneously.
Product Type:
EFSA and FDA phospholipid concentration thresholds split manufacturing investment between commodity extraction and pharmaceutical-grade purification systems.
- Liquid Lecithin:Retains native oil content of 30-40% with phosphatidylcholine concentrations typically ranging 15-25%. Bulk food processors in Germany's Ruhr industrial corridor and Iowa's processing belt specify this grade for cost-efficient emulsification in chocolate and margarine production.
- Powdered Lecithin:De-oiled through acetone precipitation to achieve 95%+ phospholipid purity with enhanced flowability. Nutraceutical encapsulation operations in Switzerland and pharmaceutical contractors in New Jersey are pulling this grade into lipid-based drug delivery systems where powder handling characteristics reduce manufacturing variability.
- Granulated Lecithin:Agglomerated form with intermediate oil content for dust-controlled handling in high-speed bakery lines.
- Soya Phospholipids:Fractionated phosphatidylcholine isolates meeting USP and EP injection-grade specifications for parenteral emulsion formulations.
Established volume favors Liquid Lecithin; emerging adoption favors Powdered Lecithin.
Application:
Clean-label formulation mandates from EU Novel Food Regulation and India's FSSAI are compressing permissible additive lists while elevating natural emulsifier specification intensity.
- Beverages:Instant drink mixes and plant-based milk alternatives deploy lecithin for fat dispersion and mouthfeel modulation. German beverage compounders and California oat milk processors are specifying non-GMO certified grades to meet retailer sustainability scorecards.
- Bakery:Bread improvers and cake emulsifiers leverage lecithin's anti-staling and crumb-softening functionality. Industrial bakeries in Chicago and Paris are consolidating procurement around ISO 22000-certified suppliers capable of lot-level allergen documentation.
- Confectionery:Chocolate viscosity reduction and bloom prevention in tempering operations.
- Feed Additives:Pellet binding and lipid metabolism enhancement in aquaculture and poultry nutrition.
Volume concentration sits with Bakery; formulation innovation intensity concentrates in Beverages.
End User:
Customer qualification timelines stretch from weeks for food compounders to years for pharmaceutical contractors, segmenting supplier development economics.
- Food Industry:Spanning bakery, confectionery, and processed meat applications with GRAS-affirmed usage levels. Procurement teams at multinational manufacturers in Illinois and Bavaria are establishing direct crushing cooperative relationships to secure traceability documentation for clean-label product lines.
- Pharmaceuticals:Parenteral and oral drug delivery systems requiring phospholipid fractions with specified fatty acid profiles and endotoxin limits. EMA and FDA inspection histories now dominate supplier selection for European and North American pharmaceutical contractors.
- Nutraceuticals:Dietary supplement encapsulation and functional food fortification.
- Cosmetics:Emulsion stabilization in skin care and hair conditioning formulations.
Margin depth favors Pharmaceuticals; transaction velocity favors Food Industry.
Distribution Channel:
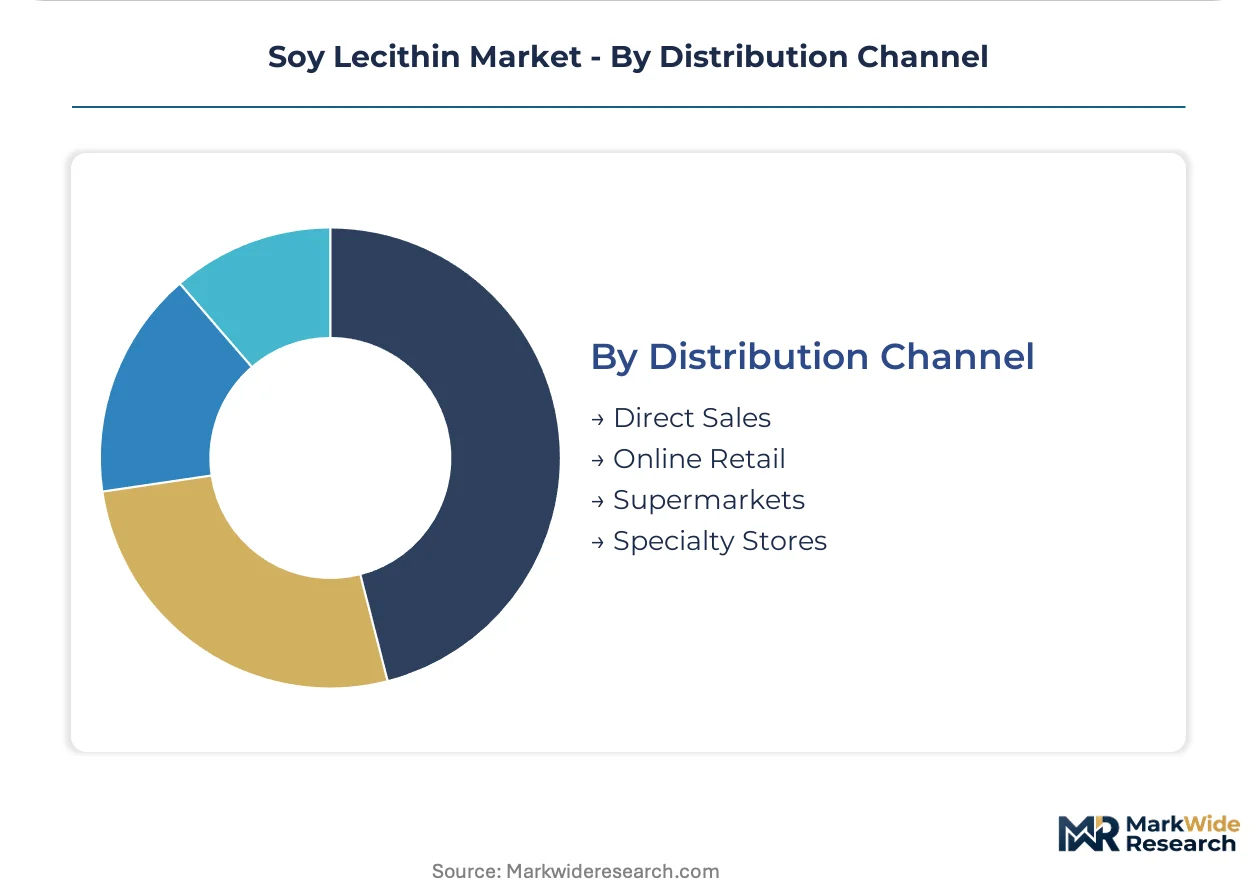
Channel selection tracks order scale and documentation complexity, with direct procurement displacing intermediaries for qualified volume buyers.
- Direct Sales:Long-term offtake agreements between crushing processors and industrial compounders. Archer Daniels Midland and Cargill leverage origination-adjacent facilities in Indiana and Iowa to bypass distributor margins for bakery and confectionery manufacturers above specified volume thresholds.
- Online Retail:E-commerce platforms serving small-scale nutraceutical formulators and specialty food artisans. Indian and Southeast Asian processors are building digital storefronts to reach European and North American buyers below minimum order quantities for direct sales teams.
- Supermarkets:Consumer-packaged lecithin for home baking and health applications.
- Specialty Stores:Organic and non-GMO certified grades for natural products retailers.
Procurement concentration is accelerating in Direct Sales; channel experimentation is expanding through Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Novel Food Regulation traceability mandates and India's FSSAI origin declaration requirements are redrawing procurement geographies for soy lecithin processors. Germany's Ruhr corridor and the US Midwest soybean belt anchor volume concentration, while regulatory divergence across jurisdictions fragments supplier qualification pathways.
Germany
Chocolate compounders in Cologne and margarine processors in Hamburg drive liquid lecithin demand for emulsification applications. EFSA purity standards and REACH Annex XVII solvent limits enforce documentation intensity that favors ISO 22000-certified crushing networks. The Ruhr industrial corridor hosts membrane filtration pilot installations serving pharmaceutical-grade phospholipid fractionation.
United States
Bakery manufacturers in Chicago and confectionery processors in Pennsylvania specify non-GMO certified grades for clean-label product lines. FDA GRAS affirmations and allergen disclosure rules under FALCPA shape formulation permissibility. Iowa and Illinois crushing cooperatives sustain backward integration into crude lecithin streams through origination-adjacent processing infrastructure.
India
Nutraceutical encapsulators in Mumbai and dietary supplement formulators in Hyderabad pull de-oiled powdered lecithin for lipid-based delivery systems. FSSAI labeling mandates scrutinize origin declarations for imported soy derivatives, formalizing documentation standards that favor established traders. Gujarat's processing belt is consolidating around FSSAI-compliant import handling facilities.
Brazil
Pharmaceutical contractors in São Paulo and Rio de Janeiro are tightening phospholipid specifications for parenteral emulsion formulations. ANVISA pharmaceutical registration pathways remain underdeveloped for high-purity lecithin, creating qualification bottlenecks. The Paraná soybean belt is attracting capital deployment toward pharmaceutical-grade purification capacity.
Switzerland
Nutraceutical manufacturers in Basel and Geneva deploy de-oiled lecithin for functional food fortification and encapsulation operations. Swissmedic pharmaceutical standards and EP pharmacopeia compliance requirements dominate supplier selection for injection-grade phospholipids. The Basel biotech cluster is integrating lipid-based drug delivery expertise with phospholipid fractionation capabilities.
Soy Lecithin Market Key Industry Players
Player mix skews toward integrated agribusiness conglomerates with captive crushing assets and specialized phospholipid fractionators serving pharmaceutical tiers. The supply base concentrates around three strategic archetypes: origination-anchored processors controlling upstream soybean streams, pharmaceutical-grade specialists commanding premium positioning through purity certification, and regional distributors bridging documentation gaps for qualified volume buyers. Dominant competitive moves include direct procurement channel compression and membrane filtration technology licensing for solvent-free extraction capabilities.
Within the integrated agribusiness tier, Archer Daniels Midland Company and Cargill, Incorporated exemplify origination-adjacent positioning through Midwest crushing network control. Lipoid GmbH occupies a specialist position representing pharmaceutical-grade purification archetypes in European markets. These three anchors illustrate the bifurcation between commodity volume processors and premium-tier fractionators competing on regulatory compliance depth rather than scale alone.
| Leading Market Players |
|---|
| DuPont de Nemours, Inc. |
| Lipoid GmbH |
| Archer Daniels Midland Company |
| Ruchi Soya Industries |
| Lasenor Emul SL |
| Cargill, Incorporated |
| Wilmar International |
| American Lecithin Company |
| Bunge Limited |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety-day inventory cycles among European compounders concentrate pricing power with origination-anchored processors in Iowa and Illinois, while spot market exposure for non-integrated buyers amplifies margin volatility across the soy lecithin value chain.
Pricing Analysis
Cost-plus contracts indexed to Chicago Board of Trade soybean oil futures dominate long-term offtake agreements between Midwest crushing networks and industrial bakery manufacturers. Pricing stratifies across pharmaceutical-grade, food-grade, and feed-grade tiers based on phosphatidylcholine concentration and ISO 22000 certification status. Cost compression in standard liquid grades intensifies because sunflower lecithin substitution erodes soybean-derived pricing power. Feed additive buyers exhibit highest price sensitivity, while pharmaceutical contractors accept premium positioning for USP-grade phospholipid isolates.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg port congestion periodically disrupt European pharmaceutical-grade supply, forcing Swiss and German nutraceutical manufacturers to maintain safety stocks. Production gravity centers on the United States, Brazil, and Argentina, with crude lecithin streams drawing from soybean crushing operations tethered to origination belts. Supply chain risk concentrates in single-source dependency on Iowa-Illinois processing infrastructure for North American food-grade volumes. Distribution runs through direct procurement channels for qualified volume buyers, supplemented by specialty chemical distributors serving small-batch nutraceutical formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane filtration technology is disrupting traditional solvent-based extraction economics, creating qualification windows for processors capable of pharmaceutical-adjacent purity without legacy infrastructure.
For Market Incumbents: Secure backward integration into Brazilian and Paraná-based crushing assets to offset Midwest concentration risk. Anchor certification depth through EMA and FDA inspection history investments, as pharmaceutical contractor qualification timelines extend supplier stickiness. Defend against sunflower lecithin substitution by accelerating solvent-free production line deployment for infant formula applications. For New Entrants and Emerging Players: Blockchain-enabled traceability services for EU CSRD compliance represent a service-layer gap where established processors under-serve mid-scale food manufacturers. Target ANVISA pharmaceutical pathway development in Brazil, where high-purity infrastructure remains underdeveloped relative to formulation demand. Pursue membrane filtration technology licensing as a capital-light entry mechanism. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified agribusiness conglomerates seeking to monetize non-core phospholipid fractionation units. Long-term viability hinges on deforestation-free sourcing credentials and precision fermentation convergence readiness. Watch for EFSA phosphatidylcholine threshold revisions as signal for pharmaceutical-grade margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Crushing Assets | Captive crude lecithin streams from Iowa and Paraná facilities insulate margin predictability against CBOT volatility. |
| Membrane Filtration Technology Licensing | Cold-pressed phospholipid recovery enables Swiss and German nutraceutical manufacturers to bypass hexane residue constraints. |
| ANVISA Pharmaceutical Registration Pathway | First-mover positioning in São Paulo parenteral emulsion markets exploits underdeveloped high-purity domestic infrastructure. |
| CSRD-Aligned Sustainability Reporting | Deforestation-free soybean documentation from Brazilian cooperatives differentiates procurement for EU corporate buyers. |
| ISO 22000 Certification Investment | Integrated food safety management systems filter competitive access as EU Novel Food Regulation tightens traceability mandates. |
Research Approach
Operator-level perspectives from crushing plant managers, pharmaceutical procurement officers, nutraceutical formulators, and FSSAI compliance consultants anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation through EFSA guidance documents, FDA GRAS affirmation notices, ANVISA registration databases, and customs trade flow records. Bottom-up volume estimates from processor capacity utilization triangulated against top-down demand projections from end-use consumption patterns.
Sensitivity analysis tested forecast robustness across crude soybean oil price bands, regulatory implementation timelines, and substitution elasticity parameters. Segmentation modeling incorporated product form, application intensity, end-user qualification depth, and regional regulatory cluster dimensions throughout the projection horizon. CAGRs derived from historical volume trajectories adjusted for capacity expansion announcements and technology adoption S-curves in membrane filtration deployment.
Underlying assumptions cover EFSA and FDA regulatory stability, continued phospholipid demand in lipid-based drug delivery systems, and commodity price corridor containment, with deviation risk concentrated in EU REACH solvent limit revisions and precision fermentation commercialization acceleration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Low Calorie Cooking Oil Market
Ingredients
Coconut Oil Based Products Market
Ingredients
Lentils Flour Market
Ingredients
Clean Label Flour Market
Ingredients
Bleached Flour Market
Ingredients
Low-Odor Fish Protein Hydrolysates from Med Species Market
Ingredients
Tapioca Pearls Market
Ingredients
Protein Ingredients Market
Ingredients
Beef Concentrate Market
Ingredients
Fermented Rennet Market
Ingredients
Pet Food Premix Market
Ingredients
Injection Grade Soybean Oil Market
Ingredients
Spain Sodium Reduction Ingredient Market
Ingredients
Lactase Enzyme Market
Ingredients
Commercial Flour Market
Ingredients
Vital Wheat Gluten Market