
 Modified Flour Market | 2026-2036
Modified Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Modified Flour Market Outlook
A wide capability gap between capital-heavy wet-milling operators and asset-light dry-processors is redrawing competitive boundaries in modified flour. Cargill, Incorporated leverages integrated grain origination networks across North American river systems. Ingredion Incorporated anchors its position through proprietary waxy maize hybrid development. Archer Daniels Midland Company sustains cost leadership via fermentation-adjacent starch complexes in the US Midwest.
Modified flour consists of native cereal or legume starches subjected to physical, chemical, or enzymatic alteration to achieve controlled viscosity, thermal stability, or freeze-thaw resistance, typically measured by Brabender amylograph peak viscosity in BU. Pregelatinized variants serve instant food manufacturers requiring cold-water dispersibility without additional heat treatment. Cross-linked modified flour dominates margin pools in retort sauces where acid and shear stability command pricing premiums. Acetylated grades are gaining fastest in refrigerated dough systems for their extended shelf-life performance.
The US FDA governs food starch-modified labeling under 21 CFR 172.892, while the EU Green Deal caps agricultural processing emissions through its Farm to Fork strategy. BIS certification requirements in India restrict unapproved chemical modification pathways for imported flour. Stakeholders must monitor evolving enzyme-modification approvals as biotechnology regulators in major consuming countries reassess processing aids.
Market Dynamics
The EU Green Deal's Farm to Fork emissions caps are forcing wet-milling operators to reconfigure thermal processing systems, while Southeast Asian bakery chains accelerate clean-label reformulation mandates. This regulatory-cost squeeze is compressing margins for legacy chemical modification pathways and redirecting capital toward enzyme-based processing infrastructure.
Growth Catalysts
- Clean-label mandates:Southeast Asian bakery chains now require modified flour with declared enzymatic processing rather than chemical modification, pulling demand toward transparent supply chains.
- EU Green Deal compliance:The Farm to Fork strategy's carbon intensity caps are creating premium pricing pools for low-emission modified flour grades in retort and refrigerated applications.
- Instant noodle sector concentration:Indonesia's instant noodle manufacturers are locking in multi-year supply contracts for pregelatinized modified flour with guaranteed cold-water dispersibility specifications.
Market Restraints
- Input cost volatility:Maize and wheat price swings tied to Black Sea supply disruptions are compressing margins for dry-processors without captive grain origination.
- Supply concentration risk:North American river-system grain terminals dominate origination for waxy maize hybrids, creating chokepoint vulnerability for Asian manufacturers.
- Regulatory friction:BIS certification requirements in India block unapproved chemical modification pathways, forcing reformulation or local partnership requirements for imported flour.
Strategic Opportunities
- Underpenetrated geography:Vietnam's emerging bakery chain sector lacks domestic modified flour capacity, creating first-mover positioning for enzyme-processing specialists.
- Regulatory tailwind:India's PLI scheme for food processing equipment subsidizes capital expenditure for enzymatic modification infrastructure.
- Technology convergence:Precision fermentation and starch modification are converging to produce novel functional proteins that displace synthetic emulsifiers in dough systems.
Industry Challenges
- Specialized talent scarcity:Enzymatic process engineering expertise concentrates with wet-milling operators, leaving dry-processors dependent on contract technology providers.
- Capex intensity:Continuous thermal processing systems for pregelatinization require eight-figure capital commitments with five-year payback horizons.
- Certification timeline compression:Evolving biotechnology regulator reassessments of processing aids in major consuming countries are extending approval cycles for novel enzyme modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Modified Flour Market |
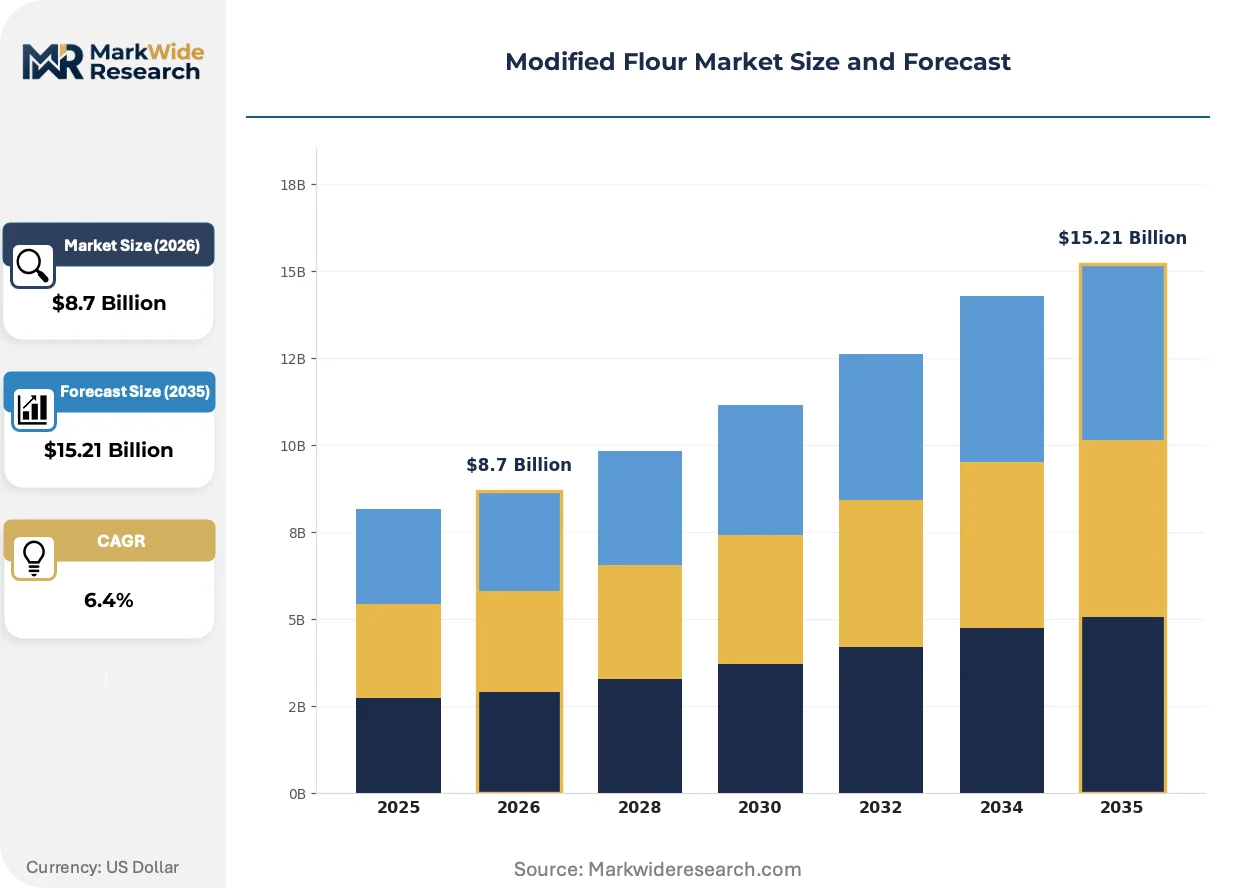
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pregelatinized, Cross-Linked, Acetylated, Oxidized End Use Industry: Bakery, Confectionery, Sauces, Snacks Packaging Type: Bags, Drums, Bulk, Sachets Quality Grade: Food Grade, Pharmaceutical Grade, Industrial Grade, Others |
| Companies Covered | Cargill, Incorporated, Archer Daniels Midland Company, Ingredion Incorporated, Tate & Lyle PLC, Roquette Frères, Bunge Limited, The Scoular Company, Grain Millers, SunOpta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modified Flour Market Strategic Shifts
Enzymatic modification pathways are displacing legacy chemical processes across premium modified flour segments. Thermal processing intensification and regulatory disclosure requirements are simultaneously reshaping equipment investment patterns and buyer qualification criteria.
Enzyme-directed starch modification is miniaturizing batch processing footprints while preserving Brabender amylograph peak viscosity precision. Southeast Asian instant food manufacturers are adopting compact enzymatic systems to bypass centralized wet-milling dependencies. This distributed processing architecture is compressing logistics costs and enabling just-in-time formulation adjustments at plant level.
The EU Green Deal's carbon accounting mandates are forcing retort sauce manufacturers to document agricultural processing emissions across modified flour supply chains. EFSA disclosure requirements now extend to upstream grain cultivation practices, not merely modification chemistry. Cross-linked modified flour grades with verified low-carbon origination are commanding contract premiums from European sauce brands facing Scope 3 reporting deadlines.
Buyer concentration among Indonesian instant noodle producers is consolidating procurement authority with technical specification teams rather than commodity traders. Direct mill-to-manufacturer contracting is displacing layered distributor networks for high-volume modified flour volumes. This channel compression is most visible in Java's industrial corridor, where instant noodle capacity expansion has outpaced regional trading infrastructure development.
Modified Flour Market Segmentation
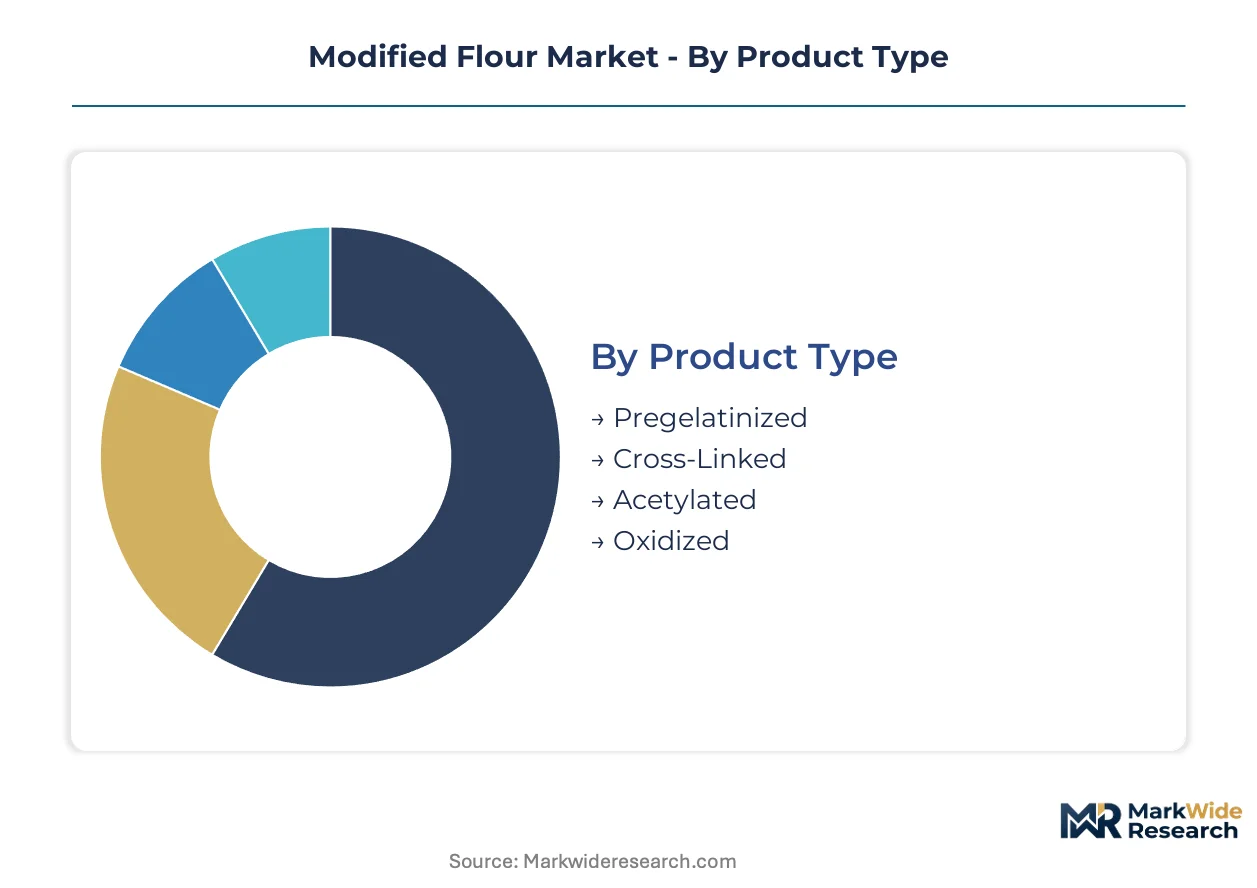
Modified flour segmentation reveals how functional specifications map to distinct margin architectures across processing technologies. Product chemistry and end-use application create the primary value stratification, while packaging format and quality certification operate as secondary differentiators in contract negotiations.
Product Type:
Margin pools concentrate in thermally and chemically stabilized variants where acid resistance and freeze-thaw performance command technical premiums.
- Pregelatinized:Native starches subjected to controlled thermal hydration achieve cold-water dispersibility without secondary heat treatment. Demand concentrates with Indonesia's instant noodle manufacturers locking multi-year supply contracts for guaranteed viscosity specifications under Brabender amylograph protocols.
- Cross-Linked:Phosphate or adipate esterification creates shear-stable molecular networks resistant to acid hydrolysis. Retort sauce manufacturers in Europe's industrial food corridor pay contract premiums for verified low-carbon origination grades meeting EU Green Deal Scope 3 reporting deadlines.
- Acetylated:Esterification with acetic anhydride extends refrigerated dough shelf-life through reduced retrogradation kinetics. Southeast Asian bakery chains specify acetylated grades for clean-label reformulation mandates displacing synthetic preservatives.
- Oxidized:Hypochlorite or peroxide treatment introduces carbonyl and carboxyl groups for improved dough conditioning and film formation. Paperboard adhesives and textile sizing applications absorb volume in industrial grade channels outside food safety jurisdictions.
The dominant share belongs to Cross-Linked modified flour, while Pregelatinized is closing the gap fastest through instant food sector procurement consolidation.
End Use Industry:
Application-driven segmentation tracks how viscosity specifications and regulatory exposure reshape customer procurement authority.
- Bakery:Laminated dough systems and clean-label bread formulations require enzymatically modified flour with declared processing transparency. Southeast Asian chain bakeries now mandate enzymatic over chemical modification in supplier qualification protocols.
- Confectionery:Gelling agents and fat replacers in sugar confectionery depend on specific amylose-amylopectin ratios from waxy maize hybrids. European confectioners face EFSA disclosure requirements extending to upstream grain cultivation practices.
- Sauces:Retort-processed emulsified sauces demand cross-linked stability under severe thermal and shear conditions. EU Green Deal carbon accounting mandates force manufacturers to document agricultural processing emissions across modified flour supply chains.
- Snacks:Extruded and coated snack applications utilize pregelatinized flour for expansion control and oil barrier properties. Indonesian and Vietnamese snack processors adopt compact enzymatic systems to bypass centralized wet-milling dependencies.
Bakery commands the largest volume position, though Sauces generates superior margin per ton through technical specification complexity.
Packaging Type:
Logistics economics and contamination risk stratify packaging selection across customer scale and geographic dispersion.
- Bags:Multi-wall paper or woven polypropylene sacks dominate 25-50kg industrial shipments to integrated food manufacturers with pneumatic handling systems. North American river-terminal grain processors favor bagged formats for containerized export to Asian instant noodle mills.
- Drums:Fiber or steel drums protect hygroscopic modified flour from moisture ingress during extended ocean freight. Pharmaceutical and specialty food grade shipments to European compounding facilities specify drum packaging with nitrogen flushing.
- Bulk:Pneumatic tanker or flexible intermediate bulk container (FIBC) deliveries minimize unit costs for high-volume continuous processors. Java's industrial corridor instant noodle plants receive bulk pregelatinized flour via direct mill-to-manufacturer contracting displacing layered distributor networks.
- Sachets:Retail and foodservice portion control formats serve small-scale bakeries and institutional kitchens lacking bulk handling infrastructure. Vietnam's emerging bakery chain sector sources sachet formats while domestic modified flour capacity remains underdeveloped.
Bulk packaging holds the cost advantage at scale, yet Sachets is expanding most quickly through foodservice channel fragmentation.
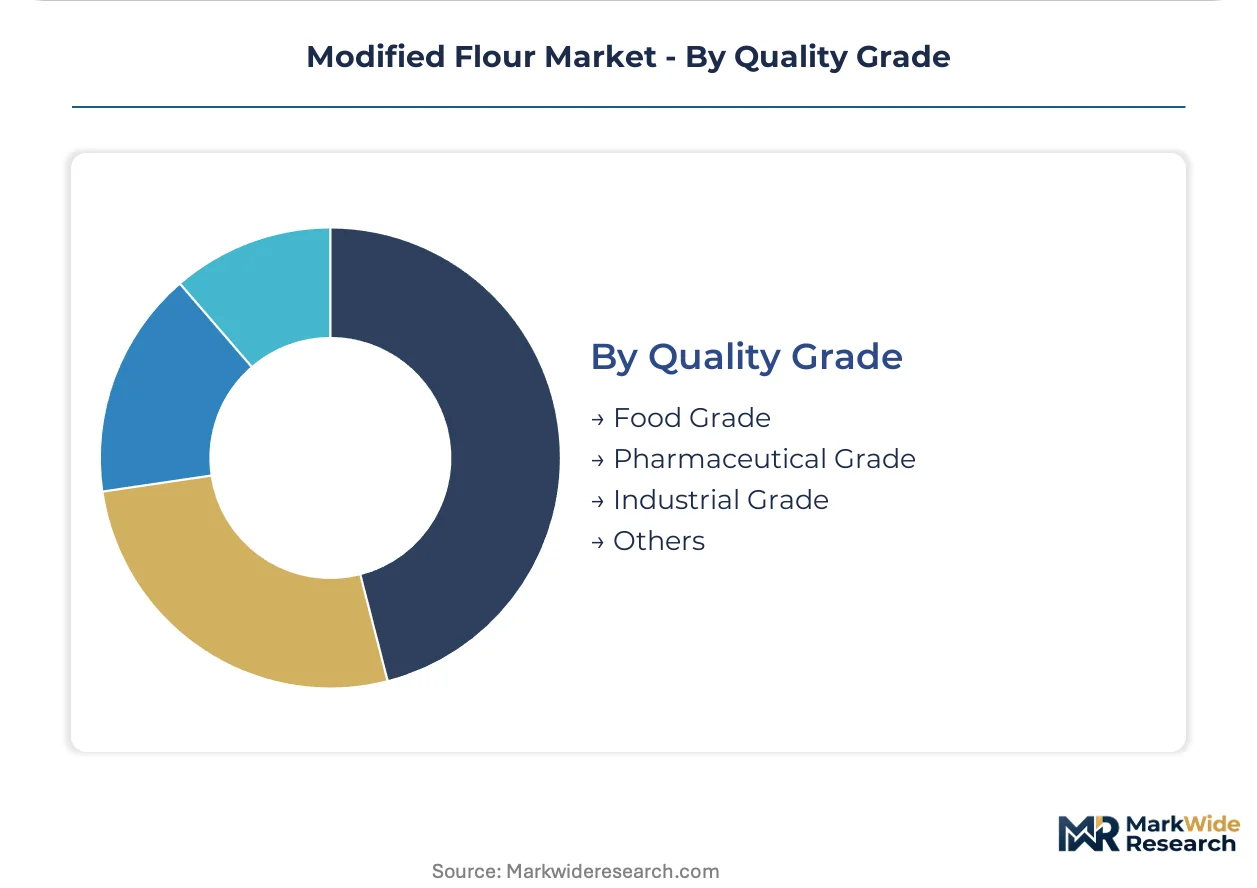
Quality Grade:
Certification tier determines market access and pricing power through regulatory jurisdiction and end-use liability exposure.
- Food Grade:Compliance with FDA 21 CFR 172.892 or EFSA food additive specifications enables broad human consumption applications. BIS certification requirements in India restrict unapproved chemical modification pathways, forcing reformulation or local partnership for imported flour.
- Pharmaceutical Grade:USP-NF or EP monograph conformance for excipient applications in tablet binders and capsule disintegrants commands the highest purity premiums. CDSCO and other national pharmaceutical regulators enforce separate approval tracks for starch excipients.
- Industrial Grade:Paperboard adhesives, textile sizing, and construction applications tolerate higher protein and lipid residuals absent food safety constraints. Oxidized modified flour flows predominantly through industrial channels outside enzymatic processing investment cycles.
- Others:Feed grade and technical specifications for fermentation substrates occupy niche volume positions with minimal modification complexity. Animal nutrition formulators prioritize cost over functional precision in viscosity control.
Food Grade maintains the volume leadership position, while Pharmaceutical Grade climbs the fastest through excipient supply security concerns in generic drug manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesian instant noodle manufacturers exhibit the lowest price elasticity, locking multi-year contracts for pregelatinized grades, while Indian dry-processors face acute margin compression from input volatility and BIS certification barriers.
United States
River-system grain terminals along the Mississippi and Illinois waterways dominate waxy maize origination for modified flour production. FDA 21 CFR 172.892 governs food starch-modified labeling, creating compliance clarity for domestic and export shipments. The US Midwest fermentation-adjacent starch complexes sustain cost leadership through captive grain supply and integrated thermal processing infrastructure.
Indonesia
Instant noodle sector procurement consolidation has shifted buying authority to technical specification teams rather than commodity traders. The country's national food safety regulator enforces additive standards that favor pregelatinized modified flour with verified cold-water dispersibility. Java's industrial corridor hosts direct mill-to-manufacturer contracting that bypasses traditional distributor networks for high-volume supply.
Germany
Retort sauce manufacturers in Europe's industrial food corridor pay contract premiums for cross-linked modified flour grades. EU Green Deal Farm to Fork carbon intensity caps force documentation of agricultural processing emissions across supply chains. The country's chemical processing clusters are reconfiguring thermal systems to meet Scope 3 reporting deadlines for European sauce brands.
India
Bakery chain expansion and snack processing growth drive modified flour consumption across Maharashtra and Gujarat. BIS certification requirements block unapproved chemical modification pathways for imported flour, forcing reformulation partnerships. The PLI scheme for food processing equipment subsidizes capital expenditure for enzymatic modification infrastructure in emerging manufacturing zones.
Vietnam
Emerging bakery chains lack domestic modified flour capacity, creating positioning opportunities for enzyme-processing specialists. The country's national standards body is developing alignment with regional food additive harmonization frameworks. Ho Chi Minh City's industrial zones see compact enzymatic system adoption to bypass centralized wet-milling dependencies and compress logistics costs.
Modified Flour Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in modified flour supply. Wet-milling operators with captive grain origination networks command margin pools in cross-linked and acetylated grades, while asset-light dry-processors compete on speed and customization for regional bakery accounts. Three archetypes dominate: integrated agribusiness conglomerates with river-system terminal control, hybrid seed developers with proprietary starch genetics, and enzymatic technology licensors with distributed processing equipment. Capacity expansion and strategic partnerships represent the dominant competitive moves, as players seek to secure origination chokepoints and deploy enzyme-based processing infrastructure ahead of regulatory disclosure mandates.
Within the integrated agribusiness tier, Cargill, Incorporated and Archer Daniels Midland Company exemplify scale-driven positioning through North American grain network control. Ingredion Incorporated occupies a specialist position anchored by proprietary waxy maize hybrid development. These three entities represent contrasting strategic anchors: river-system logistics integration, fermentation-adjacent starch complex economics, and seed-to-starch genetic pipeline ownership. Their collective presence shapes procurement authority dynamics across Indonesian instant noodle mills and European retort sauce manufacturers alike.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| Tate & Lyle PLC |
| Roquette Frères |
| Bunge Limited |
| The Scoular Company |
| Grain Millers |
| SunOpta |
| Others |
Value Chain & Pricing Dynamics
BIS certification requirements in India gate both supply qualification and price differentiation simultaneously, blocking unapproved chemical modification pathways while forcing imported flour toward premium enzymatic grades with local partnership premiums. The EU Green Deal's carbon accounting mandates add a parallel certification layer that segments European contract pricing by verified Scope 3 origination documentation.
Pricing Analysis
After-sales technical service contracts drive lifetime value for modified flour suppliers, with formulation support and just-in-time viscosity adjustment commanding recurring revenue streams. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and enzymatic processing transparency, with clean-label enzymatic grades capturing margin premiums over legacy chemical pathways. Pricing pressure stems from Black Sea grain supply disruptions compressing margins for dry-processors without captive origination. Indonesian instant noodle manufacturers exhibit the lowest price sensitivity, locking multi-year contracts for guaranteed cold-water dispersibility specifications, while Vietnam's emerging bakery chains face acute cost consciousness due to underdeveloped domestic capacity.
Supply Chain Analysis
Inventory lead times stretch longest for cross-linked grades requiring verified low-carbon origination documentation under EU Green Deal mandates. Supply concentrates in the United States, Indonesia, and Germany, with North American river-system terminals dominating waxy maize hybrid origination. Raw material dependencies center on maize and wheat feedstocks, phosphate esterification agents, and acetic anhydride for acetylation pathways. Single-source vulnerability runs through Mississippi and Illinois waterway grain terminals that chokepoint Asian manufacturer access to specialty starch genetics. Distribution runs through direct mill-to-manufacturer contracting in Java's industrial corridor, displacing layered distributor networks for high-volume instant noodle supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The modified flour market sits at a platform-economics inflection where enzymatic processing infrastructure interoperability is consolidating procurement authority with technical specification teams rather than commodity traders.
For Market Incumbents: Fortify river-system grain origination control through terminal capacity expansion along Mississippi and Illinois waterways to defend against Asian dry-processor encroachment. Deepen backward integration into proprietary waxy maize hybrid development to secure genetic pipeline differentiation against seed-to-starch specialists. Prioritize enzymatic modification certification investment ahead of biotechnology regulator reassessments in major consuming countries. For New Entrants and Emerging Players: Lead with compact enzymatic system deployment in Vietnam's emerging bakery chain sector, where domestic modified flour capacity remains underdeveloped and first-mover positioning is achievable. Target Indonesia's snack processing corridor with distributed processing architecture that compresses logistics costs and enables just-in-time formulation adjustments. Pursue PLI scheme subsidized capital expenditure partnerships in India's emerging manufacturing zones to bypass BIS certification barriers for imported flour. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pregelatinization thermal processing infrastructure, with continuous systems requiring eight-figure commitments and five-year payback horizons. Acquisition target archetypes include enzymatic technology licensors with distributed processing equipment portfolios and hybrid seed developers with verified low-carbon origination pipelines. Watch biotechnology regulator approval cycle extensions for novel enzyme modifications as the inflection signal for competitive repositioning timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grain Origination | Captive waxy maize supply from Mississippi river terminals secures specialty starch genetics for cross-linked grade production. |
| Enzymatic Processing Infrastructure Deployment | Compact distributed systems in Vietnam and Indonesia bypass wet-milling dependencies and compress logistics costs. |
| EU Green Deal Carbon Certification Program | Verified low-carbon origination documentation commands contract premiums from European retort sauce manufacturers. |
| Long-term Supply Agreement with Instant Noodle Mills | Direct mill-to-manufacturer contracting in Java's industrial corridor locks multi-year volumes with technical specification teams. |
| Joint Venture for BIS-Compliant Local Production | Indian partnership structures bypass certification barriers while accessing PLI scheme subsidized capital expenditure. |
Study Parameters
The analysis maps pregelatinized, cross-linked, acetylated, and oxidized modification pathways, each validated through interviews with wet-milling plant managers, instant noodle procurement leads, bakery chain technical directors, and enzymatic equipment licensors. Secondary sources include FDA 21 CFR 172.892 filings, EU Green Deal Farm to Fork strategy documents, BIS certification registries, and Indonesian national food safety regulator additive standards. Bottom-up volume modeling from individual facility capacities triangulates against top-down demand segmentation from end-use industry consumption patterns.
Consistency checks against external benchmarks validated output plausibility across the projection horizon. The analytical framework models product type, end-use industry, packaging format, and quality grade segmentation dimensions alongside regional regulatory cluster differentiation. CAGRs were derived from trend extrapolation of Brabender amylograph specification adoption rates and clean-label enzymatic processing penetration curves. Forecast inputs incorporate Black Sea grain supply disruption scenarios and biotechnology regulator reassessment timelines for novel enzyme modifications.
Underlying assumptions cover sustained EU Green Deal enforcement, continued Indonesian instant noodle sector procurement consolidation, and stable enzymatic processing cost curves, with deviation risk concentrated in biotechnology approval cycle extensions and Black Sea supply normalization. Revision becomes warranted when carbon accounting mandate stringency crosses thresholds that restructure retort sauce manufacturer supplier qualification protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Phytosterols Market
Ingredients
Mannan-Oligosaccharide (MOS) Market
Ingredients
Dark Yeast Extract Market
Ingredients
Grape Seed Extracts Market
Ingredients
Pea Protein Ingredients Industry Status and Prospects Professional Market
Ingredients
Meat Tenderizer Powder Market
Ingredients
Drum to Hopper Blends Market
Ingredients
Cacao Bean Market
Ingredients
Casein Market
Ingredients
Diastatic Malt Market
Ingredients
Hydrolyzed Vegetable Protein Market
Ingredients
Rye Bran Beta-Glucan Market
Ingredients
Cosmetic Bioactive Ingredients Market
Ingredients
Canola Oil Market
Ingredients
Synephrine Market
Ingredients
Kairomones Market