
 Global Starch Derivatives Market | 2026-2036
Global Starch Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Starch Derivatives Market Outlook
The starch derivatives industry is repositioning around a widening gap between premium functional grades and commodity bulk syrups. Tate & Lyle PLC leverages its specialty ingredient portfolio to command premium positioning in pharmaceutical and food-grade segments. Cargill, Incorporated anchors global supply through its integrated corn wet-milling infrastructure across multiple continents. Roquette Freres S.A. differentiates via pea and potato starch expertise, competing outside traditional corn-based supply chains.
Starch derivatives encompass chemically, physically, or enzymatically altered starch products with modified gelatinization temperatures, viscosity profiles, or digestibility characteristics, serving primarily as functional ingredients in formulated goods. Modified starch leads product-type value pools due to its versatility across thickening and stabilizing applications, while starch syrups remain volume-dominant but face margin compression from sweetener competition. Food-grade specifications command premium pricing over industrial-grade alternatives, reflecting stricter purity and traceability requirements.
The EU Green Deal and REACH frameworks restrict synthetic additive use, redirecting formulation demand toward bio-based starch alternatives in European markets. The FDA and EFSA maintain divergent approval pathways for novel starch modifications, creating compliance complexity for multinational suppliers. Stakeholders must monitor evolving clean-label certification standards and regional carbon-accounting rules that will reshape raw-material sourcing decisions.
Market Dynamics
Clean-label formulation mandates are compressing synthetic additive demand while expanding bio-based starch derivative specifications across food, pharmaceutical, and industrial applications. This regulatory-driven substitution is restructuring supplier portfolios and raw-material sourcing priorities.
Growth Catalysts
- EU Green Deal compliance:REACH restrictions on synthetic additives redirect European food processors toward modified starch alternatives for thickening and stabilizing functions.
- Enzymatic hydrolysis advances:Next-generation enzyme platforms enable precise control over dextrose equivalent profiles, expanding specialty syrup applications in confectionery and brewing.
- Southeast Asia food processing expansion:Indonesia, Vietnam, and Thailand are scaling wet-milling capacity to serve regional instant noodle, sauce, and beverage manufacturing clusters.
Market Restraints
- Corn price volatility:Feedstock cost swings constrain margin predictability for wet-millers dependent on North American and Brazilian corn belts.
- Supply concentration in ASEAN:Tapioca starch derivative output clusters in Thailand, creating geographic single-point vulnerability for cassava-based thickeners.
- Technical ceiling in high-amylose variants:Gelatinization temperature control beyond 75°C remains inconsistent, limiting applications in retort-pouch ready meals.
Strategic Opportunities
- India FSSAI clean-label adoption:India's food safety regulator is accelerating additive substitution timelines, opening formulation partnerships with domestic dairy and bakery chains.
- Pharmaceutical excipient certification:USP-NF and EP compliance for starch-based binders and disintegrants commands 40-60% price premiums over food-grade equivalents.
- Pea-potato starch convergence:Non-GMO and allergen-free positioning outside corn supply chains attracts premium positioning in European organic and free-from product lines.
Industry Challenges
- Specialized enzymology talent scarcity:Protein engineering and carbohydrate biochemistry expertise pools are shallow relative to biotech and pharma competition for the same skill sets.
- Retrogradation control IP complexity:Patent thickets around cross-linking chemistries and esterification processes create licensing friction for new market entrants.
- Wet-milling capex intensity:Fractionation, refining, and drying infrastructure requires substantial capital deployment with 7-10 year payback horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Starch Derivatives Market |
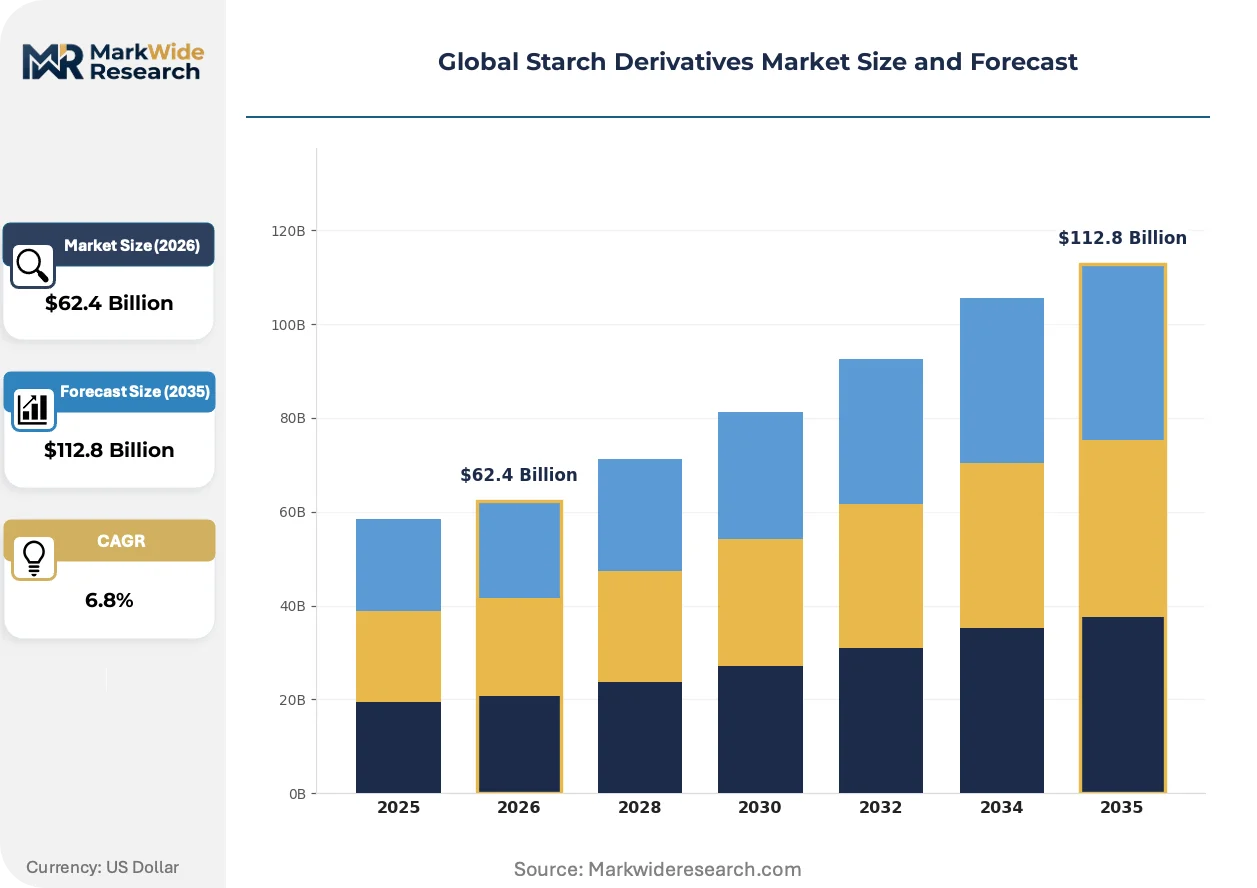
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $112.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modified Starch, Native Starch, Starch Syrup, Starch Ether End User: Food & Beverage, Pharmaceuticals, Paper & Pulp, Textiles Application: Thickening Agent, Stabilizer, Filler, Sweetener Grade: Food Grade, Industrial Grade, Pharmaceutical Grade, Feed Grade |
| Companies Covered | Tate & Lyle PLC, AGRANA Beteiligungs-AG, Archer Daniels Midland Company, Avebe U.A., Sudzucker Group, Cargill, Incorporated, Roquette Freres S.A., Tereos S.A., Ingredion Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Starch Derivatives Market Strategic Shifts
Dual-track innovation is separating markets: commodity syrup volumes consolidate while functional modified starches fragment into application-specific performance tiers. Technology investment concentrates on precision modification and carbon-accounted sourcing.
Enzymatic debranching combined with controlled retrogradation is unifying texture design across clean-label and conventional formulation platforms. Food manufacturers in Western Europe and North America are adopting these enzymatic routes at accelerated pace to eliminate chemical modification declarations. The structural consequence is unifying previously separate premium and mass-market ingredient specifications under single production trains.
REACH authorization timelines for borates and formaldehyde-based cross-linkers are tightening substitution deadlines for industrial textile and paper applications. ECHA's restriction proposals are forcing reformulation toward citrate and adipate ester alternatives in sizing and coating operations. Specialty paper mills in Germany, France, and the Netherlands are responding fastest, locking in multi-year supply contracts for compliant starch derivatives.
Ingredient procurement is consolidating through direct supplier relationships as large food manufacturers bypass distributors for modified starch and maltodextrin volumes. Regional procurement teams at multinational CPG companies are replacing spot-market purchasing with annual framework agreements specifying carbon intensity and traceability documentation. This pattern is most visible in Nordic markets where retailer sustainability scorecards mandate supply-chain transparency down to farm-level sourcing.
Global Starch Derivatives Market Segmentation
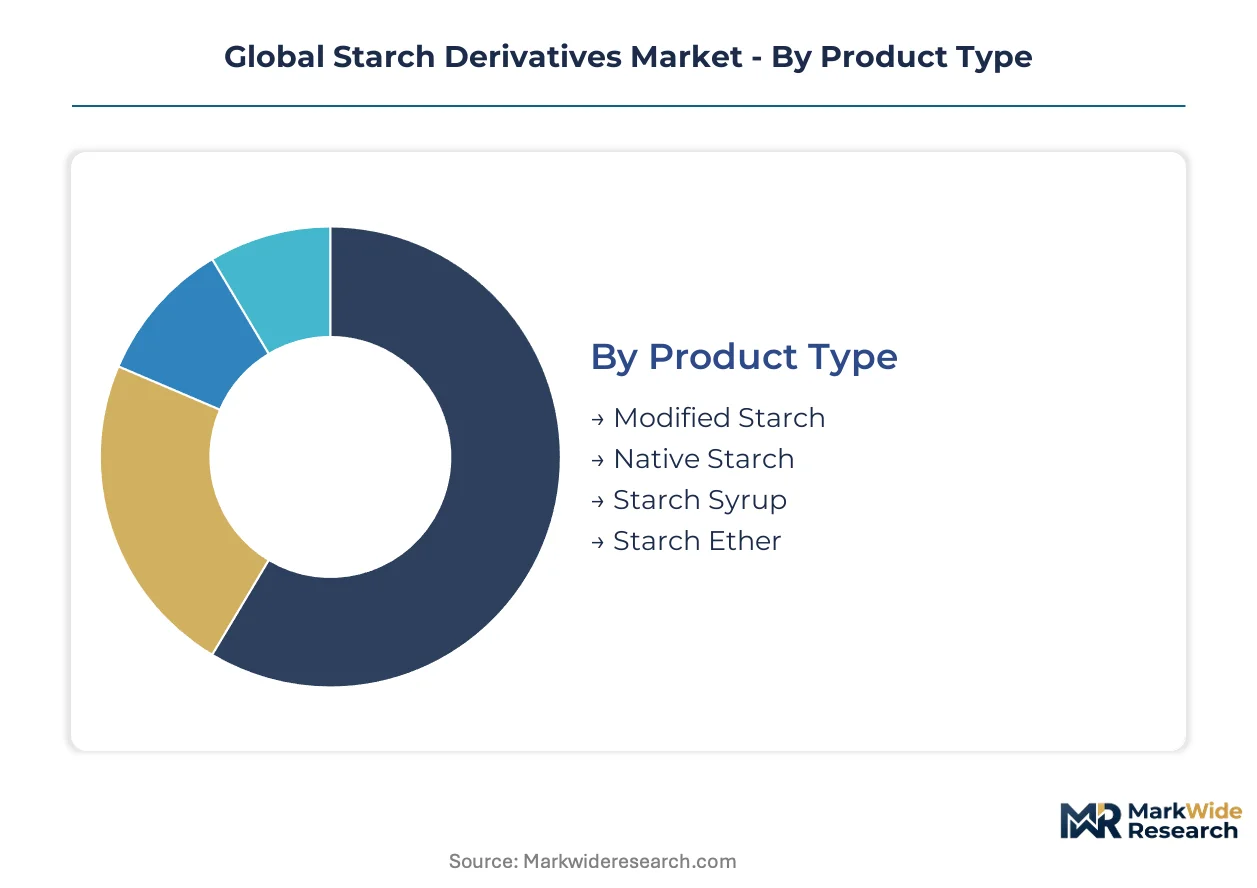
Starch derivative specifications diverge sharply across certification tiers, with pharmaceutical and food-grade segments commanding compliance burdens that reshape supplier economics. Understanding these segmentation boundaries clarifies why premium grades sustain margin structures unavailable to commodity alternatives.
Product Type:
Certification requirements intensify from native starch through chemically modified variants, with pharmaceutical and food-grade modified starches facing the most rigorous FDA and EFSA scrutiny.
- Modified Starch:Chemically, physically, or enzymatically altered to achieve specific gelatinization temperatures, viscosity profiles, or acid stability. Pharmaceutical tablet binders and clean-label food thickeners in Germany and France drive premium specifications requiring full EFSA additive authorization and USP-NF compliance documentation.
- Native Starch:Unmodified extraction from corn, tapioca, potato, or wheat retaining natural granular structure. Indonesian and Thai wet-millers supply regional instant noodle manufacturers with minimal regulatory burden beyond basic food safety registration.
- Starch Syrup:Enzymatic hydrolysis products ranging from maltodextrins to high-dextrose glucose syrups. Brewing and confectionery applications in Belgium and Netherlands concentrate volume demand.
- Starch Ether:Etherified derivatives for construction and textile sizing. REACH authorization for hydroxyethyl and hydroxypropyl grades creates formulation substitution pressure in EU building materials.
Starch syrup sits at the top of the volume ranking, with modified starch climbing the fastest.
End User:
Customer procurement sophistication separates pharmaceutical quality systems from industrial spot purchasing, creating tiered service requirements within supplier portfolios.
- Food & Beverage:Clean-label mandates across dairy, bakery, and sauce applications. EU Green Deal compliance redirects European processors toward enzymatically modified alternatives free from chemical process declarations.
- Pharmaceuticals:Excipient-grade starches for tablet binders, disintegrants, and capsule fillers. USP-NF and EP certification requirements command 40-60% price premiums over food-grade equivalents with mandatory ICH Q7 GMP audits.
- Paper & Pulp:Surface sizing and coating operations. German and French specialty mills lock in multi-year contracts for REACH-compliant citrate ester alternatives to restricted borates.
- Textiles:Warp sizing and fabric finishing. ECHA restriction proposals on formaldehyde-based cross-linkers accelerate adipate ester substitution timelines.
Food and beverage dominates absolute volume, with pharmaceuticals expanding most quickly.
Application:
Functional performance requirements determine whether enzymatic or chemical modification routes prove economically viable for specific rheological targets.
- Thickening Agent:Viscosity development in sauces, soups, and dairy desserts. Southeast Asian sauce manufacturers in Vietnam and Thailand scale enzymatic processing to meet clean-label export specifications.
- Stabilizer:Freeze-thaw resistance and emulsion maintenance. Ice cream and frozen dessert formulators in Italy and Spain prioritize modified waxy maize with specific amylopectin branching patterns.
- Filler:Bulking and compression aid in pharmaceuticals and processed foods. Direct compression tableting in Indian generic drug manufacturing concentrates demand for pregelatinized excipient grades.
- Sweetener:Glucose and maltose syrup supply for confectionery and brewing. Brazilian and US corn wet-millers compete on dextrose equivalent precision for beverage alcohol fermentation.
Thickening applications anchor volume consumption, with stabilizer functions gaining share fastest.
Grade:
Regulatory jurisdiction fragmentation creates parallel compliance tracks, with pharmaceutical and food-grade segments requiring distinct audit and documentation systems.
- Food Grade:Codex Alimentarius and national food safety compliance. FSSAI clean-label adoption in India accelerates additive substitution partnerships with domestic dairy and bakery chains.
- Industrial Grade:Performance specifications without ingestion safety requirements. Paper and textile sizing applications in Poland and Czech Republic prioritize viscosity stability over purity metrics.
- Pharmaceutical Grade:Full pharmacopeial compliance with elemental impurity and microbial limits. US FDA and EMA inspections dominate supplier qualification timelines.
- Feed Grade:Animal nutrition applications with mycotoxin and contamination thresholds. Brazilian and Argentine feed compounders integrate cassava-based derivatives into poultry and swine rations.
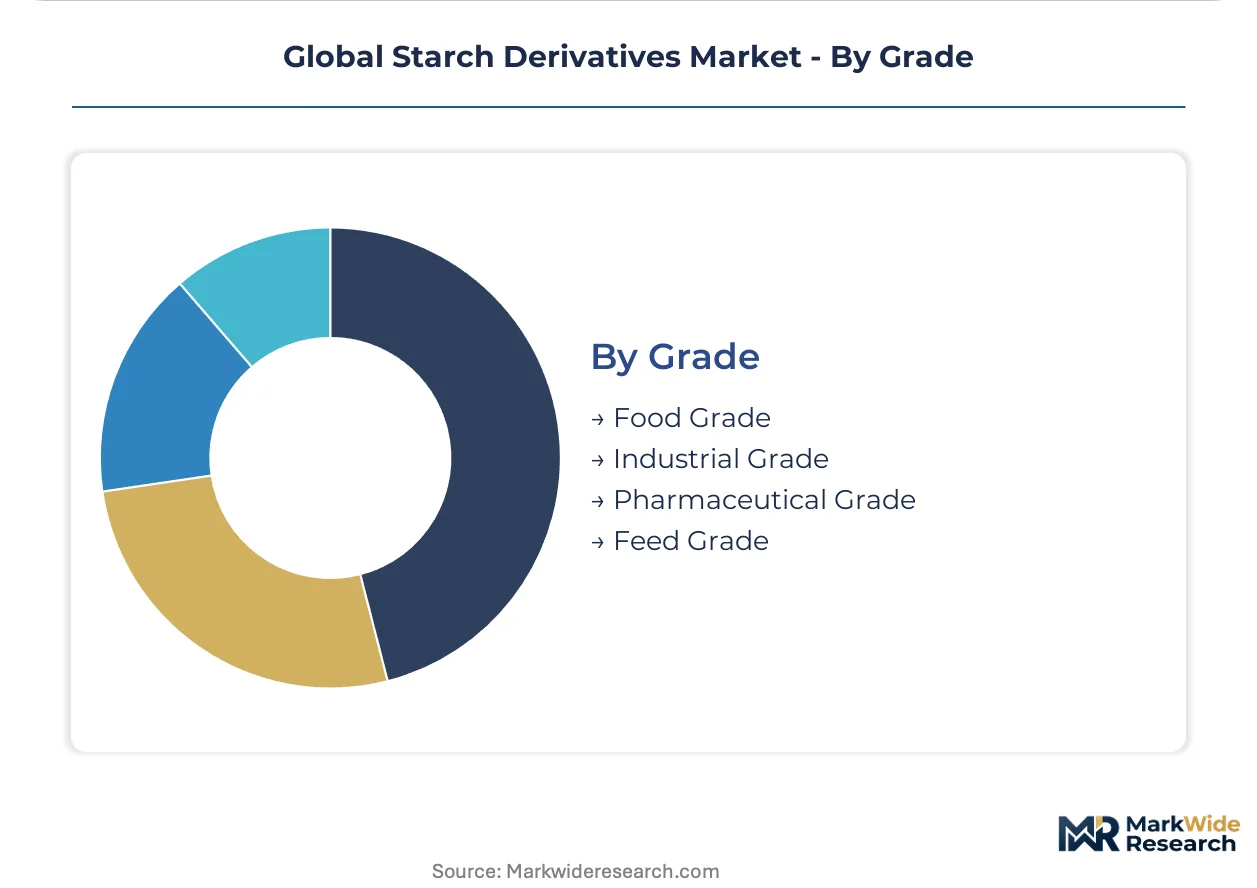
Food grade maintains volume leadership, with pharmaceutical grade showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand commands cassava-based starch derivative output while the United States anchors corn wet-milling infrastructure, creating divergent feedstock dependencies across major producing zones.
United States
Corn wet-millers in Iowa and Illinois supply modified starches to CPG manufacturers pursuing clean-label reformulations. FDA maintains distinct approval pathways for novel starch modifications compared to European counterparts. Processing clusters along the Mississippi River corridor integrate fractionation and drying infrastructure to serve domestic food and pharmaceutical demand.
Germany
Specialty paper mills in North Rhine-Westphalia lock in multi-year contracts for REACH-compliant citrate ester alternatives to restricted borates. ECHA restriction proposals on formaldehyde-based cross-linkers accelerate adipate ester substitution timelines. Cologne and Düsseldorf serve as formulation hubs where starch derivative suppliers coordinate with textile and packaging converters.
China
Domestic sauce and instant noodle manufacturers scale enzymatic processing to meet export specifications for Southeast Asian markets. SAMR enforces GB standards for food additive usage that diverge from Codex Alimentarius frameworks. Shandong Province wet-millers expand capacity to serve regional brewing and confectionery clusters.
India
FSSAI clean-label adoption accelerates additive substitution partnerships with domestic dairy and bakery chains in Maharashtra and Gujarat. CDSCO maintains separate excipient registration requirements for pharmaceutical-grade starches used in generic drug manufacturing. Mumbai-Pune pharmaceutical corridors concentrate demand for pregelatinized binder grades.
Thailand
Tapioca starch derivative output clusters in the Central Plains region, creating geographic single-point vulnerability for cassava-based thickeners. Thai FDA alignment with ASEAN harmonization protocols streamlines cross-border trade with Indonesian and Vietnamese processors. Bangkok-based exporters coordinate with regional instant noodle and sauce manufacturing facilities.
Global Starch Derivatives Market Competitive Environment
Top-tier vendors anchor pharmaceutical and food-grade certification tiers, while commodity syrup producers compete on dextrose equivalent precision and feedstock proximity. The vendor base separates into integrated agricultural processors, specialty ingredient formulators, and regional wet-milling operators. Strategic archetypes include corn-based volume players, pea-potato differentiation specialists, and enzymatic modification technology holders. Competitive moves concentrate on backward integration into captive corn supply and multi-year framework agreements specifying carbon intensity documentation.
Within the specialty modification tier, Tate & Lyle PLC and Roquette Freres S.A. exemplify divergent feedstock strategies outside traditional corn dependence, while Cargill, Incorporated occupies a position representing integrated agricultural processing scale. These three anchors illustrate how certification burdens and clean-label positioning separate premium-grade suppliers from commodity alternatives.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| AGRANA Beteiligungs-AG |
| Archer Daniels Midland Company |
| Avebe U.A. |
| Sudzucker Group |
| Cargill, Incorporated |
| Roquette Freres S.A. |
| Tereos S.A. |
| Ingredion Inc. |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal compliance gates qualified supply and premium-tier pricing access, as REACH-authorized modified starch derivatives command 40-60% markups over industrial grades while excluding uncertified wet-millers from pharmaceutical and clean-label food procurement pools. Buyers in Germany and France now mandate carbon-accounted sourcing documentation that compresses spot-market participation and locks in multi-year framework agreements with audit-ready suppliers.
Pricing Analysis
Capacity additions in Vietnam and Indonesia are reshaping price floors for commodity starch syrups, intensifying margin compression across dextrose-equivalent bulk grades. Three-tier pricing structure across pharmaceutical, food-grade, and industrial levels separates USP-NF certified excipients from FSSAI-registered food additives and uncertified feedstock derivatives. Pricing pressure stems from enzymatic hydrolysis technology diffusion that commoditizes mid-tier maltodextrin specifications. Industrial paper and textile buyers exhibit highest price sensitivity, while pharmaceutical formulators absorb premium markups for excipient-grade traceability.
Supply Chain Analysis
Dual-sourcing requirements now dominate procurement protocols as CPG manufacturers in Western Europe and North America mandate qualified backup suppliers for modified starch volumes. Geographic supply concentrates in Thailand, the United States, and China, with cassava wet-milling anchored in Thai Central Plains and corn fractionation clustering along Iowa-Illinois river corridors. Raw material dependencies rest on Brazilian and North American corn belts, Thai cassava harvests, and Indian potato starch processing. Single-source vulnerability runs through Thai tapioca derivatives, where geographic concentration creates disruption exposure. Distribution runs through direct supplier relationships as large manufacturers bypass distributors for annual framework contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with EU Green Deal additive substitution timelines and REACH authorization deadlines continuously restructuring qualified supplier pools and premium pricing tiers.
For Market Incumbents: Deepen backward integration into captive corn supply in Iowa and Illinois to defend margin position against Brazilian feedstock volatility. Lock in multi-year pharmaceutical excipient contracts with Mumbai-Pune generic drug manufacturers before CDSCO registration requirements tighten. Prioritize enzymatic modification IP acquisition to eliminate chemical process declarations from clean-label customer formulations. For New Entrants and Emerging Players: Capture FSSAI clean-label adoption momentum in Maharashtra and Gujarat dairy chains, where domestic bakery and sauce manufacturers seek additive substitution partners without established supplier relationships. Pea-potato starch convergence offers the most penetrable white-space, as European organic and free-from product lines demand non-GMO alternatives outside corn supply chains. Lead with carbon-accounted sourcing documentation to qualify for Nordic retailer sustainability scorecards. For Investors and Strategic Acquirers: Roll-up economics work for enzymatic modification technology holders because patent thickets around cross-linking chemistries create licensing friction that favors consolidated IP portfolios. Five-to-ten-year viability hinges on positioning ahead of pharmaceutical excipient certification waves and clean-label regulatory harmonization across ASEAN markets. Watch Indian FSSAI enforcement intensity as the signal for additive substitution acceleration timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Supply | Iowa-Illinois wet-millers secure margin stability against Brazilian price volatility. |
| Pharmaceutical Excipient Certification | USP-NF compliance unlocks 40-60% price premiums in Mumbai-Pune corridors. |
| Enzymatic Modification Technology Acquisition | Eliminates chemical process declarations for EU clean-label formulations. |
| Pea-Potato Starch Capacity Expansion | Non-GMO positioning captures European organic free-from product demand. |
| Carbon-Accounted Sourcing Partnerships | Nordic retailer scorecards mandate farm-level traceability documentation. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with wet-milling plant managers, procurement leads at multinational CPG manufacturers, pharmaceutical formulation scientists, and specialty paper mill technical directors with secondary validation. Trade data from customs authorities, starch industry association reports, SEC filings from listed agricultural processors, and ECHA restriction proposal documentation anchored supply-side assessment. Bottom-up capacity modeling and top-down demand segmentation triangulated market sizing across product categories.
Segment-weighting approaches applied differential growth assumptions across modified starch, native starch, starch syrup, and starch ether categories, with further granularity by food-grade, pharmaceutical-grade, industrial-grade, and feed-grade certification tiers. End-use splits modeled food and beverage, pharmaceutical, paper and pulp, and textile applications separately. CAGRs derived from regression analysis against feedstock price indices, regulatory enforcement timelines, and regional processing capacity buildouts. Enzymatic hydrolysis technology diffusion rates and REACH substitution deadlines served as key forecast inputs.
Feedstock price volatility, regulatory authorization delays, and enzymology talent scarcity are the dominant revision risks that could compress or extend projected expansion trajectories. Forecasts reflect documented assumptions about clean-label adoption velocity and pharmaceutical certification harmonization across jurisdictions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Bouillon Cubes Market
Ingredients
Commercial Amino Acids Market
Ingredients
Dry Brewing Ingredients Market
Ingredients
North America Dairy Ingredients Market
Ingredients
PHO Oils Market
Ingredients
United States Avocado Oil Market
Ingredients
Vitamin C Ingredients Market
Ingredients
Cooking Oil Market
Ingredients
Notoginseng Root Extract Market
Ingredients
Coconut Derivatives Market
Ingredients
Spelt Flour Market
Ingredients
Psyllium Husk Powder Market
Ingredients
Global Cocoa Products Market
Ingredients
Arachidonic Acid Market
Ingredients
L-Arabinose Market
Ingredients
Jojoba Oil Market