
 Potato Granules Market | 2026-2036
Potato Granules Market Size, Share, and Industry Trends Forecast 2026-2036
Potato Granules Market Analytics
Multi-source procurement toward contracted potato supply is consolidating among North American processors. McCain Foods Limited leverages backward integration into potato farming to secure raw material throughput. Lamb Weston Holdings, Inc. competes through manufacturing scale across multiple production facilities. Idahoan Foods, LLC specializes in instant-format technology that reduces rehydration time for foodservice operators.
Potato granules consist of dehydrated potato cells, typically manufactured through drum-drying or extrusion processes to achieve moisture content below 7 percent, serving primarily as a shelf-stable base for mashed potato products, snack formulations, and convenience food applications. The instant potato granules category dominates volume due to foodservice demand for rapid-preparation solutions, while organic potato granules command premium positioning in European retail channels where EFSA labeling requirements influence purchasing. Dehydrated potato granules sustain steady industrial uptake from snack manufacturers seeking consistent starch functionality.
The FDA governs food additive standards and labeling requirements for potato granules distributed in the United States, while REACH compliance shapes chemical safety documentation for processing aids used in European manufacturing facilities. BIS certification requirements in India affect import specifications for dehydrated potato products entering that market. Stakeholders must monitor evolving allergen disclosure mandates and carbon footprint reporting obligations as procurement criteria tighten across institutional buyers.
Market Dynamics
EU Green Deal agricultural processing standards are tightening dehydration energy thresholds and carbon disclosure requirements across European manufacturing, forcing capital retooling toward heat-recovery drum-drying systems.
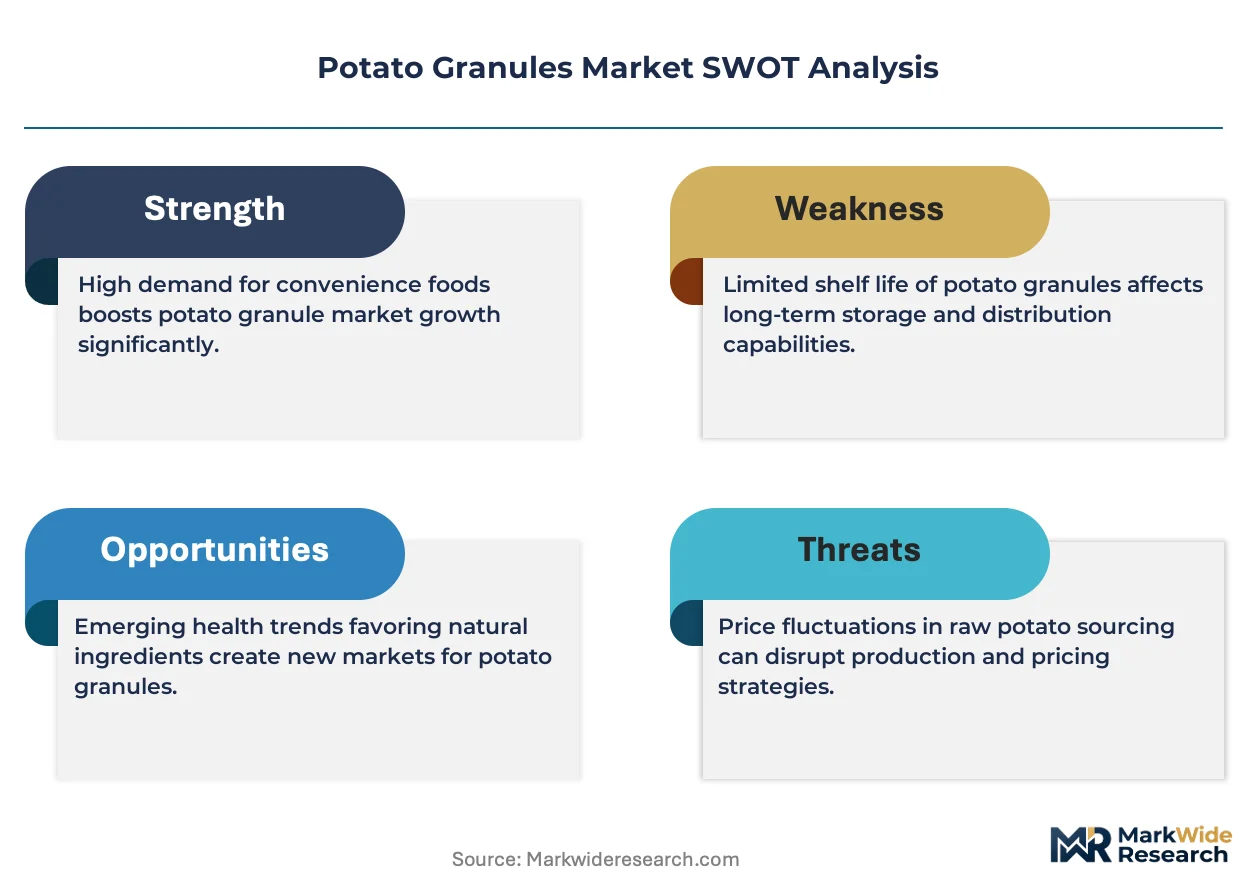
Growth Catalysts
- Foodservice operational efficiency mandates:Institutional kitchens in Germany prioritize rapid-rehydration formats to reduce labor hours and equipment needs.
- REACH chemical safety documentation:Processing aid transparency requirements accelerate adoption of clean-label potato granule formulations in European retail channels.
- Snack manufacturer procurement consolidation:North American processors expand contracted potato supply agreements to secure consistent starch functionality for extruded snack bases.
Market Restraints
- Natural gas price volatility:Drum-drying operations depend on thermal energy inputs subject to European wholesale gas market fluctuations.
- Fresh potato supply concentration:Processing-grade potato cultivation clusters in Idaho and the Netherlands create geographic vulnerability to regional weather events.
- Instant format substitution threat:Fresh-chilled mashed potato products gain refrigerated distribution shelf space in UK and French retail.
Strategic Opportunities
- Underpenetrated Indian food processing:BIS certification alignment enables import qualification for dehydrated potato products targeting quick-service restaurant chains.
- EU Green Deal carbon accounting incentives:Processors investing in renewable thermal energy capture qualify for preferential procurement scoring by institutional buyers.
- E-commerce direct-to-foodservice channels:Specialty distributors bypass traditional broadline networks to serve independent restaurant operators with customized granule specifications.
Industry Challenges
- Dehydration engineering talent scarcity:Drum-drying optimization and moisture-content control expertise concentrates among aging specialist technicians.
- Legacy ERP integration friction:Batch traceability systems for EU Green Deal compliance require costly middleware upgrades at mid-scale processing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potato Granules Market |
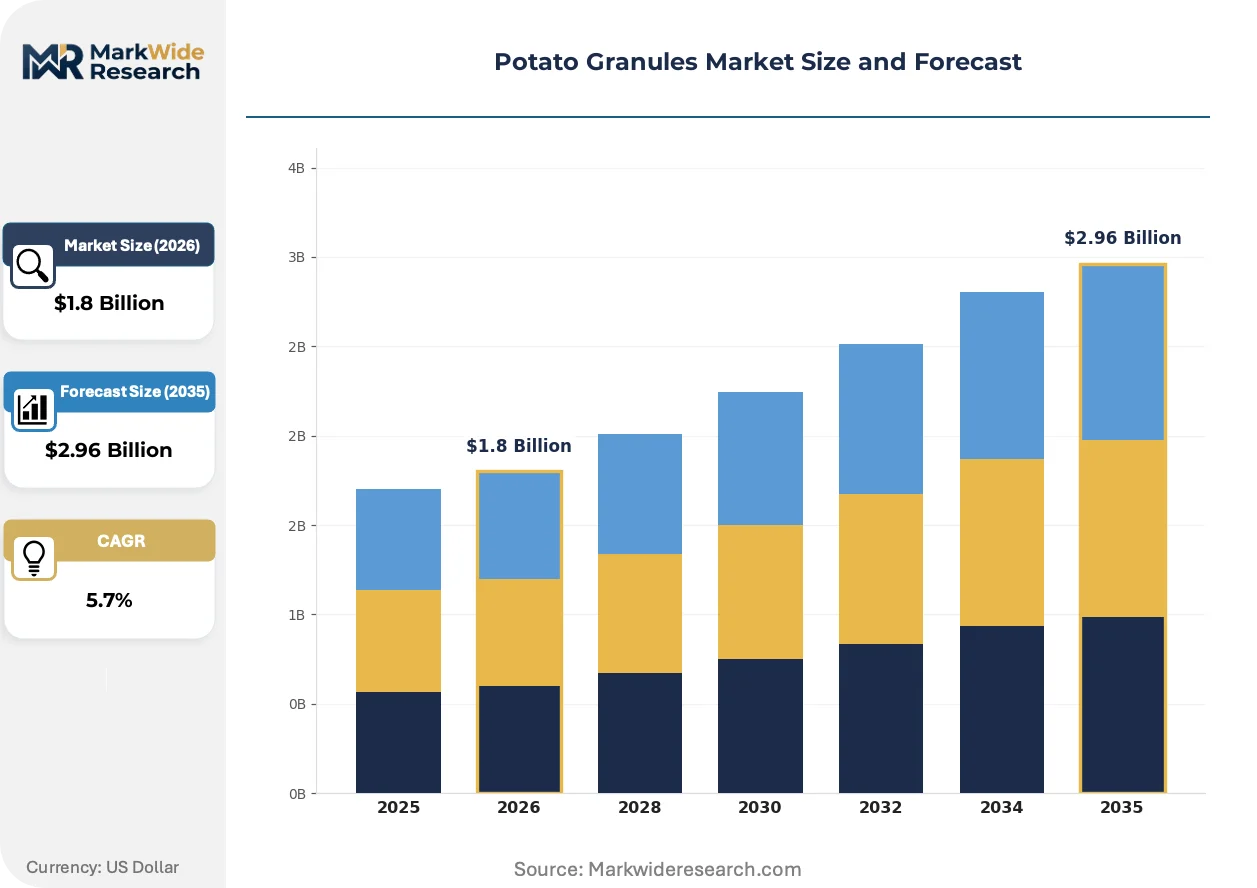
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Potato Granules, Dehydrated Potato Granules, Organic Potato Granules, Conventional Potato Granules End Use: Food Industry, Snack Manufacturers, Convenience Foods, Hospitality Sector Packaging Type: Bulk Packaging, Retail Packaging, Pouches, Containers Distribution Channel: Online Retail, Grocery Stores, Wholesalers, Specialty Stores |
| Companies Covered | McCain Foods Limited, Lamb Weston Holdings, Inc., Idahoan Foods, LLC, Aviko B.V., Basic American Foods, Idaho Pacific, Emsland Group, Procordia Food AB, R. Simplot Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potato Granules Market Evolving Landscape
Processing technology convergence and regulatory carbon accounting are compressing equipment replacement cycles while reshaping how manufacturers document energy and chemical inputs across supply chains.
Advanced heat-recovery drum-drying systems is unifying thermal efficiency with moisture-content precision in potato granule production. Foodservice distributors in Germany adopt these systems to meet EU Green Deal energy thresholds. The technology is unifying capital equipment decisions with carbon disclosure obligations, compressing payback period calculations for processor upgrade decisions.
REACH chemical safety documentation expansion now mandates processing aid disclosure down to 0.1 percent concentration thresholds in European manufacturing facilities. Industrial buyers increasingly require full material transparency for clean-label product positioning. Snack manufacturers sourcing from Dutch and German processors face the most intensive audit requirements, driving pre-qualification consolidation among suppliers with established documentation systems.
Foodservice procurement is compressing supplier rosters toward single-source contracts with integrated traceability reporting. Independent restaurant operators previously served by fragmented distributors now consolidate purchases through platforms offering lot-level carbon footprint data. This concentration pattern is most visible in German and French institutional catering contracts, where procurement officers prioritize documentation completeness over unit price negotiation.
Potato Granules Market Segmentation
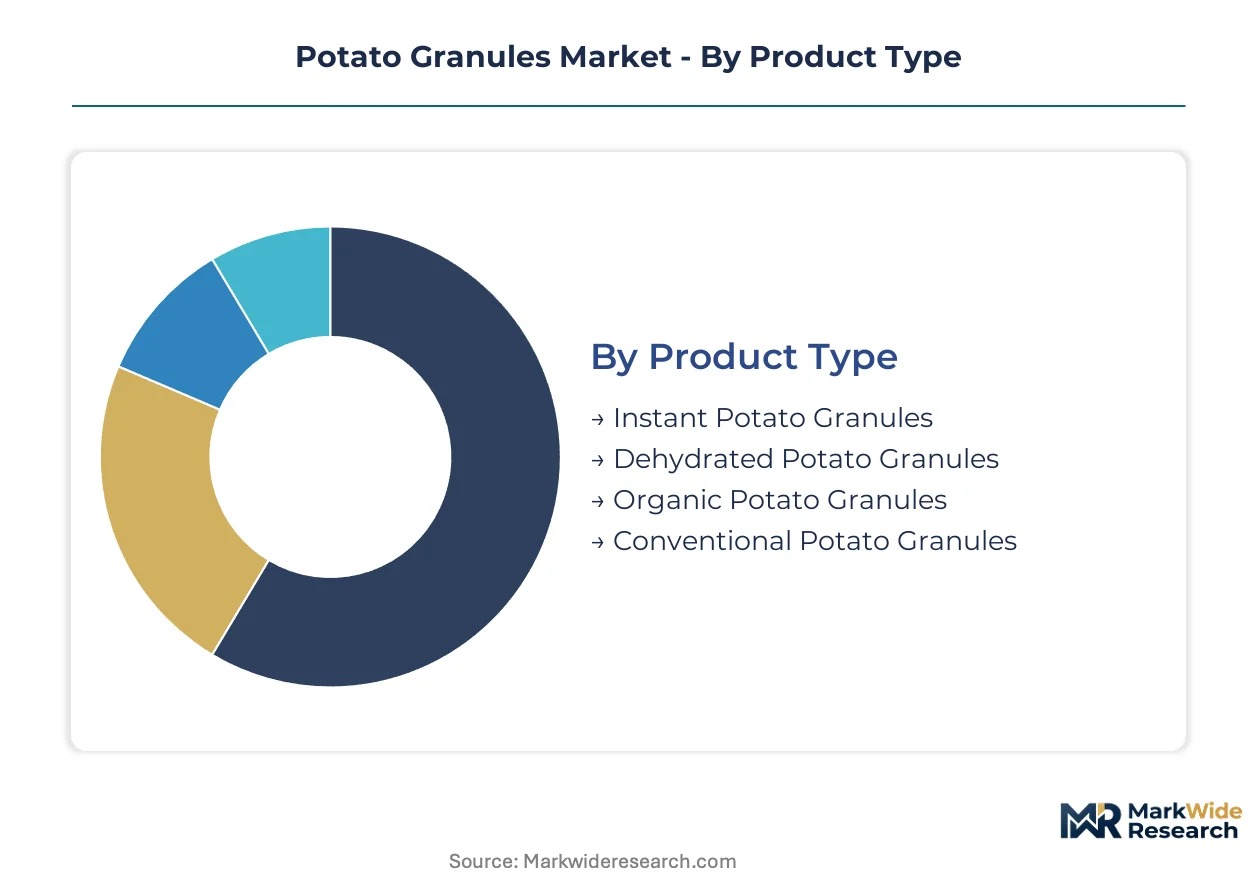
Potato granule segmentation reflects divergent compliance burdens across product formats and end-use applications. Certification requirements from FDA, EFSA, and BIS create tiered entry barriers that reshape competitive positioning in each category.
Product Type:
Certification-burden intensity varies sharply: instant formats face foodservice safety audits, organic variants require EFSA-accredited certification, while conventional grades navigate baseline FDA or BIS documentation.
- Instant Potato Granules:Rapid-rehydration formulations achieve moisture content below 7 percent through optimized drum-drying parameters. Demand concentrates in German foodservice distribution where operational efficiency mandates prioritize labor reduction and equipment minimization.
- Dehydrated Potato Granules:Standardized shelf-stable base material manufactured through controlled thermal dehydration processes. Industrial uptake from snack manufacturers in the Netherlands and Idaho clusters around consistent starch functionality for extruded product formulations.
- Organic Potato Granules:EFSA labeling compliance and accredited organic certification create premium positioning in European retail channels.
- Conventional Potato Granules:Baseline formulations without organic certification serve price-sensitive institutional procurement in India and North America.
Leading the category by volume: Dehydrated Potato Granules. Growing fastest: Organic Potato Granules.
End Use:
Cost-tier stratification separates high-documentation institutional contracts from lower-margin commodity supply to snack processors.
- Food Industry:Ingredient supply to processed food manufacturers requiring batch traceability and allergen disclosure documentation. REACH compliance and EU Green Deal carbon accounting drive pre-qualification consolidation toward suppliers with integrated ERP systems.
- Snack Manufacturers:Extruded snack base applications demand precise starch gelatinization characteristics and consistent particle size distribution. Procurement consolidation among North American processors favors contracted potato supply agreements with backward-integrated suppliers.
- Convenience Foods:Shelf-stable meal components targeting retail and foodservice channels with rapid-preparation positioning.
- Hospitality Sector:Hotel and catering operations in Germany and France prioritize single-source contracts with lot-level carbon footprint reporting.
Highest margin concentration: Snack Manufacturers. Steepest expansion trajectory: Hospitality Sector.
Packaging Type:
Volume scale and customer type determine packaging investment: bulk formats serve industrial procurement, retail-facing formats absorb higher unit costs for shelf presence.
- Bulk Packaging:Industrial tote and super-sack configurations for food manufacturers and snack processors purchasing at truckload scale. German distributors favor bulk procurement for operational efficiency in high-throughput institutional kitchens.
- Retail Packaging:Consumer-facing cartons and bags requiring EFSA-compliant nutritional labeling and shelf-life declarations.
- Pouches:Flexible single-serve and family-size formats for convenience food retail channels.
- Containers:Rigid packaging for premium organic granules in European specialty retail.
Dominant by throughput: Bulk Packaging. Gaining share fastest: Pouches.
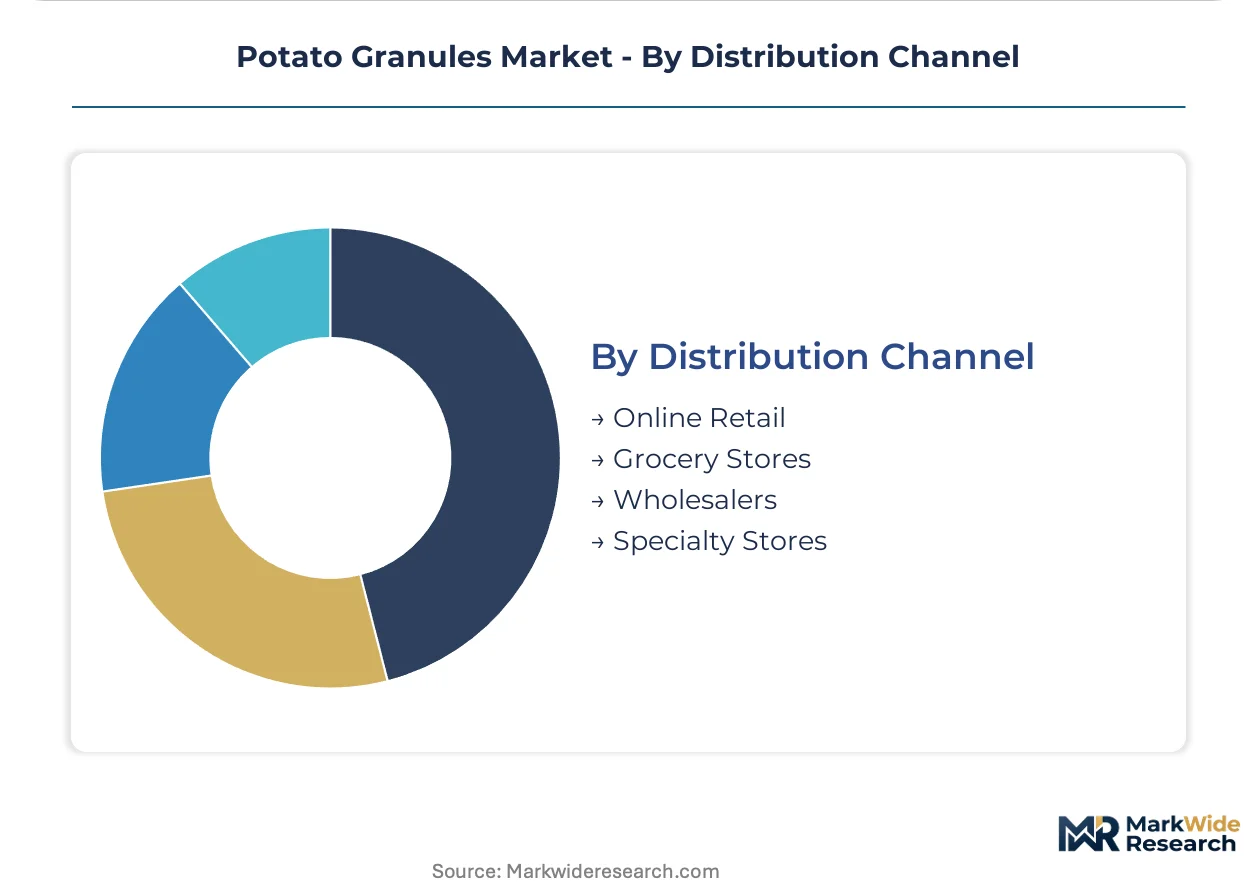
Distribution Channel:
Geographic concentration of demand shapes channel strategy: German foodservice clusters drive wholesale consolidation, while Indian market development favors online retail experimentation.
- Online Retail:Direct-to-foodservice platforms bypass traditional broadline networks to serve independent restaurant operators with customized granule specifications and carbon footprint documentation.
- Grocery Stores:Mass retail placement for instant and organic formats requires slotting fee investment and promotional support.
- Wholesalers:Broadline distributors dominate German and French institutional catering procurement with integrated traceability reporting.
- Specialty Stores:Premium organic positioning in European natural food retailers with educated consumer bases.
Channel leader by volume: Wholesalers. Expanding most quickly: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foodservice procurement concentrates in Germany, where institutional kitchens favor rapid-rehydration formats for labor efficiency. Snack manufacturing clusters in Idaho and the Netherlands drive industrial demand for consistent starch functionality. Processing standards under the EU Green Deal reshape capital investment patterns across European dehydration facilities.
United States
Idaho's processing-grade potato cultivation anchors North American supply, with drum-drying facilities concentrated in the Magic Valley region. FDA food additive standards govern labeling and safety documentation for interstate distribution. Snack manufacturers in the Midwest expand contracted supply agreements to secure extruded product base materials.
Germany
Institutional catering operations in Bavaria and North Rhine-Westphalia prioritize single-source procurement with integrated carbon footprint reporting. EU Green Deal energy thresholds force retooling toward heat-recovery drum-drying systems. Foodservice distributors in the Frankfurt-Rhine-Main cluster consolidate purchases through platforms offering lot-level traceability data.
Netherlands
Friesland and Flevoland provinces host dehydration facilities serving European snack and convenience food channels. REACH chemical safety documentation mandates processing aid disclosure down to 0.1 percent concentration. Rotterdam-area processors face intensive audit requirements from industrial buyers seeking clean-label positioning.
India
Quick-service restaurant chains in Maharashtra and Karnataka drive import qualification efforts for dehydrated potato products. BIS certification requirements shape specifications for foreign suppliers entering the market. Food processing investment concentrates in the Delhi-NCR corridor as operators seek shelf-stable ingredient alternatives.
France
Fresh-chilled mashed potato products gain refrigerated distribution shelf space in Île-de-France retail, pressuring instant format substitution. EFSA labeling requirements influence organic granule positioning in Parisian specialty channels. Hospitality procurement in Lyon and Marseille prioritizes documentation completeness over unit price negotiation.
Potato Granules Market Competitive Landscape
Backward integration into potato farming dominates the current landscape as processors secure raw material throughput. The market exhibits moderate consolidation, with large-scale integrated processors occupying tier-one positions alongside specialized dehydration technology firms and regional ingredient suppliers. Three archetypes define competitive positioning: vertically integrated agricultural processors, manufacturing-scale specialists with multi-facility networks, and instant-format technology developers. Capacity expansion and strategic procurement consolidation represent the dominant competitive moves as firms respond to foodservice operational efficiency mandates.
Within the integrated processor tier, McCain Foods Limited and Lamb Weston Holdings, Inc. exemplify backward-integrated structures with captive agricultural supply chains. Idahoan Foods, LLC occupies a position among technology-specialized operators focused on rapid-rehydration solutions. These three entities represent distinct strategic postures: agricultural integration at scale, manufacturing footprint breadth, and format-specific innovation capability.
| Leading Market Players |
|---|
| McCain Foods Limited |
| Lamb Weston Holdings, Inc. |
| Idahoan Foods, LLC |
| Aviko B.V. |
| Basic American Foods |
| Idaho Pacific |
| Emsland Group |
| Procordia Food AB |
| R. Simplot Company |
| Others |
Value Network & Pricing Analysis
EU Green Deal carbon accounting thresholds now gate qualified supply access for European dehydration facilities, simultaneously filtering premium-tier pricing eligibility toward processors with heat-recovery drum-drying investments. Foodservice procurement officers in Germany and France increasingly disqualify suppliers lacking lot-level energy disclosure, compressing margin capture toward documented producers while marginalizing conventional operators.
Pricing Analysis
Volume-scale dehydrated granules trade at commodity-thin margins while instant and organic formats capture premium spreads. Three-tier pricing structure across premium, standard, and economy levels reflects EFSA certification status, rehydration speed performance, and carbon footprint documentation completeness. Pricing pressure stems from natural gas cost volatility in European thermal processing, squeezing drum-drying operators without renewable energy hedging. Snack manufacturers exhibit lowest price sensitivity due to starch functionality requirements, whereas Indian institutional buyers prioritize unit cost minimization over certification premiums.
Supply Chain Analysis
Processing-grade potato supply rests on cultivation clusters in Idaho, the Netherlands, and Germany's Lower Saxony region. Drum-drying operations draw from natural gas inputs, specialized dehydration engineering talent pools, and REACH-compliant processing aid inventories. Single-source geographic concentration creates weather-event vulnerability across the Magic Valley and Friesland production belts. Distribution runs through German wholesale networks for foodservice, direct-platform channels for independent restaurants, and bulk tote configurations for industrial snack processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive potato farming control determines raw material security against processing-grade supply volatility. Players are pursuing backward integration into agricultural supply as the decisive upstream lever.
For Market Incumbents: Deepen heat-recovery drum-drying retrofit investments to secure EU Green Deal procurement qualification before 2027 compliance deadlines. Expand contracted potato supply agreements in Idaho and the Netherlands to buffer against regional weather concentration risk. Prioritize ERP traceability system upgrades to meet REACH documentation mandates at 0.1 percent processing aid disclosure thresholds.
For New Entrants and Emerging Players: BIS certification alignment in India opens a window for dehydrated potato import qualification targeting quick-service restaurant chains in Maharashtra and Karnataka. Penetrate the underdeveloped Indian food processing segment through direct-platform distribution bypassing traditional broadline networks. Lead with carbon footprint documentation as the differentiated go-to-market angle for European institutional catering contracts.
For Investors and Strategic Acquirers: Accelerating EU Green Deal enforcement actions against non-compliant dehydration facilities is the leading indicator that consolidation pressure will intensify toward documented producers. Position acquisition screening toward mid-scale processors with installed heat-recovery systems and established organic certification pathways. Watch for natural gas price spike persistence as the signal that thermal energy cost structure will reshape competitive viability across European manufacturing footprints.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Potato Farming | McCain Foods and Lamb Weston anchor supply security through captive agricultural production in Idaho and Alberta. |
| Heat-Recovery Drum-Drying Retrofit | German processors qualify for EU Green Deal preferential procurement scoring by institutional buyers. |
| BIS Certification Alignment | Foreign suppliers unlock import qualification for India's quick-service restaurant dehydration demand. |
| Direct-to-Foodservice Platform Launch | Specialty distributors bypass broadline networks to serve independent restaurants with customized specifications. |
| Organic Granule Line Extension | EFSA-accredited certification captures premium positioning in Parisian and Amsterdam specialty retail channels. |
Research Methodology
Document review covered FDA food additive standards, EU Green Deal technical guidance, REACH chemical safety documentation, and BIS certification specifications, complemented by interviews with dehydration plant managers, foodservice procurement directors at German institutional caterers, snack manufacturer R&D leads, and Dutch agricultural cooperative representatives. Secondary validation drew from customs trade data, SEC processor filings, EFSA labeling guidance, and industry dehydration technology literature. Bottom-up facility capacity modeling and top-down end-use demand estimation provided cross-referencing triangulation.
Historical volume trajectories were cross-referenced against expert panel input on EU Green Deal compliance timelines and natural gas cost assumptions across the projection horizon. Segmentation modeling captured product type differentiation, end-use application requirements, packaging format scale economics, and distribution channel concentration patterns. CAGRs were derived from fitted growth curves applied to baseline demand estimates, incorporating foodservice operational efficiency mandates and snack manufacturer procurement consolidation trends as primary demand drivers.
The model assumes a particular technology adoption path for heat-recovery drum-drying penetration; alternative pathways for conventional thermal dehydration retention would alter the outlook for European processor cost structures and competitive positioning. Forecasts reflect documented assumptions regarding regulatory enforcement intensity, agricultural yield stability, and energy input cost trajectories. A small set of named triggers—EU Green Deal penalty implementation timing, Idaho potato crop yield variance, and Indian QSR chain expansion rates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Asia-Pacific Dairy Ingredients Market
Ingredients
North America Alcohol Ingredients Market
Ingredients
Stabilized Starch Market
Ingredients
Global Distillers Grains Market
Ingredients
Cocoa Liquor Market
Ingredients
Global Organic Personal Care Ingredients Market
Ingredients
Food Ingredients Market
Ingredients
Fluid Lecithin Market
Ingredients
Omega-3 Encapsulation Market
Ingredients
Rice Starch Market
Ingredients
Bone and Joint Health Ingredients Market
Ingredients
Punica Granatum (Pomegranate) Seed Oil Market
Ingredients
Europe Insoluble Dietary Fibers Market
Ingredients
Encapsulated Ingredients Market
Ingredients
Industrial Sugar Market
Ingredients
Maracuja Oil Market