
 Clean Label Emulsifiers Market | 2026-2036
Clean Label Emulsifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Clean Label Emulsifiers Market Insights
ISO 22000 food safety management certification is bifurcating the competitive landscape into qualified suppliers and excluded challengers. Cargill, Incorporated leverages its integrated supply chain from oilseed crushing to refined lecithin to sustain cost advantages in plant-based emulsifier production. Kerry Group plc differentiates through clean-label texturizing systems that combine emulsification with flavor masking for reduced-fat applications.
Clean label emulsifiers are surface-active agents derived from natural or minimally processed sources—lecithin from soy or sunflower, mono- and diglycerides from vegetable oils, or saponins—typically characterized by an HLB value between 3 and 15 and manufactured through mechanical extraction or enzymatic interesterification rather than chemical synthesis, primarily functioning to stabilize oil-water interfaces in food, cosmetic, and pharmaceutical matrices. Plant-based emulsifiers occupy the dominant volume position due to allergen and kosher compliance advantages, while hybrid formulations that blend plant-derived and fermentation-produced biosurfactants represent the fastest-expanding margin pool as brands seek to eliminate synthetic mono-diglycerides entirely. The food and beverage application segment anchors overall demand, though pharmaceutical-grade lecithin for liposomal drug delivery commands price premiums that exceed standard food grades.
The FDA maintains GRAS self-affirmation pathways that allow novel clean-label emulsifiers to reach the US market faster than EMA-regulated novel food additive approvals in Europe, where EFSA mandates comprehensive toxicological dossiers that extend commercialization timelines. REACH registration requirements for chemical intermediates and the EU Green Deal's deforestation-free supply chain due diligence rules are reshaping sourcing obligations for soy and palm-derived feedstocks. Stakeholders must monitor evolving biosimilar emulsifier classifications under EMA guidance and decide whether to pursue pharmaceutical-grade certifications before competitors lock in liposomal excipient supply contracts.
Market Dynamics
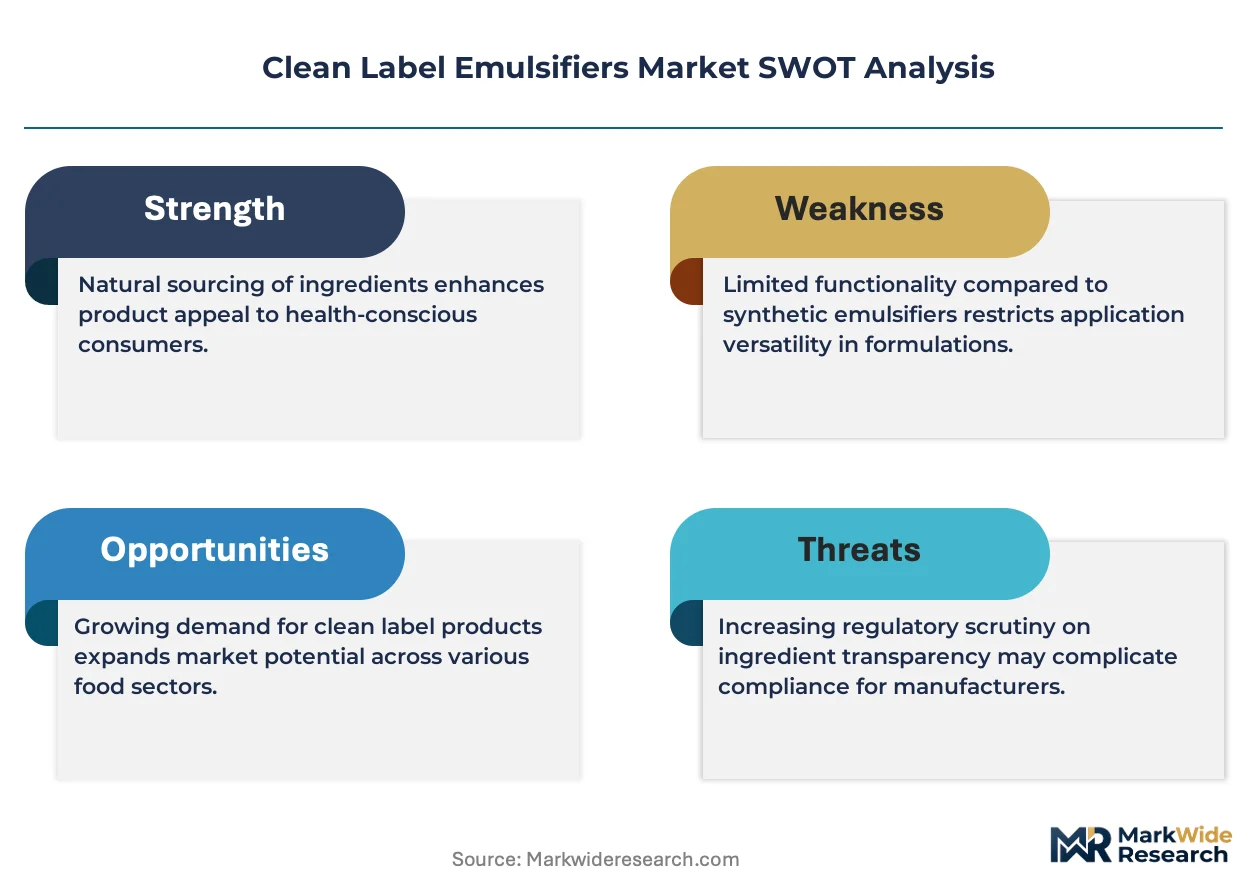
REACH registration requirements and EU Green Deal deforestation-free supply chain rules are forcing manufacturers to restructure soy and palm-derived feedstock sourcing, bifurcating the supplier base into compliant qualified vendors and excluded challengers.
Growth Catalysts
- EU Green Deal due diligence mandates:Deforestation-free supply chain rules accelerate certified lecithin adoption as bakeries and confectioners purge uncertified palm and soy derivatives to maintain market access across Germany, France, and the Netherlands.
- Enzymatic interesterification:This mechanical processing method eliminates chemical solvent residues, enabling clean-label mono- and diglycerides to meet ISO 22000 food safety standards without synthetic intermediate steps.
- Pharmaceutical liposomal delivery:Liposomal drug formulations command premium pricing for pharmaceutical-grade lecithin, pulling refined emulsifier capacity from food-grade markets into higher-margin excipient production.
Market Restraints
- Input cost volatility:Sunflower seed and non-GMO soybean prices fluctuate with Black Sea supply disruptions and US Midwest weather patterns, compressing margins for mechanical extraction processors.
- Supply concentration risk:Over half of pharmaceutical-grade lecithin refining capacity clusters in German and Dutch processing hubs, creating single-point vulnerability for liposomal excipient buyers.
- Regulatory friction:EFSA novel food additive approval timelines stretch 18-24 months longer than FDA GRAS self-affirmation pathways, delaying European commercialization of fermentation-derived biosurfactants.
Strategic Opportunities
- Hybrid biosurfactant formulations:Blending plant-derived lecithin with fermentation-produced rhamnolipids enables complete elimination of synthetic mono-diglycerides in premium bakery applications.
- Reduced-fat texturizing systems:Clean-label emulsifiers combined with flavor masking technologies unlock reformulation contracts from dairy and plant-based beverage manufacturers seeking mouthfeel restoration.
- Pharmaceutical-grade certification pre-emption:Early ISO 22000 and GMP certification for liposomal excipient production secures long-term supply contracts before competitors lock in qualified supplier status.
Industry Challenges
- Enzyme engineering talent scarcity:Specialized biochemists capable of optimizing lipase specificity for targeted interesterification remain concentrated in German and Swiss research clusters, constraining process scale-up.
- Legacy equipment retrofit costs:Transitioning from chemical solvent extraction to supercritical CO2 or aqueous enzymatic systems demands capital outlays that mid-tier processors cannot finance without strategic partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clean Label Emulsifiers Market |
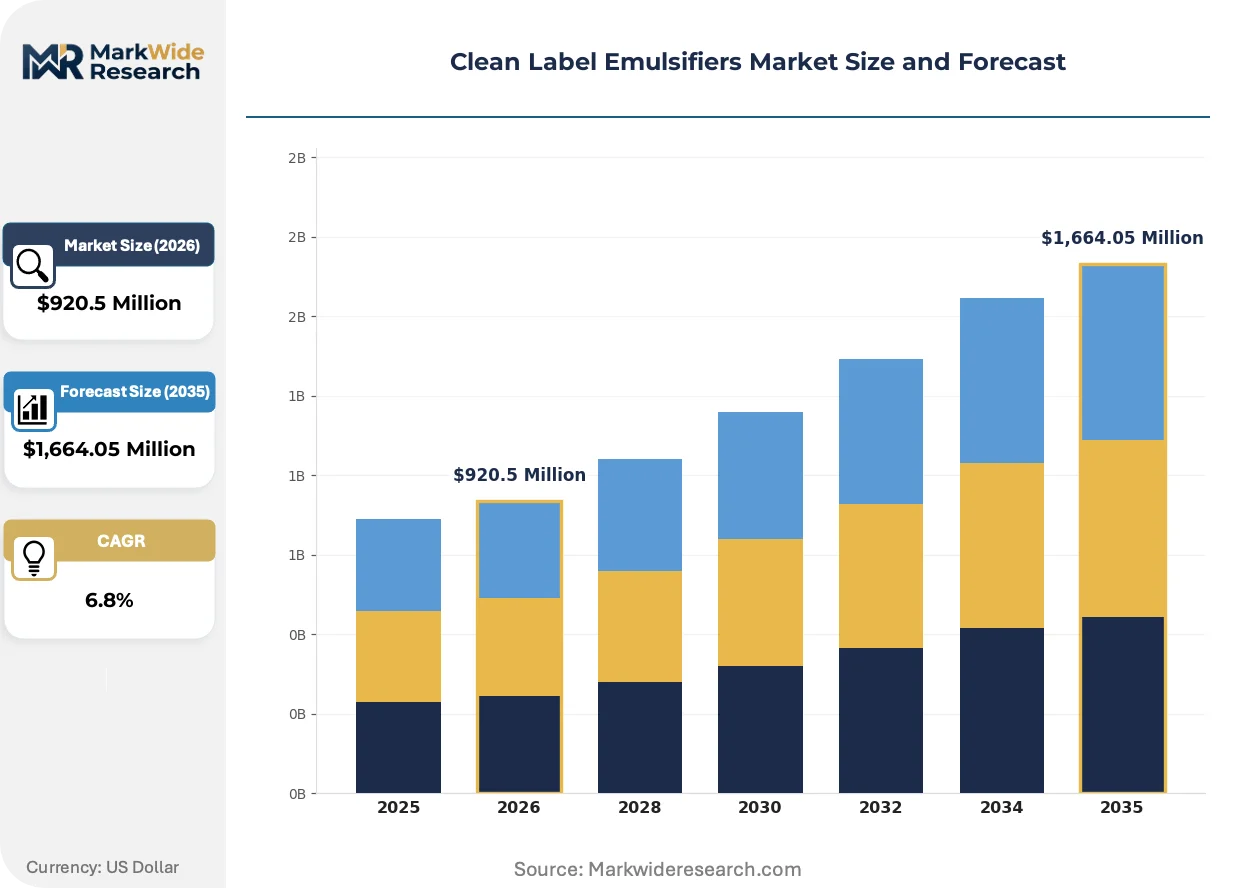
| Market Size in 2026 | $920.5 Million |
| Market Size in 2035 | $1,664.05 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plant-Based, Animal-Derived, Synthetic, Hybrid Application: Food & Beverage, Cosmetics, Pharmaceuticals, Personal Care End User: Food Manufacturers, Cosmetic Companies, Pharmaceutical Firms, Contract Manufacturers Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | Cargill, Incorporated, Archer Daniels Midland Company, Ingredion Incorporated, DuPont Nutrition & Biosciences, Kerry Group plc, Corbion NV, BASF SE, Musim Mas, Nexira, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clean Label Emulsifiers Market Trends and Innovations
Fermentation-derived biosurfactants and precision enzymatic processing are compressing the synthetic emulsifier replacement timeline, while regulatory due diligence requirements reshape sourcing geography.
Enzymatic interesterification of vegetable oils is supplanting chemical glycerolysis for mono- and diglyceride production. Bakery and confectionery manufacturers in the Netherlands and Germany are adopting these enzymatically processed emulsifiers at accelerating rates to meet retailer clean-label specifications. This technology is compressing the cost gap between synthetic and natural emulsifiers while eliminating residual solvent concerns that previously constrained premium positioning.
REACH registration requirements for chemical intermediates now extend to emulsifier feedstock derivatives, compelling suppliers to document full substance toxicity dossiers. The regulation forces reformulation of hybrid emulsifier systems that previously relied on unregistered synthetic co-surfactants. German chemical distributors are responding by consolidating sourcing through pre-registered supply chains and abandoning spot-market purchases of unverified Asian intermediates.
Buyer concentration among multinational bakery and confectionery groups has compressed supplier qualification timelines from 18 months to 8 months. Tier-one manufacturers now demand simultaneous ISO 22000 certification, deforestation-free supply chain documentation, and real-time batch traceability as table stakes for contract eligibility. This pattern is most visible in German and French procurement departments, where sustainability scorecards now outweigh price in vendor selection algorithms.
Clean Label Emulsifiers Market Segmentation
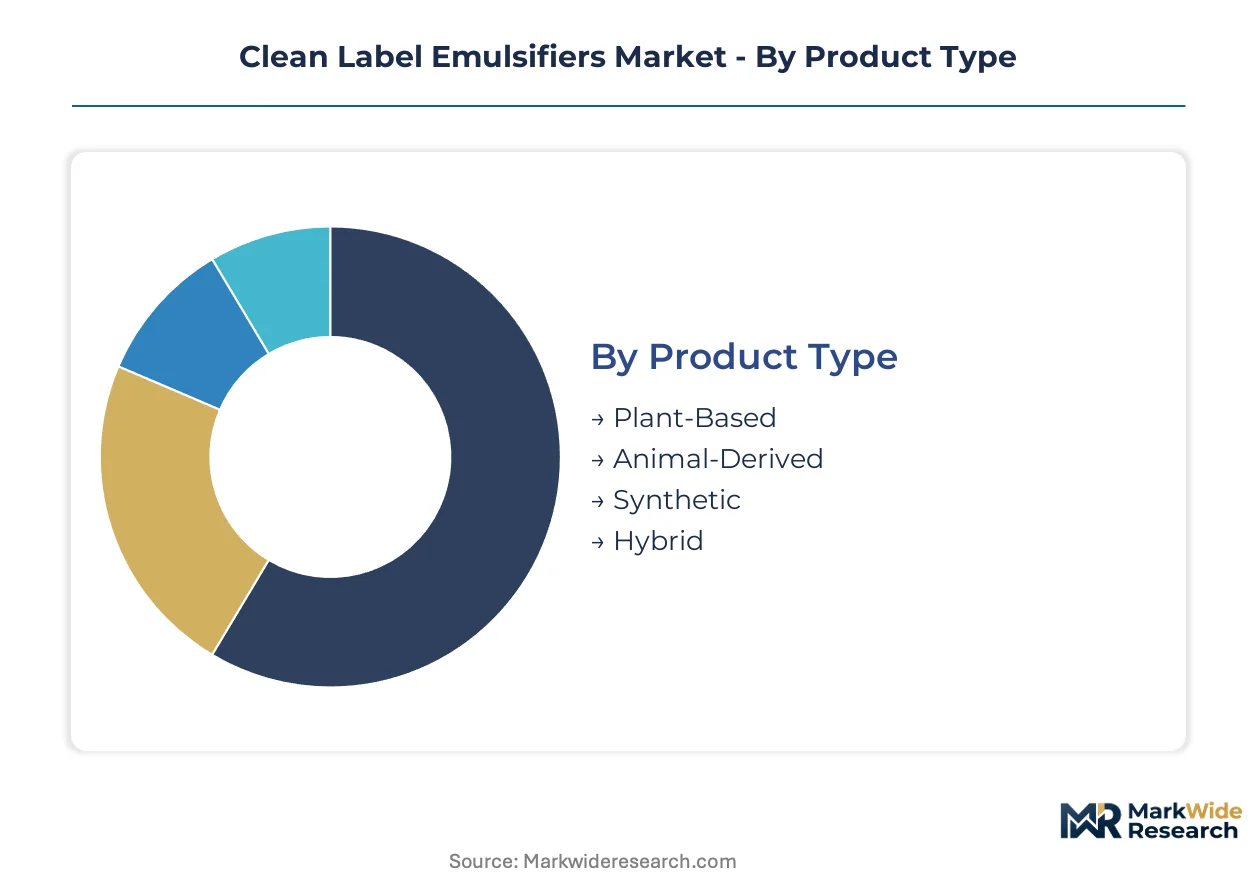
Clean label emulsifier procurement patterns diverge sharply across product origins and end-use specifications. Understanding these segment boundaries reveals where certification investments yield contract eligibility versus commodity margin compression.
Product Type:
Export-led demand concentrates in plant-based and hybrid formulations serving EU Green Deal compliance requirements, while domestic consumption patterns favor established synthetic and animal-derived grades in less regulated markets.
- Plant-Based:Derived from soy, sunflower, or rapeseed through mechanical extraction or enzymatic processing, these emulsifiers carry HLB values between 3 and 15. German and Dutch bakery manufacturers specify certified deforestation-free lecithin to satisfy retailer due diligence mandates, pulling supply away from uncertified Asian crushers.
- Hybrid:Blending plant-derived lecithin with fermentation-produced biosurfactants such as rhamnolipids or sophorolipids enables complete elimination of synthetic mono-diglycerides. Netherlands-based confectioners are adopting these systems fastest to meet clean-label specifications that pure plant grades cannot satisfy alone.
- Animal-Derived:Egg yolk phospholipids and milk-based emulsifiers retain niche positions in premium sauce and infant formula applications where emulsion stability requirements exceed plant-grade performance.
- Synthetic:Chemically synthesized mono- and diglycerides face accelerating displacement as enzymatic interesterification achieves cost parity without solvent residues.
Plant-based holds the largest share; momentum sits with hybrid.
Application:
Cost tier differentiation separates pharmaceutical-grade certifications from commodity food-grade volumes, with price premiums exceeding threefold for liposomal excipient compliance.
- Food & Beverage:Bakery and confectionery manufacturers anchor volume demand, with enzymatically processed mono- and diglycerides displacing synthetic alternatives in Dutch and German clean-label reformulations.
- Pharmaceuticals:Liposomal drug delivery systems require pharmaceutical-grade lecithin meeting GMP and ISO 22000 standards. German and Dutch refining hubs concentrate capacity, creating supply bottlenecks for qualified excipient buyers.
- Cosmetics:Natural emulsifiers stabilize oil-water interfaces in skincare formulations, with sunflower-derived lecithin preferred for allergen-free positioning.
- Personal Care:Saponin-based biosurfactants from quillaja and yucca extracts serve natural shampoo and body wash segments where foam performance must match synthetic benchmarks.
Food and beverage dominates volume; pharmaceuticals commands the steepest expansion trajectory.
End User:
Customer type determines qualification intensity, with multinational food manufacturers compressing supplier onboarding from 18 months to 8 months while demanding simultaneous sustainability documentation.
- Food Manufacturers:Tier-one bakery and confectionery groups in Germany and France now require ISO 22000 certification, deforestation-free supply chain documentation, and real-time batch traceability as baseline contract conditions.
- Pharmaceutical Firms:Liposomal formulation developers lock in long-term excipient supply contracts before competitors secure qualified supplier status, prioritizing GMP-certified refiners with documented phospholipid purity profiles.
- Cosmetic Companies:Natural and organic brands drive specification of non-GMO, mechanically extracted lecithin for emulsion stability in clean-label skincare.
- Contract Manufacturers:Toll processors serving multiple end-use segments face conflicting certification requirements, forcing redundant inventory positions or specialized facility investments.
Food manufacturers represent the largest buyer base; pharmaceutical firms are gaining share fastest.
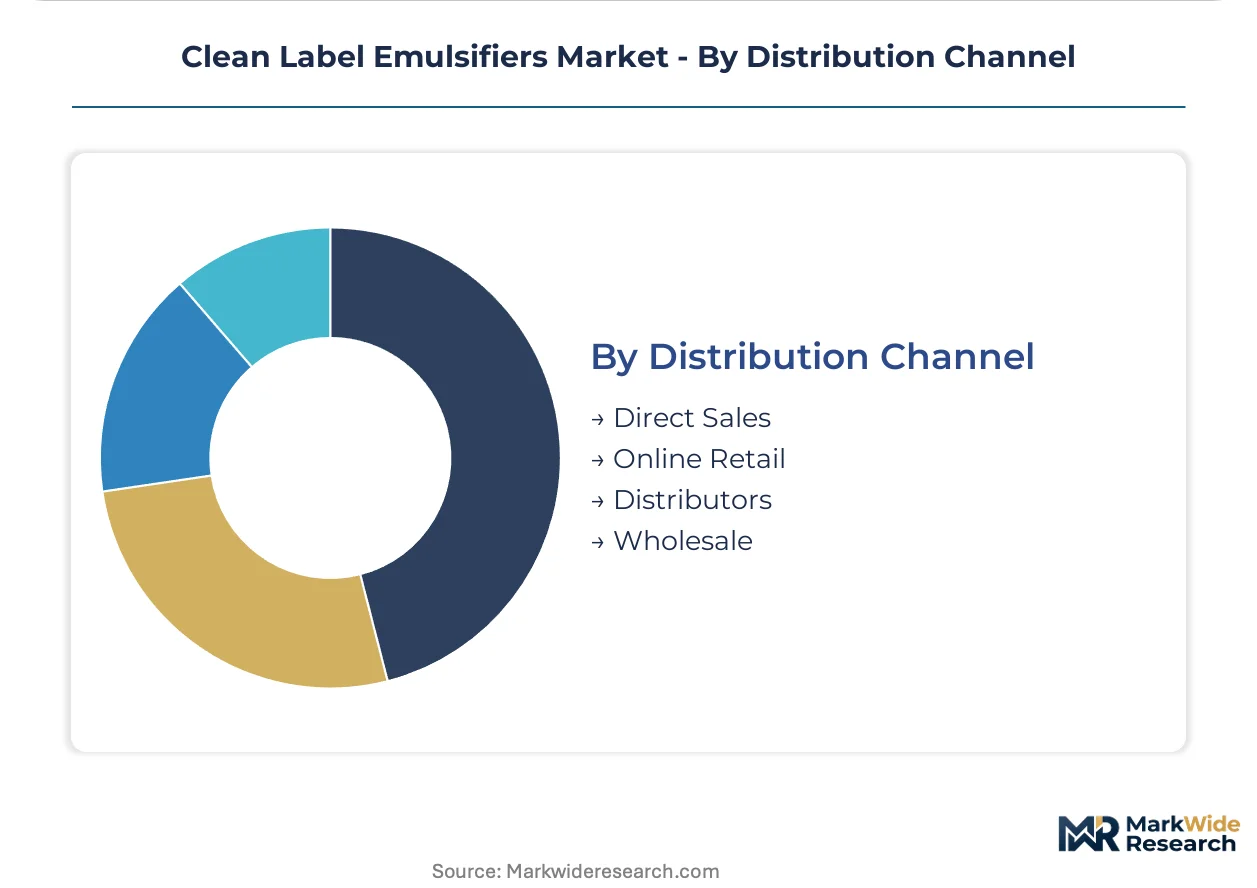
Distribution Channel:
Supply concentration in German and Dutch processing hubs shapes channel economics, with direct relationships dominating pharmaceutical-grade transactions and distributors absorbing inventory risk for commodity food grades.
- Direct Sales:Pharmaceutical-grade lecithin and large-volume food contracts move through direct manufacturer relationships, with German chemical distributors consolidating sourcing through pre-registered REACH-compliant supply chains.
- Distributors:Mid-tier food manufacturers rely on regional distributors for smaller lot sizes, though REACH registration requirements are forcing abandonment of spot-market purchases from unverified Asian intermediates.
- Wholesale:Commodity plant-based emulsifiers flow through agricultural wholesale networks tied to oilseed crushing operations, with price volatility tracking Black Sea sunflower seed and US Midwest soybean conditions.
- Online Retail:Specialty biosurfactants and small-quantity lecithin for cosmetic formulators and artisan food producers, with limited penetration in industrial-scale procurement.
Direct sales holds the largest share; distributor relationships are expanding most quickly as compliance documentation requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal deforestation-free supply chain mandates are redrawing procurement geography for clean label emulsifiers, with certified lecithin capacity concentrating in processing hubs that can document sustainable soy and sunflower sourcing.
Germany
Bakery and confectionery manufacturers in Hamburg and Cologne are accelerating adoption of enzymatically processed mono- and diglycerides. REACH registration requirements for chemical intermediates now extend to emulsifier feedstock derivatives, compelling suppliers to document full substance toxicity dossiers. The Rhine-Ruhr industrial corridor hosts refining clusters where pharmaceutical-grade lecithin capacity is expanding to serve liposomal drug delivery demand.
France
Tier-one food manufacturers in Paris and Lyon now require ISO 22000 certification, deforestation-free supply chain documentation, and real-time batch traceability as baseline contract conditions. ANSM pharmaceutical regulations align with EMA guidance on liposomal excipient classifications, creating compliance pathways for refined lecithin suppliers. The Grand Est region concentrates oilseed processing infrastructure serving both food and pharmaceutical grade markets.
Netherlands
Netherlands-based confectioners are adopting hybrid biosurfactant systems fastest to meet clean-label specifications that pure plant grades cannot satisfy alone. ECHA enforcement of REACH registration deadlines has forced abandonment of spot-market purchases from unverified Asian intermediates. The Rotterdam port cluster functions as the primary entry point for certified sustainable soy and sunflower feedstocks into European processing networks.
United States
FDA GRAS self-affirmation pathways allow novel clean-label emulsifiers to reach the US market faster than EMA-regulated approvals, attracting fermentation-derived biosurfactant developers. Midwest soybean processing hubs face margin pressure from Black Sea supply disruptions and weather volatility. Chicago-based food manufacturers are integrating clean-label texturizing systems for reduced-fat dairy and plant-based beverage reformulations.
India
FSSAI food safety standards are tightening additive profiles for bakery and confectionery applications, creating compliance demand for mechanically extracted lecithin. BIS certification requirements for imported food ingredients are filtering supplier eligibility toward documented clean-label sources. Maharashtra and Gujarat processing clusters are expanding enzymatic interesterification capacity to serve domestic clean-label reformulation demand.
Clean Label Emulsifiers Market Competitive Landscape
Player mix skews toward integrated agribusiness conglomerates with captive oilseed crushing operations and specialized ingredient technology firms with enzymatic processing capabilities. The competitive structure tiers into three archetypes: multinational agribusinesses controlling upstream feedstock supply, mid-scale enzymatic technology specialists, and regional lecithin refiners serving pharmaceutical-grade niches. Dominant competitive moves include backward integration into certified sustainable oilseed sourcing and strategic partnerships to access enzyme engineering talent concentrated in German and Swiss research clusters.
Within the integrated agribusiness tier, Cargill, Incorporated and Archer Daniels Midland Company represent archetypes of supply chain control from oilseed procurement through refined emulsifier production. Kerry Group plc occupies a position exemplifying the technology-specialist archetype, combining clean-label emulsification with adjacent formulation capabilities. These three anchors illustrate the competitive divide between scale-driven feedstock security and precision enzymatic processing differentiation.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| DuPont Nutrition & Biosciences |
| Kerry Group plc |
| Corbion NV |
| BASF SE |
| Musim Mas |
| Nexira |
| Others |
Pricing and Supply Chain Analysis
Mechanical extraction scale economies in German and Dutch processing hubs concentrate pharmaceutical-grade lecithin refining capacity, establishing price floors that mid-tier enzymatic processors cannot match without strategic partnerships. This concentration of ISO 22000-certified capacity creates tiered pricing power where GMP-compliant excipient grades command substantial premiums over standard food-grade volumes.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade and food-grade emulsifier tiers, with GMP and ISO 22000 compliance separating premium excipient pricing from commodity lecithin. Three-tier pricing structure across premium, standard, and economy levels reflects deforestation-free supply chain documentation requirements and enzymatic processing investments. Pricing pressure stems from Black Sea sunflower seed volatility and US Midwest soybean weather disruptions compressing mechanical extraction margins. Mid-tier food manufacturers exhibit highest price sensitivity, while pharmaceutical formulation developers prioritize qualified supplier security over unit cost.
Supply Chain Analysis
Rotterdam port transit underwrites European feedstock entry for certified sustainable soy and sunflower derivatives flowing to German and Dutch refining clusters. Supply concentration in Germany, Netherlands, and France draws from Ukrainian sunflower seeds, Brazilian soybeans, and domestic rapeseed as primary inputs. Single-source vulnerability runs through Rotterdam's deforestation-free certification bottleneck, where ECHA enforcement has eliminated spot-market Asian intermediary purchases. Distribution runs through direct manufacturer relationships for pharmaceutical grades and regional distributors absorbing inventory risk for commodity food volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized lipase engineering talent scarcity in German and Swiss research clusters constrains enzymatic interesterification scale-up, creating a capability moat for incumbents with established biochemist networks while forcing new entrants toward equipment partnerships or acquisition strategies.
For Market Incumbents: Consolidate pharmaceutical-grade certification pre-emption by locking GMP-compliant liposomal excipient supply contracts before competitors secure qualified supplier status. Deepen backward integration into certified deforestation-free oilseed sourcing to neutralize EU Green Deal due diligence exposure and protect margin structure against feedstock price volatility. For New Entrants and Emerging Players: Lead with hybrid biosurfactant formulations targeting Netherlands-based confectioners seeking complete synthetic mono-diglyceride elimination. The enzymatic technology specialist archetype offers the most penetrable entry point, with toll processing partnerships enabling qualification timeline compression without capital-intensive facility investment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors enzymatic processing specialists with demonstrated lipase optimization capabilities over legacy chemical extraction assets. Long-term viability hinges on pharmaceutical-grade certification traction and deforestation-free supply chain documentation depth. The signal to watch is EMA biosimilar emulsifier classification guidance, which would recalibrate competitive positioning for fermentation-derived entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade Certification Investment | GMP and ISO 22000 compliance secures liposomal excipient supply contracts from formulation developers. |
| Backward Integration into Certified Oilseed Sourcing | Deforestation-free supply chain documentation satisfies EU Green Deal due diligence mandates for bakery and confectionery buyers. |
| Enzymatic Interesterification Capacity Expansion | Mechanical processing eliminates solvent residues, enabling clean-label positioning for Dutch and German clean-label reformulations. |
| Hybrid Biosurfactant Formulation Development | Blending plant lecithin with fermentation-derived rhamnolipids addresses premium bakery specifications pure plant grades cannot satisfy. |
| Strategic Partnership for Lipase Engineering Access | Collaboration with German and Swiss research clusters overcomes biochemist talent scarcity constraining process scale-up. |
Research Methodology
A standing panel of enzymatic processing technologists, bakery procurement directors, pharmaceutical formulation scientists, and REACH compliance consultants provided ongoing calibration across primary fieldwork and secondary validation. Primary interviews with plant managers at oilseed crushing facilities, technical R&D directors at ingredient technology firms, and regulatory affairs leads at multinational food manufacturers anchored demand-side intelligence. Secondary sources included ECHA registration databases, FDA GRAS notification filings, FAO oilseed trade statistics, and SEC filings from integrated agribusiness conglomerates. Bottom-up volume modeling triangulated against top-down value estimates from customs and trade data.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. The analytical framework modeled segmentation dimensions including product origin tier, application grade, end-user qualification intensity, and distribution channel structure. CAGRs were derived from fitted growth curves incorporating input cost volatility indices, regulatory timeline assumptions, and pharmaceutical liposomal delivery expansion trajectories. Industry-specific forecast inputs captured enzymatic processing cost compression rates and EU Green Deal compliance adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement intensity or accelerated pharmaceutical-grade capacity expansion would require recalibration. Forecasts reflect documented assumptions regarding Black Sea supply stability and EMA biosimilar classification timelines. Practitioners should keep alternative scenarios live as ECHA enforcement patterns and fermentation-derived biosurfactant approval trajectories evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food Glazing Agents Market
Food Additives and Ingredients
North America Food Micronized Salt Market
Food Additives and Ingredients
Brazil Food Enzymes Market
Food Additives and Ingredients
Acetylated Monoglycerides (AMG) Market
Food Additives and Ingredients
Erythorbic Acid Market
Food Additives and Ingredients
Monostarch Phosphate Market
Food Additives and Ingredients
Global Oleate Esters Market
Food Additives and Ingredients
Global Natamycin Market
Food Additives and Ingredients
Noodles Preservatives Market
Food Additives and Ingredients
Aluminum-Free Natural Food Color Market
Food Additives and Ingredients
Food Grade Distilled Monoglyceride Market
Food Additives and Ingredients
Middle East and Africa Food Starch Market
Food Additives and Ingredients
Fruit and Vegetable Processing Enzymes Market
Food Additives and Ingredients
Europe Food Emulsifiers Market
Food Additives and Ingredients
Caramel Food Colors Market
Food Additives and Ingredients
Argentina Gellan Gum Market