
 US Plant-Based Oils Market | 2026-2036
US Plant-Based Oils Market Size, Share, and Industry Trends Forecast 2026-2036
US Plant-Based Oils Market Intelligence
Certified-origin and non-GMO verification programs are decoupling the base commodity price from the final transactional value. This shift creates distinct value tiers beyond simple processing grades. Cargill Incorporated leverages its extensive processing infrastructure to supply multiple oil types. Bunge Limited competes on logistics and global sourcing to serve US food manufacturers.
US plant-based oils are lipids derived from plant sources like seeds and fruits through mechanical pressing or solvent extraction. Their chemical composition, particularly the fatty acid profile like oleic content, determines their application and nutritional value. Canola oil represents a high-volume product for food manufacturers, while the organic grade across olive and coconut oils secures premium pricing in retail. The household end-user segment shows strong preference for extra virgin olive oil.
The Food and Drug Administration (FDA) enforces standards of identity and labeling requirements, governing how products are presented to consumers. The USDA's National Organic Program provides a framework for organic certification, impacting sourcing and production practices. Navigating the evolving consumer perceptions of health and sustainability will be critical for brand positioning and margin protection.
Market Dynamics
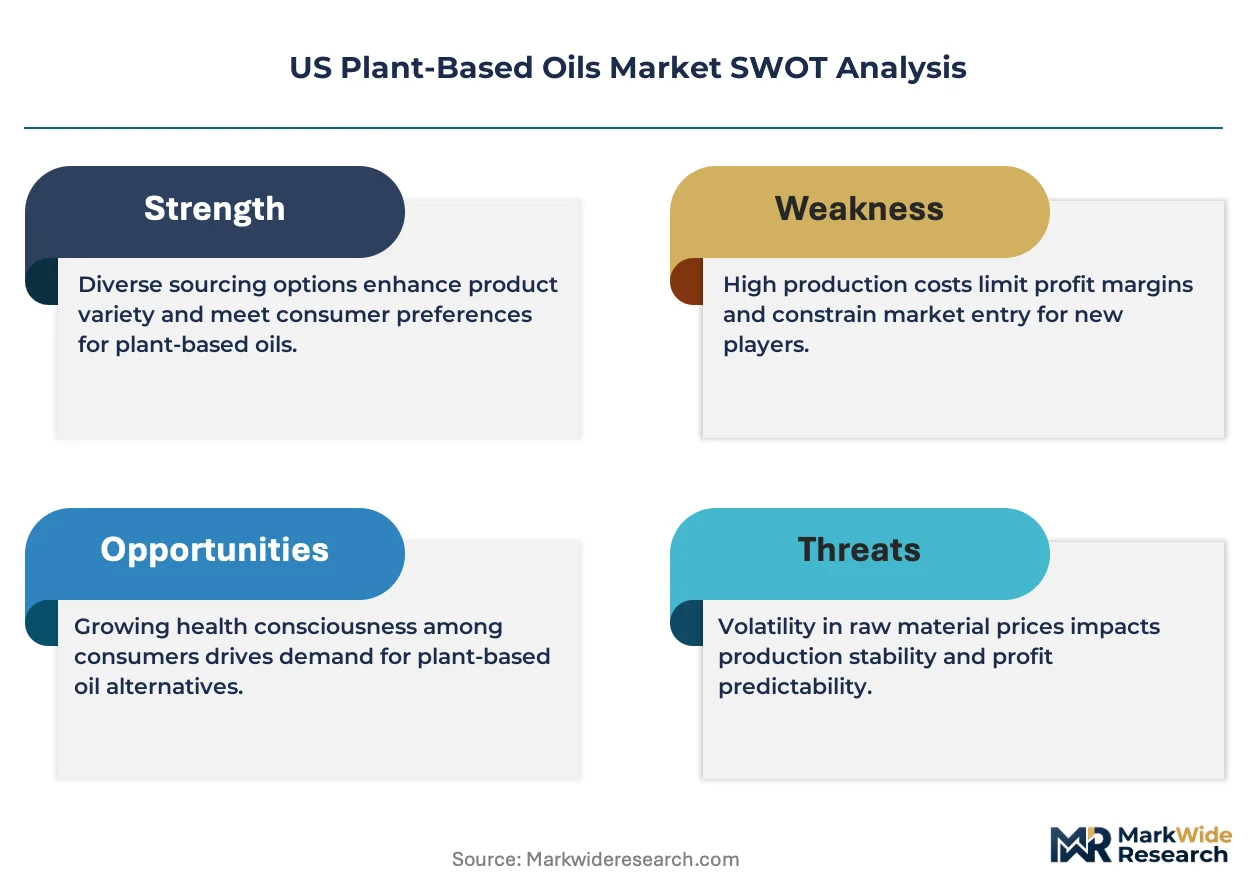
The primary structural force in the US plant-based oils market is the bifurcation of value between bulk commodity oils and identity-preserved specialty oils. This split, driven by consumer demand for non-GMO and organic attributes, is creating distinct supply chains and pricing tiers.
Growth Catalysts
- Food Manufacturing Expansion:The growing food manufacturing sector, particularly for meat and dairy alternatives, requires large, consistent volumes of functional oils like canola and soy, driving baseline demand in Midwest processing hubs.
- FDA Labeling Guidance:Regulatory clarification from the Food and Drug Administration (FDA) on labeling for plant-based foods is reducing ambiguity for manufacturers, encouraging investment in new product development and marketing.
- Nutritional Profile Demand:Consumer and food-service interest in specific fatty acid profiles, such as high-oleic content for improved stability and health perception, is creating demand for specialized oil variants.
Market Restraints
- Input Cost Volatility:The market is directly exposed to price fluctuations in agricultural commodities like soybeans, canola seed, and corn, which can compress processor margins and create price instability for end-users.
- Water Scarcity:Water availability and rights, especially in key agricultural states like California for crops like olives and almonds, present a significant structural constraint on feedstock supply and long-term production costs.
- Processing Infrastructure Bottlenecks:A limited number of facilities are equipped for segregated processing of certified organic or non-GMO crops, creating bottlenecks that restrict the supply of identity-preserved oils.
Strategic Opportunities
- High-Oleic Variants:Developing and marketing high-oleic versions of commodity oils like soybean and canola oil offers a path to premiumization, targeting food service clients who require enhanced fry-life and stability.
- USDA Organic Certification:Expanding sourcing and processing capacity for oils compliant with the USDA's National Organic Program allows producers to access high-margin retail and food ingredient segments.
- Specialty Oil Blends:Creating customized oil blends with specific functional properties, such as precise smoke points or fatty acid compositions, provides a value-added solution for industrial food producers.
Industry Challenges
- Supply Chain Segregation:Maintaining the integrity of certified-origin and non-GMO supply chains requires significant investment in segregated storage, transportation, and processing, adding complexity and cost.
- Consumer Perception Management:Brands face the challenge of educating consumers on the differences between extraction methods, such as solvent extraction versus mechanical pressing, which impacts product positioning and cost.
- Regulatory Compliance Overhead:Navigating and documenting compliance with the FDA's food safety standards and the USDA's organic certification framework represents a continuous operational burden for processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Plant-Based Oils Market |
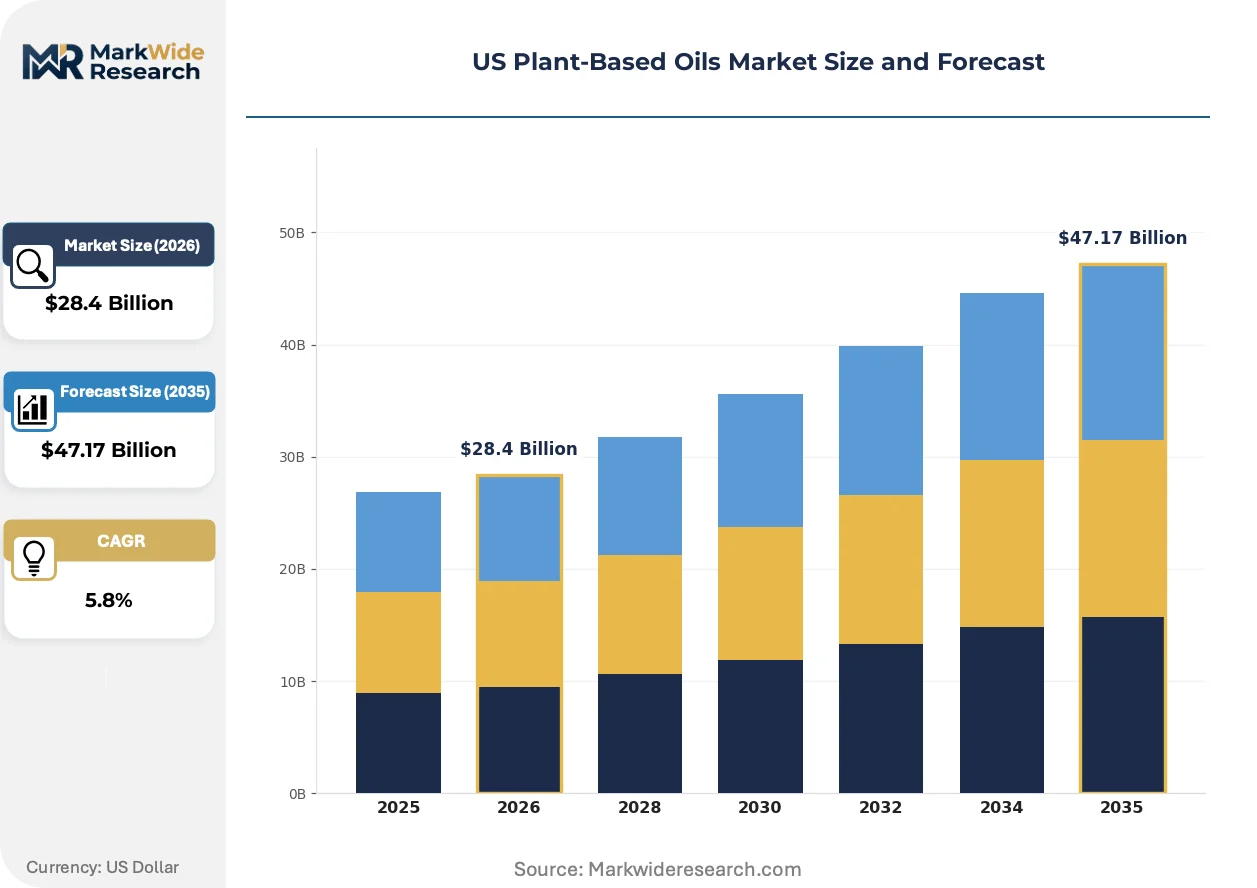
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $47.17 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Olive Oil, Canola Oil, Coconut Oil, Sunflower Oil Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Wholesale End User: Food Manufacturers, Restaurants, Households, Bakeries Grade: Extra Virgin, Refined, Organic, Conventional |
| Companies Covered | ADM, Bunge Limited, Cargill Incorporated, Westmill Foods, CHS Inc, FUJI Oil Asia Pte Ltd, Ag Processing Inc a Cooperative, Riceland Foods, ACH Food Companies Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Plant-Based Oils Market Strategic Shifts & Innovations
The US plant-based oils market is evolving from a commodity-driven model to one defined by functional attributes and supply chain transparency. Innovations in biotechnology and digital traceability are enabling producers to meet specific demands from both food manufacturers and end consumers.
Precision fermentation is an emerging technology used to create designer fats and oils with highly specific molecular structures. Food technology companies are adopting this method to produce lipids that mimic the properties of animal fats for use in next-generation meat alternatives. This advanced bio-manufacturing is converging with conventional oilseed crushing to create a hybrid supply of functional ingredients.
The FDA's guidance on labeling plant-based foods is establishing clearer market rules. This regulatory development provides manufacturers with greater confidence in how to name and market products, particularly in the dairy alternative space using oils. The prepared foods segment is most affected, adjusting marketing strategies to align with the FDA's framework.
A demand-side shift toward radical transparency is altering how products are presented to consumers. On-package QR codes that link to detailed sourcing information are becoming a key differentiator, moving beyond simple origin statements. This trend is most prominent in the premium olive and coconut oil categories, where proof of non-GMO status or organic certification is a primary value driver.
US Plant-Based Oils Market Segmentation
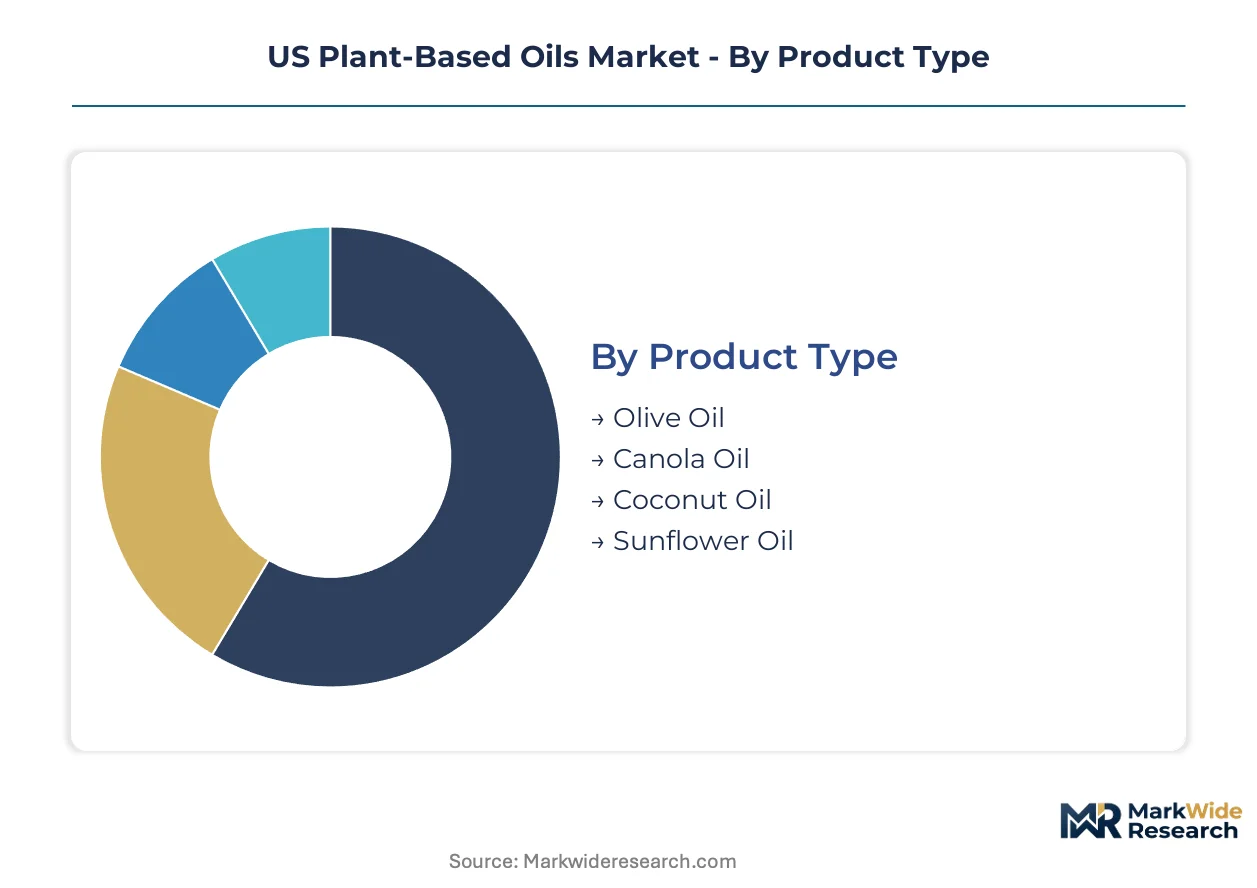
The US plant-based oils market demonstrates varied demand patterns and supply chain configurations across its core segments. Understanding these distinctions is critical for processors and manufacturers aiming to optimize product portfolios and distribution strategies. Each segment reflects unique consumer preferences or industrial requirements.
Product Type:
The market's product type segmentation highlights the diverse chemical compositions and functional attributes driving specific oil applications.
- Canola Oil:This oil, low in saturated fat and high in monounsaturated fatty acids, is widely used for its neutral flavor and high smoke point, making it a staple in food manufacturing for frying and baking applications across Midwest processing hubs.
- Olive Oil:Valued for its distinct flavor profile and perceived health benefits, particularly extra virgin varieties, olive oil commands premium pricing within the household segment, where consumers prioritize taste and nutritional quality.
- Coconut Oil:Known for its unique fatty acid composition, coconut oil finds applications in confectionery, personal care products, and as a dairy alternative ingredient, appealing to specific dietary trends.
- Sunflower Oil:Offering a light taste and high vitamin E content, sunflower oil serves both food manufacturing and household needs, with high-oleic varieties gaining traction for their extended shelf life.
Mature deployment sits with Canola Oil. Newer deployment is concentrated in Olive Oil.
Distribution Channel:
Customer purchasing patterns significantly influence the distribution channel landscape for plant-based oils.
- Supermarkets:These large retail chains serve as the primary point of purchase for household consumers, offering a broad selection of both commodity and specialty plant-based oils. Broad consumer accessibility drives significant volume through this channel.
- Wholesale:This channel supplies bulk quantities of plant-based oils directly to food manufacturers and food service operators, prioritizing consistent supply and competitive pricing for large-scale production.
- Online Retail:E-commerce platforms provide consumers with convenient access to niche and premium plant-based oils, often featuring detailed product information and direct-to-consumer delivery.
- Specialty Stores:These outlets cater to consumers seeking organic, non-GMO, or unique varietal oils, offering curated selections and often emphasizing origin and quality attributes.
Supermarkets maintain broad market penetration. Online retail channels are expanding most quickly for specialized oils.
End User:
Application-specific requirements define the end-user segments for plant-based oils across various industries.
- Food Manufacturers:This segment represents the largest consumer of plant-based oils, utilizing them as functional ingredients in a wide array of products, including meat alternatives, dairy substitutes, and processed foods, driving baseline demand for bulk quantities.
- Households:Individual consumers purchase plant-based oils for cooking, baking, and salad dressings, with a strong preference for premium options like extra virgin olive oil and certified organic varieties, influencing retail product development.
- Restaurants:Food service establishments require consistent supplies of functional oils for frying, sautéing, and dressing, often prioritizing oils with high smoke points and neutral flavors for culinary versatility.
- Bakeries:Bakeries use plant-based oils as essential ingredients in breads, pastries, and other baked goods, valuing their textural properties and ability to extend shelf life.
Food Manufacturers consume the largest volumes of plant-based oils. Household demand for premium products continues to climb.
Grade:
Margin structures vary considerably across different grades of plant-based oils, reflecting processing intensity and consumer perception.
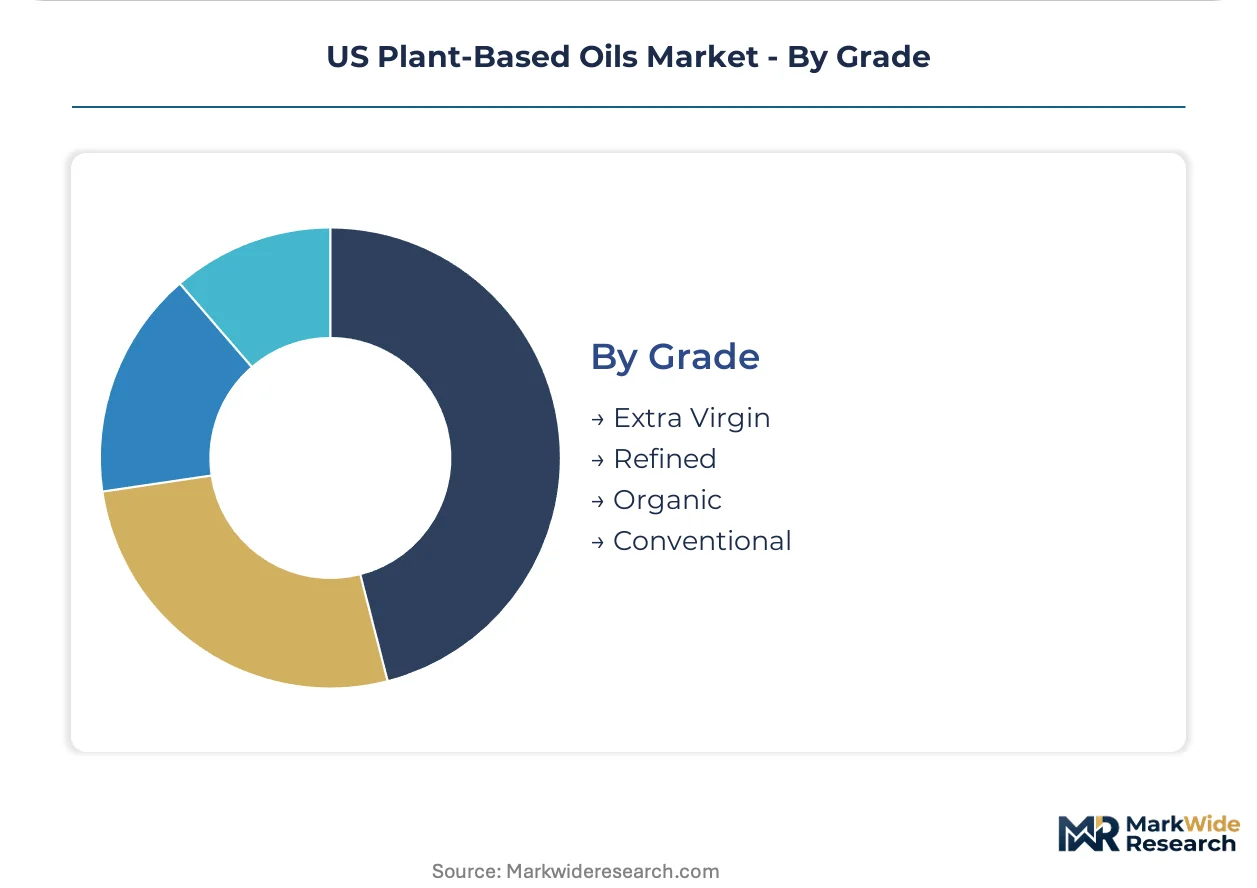
- Organic:Oils certified under the USDA's National Organic Program command premium pricing due to stringent sourcing and processing requirements, appealing to health-conscious consumers and high-margin retail segments.
- Extra Virgin:This grade, primarily for olive oil, signifies minimal processing and superior sensory qualities, securing top-tier prices within the household and gourmet food sectors.
- Refined:These oils undergo extensive processing to achieve a neutral flavor, lighter color, and higher smoke point, making them suitable for industrial frying and baking applications where consistency is paramount.
- Conventional:Representing the base commodity tier, conventional oils are produced without specific organic or non-GMO certifications, serving large-volume industrial and food service markets at competitive price points.
Conventional grades fulfill bulk industrial needs. Organic grades secure premium pricing in retail environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US plant-based oils market exhibits distinct regional demand and supply characteristics, driven by processing infrastructure and consumer preferences. Midwest food processing centers drive significant demand for bulk oils. California's specialty agriculture and high-value consumer markets shape premium oil segments. The Northeast Corridor focuses on retail distribution, while the Southeast sees expanding manufacturing.
Midwest
Food manufacturing expansion, especially for meat and dairy alternatives, drives substantial demand for functional oils like canola and soy in the Midwest. The USDA's National Organic Program influences sourcing practices for organic oilseed crops across the region. Chicago's robust food processing hub concentrates large-volume crushing and refining operations for soybean and canola oils.
California
Household demand for premium olive oil and specialty food production creates a strong market for high-value plant-based oils in California. State water rights policies significantly impact the availability and cost of feedstock for crops such as olives and almonds. The Central Valley agribusiness region concentrates olive oil and almond oil production and processing facilities.
Northeast Corridor
High consumer preference for extra virgin olive oil and a dense specialty food retail network define demand within the Northeast Corridor. FDA labeling standards provide clear guidance for manufacturers marketing plant-based products to consumers in this region. New York City's gourmet food market drives demand for certified-origin and premium quality oils.
Southeast
Expanding food manufacturing and a growing consumer interest in healthier options fuel demand for plant-based oils across the Southeast. State agricultural policies increasingly support the cultivation of oilseed crops like soybeans and sunflowers. Atlanta's burgeoning food processing sector integrates plant-based oils into a diverse range of prepared foods.
US Plant-Based Oils Market Key Industry Players
Capital-heavy producers compete with asset-light designers in the US plant-based oils market. The market maintains a tiered structure, combining a few large integrated processors with numerous specialty oil producers. Strategic archetypes include commodity giants, niche ingredient specialists, and retail brand developers. Portfolio diversification and strategic partnerships define competitive moves.
Among established processors, Cargill Incorporated and Bunge Limited exemplify large-scale operations. These companies anchor the commodity end of the market, leveraging extensive infrastructure and global sourcing capabilities. ADM also operates at this scale, representing comprehensive agricultural processing. These entities collectively shape the foundational supply of bulk plant-based oils for industrial applications.
| Leading Market Players |
|---|
| ADM |
| Bunge Limited |
| Cargill Incorporated |
| Westmill Foods |
| CHS Inc |
| FUJI Oil Asia Pte Ltd |
| Ag Processing Inc a Cooperative |
| Riceland Foods |
| ACH Food Companies Inc |
| Others |
Cost & Logistics Intelligence
Skilled labor concentration in Midwest processing hubs influences pricing tiers across the US plant-based oils market. This labor-cost differential contributes to the spread between bulk commodity oils and specialized identity-preserved products.
Pricing Analysis
Value-based pricing for plant-based oils anchors on specific functional attributes like high smoke point or certified organic status. Pricing stratifies across conventional, refined, and certified organic tiers, driven by quality grade and certification level. Pricing pressure stems from input cost volatility in agricultural commodities, impacting processor margins. Food manufacturers purchasing bulk quantities exhibit high price sensitivity, while households show less sensitivity for premium extra virgin olive oil.
Supply Chain Analysis
Used oil collection and recycling programs from the food service sector represent a minor but growing reverse logistics stream within the US plant-based oils market. Geographic supply concentrates in the Midwest for canola and soy, and in California for olive and almond oils. The market draws from raw material dependencies on soybeans, canola seed, and olives. Supply chain risk includes commodity price volatility and water scarcity in key agricultural states. Distribution runs through wholesale channels for industrial users and supermarkets with expanding online retail for consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US plant-based oils market is witnessing a vertical-integration race as companies seek to control feedstock sourcing and processing capabilities. This upstream control aims to secure consistent supply and enhance value capture.
For Market Incumbents:Cement core market share by expanding processing capacity in Midwest hubs for high-volume oils like canola and soy. Invest in USDA organic certification programs to shield against volatile commodity prices and compete with niche brands. Enhance supply chain transparency through digital tools to reinforce consumer trust. Focus R&D on high-oleic variants for improved product performance.
For New Entrants and Emerging Players:FDA labeling guidance in the US opens a window for new entrants to innovate in plant-based dairy and meat alternatives. Target the premium retail segment with certified organic and non-GMO olive and coconut oils. Develop specialty oil blends for the food service sector, offering customized functional properties. A direct-to-consumer go-to-market angle with strong origin transparency can differentiate offerings.
For Investors and Strategic Acquirers:Re-rating potential sits with mid-cap specialty processors given increasing consumer demand for certified-origin and organic products. The long-term viability of the market reflects sustained consumer shifts towards health and sustainability. Acquisition targets should include niche players with strong brand equity or unique processing technologies. Practitioners should monitor increased M&A activity in specialty oil segments as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Secures baseline supply for growing food manufacturing demand. |
| Organic Certification Investment | Accesses high-margin retail channels and health-conscious consumers. |
| High-Oleic Cultivar Development | Delivers enhanced stability and fry-life for food service clients. |
| Digital Traceability Integration | Builds consumer trust and differentiates premium offerings. |
| Specialty Blend Formulation | Provides value-added solutions for diverse food manufacturing needs. |
Research Approach
USDA agricultural reports, FDA guidance documents, and industry association publications formed the secondary backbone for this market analysis. Primary interviews with oilseed growers, food manufacturers, distributors, and retail buyers validated secondary data points. This approach combined top-down market sizing with bottom-up segment validation.
Historical trendline analysis established baseline market dynamics and growth patterns across the US plant-based oils market. The analytical framework incorporated quantitative modeling and qualitative insights to project future trends. Segmentation dimensions modeled included product type, distribution channel, end user, and grade. Compound annual growth rates were derived from historical data and projected market drivers, with agricultural commodity price forecasts as a key input.
Caveats apply where significant shifts in agricultural policy or global commodity markets could materially shift the outlook for plant-based oils. Forecasts reflect assumptions regarding consumer preferences and technological advancements. Practitioners should monitor evolving consumer health perceptions and feedstock supply stability for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Global Bioactive Ingredients Market
Ingredients
Bovine Gelatin Market
Ingredients
Asia-Pacific Food Coating Ingredients Market
Ingredients
Cold Pressed Oil Market
Ingredients
Casein and Caseinates Market
Ingredients
Chewing Gum Base Market
Ingredients
Asia-Pacific Protein Market
Ingredients
Licorice Root Market
Ingredients
Dry Mixes Market
Ingredients
Plant Based Ingredients Market
Ingredients
Mannan-Oligosaccharide (MOS) Market
Ingredients
Industrial Starch Market
Ingredients
Fats and Oils Market
Ingredients
South America Insoluble Dietary Fibers Market
Ingredients
Agarwood Oil Market
Ingredients
2'-Fucosyllactose (2'-FL) Market