
 Isoamyl Laurate Market | 2026-2036
Isoamyl Laurate Market Size, Share, and Industry Trends Forecast 2026-2036
Isoamyl Laurate Market Foresight
The EU Green Deal's chemical sustainability targets are restructuring ingredient sourcing across European personal care manufacturing. BASF SE leverages its integrated biotechnology platforms to secure fermentation-derived fatty acid supply chains. Croda International anchors its competitive position through specialty ester chemistry expertise and broad cosmetic customer relationships. Evonik Industries differentiates via advanced catalysis capabilities that tighten isoamyl alcohol conversion yields.
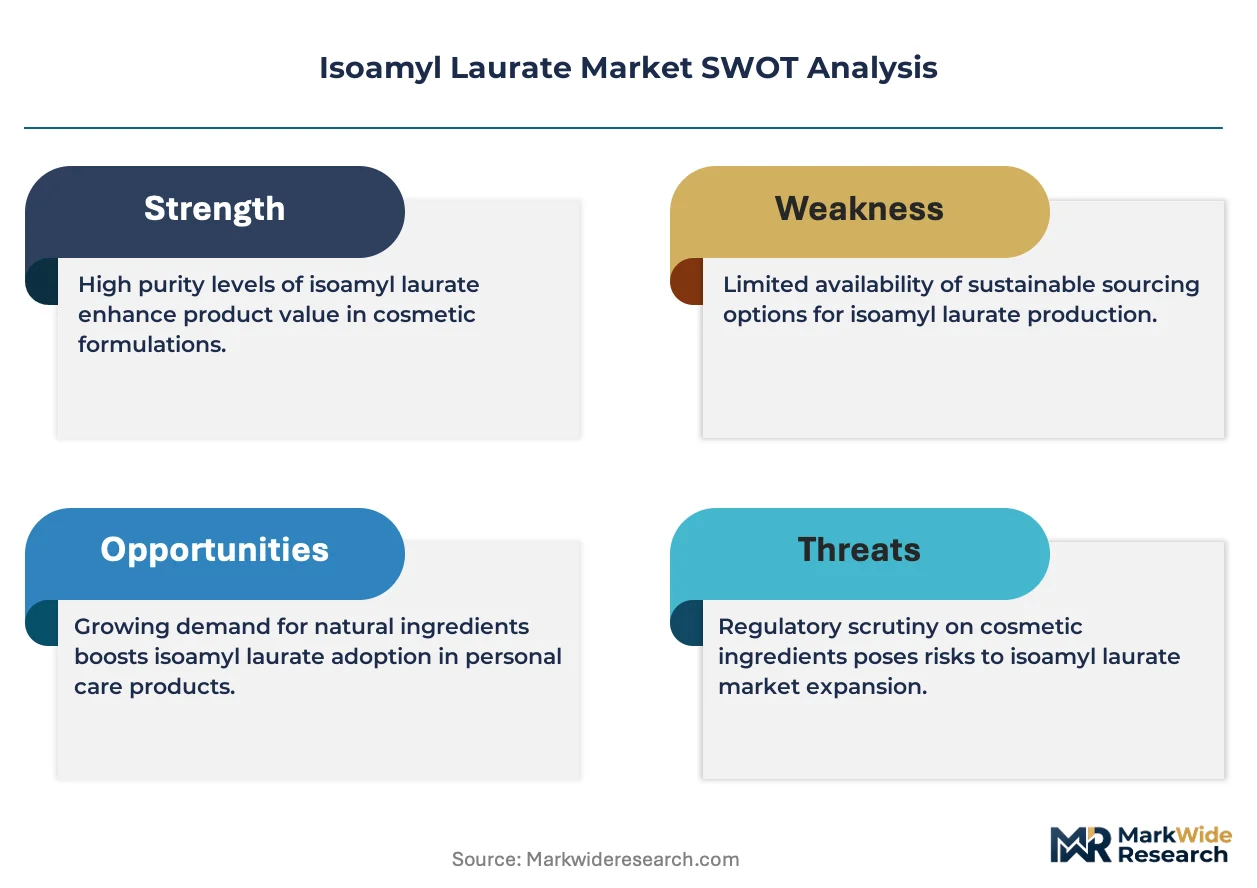
Isoamyl laurate is a fatty acid ester synthesized from isoamyl alcohol and lauric acid, typically exhibiting a light, dry emollient feel with a molecular weight around 270 g/mol and pour points below 15°C, serving primarily as a silicone alternative in skin and hair formulations. The cosmetics product type segment dominates value capture due to premium positioning of natural-origin claims in skincare and sun care applications. The personal care application segment leads volume absorption through widespread incorporation in leave-on and rinse-off products, while pharmaceutical applications sustain above-average margin pools through excipient purity requirements.
REACH registration obligations and the EU F-Gas Regulation shape raw material access and process emissions accountability for isoamyl laurate manufacturers operating within Europe. ECHA substance evaluation protocols determine continued market authorization for specific impurity profiles, directly influencing formulation reformulation cycles among downstream customers. Stakeholders must monitor evolving bio-based certification standards and polymer-grade purity thresholds to sustain formulation approval pathways.
Market Dynamics
The EU Green Deal's chemical sustainability mandates are restructuring fatty acid ester procurement across European personal care manufacturing, redirecting formulation houses toward certified bio-based supply chains and tightening compliance requirements for petrochemical-derived alternatives.
Growth Catalysts
- REACH registration pathways:ECHA's streamlined bio-based substance evaluation protocols are accelerating market authorization timelines for plant-derived isoamyl laurate variants, reducing reformulation cycle risks for cosmetics manufacturers.
- Silicone substitution demand:Formulators in Germany and France are accelerating uptake of light emollients amid tightening EU F-Gas Regulation restrictions on volatile silicone compounds in leave-on skincare.
- Fermentation platform maturation:Industrial biotechnology advances in lauric acid production are compressing cost differentials between petrochemical and bio-based feedstock routes.
Market Restraints
- Coconut oil price volatility:Tropical weather disruptions and competing food demand are destabilizing lauric acid input costs for ester manufacturers dependent on Southeast Asian supply.
- Isoamyl alcohol supply concentration:European production clusters around BASF Ludwigshafen and limited alternative suppliers create single-source vulnerability for regional formulators.
- Polymer-grade purity thresholds:Pharmaceutical excipient specifications exceeding 99.5% purity impose yield losses and filtration capex that constrain margin expansion.
Strategic Opportunities
- Pharmaceutical excipient expansion:Drug delivery system manufacturers in Switzerland are qualifying isoamyl laurate as a solubilizing agent for lipophilic APIs, opening above-average margin pools.
- CSRD disclosure alignment:The EU Corporate Sustainability Reporting Directive is creating procurement preference for esters with verified Scope 3 carbon footprints and mass-balance certifications.
- Supercritical fluid processing:Convergence of CO2 extraction technology with enzymatic esterification is enabling solvent-free production routes that qualify for organic cosmetic certifications.
Industry Challenges
- Enzyme stability engineering:Lipase catalyst deactivation during continuous esterification runs requires specialized bioprocess engineering talent scarce in traditional oleochemical operations.
- Mass-balance audit complexity:ISCC PLUS certification demands granular feedstock tracing through multi-step esterification that strains legacy ERP systems and documentation workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isoamyl Laurate Market |
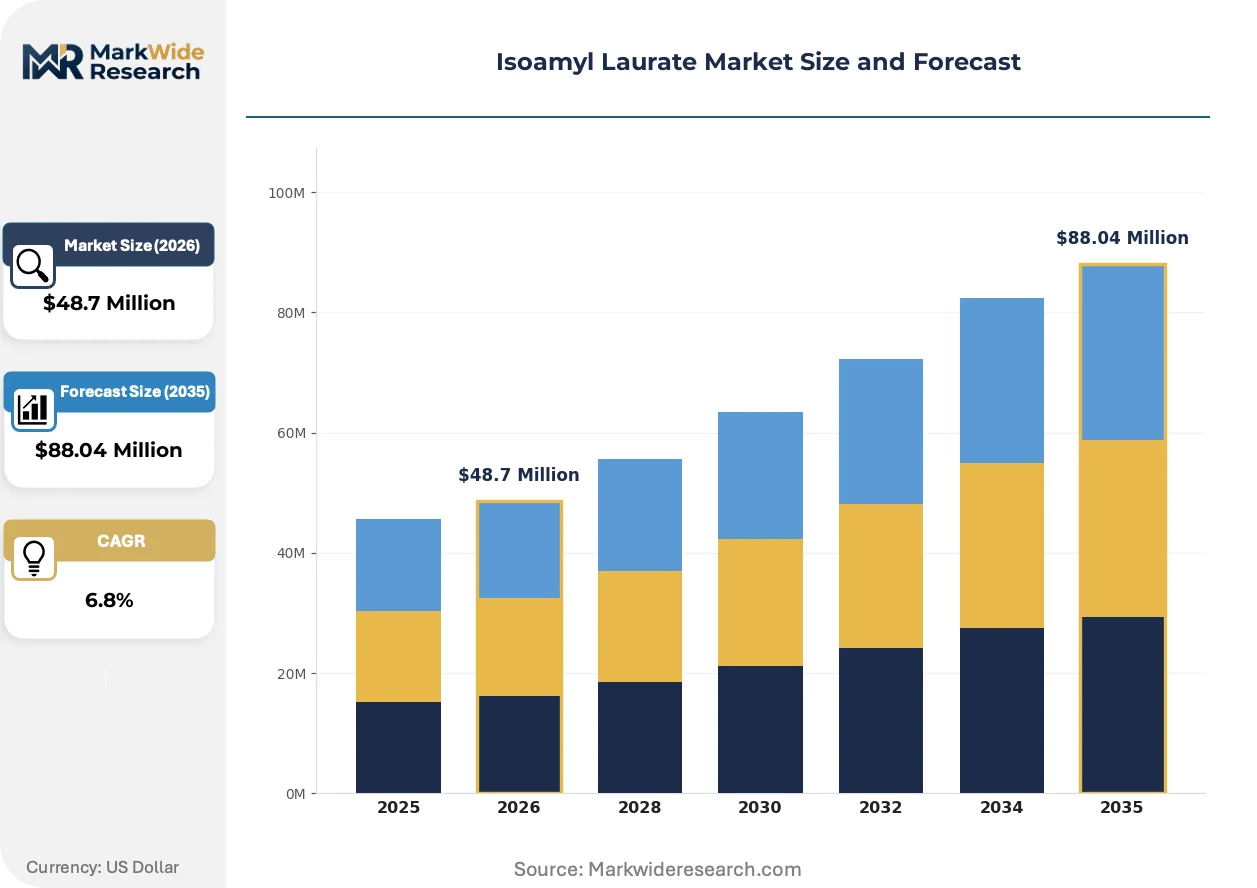
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $88.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cosmetics, Food Additive, Industrial Solvent, Emulsifier Application: Personal Care, Pharmaceuticals, Food Industry, Coatings End User: Manufacturers, Retailers, Wholesalers, Distributors Distribution Channel: Online Retail, Specialty Stores, Direct Sales, B2B Platforms |
| Companies Covered | Dow Inc., Ashland, BASF SE, Clariant, Oleon, Evonik Industries, Symrise, Seppic, Croda International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isoamyl Laurate Market Shifts & Advancements
Process intensification and regulatory disclosure requirements are converging to reshape how fatty acid esters are manufactured, certified, and procured across European personal care value chains.
Enzymatic esterification using immobilized lipase biocatalysts is modularizing production economics for mid-scale isoamyl laurate batches. Specialty chemical manufacturers in the Netherlands and Belgium are adopting these systems to avoid high-pressure thermal processing. The technology is modularizing capital deployment, enabling distributed production closer to formulation customers rather than centralized petrochemical complexes.
REACH authorization sunset clauses for specific petrochemical plasticizers are tightening substitution timelines across cosmetics and pharmaceutical applications. ECHA's 2024-2026 substance evaluation work program prioritizes endocrine-disrupting screening for legacy emollients. Sun care and baby care segments are responding fastest, with reformulation cycles compressing from 18 months to 9 months to secure continuity of market access.
Buyer concentration among European multinational personal care houses is consolidating procurement power and demanding outcome-based sustainability metrics rather than ingredient-level certifications. Regional distributors are losing share to direct manufacturer relationships as Unilever and L'Oréal centralize ester sourcing through dedicated supply agreements. France and Germany exhibit the most pronounced channel consolidation, with formulation houses bypassing traditional chemical distributors for certified bio-based supply.
Isoamyl Laurate Market Segmentation
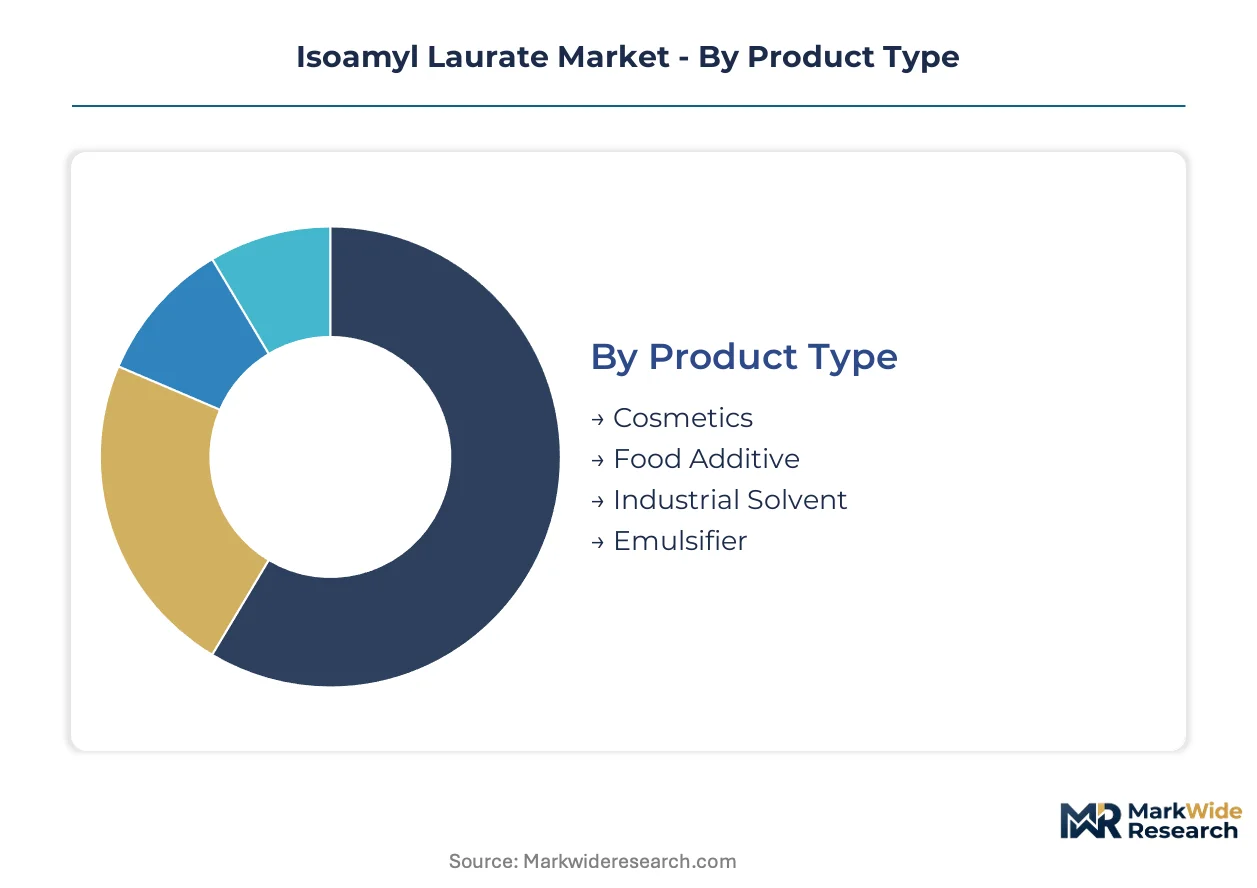
Isoamyl laurate's position as a silicone alternative and bio-based emollient creates distinct value pools across formulation grades and customer channels. Segmentation reveals where fermentation-derived supply chains command premium positioning versus commodity ester applications.
Product Type:
Capital deployment varies sharply across product categories, with pharmaceutical-grade purification infrastructure requiring the heaviest fixed-asset commitments.
- Cosmetics:High-purity ester grades meeting ECOCERT and COSMOS standards for natural-origin claims. German and French formulators absorb the majority of volume amid REACH-driven substitution of cyclomethicones in leave-on skincare. REACH authorization pressures on volatile silicones are accelerating reformulation timelines toward this segment.
- Food Additive:Flavor carrier applications leveraging isoamyl laurate's neutral taste profile and lipophilic solubility. EFSA food contact material approvals determine market access for food-grade production assets concentrated in Western Europe. Regulatory compliance costs limit producer participation to established oleochemical houses.
- Industrial Solvent:Degreasing and precision cleaning applications where low surface tension and rapid evaporation drive specification. Metalworking and electronics manufacturing in industrial clusters absorb volume through distributor networks.
- Emulsifier:Auxiliary surfactant functionality in water-in-oil systems for sun care and color cosmetics. Specialty ester chemistry expertise determines competitive positioning among European personal care ingredient suppliers.
Most installed capacity flows through Cosmetics. Expansion is steepest in Food Additive as clean-label flavor systems displace synthetic carriers.
Application:
Customer concentration patterns distinguish volume-driven personal care procurement from margin-protected pharmaceutical qualification cycles.
- Personal Care:Skin and hair formulations absorbing the majority of European ester volume through direct supply agreements with multinational houses. Unilever and L'Oréal centralization of bio-based ingredient sourcing is compressing distributor margins. Silicone substitution mandates under the EU F-Gas Regulation are restructuring leave-on product formulations toward plant-derived emollients.
- Pharmaceuticals:Drug delivery excipient applications requiring USP-NF compliance and impurity profiling below 0.1%. Swiss and German drug manufacturers are qualifying isoamyl laurate for lipophilic API solubilization. Purity thresholds above 99.5% impose yield losses that constrain supplier participation.
- Food Industry:Flavor encapsulation and controlled-release systems for bakery and confectionery applications. FSSAI and FDA parallel approvals enable export-oriented production from European bio-refineries.
- Coatings:Low-VOC solvent and coalescing agent functions in decorative and industrial paint systems. German automotive OEM specifications are incorporating bio-based content requirements into supplier scorecards.
Personal Care commands the largest volume share. Pharmaceuticals deliver the steepest margin expansion trajectory as excipient qualification cycles extend supplier relationships.
End User:
Procurement sophistication separates integrated manufacturers with dedicated supply agreements from intermediaries managing inventory risk across fragmented customer bases.
- Manufacturers:Personal care compounders and pharmaceutical formulators with direct fermentation-derived supply contracts. CSRD disclosure requirements are forcing Scope 3 carbon accounting that favors certified mass-balance supply chains.
- Retailers:Specialty beauty and natural product channels with private-label formulation programs. Clean-label positioning requirements are filtering ingredient specifications toward bio-based certification.
- Wholesalers:Regional chemical distributors consolidating small-batch orders for mid-tier cosmetics houses. REACH documentation burdens are eroding competitiveness against direct manufacturer relationships.
- Distributors:Pan-European logistics providers with inventory positioning across multiple ester grades. Channel consolidation among multinational buyers is compressing margins and reducing SKU breadth.
Manufacturers capture the deepest supply chain integration. Retailers are gaining share fastest as direct-to-consumer beauty brands proliferate.
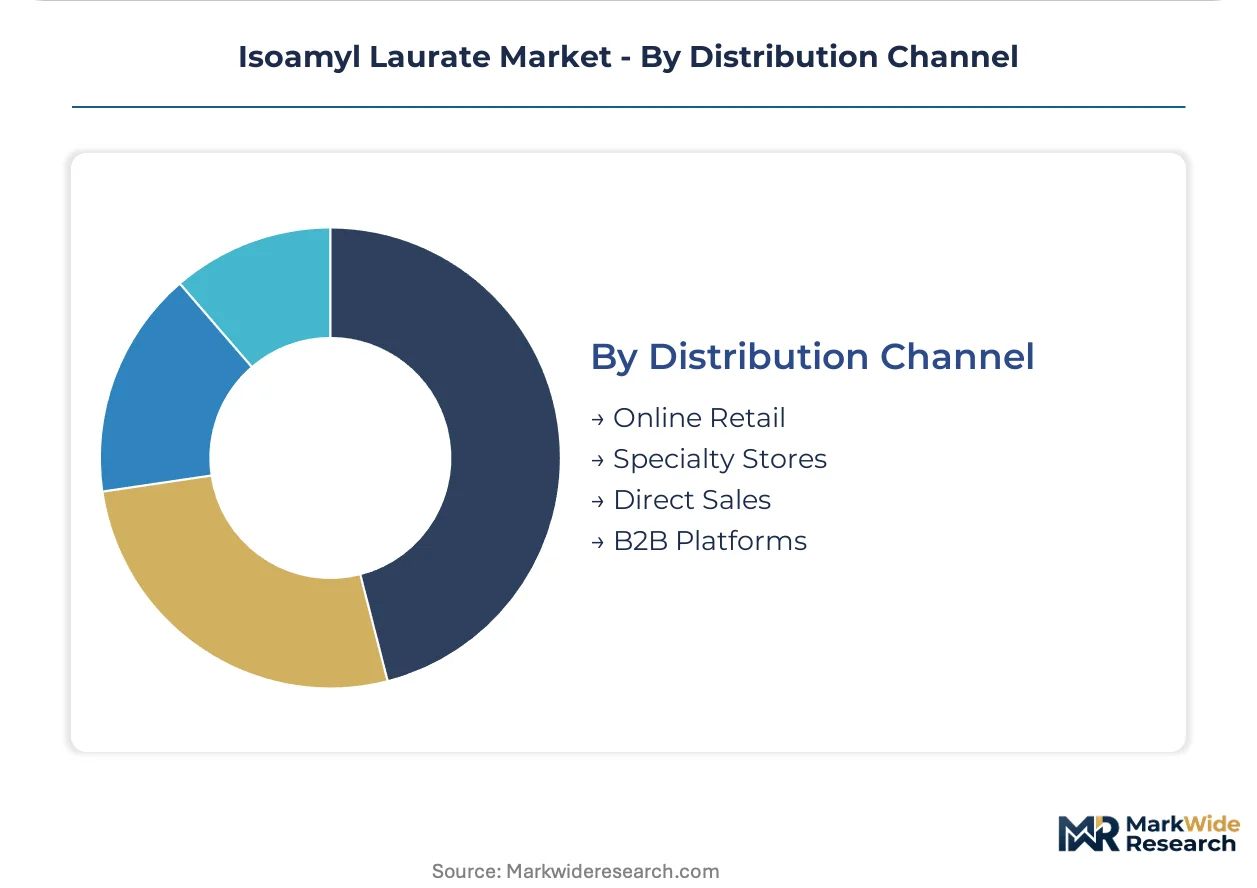
Distribution Channel:
Digital procurement infrastructure is displacing traditional specialty chemical representation for standardized ester grades.
- Online Retail:E-commerce platforms serving small-batch cosmetics startups and independent formulators. ISCC PLUS certification transparency features are becoming table stakes for platform inclusion.
- Specialty Stores:Regional chemical distributors with technical service capabilities for formulation support. REACH compliance documentation and safety data sheet management remain core value-added functions.
- Direct Sales:Dedicated account management for multinational personal care houses with annual volume commitments. Long-term offtake agreements with fermentation platform operators are locking in supply security.
- B2B Platforms:Digital marketplaces connecting mid-scale buyers with certified bio-based suppliers. Real-time carbon footprint disclosure is emerging as a procurement filter.
Direct Sales channels handle the majority of volume. B2B Platforms are expanding most quickly as procurement digitization accelerates among mid-tier formulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Isoamyl laurate production scaled first in European oleochemical clusters during the 1990s as fermentation-derived fatty acid platforms matured in Germany and the Netherlands. German chemical engineering expertise and French cosmetics formulation demand established the industry's foundational geography. Today, regional specialization concentrates around regulatory compliance capabilities and bio-refinery infrastructure.
Germany
REACH registration expertise and F-Gas Regulation compliance drive demand from personal care formulators in North Rhine-Westphalia. The country's national chemical regulator maintains stringent substance evaluation protocols that favor documented bio-based supply chains. BASF's Ludwigshafen complex anchors fermentation-derived lauric acid production, supplying ester manufacturers across the Rhine corridor.
France
Cosmetics houses in the Île-de-France region accelerate silicone substitution programs for leave-on skincare formulations. EU Green Deal chemical sustainability targets redirect procurement toward certified plant-derived emollients. L'Oréal's centralized sourcing operations in Clichy-sous-Bois lock in multi-year offtake agreements with bio-based ester suppliers.
Switzerland
Pharmaceutical excipient qualification cycles in Basel and Geneva generate above-average margin pools for ultra-high-purity grades. Swissmedic's drug delivery system approvals determine market access for lipophilic API solubilization applications. Lonza and specialized drug manufacturers in the Basel biotech cluster are qualifying isoamyl laurate for controlled-release formulations.
Netherlands
Industrial biotechnology platforms in the Rotterdam-Antwerp port corridor compress cost differentials between petrochemical and fermentation-derived feedstocks. ISCC PLUS certification infrastructure supports mass-balance tracing for cosmetics exports. Oleon's bio-refinery operations in Ghent supply enzymatic esterification capacity serving mid-scale European formulators.
Belgium
Specialty chemical distributors in the Antwerp logistics hub consolidate small-batch orders for mid-tier cosmetics houses. ECHA substance evaluation documentation requirements strain legacy ERP systems among regional traders. Clariant's Belgian operations provide formulation support services linking ester chemistry expertise to French and German personal care manufacturers.
Isoamyl Laurate Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification grade and application purity tiers. The vendor base organizes around three strategic archetypes: integrated fermentation platform operators, specialty ester chemistry houses, and regional distribution intermediaries. Consolidation pressures concentrate procurement power among multinational personal care houses. Dominant competitive moves include backward integration into lauric acid supply and direct long-term offtake agreements bypassing traditional chemical distributors.
Within the integrated platform tier, BASF SE and Evonik Industries exemplify fermentation-derived supply chain control. Among specialty ester specialists, Croda International occupies a position anchored in cosmetic customer relationships and broad certification coverage. Dow Inc. represents the diversified chemical conglomerate archetype with cross-segment portfolio breadth. These three companies illustrate how competitive positioning stratifies across biotechnology integration depth versus formulation service intensity.
| Leading Market Players |
|---|
| Dow Inc. |
| Ashland |
| BASF SE |
| Clariant |
| Oleon |
| Evonik Industries |
| Symrise |
| Seppic |
| Croda International |
| Others |
Supply & Pricing Matrix
Enzymatic esterification technology maturation is compressing cost differentials between thermal and biocatalytic production routes while dispersing manufacturing capacity across smaller, distributed sites rather than centralized petrochemical complexes. This shift fragments pricing power away from incumbent oleochemical majors and enables mid-scale European formulators to negotiate directly with fermentation platform operators.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, cosmetics-certified, and industrial-solvent levels dominates transaction structures. Price differentiation rests on certification tier—ECOCERT and COSMOS premiums command 15-25% spreads over uncertified grades—and volume scale, with multinational personal care houses extracting preferential terms through multi-year offtake commitments. Cost compression in industrial-solvent grades is intensifying because Southeast Asian lauric acid supply volatility feeds through to spot market quotations. Small-batch cosmetics startups exhibit highest price sensitivity, while Swiss pharmaceutical excipient buyers prioritize purity guarantees over unit economics.
Supply Chain Analysis
Dual-sourcing requirements mandated by REACH-registered cosmetics manufacturers are forcing formulators to qualify secondary fermentation-derived suppliers beyond BASF Ludwigshafen. Geographic supply concentrates in Germany, the Netherlands, and Belgium, with Rotterdam-Antwerp port infrastructure anchoring bio-refinery feedstock flows. Raw material dependencies draw from coconut oil fractions, isoamyl alcohol streams, and immobilized lipase biocatalysts. Single-source vulnerability around European isoamyl alcohol production creates structural risk for regional formulators. Distribution runs through direct manufacturer relationships for multinational buyers, with B2B platforms capturing mid-tier cosmetics house volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: fermentation-derived production in the Netherlands and Belgium carries 12-18% cost advantages over thermal processing in Germany due to integrated port logistics and shared bio-refinery infrastructure, while Swiss pharmaceutical qualification cycles sustain margin premiums unavailable elsewhere in Europe.
For Market Incumbents: Acquire fermentation platform assets in the Rotterdam-Antwerp corridor to secure captive lauric acid supply. BASF and Evonik should consolidate enzymatic esterification capacity to defend against specialty chemical distributors losing share to direct manufacturer relationships. ISCC PLUS certification infrastructure investment protects against EU Green Deal disclosure requirements tightening procurement qualification thresholds. For New Entrants and Emerging Players: EU F-Gas Regulation in Germany and France opens a window for silicone-substitute emollient specialists to capture reformulation cycle demand from mid-tier cosmetics houses bypassing traditional distributors. Target pharmaceutical excipient applications in Switzerland where purity premiums exceed cosmetics grades. Pursue B2B platform partnerships with real-time carbon footprint disclosure as the primary go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among regional chemical distributors with legacy ERP systems straining under mass-balance audit complexity. Long-term viability over the next decade hinges on backward integration into fermentation-derived feedstocks or downstream formulation service capabilities. Watch for ECHA substance evaluation sunset clause announcements as the inflection signal triggering accelerated M&A among specialty ester producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Assets | BASF's Ludwigshafen complex secures lauric acid supply chains against Southeast Asian price volatility. |
| ISCC PLUS Certification Investment | Oleon's Ghent bio-refinery qualifies mass-balance tracing for L'Oréal's centralized sourcing operations. |
| Pharmaceutical Excipient Qualification | Lonza's Basel cluster validates isoamyl laurate for Swissmedic-controlled drug delivery systems. |
| Enzymatic Esterification Scale-Up | Dutch and Belgian mid-scale producers avoid high-pressure thermal processing capital intensity. |
| Direct Manufacturer Relationship Programs | Unilever and L'Oréal offtake agreements displace regional chemical distributors across France and Germany. |
Research Methodology
Coverage spans Germany, France, Switzerland, the Netherlands, and Belgium, with primary inputs from each market triangulated against secondary validation. Primary interviews engaged plant managers at fermentation facilities, procurement leads at multinational personal care houses, technical R&D directors in specialty ester chemistry, and distribution channel partners in the Antwerp logistics hub. Secondary sources incorporated ECHA substance evaluation databases, SEC filings from diversified chemical conglomerates, Cefic oleochemical trade statistics, and customs records tracking lauric acid derivative flows. Bottom-up volume modeling and top-down value reconciliation ensured cross-verification of segment estimates.
Rate-of-change decomposition anchored the analytical framework, with CAGRs derived from segment-level growth differentials across the projection horizon. Segmentation dimensions modeled include product grade tier, end-use application, certification status, and regional production hub concentration. Industry-specific forecast inputs incorporated REACH authorization timeline assumptions and EU F-Gas Regulation substitution elasticity parameters for silicone alternatives.
Forecast precision tightens around the base case; tail outcomes carry wider variance under coconut oil supply disruption scenarios or accelerated ECHA endocrine-disruptor screening protocols. Forecasts reflect documented assumptions on fermentation platform yield improvements and enzymatic catalyst stability engineering timelines. Deviation in ECHA substance evaluation sunset clause schedules would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
PDO/PGI-Linked Mediterranean Ingredient Collections Market
Ingredients
Egg Yolk Powder Market
Ingredients
North America Whey Protein Ingredients Market
Ingredients
Thinned Starch Market
Ingredients
Europe Amino Acid Market
Ingredients
Roasted Grain Ingredients Market
Ingredients
Hydroxytyrosol Market
Ingredients
Cooking Oil Market
Ingredients
Asia Pacific Vegetable Oil Market
Ingredients
Yeast Flakes Market
Ingredients
Demineralized Whey Powder Ingredient Market
Ingredients
Pea Starch Market
Ingredients
Citrus Pectin Market
Ingredients
Hydrolyzed Pork Protein Market
Ingredients
Global Apricot Oil Market
Ingredients
Olive Leaf Extract Market