
 North America Potato Starch Market | 2026-2036
North America Potato Starch Market Size, Share, and Industry Trends Forecast 2026-2036
North America Potato Starch Market Intelligence
Market Context
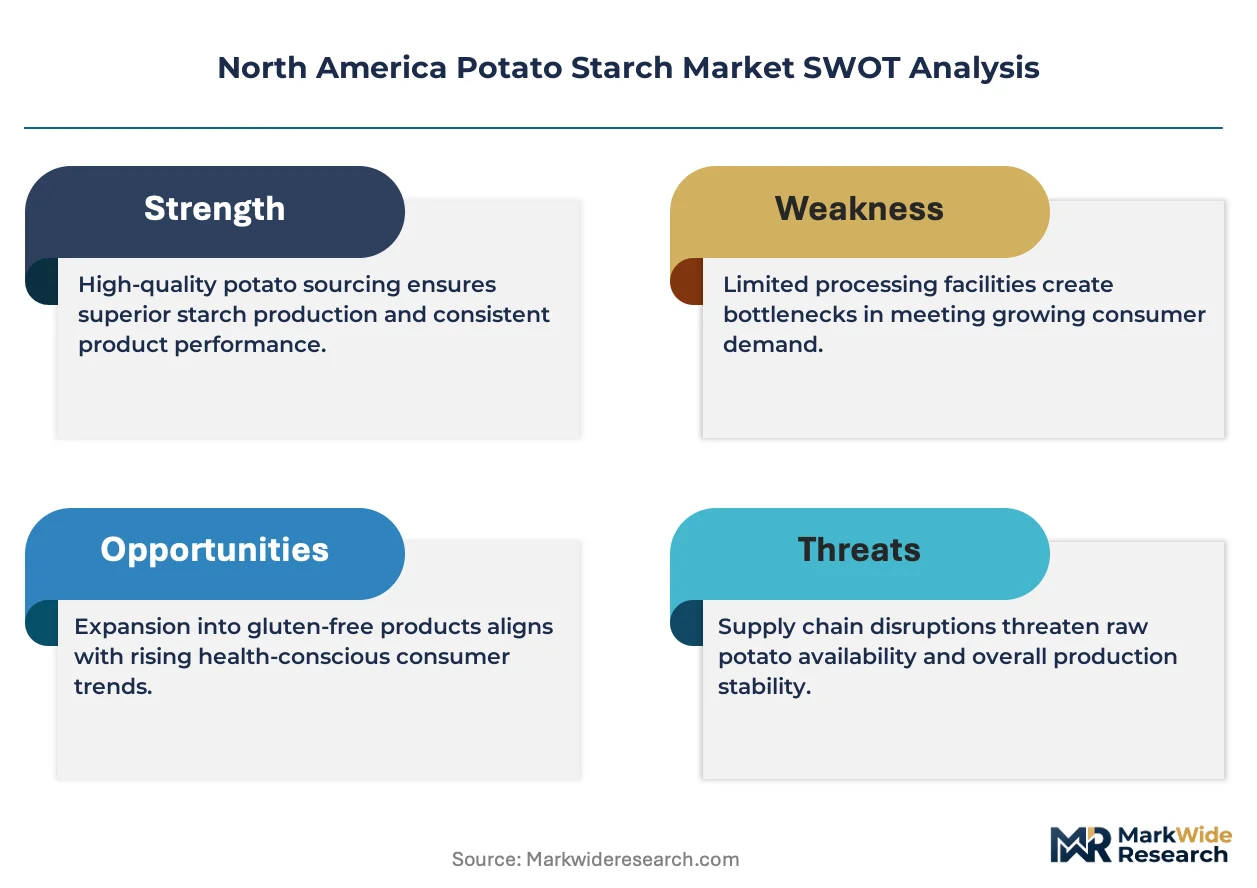
Non-GMO Project verification is reorganizing competitive access across the North America Potato Starch Market, as retailers and food manufacturers gate shelf placement behind third-party certification. Cargill, Incorporated leverages its integrated agricultural procurement network to secure identity-preserved potato supply chains from contract growers. Roquette Frères sustains technical leadership in modified starch functionalities through dedicated application laboratories in the region.
Technical Definition and Segment Structure
Potato starch is the refined carbohydrate extracted from Solanum tuberosum tubers through wet-milling, washing, and drying, yielding granules with high amylopectin content, low gelatinization temperature, and exceptional clarity in gelled applications. Native starch dominates volume flows in food manufacturing, where its neutral flavor and high viscosity suit clean-label sauces and soups, while modified starch commands margin premiums in industrial adhesives and textile sizing where cross-linked and acetylated chemistries deliver controlled rheology under shear stress. The pharmaceutical end-user segment is expanding fastest as excipient-grade potato starch meets USP-NF disintegration standards for tablet formulations.
Regulatory Framework and Outlook
The FDA governs food-grade potato starch under 21 CFR 172.892 for modified variants and GRAS self-determination for native forms, while the USDA National Organic Program shapes premium pricing for certified organic supply chains. EPA effluent guidelines for potato processing plants constrain wet-milling capacity expansion and favor investments in water-recovery systems. Stakeholders must monitor how FDA guidance on novel starch modification technologies reshapes competitive barriers between native and modified product tiers.
Market Dynamics
Clean-label reformulation mandates from major retailers are compressing synthetic thickener demand and redirecting volume toward identity-preserved potato starch supply chains across food manufacturing.
Growth Catalysts
- 21 CFR 172.892 Streamlining:The FDA's consolidated approval pathway for modified food starches accelerates product launch timelines for cross-linked potato starch variants in sauce applications.
- Midwestern Processing Clusters:North Dakota and Minnesota host integrated wet-milling facilities that reduce transport costs and enable just-in-time delivery to CPG manufacturers.
- Pharmaceutical Excipient Grade:USP-NF disintegration standards for tablet formulations pull high-purity potato starch into oral solid dosage manufacturing.
Market Restraints
- Input Cost Volatility:Fresh potato prices fluctuate with weather-driven yield variation in the Red River Valley, squeezing margin predictability for wet-mill operators.
- EPA Effluent Constraints:Water discharge limits on potato processing plants cap capacity expansion and force capital allocation toward recovery systems rather than output growth.
- Corn Starch Substitution:Lower-cost maize-derived thickeners capture volume in cost-sensitive industrial adhesives and textile sizing applications.
Strategic Opportunities
- Canadian Organic Certification:The USDA National Organic Program equivalency agreement opens premium pricing channels for Canadian-grown supply entering US distribution.
- Bioplastics Film Extrusion:Thermoplastic starch formulations are converging with blown-film equipment advances to replace petroleum-based packaging in produce wrapping.
- Direct-to-Bakery Distribution:Specialty ingredient distributors bypass traditional broadline foodservice channels to capture margin in artisan bread and gluten-free formulations.
Industry Challenges
- Non-GMO Verification Timeline:Project certification requires 12-18 month audit cycles that delay contract negotiations with retailer private-label programs.
- Wet-Milling Technical Talent:Specialized process engineers with starch separation expertise are concentrated among retiring cohorts at legacy processing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Potato Starch Market |
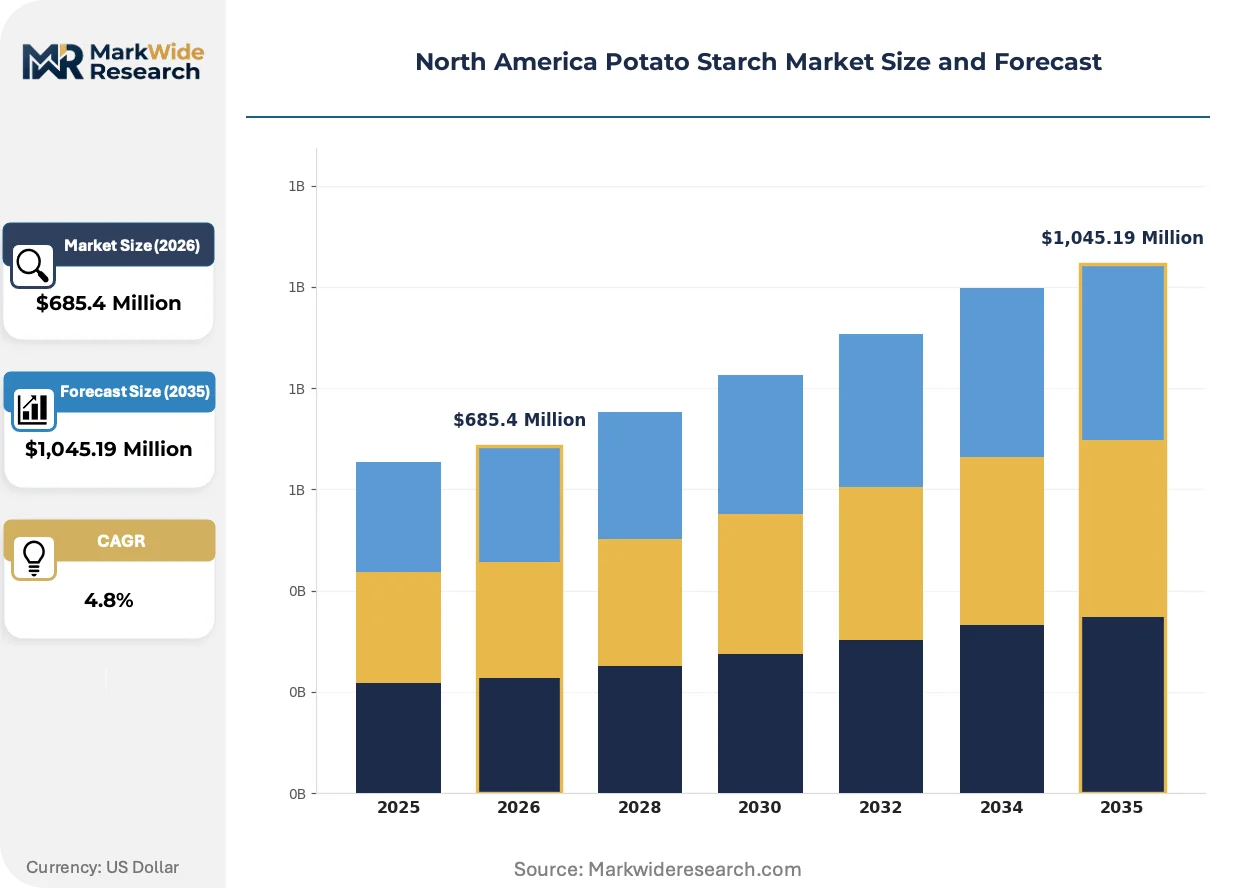
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,045.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Native Starch, Modified Starch, Pregelatinized Starch, Liquid Starch Application: Food & Beverage, Adhesives, Paper Industry, Textile Processing End User: Food Manufacturers, Pharmaceutical Industry, Personal Care, Industrial Sector Packaging Type: Bulk Bags, Retail Bags, Containers, Pails |
| Companies Covered | Tate & Lyle, Roquette Frères, Cargill, Incorporated, Cooperative Avebe UA, Manitoba Starch Inc., Ingredion, Emsland Group, KMC Ingredients, ADM, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Potato Starch Market Strategic Shifts & Innovations
Enzymatic debranching technologies are rewriting functionality specifications across modified starch tiers, enabling manufacturers to tailor viscosity profiles without synthetic chemical cross-linking.
Physical modification through annealing and heat-moisture treatment is supplanting traditional chemical modification in clean-label sauce applications. Mid-tier CPG manufacturers are adopting these processes at pilot scale to meet retailer ingredient blacklists. The shift is compressing demand for acetylated and phosphorylated variants while expanding premium positioning for physically treated native starches.
The FDA's updated GRAS self-determination guidance for novel starch modification creates compliance clarity for enzymatically treated products. Food manufacturers gain faster pathway to market without pre-market notification burdens. Small and mid-sized ingredient suppliers in the Midwest are responding by filing determination packages for emerging physical modification protocols.
Retailer-driven procurement consolidation is compressing supplier rosters as Walmart and Kroger mandate single-source accountability for clean-label ingredient categories. Broadline distributors are losing shelf placement to vertically integrated potato processors with direct bakery and sauce manufacturing relationships. The pattern is most visible in California and Pacific Northwest retail markets where private-label penetration exceeds national averages.
North America Potato Starch Market Segmentation
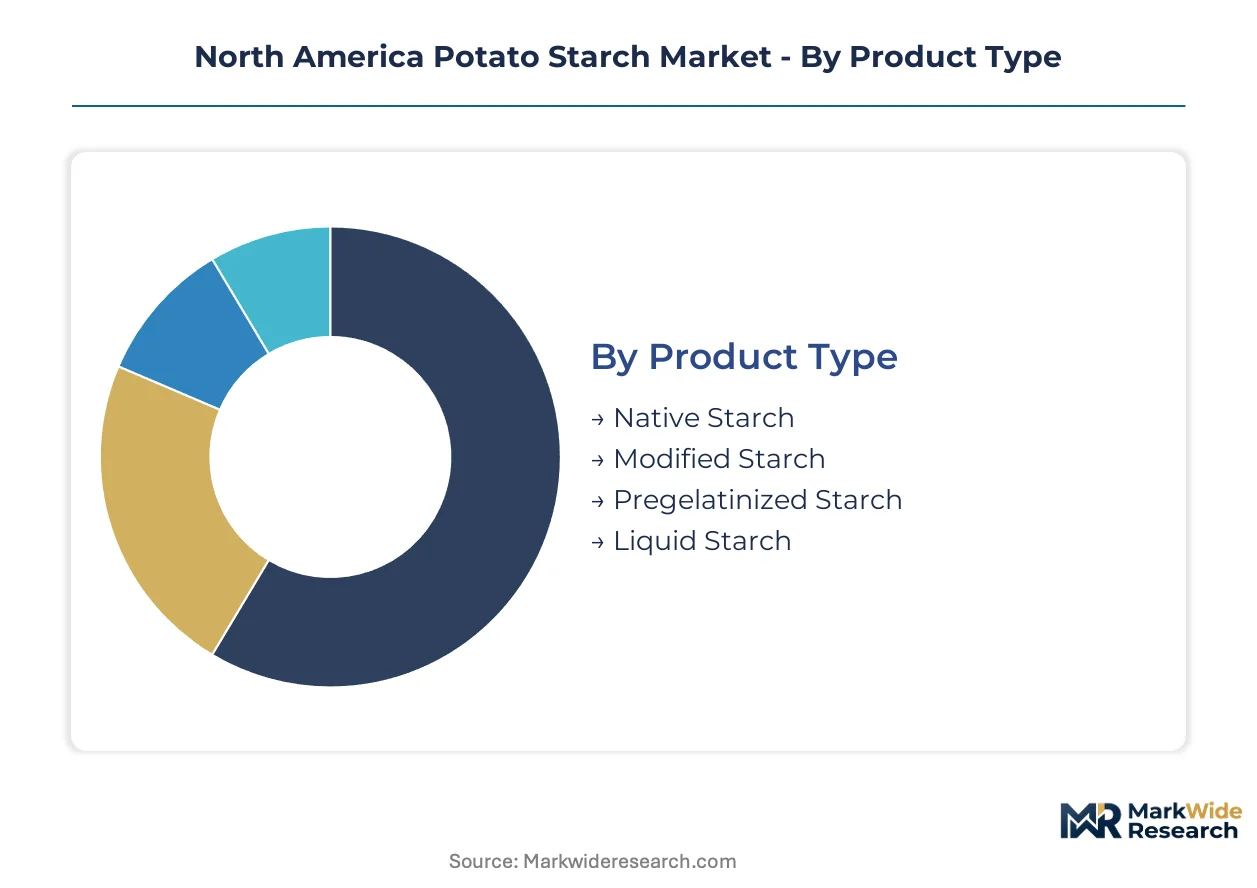
Margin concentration in North American potato starch diverges sharply across product tiers and end-use specifications. Clean-label procurement mandates from major retailers are reweighting segment priorities away from commodity volume toward certified specialty grades.
Product Type:
Modified starch commands the widest margin spreads, driven by pharmaceutical and industrial adhesive applications requiring precise rheology control.
- Native Starch:Extracted through wet-milling without chemical alteration, this grade delivers high clarity and neutral flavor for clean-label soups and sauces. Food manufacturers in the Midwest are locking in multi-year contracts with North Dakota processors to secure identity-preserved supply chains ahead of Non-GMO Project verification requirements.
- Modified Starch:Cross-linked, acetylated, and phosphorylated variants achieve controlled viscosity under thermal and shear stress. Pharmaceutical tablet manufacturers specify USP-NF grade material for disintegration performance, while textile sizing operations in the southeastern United States favor cross-linked chemistries for warp strength.
- Pregelatinized Starch:Pre-cooked granules hydrate without heating, enabling instant thickening in dry bakery mixes and convenience foods.
- Liquid Starch:Slurry formulations reduce dust exposure and simplify handling in high-volume paper coating operations.
Native starch holds installed capacity across Red River Valley wet-mills. Modified starch is rotating up the share rankings on pharmaceutical excipient demand.
Application:
Volume concentration sits with food manufacturing, though adhesive and textile segments generate superior per-ton profitability through technical specification premiums.
- Food & Beverage:Sauces, soups, and bakery applications leverage potato starch for freeze-thaw stability and sheen. Clean-label reformulations at major CPG manufacturers are displacing synthetic hydrocolloids with identity-preserved native grades, particularly in private-label programs at Walmart and Kroger.
- Adhesives:Corrugated board lamination and wood glue formulations exploit high amylopectin content for tack development. Industrial adhesive compounders in Ohio and Pennsylvania specify modified variants with controlled set times to match high-speed production lines.
- Paper Industry:Surface sizing and coating operations value starch for printability enhancement and fiber bonding.
- Textile Processing:Warp sizing protects yarn during weaving; desirability depends on complete washout without residue.
Food and beverage maintains volume leadership. Adhesives is climbing fastest on packaging sector expansion.
End User:
Pharmaceutical qualification requirements create the steepest entry barriers and corresponding margin protection for certified suppliers.
- Food Manufacturers:CPG and bakery operations constitute the foundational demand base, with procurement increasingly centralized through direct processor relationships bypassing broadline distribution.
- Pharmaceutical Industry:Oral solid dosage manufacturing requires excipient-grade material meeting USP-NF disintegration and microbial specifications. FDA inspection history and DMF availability determine supplier eligibility for ANDA filings.
- Personal Care:Powder formulations and dry shampoo applications value starch for oil absorption and tactile properties.
- Industrial Sector:Adhesive, textile, and paper operations prioritize cost-position over certification, exposing suppliers to corn starch substitution pressure.
Food manufacturers dominate volume throughput. Pharmaceutical is expanding most quickly on generic drug manufacturing growth.
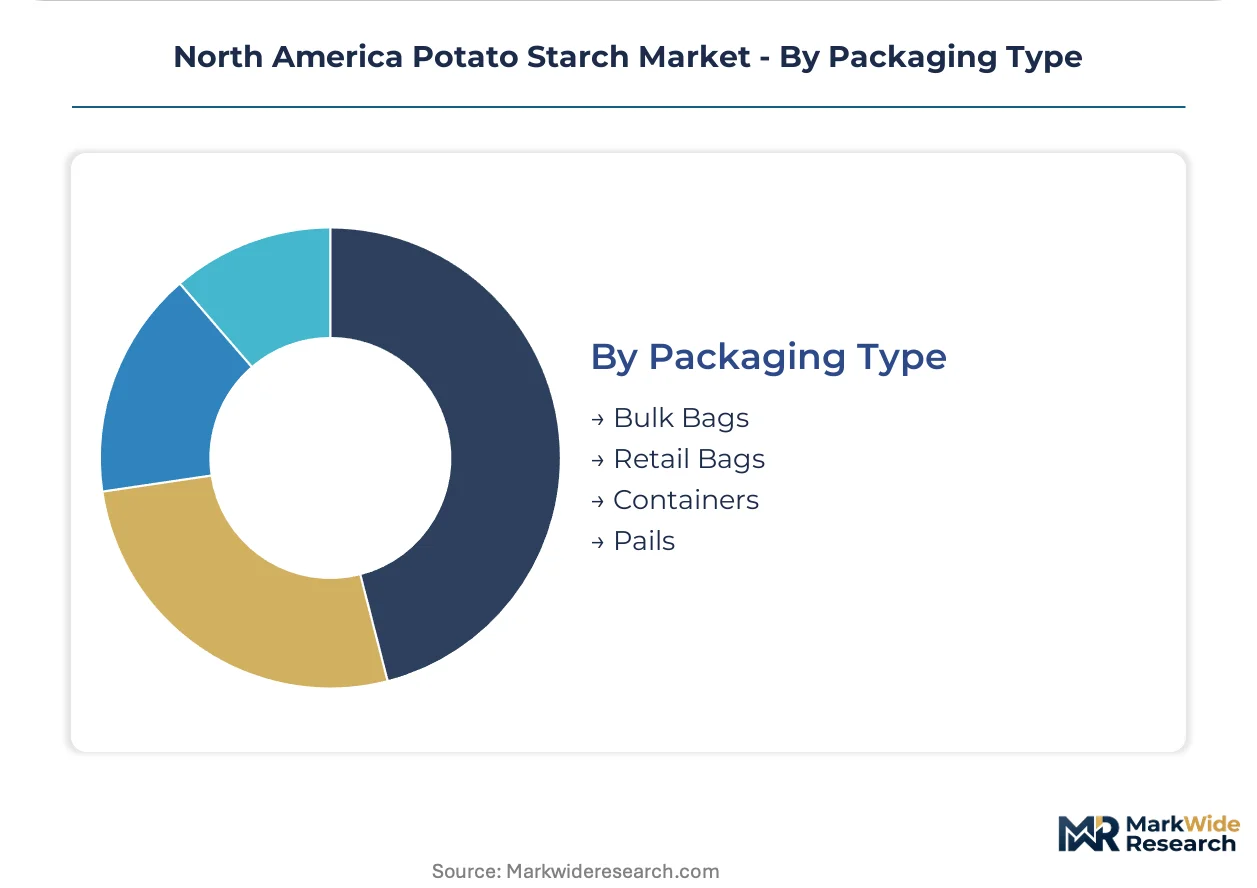
Packaging Type:
Handling economics and contamination risk shape procurement decisions across downstream operations.
- Bulk Bags:One-ton flexible intermediate bulk containers serve high-volume food and paper manufacturers with pneumatic conveying systems, minimizing per-pound handling cost.
- Retail Bags:Twenty-five to fifty-pound paper or woven polypropylene units reach artisan bakeries and small-scale food processors through specialty ingredient distributors.
- Containers:Rigid totes with liner systems protect against moisture uptake in humid distribution environments.
- Pails:Five-gallon plastic pails contain liquid starch slurries for manual dispensing in coating operations without bulk handling infrastructure.
Bulk bags hold installed capacity for integrated processors. Retail bags is rotating up the share rankings on direct-to-bakery distribution growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA National Organic Program equivalency agreements and FDA GRAS streamlining are redirecting procurement flows across North American potato starch supply chains. State-level processing incentives in the Upper Midwest and Prairie Provinces are accelerating wet-milling capacity concentration.
United States
Clean-label mandates from Walmart and Kroger are compressing synthetic thickener volumes toward identity-preserved native grades. FDA 21 CFR 172.892 consolidations accelerate modified starch approvals for sauce applications. North Dakota and Minnesota host integrated wet-milling clusters feeding just-in-time delivery to CPG manufacturers.
Canada
Manitoba's contract potato acreage supplies US-bound organic certified volumes under USDA equivalency protocols. Health Canada and PMRA coordinate food additive approvals with FDA determinations, reducing cross-border regulatory friction. Prairie Provinces processing infrastructure captures premium pricing for Non-GMO Project verified exports.
Mexico
Industrial adhesive compounders in Nuevo León specify modified potato starch for corrugated packaging serving US export markets. Mexico's national food safety authority aligns additive standards with FDA guidance, facilitating ingredient imports. Bajío Region food processors are piloting native starch formulations for clean-label tortilla and sauce applications.
North America Potato Starch Market Key Industry Players
Listed leaders compete with private specialists across certification and application expertise dimensions, creating a tiered structure where scale-driven multinationals face focused regional processors. The vendor base clusters around three strategic archetypes: integrated agricultural processors with captive supply chains, application-technical specialists with dedicated laboratories, and regional millers with identity-preserved certification depth. Dominant competitive moves include backward integration into contract potato acreage and geographic expansion through direct-to-bakery distribution bypassing broadline channels.
Among integrated agricultural processors, Cargill, Incorporated exemplifies scale-driven supply chain control through contract grower networks. Roquette Frères occupies the technical-specialist tier with modified starch functionality leadership. Cooperative Avebe UA represents the cooperative processor archetype linking member-farmers to industrial end-users.
| Leading Market Players |
|---|
| Tate & Lyle |
| Roquette Frères |
| Cargill, Incorporated |
| Cooperative Avebe UA |
| Manitoba Starch Inc. |
| Ingredion |
| Emsland Group |
| KMC Ingredients |
| ADM |
| Others |
Cost & Logistics Intelligence
Corn starch substitution in industrial adhesives and textile sizing is compressing pricing power for commodity-grade potato starch while simultaneously shifting procurement geography toward Midwestern wet-mills with captive potato supply chains. FDA 21 CFR 172.892 streamlining for modified variants creates divergent economics between pharmaceutical-grade premiums and industrial-volume discounts.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical excipient grades and industrial commodity tiers. Three-tier pricing structure across premium, standard, and economy levels reflects Non-GMO Project verification, USP-NF compliance, and unmodified native grades respectively. Pricing pressure stems from corn starch undercutting in cost-sensitive adhesive applications. Food manufacturers with clean-label mandates show least price sensitivity, while industrial compounders in Ohio and Pennsylvania exhibit highest elasticity.
Supply Chain Analysis
North Dakota and Minnesota anchor integrated wet-milling capacity feeding CPG just-in-time networks. Fresh potato supply draws from Red River Valley contract acreage, while modified starch production rests on acetic anhydride and phosphorus oxychloride chemical inputs. Single-source vulnerability concentrates in retiring process engineering talent at legacy facilities. Distribution runs through direct processor relationships bypassing broadline channels for bakery and sauce manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label procurement consolidation at Walmart and Kroger is transforming potato starch into a platform-economy battleground where certification interoperability determines supplier survival. Non-GMO Project verification and USDA organic equivalency now function as ecosystem gatekeepers comparable to software platform standards.
For Market Incumbents: Shield market position through backward integration into contract potato acreage in North Dakota and Minnesota, locking in identity-preserved supply chains before Non-GMO Project verification timelines elongate procurement cycles. Cargill-scale processors should prioritize captive wet-milling capacity over distribution breadth, as retailer consolidation favors direct relationships over broadline intermediaries. EPA effluent constraints present a margin defense opportunity through water-recovery system investments that block competitor expansion. For New Entrants and Emerging Players: USDA National Organic Program equivalency fast-track opens premium pricing channels for Canadian Prairie Provinces processors entering US distribution. Direct-to-bakery distribution in California and Pacific Northwest markets offers the most penetrable white-space, as artisan bread and gluten-free formulations demand specialty packaging sizes bypassed by integrated processors. Pharmaceutical excipient qualification represents a second viable entry path, where USP-NF compliance creates defensible niche positioning against commodity competition. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional millers possessing Non-GMO Project verification depth but lacking pharmaceutical-grade infrastructure. Long-term viability across the analysis window hinges on certification portfolio breadth rather than volume scale. The signal to watch is FDA guidance on novel enzymatic modification technologies, which would reshape competitive barriers between native and modified product tiers and trigger consolidation among mid-tier processors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Contract Acreage | Cargill-style captive supply chains secure identity-preserved potato sourcing ahead of Non-GMO verification mandates. |
| Pharmaceutical Excipient Qualification | USP-NF compliance opens oral solid dosage manufacturing with generic drug growth driving demand. |
| Water-Recovery System Investment | EPA effluent compliance blocks competitor capacity expansion while reducing operating cost exposure. |
| Direct-to-Bakery Distribution Buildout | Specialty packaging bypasses broadline channels to capture margin in artisan and gluten-free segments. |
| Canadian Organic Certification Leverage | USDA equivalency agreement unlocks premium pricing for Prairie Provinces supply entering US markets. |
Research Approach
A spread of perspectives from wet-mill operations directors, CPG procurement leads, pharmaceutical formulation scientists, and specialty ingredient distributors converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through FDA 21 CFR filings, EPA effluent compliance records, USDA National Organic Program certification databases, and customs trade data. Bottom-up capacity assessments across North Dakota and Minnesota processing facilities were triangulated against top-down demand modeling from food manufacturing and pharmaceutical end-use segments.
Segmentation dimensions modeled include product type tier, application vertical, end-user qualification requirements, and packaging format across the projection horizon. CAGRs were derived from historical volume trajectories adjusted for clean-label reformulation elasticity and pharmaceutical excipient penetration curves. Forecast inputs incorporated Non-GMO Project verification timeline constraints, EPA water discharge limit stringency, and corn starch substitution elasticity in industrial adhesive applications.
Decision-makers should treat outputs as directional under assumptions of sustained retailer clean-label mandates and stable FDA GRAS guidance; material deviation in regulatory trajectory or substitution economics would warrant model refresh. Recalibration cycles align with material shifts in EPA enforcement patterns, FDA novel modification rulings, and major retailer procurement consolidation announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Egg Replacement Ingredients Market
Ingredients
South America Insoluble Dietary Fibers Market
Ingredients
Glucose (Dextrose) Market
Ingredients
Xylooligosaccharide Market
Ingredients
Desiccated Coconut Market
Ingredients
Global Dietary Fibers Market
Ingredients
Grape Skin Extract Market
Ingredients
Colombia Food Ingredients Market
Ingredients
Jasmine Extract Market
Ingredients
Virgin Coconut Oil Market
Ingredients
Valerian Root Oil Market
Ingredients
Cocoa Beans Market
Ingredients
Feed Premix Market
Ingredients
Cocoa Market
Ingredients
Curcuma Longa (Turmeric) Root Extract Market
Ingredients
Middle East and Africa Fermented Ingredients Market