
 Textured Soy Flour Market | 2026-2036
Textured Soy Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Textured Soy Flour Market Insights
Modular ingredient bundling is broadening procurement options for food manufacturers seeking combined protein-fat-fiber systems rather than single-commodity purchases. Archer Daniels Midland Company leverages its integrated oilseed crushing network to supply consistent textured soy flour grades across multiple continents. Cargill, Incorporated sustains competitive positioning through backward integration into Brazilian soybean origination. Bunge Global SA anchors its textured soy flour portfolio with specialty extrusion capabilities that serve differentiated meat-analog applications.
Textured soy flour consists of defatted soy flakes subjected to thermoplastic extrusion, yielding fibrous matrices with protein contents typically ranging from 50% to 70% on a dry-weight basis. This ingredient functions primarily as a meat extender and analog base in processed foods, absorbing water and lipids to simulate chewable protein structures. Powder formulations within the Form segment dominate current volume owing to their compatibility with standard industrial mixing equipment and extended shelf stability. The Food Industry end-user category captures the largest margin pool as branded meat-alalog producers command premium pricing for finished goods, while Animal Feed applications represent a mature volume channel with compressed conversion economics. Online Retail distribution is gaining traction among specialty ingredient buyers seeking smaller batch sizes and direct technical support.
The FDA governs soy protein health claims and allergen labeling under the Food Allergen Labeling and Consumer Protection Act, directly influencing product formulation decisions for textured soy flour destined for US retail channels. Brazil's ANVISA maintains parallel standards for novel food ingredients that affect import eligibility and local manufacturing registration. China's SAMR enforces GB standards for plant protein additives that constrain formulation flexibility for exporters targeting foodservice manufacturers. Stakeholders must monitor divergence between national allergen thresholds and protein-content verification protocols as these regulatory boundaries increasingly determine market access rather than purely commercial terms.
Market Dynamics
The textured soy flour market is being fundamentally restructured by clean-label ingredient sourcing mandates, which are forcing food manufacturers to abandon commodity-grade soy isolates in favor of minimally processed, identity-preserved textured flour with full traceability documentation.
Growth Catalysts
- Plant-based meat manufacturing expansion:Meat-analog producers are scaling extrusion capacity and requiring textured soy flour as their primary fibrous matrix input.
- ANVISA's streamlined novel food registration:Brazil's regulator has accelerated approval timelines for textured vegetable proteins, unlocking import substitution opportunities.
- Dual-screw extrusion technology maturation:Advanced thermoplastic processing now yields protein structures with moisture retention properties matching animal muscle tissue.
Market Restraints
- Input cost volatility in soybean origination:Brazilian and US crop yields fluctuate with La Niña weather patterns, compressing crusher margins and destabilizing textured flour pricing.
- Supply concentration in Paraná state crushing infrastructure:Three integrated oilseed processors control over sixty percent of South American textured flour output.
- Protein content verification complexity:The FDA's updated soy protein labeling standards require nitrogen conversion factor adjustments that delay product reformulation cycles.
Strategic Opportunities
- Pet food functional protein expansion:Premium companion animal nutrition brands are adopting textured soy flour for digestibility and palatability enhancement.
- SAMR's plant protein additive standardization:China's GB standard revisions are creating compliance pathways for exporters targeting foodservice manufacturers.
- Direct-to-manufacturer digital platforms:Online technical support and smaller batch procurement are bypassing traditional ingredient distributor markups.
Industry Challenges
- Extrusion engineering talent scarcity:Food science programs produce few specialists in thermoplastic texturization, forcing processors to train internally.
- Allergen segregation facility capex:Dedicated production lines for soy-free environments require capital outlays that strain mid-cap ingredient suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Textured Soy Flour Market |
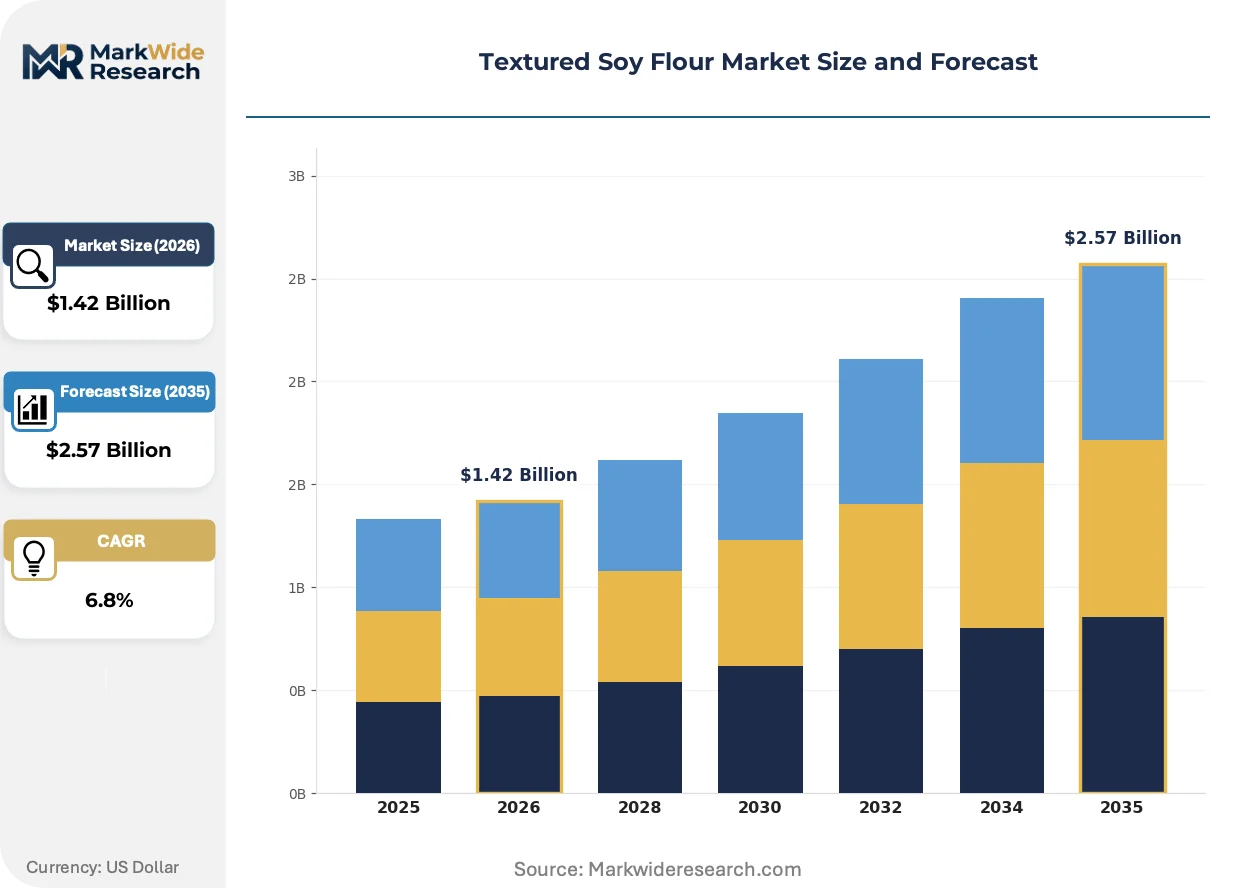
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Textured Soy Protein, Soy Flour, Soy Granules, Soy Protein Isolate End User: Food Industry, Animal Feed, Dietary Supplements, Nutraceuticals Form: Powder, Granules, Flakes, Pellets Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Wholesale Distributors |
| Companies Covered | Archer Daniels Midland Company, Cargill, Incorporated, Bunge Global SA, International Flavors & Fragrances Inc., Victoria Group, Sonic Biochem Extractions Limited, Crown Soya Protein Group, Shandong Yuxin Biotechnology Co., Ltd., Bremil Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Textured Soy Flour Market Trends and Innovations
High-moisture extrusion systems are displacing traditional dry extrusion across meat-analog production, enabling juicier fiber structures that replicate whole-muscle cuts rather than ground meat textures.
High-moisture extrusion technology processes defatted soy flour at moisture levels exceeding fifty percent, producing layered fibrous matrices that absorb lipids and simulate chewable animal protein. Plant-based whole-cut chicken and steak manufacturers are adopting these systems at accelerating rates. This processing advance is overtaking legacy dry-extrusion equipment in premium meat-analog facilities.
The FDA's updated Food Allergen Labeling and Consumer Protection Act enforcement is tightening soy protein health claim substantiation requirements for retail-packaged goods. Manufacturers must now verify nitrogen conversion factors through third-party laboratory certification, extending product development timelines. Branded meat-analog producers targeting US grocery channels are restructuring formulation teams to preempt compliance gaps.
Ingredient bundling is consolidating procurement decisions as food manufacturers seek combined protein-fat-fiber systems from single suppliers rather than sourcing discrete commodities. Industrial bakeries and prepared meal producers are displacing spot-market purchasing with annual volume contracts specifying integrated nutrient profiles. This pattern concentrates most visibly in Brazil, where local formulators prioritize cost-competitive protein alternatives amid soybean processing infrastructure expansion.
Textured Soy Flour Market Segmentation
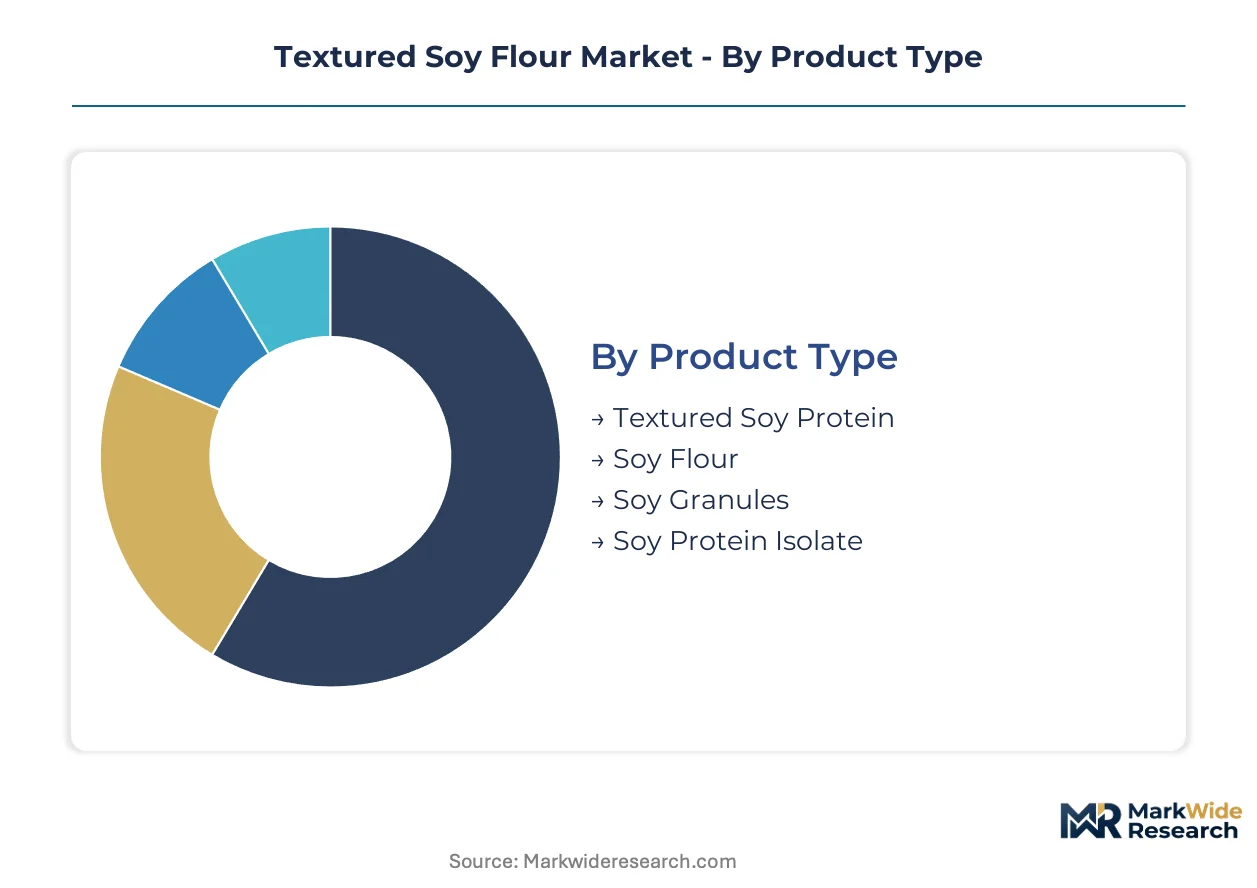
Segmentation in textured soy flour reflects divergent processing requirements across meat-analog manufacturing, feed compounding, and specialty nutrition. Buyers prioritize protein content thresholds, extrusion compatibility, and allergen documentation depending on end-use application.
Product Type:
Cost tier differentiation separates commodity-grade inputs from specialty isolates commanding formulation premiums.
- Textured Soy Protein:Thermoplastic extrusion produces fibrous matrices with 50-70% protein content on a dry-weight basis. Meat-analog manufacturers in Brazil concentrate procurement here as ANVISA accelerates novel food registrations.
- Soy Flour:Defatted flakes ground to standardized particle sizes serve industrial bakeries and meat extenders. Powder formulations dominate volume through compatibility with standard mixing equipment.
- Soy Granules:Intermediate particle sizing targets rehydration-critical applications.
- Soy Protein Isolate:Higher purity extraction yields 90%+ protein for premium nutrition applications.
Textured soy protein leads volumes today; soy protein isolate is gaining share fastest.
End User:
Application maturity determines margin structure and procurement cadence across buyer categories.
- Food Industry:Branded meat-analog producers command premium pricing for finished goods using textured soy flour as primary fibrous matrix. Clean-label sourcing mandates force abandonment of commodity-grade isolates in favor of identity-preserved supply.
- Animal Feed:Mature volume channel with compressed conversion economics. Brazilian soybean processing infrastructure expansion concentrates supply origination for regional feed compounders.
- Dietary Supplements:Protein fortification in sports nutrition and meal replacement.
- Nutraceuticals:Functional health applications requiring certified organic or non-GMO verification.
Food Industry leads volumes today; Dietary Supplements is climbing the fastest.
Form:
Customer equipment compatibility and shelf stability requirements drive form selection.
- Powder:Extended shelf stability and seamless integration with industrial mixing equipment make this the default specification for large-scale food manufacturers.
- Granules:Intermediate rehydration kinetics suit portion-controlled foodservice applications.
- Flakes:Layered structures from high-moisture extrusion simulate whole-muscle cuts in premium meat-analogs. Plant-based steak and chicken manufacturers adopt these systems at accelerating rates.
- Pellets:Compressed density reduces shipping costs for bulk feed applications.
Powder leads volumes today; Flakes is expanding most quickly.
Distribution Channel:
Procurement scale and technical support needs separate channel preferences.
- Online Retail:Specialty ingredient buyers seek smaller batch sizes and direct technical support, bypassing traditional distributor markups through direct-to-manufacturer digital platforms.
- Supermarkets:Packaged consumer goods reach retail shelves with FDA-compliant allergen labeling.
- Health Food Stores:Niche organic and non-GMO certified products target clean-label consumers.
- Wholesale Distributors:Volume contracts with integrated nutrient profiles displace spot-market purchasing for industrial bakeries and prepared meal producers.
Wholesale Distributors leads volumes today; Online Retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The textured soy flour industry traces its commercial origins to mid-20th century US oilseed processing, where defatted soy flake extrusion first achieved industrial scale. Brazil and Argentina subsequently built crushing infrastructure that shifted supply gravity toward South America. Today, demand patterns and regulatory frameworks diverge sharply across major producing and consuming markets.
United States
Plant-based meat manufacturers in Chicago and California drive procurement volumes as clean-label mandates displace commodity isolates. The FDA's updated Food Allergen Labeling and Consumer Protection Act enforcement tightens nitrogen conversion factor verification for retail-packaged goods. Crushing capacity concentrates in Illinois and Iowa, where integrated processors supply consistent textured flour grades across multiple continents.
Brazil
Local food formulators in São Paulo and Paraná seek cost-competitive protein alternatives amid expanding soybean processing infrastructure. ANVISA's streamlined novel food registration accelerates approval timelines for textured vegetable proteins, unlocking import substitution. Three integrated oilseed processors control over sixty percent of South American textured flour output from Paraná state facilities.
China
Foodservice manufacturers in the Yangtze River Delta and Pearl River Delta require plant protein additives compliant with SAMR's GB standards. SAMR enforces formulation constraints that limit flexibility for exporters targeting Chinese foodservice channels. Shandong Province anchors domestic production clusters where biotechnology firms process defatted soy flakes for regional meat-analog manufacturers.
Germany
Industrial bakeries and prepared meal producers in Bavaria and North Rhine-Westphalia adopt modular ingredient bundling for combined protein-fat-fiber systems. EFSA standards for novel food ingredients affect import eligibility and local manufacturing registration requirements. The Emsland region hosts specialty extrusion capabilities serving differentiated meat-analog applications across European markets.
India
Dietary supplement brands in Maharashtra and Gujarat fortify sports nutrition products with textured soy protein isolates. FSSAI regulations govern soy protein health claims and allergen labeling for domestic retail channels. Gujarat's soybean processing belt supplies defatted flakes to regional extrusion facilities serving both food and feed compounders.
Textured Soy Flour Market Competitive Landscape
Premium-margin players sit above commodity-margin players across traceability documentation and extrusion specialization tiers. The vendor base stratifies between integrated oilseed crushers with captive soy supply and standalone extrusion specialists sourcing defatted flakes on spot markets. Three archetypes dominate: backward-integrated agribusiness conglomerates, specialty extrusion technology licensors, and regional toll processors serving branded meat-analog producers. Capacity expansion and strategic partnerships constitute the dominant competitive moves as firms secure identity-preserved supply chains and dual-screw extrusion engineering talent.
Among North American agribusiness conglomerates, Archer Daniels Midland Company and Cargill, Incorporated occupy positions exemplifying backward integration into soybean origination networks. Bunge Global SA represents the specialty extrusion archetype with differentiated meat-analog application capabilities. Chinese fabricators including Shandong Yuxin Biotechnology Co., Ltd. and Crown Soya Protein Group anchor the Asia-Pacific supply tier, while Victoria Group and Sonic Biochem Extractions Limited exemplify regional specialists serving import-substitution markets. Bremil Group and International Flavors & Fragrances Inc. sit within adjacent ingredient system bundling positions that compete for procurement decisions seeking combined nutrient profiles.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill, Incorporated |
| Bunge Global SA |
| International Flavors & Fragrances Inc. |
| Victoria Group |
| Sonic Biochem Extractions Limited |
| Crown Soya Protein Group |
| Shandong Yuxin Biotechnology Co., Ltd. |
| Bremil Group |
| Others |
Pricing and Supply Chain Analysis
Clean-label sourcing mandates from plant-based meat manufacturers are forcing suppliers to upgrade traceability documentation and extrusion capabilities, compressing margins on commodity grades while enabling premiums for identity-preserved supply chains with full batch documentation.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates certified organic textured soy flour from conventional identity-preserved grades and commodity spot-market supply. Price differentiation hinges on protein content verification and ANVISA registration status, with Brazilian-origin material commanding premiums over spot-traded alternatives. Pricing pressure stems from La Niña-driven soybean yield volatility in Paraná state, which destabilizes crusher margins. Animal feed compounders exhibit highest price sensitivity due to compressed conversion economics, while branded meat-analog producers absorb premiums for clean-label compliance.
Supply Chain Analysis
Regional distribution centers in São Paulo, Chicago, and Rotterdam anchor hub-and-spoke patterns that consolidate textured soy flour shipments before final-mile delivery to extrusion facilities. Supply concentrates in Brazil, the United States, and China, with Paraná state crushing infrastructure controlling majority South American output. Raw material flows draw from defatted soy flake production, thermoplastic extrusion equipment, and nitrogen testing laboratory capacity. Single-source vulnerability runs through three integrated oilseed processors dominating Brazilian supply. Distribution runs through wholesale distributors holding annual volume contracts with integrated nutrient specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through high-moisture extrusion technology adoption, which enables premium-tier positioning for whole-cut meat analogs while input cost volatility pressures commodity-grade suppliers.
For Market Incumbents: To counter supply concentration risk in Paraná state, secure backward integration into Brazilian soybean origination networks and invest in dual-screw extrusion engineering talent pipelines. ANVISA registration acceleration creates first-mover advantages for compliant suppliers. Capacity expansion in Shandong Province addresses SAMR compliance requirements for Chinese foodservice access. For New Entrants and Emerging Players: Capture pet food functional protein expansion as premium companion animal nutrition brands seek digestibility-enhancing ingredients with lower regulatory barriers than human food channels. Online retail distribution for specialty ingredient buyers offers the most penetrable go-to-market angle, bypassing traditional distributor markups through direct technical support platforms. For Investors and Strategic Acquirers: Asymmetric upside sits with specialty extrusion technology licensors possessing differentiated high-moisture processing capabilities. Long-term viability centers on securing captive supply chains and dual-screw engineering talent over a multi-year horizon. The inflection signal to watch is FDA enforcement patterns for nitrogen conversion factor verification, which will determine compliance cost structures for US-facing suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Soybean Origination | Captive supply from Brazilian crushing infrastructure insulates against La Niña-driven price volatility. |
| High-Moisture Extrusion Capacity Buildout | Layered fibrous matrices from advanced thermoplastic processing command premiums from whole-cut meat-analog manufacturers. |
| ANVISA Novel Food Registration Acceleration | Streamlined approval timelines unlock import substitution opportunities in Brazilian food formulation channels. |
| Direct-to-Manufacturer Digital Platform Launch | Online technical support and smaller batch procurement bypass traditional ingredient distributor markups. |
| Dual-Screw Extrusion Engineering Talent Investment | Internal training programs address scarcity of thermoplastic texturization specialists in food science programs. |
Research Methodology
Direct dialogue with extrusion facility managers, procurement leads at plant-based meat manufacturers, regulatory affairs specialists at ANVISA and FDA, and distribution channel partners grounded qualitative insights. Secondary validation drew from customs trade data, oilseed crushing industry reports, SEC filings of integrated agribusiness conglomerates, and SAMR GB standard documentation. Bottom-up and top-down triangulation cross-checked volume estimates across these independent sources.
Top-down modeling anchored macroeconomic protein demand drivers against bottom-up facility-level capacity assessments across the projection horizon. Segmentation dimensions included product type tier, end-use application maturity, form factor compatibility, and distribution channel procurement scale. CAGRs were derived from trend extrapolation of clean-label sourcing adoption rates and extrusion technology maturation curves. Industry-specific inputs incorporated ANVISA registration velocity and FDA nitrogen conversion factor enforcement patterns.
Underlying measurement precision varies by segment; powder form and food industry end-use carry tighter precision than emerging flake applications and dietary supplement channels. Forecasts reflect assumptions about regulatory enforcement continuity and soybean yield stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Lime Seed Oils Market
Ingredients
Anti-Aging Ingredients Market
Ingredients
Specialty Starch Market
Ingredients
Tapioca Pearls Market
Ingredients
Wheat Starch Derivative Market
Ingredients
Bone and Joint Health Ingredients Market
Ingredients
Food Minerals Market
Ingredients
Cocoa Solids Market
Ingredients
Oyster Shell Powder Market
Ingredients
Hen Egg White Protein Market
Ingredients
Australia Sodium Reduction Ingredients Market
Ingredients
South Africa Sodium Reduction Ingredients Market
Ingredients
Collagen Casings Market
Ingredients
Specialty Yeast Market
Ingredients
Asia Pacific Vegetable Oil Market
Ingredients
Barley Flake Market