
 China Corn Glucose Market | 2026-2036
China Corn Glucose Market Size, Share, and Industry Trends Forecast 2026-2036
China Corn Glucose Market Intelligence
Pharmaceutical buyers is unwinding share from traditional confectionery offtake as domestic IV solution and tablet excipient requirements expand. Global Sweeteners Holdings Limited leverages its integrated corn wet milling infrastructure across Jilin and Shandong to secure raw material cost advantages. Zhucheng Dongxiao Biotechnology anchors the maltodextrin specialty tier through fermentation-grade purity certifications. Shandong Fuyang Biotechnology competes on distributed manufacturing scale, operating multiple refineries within China's northeastern corn belt.
Corn glucose is a starch hydrolysate produced by enzymatic or acid conversion of corn starch, yielding dextrose equivalents ranging from 20 to 100 DE depending on hydrolysis depth, with primary industrial functions spanning humectancy, browning control, and fermentable carbohydrate supply. Liquid glucose commands the volume lead in baking and brewing applications where moderate sweetness and viscosity modification prove essential. High fructose corn syrup is displacing cane sugar in mass-market beverage formulations, though maltodextrin captures the fastest growth trajectory within sports nutrition and infant formula segments where low osmolality and clean-label bulking properties command premium positioning.
SAMR enforces GB 15203 food additive purity standards while MEE monitors wastewater discharge from starch processing facilities under tightening dual carbon compliance timelines. BIS-equivalent provincial quality bureaus conduct random sampling of dextrose monohydrate lots entering pharmaceutical channels, creating compliance differentiation among producers with certified GMP lines. Stakeholders must monitor how Shandong's industrial cluster consolidation and carbon intensity benchmarks reshape supplier viability before committing to long-term procurement contracts.
Market Dynamics
Shandong Province's industrial cluster consolidation is compressing supplier viability as dual carbon benchmarks force wet millers to retrofit enzymatic conversion lines or exit. SAMR's GB 15203 enforcement and MEE wastewater discharge monitoring are accelerating capital intensity thresholds for corn glucose processors.
Growth Catalysts
- Pharmaceutical excipient demand:Domestic IV solution and tablet formulation requirements are expanding corn glucose procurement from traditional confectionery channels. BIS-equivalent provincial quality bureaus conduct random sampling of dextrose monohydrate lots entering pharmaceutical channels.
- Dual carbon compliance timelines:MEE monitoring of starch processing wastewater discharge is tightening processing efficiency requirements. Wet millers investing in closed-loop water systems secure operational continuity advantages.
- Sports nutrition formulation:Maltodextrin captures premium positioning within infant formula and sports nutrition segments where low osmolality and clean-label bulking properties command formulation preference.
Market Restraints
- Corn input cost volatility:Northeastern corn belt weather variability and import parity pricing expose processors to margin compression. Jilin and Shandong wet millers lack price pass-through elasticity in bulk liquid glucose contracts.
- Substitution threat from cane sugar:High fructose corn syrup faces displacement risk in mass-market beverage formulations where cane sugar achieves cost parity through Brazilian supply expansion.
- Supply concentration in Shandong:Port logistics and corn processing cluster dominance create single-point vulnerability for bulk glucose distribution networks serving North China pharmaceutical manufacturers.
Strategic Opportunities
- Fermentation-grade purity certification:Specialty maltodextrin producers securing GMP-adjacent certifications for biopharmaceutical fermentation feedstock access premium pricing tiers unavailable to commodity glucose refiners.
- Hebei and Henan underpenetration:Corn processing capacity expansion into secondary provinces reduces Shandong logistics dependency and opens direct distribution to inland pharmaceutical formulators.
- Carbon intensity benchmarking:Early adopters of anaerobic digestion biogas recovery systems position for preferential procurement contracts under provincial dual carbon implementation frameworks.
Industry Challenges
- Enzyme biocatalyst sourcing:Glucoamylase and alpha-amylase supply concentration among international specialty chemical suppliers creates formulation consistency risks for domestic wet millers.
- GMP line certification timelines:Pharmaceutical-grade dextrose monohydrate producers face 18-24 month validation cycles with provincial quality bureaus, delaying revenue conversion from capital deployment.
- Legacy starch processing infrastructure:Acid hydrolysis conversion lines require complete enzymatic retrofit to meet GB 15203 purity standards and MEE discharge limits simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Corn Glucose Market |
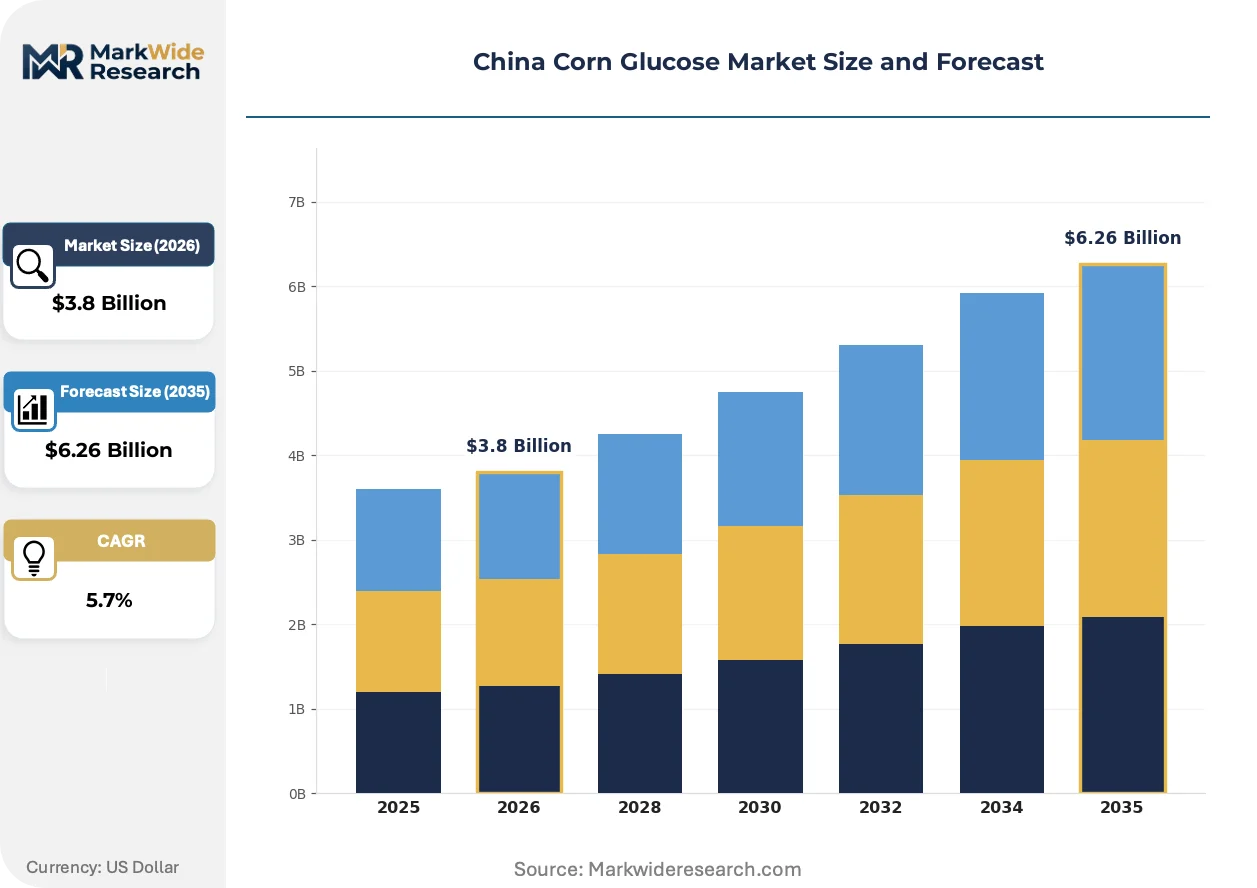
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
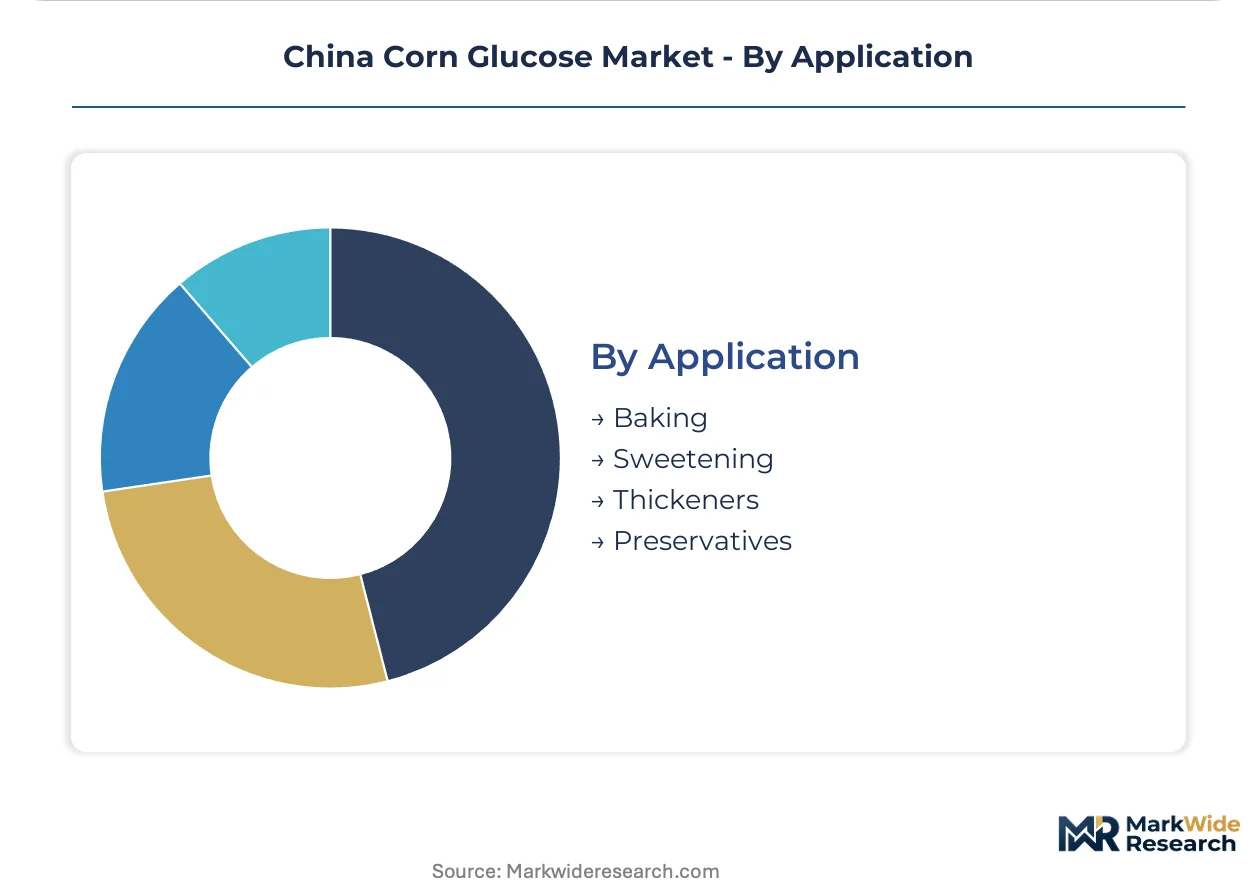
| Segmentation | Product Type: Liquid Glucose, Dextrose Monohydrate, Maltodextrin, High Fructose Corn Syrup End User: Food & Beverage, Pharmaceuticals, Confectionery, Animal Feed Distribution Channel: Online Retail, Supermarkets, Wholesalers, Direct Sales Application: Baking, Sweetening, Thickeners, Preservatives |
| Companies Covered | Global Sweeteners Holdings Limited, Guangzhou Shuangqiao Company, Dancheng Caixin Sugar Industry Co. Ltd., Fengchen Group Co. Ltd., Changchun Dacheng Industrial Group Co., Corn Products China Co., Zhucheng Dongxiao Biotechnology, Shandong Fuyang Biotechnology, Global Bio-Chem Technology Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Corn Glucose Market Strategic Shifts & Innovations
Enzymatic conversion depth variability is reshaping product portfolio architecture across China's corn glucose sector. Wet millers are repositioning around dextrose equivalent specificity rather than commodity volume.
Membrane filtration is fragmenting traditional centrifugation and evaporation sequences in glucose refining. Pharmaceutical formulators adopting DE 99.5+ dextrose monohydrate for intravenous solutions are demanding ultrapure grades that legacy acid hydrolysis lines cannot achieve. This technology is fragmenting the supplier base between retrofit-capable integrated millers and stranded commodity producers.
SAMR's GB 15203 food additive purity standards are tightening contaminant thresholds for 5-hydroxymethylfurfural and sulfite residues. Starch processors must deploy ion exchange polishing and activated carbon treatment to maintain compliance. Pharmaceutical channel entrants face the steepest compliance cost escalation as BIS-equivalent provincial sampling intensifies for dextrose monohydrate lots.
Direct mill-to-formulator contracting is displacing multi-tier distribution in bulk liquid glucose procurement. North China baking and brewing conglomerates are consolidating supplier relationships to secure DE 40-60 specification consistency. This pattern concentrates procurement leverage with Shandong cluster incumbents possessing dedicated tanker fleet capacity.
China Corn Glucose Market Segmentation
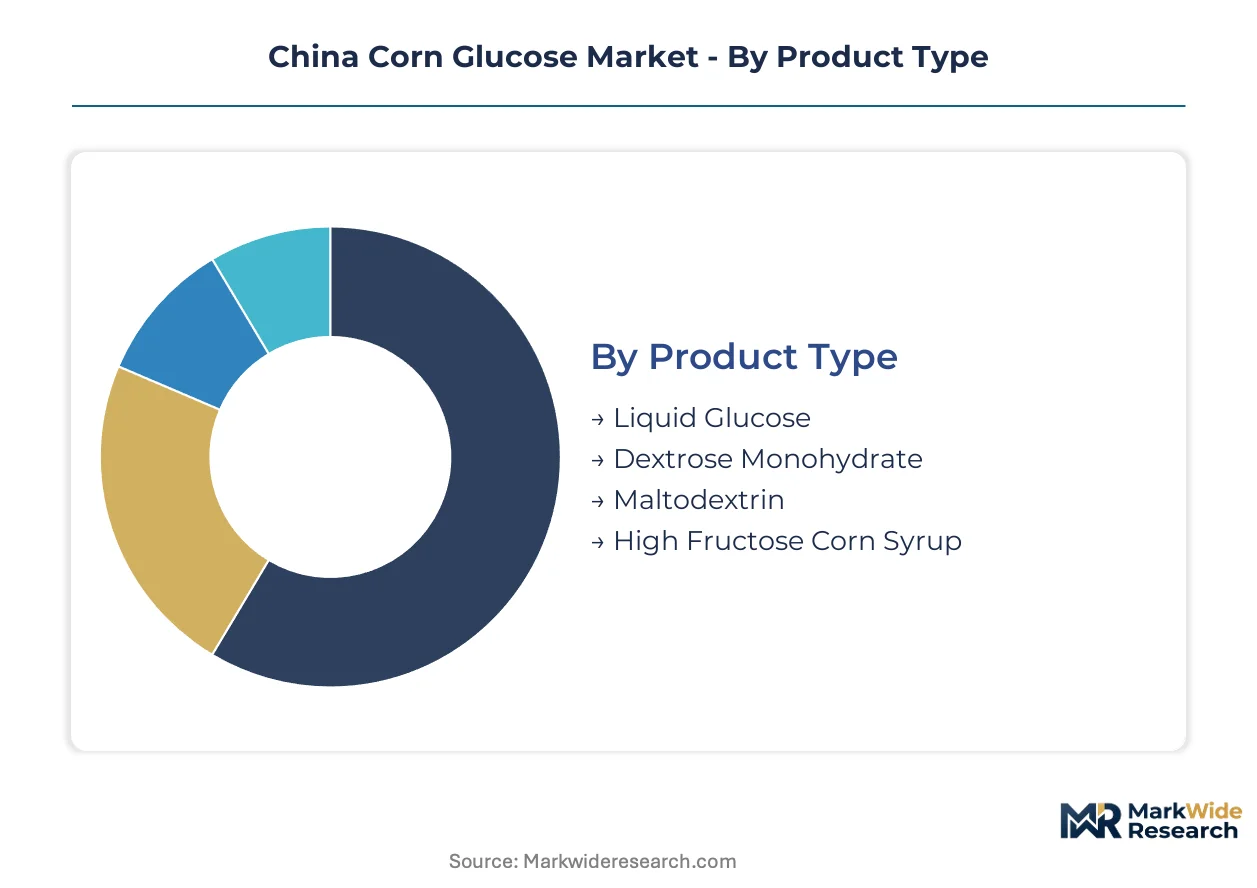
Corn glucose processors in China are repositioning portfolios around dextrose equivalent specificity rather than commodity volume. Substitution pressures from cane sugar and clean-label alternatives are fragmenting demand across product tiers, forcing wet millers to defend position through application-grade certification.
Product Type:
High fructose corn syrup faces the most acute displacement risk as Brazilian cane sugar achieves cost parity in mass-market beverages, while maltodextrin defends premium positioning through low-osmolality formulation properties.
- Liquid Glucose:A starch hydrolysate with dextrose equivalents ranging from 20 to 60 DE, produced through controlled enzymatic conversion of corn starch. Demand concentrates in Shandong Province baking and brewing facilities where moderate sweetness and viscosity modification prove essential for dough conditioning and fermentation control.
- Maltodextrin:A low-DE hydrolysate typically ranging 10 to 20 DE, valued for clean-label bulking and rapid gastric emptying properties. Sports nutrition and infant formula manufacturers in North China are expanding procurement of pharmaceutical-grade lots certified for low osmolality applications.
- Dextrose Monohydrate:Crystalline glucose with DE 99.5+ purity, serving intravenous solution and tablet excipient channels under SAMR pharmaceutical standards.
- High Fructose Corn Syrup:Enzymatically isomerized glucose-fructose blend, facing volume pressure from cane sugar substitution in carbonated beverage formulations.
Liquid glucose anchors the volume base while maltodextrin gains share at the steepest rate.
End User:
Procurement leverage is shifting toward pharmaceutical channels as domestic IV solution requirements expand, while confectionery offtake stagnates under sugar reduction mandates.
- Food & Beverage:Mass-market beverage and processed food manufacturers represent the largest volume sink for liquid glucose and high fructose corn syrup, though margin compression from input cost volatility limits processor pricing power.
- Pharmaceuticals:Formulators of intravenous solutions and solid-dose excipients are demanding DE 99.5+ dextrose monohydrate with GMP-adjacent certification, creating compliance differentiation among Shandong cluster producers.
- Confectionery:Traditional hard candy and chocolate applications face substitution from reduced-sugar formulations and alternative sweeteners.
- Animal Feed:Fermentation-grade glucose serves as carbohydrate substrate for lysine and antibiotic production in industrial biotechnology facilities.
Food and beverage commands the procurement volume while pharmaceuticals climbs the fastest as a share of processor revenue.
Distribution Channel:
Direct contracting is displacing multi-tier distribution in bulk liquid glucose procurement, concentrating leverage with integrated millers possessing dedicated tanker fleet capacity.
- Direct Sales:Mill-to-formulator contracting dominates bulk liquid glucose procurement for North China baking conglomerates requiring DE 40-60 specification consistency.
- Wholesalers:Regional distributors serve fragmented confectionery and small-scale food processors lacking volume scale for direct mill relationships.
- Supermarkets:Retail shelf presence for consumer-packaged dextrose monohydrate in baking and home brewing applications.
- Online Retail:E-commerce penetration for specialty maltodextrin in sports nutrition direct-to-consumer channels.
Direct sales captures the procurement volume while online retail expands most quickly in specialty tier access.
Application:
Functional properties rather than sweetness intensity are determining formulation selection as processors diversify beyond commodity sweetening.
- Baking:Liquid glucose at 40-60 DE provides humectancy and Maillard browning control in industrial bread and pastry production.
- Sweetening:High fructose corn syrup delivers cost-optimized sweetness in carbonated beverages facing cane sugar displacement pressure.
- Thickeners:Maltodextrin builds viscosity and mouthfeel in low-fat sauces and infant formula without excessive sweetness.
- Preservatives:Reduced water activity from concentrated glucose syrups extends shelf stability in intermediate moisture foods.
Baking anchors the application volume while thickeners gains share at the steepest rate on clean-label formulation demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qingdao Port's liquid bulk terminals anchor Shandong Province's dominance in corn glucose distribution, handling specialized tanker shipments for North China pharmaceutical manufacturers. The port's cold chain infrastructure and bonded storage zones enable just-in-time delivery to formulators in Beijing and Tianjin.
Shandong Province
Pharmaceutical-grade dextrose monohydrate demand from Beijing-Tianjin-Hebei IV solution manufacturers drives Shandong's wet milling expansion. SAMR's GB 15203 enforcement tightens contaminant thresholds for 5-hydroxymethylfurfural residues. Zhucheng and Weifang processing clusters retrofit enzymatic conversion lines to meet MEE wastewater discharge limits under dual carbon timelines.
Jilin Province
Northeastern corn belt harvest variability shapes Jilin's raw material cost structure for wet millers serving animal feed fermentation channels. Provincial agricultural subsidies stabilize processor margins against weather-driven input volatility. Changchun industrial zone concentrates starch hydrolysis capacity for lysine and antibiotic substrate production.
Guangdong Province
Pearl River Delta beverage formulators source liquid glucose for baking and brewing applications through Shenzhen port logistics. Provincial environmental bureaus enforce carbon intensity benchmarks on processors operating near Dongjiang River watersheds. Guangzhou Shuangqiao's Pearl River distribution network exemplifies southward capacity migration from Shandong dependency.
Henan Province
Underpenetrated corn processing infrastructure in Henan creates procurement vulnerability for Central China pharmaceutical formulators lacking direct mill relationships. Provincial quality bureaus conduct random sampling of dextrose monohydrate lots entering Zhengzhou medical device corridors. Zhengzhou rail freight hubs position for bulk glucose distribution network diversification.
Hebei Province
Beijing-Tianjin-Hebei pharmaceutical demand outpaces local glucose refining capacity, forcing Hebei formulators to rely on Shandong tanker shipments through vulnerable port logistics. Provincial dual carbon implementation frameworks prioritize anaerobic digestion biogas recovery for wet millers seeking preferential procurement contracts. Tangshan industrial zone hosts emerging enzymatic conversion retrofit projects.
China Corn Glucose Market Key Industry Players
Listed leaders compete with private specialists across certification tiers, with integrated wet millers holding procurement leverage through captive corn supply and dedicated tanker fleets. The vendor base stratifies between Shandong cluster incumbents with port logistics dominance and secondary province challengers building distributed manufacturing scale. Three archetypes define positioning: integrated corn-to-glucose processors with enzymatic conversion depth, specialty maltodextrin producers securing fermentation-grade purity certifications, and commodity refiners facing acid hydrolysis retrofit pressure. Competitive moves center on GMP line certification timelines for pharmaceutical channel access and anaerobic digestion biogas recovery for carbon intensity benchmarking advantages.
Within the integrated processor tier, Global Sweeteners Holdings Limited and Changchun Dacheng Industrial Group Co. exemplify northeastern corn belt positioning through Jilin and Shandong wet milling infrastructure. Zhucheng Dongxiao Biotechnology occupies a specialty maltodextrin position, representing the fermentation-grade purity certification vector that separates premium-tier producers from commodity glucose refiners. Shandong Fuyang Biotechnology anchors distributed manufacturing scale across multiple refineries within the provincial cluster.
| Leading Market Players |
|---|
| Global Sweeteners Holdings Limited |
| Guangzhou Shuangqiao Company |
| Dancheng Caixin Sugar Industry Co. Ltd. |
| Fengchen Group Co. Ltd. |
| Changchun Dacheng Industrial Group Co. |
| Corn Products China Co. |
| Zhucheng Dongxiao Biotechnology |
| Shandong Fuyang Biotechnology |
| Global Bio-Chem Technology Group |
| Others |
Cost & Logistics Intelligence
Brazilian cane sugar cost parity with high fructose corn syrup is simultaneously redrawing Shandong Province's procurement geography and compressing margin structures across liquid glucose tiers. SAMR's GB 15203 enforcement tightens purity thresholds just as MEE wastewater discharge limits elevate capital intensity, forcing wet millers to recalibrate pricing power against retrofit costs.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade certification levels governs contract negotiations. Price differentiation rests on GMP-adjacent validation status and dedicated tanker fleet availability for bulk liquid glucose. Cost compression in standard-grade liquid glucose intensifies because northeastern corn belt weather volatility exposes processors to margin pressure without pass-through elasticity. Food and beverage manufacturers exhibit highest price sensitivity due to volume scale and substitution readiness, while pharmaceutical formulators tolerate premium positioning for DE 99.5+ dextrose monohydrate with batch traceability.
Supply Chain Analysis
Qingdao Port liquid bulk terminal congestion and container availability constraints on the Northeast Asia trade lane elevate inbound logistics costs for enzymatic biocatalyst shipments. Supply concentrates in Shandong, Jilin, and Hebei provinces where corn processing clusters anchor wet milling capacity. Raw material dependencies encompass northeastern corn belt harvests, glucoamylase and alpha-amylase enzyme formulations, and ion exchange resin supplies for polishing stages. Single-source vulnerability characterizes the Shandong tanker fleet dominance serving Beijing-Tianjin-Hebei pharmaceutical corridors. Distribution runs through direct mill-to-formulator contracting for bulk liquid glucose, with regional wholesalers covering fragmented confectionery accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's corn glucose sector represents an early-cycle pharmaceutical channel expansion story. Domestic IV solution and tablet excipient requirements are accelerating faster than traditional confectionery offtake can offset.
For Market Incumbents: Compound port logistics advantages by securing dedicated tanker fleet capacity expansion ahead of Hebei and Henan capacity buildouts. Defend against cane sugar substitution in beverage channels through backward integration into captive corn supply in Jilin Province. Prioritize GMP line certification investment to capture pharmaceutical-grade premium tiers before provincial quality bureau validation timelines lengthen. For New Entrants and Emerging Players: Lead with fermentation-grade maltodextrin purity certification targeting sports nutrition and infant formula manufacturers in underpenetrated Central China corridors. Henan Province's Zhengzhou medical device corridor offers the most penetrable geography given reliance on Shandong tanker shipments. Establish direct e-commerce channels for specialty tier access before incumbent distributors consolidate online retail presence. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated wet millers with enzymatic conversion depth and carbon intensity benchmarking advantages. Long-term viability across the next decade hinges on dual carbon compliance positioning and pharmaceutical channel certification density. Acquisition targets should display anaerobic digestion biogas recovery deployment and provincial preferential procurement contract access. Monitor MEE wastewater discharge enforcement intensity as the critical inflection signal for supplier viability compression.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Line Certification Investment | Secures pharmaceutical channel access under SAMR's tightening GB 15203 enforcement timelines. |
| Anaerobic Digestion Biogas Recovery | Positions wet millers for preferential procurement contracts under provincial dual carbon frameworks. |
| Enzymatic Conversion Line Retrofit | Enables DE 99.5+ dextrose monohydrate production that acid hydrolysis infrastructure cannot achieve. |
| Direct Mill-to-Formulator Contracting | Concentrates procurement leverage with integrated processors possessing dedicated tanker fleet capacity. |
| Henan-Hebei Capacity Expansion | Reduces Shandong logistics dependency and opens direct distribution to inland pharmaceutical formulators. |
Research Approach
Desk research of customs trade records, SAMR regulatory filings, and MEE discharge monitoring reports preceded structured interviews with wet milling plant managers, pharmaceutical procurement leads, and enzymatic biocatalyst suppliers. Primary fieldwork with Shandong cluster operators and Beijing-Tianjin-Hebei formulators combined with secondary validation from provincial quality bureau sampling protocols. Bottom-up capacity assessments triangulated against top-down demand modeling across end-use segments.
Variance decomposition across product type, end user, and distribution channel dimensions anchored the analytical framework over the projection horizon. CAGRs derived from segmented demand elasticity modeling and input cost trajectory analysis. Forecast inputs incorporated corn belt harvest variability patterns, GB 15203 contaminant threshold evolution, and pharmaceutical channel penetration curves.
Underlying assumptions cover continued SAMR enforcement intensity and MEE discharge limit adherence, with deviation risk concentrated in northeastern corn belt weather shocks and Brazilian cane sugar supply expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Global Inactive Dried Yeast Market
Ingredients
India Starch and Starch Derivative Market
Ingredients
Quark Powder Market
Ingredients
Spelt Flour Market
Ingredients
Europe Algae Omega-3 Ingredients Market
Ingredients
Fruit Concentrate Market
Ingredients
Industrial and Bar-B-Que Charcoal Market
Ingredients
Specialty Yeast Market
Ingredients
Safflower Oil Market
Ingredients
Blue Light Protection Ingredients Market
Ingredients
Bean Flour Market
Ingredients
Plant Sterols and Esters Market
Ingredients
Sodium Reduction Ingredients Market
Ingredients
Europe Phytosterols Market
Ingredients
Global Tomato Powder Market
Ingredients
Oyster Shell Powder Market