
 Sodium Alginate Market | 2026-2036
Sodium Alginate Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Alginate Market Outlook
The sodium alginate trade is rebalancing between premium pharmaceutical-grade extraction and commodity industrial-grade supply, as purity specifications diverge sharply across end uses. KIMICA Corporation leverages its Japanese coastal harvesting infrastructure to sustain consistent high-viscosity alginate output for biomedical applications. Shandong Jiejing Group Corporation anchors the industrial segment through backward integration into Laminaria japonica farming along China's northern coast. Cargill Incorporated competes by extending its hydrocolloid distribution network into European food formulation channels.
Sodium alginate is a linear polysaccharide composed of β-D-mannuronic acid and α-L-guluronic acid residues, extracted via alkaline treatment of brown seaweed biomass and characterized by viscosity grades ranging from 20 to 700 mPa·s for industrial classification. Its primary commercial purpose centers on gelation, thickening, and stabilizing functions across food processing, textile printing, and controlled-release pharmaceutical matrices. Food Grade alginate dominates volume consumption but carries thinner margins, while Pharmaceutical Grade commands premium pricing due to USP-NF compliance burdens and limited qualified suppliers. Biomedical Applications represent the fastest-expanding demand pool, driven by wound dressing hydrogels and cell encapsulation protocols that require high-G-block structural integrity.
FDA food additive regulations under 21 CFR 184.1724 and USP monograph standards govern pharmaceutical-grade market access in the United States, while REACH registration and EFSA novel food assessments shape European import and formulation requirements. China's NMPA and GB standards for pharmaceutical excipients are tightening purity thresholds, forcing domestic processors to upgrade extraction protocols or exit the medical-grade segment. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and ChP standards, as divergent test methodologies threaten to fragment qualified supplier pools and reshape sourcing strategies without warning.
Market Dynamics
Pharmaceutical-grade purity mandates are splitting the sodium alginate supply base into parallel certification tracks, forcing processors to choose between capital-intensive USP-NF compliance or commodity industrial-grade volume plays.
Growth Catalysts
- EU Green Deal traceability mandates:REACH registration requirements for seaweed-derived hydrocolloids are accelerating certified supply chain investments among European food formulators seeking compliant alginate sources.
- Plant-based meat analogue expansion:Food manufacturers in Germany and the Netherlands are scaling alginate encapsulation for fat-mimetic textures in alternative protein products.
- Biomedical hydrogel protocols:High-G-block alginate specifications for cell encapsulation are pulling premium-grade extraction capacity toward wound dressing and regenerative medicine applications.
Market Restraints
- Laminaria japonica harvest volatility:Seasonal biomass availability along China's northern coast creates input cost swings that compress margins for industrial-grade processors.
- Pharmacopeial test methodology divergence:Non-harmonized purity assays between USP, EP, and ChP standards fragment qualified supplier pools and inflate cross-border compliance costs.
- Carrageenan and pectin substitution:Lower-cost hydrocolloids are displacing alginate in select food stabilization applications where gel strength requirements permit flexibility.
Strategic Opportunities
- Indian pharmaceutical excipient formalization:CDSCO's tightening excipient guidelines create first-mover advantage for alginate processors achieving USP-NF certification ahead of domestic capacity buildout.
- 3D bioprinting scaffold convergence:Crosslinking innovations combining alginate with gelatin and nanocellulose are opening tissue engineering applications beyond traditional wound care.
- Direct-to-formulator digital channels:Specialty chemical platforms are disintermediating traditional hydrocolloid distributors for mid-volume pharmaceutical and nutraceutical buyers.
Industry Challenges
- Alkaline extraction process engineering:Scaling continuous-flow caustic treatment systems requires specialized chemical engineering talent scarce in coastal seaweed processing regions.
- Dual certification timeline compression:Simultaneous USP and EP compliance audits for pharmaceutical-grade alginate extend qualification cycles and delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Alginate Market |
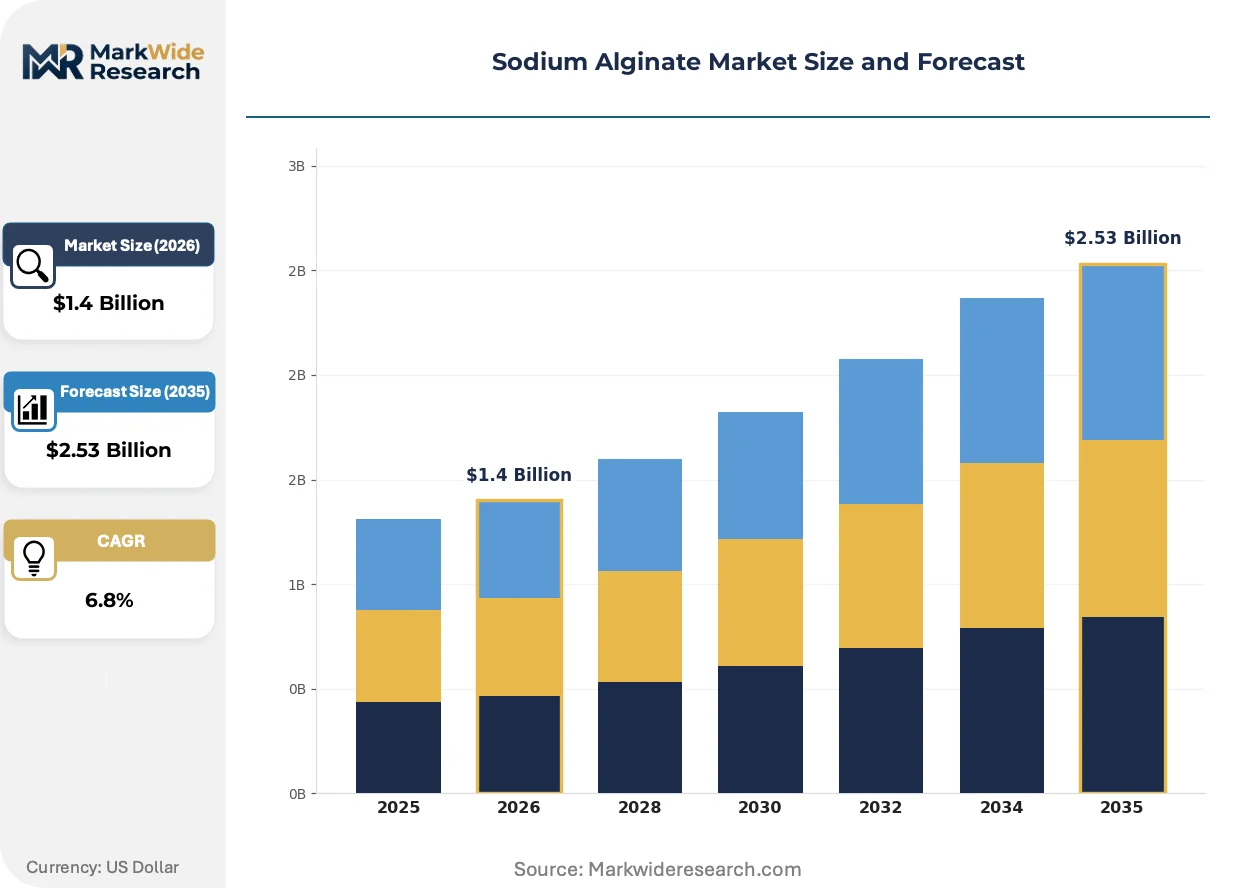
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Pharmaceutical Grade, Industrial Grade, Cosmetic Grade Application: Food Industry, Textile Industry, Pharmaceutical Applications, Biomedical Applications End User: Food Manufacturers, Textile Producers, Pharmaceutical Companies, Cosmetic Industries Distribution Channel: Online Retail, Offline Retail, Distributors, Wholesalers |
| Companies Covered | Algaia SA, Bright Moon Seaweed Group, FMC Corporation, SNAP Natural & Alginate Products, Shandong Jiejing Group Corporation, KIMICA Corporation, JiuLong Seaweed Industry, Brenntag, Cargill Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Alginate Market Strategic Shifts
Enzymatic extraction and precision fermentation are disrupting brown seaweed dependency, while regulatory data requirements and buyer consolidation reshape how alginate moves from harvest to formulation.
Continuous-flow enzymatic extraction is automating the transition from batch alkaline processing to membrane-filtered, viscosity-standardized output. Pharmaceutical formulators in Switzerland and Massachusetts are qualifying these streams for hydrogel matrices at accelerated pace. The technology is automating labor-intensive quality control steps that previously bottlenecked high-throughput biomedical-grade production.
REACH registration dossier updates under ECHA's 2023 substance evaluation work program are tightening heavy metal and microbial specification thresholds for imported seaweed hydrocolloids. European compounders dependent on Asian alginate supply must now validate extended contaminant testing protocols or face import suspension. Food-grade alginate shipments into Rotterdam and Hamburg are experiencing the most acute compliance friction, with several processors accelerating third-party laboratory partnerships.
Long-term offtake contracting is displacing spot-market hydrocolloid purchasing among multinational food manufacturers. Nestlé and Unilever procurement functions are consolidating alginate volumes through 36-48 month supply agreements with specified viscosity grade ladders. This pattern is most visible in Western European savory and dairy formulation channels, where input cost predictability now outweighs price arbitrage from quarterly spot sourcing.
Sodium Alginate Market Segmentation
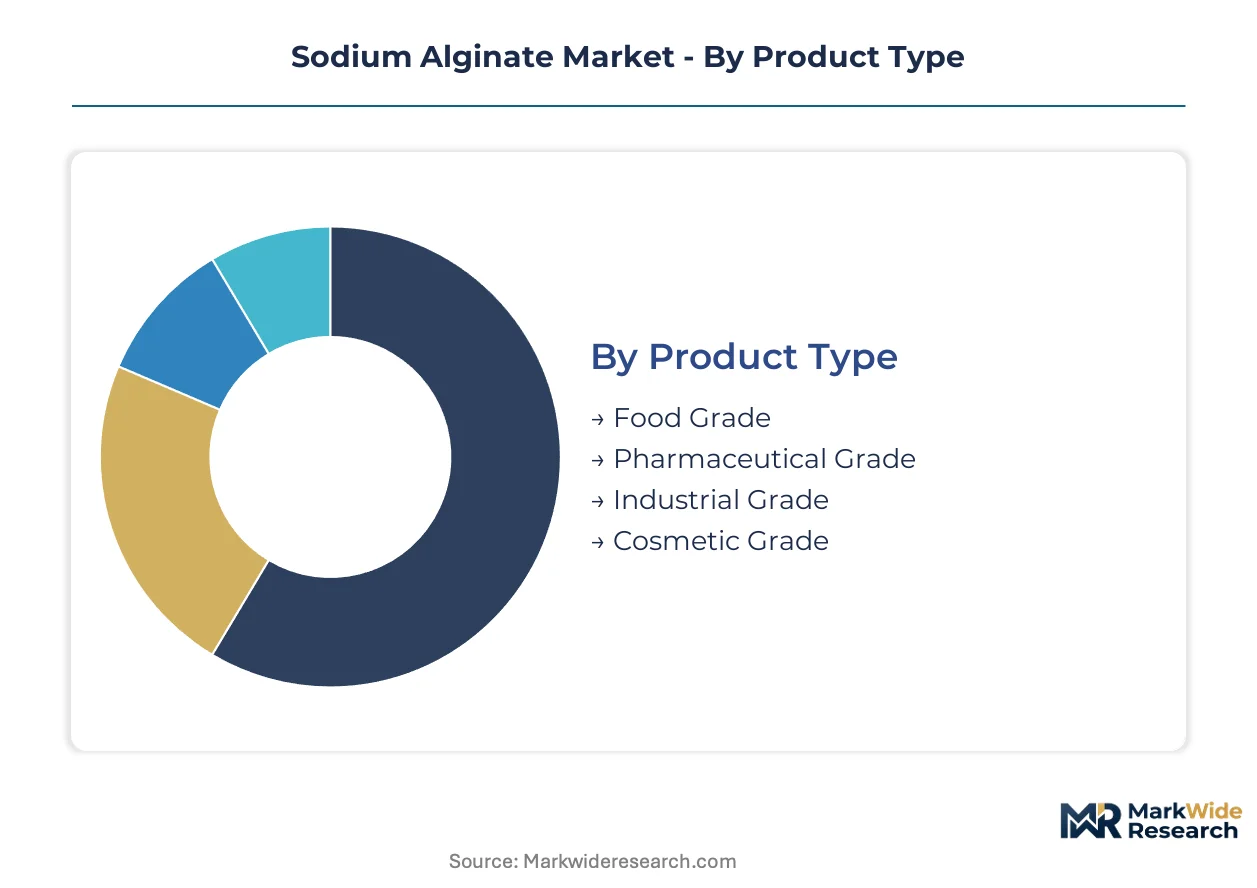
Sodium alginate markets fragment sharply across purity tiers, with certification burdens determining accessible customer pools and margin structures. Each segment carries distinct technical specifications, regulatory gatekeepers, and supply chain configurations that reshape competitive positioning.
Product Type:
USP-NF compliance burdens concentrate in pharmaceutical and food grades, while industrial and cosmetic specifications operate under lighter regulatory frameworks with faster qualification cycles.
- Food Grade:Complies with FDA 21 CFR 184.1724 and EFSA food additive specifications for thickening and gelling functions. Demand concentrates in European plant-based meat analogue formulators in Germany and the Netherlands, where EU Green Deal traceability mandates now require REACH-registered seaweed sourcing.
- Pharmaceutical Grade:Meets USP-NF monograph standards for excipient purity, with heavy metal and microbial thresholds significantly tighter than food specifications. Demand clusters in Swiss and Massachusetts-based hydrogel formulators developing cell encapsulation protocols, where dual USP-EP certification extends supplier qualification timelines.
- Industrial Grade:Standardized by viscosity ranges (20-700 mPa·s) without pharmacopeial compliance requirements. Textile printing mills in China's Zhejiang and Jiangsu provinces absorb the majority of volume.
- Cosmetic Grade:Falls under EU Cosmetics Regulation (EC) 1223/2009 and analogous national frameworks, prioritizing microbial safety over the viscosity precision demanded by biomedical applications.
Industrial Grade sits at the top of the volume ranking, with Pharmaceutical Grade climbing the fastest.
Application:
End-use concentration patterns split between mature, price-sensitive industrial channels and emerging biomedical applications commanding technical premiums.
- Food Industry:Encapsulation technologies for fat-mimetic textures in alternative proteins drive specification evolution. German and Dutch manufacturers are scaling alginate use in structured vegetable protein systems.
- Textile Industry:Reactive dye paste thickening for cotton and viscose printing remains the largest single consumption pool. China's export-oriented textile belt around Shaoxing and Nantong anchors regional demand.
- Pharmaceutical Applications:Controlled-release tablet matrices and oral suspension stabilizers require consistent viscosity profiles. CDSCO's tightening excipient guidelines in India are reshaping supplier qualification priorities for subcontinent-bound shipments.
- Biomedical Applications:High-G-block alginate for wound dressing hydrogels and cell encapsulation represents the steepest expansion trajectory. Swiss and Massachusetts formulators are accelerating qualification of enzymatic-extraction supply streams.
Textile Industry maintains the largest volume position, while Biomedical Applications gains share fastest.
End User:
Procurement sophistication varies dramatically across buyer categories, with pharmaceutical and food manufacturers driving specification tightening while textile producers prioritize cost stability.
- Food Manufacturers:Nestlé and Unilever procurement functions are consolidating alginate volumes through 36-48 month offtake agreements with specified viscosity grade ladders, displacing spot-market purchasing in Western European savory and dairy channels.
- Textile Producers:China's domestic alginate processors supply both local printing houses and export-oriented dye houses, with seasonal Laminaria japonica harvest volatility compressing margins for non-integrated buyers.
- Pharmaceutical Companies:USP-NF and EP compliance requirements fragment qualified supplier pools, with simultaneous dual-certification audits extending revenue recognition timelines for processors.
- Cosmetic Industries:Formulators prioritize REACH-registered supply chains under ECHA's tightened heavy metal and microbial specifications, with Rotterdam and Hamburg experiencing acute compliance friction for non-certified Asian shipments.
Textile Producers consume the highest absolute volumes, with Pharmaceutical Companies expanding procurement most quickly.
Distribution Channel:
Channel selection correlates with buyer scale and specification complexity, with specialty chemical platforms disintermediating traditional distributors for mid-volume pharmaceutical and nutraceutical purchasers.
- Online Retail:Serves small-scale cosmetic formulators and research laboratories requiring gram-to-kilogram quantities with rapid turnaround. Specialty chemical platforms are capturing share from traditional hydrocolloid distributors.
- Offline Retail:Regional chemical supply houses in coastal processing zones maintain inventory for textile mills and food processors with predictable, high-volume requirements.
- Distributors:Cargill's hydrocolloid distribution network extends into European food formulation channels, consolidating volumes across multiple viscosity grades for multinational manufacturers.
- Wholesalers:Industrial-grade alginate moves through bulk commodity traders in China's northern coastal provinces, with backward-integrated processors like Shandong Jiejing Group Corporation bypassing intermediaries for captive farming output.
Wholesalers handle the largest volume flows, with Online Retail expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands industrial-grade alginate volume through captive seaweed farming, while Switzerland and Massachusetts concentrate pharmaceutical-grade hydrogel formulation. This divergence between commodity supply and premium demand defines regional specialization patterns.
China
Shandong Province's Laminaria japonica harvests feed domestic textile printing mills in Zhejiang and Jiangsu provinces. NMPA's tightening GB standards for pharmaceutical excipients are forcing processors to upgrade extraction protocols or abandon medical-grade segments. Qingdao-based processors now supply both domestic formulators and export dye houses across Southeast Asia.
Germany
Plant-based meat analogue manufacturers in Cologne and Munich are scaling alginate encapsulation for fat-mimetic textures in alternative protein systems. REACH registration requirements under ECHA's substance evaluation program are accelerating certified supply chain investments among food formulators. Hamburg port authorities report acute compliance friction for non-certified Asian alginate shipments.
United States
Massachusetts hydrogel formulators are qualifying enzymatic-extraction alginate streams for cell encapsulation protocols at accelerated pace. FDA's 21 CFR 184.1724 food additive regulations and USP-NF monograph standards govern market access, with dual certification audits extending supplier qualification timelines. Boston-area biomedical clusters are pulling premium-grade extraction capacity toward regenerative medicine applications.
India
CDSCO's tightening excipient guidelines are reshaping supplier qualification priorities for subcontinent-bound pharmaceutical shipments. Mumbai and Hyderabad formulation hubs are consolidating procurement through extended supply agreements with specified viscosity grade ladders. Domestic alginate processors face margin compression from seasonal biomass volatility unless they achieve backward integration into coastal seaweed farming.
Switzerland
Swissmedic-regulated hydrogel manufacturers in Basel and Zurich are driving demand for high-G-block alginate with structural integrity specifications exceeding standard pharmacopeial thresholds. Precision fermentation research programs at federal technology institutes are exploring brown seaweed dependency reduction. Swiss formulators are accelerating qualification timelines for enzymatic-extraction supply streams from qualified Asian processors.
Sodium Alginate Market Competitive Environment
Top-tier vendors anchor pharmaceutical-grade certification tracks, while commodity industrial-grade processors compete on harvest integration and viscosity standardization. The supply base splits sharply between USP-NF compliance investments and volume-driven textile printing supply. Three archetypes dominate: coastal harvesters with captive farming operations, pharmaceutical-grade specialists with dual-certification capabilities, and distribution-integrated hydrocolloid networks. Competitive moves concentrate on backward integration into seaweed biomass and enzymatic extraction technology licensing.
Within the coastal harvester archetype, Shandong Jiejing Group Corporation and Bright Moon Seaweed Group exemplify processors leveraging geographic proximity to Laminaria japonica beds. KIMICA Corporation occupies a position representing Japanese pharmaceutical-grade specialists with coastal infrastructure advantages. Cargill Incorporated anchors the distribution-integrated tier, extending hydrocolloid networks into European food formulation channels without direct harvesting exposure.
| Leading Market Players |
|---|
| Algaia SA |
| Bright Moon Seaweed Group |
| FMC Corporation |
| SNAP Natural & Alginate Products |
| Shandong Jiejing Group Corporation |
| KIMICA Corporation |
| JiuLong Seaweed Industry |
| Brenntag |
| Cargill Incorporated |
| Others |
Value Chain & Pricing Dynamics
Family-owned coastal processors in China's Shandong and Fujian provinces anchor industrial-grade supply, their harvest integration enabling cost discipline that private-equity-rolled-up pharmaceutical specialists cannot match. This ownership fragmentation creates divergent pricing power across purity tiers, with USP-NF certification investments by Japanese and European players sustaining premium capture against commodity spot volatility.
Pricing Analysis
Service bundling separates pharmaceutical-grade alginate from unbundled industrial commodity sales. Three-tier pricing structure across premium, standard, and economy levels reflects USP-NF compliance burdens, enzymatic extraction technology, and viscosity precision. Price differentiation stems from certification level—dual USP-EP audits versus single-grade food additive compliance—and volume scale in long-term offtake agreements. Cost compression in industrial grades intensifies because Laminaria japonica harvest volatility forces spot-market processors to absorb input swings. Textile mills in China's Zhejiang province exhibit highest price sensitivity, while Swiss hydrogel formulators prioritize structural integrity over unit economics.
Supply Chain Analysis
Reverse-logistics flows for pharmaceutical-grade alginate remain minimal given single-use hydrogel applications, though enzymatic extraction byproduct streams are finding secondary cosmetic markets. Supply concentrates in China, Japan, and Norway for seaweed biomass, with downstream processing clustering in Shandong Province and coastal Japan. Raw material dependencies rest on Laminaria japonica and Macrocystis pyrifera harvests, sodium carbonate for alkaline treatment, and membrane filtration systems. Single-source vulnerability runs through China's northern coastal farming zones, where climate anomalies disrupt seasonal biomass availability. Distribution runs through Cargill's European hydrocolloid networks for food-grade volumes and direct processor relationships for pharmaceutical buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in sodium alginate hinges on enzymatic extraction technology licensing, which collapses processing costs for biomedical-grade output while preserving premium pricing power.
For Market Incumbents: Lock in backward integration into Laminaria japonica farming along China's northern coast to neutralize harvest volatility that compresses industrial-grade margins. Prioritize simultaneous USP-EP certification investments before CDSCO's tightening excipient guidelines fragment qualified supplier pools in India. Defensive consolidation around enzymatic extraction patents will block emerging biotechnology entrants from qualifying high-G-block hydrogel streams. For New Entrants and Emerging Players: The price-point gap between pharmaceutical-grade premiums and industrial-grade spot markets offers entry space for mid-tier food-grade specialists. White-space targets include Indian pharmaceutical excipient formalization ahead of domestic capacity buildout, and 3D bioprinting scaffold applications combining alginate with nanocellulose. The most penetrable segment sits in European plant-based meat analogue encapsulation, where REACH-registered supply chains face acute compliance friction. A direct-to-formulator digital channel strategy bypasses Cargill's distribution lock-in for mid-volume nutraceutical buyers. For Investors and Strategic Acquirers: Valuations sit cheapest among industrial-grade processors lacking pharmaceutical certification tracks, yet these assets carry stranded-risk if NMPA's GB standard tightening accelerates. Long-term viability favors dual-certified specialists with enzymatic extraction capabilities and coastal farming integration across the analysis window. Acquisition targets should display USP-NF qualification timelines already initiated. The signal to watch is ECHA's substance evaluation program enforcement against non-certified Asian shipments into Rotterdam and Hamburg.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seaweed Farming | Captive Laminaria japonica supply neutralizes harvest volatility compressing Shandong processor margins. |
| Dual USP-EP Certification Investment | Simultaneous audits extend qualification timelines but lock access to Swiss and Massachusetts hydrogel formulators. |
| Enzymatic Extraction Technology Licensing | Continuous-flow membrane filtration automates quality control bottlenecking high-throughput biomedical production. |
| Direct-to-Formulator Digital Channel | Specialty chemical platforms disintermediate Cargill's hydrocolloid distribution for mid-volume pharmaceutical buyers. |
| Long-term Supply Agreement Structuring | Nestlé and Unilever procurement consolidation through 36-48 month offtakes displaces spot-market purchasing in Europe. |
Study Parameters
Bottom-up food and pharmaceutical formulation modeling reconciled against top-down seaweed harvest and trade tracking forms the analytical core of this study. Primary interviews with extraction plant managers, procurement leads at textile dye houses, hydrocolloid distribution channel partners, and technical R&D directors at biomedical formulators combined with secondary validation from customs records, NMPA GB standard filings, ECHA REACH registration dossiers, and USP-NF monograph updates. Triangulation between demand-side consumption patterns and supply-side capacity buildouts ensures statistical integrity across purity tier segments.
Historical trendline analysis of viscosity-grade pricing and certification-premium trajectories informed projection modeling across the analysis window. Segmentation dimensions include product grade tier, end-use industry, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to baseline consumption estimates, with enzymatic extraction adoption rates and CDSCO excipient guideline implementation timelines serving as key forecast inputs.
Caveats apply where pharmacopeial test methodology divergence between USP, EP, and ChP standards could materially shift the outlook for qualified supplier pool fragmentation. Practitioners should monitor ECHA enforcement actions against non-certified Asian shipments and NMPA's GB standard revision timeline for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Karaya Gum Market
Ingredients
North America Rice Protein Ingredients Market
Ingredients
Honey Powder Market
Ingredients
Corn Peptide Market
Ingredients
Pet Food Premix Market
Ingredients
Banana Essence Market
Ingredients
Homecare Ingredients Market
Ingredients
Dried Tomato Lycopene-Rich Flake Ingredients Market
Ingredients
Potato Starch Market
Ingredients
Asia-Pacific Soy Protein Concentrate Market
Ingredients
Alginate Market
Ingredients
Europe Dairy Protein Market
Ingredients
China Protein Market
Ingredients
India Olive Oil Market
Ingredients
North America Milk Protein Market
Ingredients
Zea Mays Starch Market