
 China Protein Market | 2026-2036
China Protein Market Size, Share, and Industry Trends Forecast 2026-2036
China Protein Market Outlook
Soy protein isolate is decoupling from traditional livestock feed economics as precision fermentation and extrusion technologies cut production costs. Cargill leverages its crush facility network across Jiangsu and Shandong to anchor domestic soy protein supply. Shandong Yuwang Industrial specializes in pea and rice protein blends for beverage applications. International Flavors & Fragrances, Inc. competes on flavor-masked protein systems that improve palatability in high-load formulations.
China protein encompasses amino acid chains derived from animal tissue, oilseed processing, microbial fermentation, or fractionated plant matter, typically standardized to minimum protein content thresholds and functional properties such as emulsification or gelation. The primary commercial purpose centers on fortifying human foods, feed rations, and therapeutic formulations with nitrogenous compounds essential for tissue repair and metabolic function. Animal protein still occupies the largest revenue pool among product types, though plant protein is displacing share in beverage and meat-analog applications where sustainability claims command shelf space premiums. Within applications, food and beverage manufacturers represent the most concentrated buyer segment, while nutraceuticals delivers the fastest growth trajectory as functional food regulations clarify health claim pathways.
NMPA food safety registrations and GB standards for protein content labeling shape product formulation and import access conditions for foreign suppliers. China's dual carbon goals and MEE wastewater discharge rules are forcing inland processors to upgrade rendering and extraction infrastructure or face production curbs. Stakeholders must monitor how provincial environmental enforcement intensity varies across the Yangtze River basin versus northern industrial corridors.
Market Dynamics
Precision fermentation and extrusion technologies are compressing production costs for plant protein isolates, severing the historical cost link to livestock feed economics and enabling standalone pricing power for ingredient suppliers.
Growth Catalysts
- Dual carbon goals:China's national emissions targets are accelerating capital flows into low-carbon protein production infrastructure, particularly microbial fermentation systems that bypass agricultural land use.
- Sports nutrition:Health enthusiasts in coastal cities are expanding consumption of protein-fortified beverages and supplements, creating sustained demand pull for high-purity isolates.
- Precision fermentation:This biotechnology pathway is cutting unit production costs for alternative proteins while improving functional properties like emulsification stability in beverage applications.
Market Restraints
- Soy crush concentration:Domestic soy protein supply chains cluster heavily in Jiangsu and Shandong provinces, creating geographic vulnerability to localized environmental enforcement actions.
- GB standards friction:NMPA food safety registrations and protein content labeling requirements impose lengthy compliance timelines that delay foreign supplier market entry.
- Technical limitation:Flavor masking remains imperfect for high-load plant protein formulations, constraining adoption in premium ready-to-drink applications where taste thresholds are unforgiving.
Strategic Opportunities
- Clinical nutrition:Therapeutic formulations for metabolic and recovery applications represent underpenetrated white space with higher margin profiles than commodity food ingredients.
- Guangdong cluster:Southern China's manufacturing corridor offers proximity to export channels and lighter environmental enforcement intensity compared to Yangtze River basin competitors.
- Technology convergence:Integration of AI-driven formulation optimization with extrusion processing is enabling rapid prototyping of texture-matched meat analogs.
Industry Challenges
- Skill scarcity:Fermentation process engineers with food-grade biomanufacturing experience command premium compensation, constraining scale-up velocity for new entrants.
- Capex intensity:MEE wastewater discharge compliance requires rendering and extraction infrastructure upgrades that absorb 15-25% of annual capital budgets for inland processors.
- Certification timelines:NMPA novel food ingredient approvals stretch 18-36 months, freezing product launch pipelines for innovative protein sources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Protein Market |
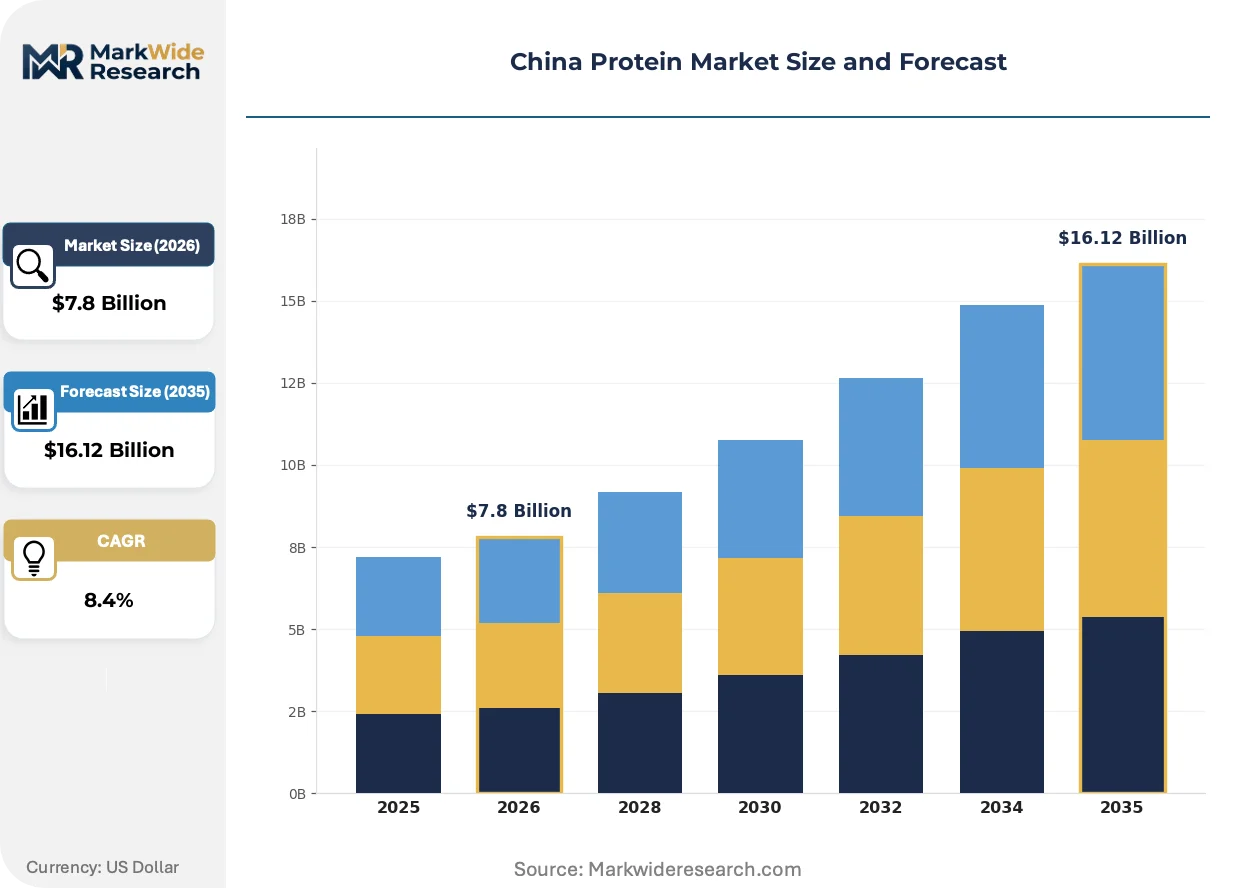
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $16.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Animal Protein, Plant Protein, Protein Supplements, Protein-enriched Foods Application: Food & Beverage, Pharmaceuticals, Nutraceuticals, Animal Feed Customer Type: Retail Consumers, Food Manufacturers, Health Enthusiasts, Fitness Centers Distribution Channel: Online Retail, Supermarkets, Health Stores, Food Service |
| Companies Covered | Darling Ingredients Inc., Cargill, Archer Daniels Midland Company, Shandong Yuwang Industrial, Fushine Bio, Fonterra Co-operative Group Limited, FUJI OIL HOLDINGS INC., Shandong Jianyuan Bioengineering, International Flavors & Fragrances, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Protein Market Strategic Shifts
Active restructuring across production technology, regulatory compliance frameworks, and buyer procurement behavior is fragmenting established competitive positions and opening entry paths for specialized suppliers.
Precision fermentation is decentralizing protein production economics by enabling microbial biomass cultivation in compact bioreactor facilities located near urban demand centers. Beverage manufacturers and meat-analog startups are adopting these systems at pilot scale ahead of regulatory clarity. This distributed production model is compressing the historical advantage of large-scale agricultural commodity processors.
NMPA food safety registrations and evolving GB standards for protein content labeling are tightening traceability requirements across the supply chain. Foreign ingredient suppliers face extended documentation burdens that favor domestic crush facility networks with established compliance histories. Clinical nutrition applications bear the heaviest documentation load, driving formulation partnerships with registered domestic entities.
Buyer concentration among coastal food and beverage manufacturers is compressing supplier negotiation cycles and unbundling technical service from base ingredient supply. Procurement teams now separate flavor-system integration from protein sourcing, creating openings for specialized mask-technology providers. This pattern is most visible in Shanghai's manufacturing cluster, where multinational beverage R&D centers drive specification standards.
China Protein Market Segmentation
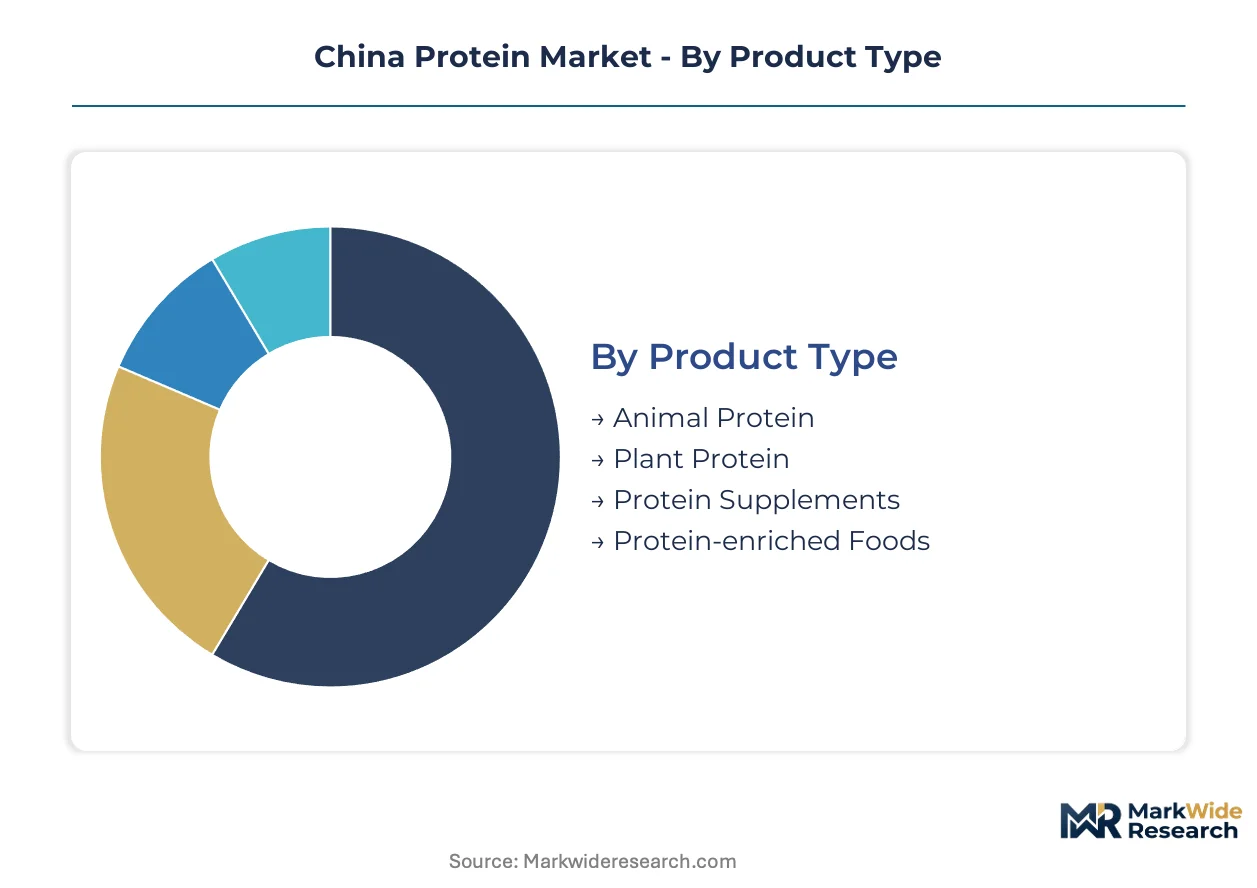
Protein market segmentation in China reveals stark capital allocation patterns across production technologies and buyer relationships. Distinct investment requirements separate commodity-scale animal processing from precision fermentation infrastructure.
Product Type:
Animal protein commands the heaviest upfront capital commitment due to rendering infrastructure and cold-chain dependencies.
- Animal Protein:Derived from rendered tissue, blood meal, and dairy fractions, standardized to minimum digestibility coefficients for feed and food-grade applications. Jiangsu and Shandong crush facilities concentrate supply, though MEE wastewater discharge rules are forcing inland processors into costly infrastructure upgrades.
- Plant Protein:Soy, pea, and rice isolates produced via extrusion and fractionation, with precision fermentation compressing unit economics. Coastal beverage manufacturers in Shanghai and Guangdong drive demand for high-purity isolates with improved emulsification stability.
- Protein Supplements:Powder and ready-to-drink formats targeting sports nutrition applications.
- Protein-enriched Foods:Fortified bakery, dairy, and snack products with label-friendly positioning.
Animal protein absorbs the bulk of installed capacity; plant protein is expanding most quickly.
Application:
Margin profiles diverge sharply between commodity food ingredients and regulated therapeutic formulations.
- Food & Beverage:The largest volume pool, encompassing meat processing, dairy fortification, and beverage applications. Buyer concentration among coastal manufacturers compresses supplier negotiation cycles and unbundles technical service from base ingredient supply.
- Pharmaceuticals:Clinical nutrition and therapeutic formulations for metabolic and recovery applications carry higher documentation burdens under NMPA novel food ingredient pathways.
- Nutraceuticals:Functional foods and dietary supplements with clarified health claim regulations driving formulation partnerships.
- Animal Feed:Livestock and aquaculture rations where soy meal economics traditionally anchored pricing.
Food and beverage commands dominant volume share; nutraceuticals climbs the fastest on regulatory clarity.
Customer Type:
Procurement sophistication separates institutional buyers from fragmented consumer channels.
- Retail Consumers:Individual purchasers through e-commerce and retail, price-sensitive and brand-driven.
- Food Manufacturers:Multinational R&D centers in Shanghai set specification standards that cascade through supplier tiers.
- Health Enthusiasts:Coastal urban consumers expanding protein-fortified beverage and supplement consumption.
- Fitness Centers:Gyms and sports facilities distributing bulk supplements to member bases.
Food manufacturers dominate procurement volume; health enthusiasts gain share fastest on lifestyle shifts.
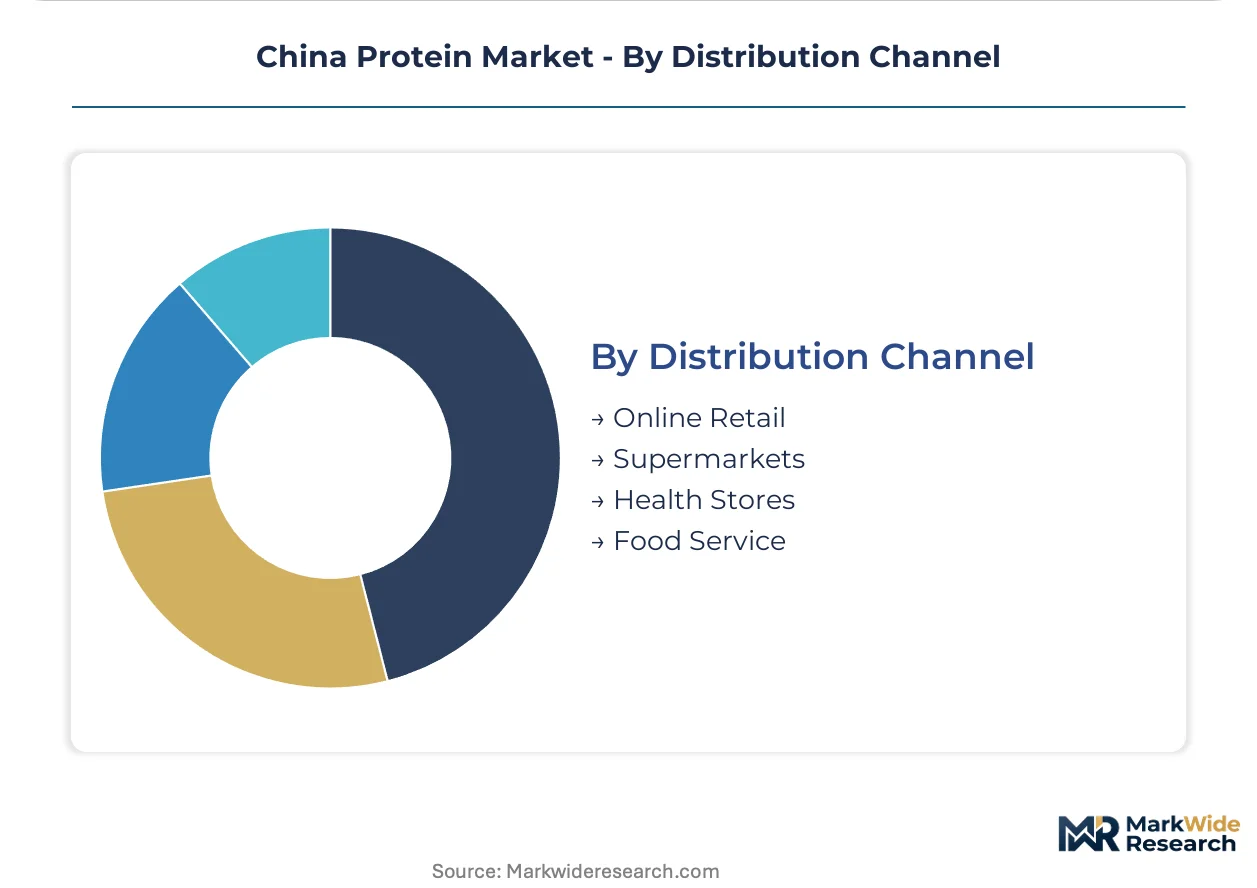
Distribution Channel:
Channel selection determines margin capture and traceability compliance intensity.
- Online Retail:Dominant growth vector with direct-to-consumer protein supplements and enriched foods.
- Supermarkets:Mass-market protein-enriched foods with shelf-space competition from private labels.
- Health Stores:Premium supplement positioning with educated staff driving conversion.
- Food Service:Ingredient supply to restaurants and institutional kitchens with bulk pricing structures.
Online retail captures the steepest expansion trajectory; supermarkets retain the largest throughput base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for protein ingredients concentrates in coastal manufacturing corridors where beverage and nutraceutical formulators cluster. Provincial environmental enforcement intensity varies sharply between the Yangtze River basin and southern industrial zones.
Yangtze River Delta
Shanghai anchors beverage R&D centers that set specification standards cascading through supplier tiers. NMPA food safety registrations impose documentation burdens favoring domestic crush facilities with established compliance histories. Precision fermentation pilots are compressing production economics for plant protein isolates in compact bioreactor facilities near urban demand centers.
Shandong Peninsula
Soy crush facilities dominate supply chain concentration for animal and plant protein fractions. MEE wastewater discharge rules are forcing inland processors into infrastructure upgrades absorbing substantial capital budgets. Cargill leverages its crush network across Jiangsu and Shandong to anchor domestic soy protein supply.
Pearl River Delta
Guangdong province offers proximity to export channels with lighter environmental enforcement intensity compared to northern competitors. Dual carbon goals are accelerating capital flows into low-carbon protein production infrastructure. Shandong Yuwang Industrial specializes in pea and rice protein blends for beverage applications targeting this cluster.
Beijing-Tianjin-Hebei
Clinical nutrition formulators drive demand for high-purity isolates with improved emulsification stability. GB standards for protein content labeling shape product formulation and import access conditions for foreign suppliers. Therapeutic formulations for metabolic applications represent underpenetrated white space with higher margin profiles.
Sichuan-Chongqing
Western China manufacturing bases are expanding protein-enriched food production for domestic consumption. SAMR market supervision frameworks are tightening traceability requirements across inland supply chains. Regional processors face skill scarcity for fermentation engineers with food-grade biomanufacturing experience.
China Protein Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with multinational ingredient suppliers holding position in flavor-system integration while domestic crush operators dominate commodity protein supply. The vendor base organizes around three archetypes: agricultural commodity processors with backward integration into oilseed crushing, precision fermentation startups with compact bioreactor footprints, and flavor-technology specialists masking high-load plant formulations. Dominant competitive moves include geographic expansion into Guangdong's lighter regulatory environment and technology licensing partnerships that bypass lengthy NMPA novel food ingredient approvals.
Within the agricultural processing tier, Cargill and Archer Daniels Midland Company exemplify scale-driven operators with crush facility networks. Among precision fermentation specialists, Fushine Bio occupies a position representing biotechnology pathways that cut unit production costs. On the flavor-system vector, International Flavors & Fragrances, Inc. anchors the segment for palatability improvement in high-load formulations. Shandong Yuwang Industrial and Shandong Jianyuan Bioengineering represent regional Chinese specialists with focused positions in plant protein blends and bioengineering applications respectively. Darling Ingredients Inc. and FUJI OIL HOLDINGS INC. sit within the rendered tissue and oilseed processing archetypes serving feed and food-grade markets.
| Leading Market Players |
|---|
| Darling Ingredients Inc. |
| Cargill |
| Archer Daniels Midland Company |
| Shandong Yuwang Industrial |
| Fushine Bio |
| Fonterra Co-operative Group Limited |
| FUJI OIL HOLDINGS INC. |
| Shandong Jianyuan Bioengineering |
| International Flavors & Fragrances, Inc. |
| Others |
Value Chain & Pricing Dynamics
Fermentation process engineers with food-grade biomanufacturing experience in Jiangsu and Shandong command premium compensation, widening spreads between commodity animal protein and precision-fermented plant isolates as labor-cost differentials stratify the market into distinct pricing tiers.
Pricing Analysis
Volume concentrates in commodity animal protein fractions while margins accrue to clinical nutrition isolates with NMPA novel food ingredient registrations. Three-tier pricing structure across premium, standard, and economy levels separates flavor-masked beverage formulations from feed-grade soy meal. Price compression runs through standard-tier plant isolates as extrusion capacity expands in coastal clusters. Food manufacturers with multinational R&D centers in Shanghai exhibit lowest price sensitivity; inland feed compounders face acute cost pressure.
Supply Chain Analysis
Regional distribution centers in Shanghai and Guangzhou operate hub-and-spoke patterns feeding beverage manufacturers and meat-analog startups. Supply concentrates in China's Jiangsu and Shandong crush corridors, with secondary sourcing from Australian dairy fractions and Brazilian soy. Raw material dependencies include non-GMO soybeans, pea protein concentrate, and microbial fermentation feedstocks. Single-source vulnerability to MEE wastewater enforcement in the Yangtze River basin threatens rendering infrastructure. Distribution runs through domestic crush facility networks with established NMPA compliance histories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
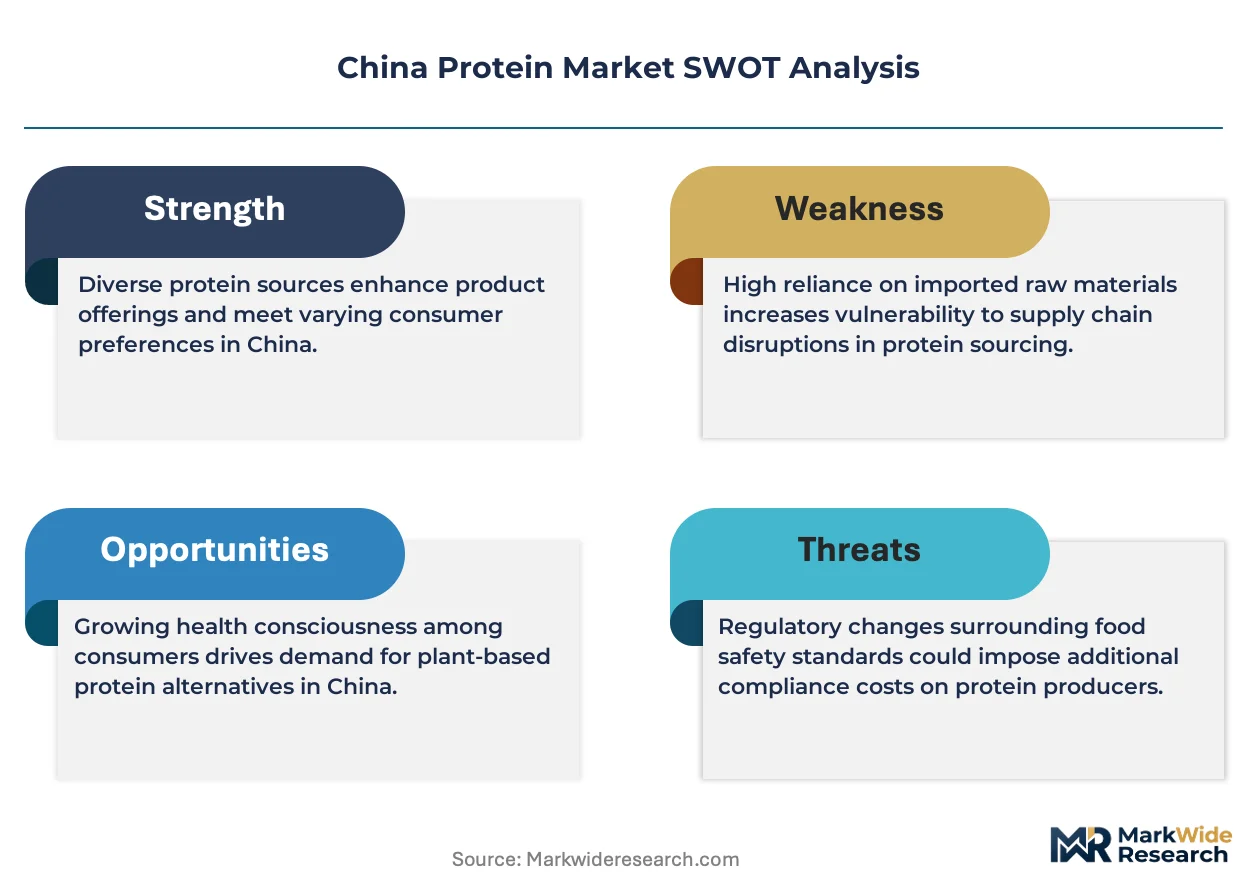
China's protein market reads as supply-constrained: NMPA novel food ingredient approval timelines stretching 18-36 months prop pricing power for registered domestic entities while freezing launch pipelines for unregistered alternatives.
For Market Incumbents: Extend backward integration into Jiangsu and Shandong crush infrastructure to secure captive supply of non-GMO soy isolates. Deepen fermentation engineering talent pools through technical university partnerships in coastal cities. Precision fermentation startups threaten commodity positioning; defend via exclusive distribution lock-ups with Guangdong beverage manufacturers.
For New Entrants and Emerging Players: Launch via direct-to-online retail channels targeting health enthusiasts in Shanghai and Shenzhen with flavor-optimized ready-to-drink formulations. Clinical nutrition applications for metabolic recovery represent the most penetrable white space, with higher documentation burdens screening out commodity suppliers. Partner with registered domestic entities to bypass NMPA approval bottlenecks.
For Investors and Strategic Acquirers: Re-rating potential sits with precision fermentation specialists given dual carbon goal acceleration into low-carbon protein infrastructure. Five-to-ten-year viability favors compact bioreactor operators with pilot-scale validation near urban demand centers. Monitor NMPA novel food ingredient approval velocity as the inflection signal for portfolio reallocation.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Dual carbon goals channel capital toward microbial systems bypassing agricultural land use in Jiangsu. |
| Flavor-System Integration Partnership | International Flavors & Fragrances, Inc. anchors palatability improvement for high-load plant formulations. |
| Guangdong Manufacturing Expansion | Lighter MEE enforcement intensity versus Yangtze River basin offers cost-advantaged production positioning. |
| NMPA Registration Fast-Track | Domestic crush facilities with established compliance histories accelerate market access for foreign suppliers. |
| Clinical Nutrition Formulation Development | Therapeutic applications for metabolic recovery carry higher margins than commodity food ingredients. |
Study Parameters
Document review covered NMPA food safety registration databases, GB standards documentation, and MEE wastewater discharge compliance records, complemented by interviews with fermentation process engineers, beverage R&D directors at multinational manufacturers, procurement leads at coastal food manufacturers, and regulatory affairs specialists navigating novel food ingredient pathways. Secondary validation drew from SAMR market supervision frameworks, customs trade data on soy isolate imports, and crush facility capacity disclosures. Bottom-up demand modeling from end-use applications triangulated against top-down supply-side capacity assessments.
Segmentation outputs across the projection horizon disaggregated volume and value by product type, application, customer archetype, and distribution channel, with additional granularity on precision fermentation versus extrusion processing technology splits. CAGRs derived from fitted growth curves incorporating regulatory approval velocity, environmental enforcement intensity differentials, and coastal versus inland manufacturing cost structures. Forecast inputs included NMPA registration pipeline data and provincial dual carbon implementation timelines.
Regulatory approval delays, abrupt MEE enforcement intensification, and fermentation feedstock price volatility are the dominant revision risks to modeled outcomes. Forecasts embed assumptions regarding NMPA pathway clarification and carbon policy continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Asia-Pacific Protein Market
Ingredients
Rye Bran Beta-Glucan Market
Ingredients
Omega Ingredients Market
Ingredients
Asia-Pacific Prebiotic Ingredients Market
Ingredients
Cocoa Derivatives Market
Ingredients
Pea Peptones Market
Ingredients
Cacao Extracts Market
Ingredients
Salt Market
Ingredients
United States Avocado Oil Market
Ingredients
Agave Inulin Market
Ingredients
Citrus Based Dietary Fibers Market
Ingredients
Liquid Egg Market
Ingredients
Calcium Caseinate Market
Ingredients
Birch Sap Market
Ingredients
Punica Granatum (Pomegranate) Seed Oil Market
Ingredients
Camelina Oil Market