
 Europe Clean Label Ingredient Market | 2026-2036
Europe Clean Label Ingredient Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Clean Label Ingredient Market Foresight
Multi-source procurement of natural colorants and plant-derived stabilizers is shifting as mid-sized European food manufacturers reduce dependency on single botanical suppliers. Cargill leverages its European grain processing network to secure regional supply chains for clean-label starches. Kerry Group PLC sustains competitive advantage through integrated taste and nutrition platforms spanning savory and dairy applications. Corbion NV specializes in fermentation-derived preservation systems that replace synthetic sorbates in baked goods.
Clean label ingredients comprise minimally processed, recognizable raw materials—such as rosemary extract, acerola cherry concentrate, or native corn starch—specified by absence of artificial preservatives, synthetic colors, and chemically modified compounds, serving primarily to maintain shelf stability, sensory performance, and nutritional equivalence in reformulated consumer packaged goods. Natural preservatives occupy the largest volume share within ingredient type segmentation, while clean label flavors command premium positioning due to complex extraction costs and intellectual property concentration. Dairy applications lead absolute demand within the application dimension, though beverage reformulation is accelerating fastest as carbonated soft drink manufacturers respond to sugar taxation and clean-label retailer standards across Northern Europe.
EFSA additive re-evaluations, EU Green Deal sustainable sourcing mandates, and REACH chemical disclosure requirements collectively tighten permissible inputs and compel ingredient suppliers to validate botanical provenance and extraction solvent profiles. CE marking alignment for novel food ingredients adds a secondary compliance layer for enzymatically modified or fermented clean-label inputs entering European commerce. Stakeholders must monitor pending EFSA opinions on titanium dioxide and azo dye replacements, as these rulings will redirect R&D spending toward plant-derived alternatives and reshape supplier qualification criteria for pan-European food manufacturers.
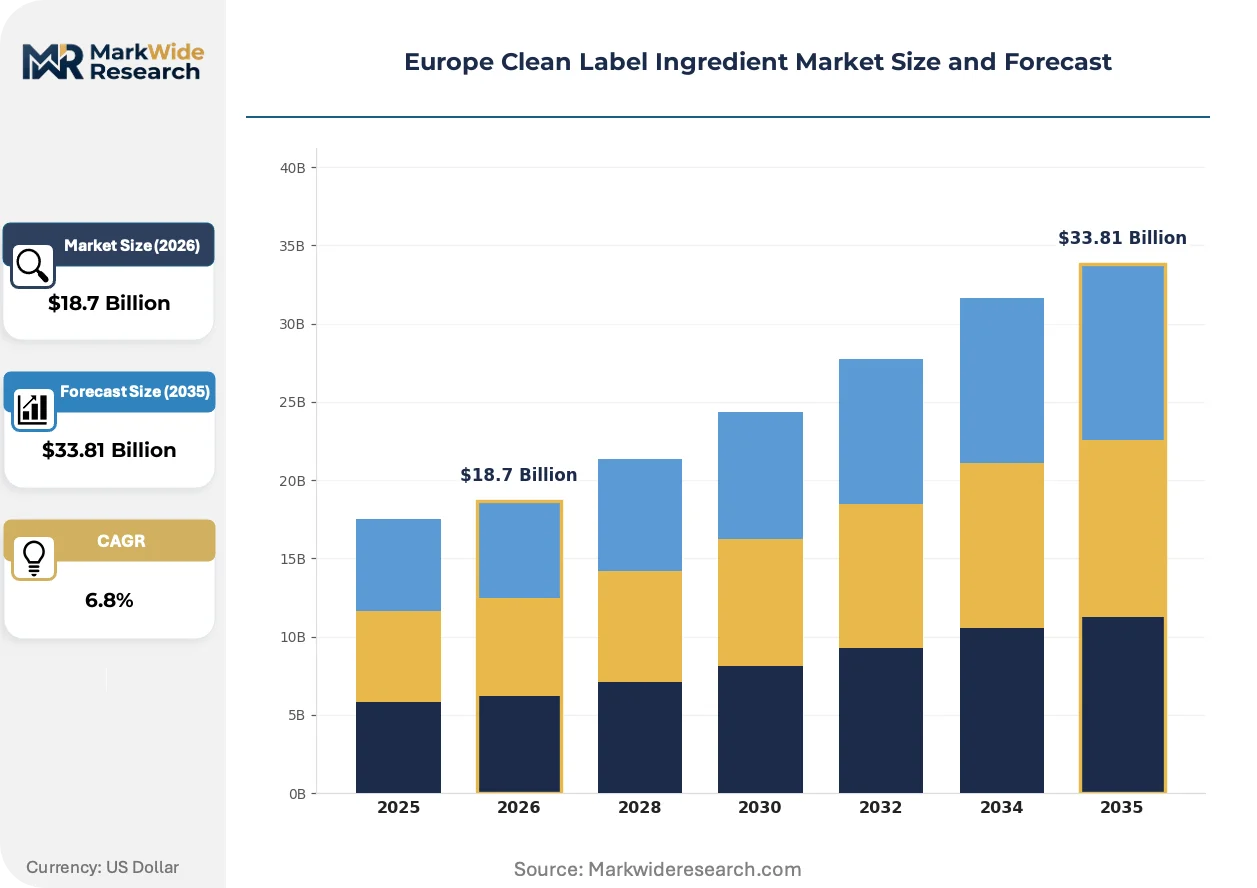
Market Dynamics
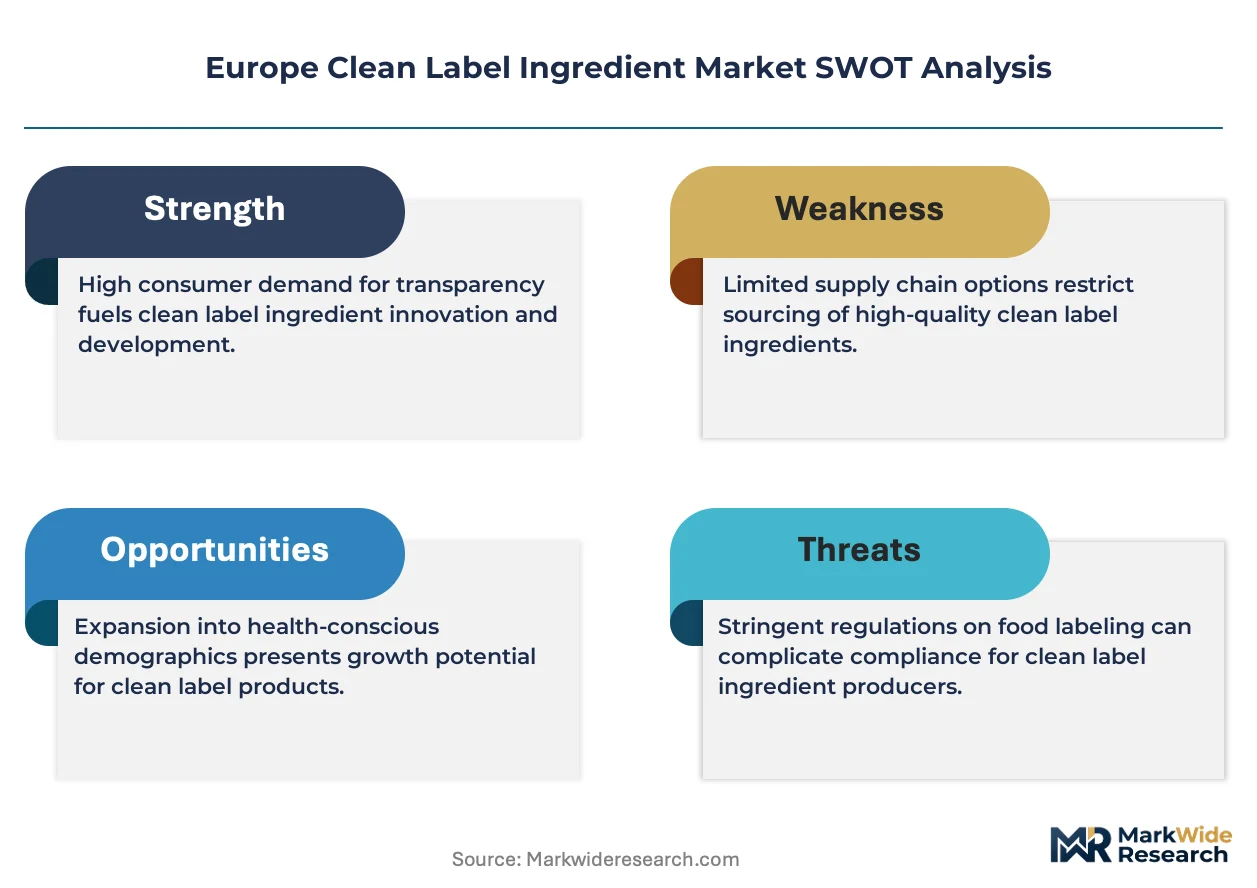
EFSA additive re-evaluations and EU Green Deal mandates are compressing approved ingredient lists, forcing European food manufacturers to rebuild formulations around botanical extracts and fermentation-derived alternatives.
Growth Catalysts
- Retailer private-label transparency protocols:German, French, and British supermarket chains enforce strict ingredient disclosure standards that cascade reformulation requirements upstream to ingredient suppliers.
- EU Green Deal sustainable sourcing mandates:These frameworks validate botanical provenance and extraction methods, creating competitive differentiation for compliant suppliers.
- Sugar taxation across Northern Europe:Carbonated soft drink manufacturers accelerate clean-label beverage reformulation to meet retailer standards and avoid levy impacts.
Market Restraints
- Complex extraction costs:Clean label flavors require sophisticated solvent recovery and intellectual property concentration that elevates input pricing versus synthetic alternatives.
- Single-supplier dependency risk:Mid-sized manufacturers historically relied on sole botanical sources for natural colorants and stabilizers, creating vulnerability to harvest volatility.
- CE marking alignment delays:Novel enzymatically modified or fermented ingredients face extended approval timelines for European commerce entry.
Strategic Opportunities
- Eastern European manufacturing expansion:Poland and Romania offer underpenetrated production capacity for clean-label ingredient processing with lower operational costs.
- Fermentation-derived preservation systems:Baked goods applications represent white space for sorbate replacements using cultured metabolites.
- REACH chemical disclosure requirements:These obligations create first-mover advantage for suppliers with pre-validated solvent profiles and extraction documentation.
Industry Challenges
- Formulation scientist scarcity:European food manufacturers face talent gaps in natural ingredient stabilization and shelf-life modeling.
- Multi-source procurement complexity:Reducing dependency on single botanical suppliers requires renegotiating qualification protocols and quality consistency validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Clean Label Ingredient Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Natural Preservatives, Organic Sweeteners, Clean Label Flavors, Whole Grain Ingredients Application: Dairy Products, Beverages, Bakery, Snack Foods Form: Powdered, Liquid, Granular, Whole Certification: USDA Organic, Non-GMO Project Verified, Kosher, Gluten-Free |
| Companies Covered | Tate & Lyle PLC, Sensient Technologies Corporation, Cargill, Ingredion Incorporated, Corbion NV, Kerry Group PLC, Koninklijke DSM NV, Givaudan SA, Archer Daniels Midland Company, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Clean Label Ingredient Market Shifts & Advancements
Ingredient processing architectures are fragmenting into specialized units that separate extraction, concentration, and stabilization functions, enabling distributed production networks across European food manufacturing regions.
Precision fermentation platforms are modularizing clean-label ingredient supply by separating biomass production from metabolite extraction. Dairy and savory manufacturers adopt these systems at pilot scale initially. This architecture compresses capital requirements for regional supply deployment.
EFSA opinions on titanium dioxide and azo dye replacements are redirecting R&D spending toward plant-derived alternatives. Pan-European food manufacturers reshape supplier qualification criteria preemptively. Baked goods and confectionery segments accelerate natural colorant trials.
Buyer concentration among Northern European retailers compresses switching cycles for ingredient suppliers. Long-term formulation contracts displace spot purchasing in dairy applications. German and British supermarket chains drive this procurement consolidation most visibly.
Europe Clean Label Ingredient Market Segmentation
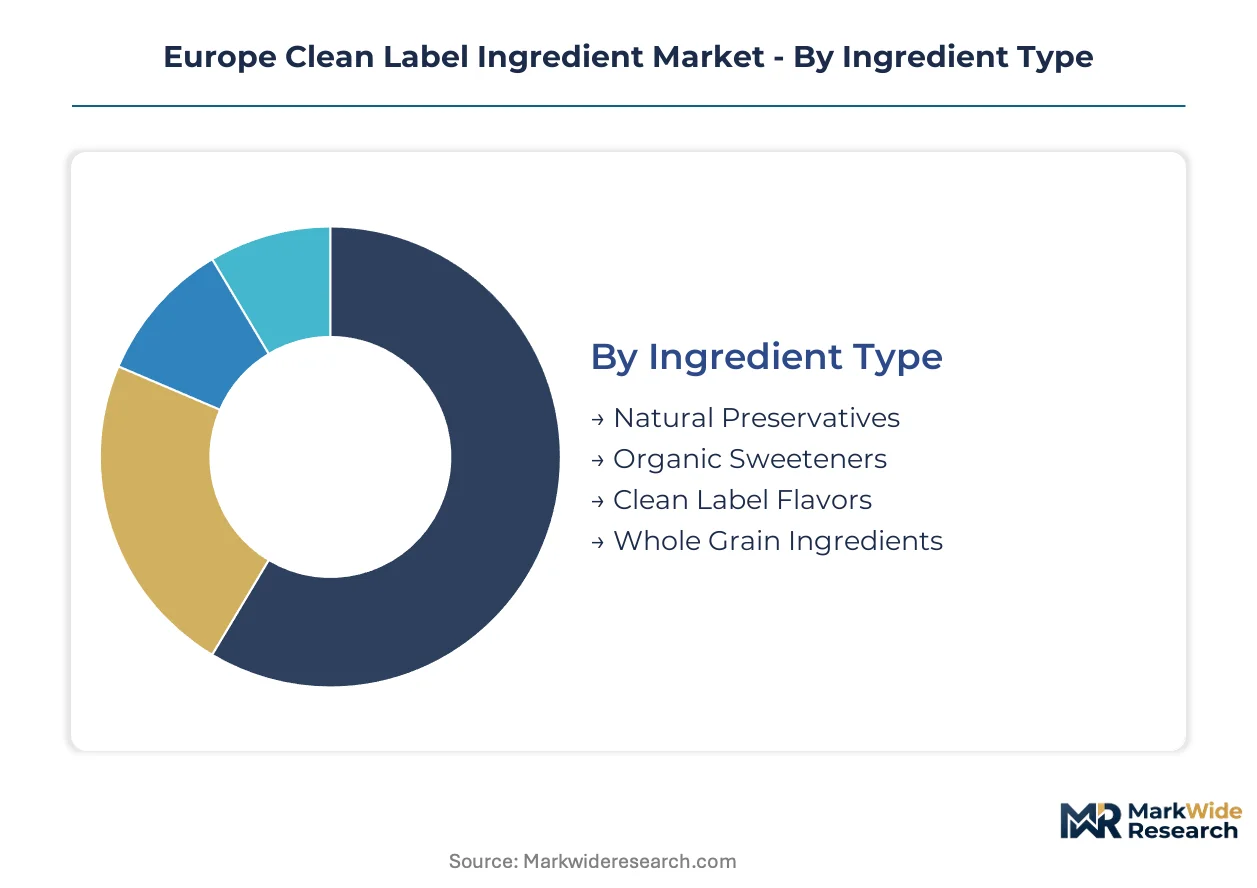
Clean label ingredient procurement across Europe varies sharply by functional requirement and end-use processing constraints. Segmentation reveals how formulation scientists balance shelf-life performance against EFSA compliance thresholds and retailer transparency mandates.
Ingredient Type:
Standardization dominates commodity categories like organic sweeteners, while natural preservatives and clean label flavors demand intensive supplier co-development and extraction protocol customization.
- Natural Preservatives:Rosemary extract, cultured dextrose, and vinegar-based systems replace synthetic sorbates and benzoates in reformulated applications. German and British dairy processors drive absolute volume as private-label programs mandate preservative-free positioning on front-of-pack labels.
- Clean Label Flavors:Botanical extracts and fermentation-derived taste modulators require sophisticated solvent recovery systems and concentrated intellectual property portfolios. Complex extraction costs elevate input pricing versus synthetic alternatives, compressing adoption among mid-sized manufacturers with constrained R&D budgets.
- Organic Sweeteners:Stevia leaf extract, monk fruit concentrate, and coconut sugar serve sugar-reduced beverage formulations across Northern Europe.
- Whole Grain Ingredients:Native starches and minimally processed flours replace modified variants in bakery and snack applications.
Leading the category by volume: Natural Preservatives. Growing fastest: Clean Label Flavors.
Application:
Volume concentration in mature categories like dairy contrasts with reformulation velocity in taxed or regulated segments.
- Dairy Products:Yogurt, cheese, and plant-based alternatives require clean label stabilizers and fermentation-derived preservation to maintain texture without carrageenan or synthetic additives. French and German retailers enforce the strictest ingredient transparency protocols, cascading requirements to reformulation teams.
- Beverages:Carbonated soft drink manufacturers accelerate clean-label transitions responding to sugar taxation and retailer standards across Northern Europe. Precision fermentation platforms enable modular supply deployment for natural colorants and flavors at pilot scale initially.
- Bakery:Clean label emulsifiers and enzyme systems replace DATEM and SSL in bread and pastry applications.
- Snack Foods:Seasoning blends and coating systems shift toward recognizable spice and herb declarations.
Dairy Products anchor absolute demand. Beverages expand most quickly as sugar taxation cascades reformulation requirements.
Form:
Processing architecture and distribution logistics determine form selection across European manufacturing networks.
- Powdered:Spray-dried extracts and dry blends optimize shelf stability and transport economics for cross-border supply chains.
- Liquid:Concentrated solutions and dispersions suit high-throughput beverage and dairy processing lines.
- Granular:Crystalline sweeteners and salt replacers meter precisely in automated bakery and snack seasoning systems.
- Whole:Intact botanicals and unprocessed grains serve premium positioning and visual authenticity cues in specialty retail.
Powdered forms dominate volume for logistics efficiency. Liquid forms gain share fastest in integrated dairy and beverage processing.
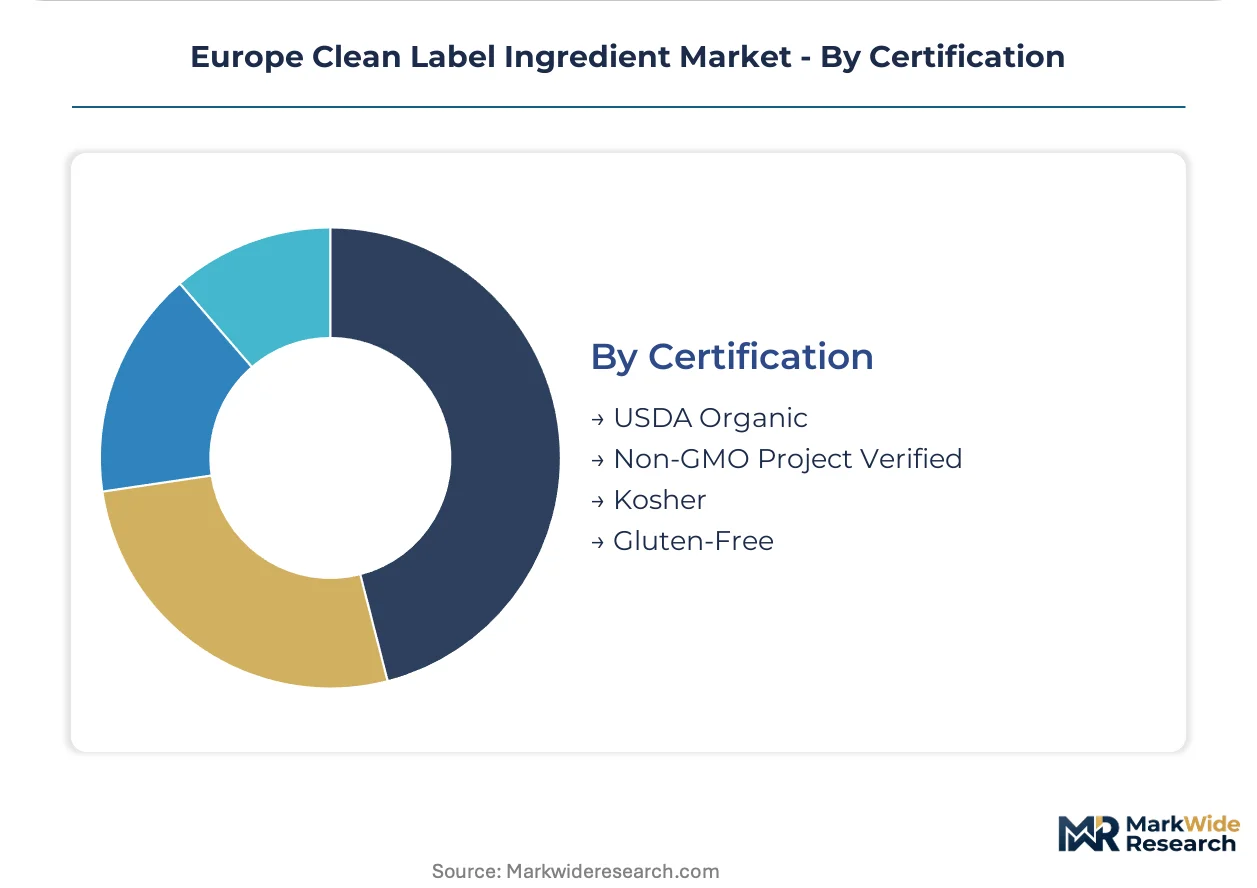
Certification:
Retailer procurement consolidation elevates multi-certification requirements above single-standard positioning.
- USDA Organic:Recognized equivalency under EU organic regulations facilitates transatlantic ingredient trade and dual-market product launches.
- Non-GMO Project Verified:Third-party testing protocols satisfy German and British supermarket chain non-GMO commitments beyond baseline EU labeling requirements.
- Kosher:Rabbinical supervision expands addressable market into specialized dietary segments and export channels.
- Gluten-Free:Analytical validation below regulatory thresholds supports celiac-safe positioning in bakery and snack reformulations.
Non-GMO Project Verified leads certification adoption by volume. USDA Organic climbs fastest as equivalency agreements streamline cross-border supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clean label ingredient demand concentrates in Germany, France, and the United Kingdom, where retailer private-label programs enforce strict ingredient transparency protocols that cascade reformulation requirements upstream to suppliers.
Germany
German supermarket chains including Aldi Süd and Rewe mandate preservative-free positioning on front-of-pack labels, driving dairy processors toward rosemary extract and cultured dextrose systems. The EU Green Deal sustainable sourcing mandates validate botanical provenance for ingredients entering German commerce. Bavaria and North Rhine-Westphalia host concentrated food manufacturing clusters where reformulation teams rebuild formulations around fermentation-derived alternatives.
France
French retailers enforce the strictest ingredient transparency protocols in Europe, particularly for yogurt and cheese applications requiring clean label stabilizers. EFSA additive re-evaluations compress approved ingredient lists for products manufactured in French facilities. The Île-de-France region anchors dairy innovation clusters where formulation scientists develop carrageenan-free texture systems for plant-based alternatives.
United Kingdom
British supermarket chains drive procurement consolidation through long-term formulation contracts that displace spot purchasing in dairy applications. Sugar taxation accelerates clean-label beverage reformulation as carbonated soft drink manufacturers respond to retailer standards and levy impacts. Greater London and the Midlands concentrate beverage manufacturing capacity where precision fermentation platforms deploy at pilot scale.
Netherlands
Dutch food manufacturers leverage Rotterdam port logistics for multi-source procurement of natural colorants and plant-derived stabilizers. REACH chemical disclosure requirements create first-mover advantage for suppliers with pre-validated solvent profiles entering Dutch supply chains. The Randstad region hosts ingredient processing architectures that separate extraction, concentration, and stabilization functions across distributed production networks.
Poland
Polish manufacturing expansion offers underpenetrated production capacity for clean-label ingredient processing with lower operational costs than Western European alternatives. CE marking alignment for novel enzymatically modified ingredients faces extended timelines, delaying entry for some fermented inputs. Warsaw and Łódź concentrate emerging food manufacturing capacity where mid-sized European producers reduce dependency on single botanical suppliers.
Europe Clean Label Ingredient Market Competitive Landscape
Strategic partnerships dominate the current landscape as ingredient suppliers align with food manufacturers facing compressed reformulation timelines. The market exhibits tiered concentration with multinational conglomerates controlling commodity categories and specialized firms occupying premium extraction segments. Three archetypes define competitive positioning: integrated taste-nutrition platforms, fermentation-derived preservation specialists, and regional grain-processing networks. M&A activity and capacity expansion in Eastern European markets represent the dominant competitive vectors reshaping supply relationships.
Within the integrated platform tier, Kerry Group PLC and Corbion NV exemplify divergent specialization strategies. Kerry Group PLC occupies a position spanning savory and dairy applications through combined taste and nutrition capabilities. Corbion NV anchors the fermentation-derived preservation segment with cultured metabolite systems targeting baked goods. Cargill represents the regional supply chain archetype, leveraging grain processing infrastructure to secure captive starch supplies for clean-label reformulations.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| Sensient Technologies Corporation |
| Cargill |
| Ingredion Incorporated |
| Corbion NV |
| Kerry Group PLC |
| Koninklijke DSM NV |
| Givaudan SA |
| Archer Daniels Midland Company |
| Others |
Supply & Pricing Matrix
Extraction solvent costs cascade through clean-label ingredient tiers from botanical harvest sites to finished goods manufacturers, compressing margins for mid-sized processors while integrated suppliers capture premium positioning through validated provenance documentation.
Pricing Analysis
Volume leaders in natural preservatives command commodity margins, while clean label flavors extract premium returns through intellectual property concentration and complex solvent recovery systems. Price differentiation hinges on EFSA compliance tier and retailer certification requirements, with German and British supermarket chains driving the strictest qualification standards. Pricing pressure intensifies in standard-grade organic sweeteners as Eastern European capacity expansion floods mid-tier supply. Small-scale dairy processors exhibit highest price sensitivity due to constrained reformulation budgets, whereas multinational beverage manufacturers absorb premium inputs to secure long-term retailer contracts.
Supply Chain Analysis
Formulation scientist scarcity in Bavaria and North Rhine-Westphalia constrains regional processing capacity expansion for fermentation-derived preservation systems. Supply concentrates in Germany, France, and the Netherlands for extraction and concentration functions, while Poland and Romania feed upstream botanical sourcing. Raw material dependencies center on rosemary cultivation in Mediterranean zones, corn starch from Cargill's European grain network, and acerola cherry concentrate from Latin American suppliers. Single-source vulnerability for natural colorants creates harvest volatility exposure. Distribution runs through Rotterdam port logistics for cross-border supply chains serving pan-European manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA additive re-evaluations are compressing approved ingredient lists and forcing sub-scale suppliers toward exit or acquisition, consolidating competitive control among integrated platforms with validated extraction documentation.
For Market Incumbents: Deploy backward integration into captive botanical sourcing to neutralize harvest volatility exposure from single-supplier dependencies. Kerry Group PLC and Corbion NV demonstrate this through controlled fermentation biomass production and regional grain processing networks. Capacity expansion in Polish extraction facilities captures Eastern European manufacturing migration while EFSA compliance investments preempt disqualification from German and French retailer procurement programs. For New Entrants and Emerging Players: Direct-to-manufacturer digital platforms bypass incumbent distributor markups in mid-sized dairy and bakery segments where formulation scientist scarcity delays reformulation timelines. Target Polish and Romanian processing capacity as the most penetrable geography, leveraging lower operational costs to undercut Western European suppliers on standard-grade natural preservatives. Precision fermentation pilot-scale deployment offers the strongest go-to-market angle for sorbate replacement systems in baked goods applications. For Investors and Strategic Acquirers: EFSA opinions on titanium dioxide and azo dye replacements are the leading indicator that R&D spending redirection toward plant-derived alternatives will accelerate acquisition premiums for extraction-technology specialists. Five-to-ten year viability favors fermentation-platform assets with modular biomass production capabilities over commodity botanical traders. Vertically integrated mid-cap specialists with validated solvent profiles and REACH documentation represent the optimal acquisition archetype.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Sourcing | Secures rosemary extract and corn starch supply chains against harvest volatility and EFSA disqualification. |
| Precision Fermentation Platform Deployment | Enables modular cultured dextrose production for dairy processors replacing synthetic sorbates. |
| REACH Chemical Disclosure Pre-Validation | Creates first-mover advantage for solvent profile documentation entering Dutch and German supply chains. |
| Eastern European Capacity Expansion | Captures Polish and Romanian manufacturing migration with lower operational cost structures. |
| Retailer Certification Co-Development | Locks long-term formulation contracts with Aldi Süd and Rewe through front-of-pack compliance. |
Research Methodology
EFSA guidance documents, EU Green Deal sustainable sourcing mandates, and REACH chemical disclosure filings formed the secondary backbone for regulatory constraint mapping. Primary interviews with formulation scientists at German dairy processors, procurement leads at French supermarket chains, extraction technology directors at Dutch ingredient suppliers, and regulatory affairs managers at fermentation-platform companies validated secondary assumptions. Trade data from Eurostat and customs records for botanical imports triangulated against bottom-up volume estimates from pan-European food manufacturers.
Bottom-up modeling aggregated segment-level demand across natural preservatives, clean label flavors, organic sweeteners, and whole grain ingredients, while top-down analysis cross-checked against EU food production statistics and retailer private-label expansion disclosures. Segmentation dimensions included ingredient type, application category, processing form, and certification tier across the projection horizon. CAGRs derived from elasticity modeling of sugar taxation impacts, EFSA re-evaluation timelines, and retailer transparency protocol adoption curves.
The model holds under continued EFSA additive compression and EU Green Deal enforcement; deviation in novel food CE marking alignment timelines or harvest failures in Mediterranean rosemary cultivation zones would shift volume projections. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
North America Food Enzymes Market
Food Additives and Ingredients
Australia Feed Additives Market
Food Additives and Ingredients
Food Grade Carrageenan Market
Food Additives and Ingredients
Alpha-Linolenic Acid Market
Food Additives and Ingredients
Fruit Ripening Agents Market
Food Additives and Ingredients
United Kingdom Anti Caking Market
Food Additives and Ingredients
Gum Hydrocolloid Market
Food Additives and Ingredients
Natural Food Preservatives Market
Food Additives and Ingredients
Blueberry Ingredient Market
Food Additives and Ingredients
Film Forming Starches Market
Food Additives and Ingredients
Cream of Tartar Market
Food Additives and Ingredients
Salt Substitutes Market
Food Additives and Ingredients
Global Lactase Market
Food Additives and Ingredients
Meat Stabilizers Blends Market
Food Additives and Ingredients
Synthetic Food Preservatives Market
Food Additives and Ingredients
North America Food Additives Market