
 Europe Malt Extract Market | 2026-2036
Europe Malt Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Malt Extract Market Analysis
CE marking for food contact materials is redrawing competitive boundaries across the Europe Malt Extract Market. Malteurop leverages its integrated malting network from France to Poland to sustain volume leadership. Boortmalt anchors supply security through backward integration into barley origination across Belgium and the Netherlands. Muntons differentiates via specialized roasted malt extracts for premium bakery applications.
Malt extract is a concentrated sweetener and fermentable substrate produced by mashing malted cereal grains, typically barley, followed by evaporation to achieve solids content ranging from 78% to 84% for syrups and below 5% moisture for dry forms; it supplies enzymatic activity, color, and flavor to food and beverage manufacturing. Liquid malt extract commands the dominant share in beer production due to brewhouse efficiency, while dry malt extract gains traction among nutraceutical companies seeking extended shelf stability and precise dosing control. The bakery sector's pull for diastatic malt powders concentrates margin pools in specialty enzyme-active formulations.
EMA food contact guidelines, EFSA novel food assessments, and the EU Green Deal's sustainability disclosure rules collectively elevate compliance costs for non-integrated suppliers while rewarding transparent sourcing. REACH chemical registration requirements further constrain additive formulations used in flavored malt syrups. Stakeholders must monitor evolving CSRD supply-chain reporting obligations and their cascading effects on barley procurement contracts.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is tightening barley sourcing requirements and forcing malt extract producers to reconfigure procurement networks across the continent. This regulatory pressure is redrawing competitive boundaries by rewarding integrated supply chains while elevating compliance costs for fragmented suppliers.
Growth Catalysts
- CE marking for food contact materials:Manufacturers achieving compliance capture premium positioning in bakery and confectionery segments where material safety documentation is mandatory for retail channel access.
- Craft brewery expansion:Small-scale brewers across Germany and France favor liquid malt extract for brewhouse efficiency, sustaining volume pull through specialized distribution channels.
- Diastatic enzyme formulations:Bakery sector demand for enzyme-active malt powders concentrates margin pools in specialty production, rewarding producers with dedicated roasting capabilities.
Market Restraints
- Barley price volatility:Weather-induced harvest fluctuations in Black Sea origination zones compress margins for non-integrated maltsters lacking captive grain supply.
- REACH chemical registration:Additive formulations in flavored malt syrups face extended toxicity evaluation timelines, delaying product line extensions by 18-24 months.
- Substitution by maltodextrin:Cost-sensitive food manufacturers in Eastern European markets pivot to enzymatically produced starch hydrolysates for neutral-flavor sweetening applications.
Strategic Opportunities
- Poland's underdeveloped craft segment:Warsaw and Krakow brewing clusters show pent-up demand for specialty roasted extracts currently supplied by German imports.
- CSRD supply-chain reporting:Early compliance creates differentiation for malt extract suppliers able to document barley farm-level carbon intensity through integrated origination networks.
- Nutraceutical dry formats:Extended shelf stability and precise dosing control position spray-dried malt extract for protein bar and meal replacement formulations.
Industry Challenges
- Malting technician scarcity:Traditional floor malting expertise concentrates in aging workforces across Bavaria and Belgium, constraining artisanal capacity expansion.
- Legacy ERP integration:Batch-level traceability requirements for EFSA novel food assessments force mid-tier producers to replace decades-old production management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Malt Extract Market |
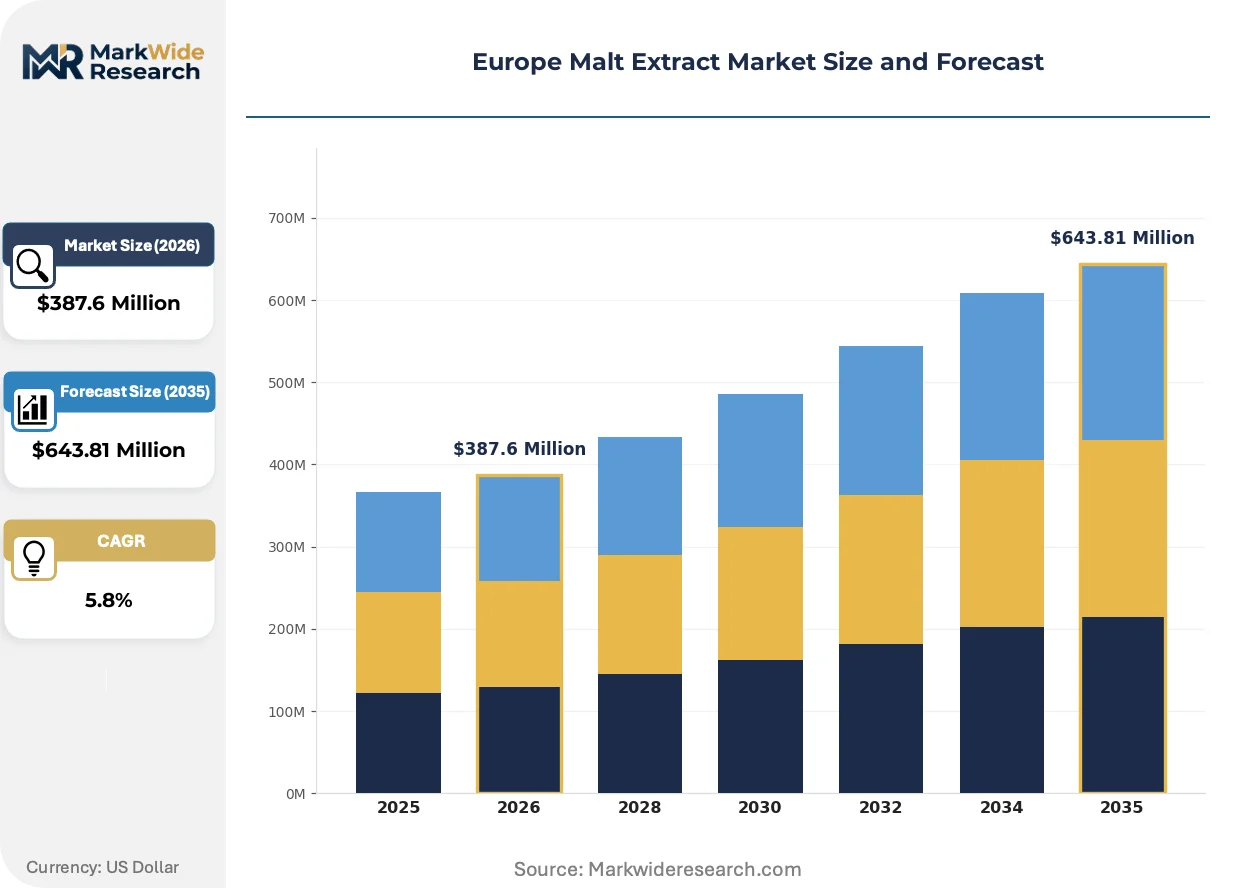
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Malt Extract, Dry Malt Extract, Powdered Malt Extract, Syrup Malt Extract End User: Beverage Industry, Bakery Sector, Confectionery Manufacturers, Nutraceutical Companies Application: Beer Production, Food Processing, Health Supplements, Flavoring Agent Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Malteurop, Boortmalt, Malteries Soufflet, Cargill, Viking Malt, Holland Malt, Muntons, IREKS GmbH, Doehler Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Malt Extract Market Emerging Trajectories
Decarbonization mandates and digital traceability tools are converging to transform how malt extract producers document provenance and optimize energy-intensive evaporation processes. These forces are compressing the technology gap between integrated multinationals and regional specialists.
Membrane filtration for pre-concentration is decomposing the traditional energy economics of malt extract production. Brewery-scale adopters in Denmark and the Netherlands are piloting ceramic microfiltration systems that reduce evaporation loads by one-third. This thermal efficiency gain is decomposing the historical advantage of large-scale central processing facilities, enabling distributed production closer to barley origination.
EMA food contact guidelines are mandating comprehensive migration testing for packaging materials in direct contact with liquid malt syrups. Manufacturers must now document specific migration limits for acrylamide and furan derivatives across temperature-stressed supply chains. German and French bakery ingredient suppliers face the steepest compliance curves, with several reformulating extract concentrations to reduce thermal processing intensity.
Buyer consolidation among European contract brewers is compressing supplier rosters and extending payment terms from 45 to 75 days. Mid-sized malt extract distributors in the Benelux region are responding by unbundling technical advisory services from product supply, shifting to fee-based formulation consulting. This service pivot is most visible in Belgium, where private-label craft beer production concentrates purchasing power among three major co-packing groups.
Europe Malt Extract Market Segmentation
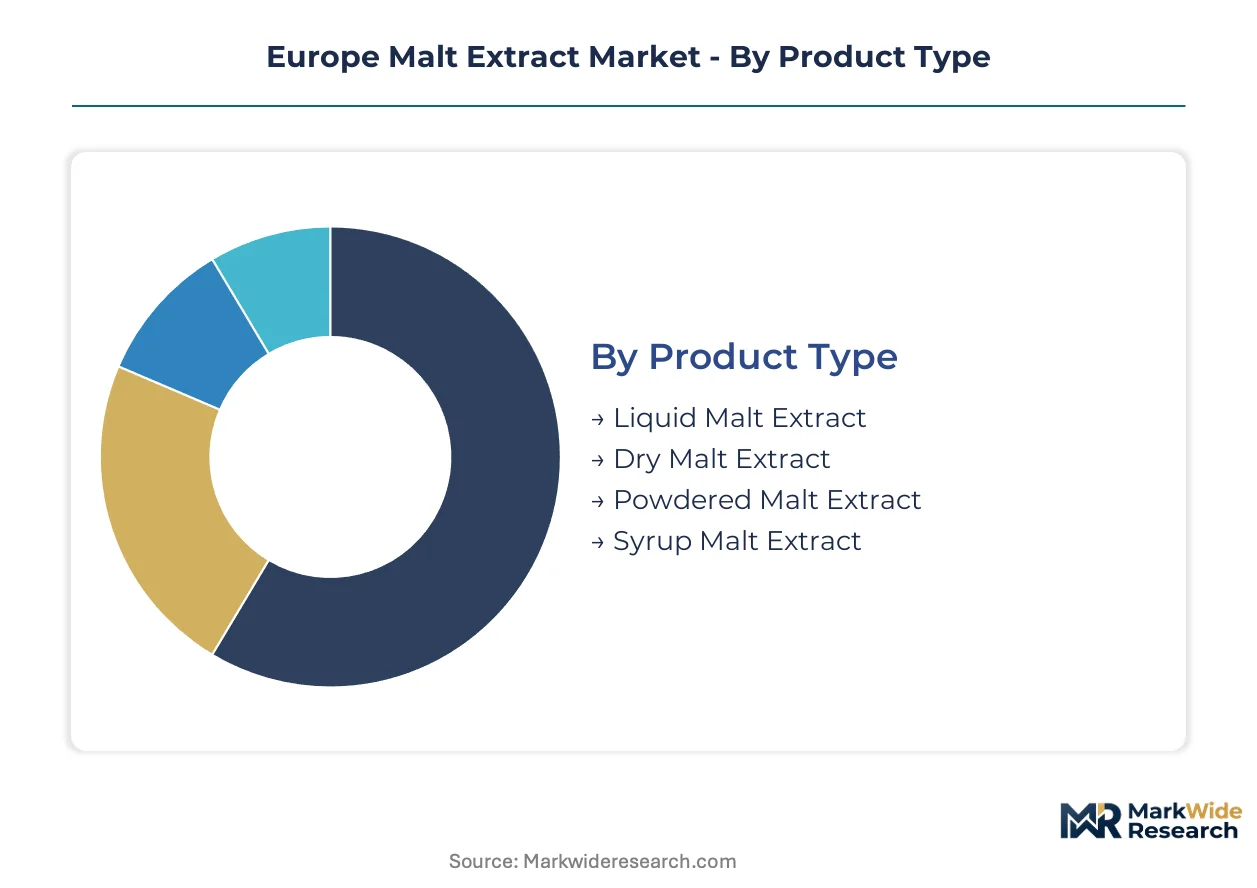
Malt extract segmentation across Europe reflects divergent substitution pressures from starch hydrolysates, synthetic sweeteners, and alternative fermentable substrates. Understanding which product formats and end-use channels face the most intense competitive displacement sharpens supplier positioning.
Product Type:
Liquid malt extract faces the most acute substitution threat from enzymatically produced maltodextrin in cost-sensitive Eastern European food manufacturing, while dry formats maintain insulation through technical performance advantages.
- Liquid Malt Extract:Concentrated syrup with 78-84% solids content serves brewhouse efficiency demands across Germany's craft brewing clusters. Bavarian microbreweries favor this format for batch consistency and reduced handling labor.
- Dry Malt Extract:Spray-dried powder below 5% moisture delivers extended shelf stability for nutraceutical applications. Protein bar manufacturers in the Netherlands and Denmark specify this format for precise dosing control in automated production lines.
- Powdered Malt Extract:Granulated variants target artisanal bakers seeking controlled enzyme activity for dough conditioning.
- Syrup Malt Extract:Viscous formulations concentrate in confectionery glazing applications where Maillard reaction control matters.
Liquid malt extract anchors the volume base while dry malt extract gains share at the steepest rate.
End User:
Margin concentration varies sharply across customer types, with beverage producers commanding scale economics and nutraceutical buyers accepting premium positioning for certification documentation.
- Beverage Industry:Beer producers across Germany, France, and Belgium drive bulk procurement through integrated malting partnerships. Craft brewery expansion in Warsaw and Krakow clusters sustains specialty extract demand.
- Bakery Sector:Diastatic malt powders concentrate margin pools in enzyme-active formulations for artisanal bread production. French and German bakery ingredient suppliers face steep EMA food contact compliance curves for migration testing.
- Confectionery Manufacturers:Caramel and glazing applications in Belgium and Switzerland specify controlled color development through roasted extract varieties.
- Nutraceutical Companies:Extended shelf stability requirements position spray-dried formats for protein bar and meal replacement formulations across Scandinavian markets.
Beverage industry procurement anchors the volume base while nutraceutical companies expand most quickly as a customer segment.
Application:
Technical specification intensity separates applications, with beer production demanding enzymatic precision and health supplements requiring novel food clearance documentation.
- Beer Production:Fermentable substrate specifications vary by brewing tradition—Bavarian lager protocols differ from Belgian abbey-style requirements. CE marking for food contact materials shapes supplier selection for brewery equipment integration.
- Food Processing:Bakery and savory applications leverage malt extract for browning control and moisture retention. REACH chemical registration constrains additive formulations in flavored syrups for this channel.
- Health Supplements:EFSA novel food assessments impose extended toxicity evaluation timelines, delaying product line extensions by 18-24 months for entrants lacking regulatory dossiers.
- Flavoring Agent:Confectionery and beverage applications specify color and taste profiles through controlled roasting parameters.
Beer production anchors the volume base while health supplements climb the fastest as regulatory pathways mature.
Distribution Channel:
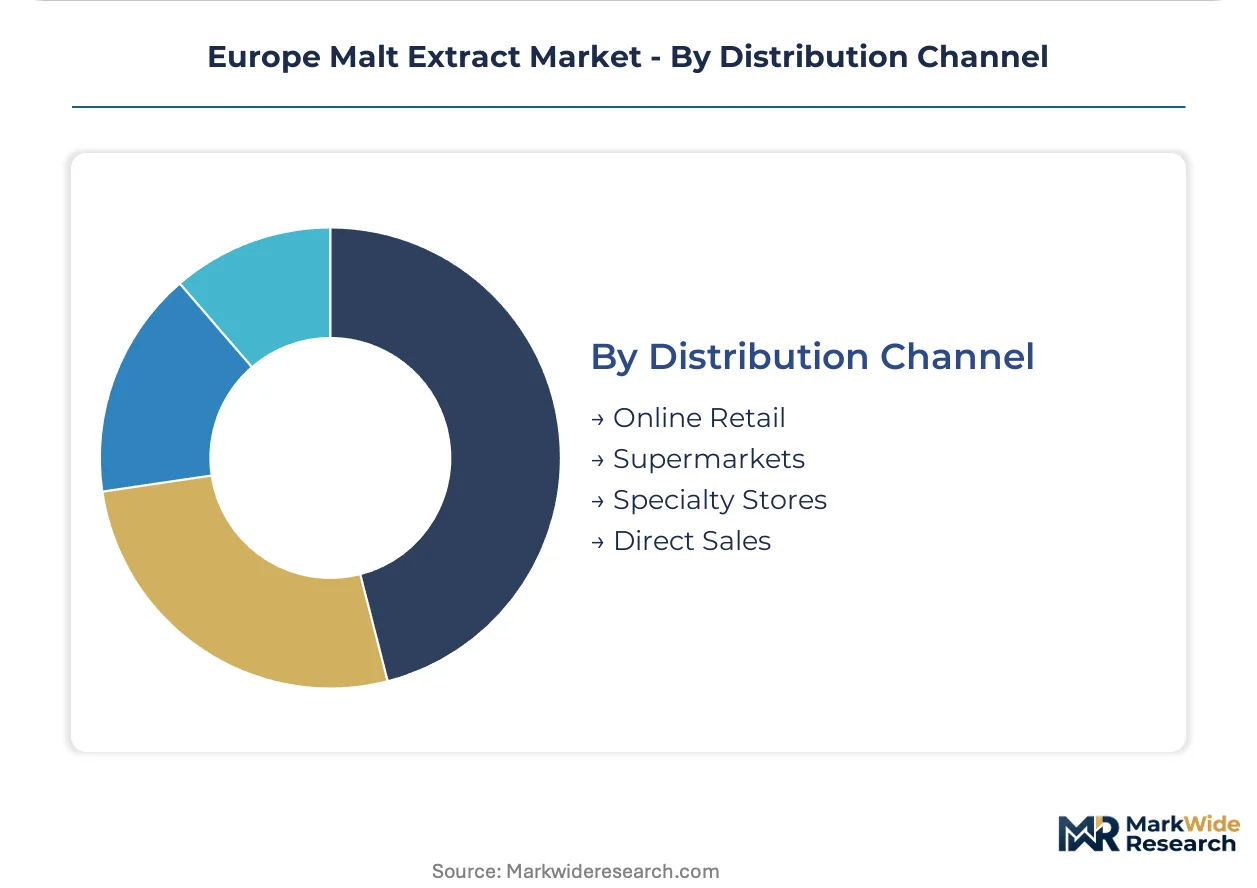
Channel economics reflect buyer consolidation pressures, with contract brewers extending payment terms and specialty stores preserving technical advisory relationships.
- Online Retail:E-commerce platforms serve small-scale craft brewers and home-baking enthusiasts with fractional packaging. German and French digital marketplaces concentrate specialty roasted extract availability.
- Supermarkets:Mass-market retail channels in the Benelux region stock standardized formats for consumer baking applications.
- Specialty Stores:Technical advisory services unbundle from product supply in Belgium, where private-label craft beer production concentrates purchasing power among three major co-packing groups.
- Direct Sales:Integrated malting networks from France to Poland sustain volume leadership through captive origination relationships with large beverage manufacturers.
Direct sales anchors the volume base while online retail gains share at the steepest rate among emerging craft segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beverage manufacturers and craft brewers concentrate procurement across four distinct national clusters, each shaped by divergent regulatory exposure and malting infrastructure maturity.
Germany
Bavarian microbreweries drive liquid malt extract consumption for brewhouse efficiency in traditional lager production. The EU Green Deal's Farm to Fork strategy tightens barley sourcing documentation requirements for maltsters operating across Munich and Nuremberg industrial corridors. Floor malting expertise concentrates in aging workforces around Bamberg, constraining artisanal capacity expansion despite craft brewery growth.
France
Specialty roasted extracts serve confectionery glazing applications in Paris and Lyon manufacturing clusters. EMA food contact guidelines mandate migration testing for acrylamide derivatives in packaging materials touching liquid malt syrups. Malting networks from Normandy to Alsace sustain volume leadership through integrated origination partnerships with large beverage manufacturers.
Belgium
Private-label craft beer production concentrates purchasing power among co-packing groups in Flanders, extending supplier payment terms from 45 to 75 days. REACH chemical registration constrains additive formulations in flavored malt syrups destined for food processing channels. Ghent and Antwerp harbor backward-integrated maltsters controlling captive barley supply from Dutch and French origination zones.
Poland
Warsaw and Krakow brewing clusters exhibit pent-up demand for specialty roasted extracts currently supplied by German imports. CSRD supply-chain reporting obligations reward early compliance by malt extract suppliers documenting farm-level carbon intensity. Poznan malting facilities expand capacity to capture craft segment growth as domestic brewing culture matures.
Netherlands
Protein bar manufacturers in Amsterdam and Rotterdam specify spray-dried malt extract for precise dosing control in automated production lines. EFSA novel food assessments impose extended toxicity evaluation timelines on health supplement applications. Ceramic microfiltration pilots in Danish-adjacent brewing networks reduce evaporation energy loads, enabling distributed production closer to barley origination.
Europe Malt Extract Market Vendor Landscape
Player mix skews toward integrated malting conglomerates with captive grain supply, creating a tiered structure where scale-driven processors coexist with specialty roasting specialists. Three strategic archetypes dominate: multinational agribusinesses with continental origination networks, regional maltsters leveraging floor malting heritage, and ingredient houses diversifying into technical advisory services. Competitive moves concentrate on backward integration into barley origination and membrane filtration technology licensing for thermal efficiency gains.
Within the integrated multinational tier, Malteurop and Boortmalt exemplify scale-driven positioning through continental malting infrastructure spanning France to Poland. Muntons occupies a specialist position representing premium roasted extract capabilities for bakery and confectionery applications. These three entities anchor competitive dynamics by demonstrating divergent pathways—continental network density versus specialty roasting differentiation—through which regional maltsters must navigate procurement reconfiguration under tightening EU sustainability disclosure rules.
| Leading Market Players |
|---|
| Malteurop |
| Boortmalt |
| Malteries Soufflet |
| Cargill |
| Viking Malt |
| Holland Malt |
| Muntons |
| IREKS GmbH |
| Doehler Group |
| Others |
Supply Flow & Price Mechanics
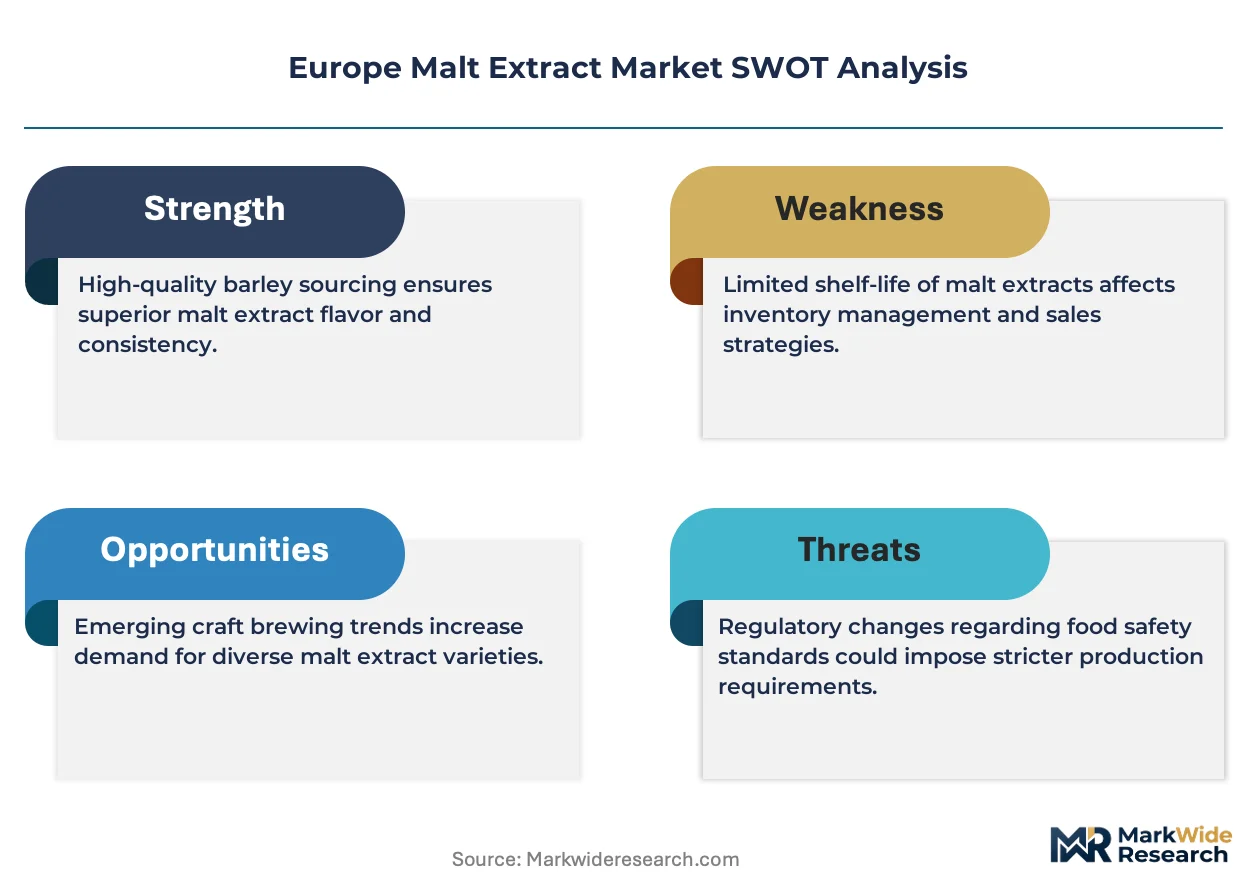
Ninety-day barley inventory cycles across Bavaria and Normandy malting clusters concentrate pricing power with integrated processors possessing captive origination networks. This lead-time compression amplifies margin pressure on non-integrated maltsters exposed to Black Sea spot markets. Buyers extending payment terms from 45 to 75 days force working-capital restructuring across mid-tier distributors.
Pricing Analysis
Cost-plus contracts indexed to Euronext barley futures dominate procurement between integrated maltsters and large beverage manufacturers. Pricing stratifies across premium, standard, and economy tiers based on enzyme activity certification and volume scale commitments. Price erosion runs through liquid malt extract formats as Eastern European food manufacturers pivot to maltodextrin substitutes. Craft brewers in Germany and France exhibit lowest price sensitivity, prioritizing batch consistency and technical advisory services over per-kilogram economics.
Supply Chain Analysis
Inventory concentration across Germany, France, and Belgium malting corridors creates single-source vulnerability for specialty roasted extract varieties. Supply chains draw from French and Polish barley origination zones, with Black Sea imports filling deficit periods. REACH chemical registration constraints and EMA food contact compliance documentation function as regulatory chokepoints. Distribution runs through direct sales relationships with integrated beverage manufacturers, supplemented by specialty stores unbundling technical consulting from product supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Malt Extract Market functions as a platform-economics inflection where CSRD supply-chain reporting interoperability creates winner-take-most dynamics for early compliance adopters.
For Market Incumbents: Shield market position through backward integration into barley origination across Poland and France, capturing farm-level carbon intensity documentation required by CSRD disclosure rules. Invest in membrane filtration licensing to decompose thermal cost advantages of centralized processing facilities. Prioritize certification investment for EFSA novel food dossiers to delay competitive entry into nutraceutical channels. For New Entrants and Emerging Players: Differentiate on carbon-intensity transparency by building farm-level traceability from inception, targeting Poland's underdeveloped craft brewing clusters in Warsaw and Krakow. White-space opportunity concentrates in specialty roasted extracts currently imported from Germany. Go-to-market angle should emphasize technical advisory services unbundled from product supply, mirroring Belgian co-packing group procurement patterns. For Investors and Strategic Acquirers: Long-term, this sits as a sustainability-premium play because EU Green Deal disclosure obligations will structurally reward integrated origination networks with documented carbon intensity. Target acquisition archetype: regional maltsters with floor malting heritage and aging workforce transition risk, where membrane filtration technology licensing can unlock distributed production economics. Signal to watch is EFSA novel food assessment pipeline velocity for spray-dried formats entering health supplement channels.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barley Origination | Captures farm-level carbon documentation required by CSRD supply-chain reporting obligations. |
| Membrane Filtration Technology Licensing | Reduces evaporation energy loads by one-third, enabling distributed production near origination zones. |
| EFSA Novel Food Dossier Investment | Creates 18-24 month regulatory moats against delayed competitive entry into nutraceutical segments. |
| Technical Advisory Service Unbundling | Responds to Belgian co-packing group procurement consolidation extending payment terms. |
| Specialty Roasted Extract Capacity Expansion | Captures pent-up demand in Poland's Warsaw and Krakow brewing clusters. |
Methodological Framework
Cross-validation between primary interviews with malting plant managers, procurement leads at beverage manufacturers, bakery ingredient technical directors, and regulatory affairs specialists anchors the qualitative findings. Secondary validation draws from EFSA novel food submission databases, EMA food contact guideline documentation, EU Green Deal Farm to Fork strategy implementation reports, and customs trade data for barley and malt extract flows. Bottom-up volume modeling triangulates against top-down market sizing across product type, end user, and application segmentation dimensions.
Sensitivity analysis frameworks test forecast robustness across barley price volatility scenarios and regulatory timeline acceleration assumptions. The analytical framework models liquid malt extract, dry malt extract, powdered malt extract, and syrup malt extract formats across beverage, bakery, confectionery, and nutraceutical end users throughout the projection horizon. CAGRs derive from segment-level volume trajectories adjusted for substitution elasticity from maltodextrin and synthetic sweeteners. Forecast inputs incorporate membrane filtration adoption curves and CSRD compliance penetration rates across integrated versus non-integrated supplier networks.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or Black Sea supply disruption scenarios would require recalibration. Forecasts reflect documented assumptions regarding craft brewery expansion velocity and EFSA assessment pipeline throughput. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
South America Fats and Oil Market
Ingredients
Middle East & Africa Prebiotic Ingredients Market
Ingredients
Fish Peptones Market
Ingredients
US Ingredients Market
Ingredients
Synephrine Market
Ingredients
Soybean Meal Market
Ingredients
Liquid Egg Market
Ingredients
Thinned Starch Market
Ingredients
Mannan-Oligosaccharide (MOS) Market
Ingredients
Asia-Pacific Lipids Market
Ingredients
Europe Alcohol Ingredients Market
Ingredients
North America Gelatin Market
Ingredients
Phytosterols Market
Ingredients
Siraitia Grosvenorii Extract Market
Ingredients
Europe Amino Acid Market
Ingredients
Omega 6 Market