
 Europe Insoluble Dietary Fibers Market | 2026-2036
Europe Insoluble Dietary Fibers Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Insoluble Dietary Fibers Market Foresight
Market Context
Premium insoluble fiber grades is shifting away from commodity cellulose on the basis of EFSA-approved health claims and organic certification requirements. Cargill, Incorporated leverages its European grain processing footprint to secure regional supply chains for food-grade cellulose. Roquette Frères sustains leadership in pea-derived fiber through dedicated extraction facilities in France and Belgium. J. Rettenmaier & Söhne GmbH & Co. KG anchors the premium tier with pharmaceutical-grade lignin and hemicellulose specialization.
Technical and Segment Structure
Europe insoluble dietary fibers comprise non-digestible carbohydrate polymers—primarily cellulose, hemicellulose, and lignin—that resist hydrolysis by human digestive enzymes and functionally add bulk, moisture retention, and texture modification in processed foods. Cellulose dominates volume throughput in industrial bakery applications across Northern Europe, while lignin extracts command margin premiums in pharmaceutical tablet binders and animal feed pelletizing agents. The nutraceutical end-user segment absorbs the fastest-growing share of hemicellulose isolates, driven by gut microbiome positioning in German and Dutch supplement markets.
Regulatory Environment and Outlook
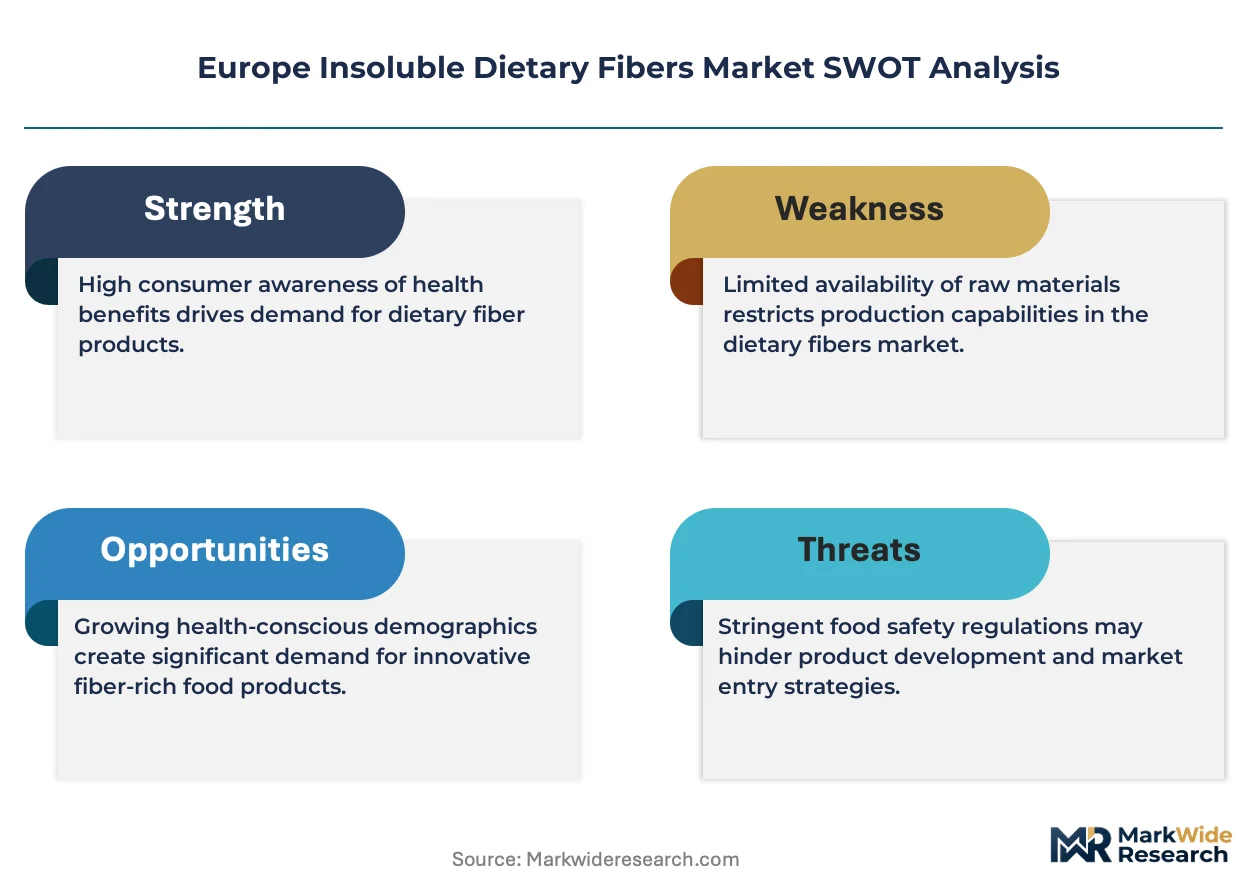
EFSA nutrition and health claims regulation, EU Green Deal sustainable sourcing mandates, and REACH chemical safety standards collectively shape product qualification pathways and market access for fiber suppliers. EMA and national food safety authorities in France and Germany enforce batch-level purity documentation that filters out uncertified imports. Stakeholders must monitor evolving EFSA opinions on novel fiber structures and pre-approval requirements for emerging hemicellulose formats.
Market Dynamics
EFSA's tightening health claims verification and the EU Green Deal's carbon border adjustments are forcing fiber suppliers to requalify supply chains and re-engineer extraction processes for cellulose and lignin variants.
Growth Catalysts
- Clean-label bakery reformulation:Industrial bakeries in Germany and France are replacing modified starches with cellulose fibers to meet EFSA-approved digestive health positioning on packaged goods.
- REACH-compliant lignin extraction:Pharmaceutical tablet manufacturers are absorbing premium lignin isolates as ECHA documentation requirements filter out non-European suppliers.
- Pea protein co-stream valorization:Roquette's Belgian extraction facilities are converting starch processing waste into hemicellulose feedstock for Dutch nutraceutical contract manufacturers.
Market Restraints
- Wood pulp input volatility:Nordic pulp mill capacity constraints and energy cost spikes in Sweden and Finland are compressing margins for cellulose fiber producers.
- EFSA novel fiber pre-approval timelines:The 18-24 month scientific opinion process for emerging hemicellulose structures delays product launches and ties up R&D capital.
- Competition from soluble fiber blends:Inulin and resistant starch formulations are capturing clean-label positioning in German dairy applications where insoluble variants previously dominated.
Strategic Opportunities
- Italian organic certification gap:Few domestic suppliers hold EU organic logos for lignin isolates, creating entry space for certified cellulose processors in Emilia-Romagna's pasta manufacturing corridor.
- Cell-based meat scaffolding:Cultivated protein startups in the Netherlands are testing hemicellulose matrices as low-cost structural alternatives to collagen.
- CSRD scope 3 reporting:The Corporate Sustainability Reporting Directive is pushing food manufacturers toward traceable European fiber sources with documented carbon footprints.
Industry Challenges
- Pharmaceutical-grade certification backlog:EMA's qualified person shortage is extending batch release timelines for lignin tablet binders by 6-8 weeks.
- Legacy bakery equipment retrofit costs:Northern European industrial bakeries face capital outlays to handle higher-fiber dough rheology without line speed degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Insoluble Dietary Fibers Market |
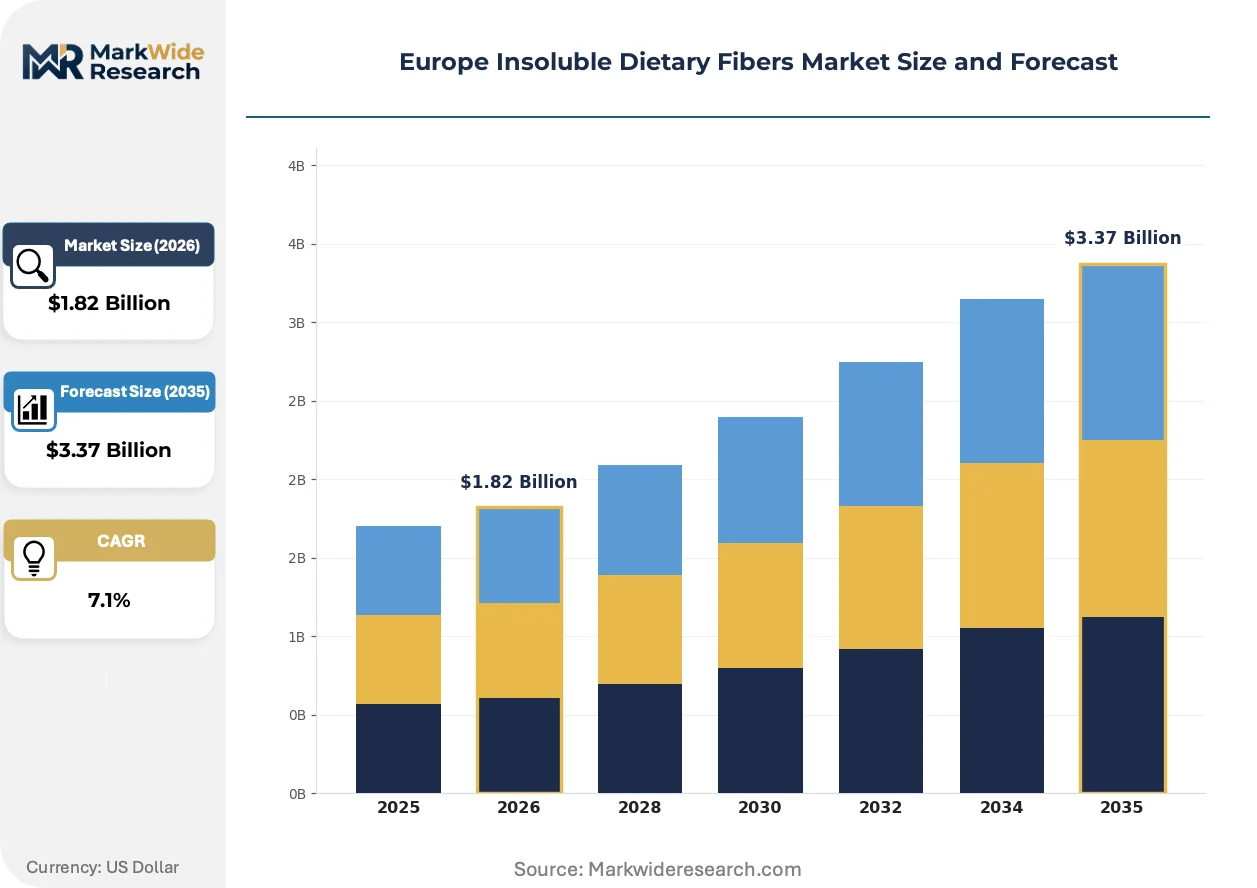
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $3.37 Billion |
| CAGR (2026 – 2036) | 7.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cellulose, Hemicellulose, Lignin, Chitin Application: Beverages, Bakery Products, Snacks, Dairy Products End User: Food Industry, Pharmaceutical Sector, Nutraceuticals, Animal Feed Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | Cargill, Incorporated, Ingredion Incorporated, SunOpta Inc., CFF GmbH & Co. KG, Grain Processing Corporation, J. Rettenmaier & Söhne GmbH & Co. KG, DuPont, InterFiber, Roquette Frères, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Insoluble Dietary Fibers Market Shifts & Advancements
Mechanical processing advances and regulatory data requirements are converging to separate premium-certified fiber grades from commodity cellulose, reshaping supplier qualification and end-user procurement criteria.
Enzymatic extraction of hemicellulose from agricultural residues is expanding into pharmaceutical-grade applications previously reserved for wood-derived lignin. Dutch supplement contract manufacturers are adopting these isolates at scale for gut microbiome positioning. The technology is expanding into margin tiers that mechanical milling cannot access, compressing price premiums for traditional lignin suppliers.
REACH registration deadlines for polymer substances are forcing cellulose processors to submit full toxicological dossiers by 2026. ECHA's substance evaluation workflow is diverting technical resources toward compliance documentation. Northern European industrial bakeries are responding by consolidating supplier lists to pre-registered vendors with existing IUCLID files.
Direct sourcing partnerships between fiber extractors and food manufacturers are displacing merchant distributor networks in Germany's Hamburg-Frankfurt corridor. Industrial bakeries and nutraceutical contract manufacturers are negotiating multi-year offtake agreements with Roquette and J. Rettenmaier & Söhne facilities. This channel consolidation is most visible in pharmaceutical-grade lignin procurement, where batch traceability requirements exceed distributor capabilities.
Europe Insoluble Dietary Fibers Market Segmentation
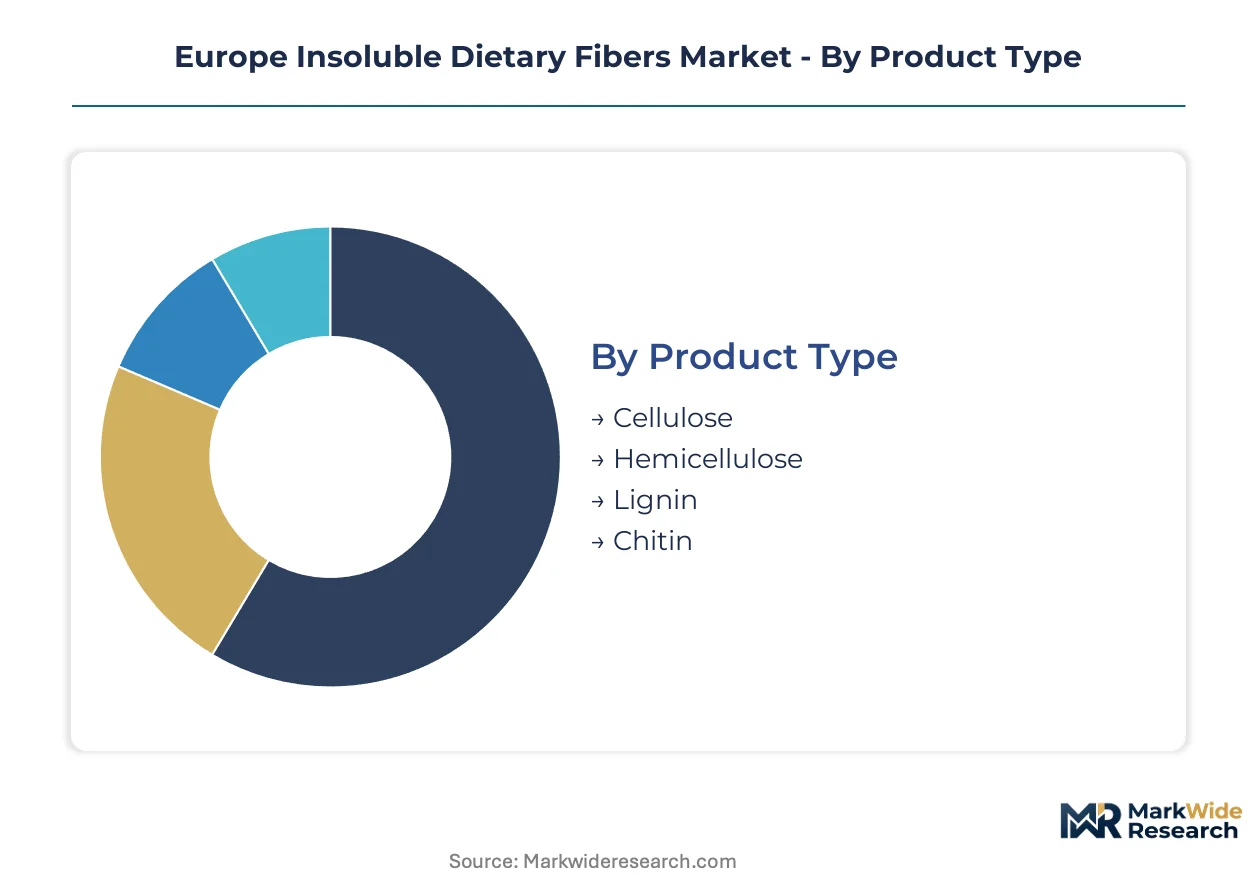
Segmentation in Europe's insoluble dietary fibers market reveals how EFSA certification tiers, extraction technology maturity, and end-use purity requirements fragment procurement strategies across food, pharmaceutical, and feed applications.
Product Type:
Standardization dominates cellulose and hemicellulose supply, while lignin and chitin require customized extraction protocols and batch-specific documentation for pharmaceutical and nutraceutical qualification.
- Cellulose:Crystalline and microcrystalline grades derived from wood pulp and agricultural residues provide bulk, moisture retention, and texture modification in industrial bakery formulations. German and French industrial bakeries around Hamburg and Frankfurt absorb the highest volumes, driven by clean-label reformulation mandates under EFSA-approved health claims frameworks.
- Hemicellulose:Branched polysaccharides extracted from pea starch co-streams and cereal husks function as prebiotic substrates in gut microbiome-positioned supplements. Dutch nutraceutical contract manufacturers in the Rotterdam-Amsterdam corridor represent the steepest demand climb, fueled by enzymatic extraction advances that reduce reliance on wood-derived inputs.
- Lignin:Phenolic polymer isolates from wood and bark serve as tablet binders in pharmaceutical applications and pelletizing agents in animal feed, requiring REACH-registered supply chains.
- Chitin:Nitrogenous polysaccharide from crustacean shells and fungal biomass supports specialized nutraceutical and cosmetic applications with limited European production scale.
Most installed capacity flows through cellulose. Expansion is steepest in hemicellulose.
Application:
Volume concentration follows industrial bakery and dairy processing infrastructure, while margin premiums cluster in beverage fortification and functional snack positioning where EFSA claim substantiation costs create barriers to entry.
- Bakery Products:Cellulose fibers replace modified starches in bread, pastry, and biscuit formulations to achieve EFSA-compliant digestive health labeling. Northern European industrial bakeries in Germany, France, and Italy's Emilia-Romagna corridor drive procurement, constrained by legacy equipment retrofit requirements for high-fiber dough handling.
- Dairy Products:Insoluble fibers add texture and satiety positioning to yogurt, cheese, and dairy alternatives. German dairy processors face competitive pressure from soluble fiber blends in clean-label applications.
- Beverages:Suspension-stable fiber grades enable fiber-fortified drinks with visible texture claims, requiring specialized micronization and hydrophobic coating technologies.
- Snacks:Extruded and puffed snack applications utilize fiber for structural integrity and reduced caloric density, with demand concentrated in private-label manufacturing for German and French retail chains.
Revenue concentration sits in bakery. Fastest share gains occur in beverages.
End User:
Food industry procurement emphasizes cost-efficient cellulose at commodity scale, while pharmaceutical and nutraceutical buyers absorb premium grades with batch-level purity documentation enforced by EMA and national competent authorities.
- Food Industry:Industrial bakeries, dairy processors, and snack manufacturers constitute the volume foundation, purchasing cellulose and hemicellulose through direct sourcing partnerships with Roquette and J. Rettenmaier facilities.
- Nutraceuticals:Dutch and German supplement contract manufacturers lead hemicellulose adoption for gut microbiome positioning, requiring organic certification and novel fiber pre-approval timelines from EFSA.
- Pharmaceutical Sector:Tablet binder and controlled-release applications for lignin isolates command the highest purity premiums, with EMA batch release timelines extending procurement cycles.
- Animal Feed:Pelletizing and digestive health applications for lignin and cellulose serve compound feed manufacturers, with sustainability documentation increasingly required under EU Green Deal supply chain mandates.
Volume leadership belongs to food industry. Margin expansion concentrates in pharmaceuticals.
Distribution Channel:
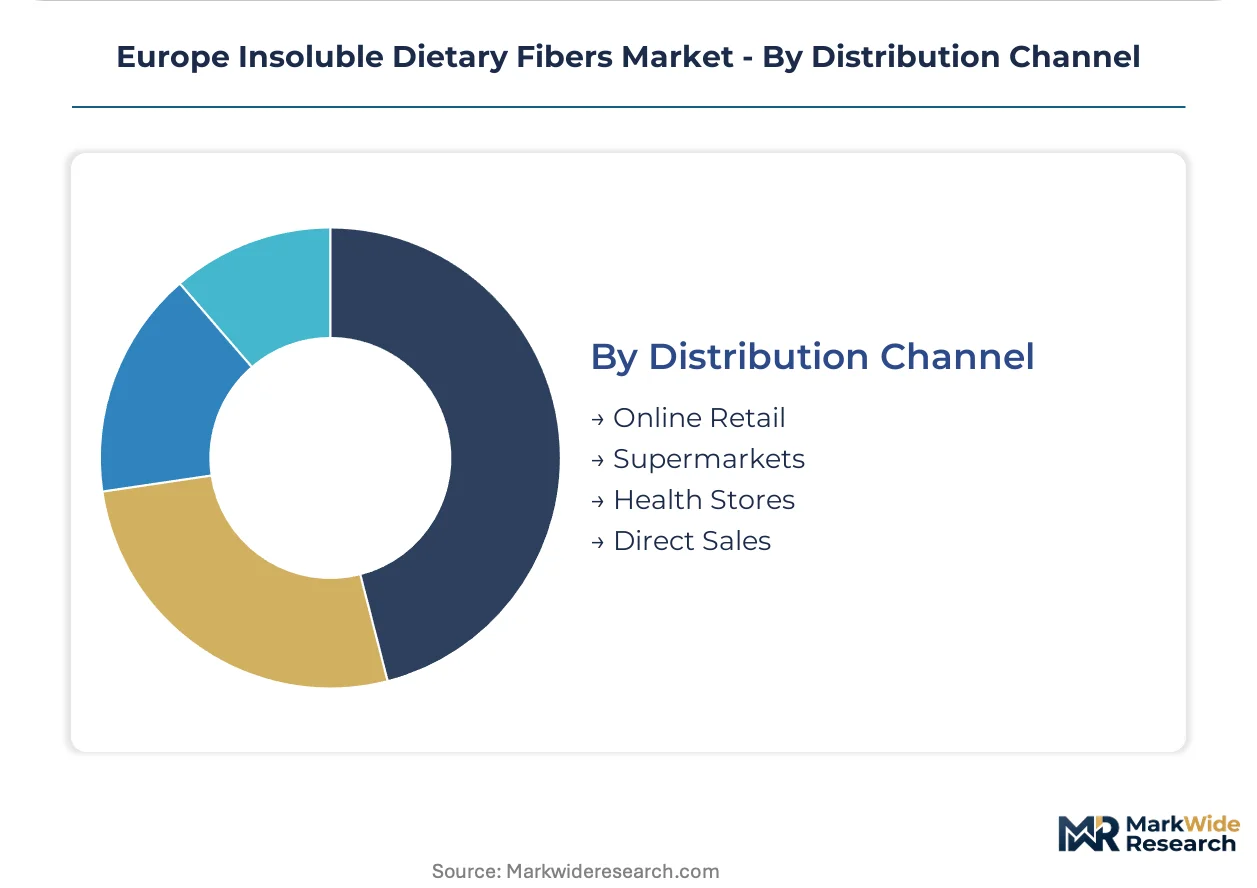
Direct sales dominate pharmaceutical-grade and large-volume food industry procurement, while health stores and online retail fragment nutraceutical and specialty ingredient access with certification-dependent qualification requirements.
- Direct Sales:Multi-year offtake agreements between fiber extractors and industrial end-users displace merchant distributors in Germany's Hamburg-Frankfurt corridor, driven by batch traceability and CSRD scope 3 reporting requirements.
- Supermarkets:Private-label fiber-fortified products channel demand through centralized retail procurement, with EFSA claim compliance filtering supplier qualification.
- Health Stores:Specialty nutraceutical and organic-certified fiber products reach consumers through dedicated retail networks, particularly in Germany and the Netherlands.
- Online Retail:Direct-to-consumer and B2B platforms serve small-scale nutraceutical manufacturers and research institutions with lower volume requirements and diverse specification needs.
Largest transaction values flow through direct sales. Channel diversification accelerates in online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food technologists and regulatory specialists cluster along the Hamburg-Frankfurt corridor and the Rotterdam-Amsterdam axis, anchoring Europe's insoluble fiber demand concentration.
Germany
Industrial bakeries in Hamburg and Frankfurt source cellulose fibers for clean-label reformulation under EFSA-approved digestive health claims. The EU Green Deal's carbon border adjustments redirect procurement toward domestic suppliers with documented scope 3 footprints. Bavaria's nutraceutical contract manufacturers absorb premium hemicellulose isolates for gut microbiome positioning.
France
Roquette Frères operates dedicated extraction facilities in Lille and Lestrem, converting pea starch co-streams into hemicellulose feedstock. REACH registration deadlines for polymer substances force processors to submit full toxicological dossiers to ECHA by 2026. The Île-de-France region hosts pharmaceutical tablet manufacturers absorbing premium lignin isolates as EMA batch release requirements filter supply chains.
Netherlands
Dutch nutraceutical contract manufacturers in the Rotterdam-Amsterdam corridor lead hemicellulose adoption for prebiotic supplement positioning. CSRD scope 3 reporting mandates push food manufacturers toward traceable European fiber sources with verified carbon footprints. Cultivated protein startups in Eindhoven test hemicellulose matrices as structural alternatives to collagen scaffolding.
Italy
Emilia-Romagna's pasta manufacturing corridor presents entry space for certified cellulose processors holding EU organic logos. Few domestic suppliers currently meet organic certification requirements for lignin isolates. Milan-based private-label manufacturers channel fiber-fortified snack demand through centralized retail procurement with EFSA claim compliance filters.
Belgium
Roquette's Belgian extraction facilities supply hemicellulose feedstock to Dutch and German nutraceutical manufacturers. The country's central logistics position supports just-in-time delivery to the Hamburg-Frankfurt industrial bakery cluster. EMA-qualified person shortages extend batch release timelines for pharmaceutical-grade fiber imports transiting through Antwerp.
Europe Insoluble Dietary Fibers Market Competitive Landscape
Top-tier vendors anchor pharmaceutical-grade certification, while commodity cellulose processors compete on volume scale and EFSA compliance speed. The vendor base stratifies across three archetypes: grain-processing conglomerates with integrated fiber extraction, specialized lignin and hemicellulose refiners with pharmaceutical-grade capabilities, and agricultural co-product valorizers converting starch processing waste. Dominant competitive moves include direct sourcing partnerships displacing distributor networks and enzymatic extraction technology licensing to access premium nutraceutical tiers.
Among German-based specialists, J. Rettenmaier & Söhne GmbH & Co. KG occupies a position exemplifying pharmaceutical-grade lignin and hemicellulose refinement. French agro-industrial conglomerate Roquette Frères represents the integrated extraction archetype through pea-derived fiber specialization. Cargill, Incorporated anchors the grain-processing tier, leveraging European milling footprints to secure regional supply chains for food-grade cellulose.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Ingredion Incorporated |
| SunOpta Inc. |
| CFF GmbH & Co. KG |
| Grain Processing Corporation |
| J. Rettenmaier & Söhne GmbH & Co. KG |
| DuPont |
| InterFiber |
| Roquette Frères |
| Others |
Supply & Pricing Matrix
Industrial bakeries and nutraceutical contract manufacturers in Germany's Hamburg-Frankfurt corridor concentrate procurement volume, anchoring a contract-based long-term offtake pricing model that rewards batch traceability and EFSA certification tiers over spot-market flexibility.
Pricing Analysis
Service bundling separates pharmaceutical-grade lignin with EMA batch documentation from unbundled commodity cellulose sold on volume contracts. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and REACH registration status. Cost compression in standard-grade cellulose is intensifying because Nordic pulp mill energy cost spikes compress producer margins. Pharmaceutical tablet manufacturers exhibit the lowest price sensitivity, while private-label snack producers in Italy's Emilia-Romagna corridor resist premium fiber grades.
Supply Chain Analysis
Direct-to-food-manufacturer channels handle industrial bakery and nutraceutical demand across Germany, France, and the Netherlands. Raw material flows draw from Swedish and Finnish wood pulp for cellulose, French and Belgian pea starch co-streams for hemicellulose, and German bark processing for lignin. Single-source vulnerability concentrates in Nordic pulp mill capacity for crystalline cellulose grades. Distribution runs through Roquette and J. Rettenmaier extraction facilities with just-in-time delivery to the Hamburg-Frankfurt corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA's evolving novel fiber pre-approval timelines compound regulatory risk into demand forecasting, with the 18-24 month scientific opinion process for emerging hemicellulose structures serving as the primary demand catalyst for established, pre-approved fiber grades.
For Market Incumbents: Anchor pharmaceutical-grade certification backlogs at EMA as a defensive moat against enzymatic extraction entrants. Prioritize backward integration into Nordic pulp supply to offset energy cost volatility. Expand dedicated extraction capacity in France and Belgium to capture Roquette-style co-stream valorization economics before agricultural processors enter fiber isolation. For New Entrants and Emerging Players: Dutch nutraceutical contract manufacturers represent the most penetrable channel partner type for enzymatic hemicellulose isolates with organic certification. Target Italy's organic certification gap in lignin isolates for pasta manufacturing corridor entry. Pursue direct sourcing partnerships with Emilia-Romagna processors as the primary go-to-market angle, bypassing established distributor networks. For Investors and Strategic Acquirers: Grain-processing conglomerates with integrated fiber extraction are the most active acquirer in this space, consolidating pea-derived and cereal co-stream capabilities. Acquisition targets should display enzymatic extraction technology and pre-submitted EFSA novel fiber dossiers. Watch EFSA publication timelines for hemicellulose structure approvals as the inflection indicator for premium tier margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nordic Pulp Supply | Roquette and J. Rettenmaier secure cellulose feedstock against Swedish and Finnish energy cost volatility. |
| Enzymatic Extraction Technology Licensing | Dutch nutraceutical contract manufacturers adopt agricultural residue hemicellulose for gut microbiome positioning. |
| EMA Pharmaceutical-Grade Certification Investment | Lignin tablet binder suppliers extend batch release timelines into defensive moats against uncertified imports. |
| Direct Sourcing Partnership Expansion | Industrial bakeries in Hamburg and Frankfurt consolidate supplier lists to pre-registered REACH vendors. |
| EU Organic Logo Acquisition | Cellulose processors penetrate Italy's pasta manufacturing corridor where domestic lignin certification is scarce. |
Research Methodology
Multiple input streams — extraction facility production data, EFSA novel fiber submission records, and REACH registration dossiers — were reconciled against primary interviews with plant managers at Roquette and J. Rettenmaier facilities, procurement leads at German industrial bakeries, regulatory affairs specialists at Dutch nutraceutical contract manufacturers, and EMA qualified persons handling batch releases. Secondary validation incorporated ECHA substance evaluation workflows, EU Green Deal supply chain documentation requirements, and customs data tracking Nordic pulp mill exports. Bottom-up capacity modeling and top-down demand estimation triangulated volume figures.
Historical capacity utilization trends were cross-referenced against panel input from fiber extraction technologists and food formulation scientists across the projection horizon. Segmentation dimensions modeled include fiber type, application category, end-user industry, and distribution channel structure. CAGRs were derived from supply-demand balance analysis incorporating EFSA pre-approval timeline assumptions and CSRD scope 3 reporting adoption curves. Forecast inputs stress-tested pulp mill energy cost scenarios and enzymatic extraction yield improvements.
Revisions become necessary when EFSA publishes adverse scientific opinions on novel fiber structures, Nordic pulp mill capacity constraints deepen, or REACH registration deadlines force processor consolidation. Forecasts reflect base-case assumptions about regulatory timeline adherence and supply chain documentation compliance. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Marine Peptides Market
Ingredients
Bean Pasta Market
Ingredients
Animal and Marine Fats and Oils Market
Ingredients
Yeast Derivatives Market
Ingredients
Food Botanicals Market
Ingredients
Middle East and Africa Fermented Ingredients Market
Ingredients
Mallow Glycolic Extract Market
Ingredients
Global Malt and Malt Extracts Market
Ingredients
China Protein Market
Ingredients
Wheat Germ Oil Market
Ingredients
Oyster Peptide Market
Ingredients
Low Fat Oil Market
Ingredients
Egg Phosphatidylcholine Market
Ingredients
Canola Oil Market
Ingredients
Spelt Flour Market
Ingredients
Ice Cream Bases Market