
 Bone and Joint Health Ingredients Market | 2026-2036
Bone and Joint Health Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Bone and Joint Health Ingredients Market Intelligence
Asset-light contract manufacturing and white-label financing is reconfiguring competitive entry barriers, allowing smaller brands to access pharmaceutical-grade production without capital-intensive facility investment. DSM-Firmenich AG leverages its integrated fermentation and biotechnology platforms to dominate glucosamine supply chains. Glanbia plc anchors its position through dairy-derived collagen peptides and sports nutrition channel control. Rousselot specializes in porcine and bovine collagen extraction, sustaining premium positioning across European and North American nutraceutical markets.
Bone and joint health ingredients comprise bioactive compounds including glucosamine sulfate, chondroitin sulfate, hydrolyzed collagen peptides, and standardized curcumin extracts formulated for connective tissue support, cartilage maintenance, and inflammatory modulation. These ingredients typically achieve functional efficacy at molecular weights below 10 kDa for collagen peptides and standardized curcuminoid concentrations of 95% in pharmaceutical-grade applications. Collagen peptides command the largest revenue pool due to cross-category penetration across beauty and sports nutrition, while curcumin formulations represent the fastest-expanding segment driven by clean-label positioning and Ayurvedic heritage marketing. Tablet and capsule formulations retain dominant pharmacy and professional channel share, though powder formats accelerate in direct-to-consumer online retail.
The FDA's New Dietary Ingredient notification requirements and cGMP enforcement shape product development timelines and compliance costs for US market participants. EFSA health claim assessments under EU Regulation 1924/2006 constrain permissible marketing language for glucosamine and collagen products across European member states. Japan's FOSHU and Foods with Function Claims systems create alternative regulatory pathways that reward clinical substantiation investments. Stakeholders must monitor evolving substantiation standards and distribution channel consolidation to determine whether clinical trial investments or geographic diversification delivers superior risk-adjusted returns.
Market Dynamics
Asset-light contract manufacturing is collapsing traditional capital barriers, enabling sports nutrition brands to launch pharmaceutical-grade collagen and glucosamine formulations without facility ownership while FDA notification timelines compress product development cycles.
Growth Catalysts
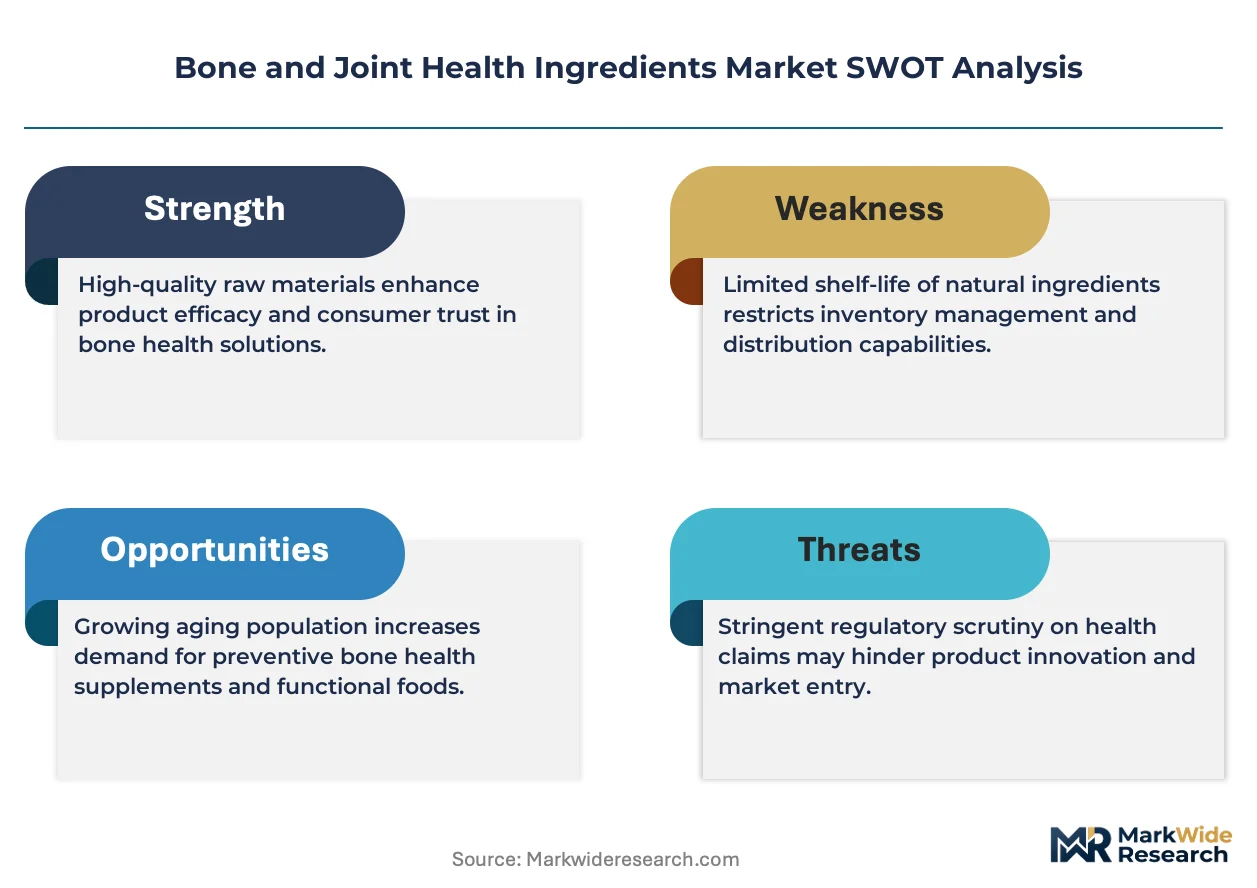
- Clean-label positioning:Standardized curcumin extracts with 95% curcuminoid concentrations command premium placement as Ayurvedic heritage marketing displaces synthetic alternatives in pharmacy channels.
- EU Regulation 1924/2006:EFSA health claim assessments create substantiation moats that reward clinical trial investments and filter marginal competitors from European markets.
- Japan's FOSHU system:Foods with Function Claims pathways accelerate functional food launches for bone and joint ingredients beyond conventional supplement formats.
Market Restraints
- Glucosamine supply concentration:Fermentation-based production clusters with biotechnology platforms create single-source vulnerability for sulfate and hydrochloride variants.
- FDA NDI notification friction:New Dietary Ingredient requirements extend formulation timelines by 12-18 months and escalate compliance costs for novel molecular structures.
- Chondroitin substitution pressure:Marine-derived alternatives and synthetic hyaluronic acid complexes erode bovine and porcine sourcing dominance in cartilage maintenance applications.
Strategic Opportunities
- Direct-to-consumer powder formats:Online retail channels bypass pharmacy gatekeepers and capture subscription revenue from fitness-oriented demographics seeking collagen peptides.
- Beauty-nutrition convergence:Cross-category positioning of hydrolyzed collagen below 10 kDa molecular weight penetrates skincare-adjacent markets with shared connective tissue claims.
- India's FSSAI functional food expansion:Regulatory clarity on nutraceutical classification opens formulation partnerships for Ayurvedic ingredient suppliers targeting domestic and export markets.
Industry Challenges
- cGMP certification bottlenecks:Pharmaceutical-grade manufacturing audits create facility backlogs that delay market entry for emerging brands without established quality systems.
- Clinical substantiation capacity:Randomized controlled trial design and biomarker validation expertise concentrates with contract research organizations, inflating study costs for mid-tier ingredient suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bone and Joint Health Ingredients Market |
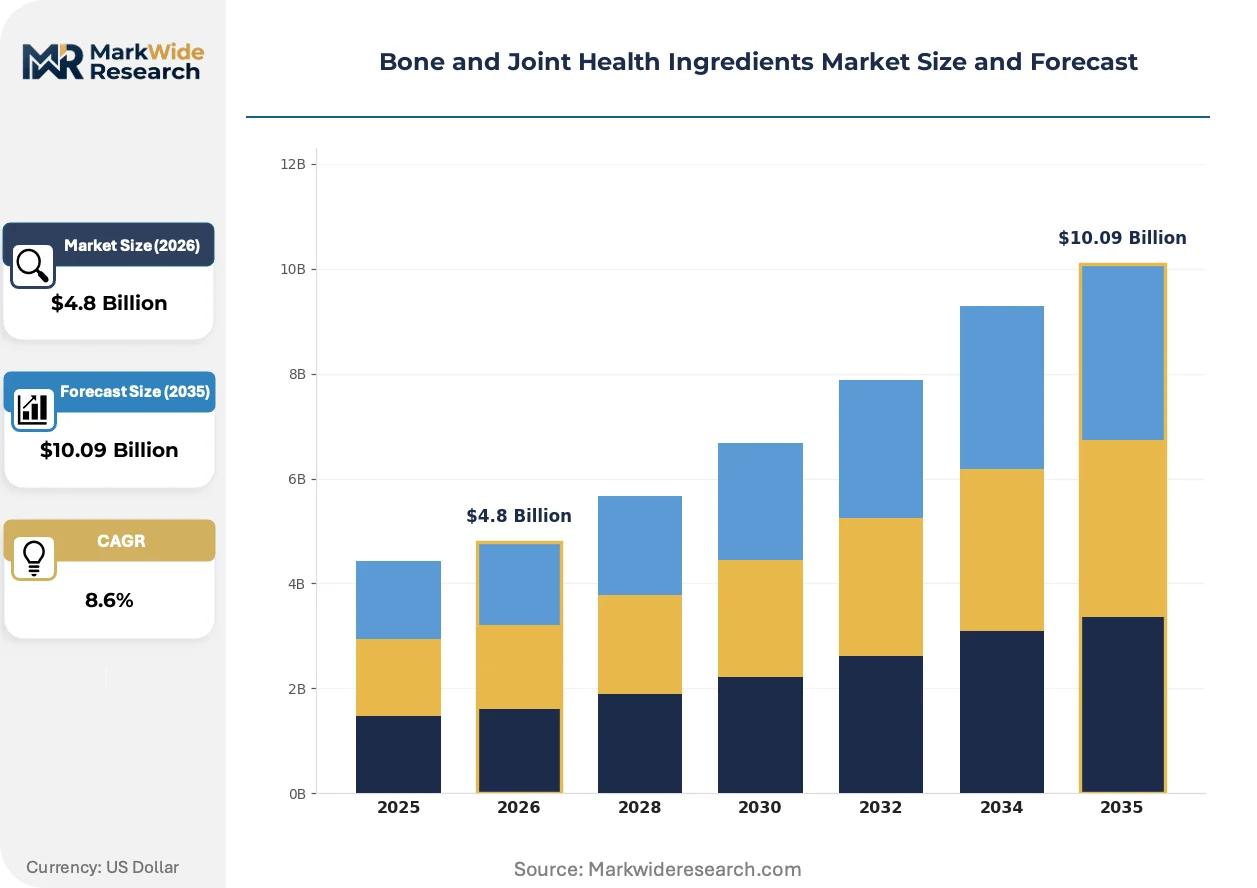
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.09 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glucosamine, Chondroitin, Collagen, Curcumin Formulation: Tablets, Powder, Liquid, Capsules End User: Adults, Seniors, Athletes, Pets Distribution Channel: Online Retail, Pharmacies, Supermarkets, Health Stores |
| Companies Covered | BASF SE, DSM-Firmenich AG, Archer-Daniels-Midland Company, Glanbia plc, Cargill, Incorporated, Rousselot, Nestle Health Science, Abbott Laboratories, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bone and Joint Health Ingredients Market Strategic Shifts & Innovations
Biotechnology platforms and regulatory data science are compressing traditional development cycles while reshaping how bone and joint ingredients achieve market authorization and consumer trust.
Precision fermentation is virtualizing conventional extraction supply chains for glucosamine and chondroitin precursors. Biotechnology firms now cultivate microbial strains that biosynthesize amino sugar backbones without shellfish or bovine raw material dependency. Sports nutrition formulators in Germany and the Netherlands are accelerating adoption as price parity with marine-sourced material approaches within 24 months.
EFSA's evolving health claim substantiation database is tightening evidentiary standards for collagen peptide and glucosamine products across European markets. The 1924/2006 regulation now demands human intervention studies with validated joint function endpoints, disqualifying traditional in-vitro cartilage models. Premium-positioned brands are responding by commissioning proprietary clinical trials while economy-tier suppliers retreat to generic wellness positioning.
Subscription-based replenishment models are displacing pharmacy-driven repurchase cycles for bone and joint supplements. Direct-to-consumer platforms now capture 60-day and 90-day commitment purchases through automated powder and capsule deliveries, compressing customer acquisition costs relative to retail slotting fees. This channel migration concentrates in United States metropolitan markets where fitness culture and aging demographics overlap most densely.
Bone and Joint Health Ingredients Market Segmentation
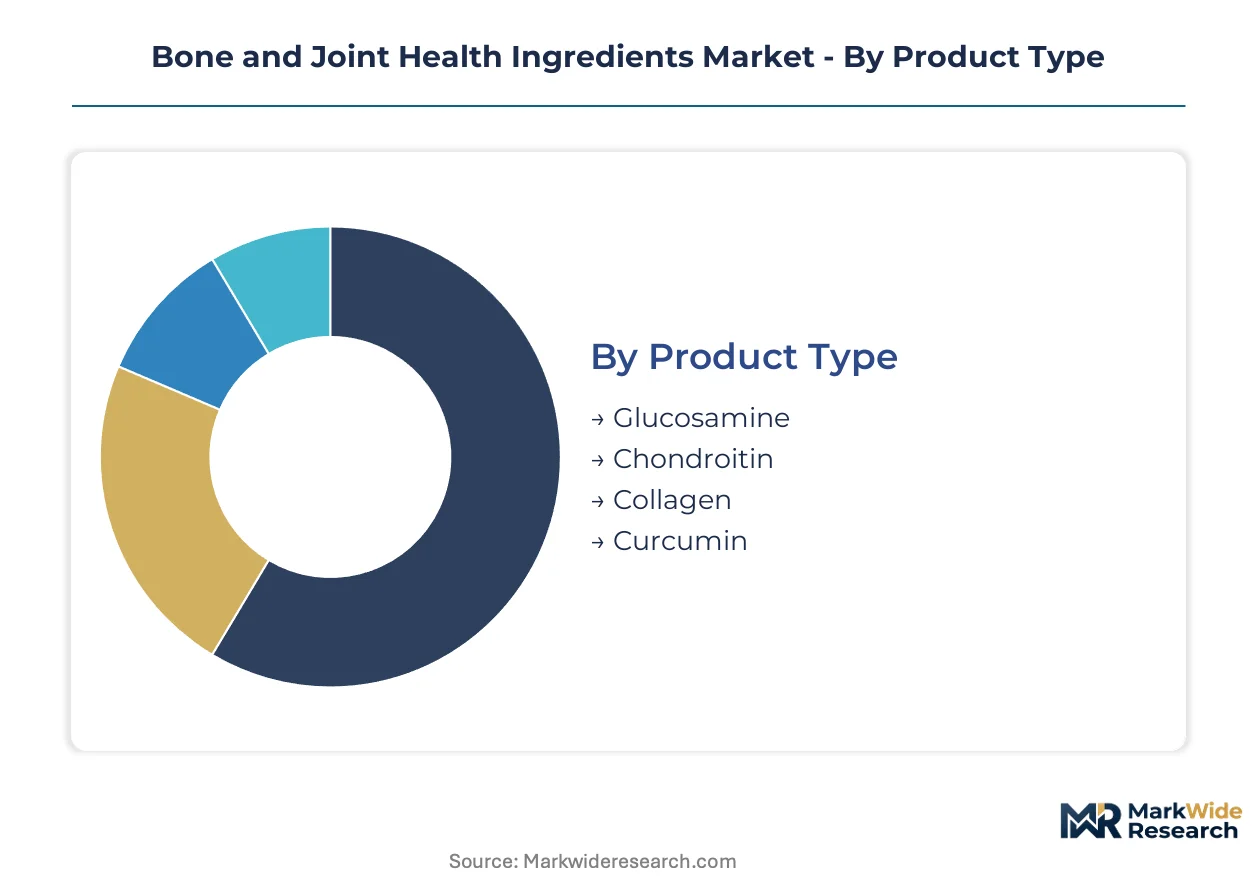
Bone and joint health ingredients fragment across four dimensions that determine formulation strategy, regulatory pathway, and margin capture. Product chemistry dictates manufacturing investment and clinical substantiation burden. Delivery format and channel selection shape customer acquisition economics across aging populations and fitness cohorts.
Product Type:
Mature commodity molecules coexist with emerging biotechnology-derived alternatives, creating tiered competitive dynamics.
- Glucosamine:Fermentation-based amino sugar production dominates sulfate and hydrochloride variants. Supply concentrates with biotechnology platforms in the Netherlands and China, where shellfish extraction faces allergen labeling constraints.
- Chondroitin:Bovine and porcine cartilage extraction retains pharmacy channel dominance despite marine-derived substitution pressure. EFSA health claim rejections under EU Regulation 1924/2006 constrain European marketing claims.
- Collagen:Hydrolyzed peptides below 10 kDa molecular weight penetrate beauty-nutrition convergence markets.
- Curcumin:Standardized 95% curcuminoid extracts displace synthetic alternatives through Ayurvedic heritage positioning.
Collagen retains volume leadership; curcumin holds the steepest expansion curve.
Formulation:
Cost tier stratification separates pharmaceutical-grade production from commodity powder blending.
- Tablets:Compressed dosage forms achieve pharmacy shelf placement through cGMP-certified manufacturing. FDA cGMP enforcement and USP dissolution standards create quality moats that filter economy-tier competitors.
- Powder:Direct-to-consumer online retail channels bypass pharmacy gatekeepers. Subscription-based replenishment models capture 60-day and 90-day commitments from fitness-oriented demographics in United States metropolitan markets.
- Liquid:Ready-to-drink formats target senior compliance and pet supplement applications.
- Capsules:Gelatin and vegetarian shell variants dominate professional channel distribution.
Tablets retain volume leadership; powder holds the steepest expansion curve.
End User:
Application intensity varies sharply across demographic segments with divergent price elasticity and clinical evidence requirements.
- Adults:Preventive consumption patterns concentrate in United States urban markets where fitness culture sustains collagen peptide demand. Sports nutrition brands drive procurement for cross-category wellness positioning.
- Seniors:Osteoarthritis symptom management generates pharmacy channel volume with reimbursement dependency. EFSA health claim substantiation demands under EU Regulation 1924/2006 filter marginal competitors from European markets.
- Athletes:Connective tissue repair claims require clinical trial investments for anti-doping certification.
- Pets:Veterinary channel expansion targets companion animal osteoarthritis with palatability-formulated products.
Seniors retain volume leadership; athletes hold the steepest expansion curve.
Distribution Channel:
Customer type concentration determines channel economics and regulatory exposure.
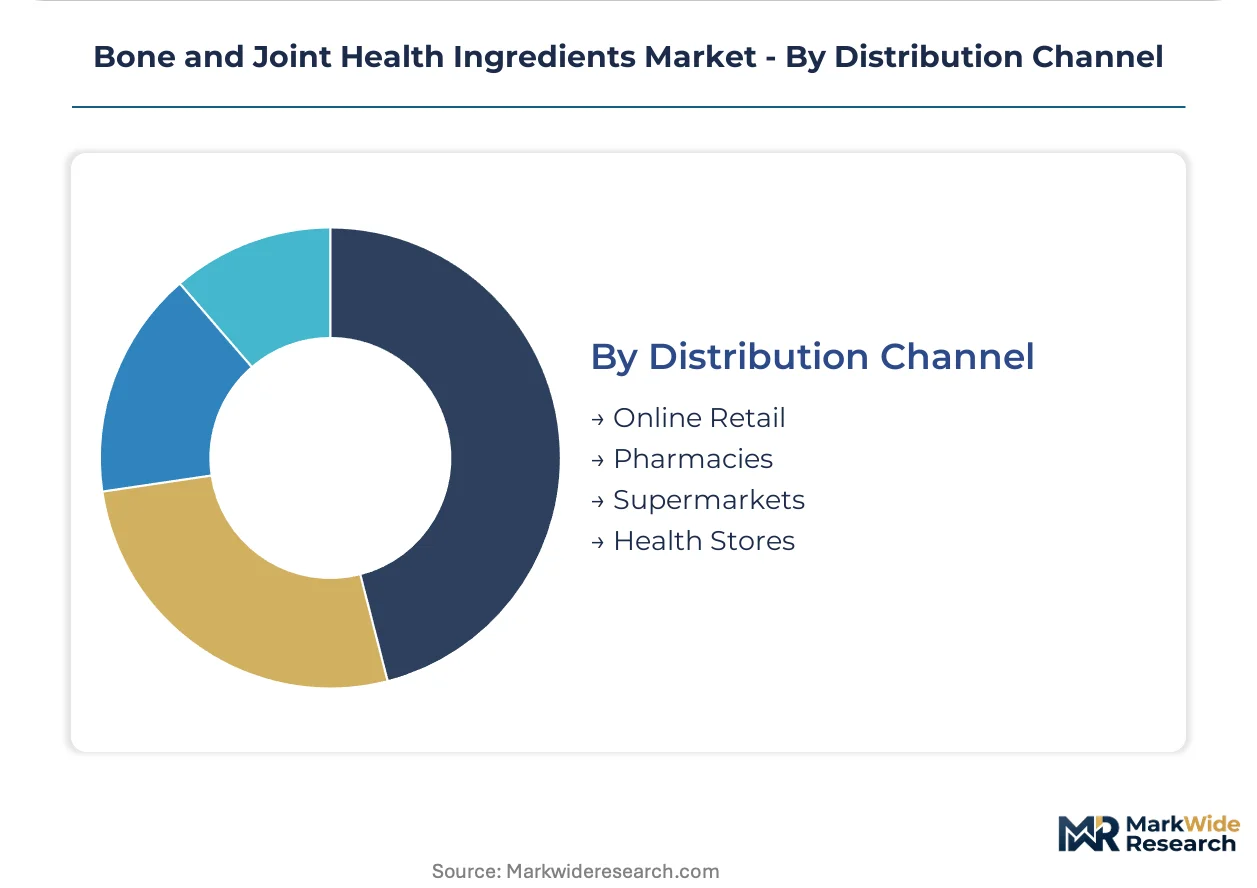
- Online Retail:Direct-to-consumer platforms compress customer acquisition costs relative to retail slotting fees. Subscription models capture recurring revenue from United States fitness demographics seeking collagen peptides and glucosamine complexes.
- Pharmacies:Professional recommendation dependency sustains glucosamine and chondroitin volume despite EFSA health claim constraints. Pharmacist counseling requirements under EU member state regulations create gatekeeper friction.
- Supermarkets:Mass-market placement targets price-sensitive preventive consumption.
- Health Stores:Specialty retail channels reward clean-label positioning and Ayurvedic heritage marketing.
Pharmacies retain volume leadership; online retail holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from Dutch and Chinese biotechnology platforms supply fermentation-derived glucosamine to United States and German formulators, while collagen peptide trade routes connect Brazilian bovine processors to European nutraceutical manufacturers seeking pharmaceutical-grade raw material.
United States
Fitness culture in metropolitan markets sustains dual demand from aging populations and sports nutrition consumers seeking collagen peptides. FDA New Dietary Ingredient notification requirements extend formulation timelines for novel molecular structures. Greater Boston and San Diego biotech clusters host contract research organizations validating joint function biomarkers for substantiation packages.
Germany
EFSA health claim assessments under EU Regulation 1924/2006 filter marginal competitors from European pharmacy channels. Precision fermentation startups in the Netherlands supply biosynthetic glucosamine precursors to German formulators at approaching price parity. The Cologne-Düsseldorf corridor concentrates white-label manufacturing capacity serving direct-to-consumer brands.
China
Shellfish extraction for glucosamine sulfate faces allergen labeling constraints that accelerate fermentation-based substitution. SAMR's evolving nutraceutical classification creates compliance uncertainty for imported collagen peptides. Zhejiang and Shandong provinces host extraction facilities supplying bovine-derived chondroitin to North American veterinary channels.
Japan
FOSHU and Foods with Function Claims systems reward clinical substantiation investments with accelerated functional food market entry. METI guidelines shape collagen peptide quality standards for beauty-nutrition convergence products. The Kansai region's Osaka-Kobe industrial zone concentrates fermentation capacity for amino sugar production.
India
FSSAI regulatory clarity on nutraceutical classification opens formulation partnerships for Ayurvedic curcumin suppliers targeting domestic and export markets. Standardized 95% curcuminoid extracts displace synthetic alternatives through heritage positioning. Maharashtra and Gujarat host extraction clusters serving European pharmacy demand for clean-label botanicals.
Bone and Joint Health Ingredients Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying pharmaceutical-grade inputs to asset-light brands. The vendor base stratifies across biotechnology platforms, dairy-derived protein processors, and animal extraction specialists. Three archetypes dominate: integrated fermentation platforms, collagen peptide specialists with cross-category reach, and contract manufacturers enabling brand entry without facility ownership. Competitive moves concentrate on capacity expansion in precision fermentation and strategic partnerships securing pharmaceutical-grade certification.
Within the integrated biotechnology tier, DSM-Firmenich AG and BASF SE represent platform consolidation spanning amino sugar fermentation and nutritional ingredient synthesis. Glanbia plc exemplifies dairy-derived positioning, anchoring supply relationships through sports nutrition channel control. These three entities occupy positions that determine raw material availability and pricing benchmarks for downstream formulators seeking cGMP-certified inputs.
| Leading Market Players |
|---|
| BASF SE |
| DSM-Firmenich AG |
| Archer-Daniels-Midland Company |
| Glanbia plc |
| Cargill, Incorporated |
| Rousselot |
| Nestle Health Science |
| Abbott Laboratories |
| DuPont |
| Others |
Cost & Logistics Intelligence
Single-source fermentation capacity in Dutch biotechnology platforms determines both pharmaceutical-grade pricing spreads and raw material procurement patterns across glucosamine sulfate supply chains. FDA cGMP certification bottlenecks compress margins for emerging brands while concentrating pricing power with integrated manufacturers possessing validated quality systems.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in bone and joint ingredient procurement. Pharmaceutical-grade collagen peptides with molecular weights below 10 kDa command certification premiums, while commodity-grade glucosamine sulfate faces cost compression from fermentation scale economies. Price differentiation hinges on cGMP compliance tier and clinical substantiation depth. Fitness-oriented direct-to-consumer brands exhibit lowest price sensitivity due to subscription model lock-in, whereas mass-market supermarket buyers drive aggressive spot-market negotiation.
Supply Chain Analysis
Contract manufacturing concentration with Lonza and Catalent pharmaceutical-grade facilities shapes downstream formulation access for asset-light sports nutrition brands. Raw material extraction clusters in the Netherlands, China, and Brazil supply fermentation-derived glucosamine precursors and bovine collagen peptides to North American and European formulators. Shellfish allergen labeling constraints and marine-derived substitution pressure create raw material transition risks. Distribution runs through direct-to-consumer subscription platforms bypassing traditional pharmacy gatekeepers in United States metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Validated clinical trial capacity represents the binding constraint separating premium-positioned ingredient suppliers from commodity competitors, with biomarker validation expertise concentrating among contract research organizations in Greater Boston and San Diego.
For Market Incumbents: Pre-empt precision fermentation adoption by securing exclusive supply partnerships with Dutch biotechnology platforms before biosynthetic glucosamine achieves price parity with marine extraction. Expand cGMP-certified capacity in the Cologne-Düsseldorf corridor to capture white-label demand from direct-to-consumer brands seeking pharmaceutical-grade collagen peptide formulations. Defend against marine-derived chondroitin substitution by investing in proprietary clinical substantiation packages that satisfy EFSA health claim requirements under EU Regulation 1924/2006. For New Entrants and Emerging Players: Pursue India's FSSAI-regulated functional food segment where Ayurvedic curcumin heritage positioning remains underexploited by established European suppliers. Target subscription-based powder formats in United States fitness demographics where customer acquisition costs trail retail slotting fees. Leverage asset-light contract manufacturing partnerships to bypass capital-intensive fermentation facility investment while accessing pharmaceutical-grade production standards. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform integrators with captive biotechnology fermentation capacity and cross-category collagen peptide distribution. Long-term viability accrues to suppliers combining clinical substantiation investments with direct-to-consumer channel control. Acquisition candidates should demonstrate validated joint function biomarker studies and cGMP certification without single-source raw material dependency. Monitor FDA NDI notification backlog resolution as inflection signal for novel molecular structure market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Substantiation Investment | EFSA health claim approvals under EU Regulation 1924/2006 filter marginal competitors from European pharmacy channels. |
| Precision Fermentation Scale-Up | Dutch biotechnology platforms approach price parity with shellfish extraction for glucosamine sulfate production. |
| Direct-to-Consumer Channel Expansion | Subscription replenishment models capture 60-day and 90-day commitments from United States fitness demographics. |
| cGMP Certification Acquisition | Pharmaceutical-grade manufacturing audits create facility backlogs that delay market entry for emerging brands. |
| Beauty-Nutrition Cross-Category Positioning | Hydrolyzed collagen below 10 kDa molecular weight penetrates skincare-adjacent markets with shared connective tissue claims. |
Research Approach
Cross-validation between primary interviews with ingredient procurement directors, sports nutrition brand managers, regulatory affairs specialists, and contract research organization executives anchors the qualitative findings in operational reality. Secondary validation draws from FDA New Dietary Ingredient notification databases, EFSA health claim assessment registers, FSSAI nutraceutical classification circulars, and SAMR import compliance bulletins. Bottom-up demand modeling triangulates against top-down supply capacity estimates from fermentation platform disclosures and extraction facility regulatory filings.
Calibration against historical price spreads between pharmaceutical-grade and commodity-tier collagen peptides refines volume projections across the analysis window. Segmentation dimensions include product chemistry tier, delivery format, end-user demographic, and distribution channel concentration. CAGRs derive from trend extrapolation of fermentation capacity expansion timelines, regulatory approval velocity, and channel migration patterns from pharmacy to direct-to-consumer platforms. Forecast inputs incorporate precision fermentation adoption curves and EFSA substantiation success rates for joint function claims.
Sensitivities concentrate around FDA NDI notification timeline extensions, EFSA health claim rejection cascades, and shellfish allergen labeling regulation tightening. Forecasts embed assumptions regarding biotechnology platform scale-up success and direct-to-consumer subscription retention rates. Quarterly review of FDA cGMP inspection backlogs, EFSA opinion publication queues, and fermentation capacity utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Hydrolyzed Starch Market
Ingredients
China Protein Market
Ingredients
RTD/High Strength Premixes Market
Ingredients
Omega 3 Ingredients Market
Ingredients
Jojoba Oil Market
Ingredients
Soy and Milk Protein Ingredients Market
Ingredients
Hydroxytyrosol Market
Ingredients
Specialty Fats and Oils Market
Ingredients
Plant Based Premix Market
Ingredients
Edible Animal Fat Market
Ingredients
China Corn Glucose Market
Ingredients
Mung Bean Protein Market
Ingredients
Desiccated Coconut Market
Ingredients
Soy Derivatives Market
Ingredients
Hydrolyzed Animal Protein Market
Ingredients
Horny Goat Weed Extract Market