
 Sodium Reduction Ingredients Market | 2026-2036
Sodium Reduction Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Reduction Ingredients Market Intelligence
The FDA voluntary sodium reduction targets for processed foods is consolidating procurement priorities across North American food manufacturers. Cargill Incorporated leverages its salt substitute portfolio and agricultural supply chain integration to sustain bulk supply contracts with national processors. Kerry Group Plc differentiates through flavor enhancement systems that mask sodium reduction in savory applications. DSM-Firmenich anchors its position with yeast extract technologies that deliver umami depth without sodium chloride.
Sodium reduction ingredients comprise functional additives and reformulation aids designed to replicate or enhance salty taste perception while lowering sodium chloride content, typically incorporating potassium chloride, amino acids, or nucleotide-based flavor modulators at specific replacement ratios. These ingredients serve primary commercial purposes in processed food manufacturing where sodium performs preservative, textural, and flavor functions beyond basic seasoning. Yeast extracts command structural importance due to their clean-label positioning and broad regulatory acceptance across savory applications. Salt substitutes represent the volume foundation of the market, though potassium chloride variants face formulation challenges related to metallic aftertaste and regulatory limits on potassium fortification. Flavor enhancers are capturing accelerated development investment as manufacturers seek multi-modal taste solutions beyond simple sodium replacement.
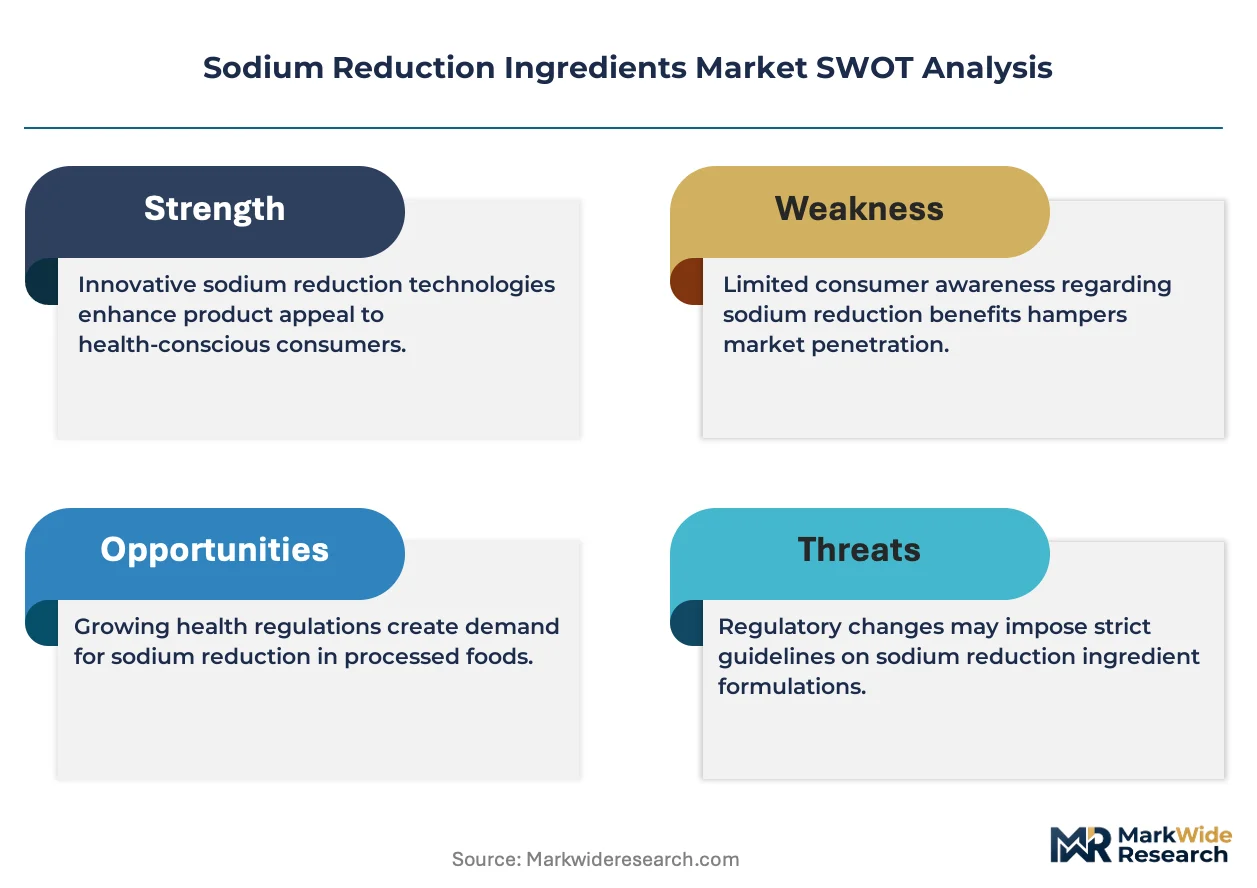
WHO sodium intake guidelines, FDA voluntary reduction targets, and EU front-of-pack Nutri-Score labeling collectively reshape product development timelines and reformulation budgets across major food manufacturing jurisdictions. Compliance with these frameworks demands documented sodium reduction pathways and validated sensory equivalence testing, raising barriers for ingredient suppliers lacking clinical or analytical capabilities. Stakeholders must monitor evolving regulatory thresholds and invest in taste modulation science to maintain formulation partnerships as mandatory labeling schemes expand.
Market Dynamics
Reformulation mandates from the FDA and front-of-pack labeling schemes in the European Union are compressing product development cycles for processed food manufacturers, forcing simultaneous investment in taste modulation science and supply chain reconfiguration.
Growth Catalysts
- FDA Voluntary Sodium Reduction Targets:Processed food manufacturers across the United States face procurement pressure to achieve phased sodium reductions in 163 food categories, driving bulk contracting for potassium chloride and yeast extract alternatives.
- Umami Enhancement Technologies:Yeast extract and nucleotide-based flavor modulators are displacing sodium chloride in savory applications where clean-label positioning commands retail shelf access.
- Front-of-Pack Labeling Mandates:Nutri-Score adoption in France, Belgium, and the Netherlands compels reformulation to avoid unfavorable color-coded ratings that depress consumer purchase intent.
Market Restraints
- Potassium Chloride Supply Concentration:Saskatchewan and Belarus collectively control 70% of global potash reserves, exposing salt substitute manufacturers to geopolitical supply disruptions and input cost volatility.
- Metallic Aftertaste Technical Limitation:Potassium chloride at replacement ratios above 30% generates persistent bitter notes that sensory masking technologies have not fully neutralized in high-sodium applications like cured meats.
- WHO Sodium Guidelines Compliance Friction:Divergent national implementation timelines for the 2,000 mg daily sodium target create fragmented formulation requirements across export markets.
Strategic Opportunities
- Plant-Based Meat Expansion:Alternative protein processors require sodium reduction ingredients to offset the high baseline sodium in pea and soy protein isolates while maintaining savory depth.
- Restaurant Chain Procurement Mandates:QSR operators in the United States are specifying sodium-reduced ingredient specifications in co-manufacturing agreements, creating dedicated supply contracts.
- Dual-Function Preservative Replacement:Clean-label demand is converging with sodium reduction as manufacturers seek ingredients that simultaneously lower sodium chloride and replace chemical preservatives in deli categories.
Industry Challenges
- Sensory Scientist Talent Scarcity:Formulation teams lack sufficient trained professionals capable of executing validated equivalence testing protocols required by major retail buyers.
- Legacy Equipment Retrofit Costs:Salt substitute hygroscopicity demands humidity-controlled handling systems that existing seasoning blending infrastructure cannot accommodate without capital expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Reduction Ingredients Market |
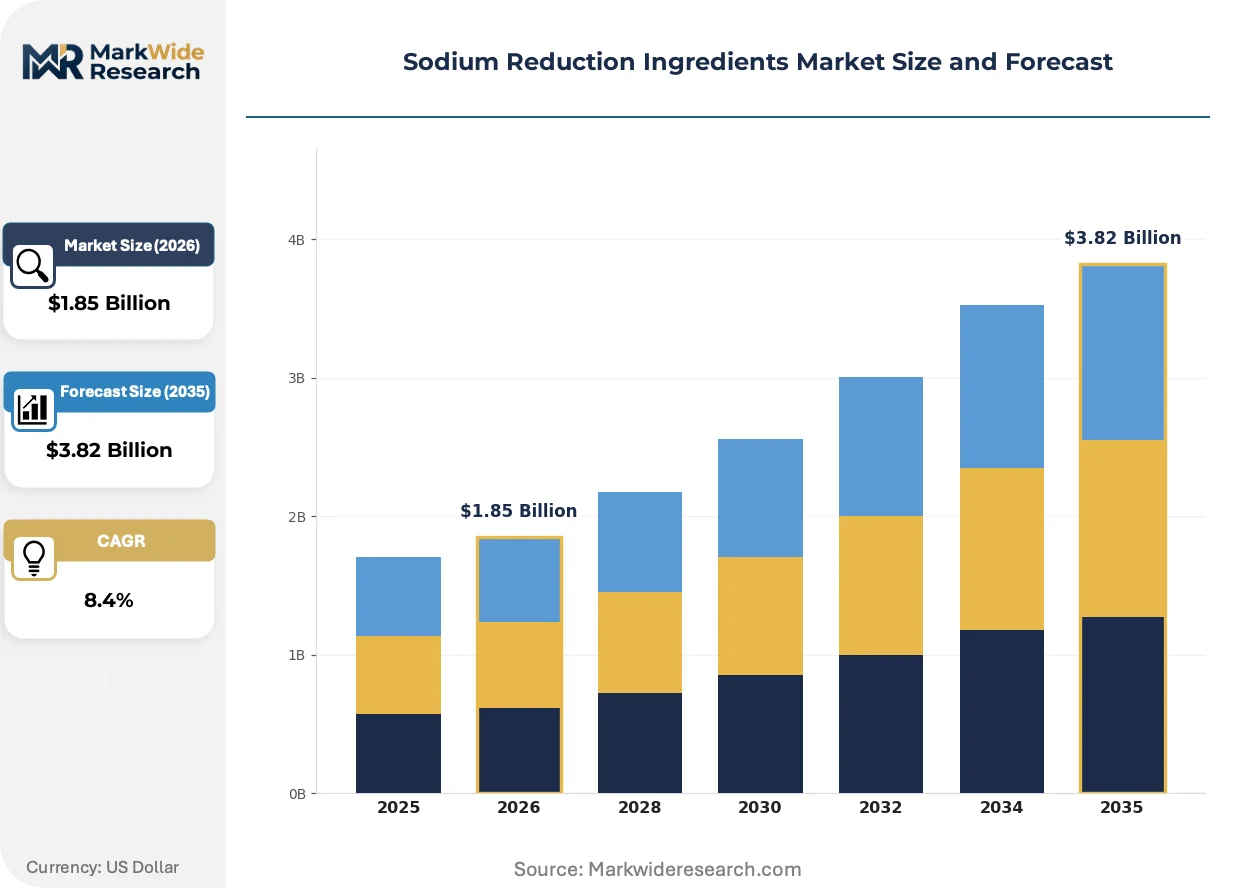
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Salt Substitutes, Flavor Enhancers, Acidulants, Yeast Extracts Application: Processed Foods, Snacks, Condiments, Beverages End User: Food Manufacturers, Restaurants, Retailers, Meal Kit Services Form: Liquid, Powder, Granular, Blends |
| Companies Covered | Cargill Incorporated, Kerry Group Plc, DSM-Firmenich, Givaudan SA, Tate & Lyle Plc, Angel Yeast Co. Ltd., Innophos Holdings Inc., Sensient Technologies Corporation, Jungbunzlauer Suisse AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Reduction Ingredients Market Strategic Shifts & Innovations
Multi-modal taste science is displacing single-ingredient sodium replacement as the dominant technical approach, with manufacturers layering potassium chloride, amino acids, and nucleotides to achieve sensory parity at lower sodium levels.
Electrolyte-balanced salt substitutes are electrifying reformulation strategies in the ready-meals segment. These systems combine microencapsulated potassium chloride with magnesium and calcium salts to distribute taste perception across the tongue. Major United States processors are adopting them at pilot scale for frozen entree lines. The technology is compressing the acceptable sodium reduction threshold from 25% to 40% without consumer rejection.
EU F-Gas Regulation phase-down schedules are indirectly pressuring sodium reduction ingredient selection by accelerating clean-label demands across refrigerated and frozen food categories. Manufacturers reformulating for sodium reduction must simultaneously eliminate chemical preservatives and synthetic flavor enhancers to meet retailer sustainability scorecards. The chilled soup and sauce segments in Germany and France are most affected, with processors consolidating supplier relationships to secure documented clean-label credentials.
Direct-to-manufacturer ingredient sourcing is displacing traditional distributor channels for sodium reduction formulations. Large food processors in the United States are negotiating multi-year supply agreements that bundle technical support, sensory validation, and regulatory documentation. This procurement compression is marginalizing regional ingredient distributors who lack in-house application laboratories. The trend is most visible in the snack food vertical, where reformulation velocity demands rapid iteration cycles that distributor intermediaries cannot support.
Sodium Reduction Ingredients Market Segmentation
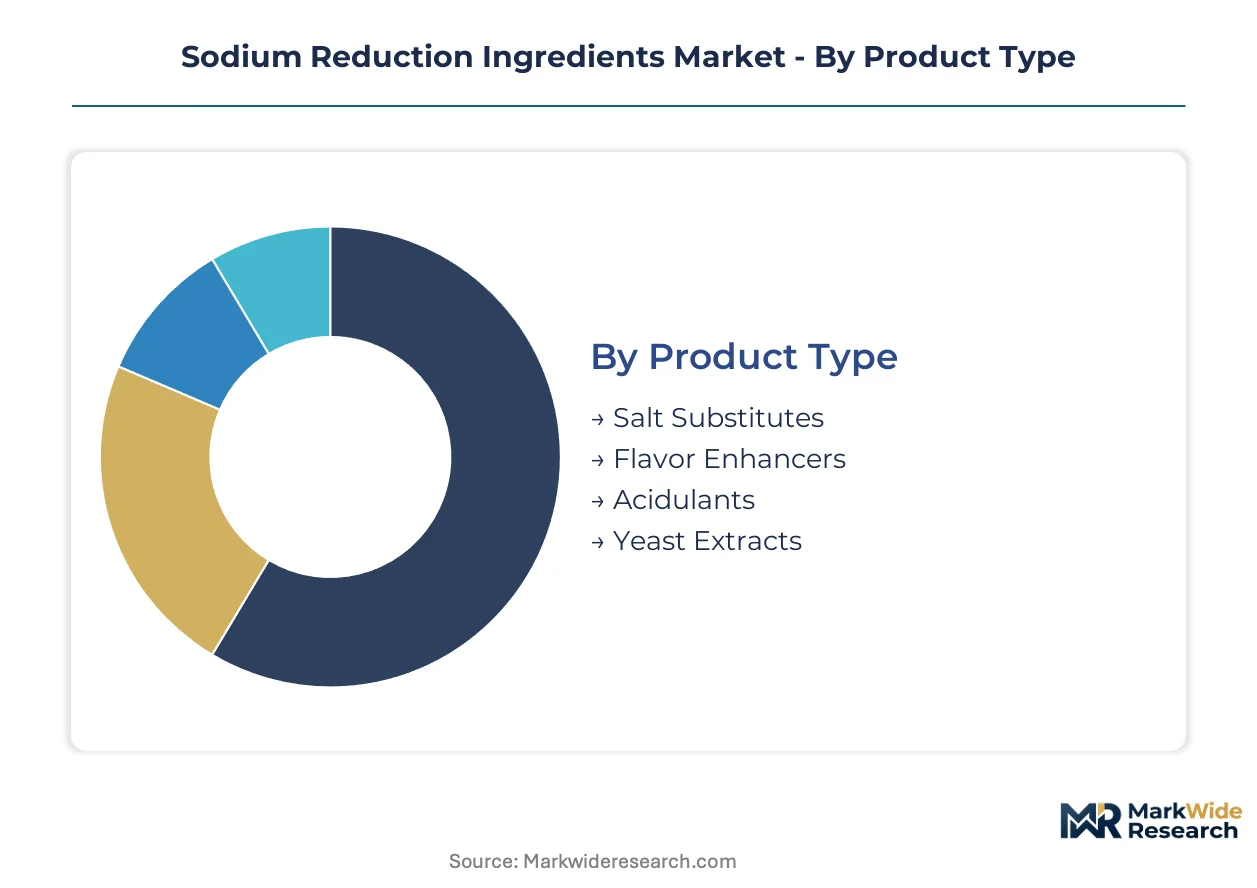
Sodium reduction ingredients require precise technical matching to application constraints, as salt substitutes, flavor modulators, and acidulants each address distinct functional gaps in reformulated products. Segmentation by product chemistry, application format, and supply chain position reveals where procurement premiums concentrate and which ingredient classes face commoditization pressure.
Product Type:
Technical specification determines replacement ratio ceilings and sensory masking requirements across savory applications.
- Salt Substitutes:Potassium chloride-based systems deliver bulk sodium replacement at 25-50% inclusion rates, though metallic off-notes limit deployment in cured meats and premium snacks where clean taste is non-negotiable. Procurement concentrates among United States frozen entree processors seeking dual-function mineral fortification alongside sodium reduction.
- Flavor Enhancers:Nucleotide and amino acid-based modulators activate umami receptors without sodium chloride, enabling deeper sodium cuts when layered with salt substitutes. Demand clusters in European soup and sauce manufacturers reformulating for Nutri-Score compliance.
- Acidulants:Citric and lactic acid derivatives brighten flavor perception to compensate for sodium absence in reduced-salt condiments and dressings.
- Yeast Extracts:Autolyzed yeast delivers clean-label umami depth through natural glutamate content, commanding formulation preference in organic and natural product lines.
Mature deployment sits with Salt Substitutes. Newer deployment is concentrated in Flavor Enhancers.
Application:
Reformulation urgency varies by category sodium baselines and regulatory exposure.
- Processed Foods:Canned soups, ready meals, and frozen entrees face the steepest FDA reduction targets across 163 food categories, driving multi-year supply contracts for integrated salt substitute and flavor enhancement systems. United States national brands are consolidating supplier relationships to secure technical support for iterative sensory validation.
- Snacks:Potato chips, crackers, and savory extruded products require hygroscopicity-controlled seasoning blends that maintain texture stability through distribution. European manufacturers are accelerating yeast extract adoption to meet front-of-pack labeling thresholds without sacrificing craveability.
- Condiments:Ketchup, mustard, and salad dressings rely on acidulant-enhanced profiles to maintain perceived intensity at reduced sodium levels.
- Beverages:Sports drinks and functional waters incorporate electrolyte-balanced mineral systems for sodium reduction without compromising hydration signaling.
Volume concentration centers on Processed Foods. Reformulation velocity is climbing fastest in Snacks.
End User:
Procurement sophistication and technical service demands diverge sharply across customer types.
- Food Manufacturers:National and regional processors command dedicated application laboratories and multi-year supply agreements bundling sensory validation, regulatory documentation, and rapid iteration support. Direct sourcing is displacing distributor channels for reformulation-intensive categories.
- Restaurants:Quick-service operators are embedding sodium specifications into co-manufacturing agreements, creating dedicated supply contracts for reduced-sodium seasoning systems.
- Retailers:Private label programs are consolidating supplier bases to secure clean-label credentials and documented sodium reduction pathways for sustainability scorecards.
- Meal Kit Services:Subscription food processors require flexible batch sizing and rapid formulation turnaround for rotating menu portfolios.
Contract sophistication peaks with Food Manufacturers. Procurement innovation is emerging from Restaurants.
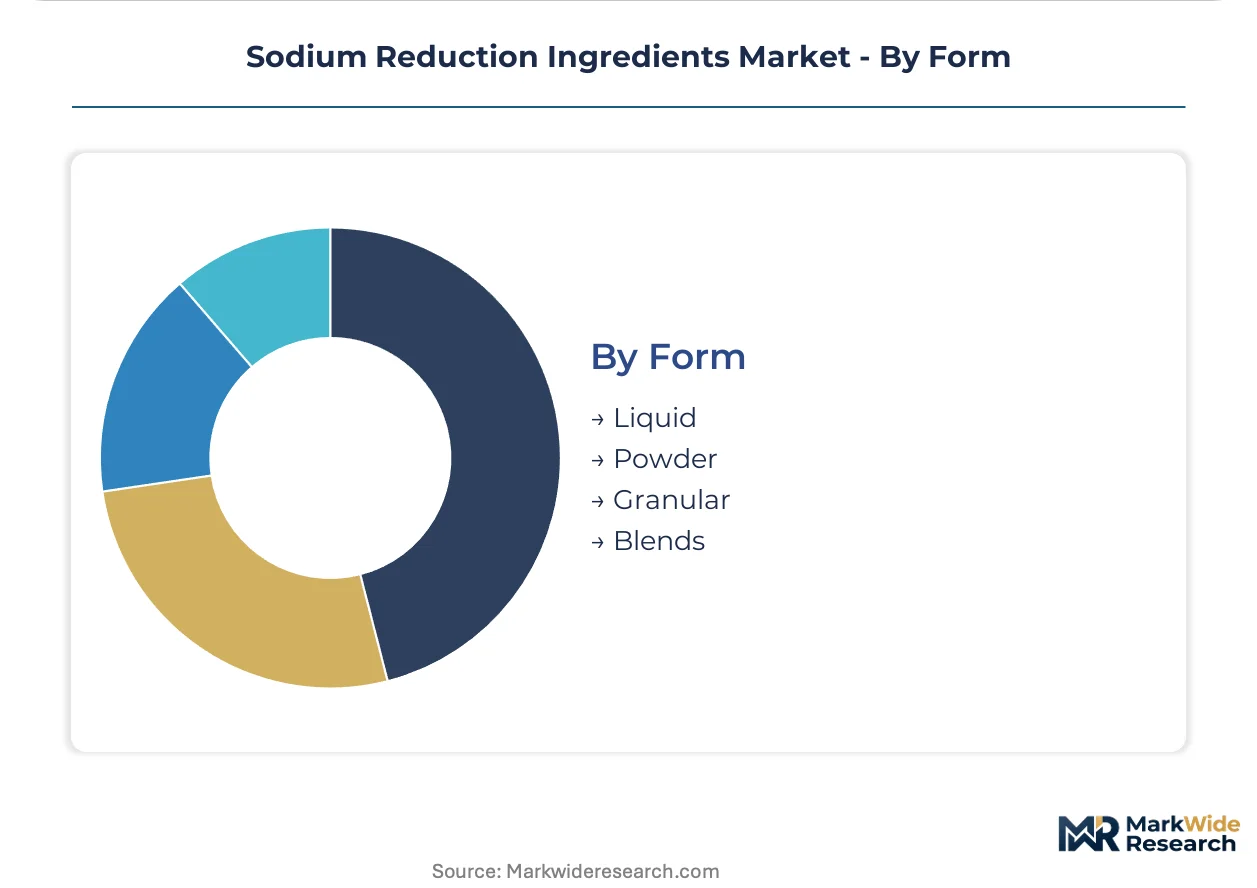
Form:
Physical state dictates handling infrastructure, dissolution kinetics, and blending compatibility.
- Liquid:Pre-dissolved sodium reduction systems enable precise dosing in continuous-process beverage and sauce manufacturing, eliminating dust exposure and hydration variability.
- Powder:Fine-grind salt substitutes and yeast extracts dominate high-volume seasoning applications where rapid dissolution and uniform distribution are critical.
- Granular:Coarse-crystal potassium chloride mimics salt mouthfeel in topical applications like snack seasoning where visual and tactile parity influences consumer acceptance.
- Blends:Pre-formulated combinations of salt substitutes, flavor enhancers, and flow agents reduce formulation complexity for mid-tier manufacturers lacking in-house sensory science capabilities.
Standardization is deepest in Powder. Technical differentiation is advancing most rapidly in Blends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicago anchors North American sodium reduction ingredient procurement through its concentration of frozen entree processors and national brand headquarters. FDA voluntary targets are compressing reformulation timelines across major manufacturing corridors.
United States
FDA voluntary sodium reduction targets for 163 food categories drive bulk contracting for potassium chloride and yeast extract alternatives. Quick-service restaurant chains embed sodium specifications into co-manufacturing agreements. Chicago and Minneapolis-St. Paul processors consolidate supplier relationships for integrated technical support.
Germany
EU F-Gas Regulation phase-down accelerates clean-label demands across refrigerated soup and sauce categories. Nutri-Score adoption compels reformulation to avoid unfavorable color-coded ratings. Cologne and Hamburg manufacturers consolidate supplier bases for documented sustainability credentials.
France
Front-of-pack Nutri-Score labeling mandates reshape product development budgets for savory applications. EFSA evaluations influence yeast extract acceptance for clean-label positioning. Paris and Lyon food processors prioritize multi-modal taste systems combining amino acids and nucleotides.
China
Processed food manufacturers face rising consumer health consciousness alongside SAMR food safety standards. Dual carbon goals indirectly pressure clean-label ingredient selection. Shanghai and Guangzhou processors adopt yeast extract technologies for umami depth without sodium chloride.
India
FSSAI draft sodium reduction guidelines signal tightening compliance thresholds for processed food categories. Urban middle-class expansion drives demand for reduced-sodium snack and ready-meal options. Mumbai and Bangalore manufacturers pilot potassium chloride blends for regional taste preferences.
Sodium Reduction Ingredients Market Key Industry Players
Premium-margin players sit above commodity-margin players across technical service capabilities and sensory validation infrastructure. The vendor base stratifies between agricultural supply chain integrators, flavor enhancement specialists, and fermentation-derived ingredient producers. Three archetypes dominate: salt substitute manufacturers with captive mineral sourcing, yeast extract fermenters with clean-label positioning, and flavor modulation technology providers. Competitive moves concentrate on multi-year supply agreement bundling and direct-to-manufacturer channel displacement.
Within the agricultural supply chain tier, Cargill Incorporated exemplifies bulk commodity positioning through integrated potash access. Kerry Group Plc and DSM-Firmenich occupy premium-tier positions as flavor enhancement and fermentation technology specialists respectively. These three anchors represent distinct strategic vectors: upstream mineral control, savory application science, and biotech-derived taste modulation.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Kerry Group Plc |
| DSM-Firmenich |
| Givaudan SA |
| Tate & Lyle Plc |
| Angel Yeast Co. Ltd. |
| Innophos Holdings Inc. |
| Sensient Technologies Corporation |
| Jungbunzlauer Suisse AG |
| Others |
Cost & Logistics Intelligence
National frozen entree processors in the United States command consolidated procurement leverage that compresses ingredient margins while rewarding suppliers bundling sensory validation services. Value-based pricing anchors on documented sodium reduction outcomes validated through equivalence testing protocols demanded by FDA compliance frameworks.
Pricing Analysis
Outcome-based pricing tied to sensory parity achievement anchors supplier contracts, with premiums attaching to documented equivalence testing and regulatory documentation bundles. Three-tier pricing structure across premium, standard, and economy levels separates fermentation-derived yeast extracts from commodity potassium chloride and unmodified mineral salts. Cost compression in salt substitutes is intensifying because Saskatchewan and Belarus supply concentration exposes buyers to potash price volatility. Mid-tier regional processors exhibit highest price sensitivity due to limited in-house sensory science capabilities, while national brands prioritize technical service over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Saskatchewan and Belarus, which collectively anchor 70% of global potash reserves essential for potassium chloride production. Raw material dependencies center on potash mining outputs, fermentation feedstocks for yeast extract, and nucleotide precursors for flavor modulators. Tariff exposure runs through Belarusian supply disruptions and export restriction risks from major potash jurisdictions. Distribution runs through direct-to-manufacturer channels displacing traditional ingredient distributors, with large processors negotiating multi-year agreements bundling technical support and rapid iteration capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Potash mining capacity constraints in politically exposed jurisdictions prop pricing premiums for suppliers securing alternative mineral sourcing. Supply tightness favors incumbents with captive upstream access or fermentation-based alternatives decoupled from extractive geology.
For Market Incumbents: Hedge against potassium chloride commodity exposure by expanding yeast extract fermentation capacity or securing potash offtake agreements in politically stable jurisdictions. Threat from nucleotide-based flavor modulators demands accelerated R&D investment in multi-modal taste systems. Backward integration into mineral sourcing or biotech-derived alternatives represents the critical defensive lever. For New Entrants and Emerging Players: Direct-to-manufacturer digital platforms offer the lowest-friction entry path, bypassing distributor channels marginalized by procurement compression. White-space concentrates in electrolyte-balanced salt substitutes for ready-meals and clean-label preservative replacements for deli categories. Plant-based meat processors present the most penetrable segment given their sodium baselines and reformulation urgency. For Investors and Strategic Acquirers: The window for entry favors fermentation technology specialists with scalable bioprocess platforms and documented clean-label credentials. Long-term viability hinges on regulatory tailwinds for front-of-pack labeling and WHO guideline adoption tightening compliance thresholds. Watch for FDA mandatory sodium reduction proposals as the inflection signal shifting voluntary targets to enforceable mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mineral Sourcing | Cargill's captive potash access insulates against Belarusian supply disruptions and price spikes. |
| Fermentation Capacity Expansion | DSM-Firmenich's yeast extract scaling captures clean-label demand from European Nutri-Score compliance. |
| Multi-year Supply Agreement Bundling | Kerry Group's technical service contracts lock in national processor relationships against distributor competition. |
| Direct-to-Manufacturer Channel Buildout | Angel Yeast's bypass of regional distributors accelerates reformulation iteration cycles for snack manufacturers. |
| Sensory Validation Laboratory Investment | Innophos's equivalence testing infrastructure meets FDA documentation demands for 163 food categories. |
Research Approach
Regulatory filings from FDA, EFSA, and FSSAI, trade data from customs authorities, and industry association reports formed the secondary backbone for market sizing and policy trajectory assessment. Primary interviews with ingredient procurement directors at national food manufacturers, sensory science leads at flavor houses, regulatory affairs managers at fermentation specialists, and category buyers at quick-service restaurant chains combined with secondary validation through bottom-up and top-down triangulation.
Historical trendline analysis of reformulation investment patterns and sodium reduction technology adoption curves informed the projection framework across the analysis window. Segmentation dimensions modeled include product chemistry tier, application category, end-user procurement sophistication, and regional regulatory cluster. CAGRs were derived from growth rate convergence analysis incorporating FDA target phase-in schedules, EU F-Gas Regulation clean-label pressures, and plant-based meat processor expansion trajectories.
The model holds under stable regulatory enforcement timelines and continued front-of-pack labeling adoption; deviation in mandatory sodium reduction legislation or potash supply disruptions would shift trajectory bounds. Forecasts reflect documented policy commitments and disclosed corporate reformulation timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Icing Shortening Market
Ingredients
India Protein Market
Ingredients
MCT Oil Market
Ingredients
Casein Glycomacropeptide Market
Ingredients
South America Phytosterols Market
Ingredients
North America Protein Ingredients Market
Ingredients
Vegetable Extract Market
Ingredients
Fruit Pectin Market
Ingredients
Polydextrose Ingredients Market
Ingredients
Chewing Gum Base Market
Ingredients
Acetylated Starch Market
Ingredients
Dairy Ingredients Market
Ingredients
Global Amaranth Oil Market
Ingredients
Cocoa Processing Market
Ingredients
Clean Label Flour Market
Ingredients
Global Inactive Dried Yeast Market