
 GCC Concealed Cistern Market | 2026-2036
GCC Concealed Cistern Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Concealed Cistern Market Insights
Plumbing installer shortages across the Gulf Cooperation Council is redrawing how concealed cistern suppliers structure training and after-sales support. Grohe leverages its German engineering heritage to sustain premium positioning in Saudi specification channels. RAK Ceramics anchors regional manufacturing scale through its UAE production base, while Jaquar competes aggressively on price-accessible wall-mounted portfolios across Indian expatriate contractor networks.
A concealed cistern houses the toilet flush tank within a wall cavity or furniture unit, typically constructed from high-density polyethylene or ceramic-composite materials with dual-flush mechanisms operating at three and six liter volumes to optimize water consumption. The product serves primarily to maximize floor space and enable minimalist bathroom aesthetics in dense urban construction. Dual flush variants dominate volume shipments across Gulf markets due to SASO and ESMA water-efficiency compliance requirements, while smart cistern integration with sensor-actuated flushing represents the fastest-expanding margin pool. Wall-mounted installation leads new construction specifications, though pre-wall systems capture renovation demand where structural retrofit constraints limit full cavity integration.
SASO's mandatory water efficiency labeling, ESMA's UAE-specific plumbing product standards, and Qatar's GSAS sustainability certification collectively dictate flush-volume ceilings and material approval pathways for concealed cistern entry into Gulf markets. The country's national construction regulator in Oman and Bahrain's national standards body enforce supplementary mechanical testing protocols that extend product development cycles by six to twelve months for new entrants. Stakeholders must monitor evolving municipal green building mandates across individual emirates and kingdoms, as these increasingly embed concealed cistern specifications directly into developer tender requirements rather than relying solely on national standards.
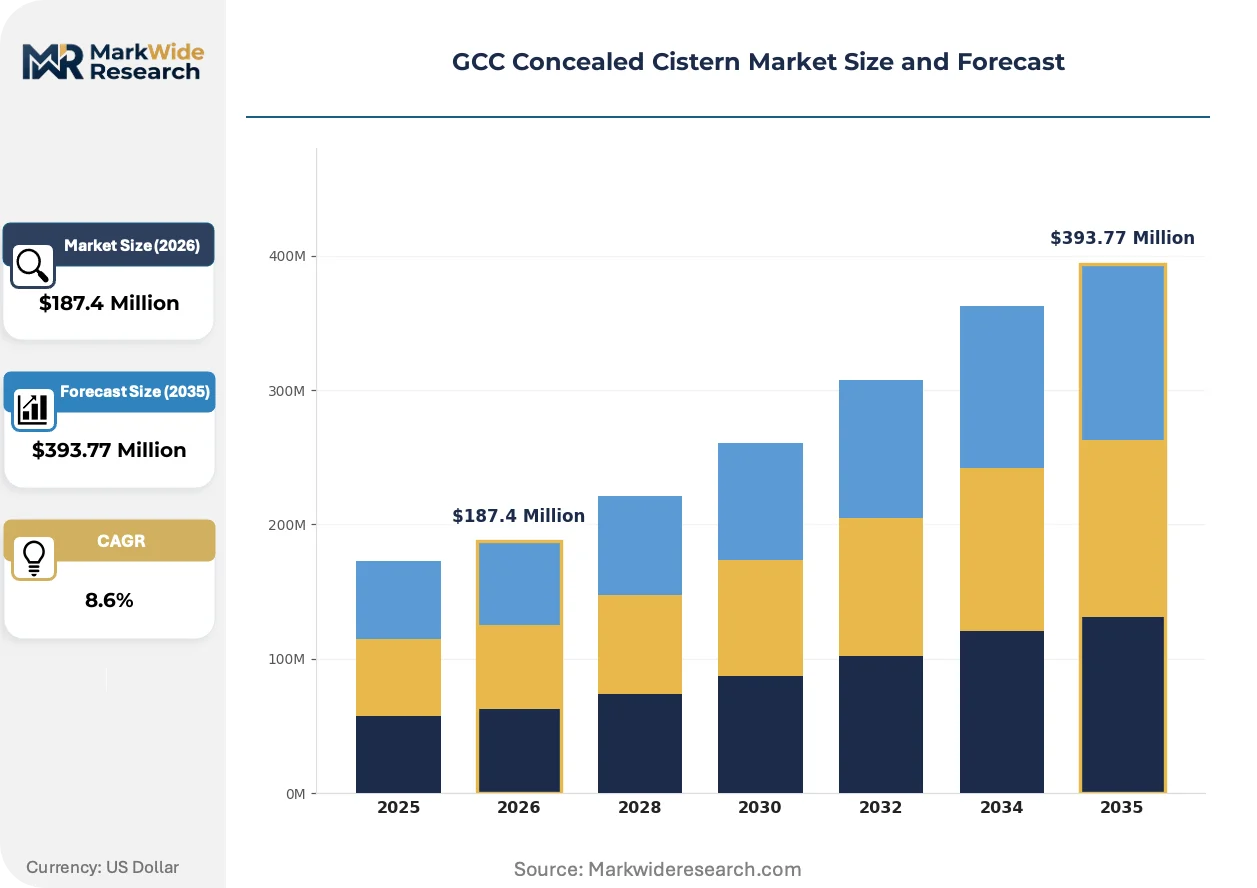
Market Dynamics
Saudi Arabia's SASO water efficiency mandates are compressing flush volumes across concealed cistern portfolios, forcing manufacturers to redesign mechanisms while maintaining performance in high-rise residential towers.
Growth Catalysts
- Dual-flush mechanism mandates:SASO and ESMA water-efficiency labeling requirements across Saudi Arabia and the UAE compel specification of three and six liter flush systems in new construction.
- Luxury hospitality pipeline:Hotel construction in Dubai and Riyadh specifies wall-mounted systems for space optimization and minimalist aesthetics in premium bathroom fit-outs.
- High-rise residential density:UAE tower developers prioritize concealed cisterns to maximize floor area in compact urban units.
Market Restraints
- HDPE resin cost volatility:High-density polyethylene input prices fluctuate with petrochemical feedstock markets, compressing margins on economy-tier cistern production.
- Plumbing installer scarcity:Gulf Cooperation Council-wide shortages of certified technicians trained in pre-wall and cavity installation limit project execution velocity.
- Extended certification timelines:Oman's national construction regulator and Bahrain's standards body impose supplementary mechanical testing protocols that delay new entrant market access by six to twelve months.
Strategic Opportunities
- Smart sensor integration:Touchless actuation systems represent the fastest-expanding margin pool as hygiene consciousness drives specification in commercial and hospitality segments.
- Qatar GSAS certification pathway:Green building mandates embed concealed cistern specifications directly into developer tender requirements beyond baseline national standards.
- Renovation pre-wall systems:Structural retrofit constraints in existing UAE and Saudi residential stock create demand for surface-mounted frame solutions that bypass full cavity integration.
Industry Challenges
- Technical workforce gaps:Concealed cistern installation demands specialized skills in waterproofing, frame alignment, and access panel integration that outpace regional vocational training output.
- Multi-jurisdiction compliance burden:Manufacturers must navigate divergent municipal green building mandates across individual emirates and kingdoms without harmonized Gulf-wide standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Concealed Cistern Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dual Flush, Single Flush, Smart Cistern, Gravity Flush Installation Type: Wall-Mounted, Floor-Mounted, Pre-wall, Hidden Tank End User: Residential, Commercial, Hospitality, Institutional Distribution Channel: Online Retail, Specialty Stores, Wholesale, Direct Sales |
| Companies Covered | Kohler, Cera, Roca, Jaquar, Fluidmaster, Grohe, Lixil, RAK Ceramics, Hindware, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Concealed Cistern Market Trends and Innovations
Sensor-actuated flushing systems are compressing traditional mechanical-lever architectures across Gulf specification channels. Three interconnected developments are reshaping product development priorities and competitive positioning.
Smart valve technology is miniaturizing. Piezoelectric and infrared sensor modules now integrate within standard 80mm wall cavities previously reserved for purely mechanical flush plates. Luxury hotel operators in Dubai and Riyadh specify these systems for hygiene differentiation. The technology is miniaturizing control electronics to fit legacy frame dimensions without structural wall modifications.
ESMA's UAE-specific plumbing product standards now mandate water efficiency labeling that exceeds baseline SASO requirements. Manufacturers must maintain dual certification portfolios to serve cross-border projects. High-rise residential developers in Abu Dhabi and Sharjah increasingly specify ESMA-compliant systems preemptively to streamline procurement across emirate boundaries.
Installer certification programs are displacing informal contractor networks. Grohe and RAK Ceramics now operate dedicated training academies in Jeddah and Ras Al Khaimah to guarantee proper pre-wall system commissioning. Saudi specification channels reward documented installer competence with preferred vendor status, concentrating project awards among certified supply chains.
GCC Concealed Cistern Market Segmentation
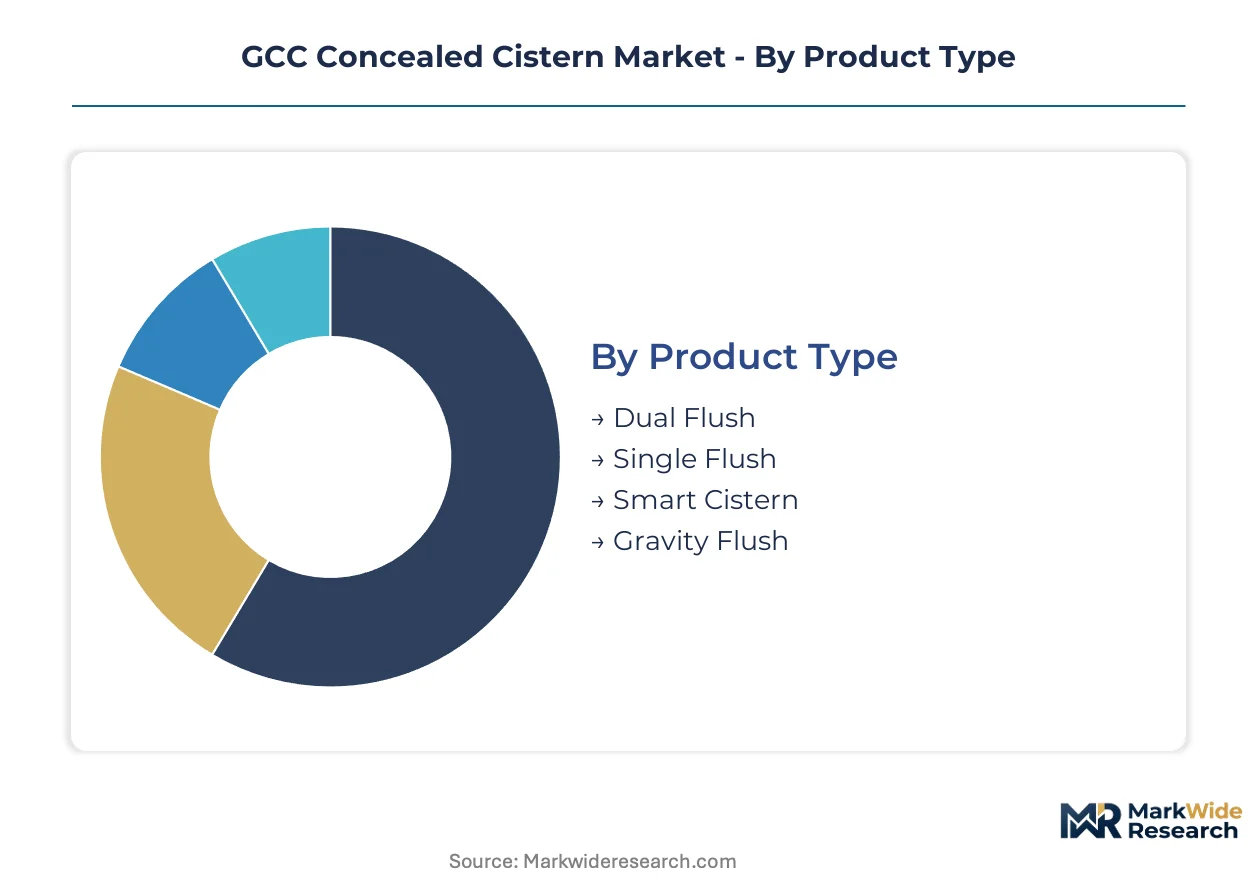
Concealed cistern procurement channels in the GCC diverge sharply between bulk project contracting and retail replacement, with product specifications varying by installation complexity and water-efficiency mandates. Understanding segment boundaries reveals where margin pools concentrate versus where volume flows.
Product Type:
Channel mix varies by flush mechanism sophistication, with dual-flush systems dominating project tenders while smart cisterns command specification premiums through direct manufacturer relationships.
- Dual Flush:Mechanisms operating at three and six liter volumes constitute the regulatory baseline for SASO and ESMA compliance. Saudi high-rise residential towers specify these systems exclusively to meet mandatory water-efficiency labeling.
- Smart Cistern:Sensor-actuated flushing with piezoelectric and infrared modules integrates within standard 80mm wall cavities. Luxury hotel operators in Dubai and Riyadh specify these for hygiene differentiation, with this segment climbing the fastest in margin contribution.
- Single Flush:Legacy mechanical systems persist in budget renovation projects where water-efficiency mandates are not yet enforced.
- Gravity Flush:Basic hydraulic systems serve economy-tier residential applications with minimal electronic components.
By volume, dual-flush systems lead. By growth pace, smart cisterns are expanding most quickly.
Installation Type:
Cost tiers separate new construction from retrofit applications, with full cavity integration commanding premium pricing against surface-mounted alternatives.
- Wall-Mounted:Frames anchored within structural cavities enable minimalist aesthetics and floor-space maximization. UAE tower developers specify these for compact urban units, though installation demands certified waterproofing and frame alignment skills.
- Pre-wall:Surface-mounted frame solutions bypass full cavity integration for structural retrofit constraints. Saudi and UAE renovation contractors favor these where existing wall conditions prohibit demolition.
- Floor-Mounted:Conventional pedestal installations retain share in budget residential segments.
- Hidden Tank:Furniture-integrated units serve premium bathroom fit-outs where access panel concealment is prioritized.
By volume, wall-mounted leads. By growth pace, pre-wall systems are gaining share fastest.
End User:
Application intensity varies by build quality standards, with hospitality and institutional segments driving specification upgrades while residential volume flows through developer bulk procurement.
- Residential:High-rise tower developers in the UAE prioritize concealed cisterns to maximize floor area ratios in dense urban construction.
- Hospitality:Luxury hotel construction across Dubai and Riyadh specifies wall-mounted dual-flush systems for space optimization and minimalist bathroom aesthetics.
- Commercial:Office fit-outs in Saudi Arabia's giga-projects incorporate smart sensor systems for hygiene-conscious tenant expectations.
- Institutional:Healthcare and education facilities in Qatar align with GSAS sustainability certification requirements.
By volume, residential leads. By specification value, hospitality commands premium positioning.
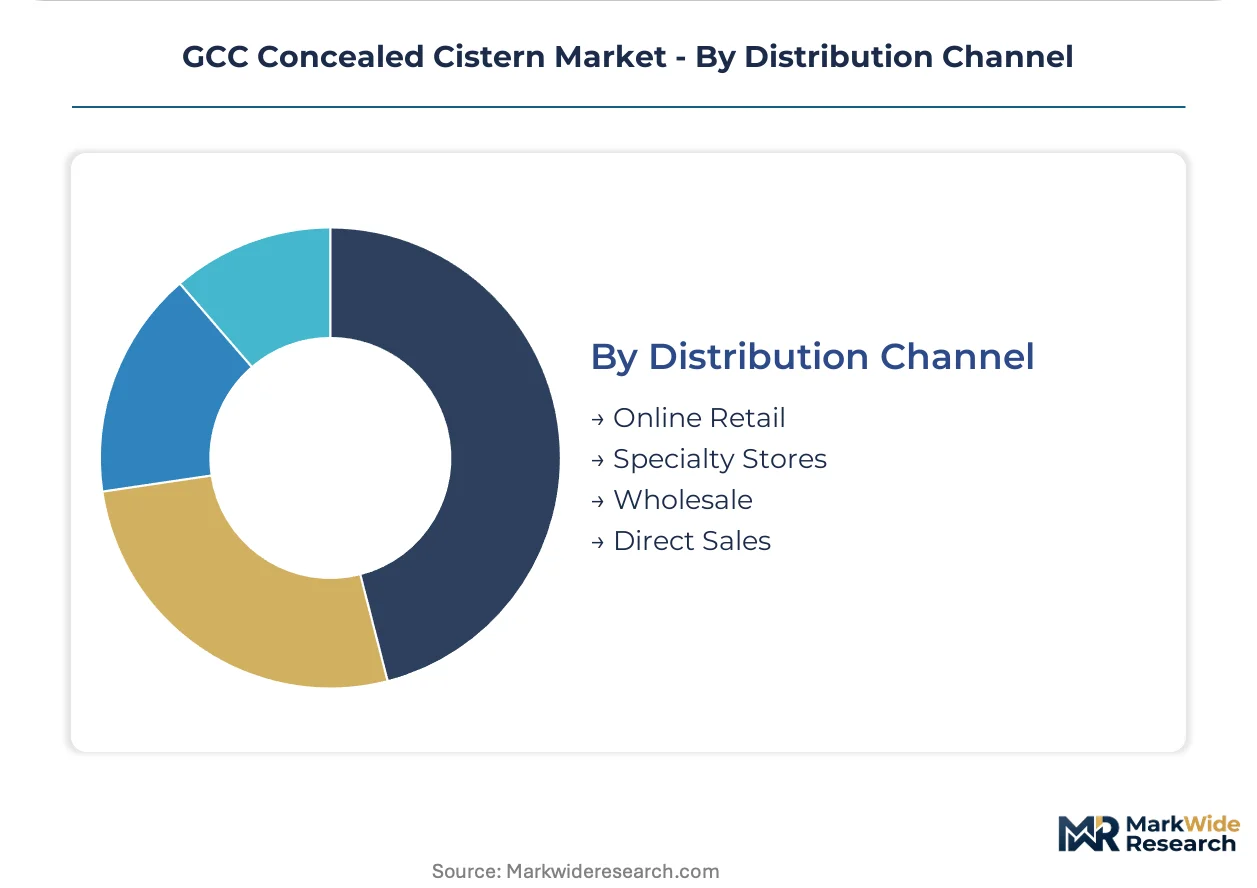
Distribution Channel:
Customer type dictates channel selection, with project developers routing through wholesale and direct sales while retail replacement flows through specialty stores.
- Wholesale:Bulk contracting channels serve developer tender requirements across Saudi giga-projects and UAE high-rise construction.
- Direct Sales:Manufacturer specification teams engage Saudi and UAE project consultants for ESMA and SASO compliance documentation.
- Specialty Stores:Showroom networks in Dubai and Riyadh capture renovation demand and architect specification influence.
- Online Retail:E-commerce platforms serve replacement part procurement and price-transparent consumer comparison.
By volume, wholesale leads. By margin retention, direct sales offer steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia and the UAE deploy concealed cisterns at scale in high-rise residential towers, while Qatar and Oman concentrate demand in hospitality and institutional segments with stricter green building mandates.
Saudi Arabia
SASO water efficiency labeling compresses flush volumes to three and six liters across Riyadh's giga-project pipeline. The Saudi Standards, Metrology and Quality Organization mandates dual-flush mechanisms in all new construction permits issued since 2023. Eastern Province industrial zones supply HDPE resin feedstock to regional cistern fabricators serving the Kingdom's western development corridor.
United Arab Emirates
ESMA plumbing standards exceed SASO baselines, forcing manufacturers to maintain dual certification portfolios for cross-emirate projects. Dubai's luxury hospitality pipeline specifies wall-mounted systems for space optimization in premium bathroom fit-outs. Abu Dhabi and Sharjah high-rise developers preemptively specify ESMA-compliant systems to streamline procurement across emirate boundaries.
Qatar
GSAS sustainability certification embeds concealed cistern specifications directly into developer tender requirements beyond national standards. The country's green building regulator mandates water-efficient fixtures in all commercial and institutional construction. Doha's healthcare and education facilities align procurement with GSAS sustainability tiers, creating premium specification channels.
Oman
The national construction regulator enforces supplementary mechanical testing protocols that extend product development cycles by six to twelve months for new entrants. Muscat's institutional building stock drives demand for pre-wall retrofit systems where structural constraints limit full cavity integration. Salalah's hospitality development zone specifies imported dual-flush systems for resort construction.
Bahrain
Bahrain's national standards body imposes extended certification timelines that filter out speculative market entrants. Manama's financial district office renovations favor surface-mounted frame solutions bypassing full wall demolition. The island's compact urban geography concentrates demand in high-density residential towers with space-constrained bathroom footprints.
GCC Concealed Cistern Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the GCC concealed cistern market. German and UAE-based manufacturers anchor premium specification channels through engineering heritage and regional production scale. Three archetypes dominate: European heritage brands competing on technical certification, regional manufacturers leveraging proximity to petrochemical feedstock, and Indian-origin specialists penetrating price-accessible contractor networks. Capacity expansion and installer certification programs constitute the dominant competitive moves as plumbing technician scarcity constrains project execution velocity.
Among European heritage manufacturers, Grohe leverages German engineering positioning in Saudi specification channels. RAK Ceramics anchors regional manufacturing scale through its UAE production base. Jaquar competes aggressively on price-accessible wall-mounted portfolios across Indian expatriate contractor networks. These three exemplify distinct archetypes: technical certification leadership, feedstock-proximate manufacturing, and contractor-network penetration.
| Leading Market Players |
|---|
| Kohler |
| Cera |
| Roca |
| Jaquar |
| Fluidmaster |
| Grohe |
| Lixil |
| RAK Ceramics |
| Hindware |
| Others |
Pricing and Supply Chain Analysis
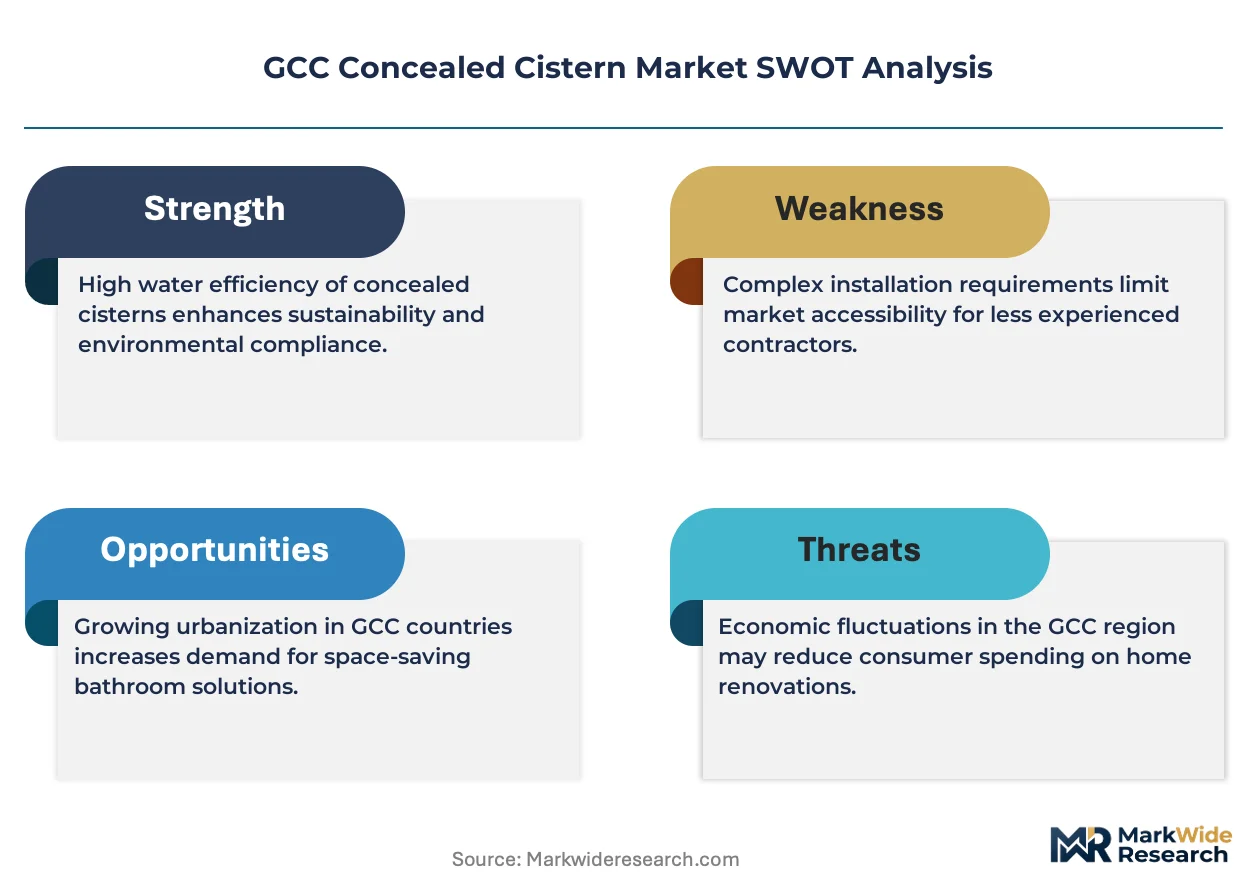
SASO water efficiency labeling and ESMA certification regimes gate both supplier qualification and price differentiation across the GCC concealed cistern market. These dual compliance frameworks compress margin pools for uncertified imports while enabling certified manufacturers to command specification premiums in Saudi and UAE project channels.
Pricing Analysis
Project-based contracting dominates concealed cistern procurement, with bulk offtake agreements linking Saudi giga-projects and UAE tower developers to manufacturers offering volume-scaled pricing. Price differentiation rests on ESMA tier certification and installer training bundling, with economy-tier HDPE systems facing cost compression from petrochemical feedstock volatility. Hospitality buyers in Dubai and Riyadh exhibit lowest price sensitivity, prioritizing hygiene differentiation through smart sensor integration.
Supply Chain Analysis
Port congestion along Jebel Ali-Dammam trade lanes elevates inbound logistics costs for European component imports serving UAE assembly operations. HDPE resin feedstock concentrates in Saudi Arabia's Eastern Province, China, and South Korea, while ceramic-composite materials draw from UAE domestic production. Single-source vulnerability runs through piezoelectric sensor modules sourced from East Asian specialists. Distribution runs through wholesale contractor networks anchored in Jeddah and Dubai specification channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates white-space opportunities as smart sensor integration and pre-wall retrofit demand splinter procurement requirements across specialist tiers.
For Market Incumbents: Shield specification position by deepening installer certification academies in Ras Al Khaimah and Jeddah to lock in project access. Accelerate backward integration into HDPE compounding to offset Eastern Province resin cost volatility. Grohe and RAK Ceramics have established this template; followers must match or exceed training throughput to maintain preferred vendor status. For New Entrants and Emerging Players: Lead with pre-wall surface-mounted systems targeting Saudi renovation contractors constrained by structural retrofit limitations. Qatar's GSAS-certified institutional segment offers the most penetrable premium tier for smart cistern specialists lacking legacy ESMA portfolios. Direct sales teams engaging Doha healthcare project consultants bypass entrenched wholesale channels. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across smart cistern electronics assembly as sensor module commoditization reduces specialized equipment requirements. Acquisition targets should display documented installer network scale or captive ESMA/SASO certification infrastructure. Watch for Saudi giga-project tender delays as an inflection signal for demand compression.| Strategic Initiative | Industry Significance |
|---|---|
| Installer Certification Academy Expansion | Grohe's Jeddah training center locks in project specification access through documented competence. |
| Backward Integration into HDPE Compounding | RAK Ceramics' UAE captive resin supply insulates margins from petrochemical feedstock swings. |
| Smart Sensor Module Partnership | Piezoelectric integration within 80mm cavities enables hygiene differentiation in Riyadh luxury hotels. |
| Pre-Wall System Portfolio Launch | Surface-mounted frames bypass structural constraints in Saudi residential renovation projects. |
| GSAS Certification Pathway Investment | Qatar's green building mandates embed cistern specifications directly into Doha healthcare tenders. |
Research Methodology
Desk research of customs trade databases, ESMA product registration filings, and SASO technical regulations preceded structured interviews with plumbing contractors, project procurement managers, and ceramic manufacturing executives across the Gulf Cooperation Council. Primary fieldwork with pre-wall installation specialists and hospitality FF&E consultants cross-validated secondary shipment data from UAE and Saudi import records. Bottom-up project pipeline tracking triangulated against top-down petrochemical feedstock demand models.
Variance decomposition across product type, installation complexity, and end-use application segments shaped the analytical framework over the projection horizon. CAGRs derived from fitted growth curves incorporating SASO mandate enforcement timelines and giga-project completion schedules. Flush volume compliance trajectories and smart sensor adoption curves served as industry-specific forecast inputs.
Underlying assumptions cover sustained Saudi residential tower construction and ESMA enforcement continuity, with deviation risk concentrated in HDPE resin price spikes and plumbing technician training bottlenecks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
United Kingdom Architectural Coatings Market
Building Materials
Europe Acrylic Resin Dispersion Based Primers in Construction Market
Building Materials
Europe Fiber Cement Market
Building Materials
Polymer-Modified Cementitious Mortar Market
Building Materials
North America Engineered Stone Market
Building Materials
Germany Aluminum Door and Window Market
Building Materials
Italy Facade Market
Building Materials
Composite Decking and Railing Market
Building Materials
US Commercial Paving Slabs Market
Building Materials
Asia-Pacific Building and Construction Sheets Market
Building Materials
Foam Concrete Market
Building Materials
Asia-Pacific Dry-Mix Mortar Market
Building Materials
China Cement Market
Building Materials
Global Commercial Paving Slabs Market
Building Materials
East Africa Cement Market
Building Materials
Qatar Cement Market