
 Concrete and Cement Market | 2026-2036
Concrete and Cement Market Size, Share, and Industry Trends Forecast 2026-2036
Concrete and Cement Market Analysis
Multi-source procurement of clinker and supplementary cementitious materials is realigning supply chain strategies across the industry. Heidelberg Materials leverages vertical integration from limestone quarries to ready-mix operations across European markets. UltraTech Cement anchors its position through massive manufacturing scale and distribution depth across the Indian subcontinent.
Concrete and cement comprise a composite construction material formed from Portland cement, aggregates, and water, with compressive strength typically measured at 28 days to verify structural performance. The material serves as the foundational substrate for modern building construction, road infrastructure, and industrial flooring systems. Ready-mix concrete dominates volume flows due to its batch-controlled quality and just-in-time delivery model, while precast concrete commands premium positioning through factory-cured precision and reduced on-site labor. Infrastructure development represents the fastest-growing end-user channel as governments fund bridge, highway, and utility projects with extended multi-year procurement cycles.
The US Environmental Protection Agency enforces National Emission Standards for Hazardous Air Pollutants at Portland cement kilns, forcing producers to invest in emission control technology or face facility constraints. The EU Green Deal and associated F-Gas Regulation impose carbon intensity thresholds on cement imports, reshaping trade flows and domestic production economics. China's Ministry of Ecology and Environment enforces dual carbon goals that cap clinker capacity expansion while mandating alternative fuel substitution. Stakeholders must monitor regulatory divergence across these jurisdictions to anticipate where production cost advantages will shift and where low-carbon cement formulations will unlock market access.
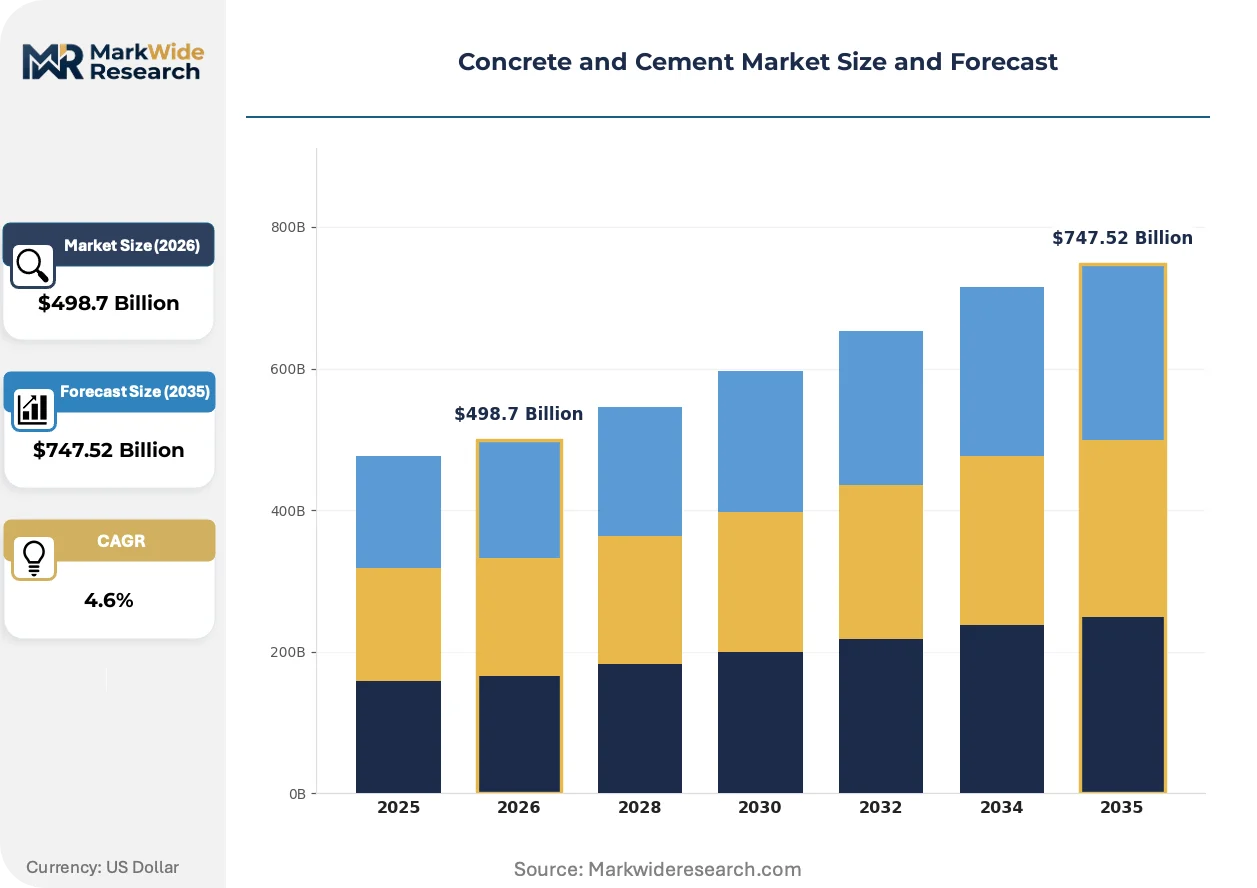
Market Dynamics
Carbon border adjustments are forcing cement producers to reconfigure supply chains and invest in kiln emissions abatement before trade penalties activate.
Growth Catalysts
- National infrastructure programs:Bridge and highway construction across India, Indonesia, and Vietnam is accelerating procurement of high-strength concrete. Government capital allocation for multi-year transport projects sustains volume demand.
- EU Carbon Border Adjustment Mechanism:Import tariffs on carbon-intensive cement are compelling non-EU producers to adopt cleaner production methods. This creates competitive advantage for early decarbonizers accessing European markets.
- Geopolymer binder technology:Alkali-activated materials are displacing clinker in select precast applications. Reduced thermal processing requirements lower both energy costs and Scope 1 emissions.
Market Restraints
- Limestone feedstock concentration:High-purity calcium carbonate deposits concentrate in specific geographies, creating supply vulnerability for distant grinding operations. Transport costs erode margin for import-dependent facilities.
- Clinker substitution limits:Supplementary cementitious material availability constrains blended cement production in regions lacking fly ash or slag access. Technical performance standards cap replacement ratios.
- Natural gas price volatility:Kiln fuel costs swing with European and Asian spot markets. Producers without alternative fuel infrastructure face margin compression during energy price spikes.
Strategic Opportunities
- Carbon capture retrofitting:Post-combustion capture systems at existing kilns qualify for EU Innovation Fund and US IRA tax credits. Early movers secure offtake agreements with hard-to-abate industrial buyers.
- Ready-mix urban penetration:Informal construction markets in Lagos, Nairobi, and Dhaka remain underpenetrated by batch-controlled delivery. Mobile mixing units can displace site-mixed concrete quality inconsistencies.
- 3D printing concrete formulations:Extrusion-compatible mixes with tailored rheology open architectural applications. Construction automation partnerships enable prefabrication of complex structural elements.
Industry Challenges
- Process engineer scarcity:Alternative fuel co-processing and carbon capture operations require specialized kiln chemistry expertise. Talent competition from adjacent heavy industries elevates compensation costs.
- Certification timeline compression:New low-carbon cement categories face extended testing protocols for structural code approval. Construction liability insurers demand multi-year performance data before coverage extension.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Concrete and Cement Market |
| Market Size in 2026 | $498.7 Billion |
| Market Size in 2035 | $747.52 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ready-Mix Concrete, Precast Concrete, High-Strength Concrete, Reinforced Concrete End User: Residential Construction, Commercial Construction, Infrastructure Development, Industrial Projects Application: Building Construction, Road Construction, Bridge Construction, Flooring Distribution Channel: Direct Sales, Retail Sales, Online Sales, Wholesalers |
| Companies Covered | CRH, Holcim Group, Heidelberg Materials, UltraTech Cement, Cemex, Anhui Conch Cement, CNBM, Buzzi Unicem, Siam Cement Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Concrete and Cement Market Emerging Trajectories
Digital batch optimization and alternative fuel systems are converging to reduce both variable costs and regulatory exposure across kiln operations.
Calcined clay activation is integrating into blended cement formulations as a proven clinker reduction pathway. European precast manufacturers are adopting LC3 mixes at scale for facade and structural elements. The technology is compressing carbon intensity per ton while maintaining compressive performance standards.
The EU F-Gas Regulation imposes phasedown schedules on hydrofluorocarbon refrigerants used in cement plant cooling systems. Industrial refrigeration retrofits are diverting capital from core production equipment. German and Polish facilities face the most compressed compliance timelines due to older installed bases.
Consolidated buyer purchasing is concentrating volume with fewer ready-mix suppliers in metropolitan construction markets. Single-source agreements are displacing spot procurement for major infrastructure projects. This pattern is most visible in Indian urban agglomerations where national contractors centralize material sourcing.
Concrete and Cement Market Segmentation
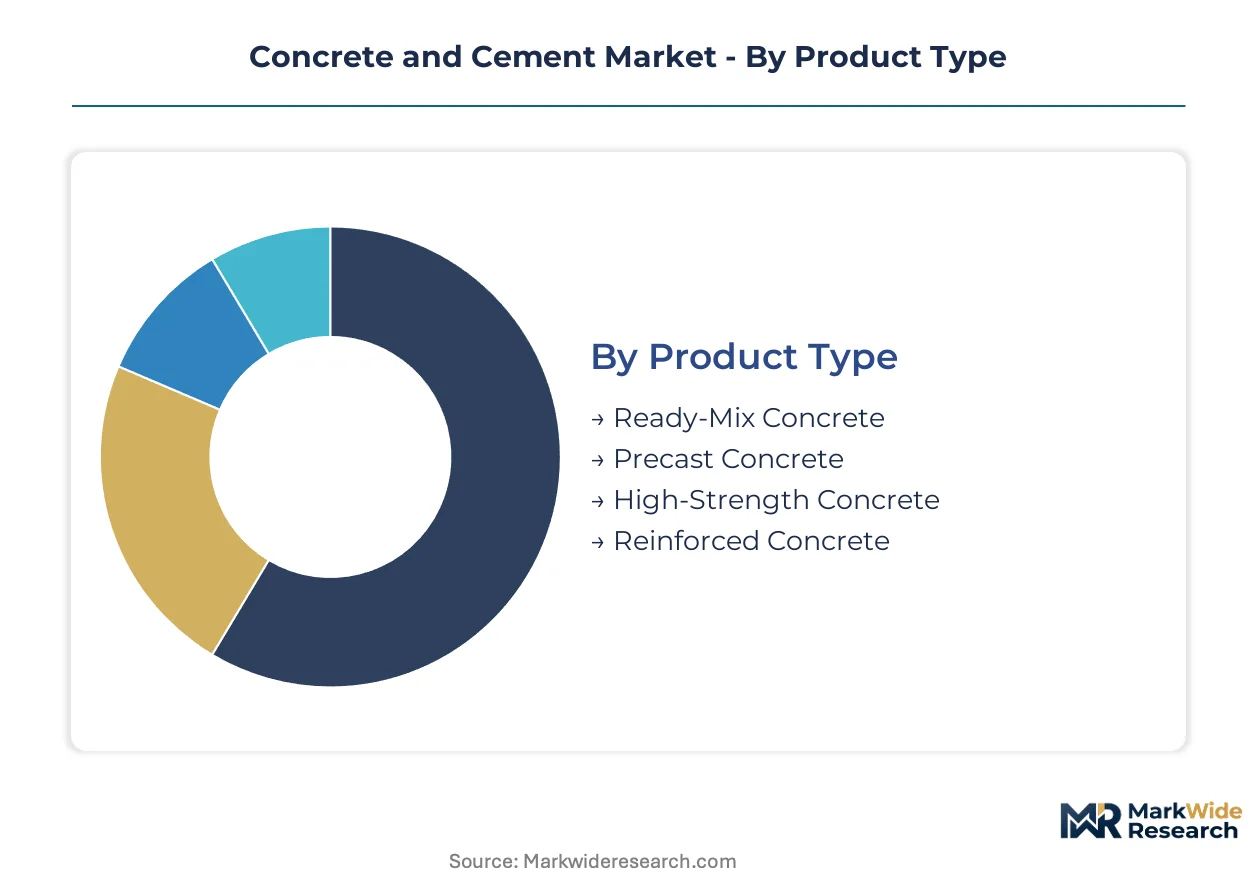
Concrete and cement markets fragment across production methods, construction phases, and procurement channels. Each segment demands distinct capital deployment, logistics infrastructure, and technical certification. Producers align manufacturing assets to capture volume concentration in infrastructure while defending margin in specialized precast applications.
Product Type:
Capital intensity peaks in ready-mix networks requiring fleet and batch plant density, while precast demands mold fabrication and curing infrastructure.
- Ready-Mix Concrete:Batch-controlled production at dedicated plants enables just-in-time delivery to active construction sites. Demand concentrates in Indian metropolitan corridors where UltraTech Cement and national infrastructure programs expand distribution depth. Fleet utilization rates and slump testing protocols determine competitive position.
- Precast Concrete:Factory-cured structural elements achieve dimensional precision through controlled curing environments and steel formwork systems. Bridge and highway contractors in Germany and Poland specify precast girders for accelerated construction schedules. EU Carbon Border Adjustment Mechanism compliance costs favor domestic precast over imported alternatives.
- High-Strength Concrete:Mix designs exceeding 50 MPa compressive strength serve seismic-resistant structures and high-rise cores.
- Reinforced Concrete:Steel rebar integration dominates foundational and load-bearing applications across residential and commercial verticals.
Most installed capacity flows through Ready-Mix Concrete. Expansion is steepest in Precast Concrete.
End User:
Procurement scale and payment terms vary sharply across customer categories, from fragmented residential builders to consolidated infrastructure agencies.
- Infrastructure Development:Multi-year government contracts for bridge, highway, and utility projects sustain the highest volume throughput. India's National Highways Authority and Indonesia's toll road authorities specify performance-graded concrete with extended warranty terms. Procurement cycles extend 24-48 months, locking in supplier relationships early.
- Commercial Construction:Office towers, retail complexes, and logistics facilities demand consistent supply continuity for accelerated structural schedules. German and French general contractors centralize sourcing through single-source ready-mix agreements to reduce quality variance. LEED and BREEAM certification requirements drive low-carbon concrete specification.
- Residential Construction:Single-family and multi-family housing projects exhibit fragmented demand across thousands of small contractors.
- Industrial Projects:Manufacturing facilities and energy infrastructure require specialized flooring and containment specifications.
Volume concentrates in Infrastructure Development. Margin expansion is strongest in Commercial Construction.
Application:
Technical performance standards diverge across structural use cases, with seismic and load-bearing specifications demanding premium mix designs.
- Bridge Construction:Prestressed and post-tensioned concrete elements must achieve 50+ year durability ratings against chloride ingress and freeze-thaw cycling. US state transportation departments enforce AASHTO specifications that limit approved supplier pools. Carbon capture-enabled cement qualifies for federal infrastructure funding preference under US IRA provisions.
- Building Construction:Vertical structural elements combine ready-mix columns with precast floor plates to accelerate enclosure schedules. Indian urban agglomerations drive demand as national contractors consolidate material sourcing for high-rise residential towers. Building code adoption of EN 206 and IS 456 standards harmonizes quality expectations.
- Road Construction:Pavement concrete emphasizes flexural strength and surface durability for heavy vehicle loading.
- Flooring:Industrial and commercial slabs require flatness tolerances and abrasion resistance specifications.
Bridge Construction commands the highest specification premiums. Building Construction generates the largest absolute tonnage.
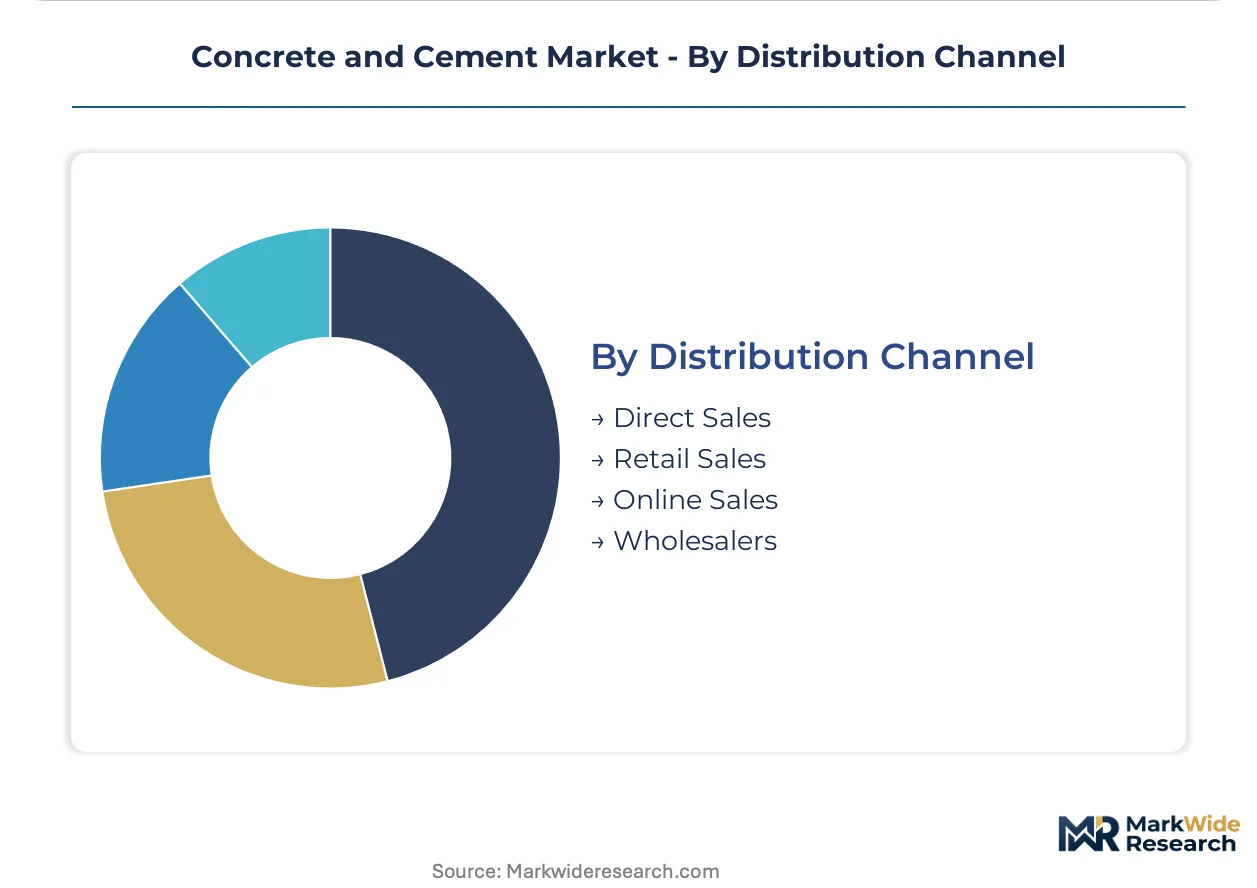
Distribution Channel:
Channel economics reflect customer scale, with direct sales capturing institutional volume and retail serving fragmented repair and renovation demand.
- Direct Sales:Long-term supply agreements with national contractors, infrastructure agencies, and ready-mix operators lock in volume commitments. Heidelberg Materials leverages quarry-to-site vertical control across European markets to secure direct relationships. Contract terms specify price adjustment clauses tied to energy and clinker input costs.
- Wholesalers:Regional distributors aggregate bagged cement and specialty concrete products for mid-sized construction firms. Inventory holding requirements and credit extension capabilities filter competitive participation. Indian and Southeast Asian markets retain substantial wholesaler penetration due to contractor fragmentation.
- Retail Sales:Hardware and construction supply stores serve renovation contractors and small-scale builders.
- Online Sales:Digital procurement platforms emerge for standardized bagged products and project estimation tools.
Direct Sales channels capture the majority of institutional volume. Wholesalers retain importance in fragmented construction markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr industrial corridor anchors European cement production, while emerging Asian markets drive absolute volume expansion through infrastructure-led procurement.
United States
Bridge reconstruction and federal infrastructure spending sustain ready-mix demand across the Midwest and Southeast. The EPA enforces National Emission Standards for Hazardous Air Pollutants at Portland cement kilns, compelling emission control investments. Texas and California clusters concentrate production capacity near limestone formations and coastal import terminals.
Germany
Precast concrete specification dominates highway and commercial verticals as contractors accelerate construction schedules. The EU F-Gas Regulation imposes phasedown timelines on cement plant cooling systems, diverting capital toward industrial refrigeration retrofits. The North Rhine-Westphalia and Bavaria regions host integrated quarry-to-plant operations with deep ready-mix penetration.
India
National highway programs and urban high-rise construction concentrate demand in Maharashtra, Gujarat, and Karnataka. The Bureau of Indian Standards enforces IS 456 quality protocols for structural concrete, harmonizing construction code expectations. UltraTech Cement anchors manufacturing scale across the subcontinent with distribution depth in metropolitan corridors.
China
Clinker capacity caps and alternative fuel mandates reshape production economics under dual carbon goals enforced by the Ministry of Ecology and Environment. The Yangtze River Delta and Pearl River Delta regions consolidate cement grinding capacity near coastal demand centers while inland kilns face utilization pressure.
Indonesia
Toll road authorities and port expansion projects sustain multi-year concrete procurement cycles across Java and Sumatra. National infrastructure programs specify performance-graded mixes with extended warranty terms. Jakarta and Surabaya agglomerations concentrate ready-mix batch plant density to serve consolidated contractor sourcing.
Concrete and Cement Market Vendor Landscape
Global majors compete with regional champions across production scale and distribution depth, creating a tiered structure where integrated quarry-to-plant operators hold cost advantages over import-dependent grinding facilities. The vendor base clusters around three strategic archetypes: vertically integrated multinationals with limestone captive supply, national champions with government contract access, and specialized precast fabricators with mold fabrication expertise. Dominant competitive moves include kiln emissions abatement retrofitting to qualify for carbon border adjustment compliance and ready-mix fleet expansion to capture urban infrastructure volume.
Among European-integrated operators, Heidelberg Materials exemplifies quarry-to-site vertical control across Rhine-Ruhr and Bavarian markets. UltraTech Cement occupies a position as the scale-driven national champion with manufacturing concentration across the Indian subcontinent. CRH and Holcim Group sit within the multinational tier, anchoring diversified geographic portfolios that span developed and emerging construction markets.
| Leading Market Players |
|---|
| CRH |
| Holcim Group |
| Heidelberg Materials |
| UltraTech Cement |
| Cemex |
| Anhui Conch Cement |
| CNBM |
| Buzzi Unicem |
| Siam Cement Group |
| Others |
Supply Flow & Price Mechanics
Family-owned quarry operators across the Indian subcontinent and Mediterranean basin anchor limestone supply, translating captive mineral access into pricing discipline that resists spot-market volatility. Their multi-generational holding structures prioritize long-term contract security over quarterly margin optimization, creating regional price floors that multinational producers must match or exit.
Pricing Analysis
Input-cost pass-through dominates cement pricing, with energy and clinker costs flowing directly into contract adjustment clauses. Pricing stratifies across premium low-carbon certified, standard blended, and economy bulk grades, with EU Carbon Border Adjustment Mechanism compliance adding tier separation. Pricing pressure stems from natural gas cost spikes in European kiln operations, compressing margins at import-dependent grinding facilities. Infrastructure agencies exhibit lowest price sensitivity due to multi-year procurement locks, while residential contractors face acute margin pressure from spot market exposure.
Supply Chain Analysis
Dual-sourcing requirements from German and French infrastructure agencies mandate qualified backup suppliers for critical bridge and highway projects, preventing single-source concentration. Supply concentrates in China, India, and Vietnam for clinker and grinding capacity, with limestone feedstock drawing from captive quarries in Rajasthan, Guangdong, and Thanh Hoa provinces. Single-source vulnerability runs through high-purity calcium carbonate deposits concentrated in specific geographies. Distribution runs through direct sales to national contractors, with ready-mix fleet density determining urban market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Concrete and Cement Market functions as a regulatory compounder, where EU Carbon Border Adjustment Mechanism enforcement is restructuring import economics and rewarding early decarbonizers with preferential market access.
For Market Incumbents: Deepen alternative fuel co-processing capabilities at coastal kilns to secure EU compliance before tariff activation locks out carbon-intensive imports. Anchor position through backward integration into calcined clay supply chains, locking in LC3 formulation inputs that competitors cannot replicate. Geopolymer binder substitution represents the most credible technology threat to traditional Portland cement volumes. For New Entrants and Emerging Players: Capture ready-mix penetration gaps in informal construction markets across Lagos, Nairobi, and Dhaka, where site-mixed concrete quality inconsistencies create service differentiation openings. Mobile batching units with slump-testing certification offer the most penetrable go-to-market angle, bypassing fixed-plant capital requirements that block incumbent expansion. For Investors and Strategic Acquirers: Valuations sit cheapest among import-dependent grinding facilities facing carbon border adjustment exposure, creating distressed acquisition targets with retrofit optionality. Long-term viability hinges on kiln emissions abatement execution within the medium-term regulatory window. Watch EU Innovation Fund disbursement velocity as the inflection signal for carbon capture project economics.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofitting | Post-combustion systems at Heidelberg Materials kilns qualify for EU Innovation Fund credits and offtake agreements. |
| Calcined Clay Integration | LC3 formulation adoption by European precast manufacturers reduces clinker intensity while maintaining EN 206 compliance. |
| Alternative Fuel Infrastructure | Co-processing systems at Indian and Chinese facilities lower Scope 1 emissions under Ministry of Ecology and Environment mandates. |
| Ready-Mix Fleet Expansion | UltraTech Cement density in Maharashtra and Gujarat corridors captures National Highways Authority volume commitments. |
| Direct Sales Channel Control | Vertical quarry-to-site relationships across Rhine-Ruhr markets lock in German infrastructure agency procurement. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with plant operations directors, procurement leads at ready-mix operators, infrastructure agency specification engineers, and alternative fuel technology providers anchored demand-side intelligence. Secondary sources included EPA emission compliance filings, EU ETS carbon price data, Bureau of Indian Standards certification records, and customs trade statistics for clinker and cementitious materials. Bottom-up volume modeling triangulated against top-down macro construction spend data.
Granularity-level modeling operated at product type, end-user category, and application dimensions, with additional disaggregation by regional regulatory cluster and kiln fuel type. CAGRs derived from regression analysis against construction output indices and infrastructure budget appropriations across the projection horizon. Forecast inputs incorporated clinker substitution rates, alternative fuel penetration curves, and carbon border adjustment implementation timelines.
Underlying measurement precision varies by segment; ready-mix concrete volume carries tighter precision than emerging geopolymer binder categories due to established reporting infrastructure. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and infrastructure budget execution. Deviation in EU Carbon Border Adjustment Mechanism tariff calibration or Chinese dual carbon goal acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Natural Stone Market
Building Materials
Mass Timber Construction Market
Building Materials
Fiber Cement Market
Building Materials
France Architectural Coatings Market
Building Materials
Global Lightweight Aggregate Concrete Market
Building Materials
Southeast Asia Concrete Admixtures Market
Building Materials
Construction Repair Composites Market
Building Materials
Gravity Retaining Wall Market
Building Materials
China Cement Market
Building Materials
Portland Cement Market
Building Materials
Radiant Barriers and Reflective Insulation Market
Building Materials
North America Spray Polyurethane Foam for Building and Construction Market
Building Materials
India Aluminum Door and Window Market
Building Materials
Global Pozzolan Market
Building Materials
Australia Architectural Coatings Market
Building Materials
Fly Ash Bricks Market