
 Fire Resistant Mortar Market | 2026-2036
Fire Resistant Mortar Market Size, Share, and Industry Trends Forecast 2026-2036
Fire Resistant Mortar Market Foresight
REACH compliance is decoupling small-scale producers from premium specification tiers across European construction supply chains. BASF SE leverages its integrated binders portfolio to control raw material quality for hydraulic mortar formulations. Sika SE anchors its position through specialized distribution partnerships with firestop system installers. Morgan Advanced Materials competes on refractory-grade mineral expertise inherited from aerospace thermal protection programs.
Fire resistant mortar is a cementitious or gypsum-based compound engineered to maintain structural integrity at temperatures exceeding 1000°C, typically achieving fire ratings between one and four hours depending on thickness and substrate configuration. Its primary purpose is sealing penetrations, joints, and gaps in fire-rated assemblies to prevent flame propagation and smoke migration between compartments. Hydraulic mortar dominates specification for high-load commercial foundations where moisture resistance and thermal stability must coexist, while premixed mortar captures share among contractor segments prioritizing field consistency and reduced mixing labor. Thin-set mortar occupies a narrower but higher-margin niche in retrofit applications where minimal added weight and dimensional constraints govern material selection.
EMA construction product assessments, ECHA substance restrictions on crystalline silica content, and national building codes enforced by Germany's KBA-equivalent state construction authorities collectively elevate testing documentation requirements for market access. These frameworks shift procurement criteria toward third-party-certified systems rather than commodity mortar purchases. Stakeholders must monitor evolving reaction-to-fire classification harmonization between EU member states and emerging demands for Environmental Product Declarations ahead of CSRD-aligned supply chain disclosures.
Market Dynamics
EU Construction Products Regulation harmonization is compressing specification timelines while elevating third-party certification requirements, forcing procurement departments to abandon commodity mortar purchasing for system-certified solutions.
Growth Catalysts
- High-rise commercial development:Fire-rated joint system specifications are expanding across multi-story residential and office towers in Germany and France.
- REACH compliance tiering:Regulatory decoupling of small-scale producers from premium specification tiers is consolidating qualified supplier pools.
- Crystalline silica restrictions:ECHA substance limitations on hazardous content are accelerating reformulation investments toward safer binder chemistries.
Market Restraints
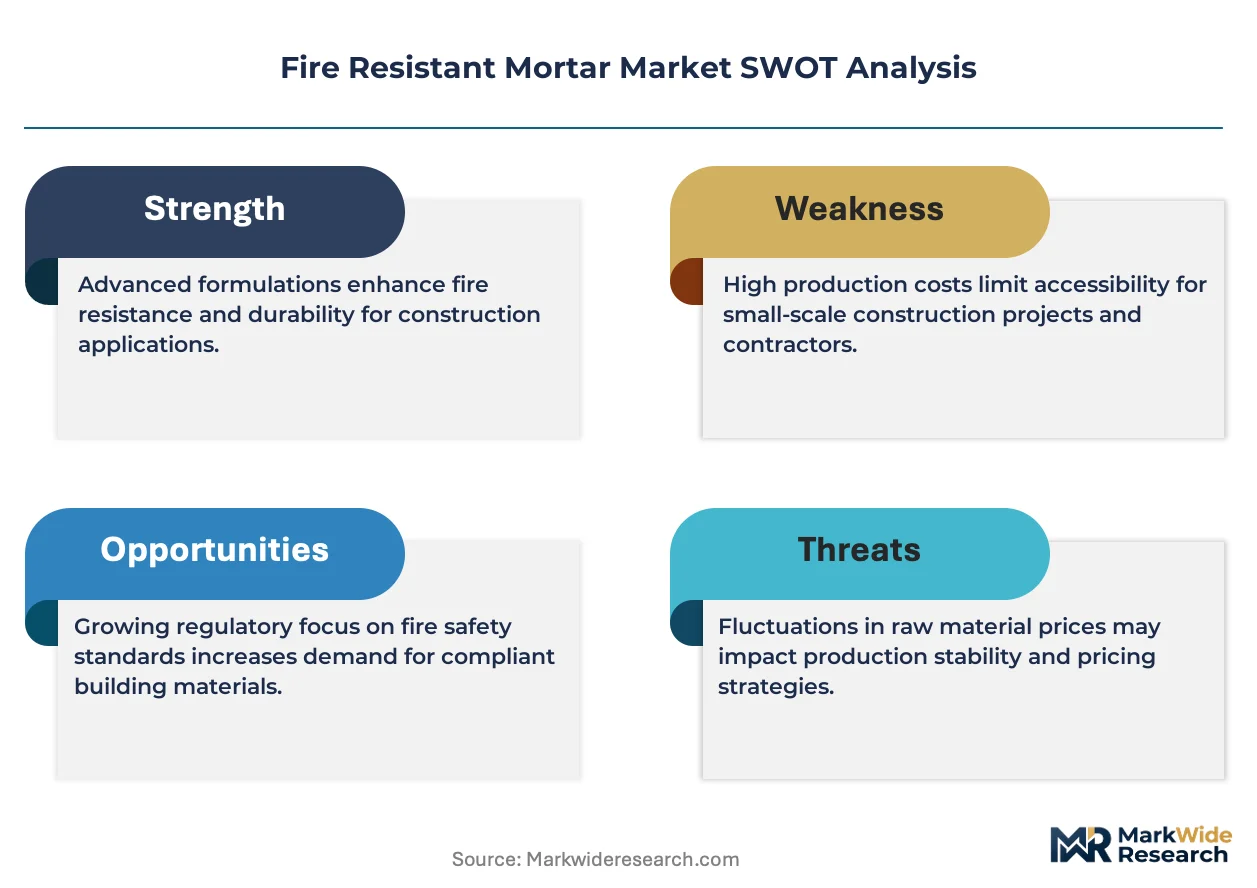
- Refractory mineral supply concentration:Specialty alumina-silicate sourcing clusters in limited extraction regions create input vulnerability.
- Hydraulic binder cost volatility:Portland cement and calcium aluminate price swings compress margin stability for formulation-dependent producers.
- Reaction-to-fire testing fragmentation:Divergent national interpretations of EN 13501-2 protocols extend certification timelines and duplicate expenses.
Strategic Opportunities
- Renovation cycle acceleration:Aging building stock across the United Kingdom creates retrofit specification volume for thin-set mortar applications.
- CSRD-aligned supply chain disclosures:Environmental Product Declaration mandates ahead of corporate sustainability reporting requirements favor documented low-carbon formulations.
- Premixed mortar channel expansion:Direct contractor supply relationships bypass traditional distributor markups while capturing field-consistency premiums.
Industry Challenges
- Firestop system installer certification gaps:Shortage of qualified applicators trained to EN 1366-3 penetration sealing standards delays project completion.
- Legacy substrate compatibility testing:Uncertainty around adhesion performance on aged concrete and masonry surfaces requires extensive pre-qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fire Resistant Mortar Market |
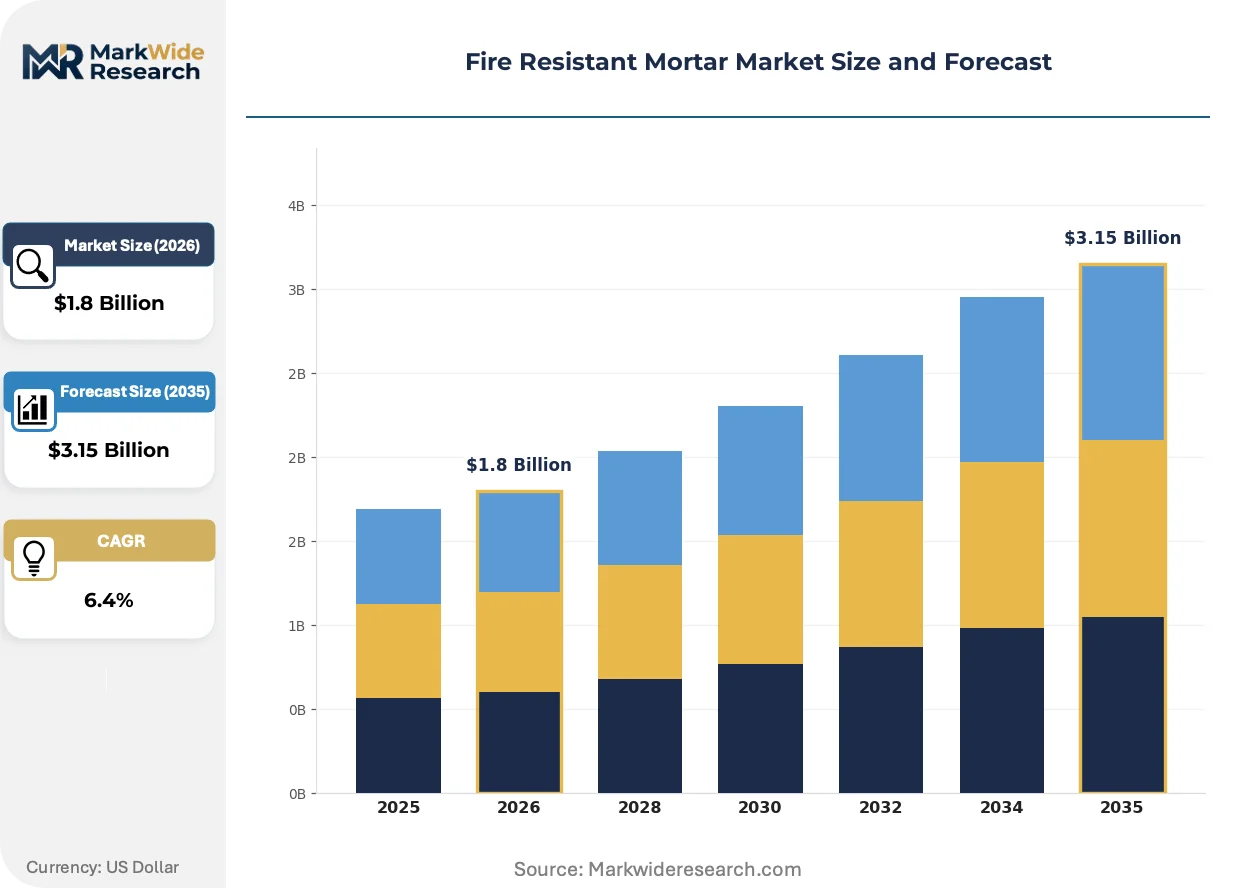
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Mortar, Thin-Set Mortar, Premixed Mortar, Repair Mortar Application: Residential Construction, Commercial Construction, Industrial Applications, Fireproofing End User: Contractors, Builders, Architects, Engineers Distribution Channel: Online Sales, Retail Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | 3M, Hilti Group, Sika AG, Morgan Advanced Materials, AkzoNobel N.V., BASF SE, ETEX, Specified Technologies Inc, Rolf Kuhn GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fire Resistant Mortar Market Shifts & Advancements
Specification workflows are digitizing while material chemistries evolve toward lower-carbon binders, compressing traditional competitive advantages rooted in formulation secrecy alone.
Prefabricated firestop module systems are modularizing installation processes for cable and pipe penetration assemblies. MEP contractors in high-rise developments are specifying these units to reduce field labor hours and eliminate mixing variability. The technology is modularizing competitive positioning away from raw material suppliers toward system integrators controlling installation certification.
REACH authorization requirements for crystalline silica are tightening occupational exposure limits across EU member states. Formulators must demonstrate substitution feasibility or secure time-limited authorizations for continued use. Hydraulic mortar producers are accelerating alternative binder development, with Germany's KBA-equivalent state construction authorities enforcing documentation standards.
Buyer consolidation among European facilities management groups is compressing supplier rosters toward multi-product system providers. Single-product mortar vendors face exclusion from framework agreements covering integrated passive fire protection. Facility management procurement in France and the Netherlands is most advanced in this consolidation pattern.
Fire Resistant Mortar Market Segmentation
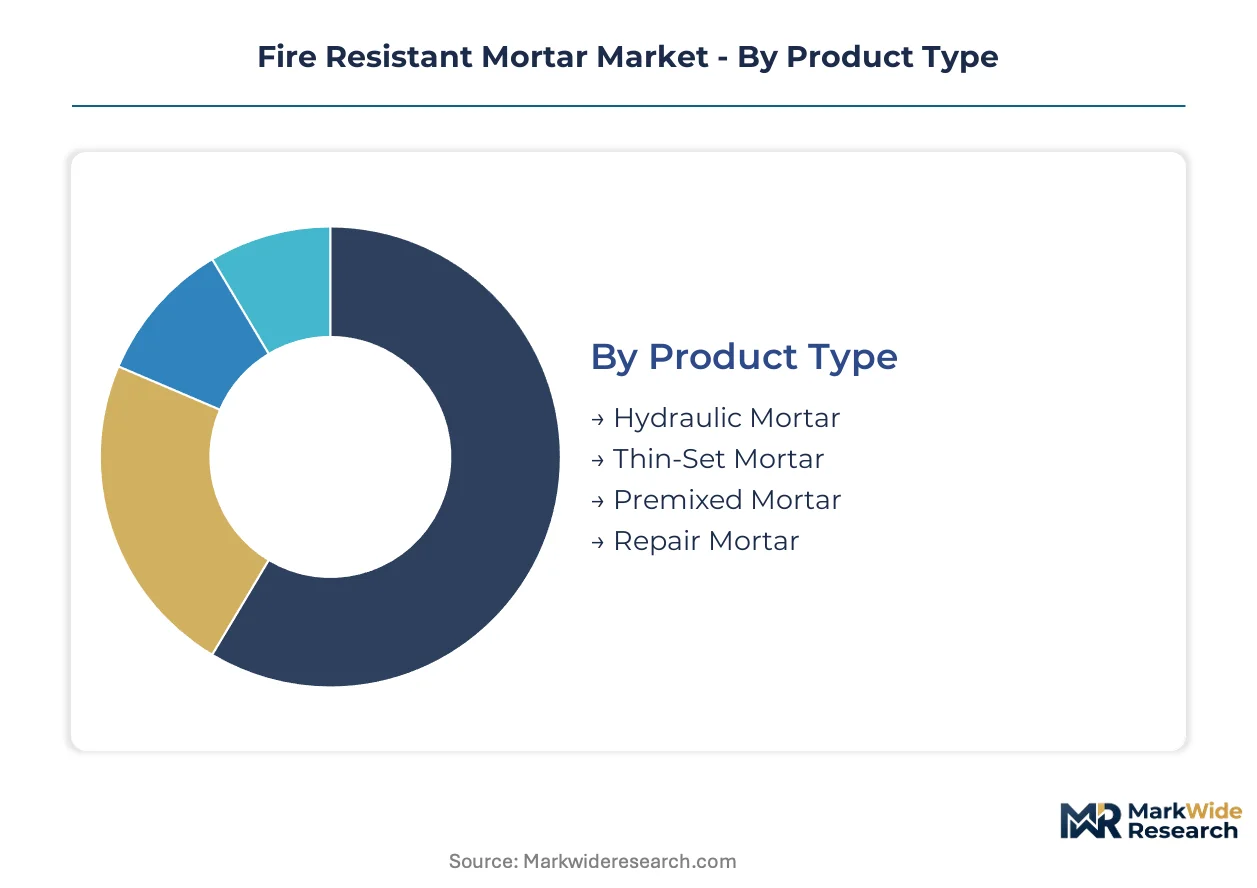
Fire resistant mortar specification diverges sharply across load-bearing requirements, installation constraints, and procurement workflows. Procurement departments select product formats based on project scale, substrate condition, and labor availability rather than material performance alone.
Product Type:
Technology and specification requirements govern selection across structural load, moisture exposure, and field preparation capabilities.
- Hydraulic Mortar:Cementitious formulations incorporating calcium aluminate or Portland cement binders deliver compressive strength exceeding structural fire-rated assemblies in high-load commercial foundations across Germany. REACH crystalline silica restrictions are forcing reformulation investments toward alternative binder chemistries.
- Premixed Mortar:Factory-blended compounds eliminate on-site mixing variability and reduce skilled labor requirements. Demand concentrates among French contractor segments prioritizing installation speed and documentation consistency for third-party certification.
- Thin-Set Mortar:Lightweight compounds applied in minimal thickness govern retrofit specifications where dimensional constraints and added weight limits apply.
- Repair Mortar:Specialized formulations restore fire-rated integrity to degraded concrete and masonry substrates in aging United Kingdom building stock.
Mature deployment sits with Hydraulic Mortar. Newer deployment is concentrated in Premixed Mortar.
Application:
Construction verticals impose distinct fire rating durations, compartmentation complexity, and regulatory scrutiny levels.
- Commercial Construction:High-rise office and residential towers in France and Germany specify multi-hour fire-rated joint systems for vertical and horizontal compartmentation. EU Construction Products Regulation harmonization compresses procurement timelines toward pre-certified system solutions.
- Fireproofing:Penetration sealing and gap-filling applications protect structural steel and cable runs. United Kingdom infrastructure renewal drives specification volume for passive fire protection upgrades.
- Industrial Applications:Petrochemical and power generation facilities demand refractory-grade performance at extreme temperatures.
- Residential Construction:Single-family and low-rise multi-family projects apply simplified fire-rated assemblies with shorter rating requirements.
Commercial Construction absorbs the largest specification volume. Fireproofing applications are gaining share fastest.
End User:
Professional role determines information requirements, certification accountability, and procurement authority within project workflows.
- Contractors:Installation firms execute specification compliance and maintain EN 1366-3 penetration sealing certifications. Shortage of qualified applicators delays project completion across high-rise developments.
- Architects:Design professionals specify system-certified solutions rather than commodity mortar to satisfy EU Construction Products Regulation documentation requirements.
- Builders:Construction management entities coordinate material procurement across multi-trade firestop installations.
- Engineers:Structural and fire protection engineers validate thermal performance calculations and substrate compatibility.
Contractors control installation execution. Architects are shifting procurement criteria toward integrated system providers.
Distribution Channel:
Channel selection reflects order scale, technical support requirements, and documentation needs for regulatory compliance.
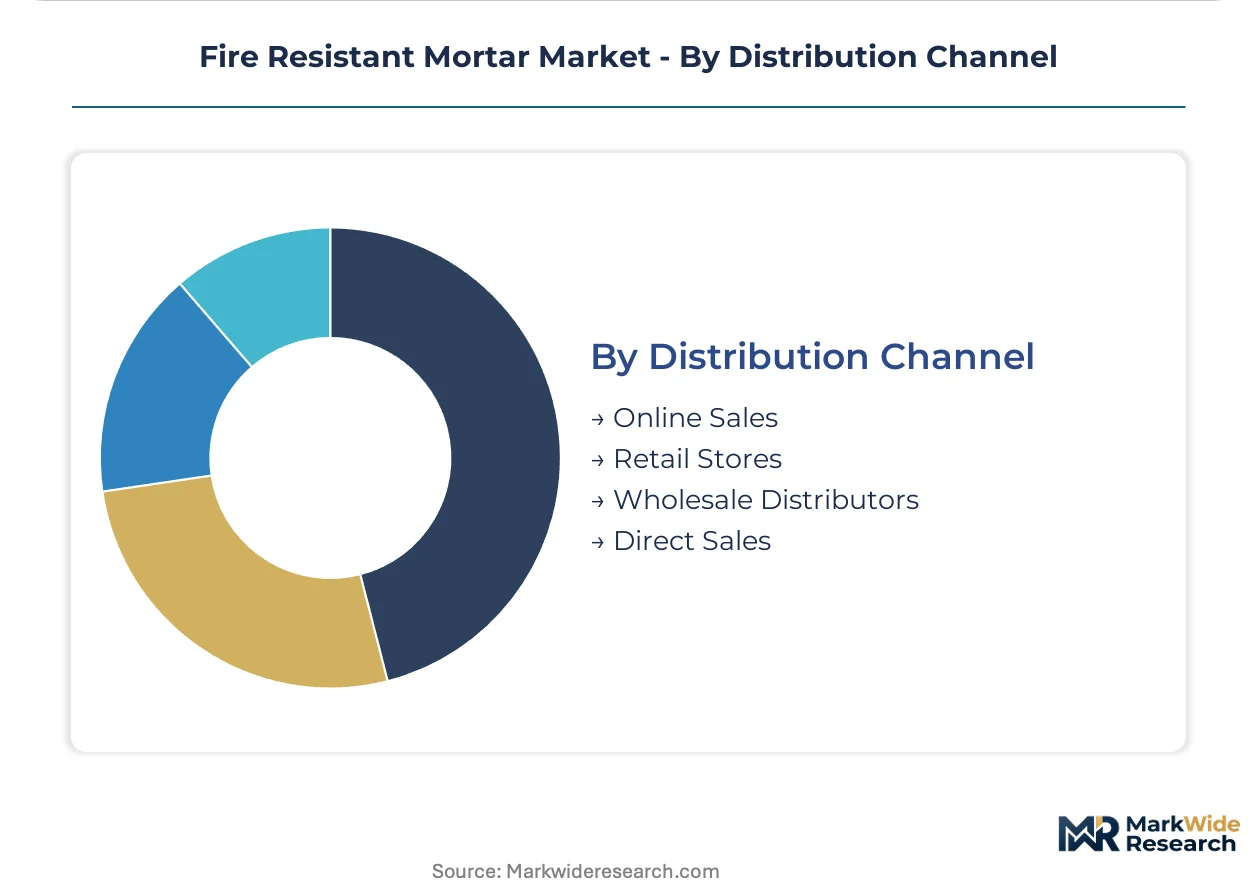
- Wholesale Distributors:Regional building material suppliers aggregate multiple product lines and provide logistics coordination for large-scale commercial projects across Germany.
- Direct Sales:Manufacturer-contractor relationships bypass distributor markups and capture field-consistency premiums for premixed mortar formats.
- Retail Stores:Localized outlets serve small-scale repair and residential applications with limited technical consultation.
- Online Sales:Digital procurement channels facilitate specification documentation access and comparison shopping for standardized product grades.
Wholesale Distributors anchor commercial project supply. Direct Sales channels are expanding fastest among contractor segments prioritizing premixed formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for construction materials manufacturing in Germany's North Rhine-Westphalia and China's Yangtze River Delta concentrate fire-resistant mortar production capacity. These zones offer accelerated permitting for REACH-compliant formulation facilities. Tax incentives for green building material production are reshaping investment flows toward certified low-carbon binder operations.
Germany
High-rise residential towers in Frankfurt and Munich drive specification volume for multi-hour fire-rated joint systems. State construction authorities enforce documentation standards under the EU Construction Products Regulation for all commercial penetration sealing. The Ruhr industrial corridor hosts formulation plants serving renovation cycles across aging building stock in North Rhine-Westphalia.
France
Commercial developments in Paris La Défense and Lyon Confluence specify system-certified solutions rather than commodity mortar purchases. ANSM-equivalent building material regulators coordinate with ECHA on crystalline silica exposure limits for construction workers. Facility management procurement consolidation in Île-de-France favors multi-product passive fire protection providers.
United Kingdom
Infrastructure renewal programs and high-rise remediation projects create retrofit demand for thin-set mortar applications. National building codes enforced by local authorities mandate third-party certification for firestop installations in commercial buildings. The Midlands manufacturing belt supplies repair mortar formulations for concrete substrate restoration in aging urban centers.
China
Mega-infrastructure projects in Shanghai and Shenzhen specify fire-rated assemblies for transportation hubs and commercial complexes. GB standards for construction fire safety are tightening testing protocols for reaction-to-fire classifications. The Yangtze River Delta industrial cluster concentrates calcium aluminate binder production for hydraulic mortar exports.
United States
High-rise commercial construction in New York and Chicago expands specification of fire-rated joint systems for vertical compartmentation. OSHA enforces occupational exposure limits for crystalline silica in mortar mixing operations. The Gulf Coast petrochemical corridor demands refractory-grade mortar for industrial fireproofing applications at extreme temperatures.
Fire Resistant Mortar Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across specification tiers in the fire-resistant mortar market. The vendor base organizes around three strategic archetypes: integrated chemical conglomerates controlling binder supply chains, specialized construction material firms with installation certification networks, and refractory-grade mineral experts leveraging aerospace thermal protection heritage. Dominant competitive moves include strategic partnerships with firestop system installers and portfolio diversification into prefabricated penetration sealing modules.
Within the diversified chemical tier, BASF SE and Sika AG exemplify integrated binder-to-formulation control. Morgan Advanced Materials occupies a position among refractory-grade specialists. These three anchors represent distinct competitive vectors: chemical supply chain integration, specialized distribution partnership networks, and high-temperature mineral expertise respectively.
| Leading Market Players |
|---|
| 3M |
| Hilti Group |
| Sika AG |
| Morgan Advanced Materials |
| AkzoNobel N.V. |
| BASF SE |
| ETEX |
| Specified Technologies Inc |
| Rolf Kuhn GmbH |
| Others |
Supply & Pricing Matrix
Calcium aluminate cement price indices cascade through hydraulic mortar formulations, compressing margins for producers lacking captive binder supply while amplifying pricing power for integrated chemical conglomerates controlling upstream alumina refining.
Pricing Analysis
Expedited lead-time premiums separate contractor procurement tiers, with EN 1366-3 certified premixed mortar commanding substantial markups for just-in-time delivery against spot-market hydraulic binder pricing for bulk foundation work. Three-tier pricing structure across system-certified, third-party-validated, and commodity-grade levels reflects certification depth and documentation burden. Cost compression in standard-grade hydraulic mortar intensifies as REACH crystalline silica reformulation expenses accumulate. Small-scale contractors exhibit acute price sensitivity, while facilities management groups prioritize total installation cost over unit material pricing.
Supply Chain Analysis
Qualified applicator shortages across Germany's Ruhr industrial corridor and France's Île-de-France constrain formulation plant throughput regardless of raw material availability. Manufacturing gravity centers on Germany, China, and the United States, with specialty alumina-silicate refractory minerals drawing from concentrated Australian and Chinese extraction basins. Single-source vulnerability pervades calcium aluminate binder supply, where limited European production capacity hinges on Asian intermediate feedstock. Distribution runs through wholesale distributors anchoring commercial project logistics, though direct manufacturer-contractor channels expand for premixed mortar formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration momentum defines competitive positioning, with binder supply control emerging as the decisive margin lever separating integrated conglomerates from formulation-dependent specialists.
For Market Incumbents: Hedge crystalline silica exposure by accelerating alternative binder R&D partnerships ahead of ECHA authorization deadlines. Secure multi-year calcium aluminate offtake agreements to dampen input cost volatility threatening hydraulic mortar profitability. Backward integration into specialty alumina-silicate sourcing mitigates refractory mineral concentration risk. For New Entrants and Emerging Players: Prefabricated firestop module technology offers entry path into high-rise commercial specifications without competing against entrenched mortar formulation expertise. Target United Kingdom retrofit applications where thin-set mortar demand outpaces qualified domestic supply. Pursue direct contractor certification programs to bypass wholesale distributor gatekeeping. For Investors and Strategic Acquirers: Distressed-cycle entries favor refractory-grade mineral specialists with aerospace thermal protection heritage in German manufacturing clusters. Five-to-ten year viability hinges on CSRD-aligned Environmental Product Declaration capabilities ahead of corporate sustainability reporting mandates. Monitor ECHA crystalline silica authorization timelines as inflection trigger for reformulation investment surges.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Binder Supply | Captive calcium aluminate production insulates margin stability against commodity price swings. |
| Prefabricated Firestop Module Development | Modular penetration sealing displaces field-mixed mortar in high-rise MEP specifications. |
| Installer Certification Network Expansion | EN 1366-3 qualified applicator pipelines accelerate project completion and specification capture. |
| Environmental Product Declaration Investment | CSRD-aligned documentation secures framework agreements with consolidating facilities management groups. |
| Alternative Binder Chemistry Partnership | REACH-compliant formulations decouple from crystalline silica exposure limits ahead of regulatory deadlines. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with firestop system installers, construction procurement managers, formulation plant engineers, and passive fire protection consultants. ECHA substance restriction databases, EU Construction Products Regulation harmonization documents, and national building code enforcement records provided regulatory trajectory validation. Bottom-up project pipeline assessments triangulated against top-down construction spending forecasts across commercial verticals.
Segmentation outputs reconciled shipment volumes, specification frequencies, and installed-base renewal cycles across the projection horizon. Modeled dimensions span product format, application vertical, end-user professional role, and distribution channel, with regional regulatory cluster overlays for reaction-to-fire classification harmonization. CAGRs derived from elasticity-adjusted demand curves incorporating renovation cycle acceleration and high-rise development permitting trends.
Forecast precision tightens around the base case; tail outcomes carry wider variance under crystalline silica substitution breakthroughs or ECHA authorization timeline extensions. Material deviation in REACH enforcement intensity or EU member state reaction-to-fire protocol harmonization warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Middle East and Africa Concrete Admixtures Market
Building Materials
Cellular Concrete Market
Building Materials
Dry Mix Mortar Market
Building Materials
India Construction Ornamental Stone Market
Building Materials
Global FRP Rebar Market
Building Materials
ASEAN Dry Mix Mortar Market
Building Materials
Stone Coated Steel Roofing Market
Building Materials
US Contract Glazing Market
Building Materials
Granite Market
Building Materials
Global Corrugated Steel Sheets Market
Building Materials
Timber Frames Market
Building Materials
UK Aluminum Door and Window Market
Building Materials
Europe Exterior Sheathing Market
Building Materials
Roofing and Tile Underlayment Market
Building Materials
Fly Ash Bricks Market
Building Materials
Foam Bricks Market