
 Dutch Brick Market | 2026-2036
Dutch Brick Market Size, Share, and Industry Trends Forecast 2026-2036
Dutch Brick Market Insights
Belgium's cross-border clay extraction expansion is reconfiguring raw material flows into Dutch manufacturing corridors. Wienerberger leverages its vertically integrated quarry-to-kiln network to sustain cost discipline across the Benelux. Excluton anchors premium facade supply through specialized color and texture ranges for architect-specified projects. Daas Baksteen Zeddam competes on heritage restoration authenticity, controlling niche specification channels for monument conservation.
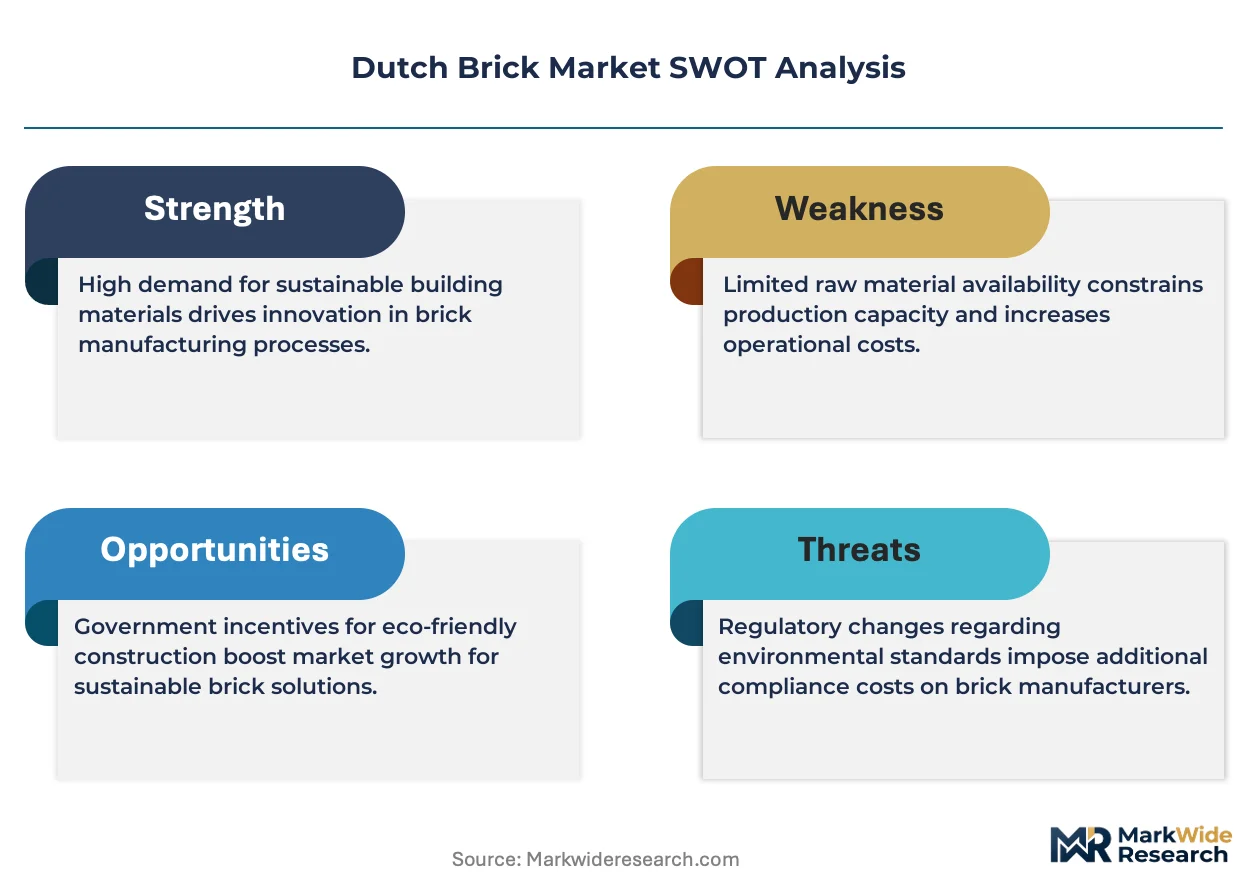
Dutch bricks are fired clay or concrete masonry units, typically measuring 210 by 100 by 50 millimeters, engineered for compressive strengths exceeding 20 N/mm² in structural applications and thermal performance in cavity wall assemblies. Their primary purpose is to provide load-bearing capacity, moisture resistance, and aesthetic finish in building envelopes across residential and commercial construction. Clay bricks dominate heritage-sensitive applications where color stability and breathability command specification loyalty, while concrete bricks capture volume-driven residential foundations and utility structures through cost efficiency. Hollow and perforated forms lead growth trajectories as thermal bridging regulations tighten, with modular formats gaining share among prefabrication-oriented contractors seeking site labor reduction.
The Netherlands Building Decree (Bouwbesluit) mandates escalating energy performance coefficients, while CE marking under the EU Construction Products Regulation enforces harmonized structural and fire-safety testing. BIS standards alignment for imported materials and the EU Green Deal's carbon border adjustments progressively filter market access for non-compliant suppliers. Stakeholders must monitor embodied carbon disclosure thresholds and kiln fuel-switching economics as natural gas phase-out deadlines approach in Dutch industrial policy.
Market Dynamics
The Netherlands Building Decree's tightening energy performance coefficients are compressing specification windows for masonry products, forcing manufacturers to reengineer thermal properties while maintaining structural integrity and heritage aesthetics.
Growth Catalysts
- EU Green Deal embodied carbon mandates:The Construction Products Regulation's carbon disclosure thresholds are elevating demand for low-carbon kiln technologies and bio-based firing fuels among Dutch housing associations.
- Heritage restoration specifications:Monument conservation authorities in Utrecht and Amsterdam are mandating authentic clay brick matches for protected facades, creating specification-locked demand channels.
- Prefabricated wall systems:Modular construction contractors are specifying hollow perforated bricks for reduced site labor and accelerated envelope assembly in Randstad residential towers.
Market Restraints
- Natural gas phase-out economics:Dutch industrial policy deadlines for kiln fuel switching are imposing capital intensity burdens on mid-scale producers without captive renewable energy contracts.
- Belgian clay extraction concentration:Cross-border raw material flows through Flemish quarries are creating supply vulnerability exposure for non-vertically integrated Dutch manufacturers.
- Concrete masonry substitution:Cost-driven residential foundation segments are specifying concrete bricks for utility structures where thermal performance requirements remain minimal.
Strategic Opportunities
- Carbon border adjustment positioning:The EU Green Deal's import filtering mechanisms are creating first-mover advantage for Dutch producers with verified embodied carbon documentation.
- Smart facade integration:Converging masonry units with embedded sensor networks and phase-change materials is opening specification channels in high-performance commercial envelopes.
- Regional housing association retrofit programs:Energy-efficient cavity wall upgrades across South Holland and North Brabant social housing stocks are concentrating demand for thermally optimized brick systems.
Industry Challenges
- Kiln engineering talent scarcity:Specialized expertise in hydrogen-fired and electric kiln conversion is concentrating among a shrinking cohort of Dutch ceramic engineers.
- CE marking compliance timelines:Harmonized structural and fire-safety testing under the EU Construction Products Regulation is extending product certification cycles for novel brick formulations.
- Supply chain reconfiguration friction:Belgian clay transport dependency is forcing logistics recalibration as cross-border carbon accounting tightens under EU Green Deal implementation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dutch Brick Market |
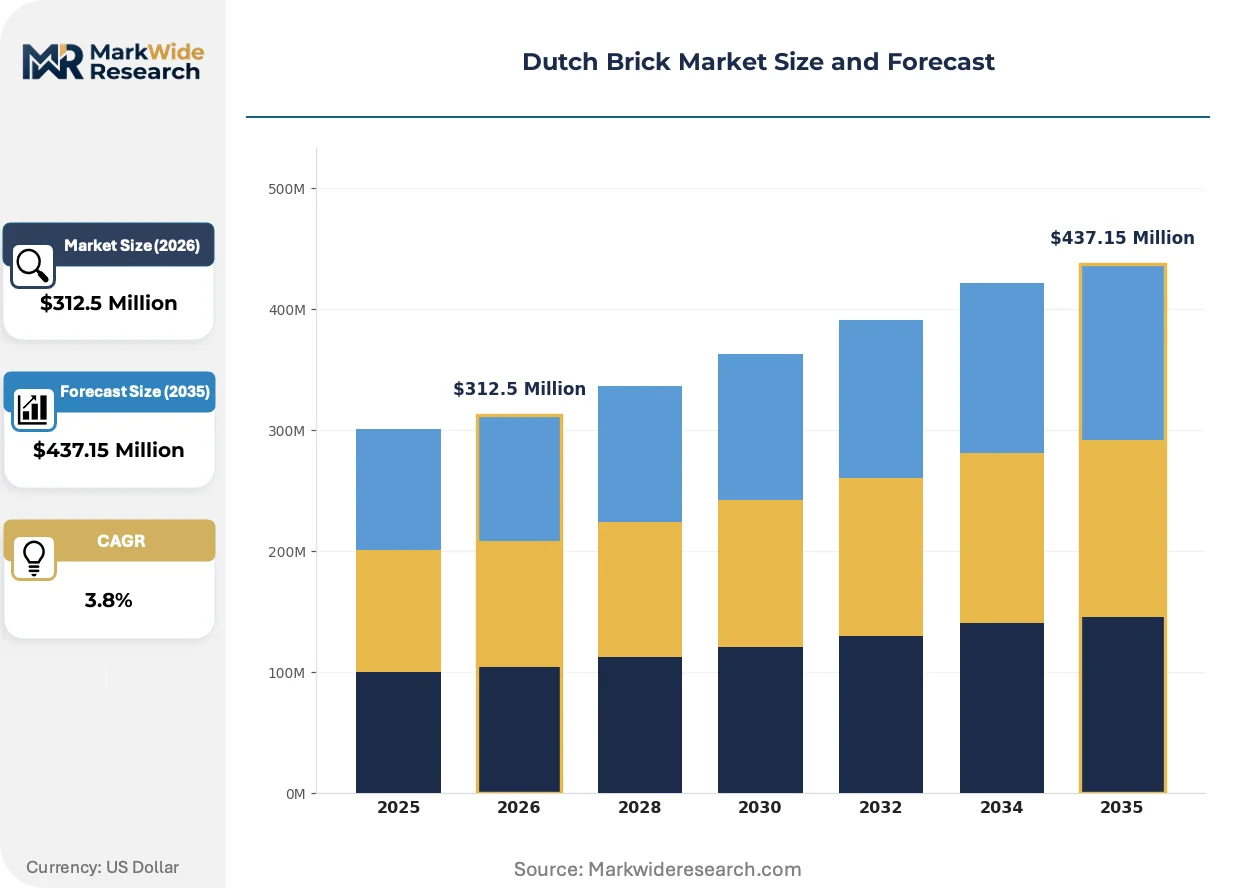
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $437.15 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clay Bricks, Concrete Bricks, Fly Ash Bricks, Calcium Silicate Bricks, Refractory Bricks Application: Residential Construction, Commercial Facilities, Infrastructure Projects, Landscaping, Industrial Establishments Form: Solid Bricks, Hollow Bricks, Perforated Bricks, Modular Bricks, Interlocking Bricks Customer Type: Construction Companies, Real Estate Developers, Government Agencies, Contractors, Renovation Specialists |
| Companies Covered | Wienerberger, Excluton, Ter Stege Betonvormen, Kooy Baksteencentrum, Steenfabriek Spijkenisse, Normteq, Kalkzandsteenfabriek Harderwijk, Mulderij Metsel- en Timmerbedrijf, Daas Baksteen Zeddam, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dutch Brick Market Trends and Innovations
Digital manufacturing integration and regulatory carbon accounting are converging to reshape Dutch brick production economics, with specification power shifting toward data-verified performance claims rather than traditional material loyalty.
Building information modeling is digitizing specification workflows across Dutch architectural practices, enabling real-time thermal performance simulation and automated compliance checking against Bouwbesluit energy coefficients. Housing associations in Rotterdam and The Hague are mandating BIM-compatible product data submissions, compressing traditional brick selection timelines and elevating manufacturers with structured digital catalogs.
The EU Green Deal's carbon border adjustment mechanism is tightening documentation requirements for imported construction materials, compelling Dutch producers to invest in lifecycle assessment certification and blockchain-tracked supply chain transparency. CE marking enforcement under the Construction Products Regulation is intensifying laboratory testing protocols, with hollow perforated brick categories facing expanded fire-safety validation scope.
Architect-specified procurement is consolidating decision authority within Dutch design firms, displacing traditional merchant-distributor influence in premium facade segments. Contractor-direct purchasing is expanding in volume residential foundations, compressing channel margins and favoring manufacturers with captive logistics networks serving Randstad construction corridors.
Dutch Brick Market Segmentation
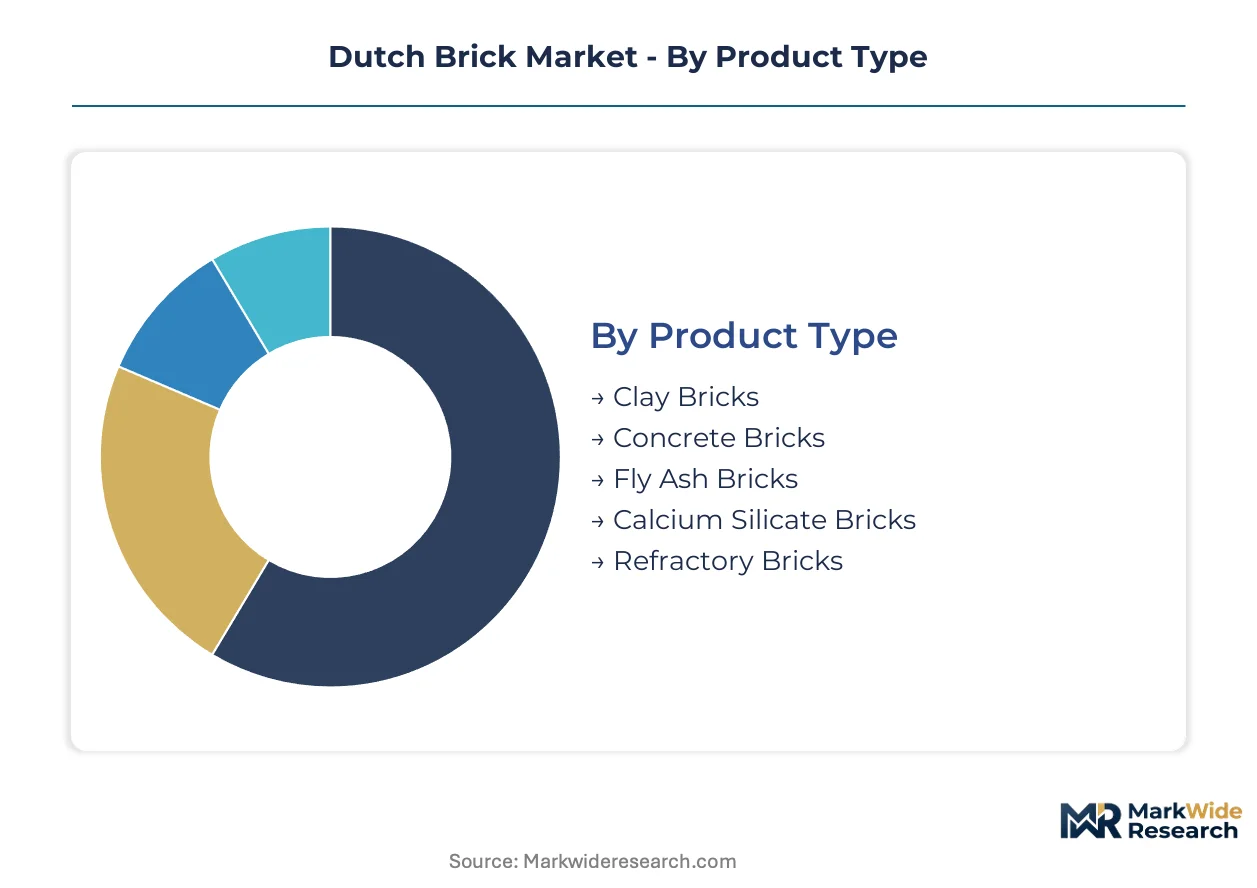
Dutch brick segmentation reveals distinct service intensity patterns across product categories, with heritage-matched clay requiring specification support while concrete foundations demand logistics reliability. Specification complexity varies dramatically by end-use, driving divergent channel strategies among manufacturers.
Product Type:
After-sales intensity concentrates in heritage-sensitive categories where color matching and technical consultation extend project timelines.
- Clay Bricks:Fired clay units prized for color stability and breathability in monument conservation. Amsterdam and Utrecht heritage authorities mandate authentic matches for protected facades, locking suppliers into multi-year specification relationships.
- Concrete Bricks:Cement-aggregate masonry capturing volume-driven residential foundations through cost efficiency. Randstad volume builders specify these for utility structures where thermal requirements remain minimal and procurement prioritizes logistics reliability.
- Fly Ash Bricks:Industrial byproduct-based units offering embodied carbon advantages under EU Green Deal accounting.
- Calcium Silicate Bricks:Sand-lime compositions suited to precision dimensional requirements in prefabricated systems.
- Refractory Bricks:High-alumina formulations serving industrial kiln linings and thermal containment applications.
Clay bricks hold the largest share; momentum sits with fly ash formulations as carbon disclosure thresholds tighten.
Application:
Cost tier stratification separates premium facade specifications from commodity foundation procurement across Dutch construction verticals.
- Residential Construction:Dominant demand channel encompassing single-family housing and multi-unit towers. South Holland and North Brabant housing associations are concentrating retrofit programs for cavity wall upgrades, specifying thermally optimized brick systems with verified performance data.
- Commercial Facilities:Office and retail envelopes where architect-specified facades command premium positioning. Rotterdam and The Hague design firms are consolidating decision authority, mandating BIM-compatible product submissions that compress traditional selection timelines.
- Infrastructure Projects:Civil works and transportation structures requiring structural durability certifications.
- Landscaping:Non-structural paving and garden wall applications with aesthetic prioritization.
- Industrial Establishments:Manufacturing facilities and warehouse envelopes with functional performance requirements.
Residential construction dominates absolute volume; commercial facilities are climbing the fastest as BIM-enabled specification workflows expand.
Form:
Volume concentration favors formats compatible with mechanized laying and prefabricated wall assembly.
- Hollow Bricks:Cavity configurations reducing thermal bridging in energy-compliant envelopes. Modular construction contractors across Randstad corridors are specifying these for reduced site labor and accelerated envelope assembly in residential towers.
- Perforated Bricks:Patterned void structures optimizing strength-to-weight ratios for multi-story applications. These formats face expanded fire-safety validation scope under intensified CE marking enforcement.
- Solid Bricks:Dense traditional units retaining specification in load-bearing heritage restoration.
- Modular Bricks:Dimensionally standardized for prefabrication-oriented contractors seeking site labor reduction.
- Interlocking Bricks:Self-aligning geometries for dry-stack construction in landscaping and temporary structures.
Hollow bricks command the greatest volume; modular formats are gaining share fastest among prefabrication specialists.
Customer Type:
Margin differentiation separates architect-influenced specification channels from contractor-direct procurement in foundation segments.
- Construction Companies:General contractors balancing specification compliance with procurement efficiency across project portfolios. These stakeholders are prioritizing manufacturers with captive logistics networks serving Randstad construction corridors.
- Real Estate Developers:Project sponsors controlling material selection in speculative residential and commercial schemes. Developers are mandating embodied carbon documentation to preempt EU Green Deal compliance risks.
- Government Agencies:Public works authorities with mandated procurement transparency and lifecycle cost evaluation.
- Contractors:Specialized trades executing foundation and envelope work with equipment-dependent format preferences.
- Renovation Specialists:Heritage restoration contractors requiring color-matching services and technical consultation.
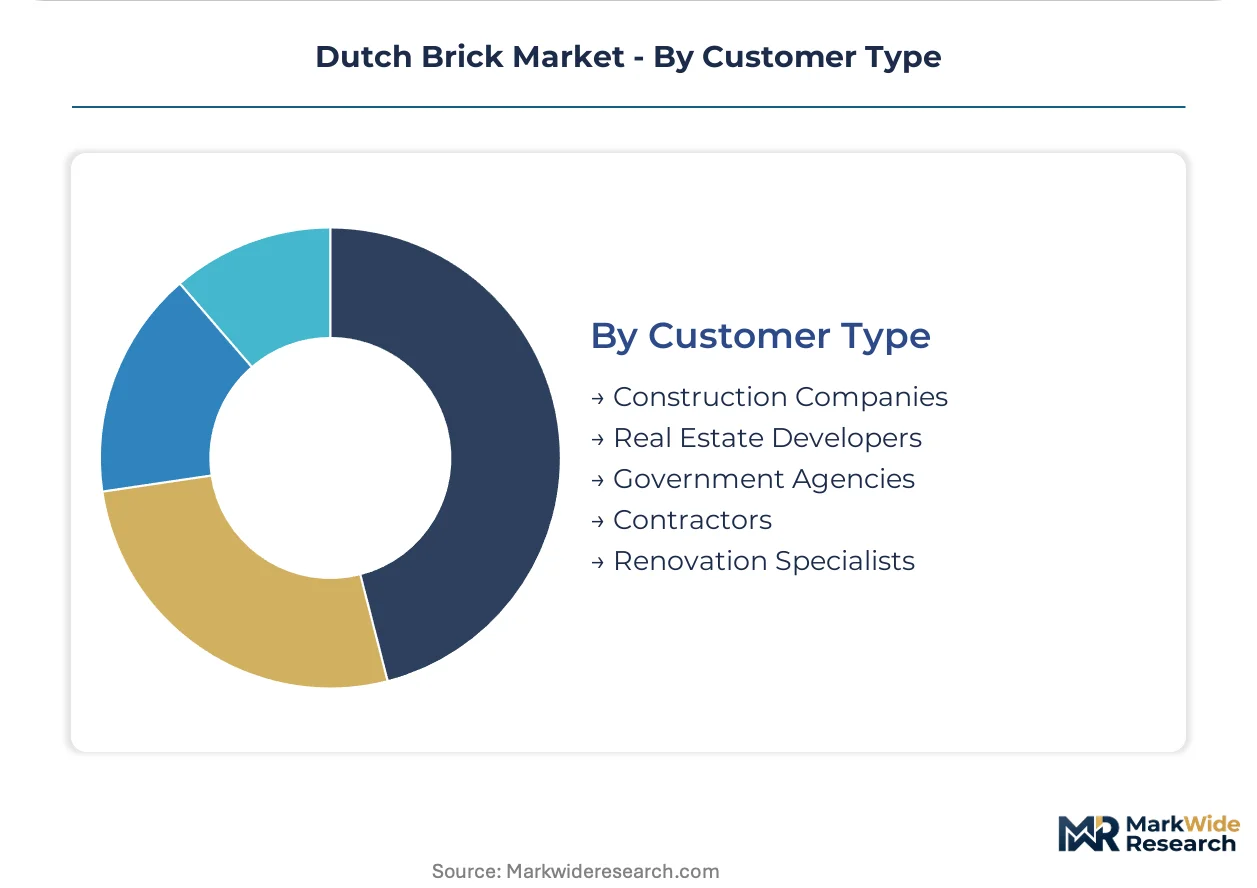
Construction companies represent the largest customer base; real estate developers are expanding procurement influence fastest through sustainability mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Scheldt-Meuse delta port complex underwrites the Netherlands' position as a continental brick distribution hub, channeling Belgian clay imports and finished goods across northwestern Europe.
Randstad Metropolitan Corridor
Amsterdam, Rotterdam, The Hague and Utrecht concentrate demand for thermally optimized hollow bricks in multi-unit residential towers. The Netherlands Building Decree's tightening energy performance coefficients mandate cavity wall upgrades across social housing stocks. South Holland housing associations are specifying BIM-compatible brick systems for accelerated envelope assembly.
North Brabant
Eindhoven's technology corridor generates demand for precision-engineered calcium silicate bricks in cleanroom and research facilities. Provincial retrofit programs are channeling investment into heritage-sensitive clay brick restoration for Brabant's monument-protected industrial architecture. Tilburg and Breda contractors are consolidating procurement through direct manufacturer relationships.
Northern Netherlands
Groningen and Friesland face distinct seismic stabilization requirements following induced earthquake damage from gas extraction. The national gas phase-out policy is accelerating kiln fuel-switching investments in Drenthe manufacturing zones. Leeuwarden-based renovation specialists are locking multi-year heritage restoration contracts.
Limburg
Maastricht's proximity to Belgian clay quarries in Flanders creates supply chain integration with cross-border raw material flows. The province's limestone-rich subsoil supports calcium silicate brick production for precision prefabricated systems. Venlo logistics hubs are serving German construction corridors along the A67 motorway.
Dutch Brick Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in raw material and format niches. The Dutch brick market structures around vertically integrated quarry-to-kiln networks, regional merchant-distributor hybrids, and heritage-authentication specialists. Three archetypes dominate: Benelux-scale platform operators with captive clay reserves, Randstad-focused logistics-integrated suppliers, and monument-conservation authenticators with specification-locked restoration channels. Competitive moves concentrate on backward integration into Belgian quarry assets and carbon-verified product data certification for EU Green Deal positioning.
Among Benelux-integrated producers, Wienerberger anchors the platform tier with vertically controlled raw material flows, while Excluton occupies premium facade positioning through specialized color and texture ranges. Daas Baksteen Zeddam exemplifies the heritage-authentication archetype, controlling niche specification channels for monument conservation in Utrecht and Amsterdam protected zones.
| Leading Market Players |
|---|
| Wienerberger |
| Excluton |
| Ter Stege Betonvormen |
| Kooy Baksteencentrum |
| Steenfabriek Spijkenisse |
| Normteq |
| Kalkzandsteenfabriek Harderwijk |
| Mulderij Metsel- en Timmerbedrijf |
| Daas Baksteen Zeddam |
| Others |
Pricing and Supply Chain Analysis
Overcapacity signals in Belgian clay extraction corridors are compressing margin buffers for non-vertically integrated Dutch manufacturers, forcing kiln operators to absorb fuel-switching costs while Belgian feedstock suppliers retain pricing power through cross-border dependency.
Pricing Analysis
The EU Green Deal's embodied carbon disclosure thresholds dictate the pricing tier structure across Dutch brick manufacturing. Three-tier pricing structure across premium, standard, and economy levels separates heritage-authenticated clay units from commodity concrete foundations and unverified imports. Price differentiation centers on CE marking compliance grade and volume scale, with housing association bulk procurement commanding logistics discounts. Pricing pressure stems from natural gas phase-out capital burdens, while renovation specialists show least price sensitivity for color-matched heritage specifications.
Supply Chain Analysis
Belgian clay deposits in Flanders feed the upstream raw material base for Dutch kiln operations. Manufacturing draws from cross-border quarry flows, bio-based firing fuel trials, and hydrogen infrastructure pilots. Single-source vulnerability concentrates in Flemish clay transport corridors where carbon accounting tightening threatens logistics economics. Distribution runs through Randstad merchant-distributor networks and contractor-direct channels serving residential foundation segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Dutch brick market is approaching a platform-economics inflection as BIM-enabled specification workflows consolidate decision authority within architect practices, creating data-interoperability requirements that favor manufacturers with structured digital product catalogs over traditional merchant relationships.
For Market Incumbents: Harden specification lock-in through captive Belgian quarry assets and accelerated lifecycle assessment certification to preempt EU Green Deal carbon border filtering. Invest in hydrogen-fired kiln engineering talent pools before scarcity intensifies, and defend heritage restoration channels against emerging calcium silicate substitutes through color-matching service depth. For New Entrants and Emerging Players: Fly ash brick production for housing association retrofit programs represents the most penetrable entry point, given embodied carbon advantages under tightening disclosure mandates. Modular format manufacturing for prefabricated wall system contractors offers second-mover positioning without heritage specification barriers. Lead with blockchain-tracked supply chain transparency as the go-to-market differentiator. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because kiln fuel-switching capital intensity will force mid-scale producer exits, concentrating share among vertically integrated quarry-to-kiln operators. Target acquisition archetypes include Belgian clay reserve holders and heritage-authentication specialists with monument conservation relationships. Monitor hydrogen infrastructure subsidy announcements as the signal for conversion economics inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Belgian Quarries | Captive clay supply secures margin control against cross-border carbon accounting tightening. |
| Hydrogen-Fired Kiln Conversion | Natural gas phase-out deadlines make renewable fuel infrastructure a compliance necessity. |
| BIM-Compatible Product Data Investment | Architect specification workflows now mandate structured digital catalogs for project inclusion. |
| Lifecycle Assessment Certification | EU Green Deal carbon border adjustments filter market access for non-documented suppliers. |
| Heritage Color-Matching Service Expansion | Monument conservation authorities in Amsterdam and Utrecht mandate authentic material matches. |
Research Methodology
Operator-level perspectives from kiln operations managers, housing association procurement directors, architect specification leads, and heritage conservation officers anchored the qualitative base. These interviews combined with secondary validation from Dutch Building Decree regulatory filings, EU Construction Products Regulation CE marking databases, Belgian geological survey clay reserve estimates, and Benelux customs trade flow records. Bottom-up production capacity modeling and top-down construction spend allocation were triangulated for convergence.
Scenario-bracketing framed the analytical approach across the projection horizon, with high-low fuel-switching investment cases and carbon border adjustment implementation timelines. Segmentation dimensions modeled include product type, application vertical, brick form factor, and customer procurement archetype. CAGRs were derived from elasticity-adjusted demand curves incorporating Bouwbesluit energy coefficient tightening schedules and housing association retrofit program commitments.
Stress conditions across natural gas price volatility, Belgian transport corridor disruption, and hydrogen infrastructure deployment delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory implementation pacing and construction sector labor availability. Quarterly review of kiln fuel-switching capital commitment announcements and heritage authority specification mandate updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Fiber Reinforced Polymer (FRP) Rebars Market
Building Materials
Fiber Reinforced Polymer Composites (FRP) Market
Building Materials
Steel Sleepers Market
Building Materials
Europe Fiber Cement Market
Building Materials
Radiant Barriers and Reflective Insulation Market
Building Materials
Latin America Aluminum Door and Window Market
Building Materials
Building and Construction Plastics Market
Building Materials
Fiber Reinforced Concrete Market
Building Materials
Stone Coated Steel Roofing Market
Building Materials
Germany Aluminum Door and Window Market
Building Materials
Asia-Pacific Kinetic Tiles Market
Building Materials
Bio-Based Structural Wood Adhesives for Modular Construction Market
Building Materials
Global Corrugated Steel Sheets Market
Building Materials
Concrete Admixtures Market
Building Materials
Global Magnesia Chrome Brick Market
Building Materials
Global Commercial Paving Slabs Market