
 Cement Consistometer Market | 2026-2036
Cement Consistometer Market Size, Share, and Industry Trends Forecast 2026-2036
Cement Consistometer Market Analysis
API Specification 10A qualification is rotating vendor eligibility as cementing service companies demand traceable thickening-time calibration certificates. Chandler Engineering leverages its Tulsa manufacturing base to sustain domestic channel control for pressure-cell units. Fann Instrument Company anchors its position through deep specialization in high-temperature high-pressure rheology systems. Rigchina Group competes on cost-engineered portable units that occupy mid-tier procurement budgets across Asian drilling contractors.
A cement consistometer measures the thickening time and consistency of cement slurries under simulated downhole temperature and pressure conditions, typically employing a rotating paddle viscometer within a pressurized test cell rated to 400°F and 30,000 psi to replicate wellbore environments. Its primary purpose is to validate that oil well cement will maintain pumpability through the full placement window before setting. Portable consistometer demand is accelerating fastest in remote field locations where rig-site quality assurance eliminates lab transit delays. Electronic technology variants command premium positioning due to automated data logging and repeatability advantages over mechanical dial-gauge predecessors. Laboratory consistometer installations remain the margin pool anchor as cement manufacturers and research institutions specify multi-cell systems for parallel batch testing.
The American Petroleum Institute governs instrument performance benchmarks through API RP 10B-2, while OSHA mandates pressurized equipment certification for laboratory operator safety. EPA spill-prevention protocols indirectly shape slurry testing intensity by raising the compliance cost of failed primary cement jobs. ASTM C191 provides parallel specification pathways for construction-grade cement testing that broadens addressable demand beyond hydrocarbon applications. Stakeholders must monitor evolving API revision cycles and decide calibration infrastructure investments before specification shifts obsolete existing instrument fleets.
Market Dynamics
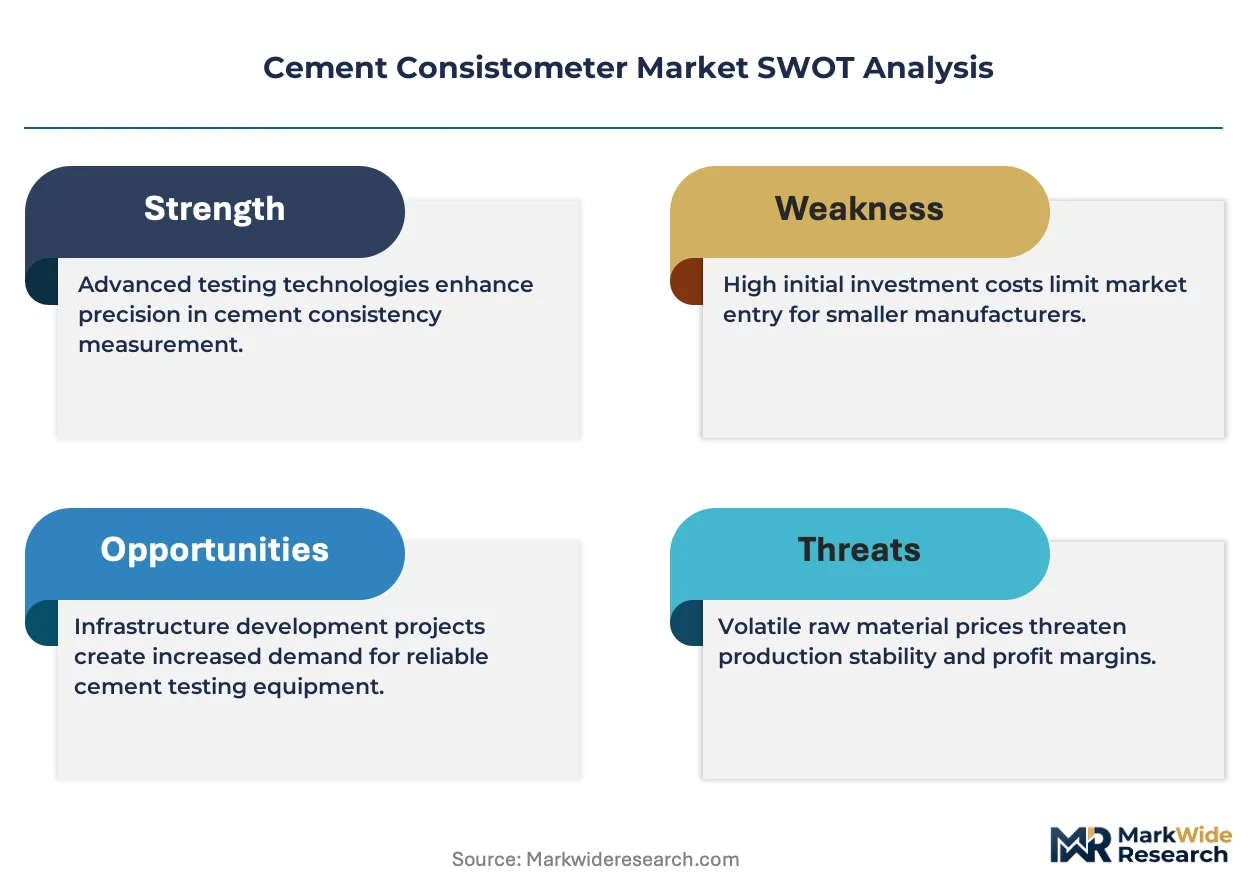
API Specification 10A thickening-time compliance is compressing vendor qualification cycles as cementing service companies demand traceable calibration certificates for every pressure-cell unit deployed in shale basins. This regulatory tightening is forcing procurement departments to prioritize instrument fleets with documented metrology chains over legacy mechanical dial-gauge systems.
Growth Catalysts
- Shale Basin Drilling Intensity:Permian and Bakken operators are replacing aging benchtop consistometers at accelerated rates to maintain API-compliant rheology validation for high-pressure cement jobs.
- EPA Spill-Prevention Protocols:Failed primary cement jobs now carry elevated environmental liability costs, intensifying slurry testing frequency at both laboratory and rig-site locations.
- Electronic Data Logging:Automated thickening-time recording with digital repeatability is displacing manual dial-gauge readings in quality-sensitive procurement specifications.
Market Restraints
- High-Temperature Sensor Costs:Pressure transducers rated beyond 400°F and 30,000 psi command premium pricing that constrains mid-tier drilling contractor budgets.
- Calibration Infrastructure Concentration:Traceable thickening-time certification capacity clusters in Tulsa and Houston, creating geographic bottlenecks for international instrument deployment.
- Mechanical System Longevity:Decades-old dial-gauge consistometers remain functional in low-stakes construction cement testing, delaying replacement demand in non-oilfield segments.
Strategic Opportunities
- Portable Rig-Site Deployment:Remote field locations in North Dakota and West Texas are eliminating lab transit delays through on-location quality assurance units.
- ASTM C191 Construction Pathway:Specification compliance for construction-grade cement testing opens addressable demand beyond hydrocarbon applications into infrastructure projects.
- Multi-Cell Parallel Testing:Research institutions and cement manufacturers are specifying laboratory systems that process simultaneous batch comparisons.
Industry Challenges
- API Revision Cycle Uncertainty:Calibration infrastructure investments risk obsolescence when specification shifts invalidate existing instrument fleets before depreciation cycles complete.
- Pressurized Equipment Certification:OSHA-mandated safety protocols for laboratory operators extend procurement timelines and elevate compliance documentation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cement Consistometer Market |
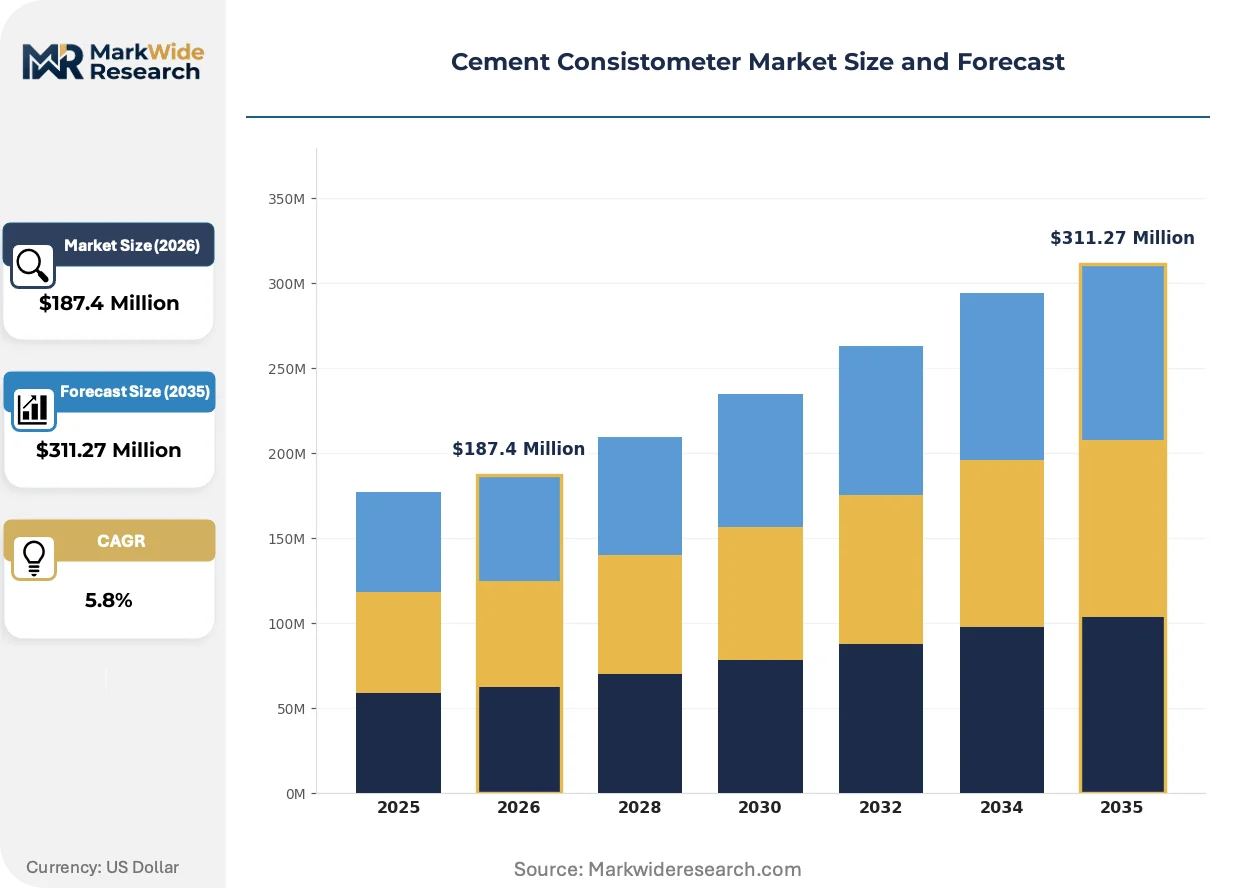
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Consistometer, Laboratory Consistometer, Automatic Consistometer, Manual Consistometer Technology: Electronic, Mechanical, Hydraulic, Pneumatic End User: Cement Manufacturers, Construction Companies, Research Institutions, Quality Control Laboratories Application: Construction Testing, Research & Development, Quality Assurance, Field Testing |
| Companies Covered | Chandler Engineering, OFI Testing Equipment, Inc., Fann Instrument Company, Grace Instrument Company, Rigchina Group, Cooper Research Technology Ltd., Tianjin Nithons Technology Co. Ltd., Humboldt Mfg. Co., Matest S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cement Consistometer Market Emerging Trajectories
Electronic thickening-time instrumentation is actively compressing the competitive position of mechanical predecessors while regulatory revision cycles and procurement model evolution reshape how cementing service companies qualify their quality assurance assets.
Automated paddle viscometer systems with integrated data logging is supplanting manual dial-gauge consistometers in operator procurement specifications. Cementing service companies in Texas and North Dakota are specifying electronic variants for all new pressure-cell purchases. This technology transition is compressing the residual value of mechanical instrument fleets and elevating vendor qualification barriers to firms with digital calibration infrastructure.
OSHA pressurized equipment certification mandates are extending procurement timelines for laboratory consistometer installations. Safety documentation requirements now precede instrument commissioning by several weeks in domestic facilities. Laboratory operators are responding by consolidating purchases with vendors offering pre-certified turnkey systems rather than component-level procurement.
Rig-site quality assurance is displacing centralized laboratory testing for time-sensitive cement jobs in remote shale basins. Drilling contractors in the Permian are specifying portable electronic consistometers that eliminate sample transit delays. This behavioral shift is most visible among independent operators running batch drilling programs where cement placement windows are measured in hours rather than days.
Cement Consistometer Market Segmentation
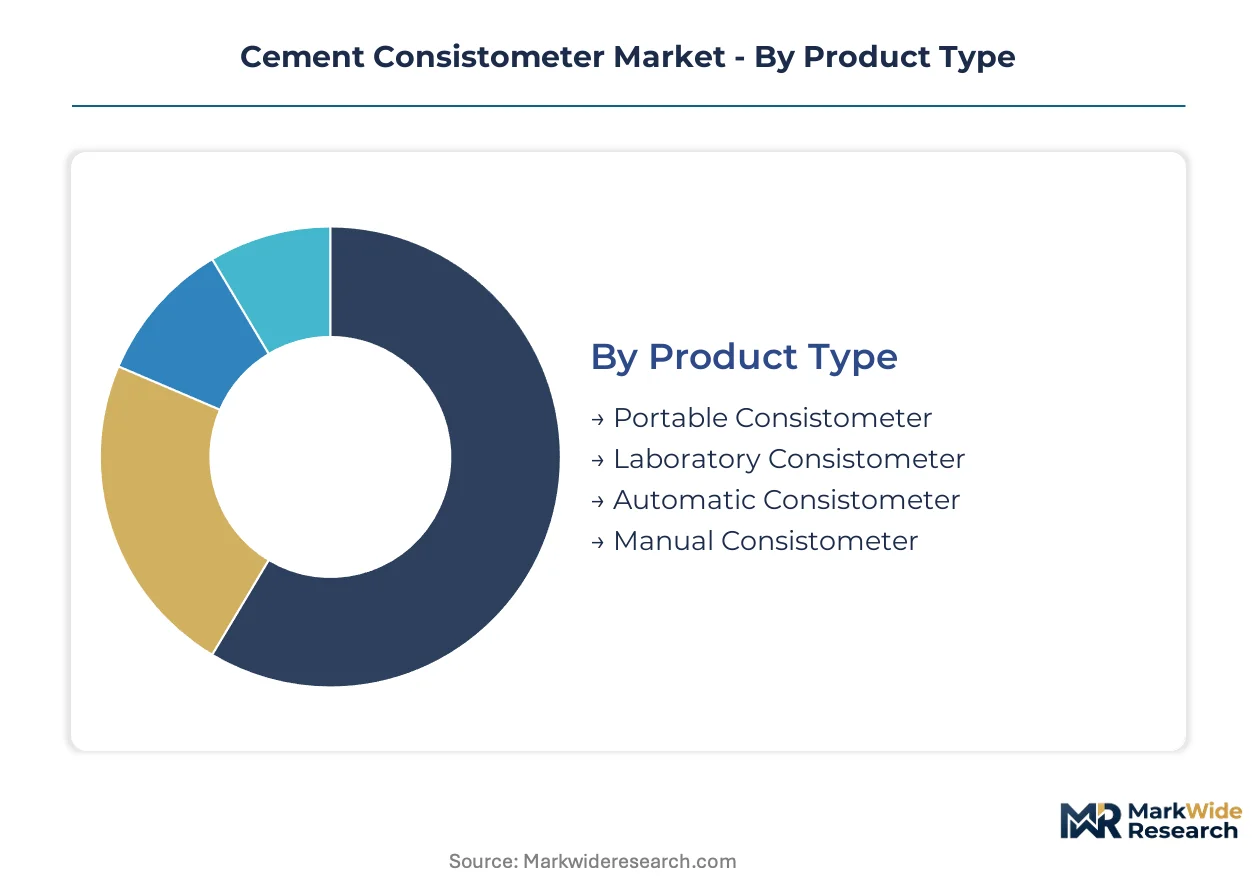
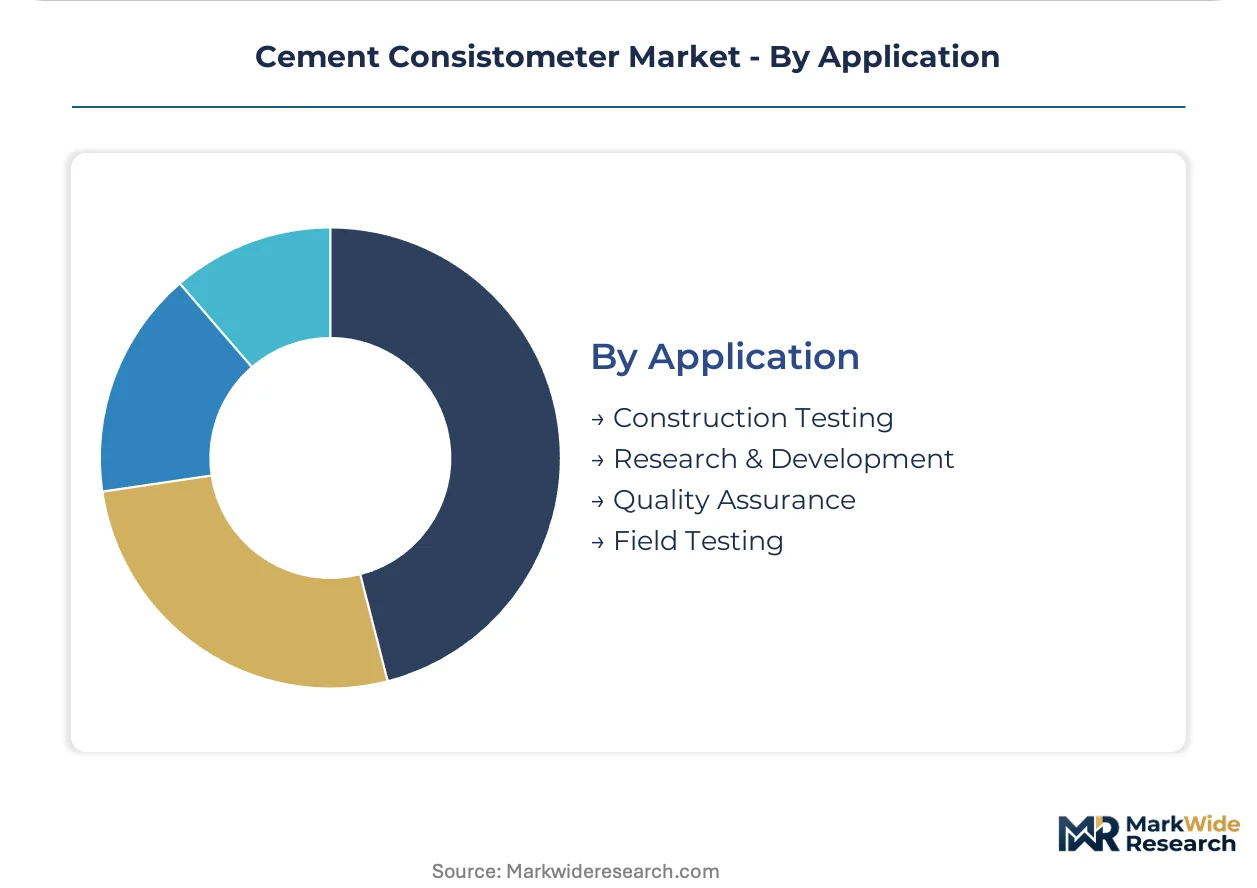
Segmentation in the cement consistometer market reflects divergent procurement priorities across oilfield service companies, construction material suppliers, and research institutions. Each segment category carries distinct regulatory burdens, calibration requirements, and replacement cycles that shape vendor positioning and pricing architecture.
Product Type:
API Specification 10A thickening-time compliance separates instrument classes by validation environment and mobility requirements.
- Laboratory Consistometer:Multi-cell pressure-rated systems process parallel batch testing for cement manufacturers and research institutions under controlled temperature-pressure conditions up to 400°F and 30,000 psi. Cement manufacturers in Texas and North Dakota specify these units for API-compliant rheology validation where traceable calibration certificates are mandatory for every deployment.
- Portable Consistometer:Battery-powered or rig-site powered units enable on-location quality assurance without laboratory transit delays. Drilling contractors in the Permian Basin are accelerating procurement of electronic portable variants where cement placement windows compress to hours rather than days.
- Automatic Consistometer:Paddle viscometer systems with integrated data logging automate thickening-time recording and eliminate manual dial-gauge reading errors.
- Manual Consistometer:Mechanical dial-gauge predecessors retain residual demand in construction-grade cement testing where API compliance is not required.
Established volume favors laboratory consistometers; emerging adoption favors portable units.
Technology:
Cost tier differentiation separates premium electronic systems from legacy mechanical infrastructure.
- Electronic:Automated sensor arrays with digital repeatability and automated data logging command premium positioning in operator procurement specifications. Cementing service companies in shale basins now specify electronic variants exclusively for new pressure-cell purchases.
- Mechanical:Dial-gauge systems with manual paddle rotation persist in low-stakes construction applications and budget-constrained international markets.
- Hydraulic:Pressure generation systems utilizing fluid-driven actuation for high-pressure test cell environments.
- Pneumatic:Compressed air-driven pressure systems for lower-pressure testing applications and field-portable deployments.
Electronic systems capture margin concentration; mechanical systems retain replacement-delayed installed base.
End User:
Customer type determines calibration infrastructure investment and specification stringency.
- Cement Manufacturers:Multi-cell laboratory installations with parallel batch processing capabilities dominate capital allocation for API Specification 10A compliance and research-grade rheology validation.
- Construction Companies:ASTM C191 pathway compliance for construction-grade cement testing opens addressable demand beyond hydrocarbon applications into infrastructure projects.
- Research Institutions:Academic and government laboratories specify high-precision systems for cement chemistry investigation and additive formulation development.
- Quality Control Laboratories:Third-party testing facilities serving multiple client verticals require flexible instrument configurations spanning oilfield and construction specifications.
Cement manufacturers anchor revenue concentration; construction companies represent the steepest expansion trajectory.
Application:
Geography and urgency differentiate centralized laboratory testing from distributed field deployment.
- Quality Assurance:Rig-site and laboratory validation of cement slurry pumpability before placement, with EPA spill-prevention protocols intensifying testing frequency.
- Field Testing:Portable deployment in remote shale basin locations eliminates sample transit delays where drilling contractors operate batch programs with compressed cementing windows.
- Research & Development:Cement additive formulation and novel binder chemistry investigation requiring precise temperature-pressure simulation.
- Construction Testing:ASTM C191-compliant validation of construction-grade cement performance for infrastructure project specifications.
Quality assurance commands specification premium; field testing gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oilfield service companies concentrate procurement authority in shale drilling corridors where API-compliant thickening-time validation determines cement job success. Equipment buyers cluster around Permian Basin operations, Bakken formation activity, and international unconventional plays where pressure-rated instrument deployment carries regulatory weight.
United States
Permian Basin operators in Texas and North Dakota Bakken drillers sustain replacement cycles for aging benchtop consistometers as EPA spill-prevention protocols intensify slurry testing frequency. OSHA pressurized equipment certification mandates extend procurement timelines for laboratory installations. Tulsa and Houston anchor domestic manufacturing and calibration infrastructure for pressure-cell units.
China
Domestic drilling contractors in Sichuan-Chongqing shale gas blocks and Xinjiang oilfields drive demand for cost-engineered portable units that occupy mid-tier procurement budgets. MIIT industrial equipment standards and GB calibration protocols shape vendor qualification requirements. Zhengzhou and Tianjin instrument clusters supply regional oilfield service companies with ASTM C191-compliant construction cement testing capacity.
Saudi Arabia
Aramco-led unconventional gas development in the Jafurah Basin creates demand for high-temperature high-pressure rheology systems rated beyond 400°F. The national oil company's engineering standards exceed API Specification 10A baseline requirements for thickening-time documentation. Dammam and Jubail industrial zones concentrate procurement decision-making for pressure-cell fleet expansion.
Canada
Montney and Duvernay formation operators in Alberta and British Columbia specify electronic consistometers with automated data logging for cold-weather cementing operations. Health Canada workplace safety regulations parallel OSHA pressurized equipment protocols for laboratory installations. Calgary anchors oilfield service company headquarters where procurement specifications originate for Western Canadian Sedimentary Basin deployment.
United Arab Emirates
ADNOC offshore expansion and unconventional exploration in the Al Dhafra region drive instrument procurement for high-pressure cement jobs in high-temperature reservoirs. MOHAP industrial safety standards govern laboratory equipment certification timelines. Abu Dhabi and Dubai serve as procurement hubs for Middle East and North Africa drilling contractor fleets.
Cement Consistometer Market Vendor Landscape
Player mix skews toward specialized oilfield instrumentation manufacturers with deep API compliance expertise rather than diversified industrial conglomerates. Market structure concentrates around three tiers: premium-tier vendors with Tulsa-based calibration infrastructure, mid-tier Asian fabricators competing on portable unit cost engineering, and construction-grade specialists serving ASTM C191 pathways. Dominant competitive moves include geographic expansion into shale basin service corridors and technology licensing for electronic data logging systems.
Within the premium-tier vector, Chandler Engineering and Fann Instrument Company exemplify vendors with domestic manufacturing bases and established metrology chains for traceable thickening-time certification. Rigchina Group occupies a position among cost-focused portable unit suppliers targeting Asian drilling contractor budgets. Among laboratory equipment specialists, Cooper Research Technology Ltd. and Matest S.p.A. represent European fabricants with construction-grade cement testing capabilities extending beyond hydrocarbon applications.
| Leading Market Players |
|---|
| Chandler Engineering |
| OFI Testing Equipment, Inc. |
| Fann Instrument Company |
| Grace Instrument Company |
| Rigchina Group |
| Cooper Research Technology Ltd. |
| Tianjin Nithons Technology Co. Ltd. |
| Humboldt Mfg. Co. |
| Matest S.p.A. |
| Others |
Supply Flow & Price Mechanics
Long-term calibration service contracts with API-traceable certification indexation lock in both instrument fleet access and predictable lifecycle cost visibility for cementing service companies operating across Permian and Bakken shale corridors. This contract pattern concentrates pricing power with Tulsa and Houston-based vendors possessing documented metrology chains while compressing margins for mid-tier suppliers lacking in-house calibration infrastructure.
Pricing Analysis
Cost-plus contracts with sensor component indexation dominate procurement for high-temperature pressure transducers rated beyond 400°F. Price differentiation hinges on API Specification 10A certification tier and after-sales calibration bundling. Electronic data logging variants command premium positioning while mechanical dial-gauge systems face price erosion from shrinking replacement demand. Mid-tier Asian drilling contractors exhibit highest price sensitivity; Aramco-tier operators show lowest sensitivity due to engineering standard stringency exceeding baseline API requirements.
Supply Chain Analysis
Inbound logistics costs through Houston port congestion and container availability constraints on Asia-US trade lanes elevate landed costs for pressure-cell components sourced from Zhengzhou and Tianjin manufacturing clusters. Pressure transducers and high-temperature sensor arrays draw from US, German, and Japanese component suppliers. Single-source vulnerability concentrates in traceable thickening-time certification capacity. Distribution runs through oilfield service company procurement headquarters in Calgary, Dubai, and Houston.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among consolidated cementing service companies running multi-basin fleet operations, fragmenting pricing leverage for vendors without established API calibration infrastructure.
For Market Incumbents: Compound defensive positioning through backward integration into sensor manufacturing and captive calibration laboratory capacity in Tulsa. Cementing service company procurement consolidation threatens margin compression for vendors lacking documented metrology chains. Prioritize API Specification 10A revision-cycle readiness to preempt fleet obsolescence risk. For New Entrants and Emerging Players: Lead with ASTM C191 construction-grade certification as the most penetrable pathway beyond hydrocarbon applications. Infrastructure project specifications in China and India present white-space opportunity underserved by oilfield-specialized incumbents. Deploy cost-engineered portable units through regional distributor partnerships rather than direct sales infrastructure. For Investors and Strategic Acquirers: Capital is best deployed toward electronic instrumentation specialists with existing API calibration infrastructure and proven shale basin customer relationships. Long-term viability favors vendors positioned for regulatory specification shifts rather than mechanical system residual value extraction. Watch API RP 10B-2 revision timing as inflection indicator for calibration infrastructure investment urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Captive supply of high-temperature transducers reduces dependency on German and Japanese component suppliers. |
| API Calibration Laboratory Expansion | Traceable thickening-time certification capacity in Houston and Tulsa locks in cementing service company procurement preference. |
| ASTM C191 Construction Pathway Certification | Specification compliance opens addressable demand for infrastructure projects in China and India. |
| Portable Electronic Unit Development | Battery-powered rig-site deployment eliminates laboratory transit delays for Permian batch drilling programs. |
| Multi-Cell Parallel Testing Systems | Simultaneous batch processing capabilities anchor cement manufacturer laboratory procurement specifications. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cementing service company procurement directors, API calibration laboratory technicians, oilfield instrumentation R&D heads, and shale basin drilling contractors. Secondary validation drew from API Specification 10A documentation, EPA spill-prevention protocol filings, OSHA pressurized equipment certification records, and ASTM C191 testing standards. Bottom-up instrument shipment data triangulated against top-down cement slurry testing intensity metrics across the analysis window.
Across the projection horizon, volume and value outputs reflect segmentation modeling by product type, technology tier, end-user category, and application environment. CAGRs were derived from replacement cycle analysis for aging mechanical fleets and adoption curve projection for electronic data logging systems. Forecast inputs incorporated shale basin drilling permit trajectories and API specification revision probability weighting.
The analysis sits within stated boundaries; outcomes outside sustained Permian and Bakken drilling intensity or accelerated API specification shifts would require recalibration. Forecasts reflect documented assumptions regarding electronic technology displacement rates and calibration infrastructure concentration patterns. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Backhoes Market
Construction Equipment
Manual Welding Positioner Market
Construction Equipment
Backhoe Loaders Market
Construction Equipment
Construction Equipment Market
Construction Equipment
Piling Machine Market
Construction Equipment
Global Floor Grinding Machine Market
Construction Equipment
GCC Crane Market
Construction Equipment
Welding Equipment Market
Construction Equipment
Global CNC Tool and Cutter Grinding Machine Market
Construction Equipment
Europe Multi Attachment Loaders Market
Construction Equipment
Earthmoving Equipment Undercarriage Market
Construction Equipment
Europe Used Construction Machinery Market
Construction Equipment
Industrial Steam Washer Market
Construction Equipment
Trailer Winch Market
Construction Equipment
Indonesia Construction Equipment Market
Construction Equipment
Electric Excavators Market