
 Cellular Concrete Market | 2026-2036
Cellular Concrete Market Size, Share, and Industry Trends Forecast 2026-2036
Cellular Concrete Market Analysis
The capital-intensity divergence between integrated cement majors and regional foaming specialists is collapsing as automated batching plants reduce minimum efficient scale. Saint-Gobain leverages its gypsum-to-concrete technology crossover to anchor European specification channels for precast panels. LafargeHolcim sustains raw-source dominance across multiple continents through captive limestone reserves and clinker substitution programs. Aerix Industries competes on project-specific mix design capability, navigating complex geotechnical briefs that commodity producers avoid.
Cellular concrete is a cementitious material containing uniformly distributed air voids achieved through mechanical foaming, chemical reaction, or lightweight aggregate inclusion, with typical dry densities ranging from 300 to 1800 kg per cubic meter. Its primary purpose is to reduce dead loads in structural and geotechnical applications while providing thermal insulation and fire resistance. The application dimension shows building construction occupying the largest volume share as developers specify blocks and panels for mid-rise residential envelopes, while thermal insulation represents the fastest-growing margin pool as energy-code stringency escalates across jurisdictions. Technology segmentation reveals foaming-agent systems leading in project flexibility, though aerated processes dominate where capital-intensive autoclave capacity already exists.
CE marking under the EU Construction Products Regulation governs structural performance declarations for cellular concrete placed in European member states, while the EPA's industrial effluent guidelines constrain foaming-agent chemistry in US manufacturing facilities. India's BIS certification mandates density and compressive-strength grading for cellular concrete products deployed in public infrastructure, creating compliance barriers for uncertified imports. Stakeholders must monitor how embodied-carbon accounting standards reshape material substitution decisions across procurement offices.
Market Dynamics
The EU Green Deal's embodied-carbon accounting rules are forcing procurement offices across Europe to substitute conventional concrete with low-density cementitious systems, collapsing specification timelines and redistributing contract awards toward foaming-capable producers.
Growth Catalysts
- Seismic retrofit mandates:Japan's infrastructure agencies specify cellular concrete for base isolation in public buildings, creating specification pull for high-damping mix designs.
- REACH-compliant foaming agents:ECHA restrictions on synthetic surfactants are accelerating bio-based foamer adoption in German precast plants.
- Soft subgrade roadbuilding:State highway authorities in Maharashtra and Gujarat deploy cellular concrete for embankments over deltaic soils, concentrating demand in India's western coastal belt.
Market Restraints
- Clinker cost volatility:Energy-price spikes and EU carbon-border adjustments on imported cement are compressing margins for non-integrated cellular concrete specialists.
- Autoclave capacity concentration:Aerated concrete production clusters in Poland and the Czech Republic create supply vulnerability for Central European project timelines.
- Structural density floors:CE marking under the EU Construction Products Regulation mandates minimum compressive strengths that exclude ultra-lightweight formulations from load-bearing applications.
Strategic Opportunities
- Data center thermal envelopes:Hyperscale operators in Ireland and the Netherlands are specifying cellular concrete panels for passive cooling, opening a margin-rich specification channel.
- CSRD-linked procurement:The EU Corporate Sustainability Reporting Directive creates audit-trail requirements that favor cellular concrete with verified embodied-carbon documentation.
- Geopolymer-foam convergence:Alkali-activated binders paired with mechanical foaming are enabling clinker-free products that bypass carbon-border tariffs.
Industry Challenges
- Mix-design engineering scarcity:Project-specific geotechnical briefs require rare expertise in rheology-modified foamed systems, constraining specialist contractor capacity.
- BIS certification timelines:Indian public infrastructure mandates density-graded product certification that delays import market entry by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cellular Concrete Market |
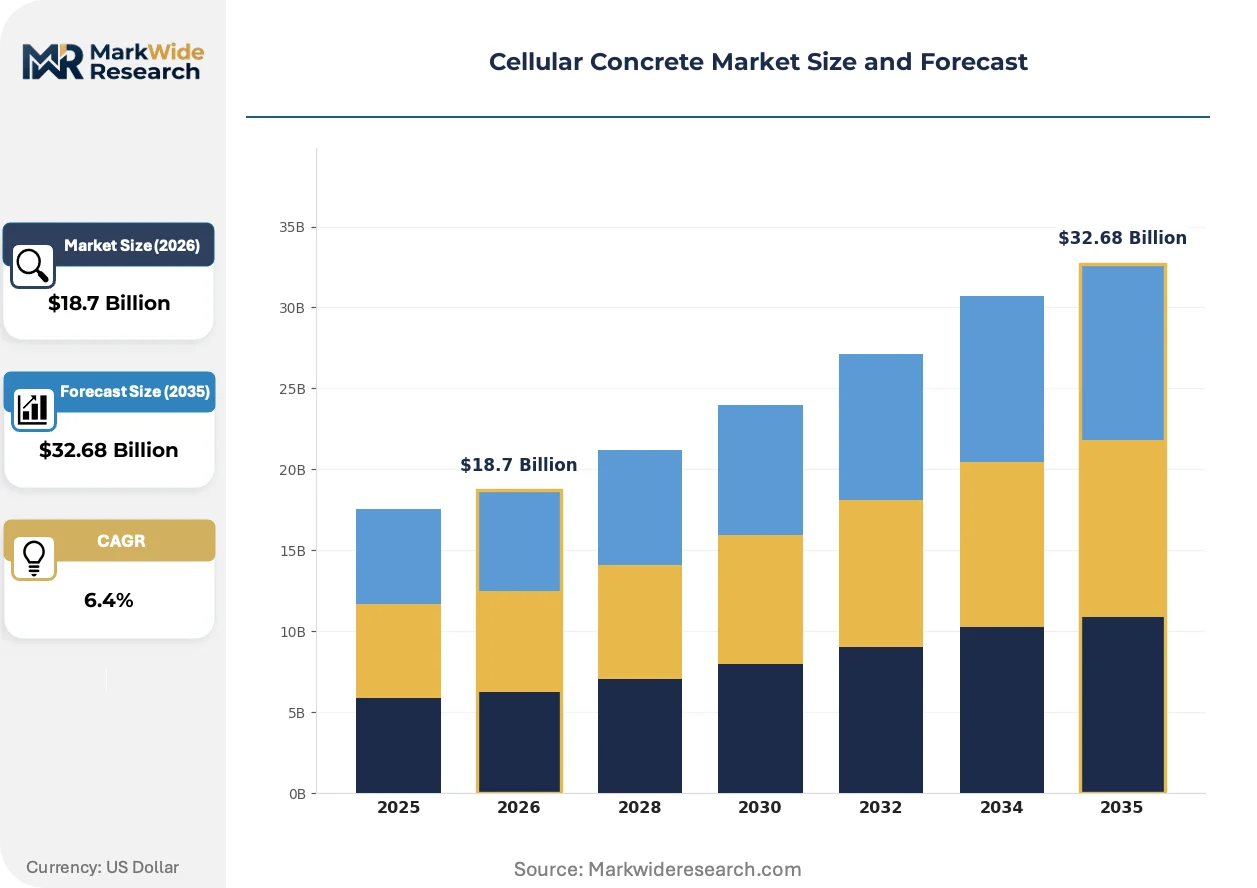
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Precast Panels, Blocks, Bricks, Lightweight Fill Application: Building Construction, Road Construction, Thermal Insulation, Fireproofing End User: Residential, Commercial, Industrial, Infrastructure Technology: Foaming Agent, Aerated, Lightweight Aggregates, Others |
| Companies Covered | Saint-Gobain, LafargeHolcim, Xella Group, Aerix Industries, CEMEX, H+H, ACICO, Cematrix, Sika AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cellular Concrete Market Emerging Trajectories
Mechanical foaming systems are overtaking autoclave-dependent processes as the dominant production paradigm, compressing capital requirements and enabling distributed manufacturing closer to project sites.
Alkali-activated cellular concrete is supplanting Portland-based formulations in European infrastructure tenders. Contractors in Denmark and Sweden specify these binders for marine applications where chloride resistance matters. The shift is compressing the addressable market for conventional clinker imports while expanding specification autonomy for Nordic producers with access to blast-furnace slag.
EPA industrial effluent guidelines are constraining foaming-agent chemistry in US manufacturing facilities. The rules force reformulation of synthetic surfactants and increase compliance costs for Gulf Coast batching plants. Precast producers are responding by qualifying bio-based protein foamers that bypass discharge permitting thresholds.
Specification-driven procurement is consolidating buying power among engineering-procurement-construction firms with in-house material-science capabilities. Tier-one contractors in Germany and Japan now demand project-specific performance guarantees rather than commodity product grades. This behavior is most visible in tunneling contracts where geotechnical risk transfer favors integrated design-build entities over traditional material suppliers.
Cellular Concrete Market Segmentation
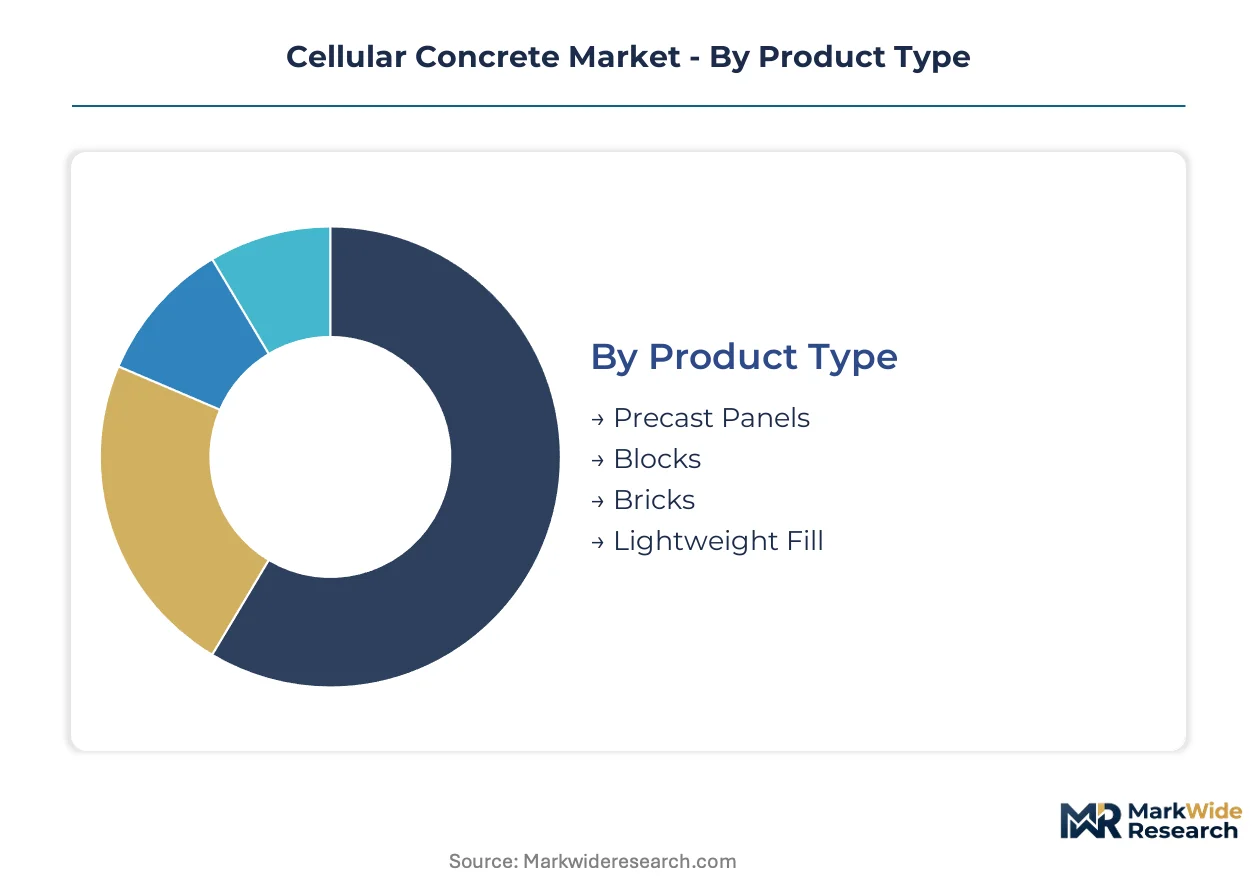
Cellular concrete's value chain fragments across distinct production technologies and specification channels. Understanding where margin pools concentrate within each dimension reveals which product configurations command premium pricing versus commodity positioning.
Product Type:
Margin pools concentrate in precast elements where factory-controlled curing enables performance guarantees that site-cast alternatives cannot match.
- Blocks:These masonry units dominate residential envelope specifications across India and Central Europe, with BIS-certified density grades commanding 15-20% price premiums over uncertified imports in Maharashtra public housing tenders.
- Precast Panels:Factory-cast wall and floor elements incorporate embedded reinforcement and thermal-break detailing that hyperscale data center operators in Ireland specify for passive cooling envelopes, creating audit-trail advantages under CSRD-linked procurement rules.
- Bricks:Traditional format cellular units serve heritage-sensitive renovations in German city centers where facades must replicate historic masonry dimensions while meeting current energy codes.
- Lightweight Fill:Flowable low-density formulations for geotechnical backfill compete primarily on delivered cost per cubic meter, compressing margins toward transport economics.
The dominant share belongs to Blocks, while Precast Panels is closing the gap fastest.
Application:
Volume concentrates in structural applications, though thermal performance specifications are expanding addressable margin through energy-code stringency.
- Building Construction:Mid-rise residential envelopes in Germany and Japan absorb the majority of block and panel volume, with seismic base-isolation designs in Tokyo public buildings requiring high-damping mix formulations that specialty contractors engineer project-by-project.
- Thermal Insulation:Energy-code escalation across EU member states is redirecting specification budgets toward cellular concrete's lambda-value advantages, particularly in Netherlands passive-house developments where embodied-carbon accounting favors low-density cementitious systems over synthetic alternatives.
- Road Construction:Maharashtra and Gujarat state highway authorities deploy embankment fill over soft deltaic soils, concentrating demand in India's western coastal belt where subgrade bearing capacity constraints exclude conventional aggregates.
- Fireproofing:Tunnel lining and structural steel encasement applications leverage cellular concrete's inherent fire resistance, with German infrastructure agencies mandating specific thickness-to-density ratios for rail tunnel backfill.
Building Construction retains the largest volume position, though Thermal Insulation exhibits the steepest expansion trajectory as jurisdictions tighten envelope performance standards.
End User:
Procurement sophistication varies sharply across customer categories, with infrastructure agencies imposing the most demanding compliance frameworks.
- Infrastructure:Japanese METI-specified seismic retrofits and German tunneling contracts require project-specific performance guarantees and extended warranty terms that filter out commodity producers.
- Commercial:Data center developers in Ireland and the Netherlands specify cellular concrete panels for thermal management, creating margin-rich channels distinct from generic construction supply.
- Residential:Volume concentration in mid-rise multifamily construction across Central Europe and western India, with developer procurement typically price-sensitive and grade-standardized.
- Industrial:Warehouse and manufacturing facility specifications emphasize floor slab dead-load reduction and fire separation, with less differentiation on thermal performance than commercial or residential segments.
Infrastructure commands the highest compliance barriers, while Commercial is gaining specification sophistication fastest through CSRD-linked sustainability auditing.
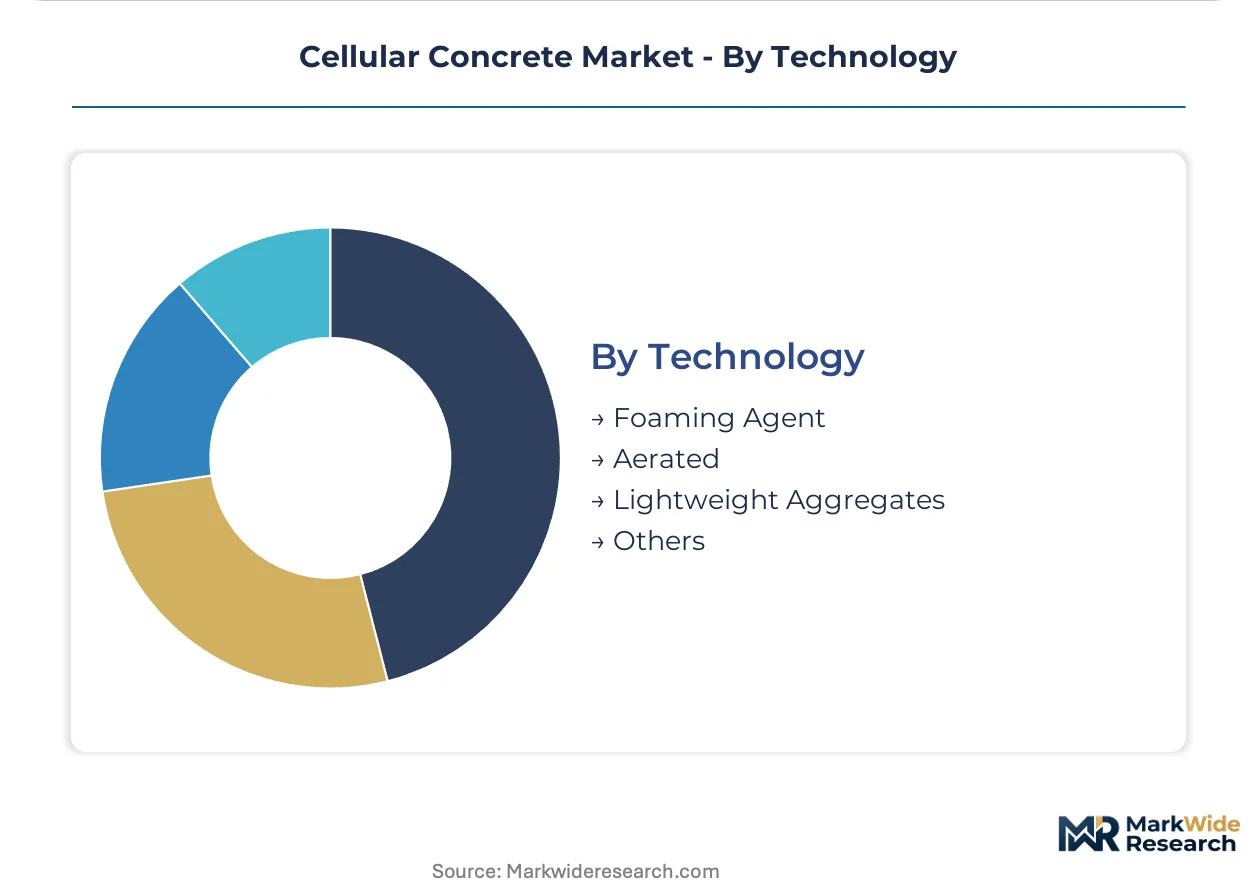
Technology:
Capital requirements and regulatory exposure divide production approaches, with mechanical foaming enabling distributed manufacturing that autoclave-dependent processes cannot match.
- Foaming Agent:Mechanical foaming systems using protein-based or synthetic surfactants offer project-specific density control and bypass autoclave capacity constraints, with EPA effluent guidelines in US Gulf Coast facilities accelerating bio-based reformulation.
- Aerated:Autoclave-cured processes dominate where capital-intensive steam-curing infrastructure already exists, particularly in Poland and Czech Republic production clusters that supply Central European panel demand.
- Lightweight Aggregates:Expanded shale or clay inclusion provides density reduction without foaming chemistry, suited to applications where effluent compliance costs or mix-design expertise scarcity excludes mechanical alternatives.
- Others:Emerging alkali-activated and geopolymer foams enable clinker-free formulations that bypass EU carbon-border adjustments, with Nordic producers leveraging blast-furnace slag access for marine applications requiring chloride resistance.
Foaming Agent systems lead in project flexibility, while Aerated retains scale advantages where existing autoclave capacity anchors supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances vary sharply across major cellular concrete markets, with integrated cement majors in Europe and North America maintaining raw-source dominance while Asian demand concentrates in domestic supply corridors. Trade flows reflect regulatory divergence on embodied-carbon accounting and local certification barriers.
Germany
Infrastructure agencies specify cellular concrete for tunnel backfill and seismic base isolation, creating specification pull for high-performance formulations. REACH-compliant foaming agents under ECHA restrictions accelerate bio-based surfactant adoption in precast plants. Production clusters in North Rhine-Westphalia supply Central European panel demand through factory-controlled curing systems.
Japan
METI-mandated seismic retrofits in public buildings drive demand for high-damping cellular concrete mix designs. JIS standards govern structural performance declarations, filtering out uncertified imports. Tokyo metropolitan contractors dominate specification channels for base-isolation projects requiring project-specific engineering guarantees.
India
State highway authorities in Maharashtra and Gujarat deploy embankment fill over soft deltaic soils, concentrating demand in the western coastal belt. BIS certification mandates density-graded product standards that delay import market entry by 14-18 months. Ahmedabad and Mumbai production corridors anchor domestic supply for public infrastructure tenders.
United States
EPA industrial effluent guidelines constrain foaming-agent chemistry in Gulf Coast manufacturing facilities, forcing synthetic surfactant reformulation. Data center developers in Virginia and Texas specify cellular concrete panels for thermal management in hyperscale facilities. Regional batching plants leverage mechanical foaming to bypass autoclave capacity constraints.
Netherlands
Passive-house developments redirect specification budgets toward cellular concrete's lambda-value advantages under tightening energy codes. CSRD-linked procurement creates audit-trail requirements favoring products with verified embodied-carbon documentation. Rotterdam-area contractors supply marine applications where chloride-resistant formulations matter.
Cellular Concrete Market Vendor Landscape
Concentration sits with integrated building materials conglomerates that leverage captive limestone reserves and cross-technology gypsum-to-concrete capabilities. Regional foaming specialists compete on project-specific mix design engineering for complex geotechnical briefs. Strategic moves center on clinker substitution programs and automated batching plant deployment that collapses minimum efficient scale thresholds.
Within the integrated materials tier, Saint-Gobain and LafargeHolcim exemplify archetypes combining raw-source dominance with specification channel control. Aerix Industries occupies a specialist position navigating geotechnical risk transfer in tunneling and seismic applications. These three anchors represent the spectrum from commodity scale to project-engineering capability.
| Leading Market Players |
|---|
| Saint-Gobain |
| LafargeHolcim |
| Xella Group |
| Aerix Industries |
| CEMEX |
| H+H |
| ACICO |
| Cematrix |
| Sika AG |
| Others |
Supply Flow & Price Mechanics
Autoclave capacity utilization in Poland and the Czech Republic anchors supply-side scale economies, compressing per-unit fixed costs for aerated panel producers while simultaneously elevating price floors for mechanical foaming specialists lacking comparable throughput. This divergence collapses as automated batching plants reduce minimum efficient scale, redistributing pricing power toward regional operators with project-specific mix design capabilities.
Pricing Analysis
Industrial OEM buyers anchor project-based contract pricing for cellular concrete, with three-tier pricing structure across premium, standard, and economy levels separating BIS-certified density grades from uncertified imports and commodity block formulations. Price differentiation rests on certification tier and volume scale, with Maharashtra public housing tenders commanding 15-20% premiums for certified products. Cost compression in standard-grade blocks is intensifying because clinker substitution programs erode raw-source advantages among integrated cement majors. Infrastructure agencies exhibit lowest price sensitivity, while residential developers in India's western states remain most cost-conscious.
Supply Chain Analysis
Just-in-time inventory preferences dominate mechanical foaming operations, while aerated producers in Central Europe maintain strategic stockpiles of autoclave-cured panels to buffer project timeline volatility. Geographic supply concentration centers on Germany, Poland, and India, with raw material dependencies drawing from captive limestone reserves, synthetic surfactant formulations, and blast-furnace slag for alkali-activated binders. Single-source vulnerability in REACH-compliant foaming agent chemistry elevates supply risk for German precast plants. Distribution runs through engineering-procurement-construction firms with in-house material-science capabilities, consolidating buying power among tier-one contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cellular concrete sits in early-cycle expansion as embodied-carbon accounting rules across European procurement offices accelerate material substitution away from conventional concrete. EU Green Deal implementation and tightening energy codes create structural tailwinds for low-density cementitious systems.
For Market Incumbents: Consolidate specification channel control through captive clinker substitution programs and backward integration into bio-based foaming agent production. Saint-Gobain's gypsum-to-concrete technology crossover exemplifies cross-technology leverage that defends margin position against emerging alkali-foam specialists. Automated batching plant deployment collapses minimum efficient scale thresholds, enabling regional capacity additions that preempt specialist encroachment in geotechnical applications. For New Entrants and Emerging Players: BIS certification fast-tracks in India open 14-18 month market entry pathways for density-graded products targeting Maharashtra and Gujarat state highway embankment tenders. Data center thermal envelope specifications in Ireland and the Netherlands present the most penetrable white-space, with CSRD-linked procurement creating audit-trail advantages for entrants with verified embodied-carbon documentation. Go-to-market positioning should emphasize project-specific performance guarantees rather than commodity grades. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors mechanical foaming specialists with geotechnical engineering capabilities over autoclave-dependent scale players facing stranded asset risk. Long-term viability across the analysis window hinges on clinker-free formulation portfolios that bypass EU carbon-border adjustments. Acquisition target archetype: regional foaming specialists with blast-furnace slag access and marine application track records. The signal to watch is alkali-activated foam specification share in Nordic infrastructure tenders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Foaming Agents | REACH compliance under ECHA restrictions secures specification access for German precast producers. |
| Automated Batching Plant Deployment | Distributed manufacturing compresses transport economics for Maharashtra road embankment projects. |
| Alkali-activated Formulation Development | Clinker-free binders bypass EU carbon-border adjustments while serving Danish marine specifications. |
| CSRD-linked Certification Investment | Verified embodied-carbon documentation unlocks hyperscale data center procurement in the Netherlands. |
| Geotechnical Engineering Capability Buildout | Project-specific mix design expertise filters out commodity competition in Japanese METI-mandated retrofits. |
Methodological Framework
Operator-level perspectives from plant managers at integrated cement majors, procurement leads at German infrastructure agencies, EPC contractors in tunneling applications, and technical R&D directors at foaming agent suppliers anchored the qualitative base. Secondary validation drew from EU Construction Products Regulation filings, BIS certification records, ECHA REACH substance registrations, and SEC disclosures from listed building materials conglomerates. Bottom-up project pipeline assessments and top-down construction spend forecasts were triangulated against production capacity databases.
Sensitivity analysis around clinker cost volatility, carbon-border adjustment implementation timing, and foaming agent chemistry reformulation costs framed the analytical approach across the projection horizon. Segmentation dimensions modeled include product type, application, end-user category, and production technology, with regional regulatory clusters capturing divergence in embodied-carbon accounting standards. CAGRs were derived from elasticity-adjusted demand curves incorporating energy-code stringency indices and infrastructure tender award patterns.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal implementation and stable BIS certification timelines; material deviation would warrant model refresh. Revision becomes warranted when alkali-activated foam specification share in public infrastructure crosses threshold penetration or when autoclave capacity constraints trigger supply rationing in Central European panel markets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Latin America Aluminum Door and Window Market
Building Materials
Concrete Admixtures Market
Building Materials
Roofing and Tile Underlayment Market
Building Materials
Middle East and Africa Concrete Admixtures Market
Building Materials
Asia-Pacific Facade Market
Building Materials
Building and Construction Plastics Market
Building Materials
Global Glass Fiber Reinforced Concrete Market
Building Materials
Asia-Pacific Building and Construction Sheets Market
Building Materials
Fire Resistant Mortar Market
Building Materials
India Dry Mix Mortar Market
Building Materials
Global Builders Joinery and Carpentry of Wood Market
Building Materials
United Kingdom Architectural Coatings Market
Building Materials
Engineered Stone Market
Building Materials
Qatar Facade Market
Building Materials
China Architectural Coatings Market
Building Materials
Global Lightweight Aggregate Concrete Market