
 North America Construction Aggregates Market | 2026-2036
North America Construction Aggregates Market Size, Share, and Industry Trends Forecast 2026-2036
North America Construction Aggregates Market Analytics
Subscription-based fleet management and telematics-enabled haul optimization is restructuring how aggregate producers monetize logistics capacity. Vulcan Materials Company leverages embedded sensor networks across its quarry-to-project delivery chain. Martin Marietta Materials sustains captive rail and barge networks that anchor its Southeast and Southwest distribution density. CRH Americas Materials differentiates through vertically integrated asphalt and ready-mix operations that tighten project-level coordination.
Construction aggregates are granular mineral materials—crushed stone, sand, gravel, and recycled concrete—graded by particle size distribution, abrasion resistance, and absorption rates for use in Portland cement concrete, asphalt binders, railroad ballast, and engineered fill. Crushed stone commands the largest value share due to its structural load-bearing performance in highway base courses and high-specification concrete. Sand segments compete on fineness modulus and silt content thresholds, with specialty silica grades capturing premium positioning in precast and masonry applications. Recycled aggregate occupies a narrowing but regulated niche as state DOTs relax substitution limits for non-structural fill and base layers.
Federal Highway Administration standards, EPA National Ambient Air Quality Standards for particulate matter, and state-level Department of Transportation material certification protocols collectively constrain quarry permitting and product eligibility for publicly funded projects. State environmental agencies in Texas, California, and Florida enforce additional groundwater monitoring and reclamation bonding requirements that extend project development timelines. Stakeholders must monitor how evolving Buy America domestic content thresholds and carbon intensity disclosure rules reshape supplier qualification criteria for infrastructure awards.
Market Dynamics
Federal infrastructure appropriations and EPA stormwater mandates are compressing quarry permitting timelines while simultaneously expanding material specification requirements for publicly funded projects.
Growth Catalysts
- Infrastructure Investment and Jobs Act disbursements:Highway rehabilitation programs across Texas, California, and Florida are accelerating aggregate consumption for base course and asphalt binder applications.
- Logistics corridor densification:Warehouse construction along the Texas Triangle and Inland Empire corridors is driving demand for engineered fill and high-specification concrete aggregates.
- Telematics-enabled fleet optimization:Real-time haul routing and payload monitoring systems are monetizing excess logistics capacity for mid-scale producers.
Market Restraints
- Diesel fuel cost volatility:Quarry-to-project haul economics remain exposed to petroleum price swings that compress margins on fixed-price municipal contracts.
- Permit approval timelines:EPA National Ambient Air Quality Standards and state groundwater monitoring protocols in California and Florida extend greenfield quarry development cycles.
- Natural sand depletion:Alluvial deposit exhaustion in the Midwest and Southeast is forcing substitution toward manufactured sand with higher processing energy intensity.
Strategic Opportunities
- Recycled content mandate expansion:State DOTs in Texas and California are relaxing substitution limits for crushed concrete in non-structural base layers.
- Rail-to-barge modal shift:Captive barge networks on the Mississippi and Ohio river systems offer untapped distribution reach for Gulf Coast producers.
- Carbon intensity disclosure requirements:Buy America domestic content thresholds are creating qualification advantages for regionally sourced aggregate suppliers.
Industry Challenges
- Geotechnical engineer scarcity:Specialized expertise in quarry design and reclamation bonding is concentrating among aging practitioner pools in the Mountain West.
- Legacy equipment integration:Retrofitting continuous processing lines with sensor networks for predictive maintenance requires capital outlays that strain family-owned operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Construction Aggregates Market |
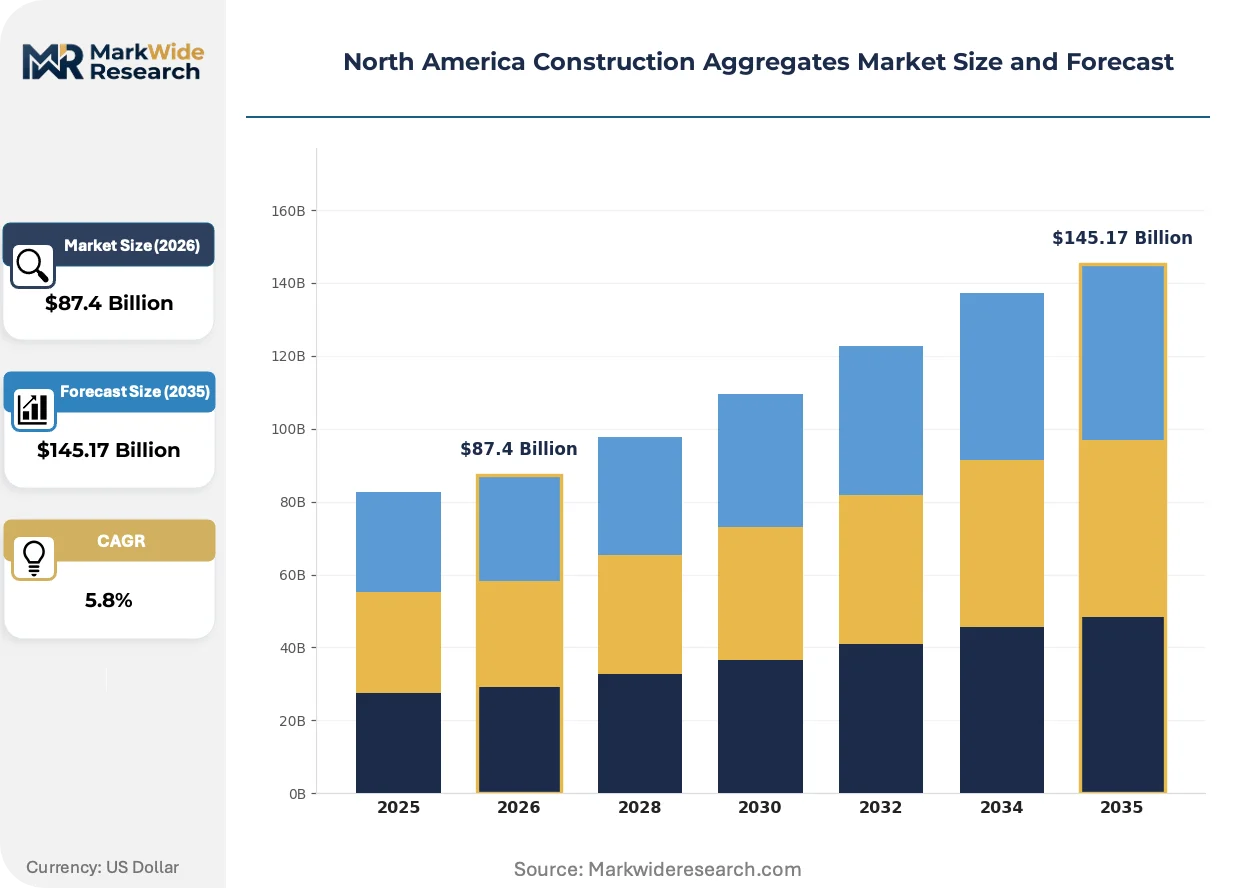
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $145.17 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crushed Stone, Sand, Gravel, Recycled Aggregate Application: Residential Construction, Commercial Construction, Infrastructure, Landscaping End User: Contractors, Government Agencies, Material Suppliers, Builders Distribution Channel: Direct Sales, Distributors, Online Sales, Retailers |
| Companies Covered | Heidelberg Materials, CEMEX USA, Vulcan Materials Company, Rogers Group, Summit Materials, Martin Marietta Materials, Holcim US, Knife River Corp., CRH Americas Materials, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Construction Aggregates Market Evolving Landscape
Digital quarry management and alternative material qualification are compressing traditional supply hierarchies while regulatory disclosure mandates reshape procurement specifications.
Electric haul truck pilot programs at select Texas and Arizona quarries are electrifying diesel-intensive load-haul-dump cycles. Large infrastructure contractors are trialing battery-electric articulated trucks for urban quarry-to-project routes under 50 miles. This electrification is compressing total cost of ownership calculations against diesel equivalents within five-year payback windows.
EPA stormwater general permit reauthorization is tightening sediment discharge thresholds for active quarry operations. Industrial consequence includes mandatory turbidity monitoring and adaptive management plans for sites above 5 disturbed acres. California and Florida aggregate producers are responding with closed-loop water recycling systems and polymer-based flocculation infrastructure.
Project-level carbon accounting is reshaping material specification preferences among design-build contractors. State DOTs in Texas and California are embedding embodied carbon thresholds into bid evaluation criteria, displacing lowest-unit-cost procurement. This specification shift is most visible in precast concrete and high-performance pavement contracts across the Southwest corridor.
North America Construction Aggregates Market Segmentation
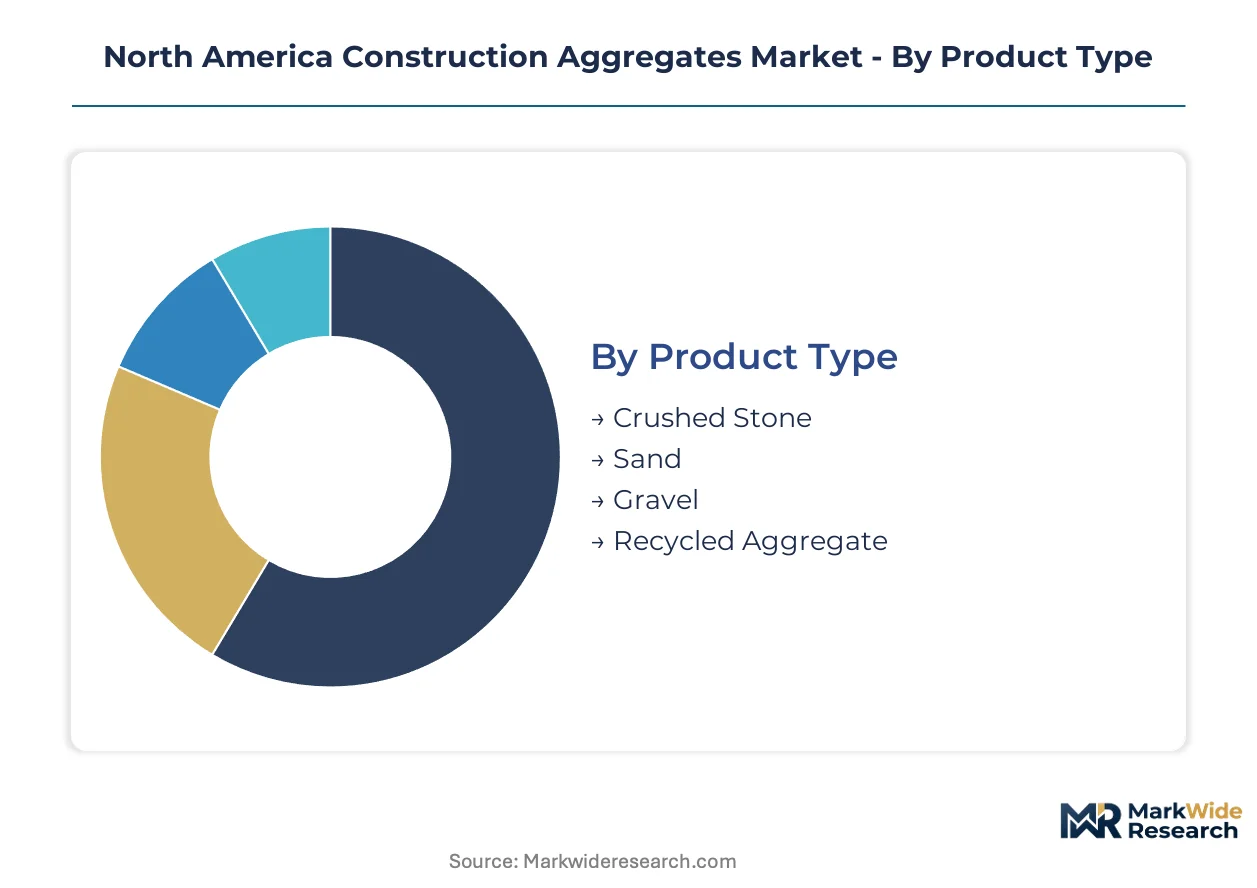
Product certification tiers and application specifications determine procurement pathways across North American construction aggregates. Segmentation reveals how material grades align with project funding sources and regulatory oversight intensity.
Product Type:
State DOT material certification protocols and EPA stormwater permit classifications impose divergent testing burdens across mineral categories.
- Crushed Stone:Igneous, sedimentary, and metamorphic rock processed to specified gradations for load-bearing applications. Demand concentrates in Texas Triangle highway base courses and high-specification concrete projects where Federal Highway Administration standards mandate Los Angeles abrasion resistance below 40 percent.
- Sand:Natural alluvial or manufactured granular material graded by fineness modulus and silt content. Consumption clusters in Southern California precast concrete and masonry applications where specialty silica grades command premium positioning against depleting riverbed deposits.
- Gravel:Unconsolidated mineral particles retained on 4.75mm sieves, typically employed in drainage layers and railroad ballast. Specifications follow American Railway Engineering and Maintenance-of-Way Association standards for mainline track substructure.
- Recycled Aggregate:Processed concrete, asphalt, and masonry debris screened to substitute for virgin materials in non-structural applications. State DOTs in Texas and California are relaxing substitution limits for base course and engineered fill layers.
Leading the category by volume: Crushed Stone. Growing fastest: Recycled Aggregate.
Application:
Funding authorization tiers separate federally reimbursed infrastructure from privately financed commercial development.
- Infrastructure:Highway, bridge, airport, and waterway projects governed by Federal Highway Administration and Army Corps of Engineers material specifications. Buy America domestic content thresholds and carbon intensity disclosure rules reshape supplier qualification criteria for infrastructure awards.
- Commercial Construction:Office, retail, logistics warehouse, and industrial facility development driven by private capital deployment. Warehouse construction along the Inland Empire and Texas Triangle corridors is driving demand for engineered fill and high-specification concrete aggregates.
- Residential Construction:Single-family and multifamily housing foundations, driveways, and hardscaping subject to local building code enforcement. Permitting velocity fluctuates with mortgage rate sensitivity and municipal capacity constraints.
- Landscaping:Decorative stone, pathway materials, and erosion control applications with minimal structural performance requirements. Seasonal demand patterns align with residential improvement cycles in Sun Belt metropolitan areas.
Highest specification burden: Infrastructure. Steepest expansion trajectory: Commercial Construction.
End User:
Procurement sophistication varies from municipal competitive bidding to integrated supply chain coordination.
- Government Agencies:State DOTs, county public works departments, and federal land management authorities awarding projects through sealed bid processes. EPA stormwater regulations and state-level recycled content mandates alter material specifications for publicly funded work.
- Contractors:General and specialty construction firms managing quarry-to-project logistics through telematics-enabled fleet optimization. Real-time haul routing systems monetize excess logistics capacity for mid-scale producers serving urban corridors.
- Builders:Production homebuilders and custom residential developers sourcing aggregates through established material supplier relationships. Volume commitments secure preferential pricing during peak construction seasons.
- Material Suppliers:Independent distributors and vertically integrated producers managing inventory positions across multiple quarry sources. Rail and barge network access anchors distribution density in the Southeast and Southwest.
Dominant procurement volume: Government Agencies. Fastest digitizing: Contractors.
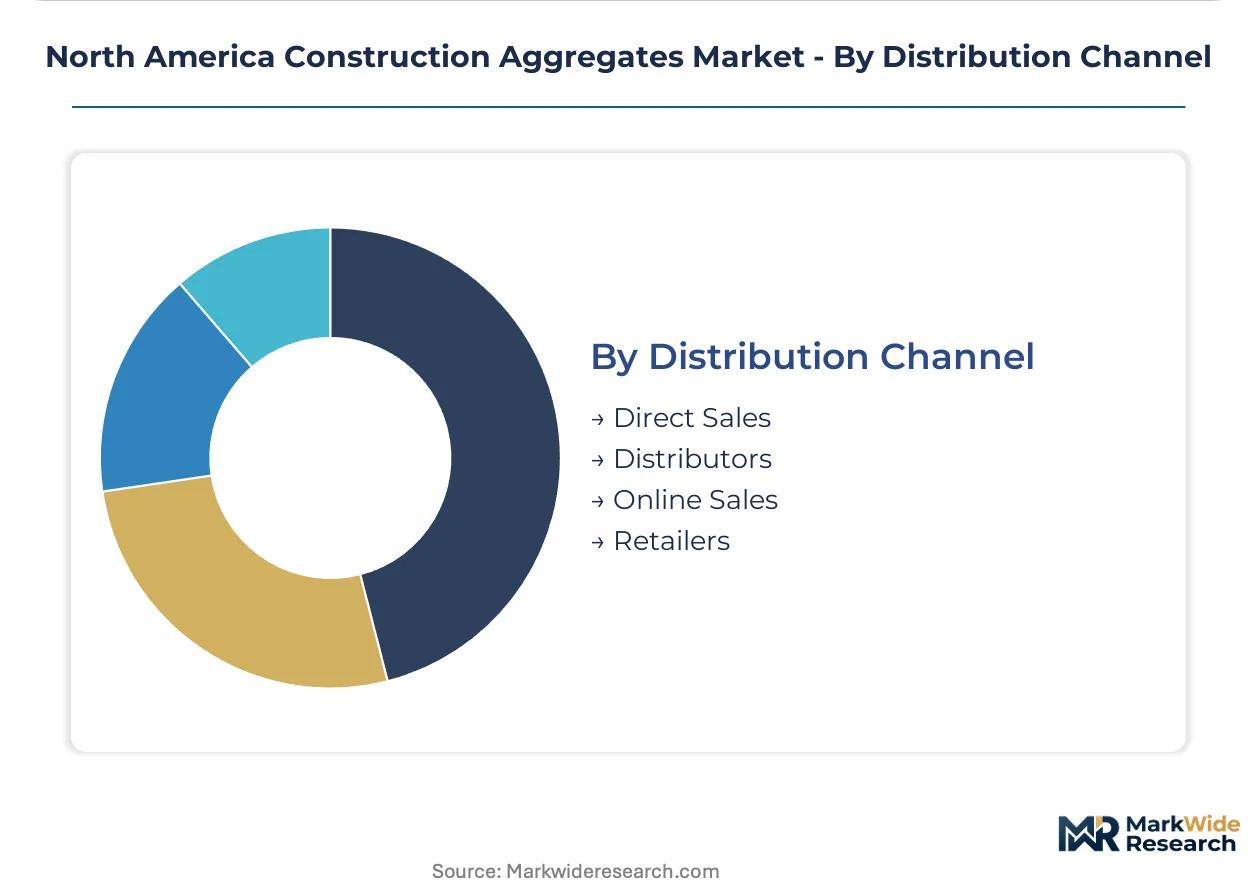
Distribution Channel:
Logistics infrastructure ownership separates captive delivery networks from third-party haul arrangements.
- Direct Sales:Quarry-to-project delivery coordinated through producer-controlled truck fleets and rail spurs. Captive barge networks on the Mississippi and Ohio river systems offer untapped distribution reach for Gulf Coast producers.
- Distributors:Independent intermediaries aggregating material from multiple quarries to serve dispersed construction sites. Inventory positioning near urban demand centers reduces haul distance economics for smaller contractors.
- Retailers:Home improvement and landscape supply yards serving residential and light commercial customers in bagged or bulk quantities. Seasonal staffing adjusts to spring and fall landscaping demand peaks.
- Online Sales:Digital platforms for material specification comparison and delivery scheduling, still nascent in heavy construction aggregates. Telematics integration enables real-time payload monitoring and route optimization.
Highest margin capture: Direct Sales. Channel expanding most quickly: Online Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aggregate production capacity concentrates in the Mountain West and Southeast while consumption gravity pulls toward coastal metropolitan corridors. This geographic mismatch forces long-haul logistics investments that reshape regional competitive economics. Permitting velocity varies sharply across state environmental agencies, fragmentating supply responsiveness.
United States
Texas Triangle highway rehabilitation and Inland Empire warehouse construction absorb the largest aggregate volumes nationally. EPA stormwater general permit reauthorization tightens turbidity discharge thresholds for quarries above five disturbed acres. Southern California silica sand extraction faces depletion constraints that elevate manufactured sand processing intensity.
Canada
Ontario's Golden Horseshoe infrastructure programs and Alberta oil sands remediation drive specialized aggregate demand. Health Canada coordinates with provincial regulators on quarry dust exposure limits that exceed federal baseline requirements. British Columbia coastal quarries supply engineered fill for Vancouver port expansion and seismic retrofit projects.
Mexico
Nuevo León industrial corridor development and Mexico City Metro rail extensions consume high-specification concrete aggregates. SEMARNAT environmental impact assessments extend greenfield quarry approval cycles beyond eighteen months. Bajío Region automotive manufacturing clusters source crushed stone for plant foundations and logistics parks.
Southeast United States
Florida DOT bridge replacement programs and Georgia logistics warehouse construction accelerate consumption of limestone base courses. State groundwater monitoring protocols in Florida impose reclamation bonding requirements that extend project development timelines. Atlanta metropolitan aggregate terminals anchor distribution networks serving Carolinas infrastructure corridors.
Pacific Northwest
Seattle-Tacoma port modernization and Oregon highway seismic upgrades drive demand for abrasion-resistant basalt aggregates. Washington State Department of Ecology enforces stormwater retention standards that mandate closed-loop water recycling at active quarries. Columbia River barge terminals enable cost-effective distribution to coastal construction markets.
North America Construction Aggregates Market Competitive Landscape
Capital-heavy producers compete with asset-light logistics specialists across differentiated quarry-to-project delivery models. The market structure consolidates around vertically integrated majors controlling captive rail and barge networks while regional independents survive on localized haul economics. Three archetypes dominate: scale-driven national operators, geography-focused regional consolidators, and specialty recycled material processors. Competitive intensity centers on M&A-driven reserve base expansion and telematics-enabled fleet optimization that monetizes excess logistics capacity.
Within the integrated-major tier, Vulcan Materials Company and Martin Marietta Materials exemplify scale-driven positioning through embedded sensor networks and captive distribution infrastructure. Heidelberg Materials anchors European-headquartered multinational presence with North American quarry assets. Summit Materials represents the regional-consolidator archetype through decentralized operational models. CEMEX USA and Holcim US occupy positions as cement-major affiliates leveraging downstream concrete integration. CRH Americas Materials exemplifies vertically integrated asphalt and ready-mix coordination that tightens project-level supply chain responsiveness.
| Leading Market Players |
|---|
| Heidelberg Materials |
| CEMEX USA |
| Vulcan Materials Company |
| Rogers Group |
| Summit Materials |
| Martin Marietta Materials |
| Holcim US |
| Knife River Corp. |
| CRH Americas Materials |
| Others |
Value Network & Pricing Analysis
Electric haul truck pilot programs across Texas and Arizona quarries simultaneously compress diesel cost exposure and concentrate production economics among capitalized operators capable of absorbing fleet conversion outlays. This electrification transition reshapes competitive positioning by tethering pricing power to logistics infrastructure ownership rather than reserve base scale alone.
Pricing Analysis
Margin tightening in municipal contract tiers reflects diesel fuel cost volatility that compresses returns on fixed-price highway rehabilitation awards. Contract-based long-term offtake structures dominate infrastructure procurement, with price differentiation resting on Los Angeles abrasion certification grade and volume scale commitments. Cost-down pressure on spot market deliveries accelerates as manufactured sand substitution elevates processing energy intensity. State DOTs exhibit lowest price sensitivity due to Federal Highway Administration specification rigidity, while residential builders face acute margin compression during mortgage rate volatility.
Supply Chain Analysis
Freight economics anchor competitive positioning across the Mountain West extraction belt and Texas Triangle consumption corridor. Production concentrates in the United States, Canada, and Mexico with cross-border rail spurs enabling cost-effective distribution to coastal metropolitan markets. Raw material dependencies center on diesel fuel, explosive ammonium nitrate, and steel wear components for crushing equipment. Single-source vulnerability concentrates in alluvial sand deposits facing depletion across the Midwest and Southeast. Distribution runs through captive barge networks on the Mississippi and Ohio river systems, third-party trucking fleets, and rail-to-truck transload terminals serving urban construction corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
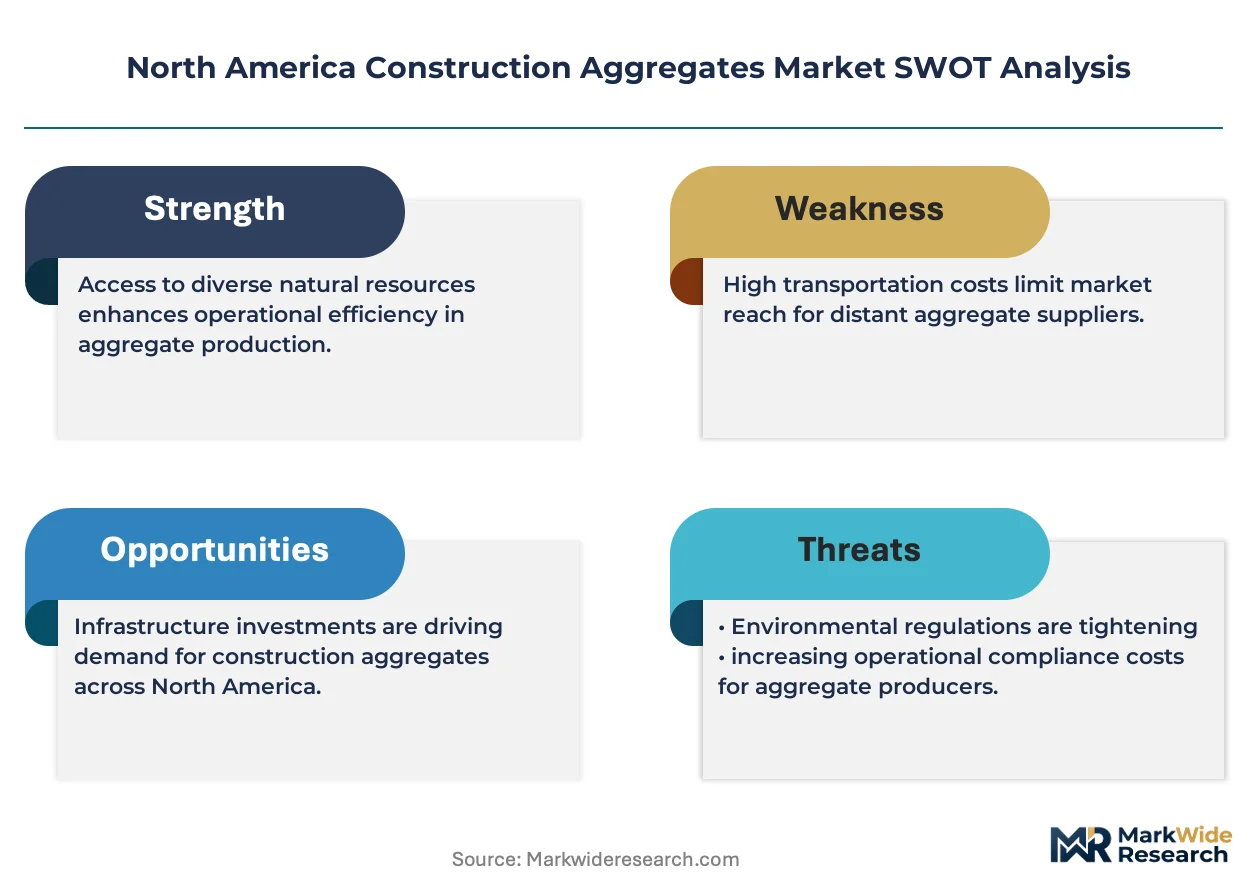
EPA National Ambient Air Quality Standards for particulate matter create a compliance moat that favors incumbent producers with established permitting track records and reclamation bonding capacity. This regulatory barrier-to-entry structure rewards early investment in closed-loop water recycling and adaptive management infrastructure.
For Market Incumbents: Anticipate recycled aggregate substitution limits relaxing in Texas and California by securing crushed concrete processing capacity ahead of state DOT specification revisions. Deepen captive rail and barge network control to defend logistics margin position against diesel price volatility. Prioritize telematics-enabled fleet optimization that monetizes excess haul capacity during demand troughs.
For New Entrants and Emerging Players: Launch via specialty silica sand positioning in Southern California precast concrete applications where riverbed depletion creates supply gaps and premium pricing tolerance. Target engineered fill contracts for Texas Triangle logistics warehouse construction where rapid permit velocity favors nimble operators. Pursue carbon intensity disclosure advantages through regional sourcing certifications that qualify for Buy America domestic content thresholds.
For Investors and Strategic Acquirers: Exit pathways concentrate in regional consolidator acquisitions by scale-driven national operators seeking reserve base expansion in the Southeast and Southwest. Long-term viability favors vertically integrated asphalt and ready-mix operations with project-level supply chain coordination capabilities. Monitor state-level recycled content mandate expansion as the inflection signal for recycled aggregate processor valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Barge Network Expansion | Mississippi River terminal access reduces Gulf Coast producers' exposure to diesel haul economics. |
| Recycled Aggregate Processing Scale-Up | Texas DOT specification relaxation creates first-mover advantage in crushed concrete base course supply. |
| Telematics Fleet Integration | Real-time payload monitoring monetizes excess logistics capacity for mid-scale quarry operators. |
| Carbon Intensity Certification Investment | Embodied carbon thresholds in California DOT bid criteria reward regionally sourced material suppliers. |
| Electric Haul Truck Pilot Conversion | Battery-electric articulated trucks compress total cost of ownership against diesel equivalents within five-year payback windows. |
Research Methodology
SEC 10-K filings, state DOT material certification databases, and EPA stormwater permit records formed the secondary backbone for reserve base and production capacity estimation. Quarry operations managers, geotechnical engineers, and infrastructure contractor procurement leads provided primary field intelligence on specification evolution and logistics cost structures. Customs and trade data on aggregate equipment imports supplemented domestic manufacturing capacity assessments. Bottom-up quarry-level production estimates triangulated against top-down construction spending forecasts across the analysis window.
Historical trendline analysis of Federal Highway Administration obligation authority and state-level infrastructure appropriations anchored demand-side modeling. Segmentation dimensions included product type, application tier, end-user procurement sophistication, and distribution channel ownership structure. CAGRs derived from regression analysis of construction spending intensity against population growth corridors. Forecast inputs incorporated EPA stormwater permit reauthorization timelines and state-level recycled content mandate adoption trajectories.
Diesel fuel price volatility, quarry permitting approval delays, and natural sand deposit depletion rates are the dominant revision risks to production capacity assumptions. Forecasts reflect documented assumptions about infrastructure appropriation continuity and regulatory specification stability. Stakeholders should weight assumptions against their own operating context and regional permit velocity experience.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Construction Glass Market
Building Materials
Roof Cover Boards Market
Building Materials
Fireproof Cladding Market
Building Materials
Concrete Admixtures Market
Building Materials
Mexico Architectural Coatings Market
Building Materials
Earthen Plasters Market
Building Materials
Indonesia Architectural Coatings Market
Building Materials
Precast Concrete Retaining Walls Market
Building Materials
Construction Materials Market
Building Materials
Foam Bricks Market
Building Materials
Cement Market
Building Materials
Africa Aluminum Door and Window Market
Building Materials
Latin America Aluminum Door and Window Market
Building Materials
Bolt (Fastener) Market
Building Materials
Fiber Reinforced Polymer Composites (FRP) Market
Building Materials
Indonesia Dry Mix Mortar Market