

Bio-Based Structural Wood Adhesives for Modular Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Based Structural Wood Adhesives for Modular Construction Market Insights
Petroleum-derived phenol-formaldehyde is decoupling from engineered wood panel specifications as bio-based tannin and lignin formulations achieve comparable shear strength at competitive curing temperatures. Henkel AG & Co. KGaA leverages its European adhesive R&D network to anchor development of formaldehyde-free structural bonding systems. Stora Enso sustains upstream integration from Nordic forest holdings through to adhesive-ready engineered timber products. Arkema competes on specialty epoxy hardeners derived from renewable feedstocks, positioning its portfolio for modular factory specifications.
Bio-based structural wood adhesives for modular construction comprise bonding systems formulated from renewable precursors such as tannins, lignins, proteins, and polysaccharides, designed to achieve minimum wood failure percentages and creep resistance under sustained load per EN 15416 and ASTM D7247 test protocols. These adhesives serve the primary industrial purpose of creating load-bearing engineered wood products that qualify for Type I durability exposure in factory-built modules. Polyurethane adhesives lead product type demand due to superior gap-filling performance in mass timber beam assembly, while waterborne technology dominates formulation development as VOC thresholds tighten across European and North American building codes. Prefabricated panels and wall systems anchor application volume, though roof assemblies represent the fastest-growing segment as pitched timber roofs gain share in multi-story modular residential projects.
EMA and ECHA frameworks in Europe mandate REACH-compliant substance registration for construction adhesives, while the EU Green Deal's embodied carbon reporting requirements are pushing modular builders toward bio-based bonding certifications. In the United States, EPA TSCA Section 6 restrictions on formaldehyde emissions from composite wood products directly expand addressable market for bio-based structural alternatives in HUD-code and state-level modular programs. Stakeholders must monitor evolving harmonization between ISO 12466 wood adhesive durability standards and national building approval pathways, as divergence between European CE-marking and North American ICC-ES evaluation criteria threatens to fragment product qualification timelines.
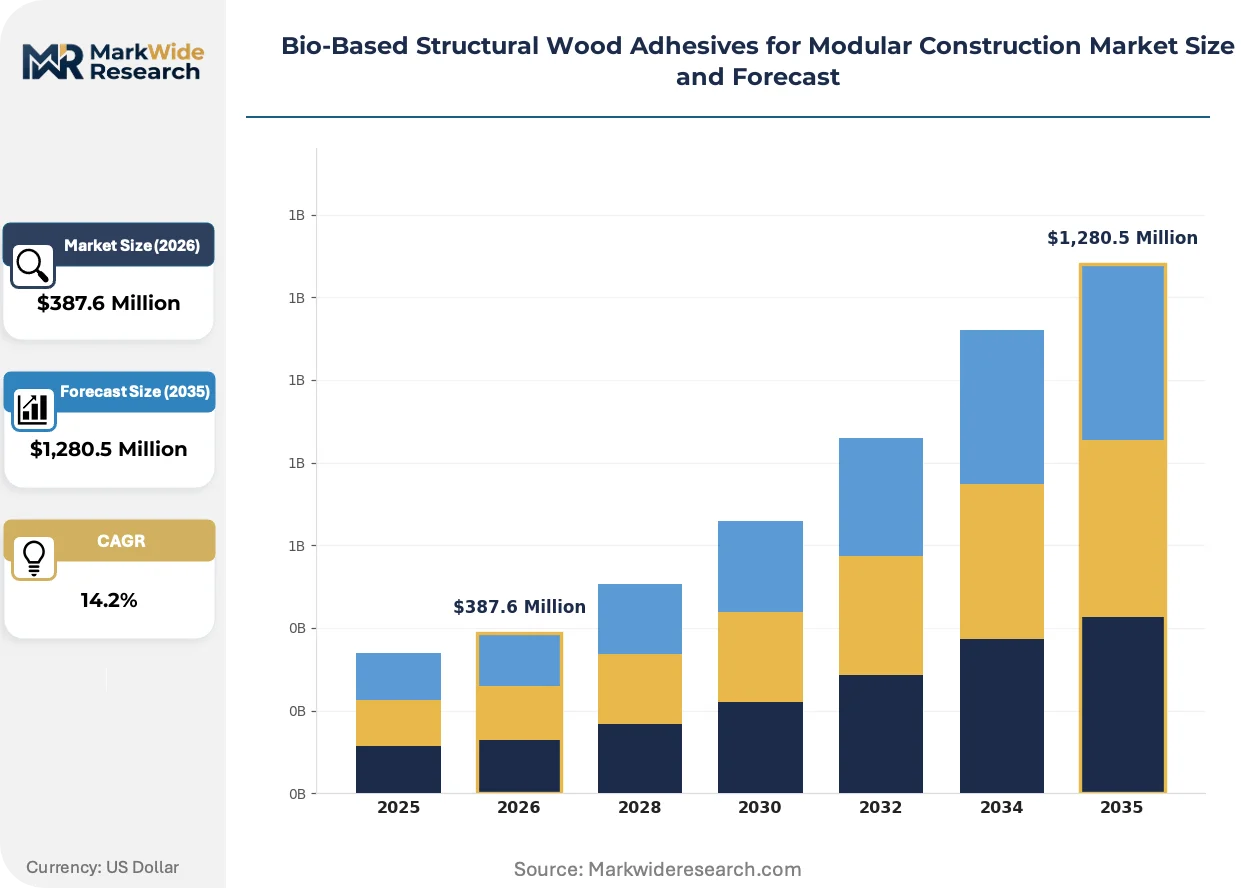
Market Dynamics
Petroleum-derived phenol-formaldehyde adhesives face systematic displacement as bio-based tannin and lignin formulations achieve structural parity at competitive curing temperatures, compressing specification timelines across engineered wood panel manufacturing.
Growth Catalysts
- EU F-Gas Regulation:Chemical disclosure mandates under the EU Green Deal are accelerating modular builder procurement of certified bio-based bonding systems for cross-laminated timber assemblies.
- Mass timber beam assembly:Polyurethane adhesives with superior gap-filling performance are capturing specification share in factory-built module production for multi-story residential projects.
- German timber engineering clusters:Stuttgart and Munich specification networks are driving certified structural bonding system adoption across Central European modular construction supply chains.
Market Restraints
- Tannin feedstock concentration:Supply of condensed tannins from quebracho and mimosa bark concentrates in South American extractive regions, exposing formulators to harvest volatility and currency fluctuation.
- Cure temperature requirements:Lignin-based adhesives require elevated pressing temperatures that exceed capabilities of legacy modular factory hot-press equipment, constraining retrofit economics.
- Petroleum resin price anchoring:Conventional phenol-formaldehyde maintains cost advantage at scale, compressing margin structures for bio-based alternatives in price-sensitive HUD-code modular programs.
Strategic Opportunities
- Pitched timber roof assemblies:Multi-story modular residential projects in Nordic markets are specifying bio-based structural adhesives for load-bearing roof systems, expanding application beyond wall panels.
- Waterborne formulation development:Tightening VOC thresholds across European and North American building codes are opening specification pathways for low-emission bio-based bonding technologies.
- CE marking harmonization:Convergence between ISO 12466 durability standards and national building approval pathways could streamline product qualification timelines for cross-border modular suppliers.
Industry Challenges
- Certification timeline compression:Divergence between European CE-marking and North American ICC-ES evaluation criteria is fragmenting product qualification pathways, forcing dual-track testing investments.
- Adhesive chemist talent scarcity:Formulation expertise spanning wood science, polymer chemistry, and construction code compliance concentrates in aging technical workforces across adhesive manufacturers.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Based Structural Wood Adhesives for Modular Construction Market Trends and Innovations
Digital manufacturing integration and feedstock traceability systems are compressing development cycles for structural bio-adhesives, while regulatory carbon accounting is embedding material provenance into specification logic.
Hot-melt polyurethane reactive systems are decentralizing production workflows by enabling ambient-temperature curing in modular factory environments, eliminating energy-intensive hot-press bottlenecks. Prefabricated panel manufacturers in Germany and Austria are adopting these systems for cross-laminated timber wall production, reducing factory reconfiguration costs and accelerating line changeovers between product specifications.
REACH substance registration requirements under ECHA frameworks are mandating granular chemical disclosure for construction adhesives, forcing reformulation of legacy bonding systems. Modular builders in France and the Netherlands are responding by pre-qualifying suppliers with complete substance transparency, shifting procurement criteria toward certified bio-based alternatives ahead of formal mandate deadlines.
Buyer concentration among large modular developers is compressing supplier qualification timelines and unbundling technical service from material supply contracts. Tier-one modular factory operators in Sweden and Finland are consolidating adhesive procurement through direct specification agreements, bypassing traditional distributor channels and demanding dedicated R&D support as a contract condition.
Bio-Based Structural Wood Adhesives for Modular Construction Market Segmentation
Modular construction procurement teams evaluate adhesives across multiple technical and commercial dimensions simultaneously. Specification decisions hinge on curing temperature compatibility with factory equipment, code compliance for structural exposure ratings, and embodied carbon credentials under tightening disclosure mandates.
Product Type:
Buyers prioritize gap-filling performance and cure speed when selecting adhesive chemistry for mass timber production lines.
- Epoxy:Two-part systems formulated with renewable hardeners deliver exceptional shear strength for primary structural joints in cross-laminated timber. German modular factories specify these for load-bearing wall connections where EN 15416 durability certification is mandatory.
- Polyurethane:Reactive systems dominate factory-floor specifications due to superior gap tolerance in irregular timber surfaces and ambient-temperature curing that eliminates hot-press bottlenecks. Swedish and Finnish manufacturers specify moisture-cure polyurethanes for beam-to-column connections in multi-story residential modules.
- Polyvinyl Acetate:Waterborne emulsions serve interior non-structural applications where formaldehyde-free credentials support green building certifications.
- Phenolic:Tannin-modified formulations replace petroleum-derived resins in exterior-grade panel bonding for Type I durability exposure.
- Melamine:Hybrid systems combine with urea-formaldehyde alternatives for cost-sensitive HUD-code modular programs requiring moderate moisture resistance.
- Isocyanate:pMDI variants derived from bio-based polyols penetrate engineered strand board production for structural floor cassettes.
Volume sits with polyurethane systems; growth tilts toward epoxy formulations as high-rise timber construction expands.
Application:
Assembly location within the building envelope determines moisture exposure ratings and corresponding adhesive durability requirements.
- Prefabricated Panels:Factory-built wall and floor cassettes use automated dispensing systems for consistent bond-line thickness. Austrian manufacturers integrate hot-melt polyurethane reactive systems for CLT panel production, compressing cycle times.
- Wall Systems:Vertical load-bearing assemblies demand creep-resistant formulations certified for sustained dead and live loads per ASTM D7247 protocols. Stuttgart engineering consultancies specify bio-based structural adhesives for multi-story modular residential projects.
- Flooring:Engineered joist and subfloor assemblies utilize moisture-cure systems tolerant of construction-phase humidity variation.
- Roof Assemblies:Pitched timber roof structures specify adhesives with enhanced thermal cycling resistance for Nordic climate exposure.
- Beam Assembly:Glulam and LVL connection points require gap-filling formulations accommodating natural timber dimensional variation.
- Partition Systems:Non-load-bearing interior divisions utilize lower-strength waterborne systems where fire rating supersedes structural demand.
Prefabricated panels capture the largest share; roof assemblies climb the fastest as timber-framed pitched roofs penetrate mid-rise residential construction.
End User:
Technical sophistication and procurement scale vary sharply across buyer categories, fragmenting supplier engagement models.
- Construction Firms:General contractors specify adhesive systems through performance-based subcontractor agreements, prioritizing warranty transfer and installation speed.
- Modular Builders:Factory operators consolidate procurement through direct specification agreements, demanding dedicated R&D support and batch traceability systems.
- Engineering Consultancies:Stuttgart and Munich-based timber engineering clusters drive certified structural bonding system adoption through specification authority in Central European markets.
- Structural Contractors:Site-based assembly crews require ambient-cure systems compatible with field moisture conditions and limited climate control.
- Timber Product Manufacturers:Engineered wood panel producers integrate adhesive selection into continuous press line configurations, locking in multi-year supply contracts.
Modular builders concentrate purchasing volume; engineering consultancies steer fastest-growing specification influence as design-build integration deepens.
Technology:
Formulation chemistry and cure mechanism determine factory capital requirements and emissions profile under evolving building codes.
- Cross-linking:Covalent bond formation between bio-based polymers and wood substrates enhances creep resistance under sustained load for primary structural applications.
- Thermosetting:Irreversible cure chemistry dominates exterior-grade specifications where dimensional stability through moisture cycling is non-negotiable.
- Waterborne:Low-VOC emulsion systems capture specification share as EPA TSCA and EU Green Deal disclosure requirements tighten across North American and European jurisdictions.
- Solvent-free:Elimination of volatile carriers supports factory air quality compliance and worker exposure limits in continuous production environments.
- Hot Melt:Reactive polyurethane hot-melt systems enable ambient-temperature curing, eliminating energy-intensive press equipment retrofits in legacy modular factories.
- Reactive:Moisture-cure and two-part systems provide tunable working times for automated and manual assembly operations respectively.
Waterborne formulations lead current volume; hot-melt reactive systems gain share fastest as factory energy costs and reconfiguration economics reshape technology selection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Modular builders in Germany concentrate procurement of certified bio-based bonding systems, while timber engineering clusters across Stuttgart and Munich anchor specification authority for cross-laminated timber wall systems.
Germany
Stuttgart and Munich engineering consultancies specify EN 15416-certified structural adhesives for multi-story residential modules. The EU Green Deal's embodied carbon reporting requirements push modular factories toward bio-based alternatives ahead of formal deadlines. Bavarian timber clusters around Rosenheim integrate hot-melt polyurethane systems for CLT panel production.
United States
HUD-code and state-level modular programs expand addressable market for formaldehyde-free alternatives as EPA TSCA Section 6 restrictions tighten. Pacific Northwest mass timber projects specify bio-based adhesives for cross-laminated timber beam connections. Oregon and Washington factory operators consolidate procurement through direct specification agreements with dedicated R&D support demands.
Sweden
Tier-one modular factory operators specify moisture-cure polyurethanes for beam-to-column connections in multi-story residential modules. REACH-compliant substance registration under ECHA frameworks mandates granular chemical disclosure, forcing supplier pre-qualification. Stockholm and Gothenburg manufacturing clusters adopt reactive hot-melt systems to eliminate energy-intensive press bottlenecks.
Austria
Prefabricated panel manufacturers integrate automated dispensing systems for consistent bond-line thickness in CLT wall cassettes. Tightening VOC thresholds across European building codes open specification pathways for waterborne bio-based technologies. Upper Austrian timber regions around Wels and Linz anchor production of adhesive-ready engineered timber products.
Finland
Nordic climate exposure specifications drive demand for adhesives with enhanced thermal cycling resistance in pitched timber roof assemblies. EMA and ECHA frameworks mandate complete substance transparency, shifting procurement criteria toward certified bio-based bonding systems. Helsinki and Tampere modular developers consolidate adhesive procurement through bypassing traditional distributor channels.
Bio-Based Structural Wood Adhesives for Modular Construction Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with adhesive formulators and engineered wood producers occupying distinct competitive positions. Market structure tilts toward consolidation among European chemical conglomerates with captive R&D networks, while regional specialists compete on formulation customization for factory-specific curing equipment. Three archetypes dominate: diversified chemical majors with construction adhesive portfolios, forest products companies with downstream integration into bonding systems, and specialty chemical developers focused on renewable feedstock hardeners. Competitive moves center on backward integration into tannin and lignin feedstock supply, plus technology licensing partnerships to compress qualification timelines across dual-track CE-marking and ICC-ES evaluation pathways.
Among European-based chemical conglomerates, Henkel AG & Co. KGaA and Arkema exemplify the diversified major archetype, leveraging established adhesive R&D infrastructure to anchor development of formaldehyde-free structural bonding systems. Stora Enso occupies a distinct position representing forest products verticalization, with upstream control over Nordic forest holdings flowing through to adhesive-ready engineered timber products. These three companies illustrate the competitive tension between chemical formulation expertise and captive raw material access in modular construction specification battles.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Arkema |
| H.B. Fuller Company |
| Sika |
| 3M |
| Ashland |
| Stora Enso |
| UPM-Kymmene Corporation |
| BioBond Adhesives |
| Others |
Pricing and Supply Chain Analysis
Condensed tannin feedstock costs from South American quebracho and mimosa bark extraction cascade through three distinct pricing tiers, with certified EN 15416-compliant formulations commanding premium positioning over conventional phenol-formaldehyde alternatives in German modular factory procurement.
Pricing Analysis
Volume concentrates in polyurethane systems sold through contract-based long-term offtake agreements, while margin accrues to epoxy formulations with renewable hardener content. Price differentiation separates CE-marked structural grades from economy-tier HUD-code alternatives, with certification investment and volume scale as the primary drivers. Cost compression in the standard tier is intensifying because petroleum resin price anchoring constrains bio-based alternatives. Modular builders in price-sensitive North American programs exhibit highest price sensitivity; engineering consultancies in Stuttgart and Munich clusters demonstrate lowest sensitivity due to specification authority.
Supply Chain Analysis
Direct-to-OEM channels handle tier-one modular factory demand in Germany, Sweden, and Finland, bypassing traditional distributor networks. Supply concentrates in Brazil and Argentina for condensed tannins, with Nordic forest holdings feeding lignin feedstock streams. Raw material dependencies center on quebracho bark extract, mimosa tannin, and bio-based polyol precursors. Single-source vulnerability from South American harvest volatility threatens formulator margin stability. Distribution runs through direct specification agreements with dedicated R&D support as a contract condition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around formulators with captive feedstock access, as REACH-compliant substance registration mandates under ECHA frameworks force smaller players into prohibitive dual-track testing investments for CE-marking and ICC-ES pathways.
For Market Incumbents: Lock in backward integration into Nordic forest holdings or South American tannin extraction to secure feedstock cost visibility against currency fluctuation. Expand hot-melt polyurethane reactive capacity in Bavarian timber clusters around Rosenheim to capture factory reconfiguration demand. Prioritize certification investment in ISO 12466 harmonization to compress qualification timelines before regulatory divergence hardens. For New Entrants and Emerging Players: Engineering consultancies in Stuttgart and Munich represent the most penetrable specification gate, as their influence over multi-story modular residential projects remains undercontested by bio-specialist formulators. Target pitched timber roof assemblies in Nordic markets, where thermal cycling resistance requirements create white-space for differentiated adhesive development. Pursue white-label partnerships with Austrian prefabricated panel manufacturers seeking automated dispensing system integration. For Investors and Strategic Acquirers: First-mover adoption of hot-melt reactive systems by Stockholm and Gothenburg manufacturing clusters is the leading indicator that factory energy cost economics are shifting procurement criteria decisively. The 5-10 year viability window favors acquisition of specialty chemical developers with renewable feedstock hardener expertise and existing ECHA substance registration portfolios. Watch for consolidation signals when tier-one modular operators begin unbundling technical service from material supply contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tannin Feedstock | Captive quebracho and mimosa supply secures cost visibility against South American currency volatility. |
| Hot-Melt Reactive System Capacity Expansion | Rosenheim and Bavarian timber clusters demand ambient-cure systems to eliminate press bottlenecks. |
| Dual-Track Certification Investment | Parallel CE-marking and ICC-ES pathways compress product qualification timelines for cross-border suppliers. |
| Direct Specification Agreements | Swedish and Finnish tier-one factories consolidate procurement through bypassing distributor channels. |
| Waterborne Formulation Development | EPA TSCA and EU Green Deal VOC thresholds open specification pathways for low-emission bonding technologies. |
Research Methodology
Document review covered ECHA REACH registration databases, EU Green Deal policy frameworks, and ASTM/EN wood adhesive durability standards, complemented by interviews with adhesive R&D directors at European chemical conglomerates, procurement leads at German modular factories, timber engineering consultants in Stuttgart and Munich, and plant managers at Austrian CLT panel manufacturers. Secondary validation drew from customs trade data on tannin and lignin feedstock flows, SEC filings of diversified chemical majors, and national building code adoption tracking. Bottom-up demand modeling from factory-level adhesive consumption triangulated against top-down market sizing from engineered wood panel production forecasts.
Market size and growth trajectory outputs reflect segmentation across product type, application, end user, and technology dimensions, with additional modeling of cure temperature compatibility and certification tier penetration. CAGRs were derived from regression analysis of historical specification shifts and forward projection of regulatory mandate timelines. Key forecast inputs included EU F-Gas Regulation implementation pacing, EPA TSCA Section 6 enforcement intensity, and modular factory capital expenditure cycles for hot-press equipment replacement.
Caveats apply where South American harvest volatility, currency fluctuation, or divergence between ISO 12466 and national building approval pathways could materially shift the outlook. Forecasts reflect base-case assumptions on regulatory harmonization and feedstock supply continuity. Periodic stress-testing of base assumptions against EMA and ECHA framework evolution is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.