
 Natural Stone Slab Market | 2026-2036
Natural Stone Slab Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Stone Slab Market Intelligence
Italian quarries and Brazilian processing clusters are recalibrating output schedules after prolonged energy cost volatility across Europe. Cosentino leverages its integrated slab production and distribution network to sustain pricing power in North American specification channels. Levantina anchors Mediterranean supply through its captive quarry positions in Spain and Portugal. Polycor competes aggressively in the heritage restoration segment where domestic sourcing requirements favor its North American granite deposits.
Natural stone slabs are dimension stone products cut from quarried blocks, typically finished to thicknesses of two or three centimeters for structural and decorative surfacing applications. These materials serve primarily as load-bearing cladding, interior finishes, and prestige countertops where mineral composition and veining patterns determine aesthetic and performance grades. Granite and quartzite command premium positioning in high-traffic commercial flooring due to superior Mohs hardness ratings and abrasion resistance. Marble dominates interior specification for luxury residential and hospitality projects where distinctive veining justifies higher material and maintenance costs. Limestone occupies a mature niche in exterior cladding and historical restoration where porosity and weathering characteristics align with conservation standards.
REACH compliance in the European Union and OSHA silica exposure limits in the United States are reshaping quarrying and fabrication workflows, forcing capital investment in water-based cutting and automated polishing systems. India's BIS certification requirements for dimension stone exports are raising quality thresholds for Rajasthan and Andhra Pradesh processors seeking premium market access. China's GB standards for radioactive emission levels in building materials restrict certain granite varieties from interior residential use. Stakeholders must monitor evolving embodied carbon accounting methodologies and regional procurement mandates that increasingly favor domestically sourced or low-carbon-processed stone over long-haul imports.
Market Dynamics
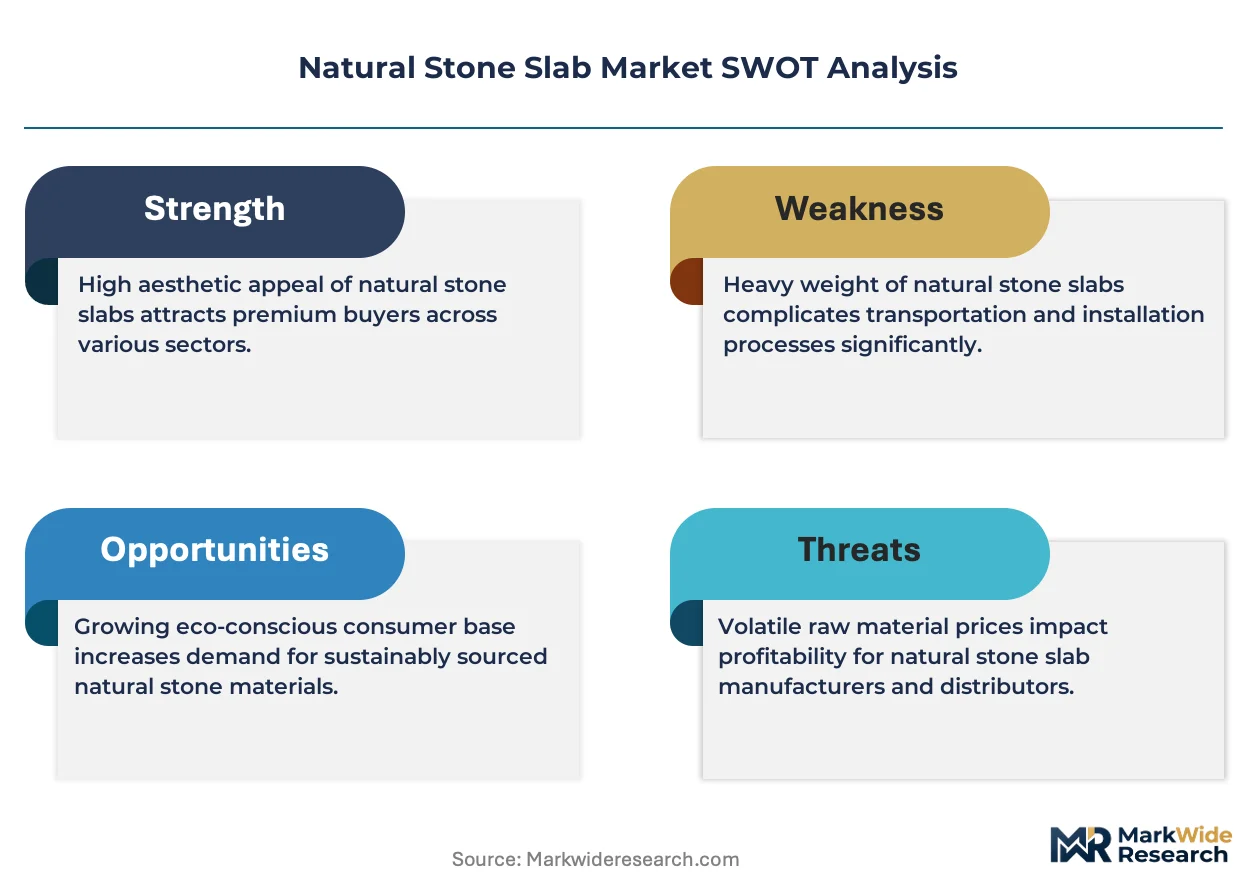
EU Green Deal embodied carbon disclosure mandates are forcing quarry operators and fabricators to reconfigure supply chains around verified low-carbon processing methods, compressing margins for long-haul importers while rewarding captive quarry-to-slab integration.
Growth Catalysts
- Luxury Hospitality Specification:Dubai and Riyadh developers are expanding book-matched marble installations in premium hotel lobbies and suites, pulling volume from Mediterranean quarries.
- REACH Compliance Investment:Water-based cutting systems and automated polishing workflows are unlocking premium EU market access for processors who retrofit capital equipment.
- China Tier-One Urbanization:Premium residential developments in Shanghai and Shenzhen specify imported granite and quartzite finishes, concentrating demand in high-value segments.
Market Restraints
- Energy Cost Volatility:Italian quarries and Brazilian processing clusters face margin compression from prolonged European electricity price instability.
- Radioactive Emission Limits:China's GB standards restrict certain granite varieties from interior residential applications, eliminating specified deposits from consideration.
- Engineered Stone Substitution:Sintered compact surfaces and quartz composites capture mid-market countertop specification through consistent supply and lower maintenance requirements.
Strategic Opportunities
- Heritage Restoration Demand:Conservation-grade limestone specification for historical building facades creates premium niches where porosity and weathering characteristics justify specialized sourcing.
- Domestic Procurement Mandates:US federal and state infrastructure projects increasingly require domestic granite sourcing, favoring North American quarry operators with verified provenance.
- Digital Templating Convergence:Integration of 3D scanning with CNC fabrication is reducing slab waste rates and enabling just-in-time production for custom residential installations.
Industry Challenges
- Silica Exposure Compliance:OSHA respirable crystalline silica limits require capital-intensive wet-cutting infrastructure upgrades and continuous workplace monitoring systems.
- Skilled Fabrication Shortage:Master craftsmen capable of complex book-matching and vein alignment command premium wages, constraining output scaling for luxury projects.
- BIS Certification Timelines:Indian processors in Rajasthan and Andhra Pradesh face extended quality verification periods that delay premium market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Stone Slab Market |
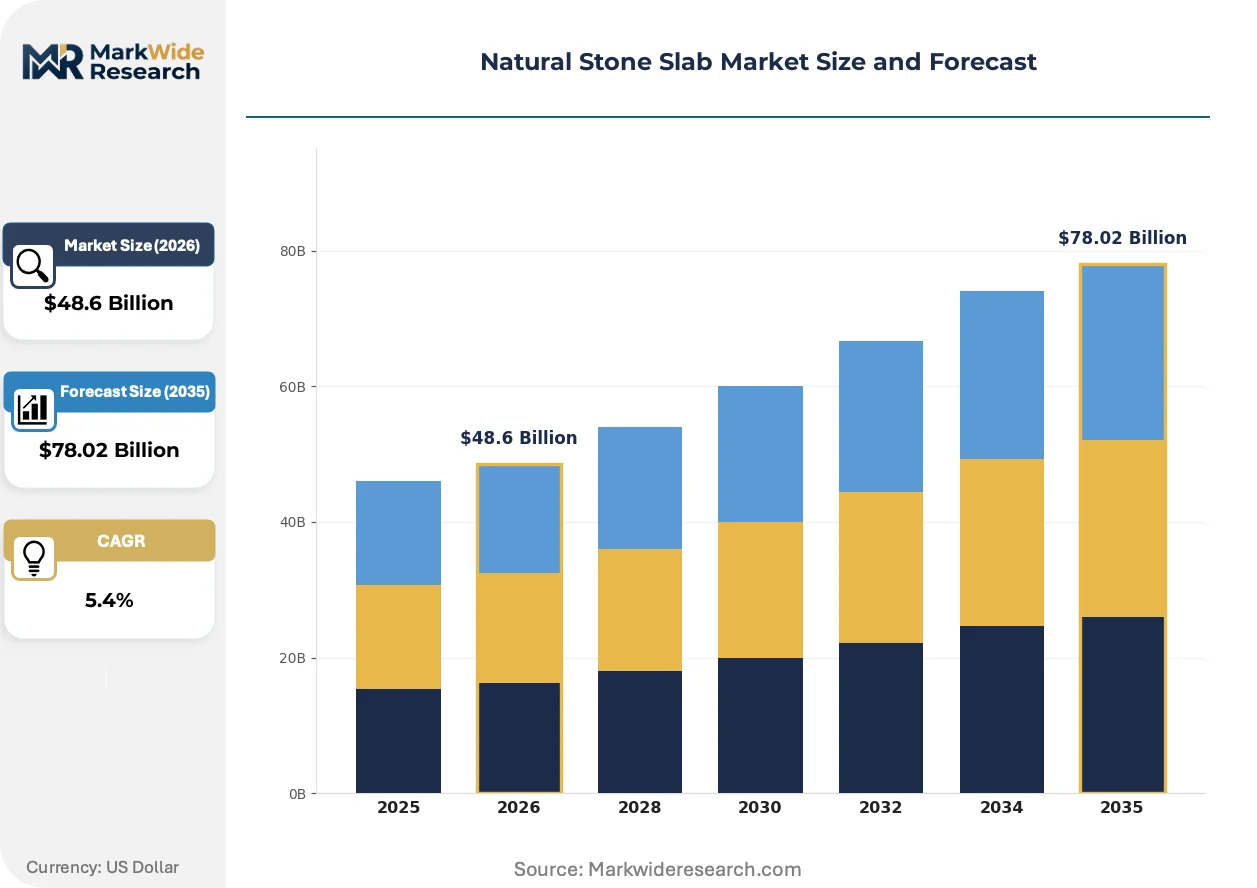
| Market Size in 2026 | $48.6 Billion |
| Market Size in 2035 | $78.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granite, Marble, Limestone, Quartzite Installation Type: Exterior, Interior, Countertops, Flooring End Use: Residential, Commercial, Industrial, Renovation Finish Type: Polished, Honed, Textured, Sandblasted |
| Companies Covered | Cosentino, Dal Tile, Levantina, Indian Natural Stones, Pokarna Limited, Polycor, Arizona Tile, M S International, Antolini, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Stone Slab Market Strategic Shifts & Innovations
Digitization of quarry-to-site workflows is compressing specification cycles while embedded carbon accounting is rewiring procurement criteria across commercial construction channels.
CNC-assisted book-matching software is modularizing how fabricators align veining patterns across sequential slabs. Luxury residential developers in London and Manhattan now expect digital previews of installed sequences before quarry release. This capability is compressing the traditional architect-fabricator negotiation cycle from weeks to days.
EU Construction Products Regulation revision is tightening embodied carbon disclosure thresholds for building materials placed on the European market. Quarry operators must now commission third-party lifecycle assessments to maintain specification eligibility. Mediterranean producers with captive renewable energy supply are capturing preferential positioning in Dutch and German commercial tenders.
Architects and interior designers now specify stone through direct quarry relationships rather than traditional distributor channels. Hospitality procurement teams in Singapore and Miami source slabs via digital platforms that aggregate inventory from multiple quarry clusters. This disintermediation is compressing distributor margins while rewarding operators with transparent provenance documentation and real-time availability visibility.
Natural Stone Slab Market Segmentation
Natural stone slab procurement decisions cascade through mineral hardness, installation environment, and finish specification. Each segmentation dimension carries distinct margin profiles and regulatory exposure that reshape supplier positioning across construction channels.
Product Type:
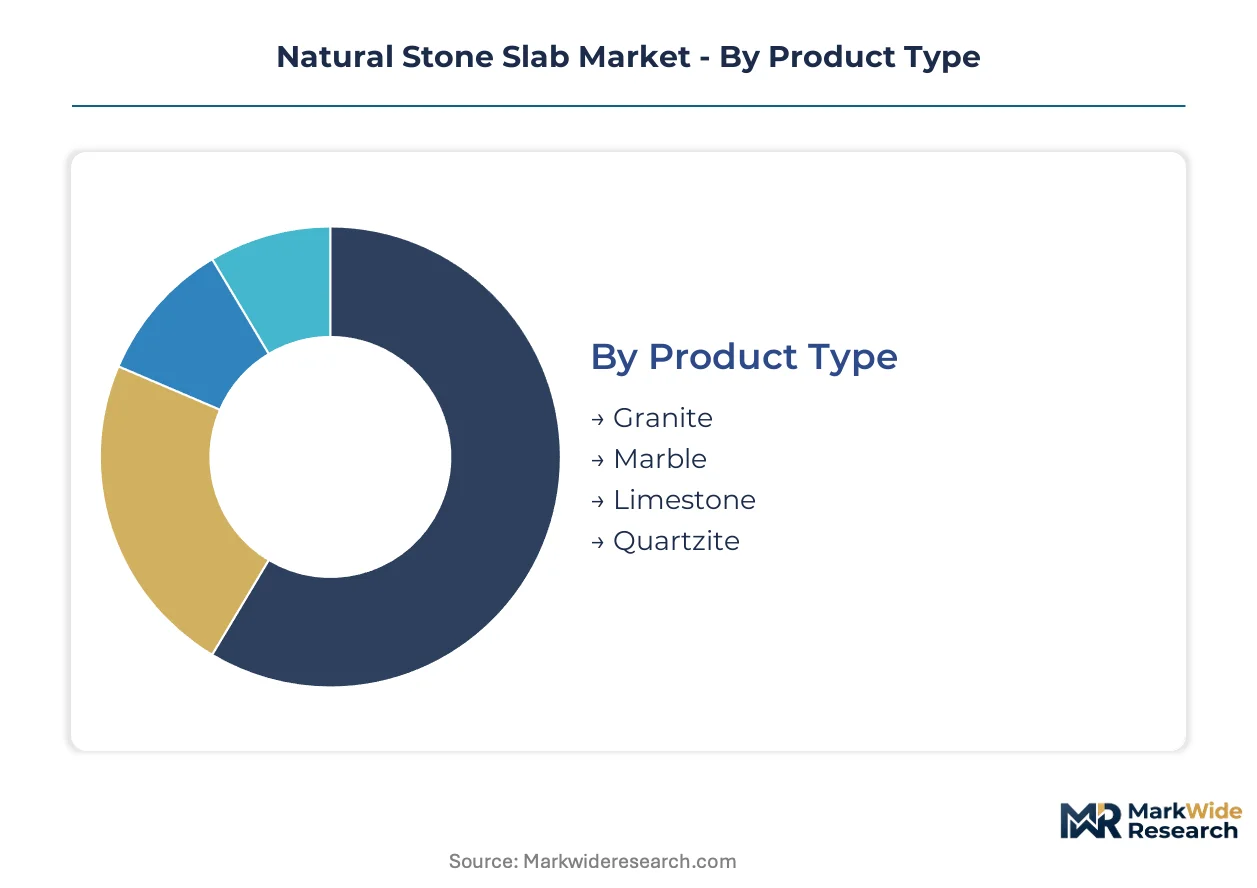
Granite and marble anchor specification in structural load-bearing applications, while limestone and quartzite occupy specialized niches where porosity or hardness differentiates performance.
- Granite:Igneous rock with superior Mohs hardness ratings above 6.5 enables high-traffic commercial flooring in Dubai luxury hospitality developments where abrasion resistance justifies premium sourcing. OSHA silica exposure limits during fabrication compress margins for untreated material.
- Marble:Metamorphic limestone with distinctive veining patterns commands book-matched installations in Riyadh hotel lobbies. Mediterranean quarry operators with captive renewable energy supply capture preferential positioning in EU Green Deal procurement.
- Limestone:Sedimentary carbonate with controlled porosity serves conservation-grade exterior cladding where weathering characteristics align with heritage restoration standards.
- Quartzite:Metamorphosed sandstone combining granite-like durability with marble aesthetic range specifies for premium residential countertops in China's tier-one cities facing GB radioactive emission restrictions.
Granite leads volumes today; quartzite is gaining share fastest.
Installation Type:
Exterior and interior applications diverge in structural engineering requirements, while countertops and flooring concentrate demand in finish-sensitive specification channels.
- Exterior:Load-bearing cladding systems require freeze-thaw resistance and anchoring compatibility. EU Construction Products Regulation embodied carbon disclosure mandates favor low-carbon-processed stone in Dutch and German commercial tenders.
- Interior:Non-structural wall and floor finishes prioritize aesthetic consistency over mechanical performance. REACH compliance investment in water-based cutting unlocks premium market access for retrofitted processors.
- Countertops:Horizontal surfacing demands stain resistance and edge fabrication precision. Engineered stone substitution pressure concentrates in mid-market residential specification.
- Flooring:Abrasion-rated installations in high-traffic hospitality and transit environments specify hardness-tested material with verified slip resistance.
Interior applications dominate revenue today; exterior cladding is expanding most quickly under green building mandates.
End Use:
Residential and commercial construction drive volume concentration, while industrial and renovation segments reward specialized sourcing capabilities.
- Residential:Single-family and multi-family specification splits between imported granite in premium developments and domestic stone in mid-market construction. China's tier-one urbanization concentrates demand in Shanghai and Shenzhen.
- Commercial:Office, retail, and hospitality projects generate book-matched marble volume from Mediterranean quarries. Digital templating convergence reduces slab waste for custom installations.
- Industrial:Manufacturing and logistics facilities specify utilitarian grades where chemical resistance and load capacity override aesthetic considerations.
- Renovation:Historical restoration and building modernization creates premium niches for conservation-grade limestone with provenance documentation.
Commercial projects anchor revenue today; renovation is climbing the fastest on heritage preservation funding.
Finish Type:
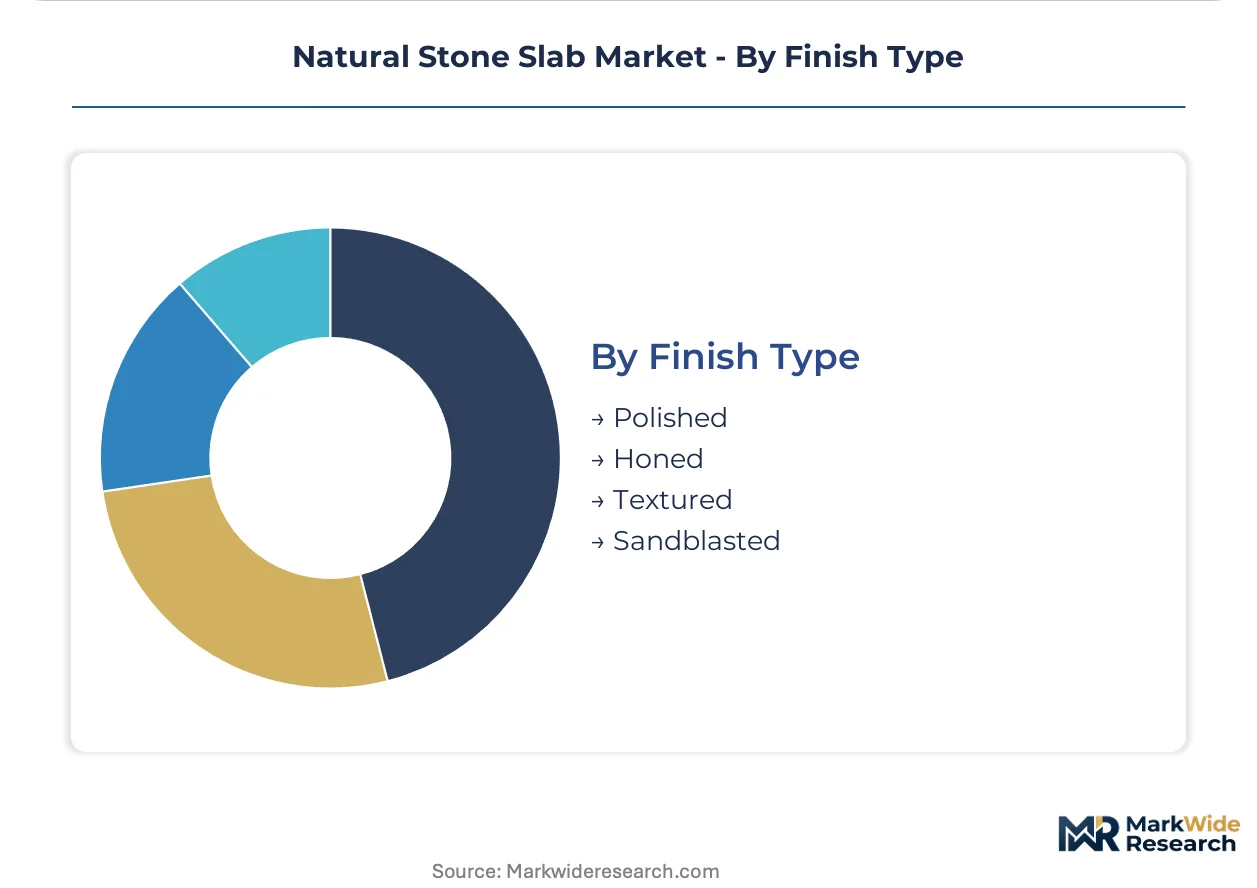
Polished and honed surfaces dominate specification, while textured and sandblasted treatments serve safety-critical and aesthetic-specialist applications.
- Polished:Mirror-finish surfaces maximize veining visibility in luxury residential and hospitality specification. Automated polishing workflows require capital investment that filters supplier base.
- Honed:Matte finish reduces glare and slip hazard in commercial flooring while maintaining color saturation. CNC fabrication integration enables just-in-time production for custom sequences.
- Textured:Mechanical or thermal surface modification enhances slip resistance for exterior paving and wet-area applications.
- Sandblasted:Abrasive particle treatment creates uniform roughness for historical restoration matching and contemporary architectural texture.
Polished finishes command volume leadership today; honed surfaces are gaining share fastest on safety specification trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy's marble quarries command premium book-matched specification, while Brazil's processing clusters struggle with energy cost volatility that compresses export margins.
United States
Domestic granite deposits in Vermont and Georgia anchor heritage restoration and federal infrastructure procurement. OSHA respirable crystalline silica enforcement drives capital investment in wet-cutting infrastructure across fabrication clusters. Texas and Florida distribution hubs consolidate inventory for commercial hospitality specification.
Italy
Carrara and Massa quarry operators supply book-matched marble for Dubai and Riyadh luxury hotel developments. EU Green Deal embodied carbon disclosure mandates favor processors with captive renewable energy supply. Tuscany-based fabricators integrate automated polishing workflows to maintain REACH compliance eligibility.
China
Shanghai and Shenzhen premium residential towers specify imported granite and quartzite finishes. GB standards for radioactive emission levels restrict certain domestic granite varieties from interior use. Fujian and Guangdong processing clusters recalibrate output toward export-compliant material grades.
India
Rajasthan and Andhra Pradesh processors seek premium market access through BIS certification compliance. Conservation-grade limestone from Kota and Jaisalmer serves heritage restoration demand in European markets. Extended quality verification timelines delay entry into specification-driven segments.
Brazil
Minas Gerais granite deposits supply high-traffic commercial flooring specification globally. Prolonged European electricity price instability forces processing clusters to reconfigure shift schedules. Espírito Santo fabrication hubs face margin compression on long-haul export routes.
Natural Stone Slab Market Key Industry Players
Mediterranean producers anchor one tier; North American specialists hold domestic procurement advantages. The vendor base stratifies across captive quarry operators, integrated fabricator-distributors, and regional processors serving specification channels. Three archetypes dominate: vertically integrated quarry-to-slab operators, heritage restoration specialists with provenance documentation, and digital platform aggregators disintermediating traditional distribution. Competitive intensity concentrates on M&A for quarry access and capital deployment into automated fabrication infrastructure.
Among Mediterranean integrated operators, Cosentino and Levantina exemplify quarry-captive positioning that sustains pricing power in specification channels. Polycor represents the North American heritage specialist archetype, leveraging domestic granite deposits where federal procurement mandates favor verified provenance. Dal Tile occupies a position within the distributor-fabricator tier, bridging quarry supply with regional installation networks.
| Leading Market Players |
|---|
| Cosentino |
| Dal Tile |
| Levantina |
| Indian Natural Stones |
| Pokarna Limited |
| Polycor |
| Arizona Tile |
| M S International |
| Antolini |
| Others |
Cost & Logistics Intelligence
EU Green Deal embodied carbon disclosure mandates gate qualified supply and premium-tier pricing access, compressing margins for long-haul importers while rewarding captive quarry-to-slab operators with verified low-carbon processing credentials.
Pricing Analysis
Capacity additions in Brazil are reshaping price floors for standard-grade granite exports. Three-tier pricing structure across premium, standard, and economy levels separates book-matched marble with renewable energy certification from untreated commodity slabs. Cost compression in mid-market segments is intensifying because engineered stone substitutes capture countertop specification. Hospitality developers in Dubai and Riyadh show least price sensitivity; mid-market residential builders in China's tier-three cities exhibit highest.
Supply Chain Analysis
Dual-sourcing requirements from US federal infrastructure procurement mandate multi-supplier qualification, forcing project developers to maintain relationships with both domestic and Mediterranean quarry operators. Supply concentrates in Italy, Brazil, and India, with raw material dependencies spanning diesel fuel for extraction, diamond wire for block cutting, and resin for surface treatment. Single-source vulnerability runs through Carrara's book-matched marble capacity for luxury hospitality. Distribution runs through regional fabricator-distributor hubs in Texas and Florida.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EU Construction Products Regulation revision tightens embodied carbon thresholds and pulls demand toward verified low-carbon stone.
For Market Incumbents: Cement pricing power through captive renewable energy supply at Mediterranean quarry positions. Defend specification channels against sintered compact surface substitution by accelerating automated polishing workflow deployment. Prioritize REACH compliance investment to maintain EU market eligibility. For New Entrants and Emerging Players: Capture heritage restoration demand where domestic sourcing requirements favor North American granite deposits with provenance documentation. The most penetrable segment lies in US federal infrastructure projects requiring verified domestic origin. Lead with digital templating integration to reduce slab waste and compress project timelines. For Investors and Strategic Acquirers: Roll-up economics work for regional fabricator-distributors because specification channels reward local installation networks with just-in-time CNC capability. Long-term viability centers on quarry access positions with captive block supply. Watch EU Green Deal procurement mandate expansion as inflection indicator for premium-tier demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Quarry Assets | Captive block supply secures margin control against energy cost volatility in Brazil. |
| Automated Polishing Workflow Deployment | OSHA silica compliance unlocks premium US specification channel access. |
| Digital Templating Platform Integration | 3D scanning convergence reduces waste rates for Manhattan luxury residential developers. |
| Renewable Energy Supply Certification | EU Green Deal eligibility captures Dutch and German commercial tender preference. |
| Heritage Restoration Provenance Documentation | Conservation-grade limestone specification rewards verified North American deposit sourcing. |
Research Approach
Multiple input streams — quarry operator production data, fabricator capacity surveys, and hospitality procurement pipeline tracking — were reconciled across primary interviews with quarry operations managers, stone fabrication facility owners, and commercial specification architects, validated against secondary sources including EU Construction Products Regulation filings, USGS mineral commodity summaries, and Indian BIS certification registries, with bottom-up volume modeling cross-checked against top-down construction spend allocation.
Historical shipment volumes from Carrara and Minas Gerais clusters were cross-referenced against panel input from Mediterranean export associations and North American distributor networks across the analysis window. Segmentation modeling spanned mineral hardness tier, installation environment, finish specification, and end-use vertical. CAGRs were derived from regression analysis of construction completion data and material specification rates, with carbon accounting methodology shifts and engineered stone penetration rates as key forecast inputs.
Energy cost volatility, regulatory timeline delays for BIS certification, and engineered stone substitution acceleration are the dominant revision risks. Deviation in EU Green Deal enforcement stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Fire Resistant Mortar Market
Building Materials
Global Builders Joinery and Carpentry of Wood Market
Building Materials
Composite Decking and Railing Market
Building Materials
Ireland Cement Market
Building Materials
Door Frame Metal Market
Building Materials
Global Corrugated Steel Sheets Market
Building Materials
United States Architectural Coatings Market
Building Materials
Blind Bolts Market
Building Materials
Cement Market
Building Materials
Global Pozzolan Market
Building Materials
Fireproof Cladding Market
Building Materials
North America Architectural Coatings Market
Building Materials
GRC Cladding Market
Building Materials
Long Steel Market
Building Materials
Concrete Blocks and Bricks Market
Building Materials
Australia Architectural Coatings Market