
 Construction Coatings Market | 2026-2036
Construction Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Coatings Market Analysis
The capital-intensity divergence between integrated resin producers and formulation-only specialists is unwinding competitive stability in the construction coatings sector. Sherwin-Williams leverages captive raw material supply to sustain margin resilience across North American distribution networks. PPG Industries anchors its position through R&D intensity in high-performance architectural systems. AkzoNobel competes on reformulation speed as European regulatory deadlines compress product development cycles.
Construction coatings encompass liquid, powder, and film-forming materials engineered from acrylic, epoxy, polyurethane, or alkyd resin matrices with pigment loadings typically between 15% and 35% by volume, designed to protect structural substrates from moisture ingress, UV degradation, and chemical attack. Water-based technology leads volume shipments due to regulatory pressure on volatile organic compound emissions, while powder coating captures margin pools in industrial and infrastructure applications where film thickness and durability specifications are most stringent. The residential application segment dominates absolute consumption, though infrastructure end-use is accelerating fastest as government-funded bridge, tunnel, and transit projects multiply across developing and developed economies.
EPA VOC regulations in the United States, REACH chemical restrictions administered by ECHA in Europe, and China's MEE environmental compliance audits collectively elevate reformulation costs and reshape raw material procurement. These frameworks force manufacturers to document substance safety across extended supply chains or risk market exclusion. Stakeholders must monitor regulatory divergence between jurisdictions where compliance in one geography no longer guarantees access in another.
Market Dynamics
The construction coatings sector is undergoing a fundamental restructuring as regulatory divergence between jurisdictions forces parallel formulation tracks, elevating R&D overhead and compressing product lifecycles for manufacturers serving multiple markets simultaneously.
Growth Catalysts
- REACH and EU Green Deal compliance deadlines:European regulatory pressure on volatile organic compound emissions is redirecting capital toward water-based resin systems, expanding addressable market share for compliant suppliers.
- Infrastructure end-use acceleration:Government-funded bridge, tunnel, and transit projects across developing economies are absorbing high-performance coating volumes at premium specifications.
- China urban renewal pipeline:Municipal renovation programs and state-directed infrastructure spending are concentrating demand for exterior architectural systems in tier-one and tier-two cities.
Market Restraints
- Petrochemical feedstock volatility:Acrylic and epoxy resin costs fluctuate with crude oil derivatives, compressing margin predictability for formulation specialists lacking captive supply.
- Raw material supplier concentration:Specialty pigment and additive production clusters in China create geographic supply risk amplified by MEE environmental audit disruptions.
- Film thickness limitations in water-based systems:Technical performance gaps versus solvent-borne alternatives restrict adoption in heavy-duty infrastructure specifications.
Strategic Opportunities
- India commercial construction expansion:Underpenetrated protective coatings penetration in industrial facilities and warehousing creates volume expansion potential for early entrants.
- Digital specification platforms:Architect and contractor procurement via building information modeling-integrated coating selection tools is opening direct channel access bypassing traditional distribution.
- EU Taxonomy-aligned green building mandates:Regulatory tailwinds for low-carbon construction materials are creating premium positioning for bio-based binder technologies.
Industry Challenges
- Formulation chemist talent scarcity:Specialized expertise in hybrid resin systems and regulatory compliance documentation is concentrating at integrated producers, constraining specialist hiring pipelines.
- Multi-jurisdiction certification timelines:Parallel substance safety dossier preparation for EPA, ECHA, and MEE requirements extends product launch cycles and elevates compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Coatings Market |
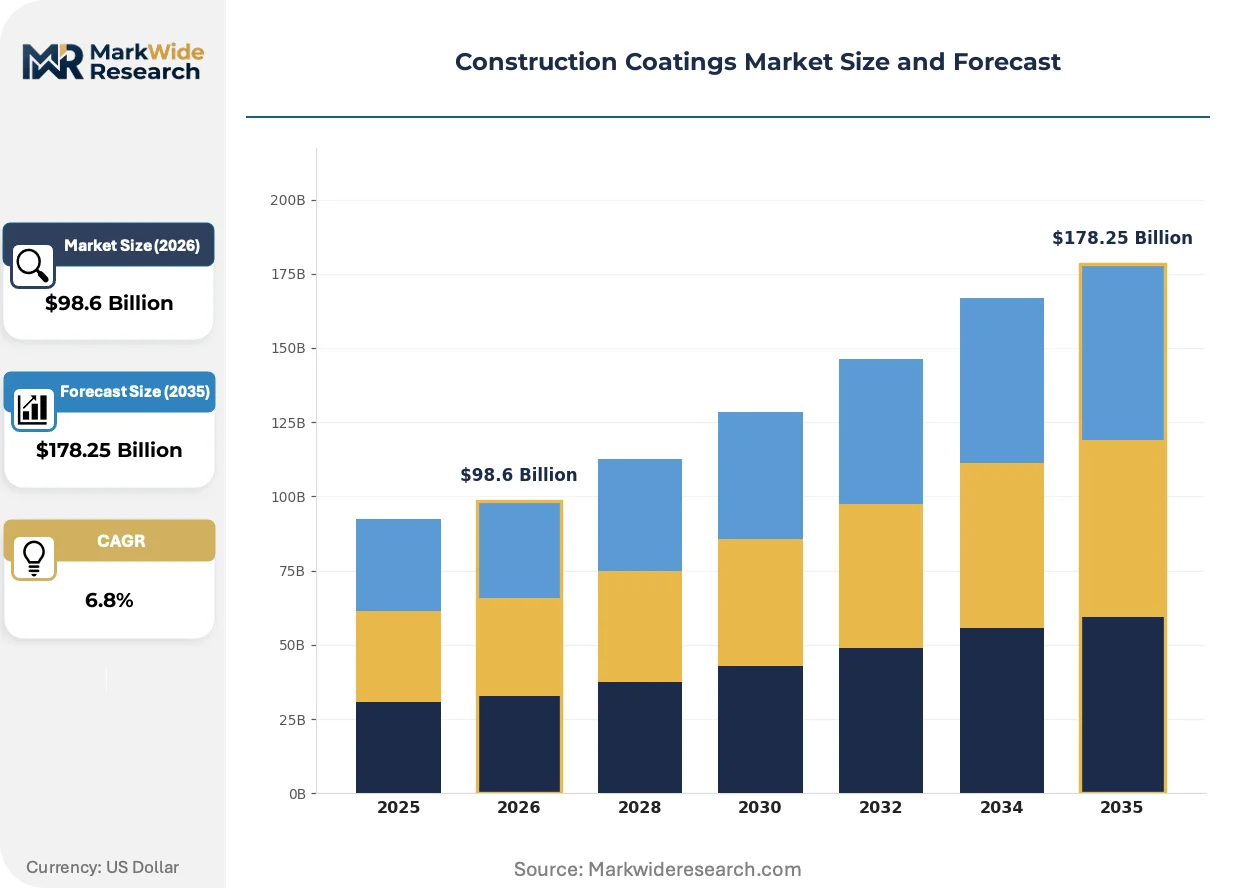
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $178.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Acrylic, Polyurethane, Alkyd Application: Commercial, Residential, Industrial, Infrastructure Technology: Water-Based, Solvent-Based, Powder Coating, High-Performance End User: Contractors, DIY Enthusiasts, Manufacturers, Property Developers |
| Companies Covered | Sherwin-Williams Company, PPG Industries, AkzoNobel, BASF, Nippon Paint Holdings, RPM International, Axalta Coating Systems, Asian Paints, Jotun Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Coatings Market Emerging Trajectories
Formulation science is diverging along regulatory fault lines while digital tools reshape how specifications reach end-users, creating simultaneous pressure on R&D productivity and commercial access.
Self-healing coating chemistry is fragmenting competitive positioning in high-value infrastructure applications. Microcapsule-based autonomic repair systems embedded in epoxy matrices enable crack closure without manual intervention. Bridge and marine asset owners in Germany and Japan are specifying these systems for inaccessible structural elements, compressing maintenance cycle economics and displacing conventional passive protection.
REACH substance restriction expansions administered by ECHA are forcing systematic raw material substitution across European supply chains. The sunset date pressure on chromium-based corrosion inhibitors is accelerating trivalent and organic alternative qualification programs. Decorative and protective coating lines serving German residential developers are reformulating fastest to maintain specification access.
Building information modeling integration is reshaping how architects and contractors evaluate coating performance. Digital specification libraries now embed durability simulation and lifecycle carbon data alongside aesthetic attributes. Commercial construction procurement teams in France and the Netherlands are prioritizing BIM-compatible coating systems, rewarding manufacturers with structured technical data delivery over traditional relationship-based specification.
Construction Coatings Market Segmentation
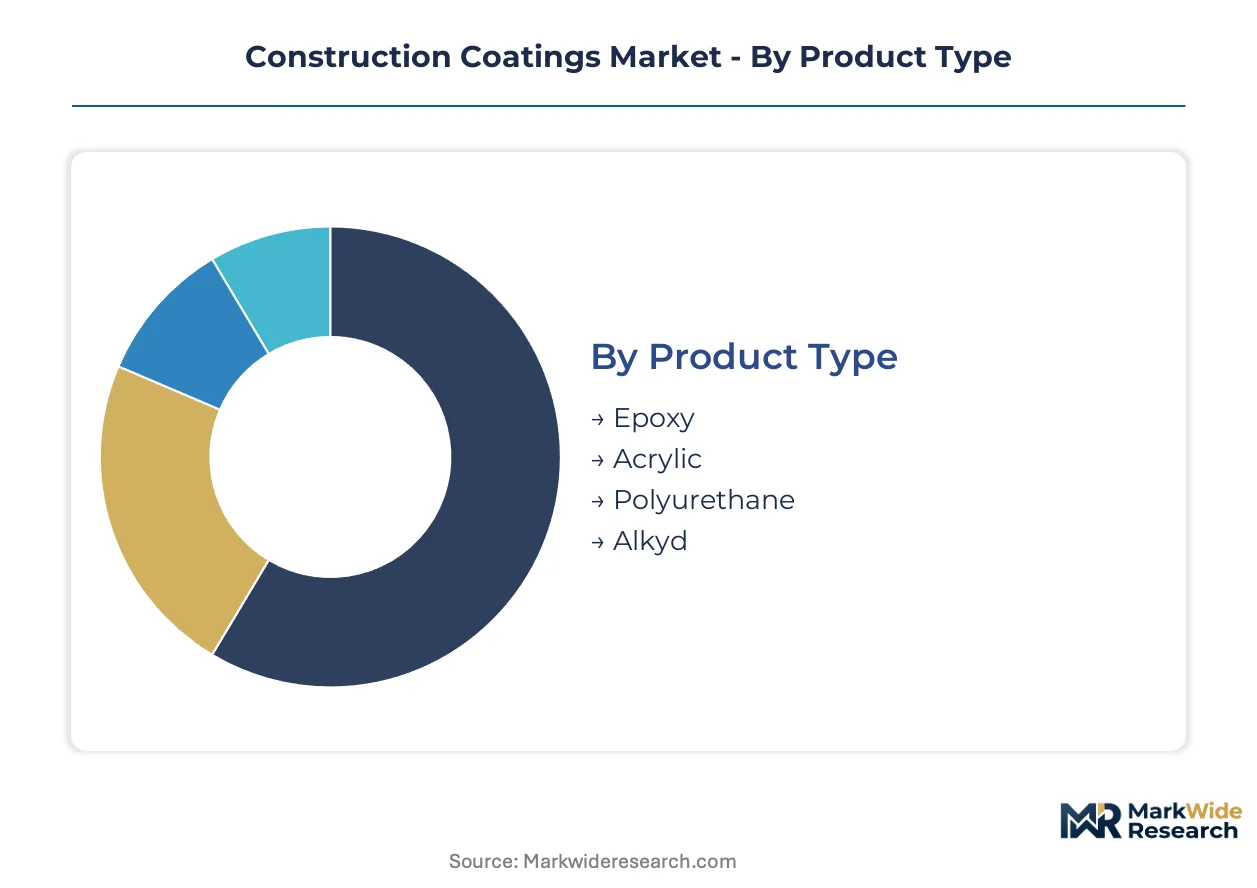
Construction coatings segmentation reveals how regulatory pressure and substrate requirements fragment demand across resin chemistries, application environments, and procurement channels. Manufacturers configure product portfolios around jurisdiction-specific compliance thresholds rather than universal performance standards.
Product Type:
REACH substance restrictions and EPA VOC limits are forcing divergent formulation investments across resin platforms, with European producers accelerating water-compatible binder development while North American capacity favors low-exempt solvent systems.
- Epoxy:Two-part thermosetting systems built from bisphenol-A or bisphenol-F precursors deliver chemical resistance and adhesion to concrete, steel, and masonry substrates. Infrastructure end-use in Germany and Japan specifies epoxy for bridge decks and marine pilings where film integrity under cyclic loading is mandatory. REACH sunset dates on chromium-based corrosion inhibitors are accelerating trivalent alternative qualification within epoxy primers.
- Acrylic:Thermoplastic emulsions and solvent-borne solutions provide UV stability and color retention for exterior architectural applications. Residential property developers in China specify acrylic emulsions for urban renewal facades driven by MEE compliance audits and municipal air quality mandates.
- Polyurethane:Aliphatic and aromatic isocyanate-cured systems balance flexibility with abrasion resistance for high-traffic commercial flooring.
- Alkyd:Oil-modified polyester resins retain share in solvent-tolerant industrial maintenance where dry-film thickness requirements exceed water-based limitations.
Established volume favors alkyd in solvent-permissive industrial maintenance; emerging adoption favors epoxy in infrastructure specifications demanding autonomic repair and extended service intervals.
Application:
Capital deployment intensity varies sharply across construction verticals, with government-funded infrastructure absorbing premium-priced high-performance systems and residential volume concentrating in cost-optimized architectural grades.
- Commercial:Office, retail, and hospitality projects specify coating systems through building information modeling platforms where durability simulation and lifecycle carbon data influence procurement. French and Dutch contractors prioritize BIM-compatible technical data delivery over traditional distributor relationships.
- Infrastructure:Bridge, tunnel, and transit authorities specify film-forming materials with autonomic repair capabilities and extended recoat intervals. German asset owners microcapsule-based self-healing epoxy for inaccessible structural elements, compressing maintenance economics and displacing passive protection.
- Residential:Single-family and multi-family construction drives absolute coating consumption through developer-specified exterior systems.
- Industrial:Manufacturing facilities and warehousing demand chemical-resistant flooring and containment coatings.
Residential commands absolute tonnage; infrastructure captures the steepest expansion trajectory as state-directed spending multiplies across developed and developing economies.
Technology:
Environmental compliance frameworks are collapsing the solvent-borne addressable market in Europe while powder coating captures margin pools where film thickness and durability specifications are most stringent.
- Water-Based:Acrylic and polyurethane dispersions with VOC content below regulatory thresholds dominate European architectural shipments. German residential developers expand adoption of low-VOC exterior systems ahead of EU Green Deal implementation deadlines.
- Powder Coating:Thermosetting resin systems applied electrostatically and cured without liquid carriers achieve 50-150 micron dry film thickness on metal substrates. Industrial and infrastructure fabricators in China specify powder for rebar, structural steel, and transit equipment where edge coverage and corrosion resistance are critical.
- Solvent-Based:High-solids and exempt-solvent formulations retain infrastructure and industrial share where ambient cure in low-temperature environments is required.
- High-Performance:Fluoropolymer, polysiloxane, and ceramic-modified systems command specification in extreme exposure environments.
Water-based technology leads volume shipments; powder coating gains share fastest in industrial applications where zero-VOC cure and reclaimed overspray improve process economics.
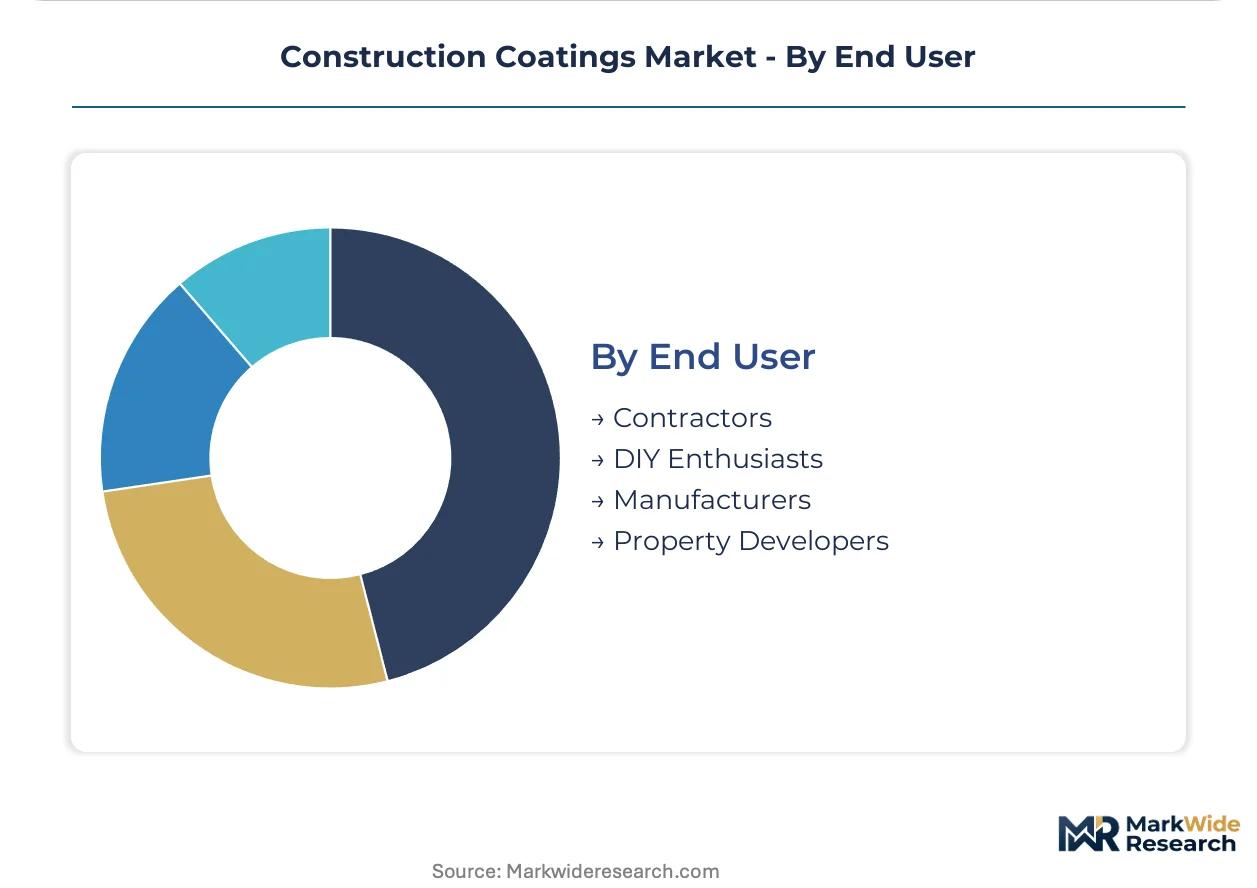
End User:
Procurement authority is fragmenting across the value chain as digital specification tools empower architects while contractor purchasing consolidates through distributor networks.
- Property Developers:Residential and commercial project sponsors specify coating systems during design development, influencing formulation selection before contractor engagement. Urban renewal programs in Chinese tier-one cities concentrate developer demand for exterior architectural systems with documented carbon intensity.
- Contractors:Application specialists procure through distributor networks where technical support and just-in-time delivery determine supplier selection. North American painting contractors specify through Sherwin-Williams store networks with embedded color matching and substrate preparation guidance.
- DIY Enthusiasts:Home improvement retail channels serve residential maintenance and renovation demand.
- Manufacturers:Industrial fabricators and OEMs specify shop-applied coatings for component protection.
Contractor channel captures the highest transaction frequency; property developer specification is climbing the fastest as green building mandates elevate upstream material selection authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across construction coatings markets, with infrastructure buyers in Germany and Japan absorbing premium pricing for autonomic repair systems while residential developers in India and Southeast Asia prioritize cost-optimized architectural grades.
United States
Infrastructure renewal programs and commercial construction recovery are absorbing high-performance coating volumes. EPA VOC regulations under the National Ambient Air Quality Standards redirect formulation investments toward water-based and exempt-solvent systems. Texas and California construction corridors concentrate demand for protective coatings in energy and transit infrastructure.
Germany
Bridge deck rehabilitation and marine asset maintenance specify self-healing epoxy systems with extended service intervals. REACH substance restrictions administered by ECHA accelerate trivalent corrosion inhibitor substitution in protective primers. The Rhine-Ruhr industrial cluster anchors specification authority for heavy-duty infrastructure coatings across Central Europe.
China
Urban renewal pipelines in tier-one cities and state-directed infrastructure spending concentrate demand for exterior architectural systems. MEE environmental compliance audits enforce VOC content thresholds on manufacturing facilities. The Yangtze River Delta manufacturing belt supplies powder coating systems for structural steel and transit equipment fabrication.
India
Commercial construction expansion and industrial warehousing development create underpenetrated demand for protective coatings. BIS certification requirements for construction materials elevate quality thresholds for imported formulations. The Maharashtra-Gujarat industrial corridor concentrates manufacturing facility construction and associated coating procurement.
Japan
Marine infrastructure and seismic-resistant building specifications drive adoption of high-durability coating systems. METI energy efficiency standards for buildings influence exterior system selection toward heat-reflective technologies. The Kansai region around Osaka anchors demand for heavy-duty protective coatings in port and bridge maintenance.
Construction Coatings Market Vendor Landscape
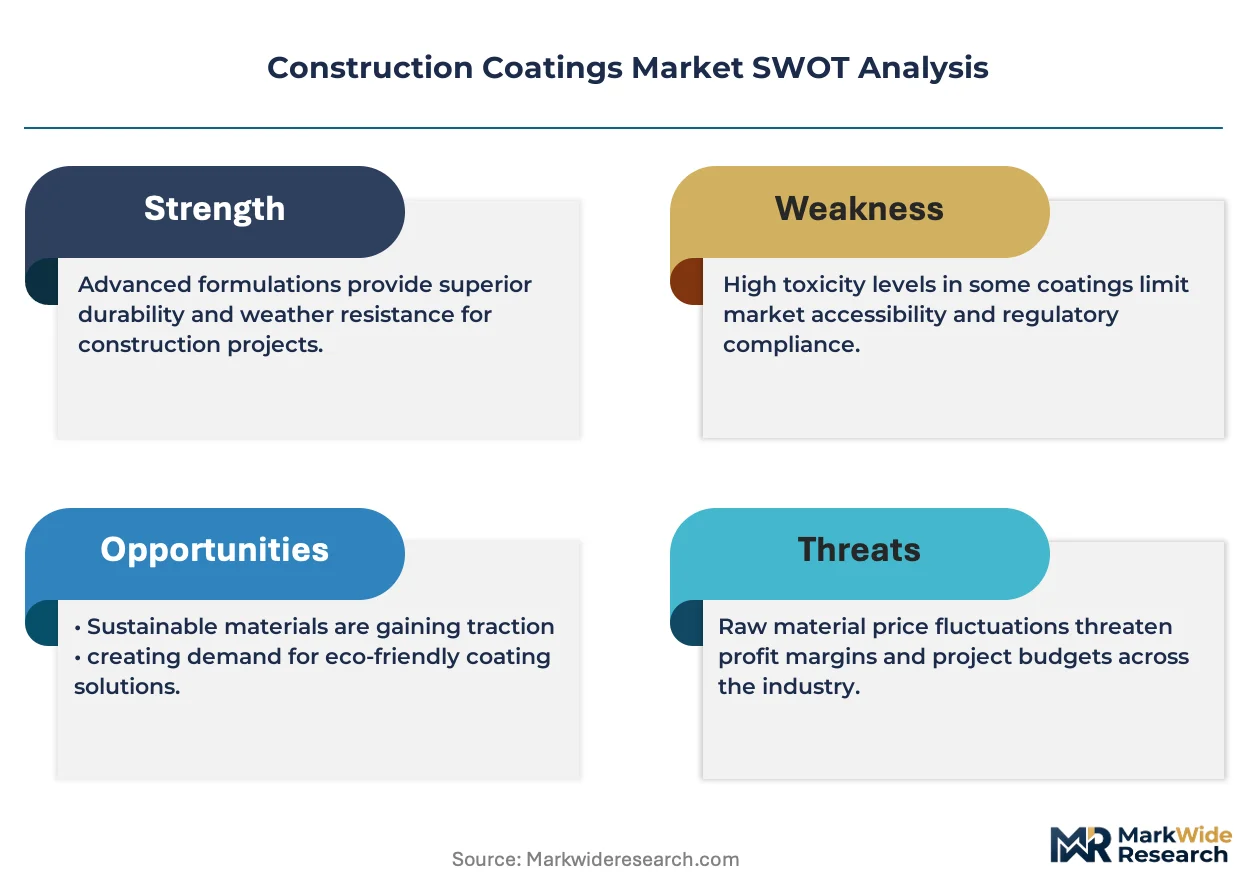
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated resin producers with captive raw material supply sustain margin resilience against formulation specialists exposed to petrochemical feedstock volatility. The market organizes around three strategic archetypes: vertically integrated multinationals controlling upstream resin production, regional formulation specialists competing on reformulation speed and local service, and technology-focused innovators commercializing autonomic repair and bio-based binder systems. Dominant competitive moves include backward integration into specialty resin production and strategic partnerships with digital specification platform providers.
Among North American integrated producers, Sherwin-Williams Company and PPG Industries exemplify the vertically integrated archetype with captive supply advantages. AkzoNobel occupies a position representing European reformulation specialists competing on regulatory compliance velocity. These three anchors illustrate how geographic regulatory divergence rewards different capability configurations across the Atlantic.
| Leading Market Players |
|---|
| Sherwin-Williams Company |
| PPG Industries |
| AkzoNobel |
| BASF |
| Nippon Paint Holdings |
| RPM International |
| Axalta Coating Systems |
| Asian Paints |
| Jotun Group |
| Others |
Supply Flow & Price Mechanics
Trivalent chromium corrosion inhibitor substitution in European protective primers simultaneously relocates raw material sourcing toward Chinese specialty chemical producers and compresses margin pools for formulation specialists lacking captive supply. This input transition elevates procurement risk for German and Dutch coating manufacturers while rewarding integrated resin producers with upstream control over alternative corrosion chemistry.
Pricing Analysis
Extended coating service contracts and lifecycle maintenance agreements capture lifetime value beyond initial product shipment. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and volume commitment, with BIM-compatible technical data packages commanding developer premiums. Cost compression in water-based architectural grades is intensifying because MEE audit compliance elevates manufacturing overhead. Residential property developers in China exhibit highest price sensitivity; infrastructure asset owners in Germany and Japan absorb premium positioning for autonomic repair systems.
Supply Chain Analysis
China and Germany anchor global production of specialty epoxy resins and water-based acrylic dispersions. Formulation chemistry draws from bisphenol-A precursors, titanium dioxide pigments, and aliphatic isocyanate curing agents. Single-source vulnerability concentrates in Chinese MEE-regulated pigment additive clusters subject to environmental audit disruption. Distribution runs through Sherwin-Williams store networks in North America and AkzoNobel specification relationships with European architects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Construction coatings incumbents face substitution defense imperatives as bio-based binder technologies and digital specification platforms threaten traditional formulation value capture. Plant-based resin alternatives and BIM-integrated procurement tools erode incumbent specification authority.
For Market Incumbents: Secure captive supply of trivalent corrosion inhibitors and hybrid resin systems ahead of REACH sunset deadlines. Deepen backward integration into water-compatible acrylic emulsion production to offset petrochemical feedstock volatility. Prioritize certification investment for EU Taxonomy-aligned green building mandates. For New Entrants and Emerging Players: Differentiate on bio-based polyurethane dispersions for EU Green Deal-compliant commercial construction. Target underpenetrated protective coatings penetration in Indian industrial warehousing and Maharashtra-Gujarat manufacturing corridor development. Pursue direct specification relationships with French and Dutch architects via BIM platform integration. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional formulation specialists in Southeast Asia and Central Europe lacking upstream resin control. Five-to-ten year viability hinges on regulatory compliance velocity and digital channel access. Monitor ECHA substance restriction expansion timelines as inflection indicator for reformulation capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Resin Production | Captive bisphenol-A and acrylic emulsion supply shields Sherwin-Williams from petrochemical volatility. |
| Green Manufacturing Transition | EU Taxonomy-aligned bio-based binder qualification opens premium specification access with German developers. |
| Long-term Supply Agreement | Fixed-price titanium dioxide contracts with Chinese producers stabilize formulation cost predictability. |
| Joint Venture | Digital specification platform partnerships with Autodesk and Nemetschek embed coating selection in BIM workflows. |
| Capacity Expansion | Yangtze River Delta powder coating buildout captures Chinese infrastructure steel protection demand. |
Methodological Framework
Initial hypotheses were tested against primary input from formulation R&D directors, procurement leads at German property developers, ECHA regulatory affairs specialists, and North American distributor network managers and refined through secondary validation. Customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and ECHA substance restriction databases anchored quantitative baselines. Bottom-up coating volume estimates triangulated against top-down construction spending forecasts.
Variance decomposition across resin chemistry, application vertical, technology platform, and regional regulatory cluster shaped the analytical framework. CAGRs derived from segment-level volume elasticity modeling against construction output indices and infrastructure spending pipelines. Modeling incorporated REACH compliance cost pass-through assumptions and MEE audit disruption probability weighting for Chinese supply clusters.
Material uncertainties — petrochemical feedstock volatility, ECHA substance restriction expansion scope, and MEE enforcement intensity — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory timeline adherence and infrastructure spending continuity. Recalibration cycles align with material shifts in EU Green Deal implementation deadlines and Chinese urban renewal program authorization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Construction Stone Market
Building Materials
Qatar Cement Market
Building Materials
Concrete Admixtures Market
Building Materials
Asia-Pacific Shotcrete Market
Building Materials
US Commercial Paving Slabs Market
Building Materials
Australia Architectural Coatings Market
Building Materials
Asia-Pacific White Cement Market
Building Materials
Dutch Brick Market
Building Materials
North America Architectural Coatings Market
Building Materials
Cellular Concrete Market
Building Materials
India Construction Ornamental Stone Market
Building Materials
Solar Control Window Film Market
Building Materials
GRC Cladding Market
Building Materials
Radiant Barriers and Reflective Insulation Market
Building Materials
Europe Aluminum Door and Window Market
Building Materials
Global Lightweight Aggregate Concrete Market