
 Saudi Arabia Prefabricated Buildings Market | 2026-2036
Saudi Arabia Prefabricated Buildings Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Prefabricated Buildings Market Analytics
A capital-intensity divergence between integrated steel fabricators and project-assembly contractors is redrawing competitive boundaries in the Saudi prefabricated buildings sector. Kirby Building Systems leverages captive galvanizing capacity and regional mill relationships to sustain margin discipline across large-scale pre-engineered building contracts. Red Sea Housing Services differentiates through turnkey camp and workforce accommodation expertise anchored in Eastern Province industrial zones. Zamil Industrial Investment Co. controls a vertically integrated supply chain spanning coil processing through final erection, positioning it for recurring infrastructure awards.
Prefabricated buildings in Saudi Arabia comprise factory-manufactured structural assemblies using light gauge steel framing, insulated metal panels, or precast concrete elements engineered for rapid site installation with reduced labor exposure. These systems serve primary commercial and industrial purposes where compressed construction schedules and standardized quality override traditional cast-in-place methods. Panelized systems lead current volume given their compatibility with Saudi Aramco contractor specifications and Ministry of Housing quality benchmarks, while modular homes represent the fastest-expanding category as Residential Developers pursue Vision 2030 housing delivery targets. Pre-engineered buildings retain mature, high-share status in warehouse and logistics applications where span requirements and crane-loading criteria favor rigid-frame steel geometries.
SFDA and SASO administer product conformity and building material safety protocols, while the Saudi Building Code enforcement through municipal authorities shapes seismic design loads and thermal transmittance thresholds for factory-built assemblies. Compliance with these overlapping regimes determines market access for imported panel systems and governs domestic manufacturer certification cycles. Stakeholders must monitor evolving energy efficiency mandates and local content requirements that will reshape supplier qualification criteria and project bidding dynamics.
Market Dynamics
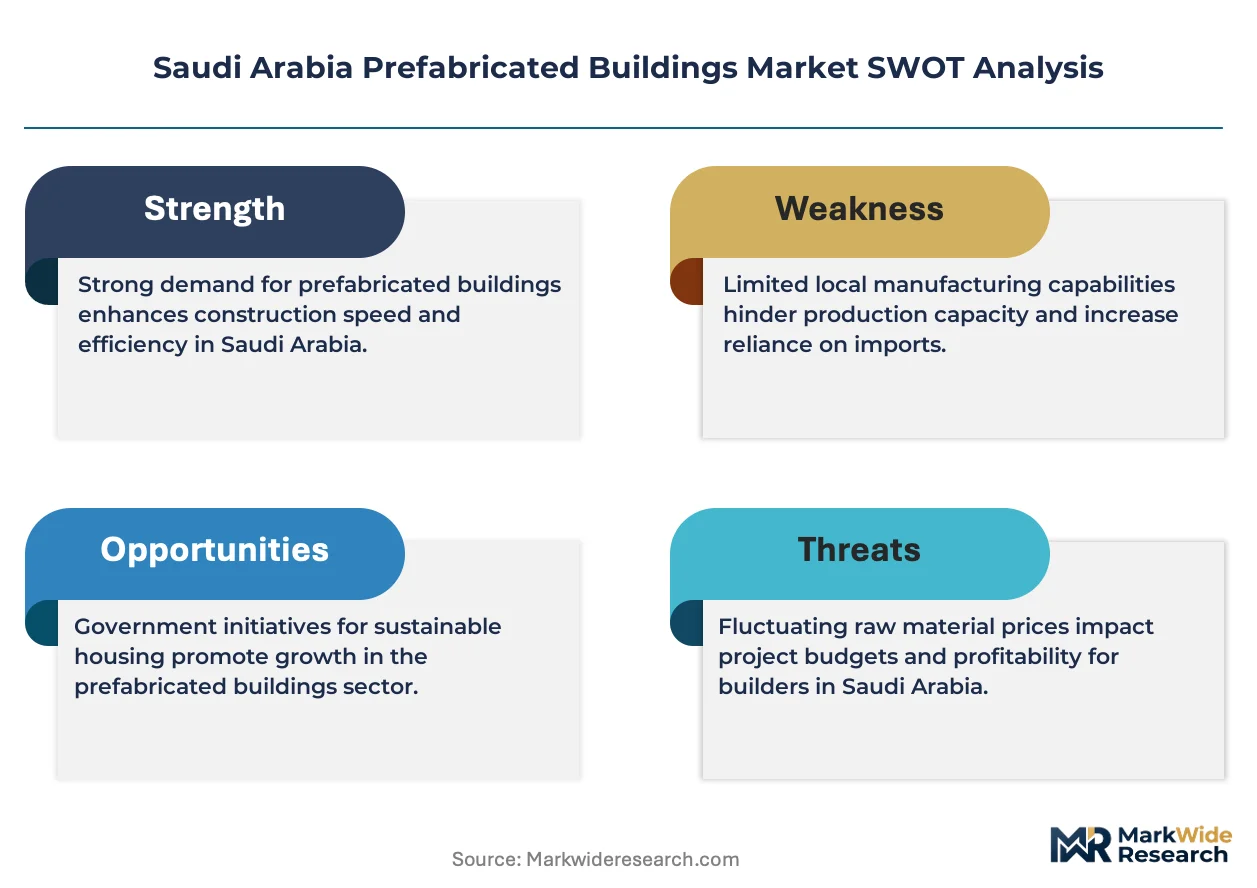
Capital discipline among Saudi developers is compressing project timelines and forcing a structural pivot toward factory-controlled quality assurance over site-dependent labor inputs. This shift intensifies as Vision 2030 housing delivery targets collide with constrained skilled construction workforce availability.
Growth Catalysts
- Vision 2030 Housing Mandates:Government residential delivery targets are channeling public procurement toward panelized systems that compress completion schedules by half versus conventional methods.
- SASO Thermal Performance Standards:Mandatory energy efficiency thresholds for building envelopes are disqualifying traditional block-and-plaster construction in favor of insulated metal panel assemblies.
- Red Sea Project Industrial Corridors:Giga-project construction camps and logistics facilities in the Western Province are generating concentrated demand for turnkey workforce accommodation units.
Market Restraints
- Steel Coil Price Volatility:Input cost swings for galvanized steel sheet directly compress fabricator margins on fixed-price pre-engineered building contracts.
- Import Dependency for Polyurethane Core Materials:Domestic production gaps in rigid foam insulation force reliance on Gulf petrochemical suppliers, creating lead time vulnerability.
- Seismic Design Load Escalation: Saudi Building Code amendments are raising structural engineering requirements that obsolete legacy connection details and demand recertification of established panel systems.
Strategic Opportunities
- Eastern Province Industrial Zone Expansion:Aramco contractor camp renewal cycles and downstream petrochemical facility builds offer recurring volume for modular accommodation specialists.
- BIM-Integrated Manufacturing:Convergence of building information modeling with CNC roll-forming equipment is enabling mass customization of light-gauge steel framing at panelized system price points.
- NEOM Construction Logistics:The linear city's phased development is creating demand for relocatable modular units that can migrate across construction zones as workfronts advance.
Industry Challenges
- Welding Certification Bottlenecks:SFDA structural steel fabricator approval timelines extend 4-6 months, delaying project mobilization for new market entrants.
- Site-Site Coordination Complexity:Just-in-time panel delivery schedules require precision alignment between factory production cycles, customs clearance, and crane availability at congested Riyadh megaproject sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Prefabricated Buildings Market |
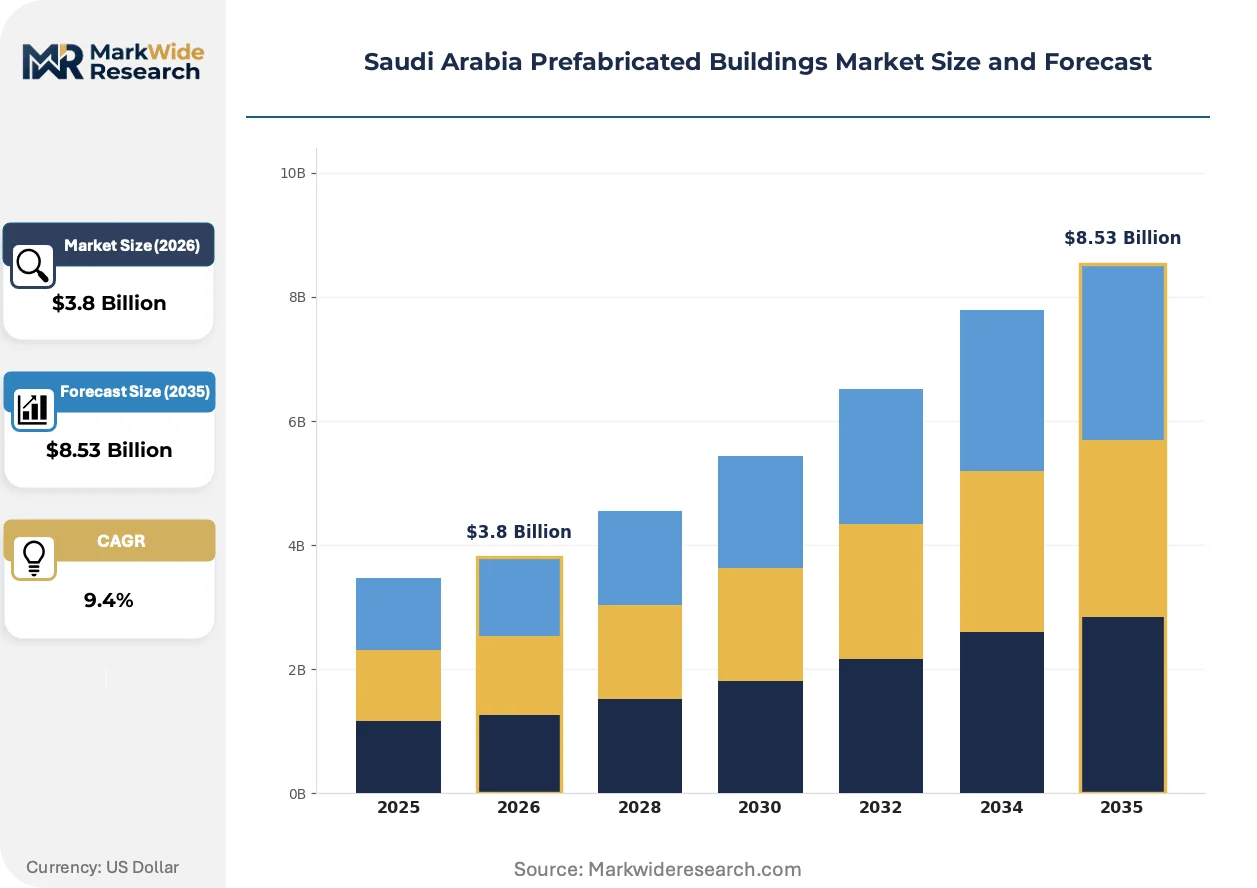
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Homes, Panelized Systems, Pre-Engineered Buildings, Shipping Container Structures Construction Method: Light Gauge Steel, Concrete Panels, Wood Framing, Hybrid Systems End User: Residential Developers, Commercial Constructors, Infrastructure Projects, Industrial Applications Market Channel: Direct Sales, Distributors, Online Platforms, Project-Based Contracts |
| Companies Covered | Kirby Building Systems, Al Jazera Factory For Engineering Construction Co. Ltd., Red Sea Housing Services, Al-Shahin Metal Industries, Katerra Saudi Arabia, Saudi Building Systems Mfg Co., United Company for Caravans and Prefab Houses, Nesma & Partners – Modular Division, Zamil Industrial Investment Co., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Prefabricated Buildings Market Evolving Landscape
Digital fabrication workflows and regulatory pressure on embodied carbon are restructuring how structural assemblies move from factory floor to foundation. These forces favor capital-intensive producers with captive engineering capability over project-assembly contractors.
Cold-formed steel framing systems with integrated MEP rough-in are displacing conventional stick-built construction in mid-rise residential podiums. Saudi developers in Jeddah's northern corridor are specifying these systems for 8-12 story workforce housing blocks. The technology is displacing cast-in-place concrete shear walls by halving structural dead load and enabling smaller foundation footprints on challenging soil conditions.
SASO's expanded scope for factory production control certification now covers thermal transmittance testing and fire resistance rating validation for insulated panel assemblies. Manufacturers must maintain third-party audit trails from raw material batch records through finished goods dispatch. Eastern Province industrial contractors are responding by consolidating supplier bases to pre-approved fabricators with established conformity assessment documentation.
Developer procurement teams are bundling design, fabrication, and erection into single-source contracts with liquidated damages clauses tied to weather-tight enclosure dates. This model displaces fragmented general contracting where separate trades managed structural, envelope, and MEP sequencing. The shift is most visible in Riyadh's Diriyah Gate and Qiddiya entertainment district projects, where master developers demand turnkey accountability from prefabricated building specialists.
Saudi Arabia Prefabricated Buildings Market Segmentation
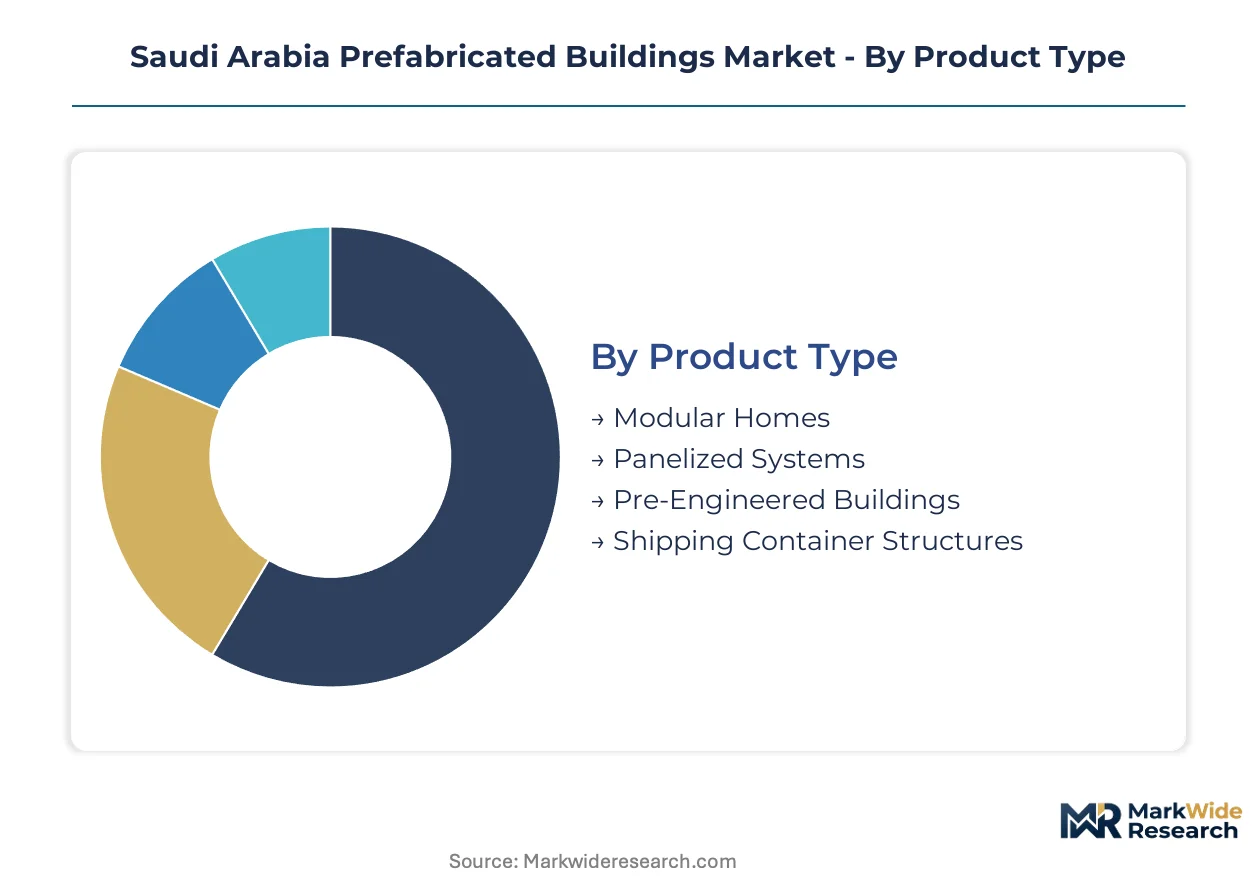
Margin pools in Saudi Arabia's prefabricated buildings sector concentrate where factory-controlled quality intersects with compressed construction timelines mandated by Vision 2030 housing delivery targets. Understanding segment-level profit dynamics reveals where capital discipline and regulatory compliance create sustainable competitive positions.
Product Type:
Margin concentration follows installation speed and customization complexity, with turnkey solutions commanding premium pricing over component sales.
- Panelized Systems:Factory-manufactured wall and roof assemblies using light gauge steel framing with insulated metal panel infill. Demand concentrates in Riyadh megaproject corridors where Saudi Aramco contractor specifications and Ministry of Housing quality benchmarks favor standardized envelope solutions. SASO thermal performance mandates are disqualifying traditional block-and-plaster alternatives.
- Modular Homes:Volumetric units complete with MEP rough-in and interior finishes, engineered for crane-set installation. Residential developers across Jeddah's northern corridor are deploying these for 8-12 story workforce housing blocks where foundation constraints and seismic design loads favor reduced structural dead weight.
- Pre-Engineered Buildings:Rigid-frame steel structures dominate warehouse and logistics applications where wide clear spans and heavy crane-loading criteria apply.
- Shipping Container Structures:Repurposed maritime containers with cutouts and reinforcement for workforce accommodation and temporary facilities serve Red Sea Project construction logistics.
Panelized Systems hold installed capacity. Modular Homes is rotating up the share rankings.
Construction Method:
Cost tier differentiation separates capital-intensive producers with captive coil processing from project-assembly contractors sourcing commodity materials.
- Light Gauge Steel:Cold-formed steel framing with integrated MEP rough-in channels displaces conventional stick-built construction in mid-rise residential podiums. Eastern Province petrochemical facility contractors specify these systems for rapid enclosure of process buildings where corrosion resistance and seismic ductility are critical.
- Concrete Panels:Precast wall and floor elements with embedded reinforcement and insulation cores serve infrastructure projects requiring fire resistance ratings and acoustic separation. Diriyah Gate master developers are bundling these into single-source contracts with liquidated damages clauses tied to weather-tight dates.
- Wood Framing:Limited adoption constrained by Saudi Building Code fire resistance requirements and domestic lumber supply gaps.
- Hybrid Systems:Combinations of steel framing with concrete cores or composite panels address specialized span and load conditions in Qiddiya entertainment district structures.
Light Gauge Steel dominates residential volume. Concrete Panels is climbing the fastest in infrastructure awards.
End User:
Customer type determines procurement complexity, with public-sector residential mandates favoring standardized specifications over private commercial customization.
- Residential Developers:Vision 2030 housing targets channel public procurement toward panelized systems that compress completion schedules versus conventional methods. NEOM's linear city development is creating demand for relocatable modular units that migrate across construction zones as workfronts advance.
- Industrial Applications:Aramco contractor camp renewal cycles and downstream petrochemical facility builds in the Eastern Province offer recurring volume for turnkey workforce accommodation specialists with established SFDA fabricator certification.
- Commercial Constructors:Office and retail developers in Riyadh's central business district specify pre-engineered building systems for speed-to-market on speculative developments.
- Infrastructure Projects:Transportation and utility contractors deploy shipping container structures for site offices and equipment housing on remote project locations.
Residential Developers anchor public procurement volume. Industrial Applications is gaining share fastest through recurring camp renewal cycles.
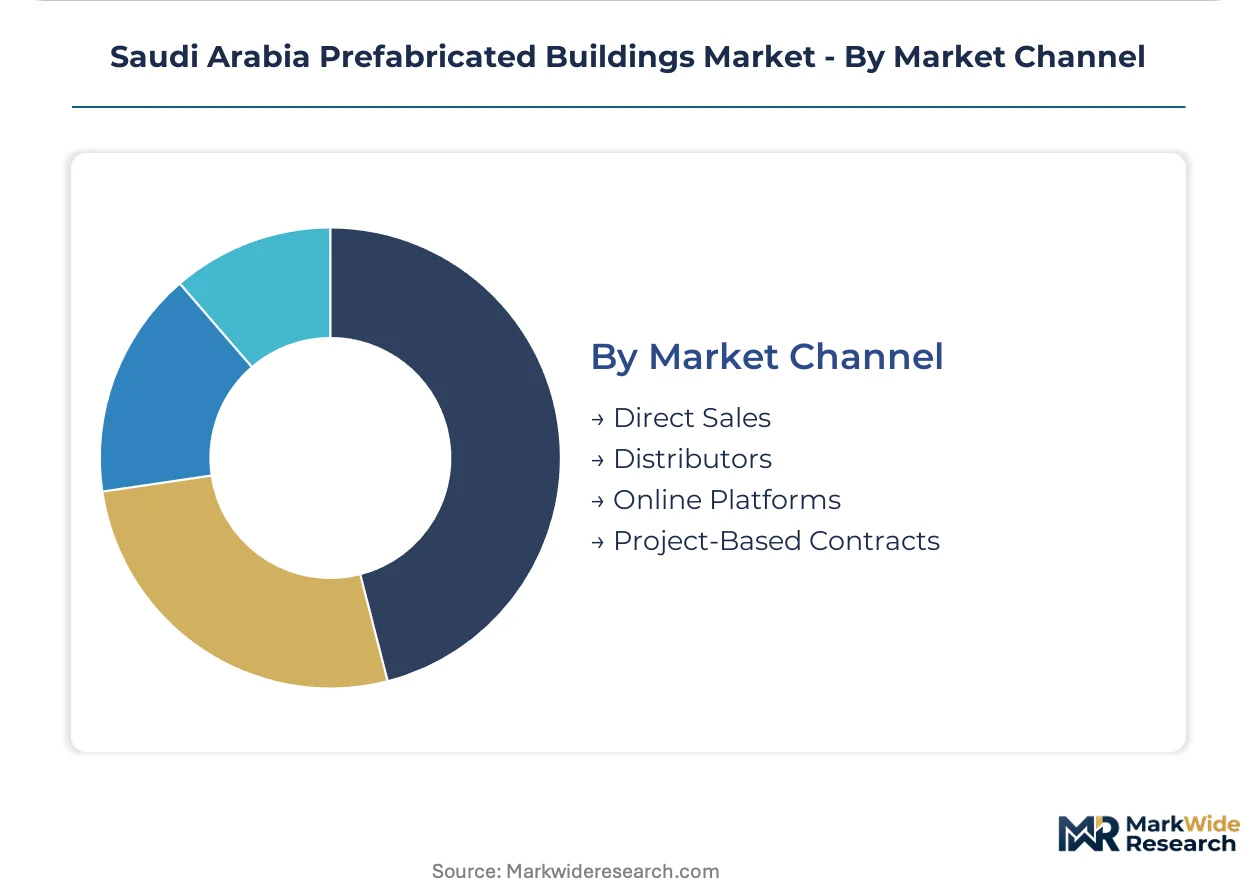
Market Channel:
Supply concentration favors project-based relationships over transactional distribution where just-in-time delivery coordination determines contract profitability.
- Project-Based Contracts:Bundled design-fabrication-erection agreements with liquidated damages clauses displace fragmented general contracting. Master developers at Diriyah Gate and Qiddiya demand turnkey accountability with weather-tight enclosure guarantees.
- Direct Sales:Large-scale pre-engineered building contracts flow through manufacturer-direct relationships with repeat industrial clients, bypassing distributor markups on standardized warehouse specifications.
- Distributors:Regional stockists serve smaller commercial contractors with panelized system components for retrofit and expansion projects.
- Online Platforms:Emerging digital procurement channels for standardized modular units face constraints from SFDA conformity assessment documentation requirements and site-specific engineering customization needs.
Project-Based Contracts command premium pricing. Direct Sales is rotating up the share rankings through repeat industrial awards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Riyadh's megaproject corridor show lowest price elasticity given compressed delivery mandates, while smaller contractors in secondary cities retain higher sensitivity to steel coil volatility. This demand-elasticity gradient shapes where fabricators deploy premium engineering resources versus standardized panel production.
Riyadh
Vision 2030 housing targets and Diriyah Gate master development are channeling procurement toward turnkey panelized systems with liquidated damages clauses. SASO thermal performance mandates are disqualifying traditional block construction. The Riyadh megaproject corridor concentrates demand for weather-tight enclosure guarantees.
Eastern Province
Aramco contractor camp renewal cycles and downstream petrochemical facility builds generate recurring volume for modular accommodation specialists. SFDA structural steel fabricator certification requirements extend approval timelines. Dammam and Jubail industrial zones anchor workforce housing procurement for energy sector contractors.
Jeddah
Residential developers in the northern corridor are deploying cold-formed steel framing for 8-12 story workforce housing blocks. Saudi Building Code seismic design loads favor reduced structural dead weight. The Jeddah Islamic Port logistics cluster drives demand for rapid-assembly warehouse systems.
Western Region
Red Sea Project construction camps and tourism infrastructure are generating concentrated demand for relocatable modular units. Giga-project logistics require units that migrate across construction zones as workfronts advance. The King Abdullah Economic City development zone is emerging as a secondary demand node.
NEOM Northwest
The linear city's phased development is creating demand for modular units with standardized MEP rough-in for rapid redeployment. NEOM construction logistics favor factory-controlled quality over site-dependent labor inputs. The Trojena and Oxagon project zones are specifying BIM-integrated manufacturing for mass customization.
Saudi Arabia Prefabricated Buildings Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Saudi prefabricated buildings sector. Integrated steel fabricators with captive galvanizing capacity command premium positioning on large-scale pre-engineered contracts, while project-assembly contractors compete on mobilization speed for camp and temporary facility awards. Three archetypes dominate: vertically integrated metal building specialists, turnkey workforce accommodation providers, and modular residential developers with BIM-integrated manufacturing. Competitive dynamics center on backward integration into coil processing and strategic consolidation of design-fabrication-erection capabilities under single-source accountability.
Among established Saudi fabricators, Kirby Building Systems exemplifies the integrated steel archetype with regional mill relationships sustaining margin discipline. Red Sea Housing Services anchors the turnkey accommodation tier through Eastern Province industrial zone expertise. Zamil Industrial Investment Co. represents vertically integrated supply chain control spanning upstream coil processing through final erection.
| Leading Market Players |
|---|
| Kirby Building Systems |
| Al Jazera Factory For Engineering Construction Co. Ltd. |
| Red Sea Housing Services |
| Al-Shahin Metal Industries |
| Katerra Saudi Arabia |
| Saudi Building Systems Mfg Co. |
| United Company for Caravans and Prefab Houses |
| Nesma & Partners – Modular Division |
| Zamil Industrial Investment Co. |
| Others |
Value Network & Pricing Analysis
Galvanizing capacity utilization at Eastern Province steel mills shapes margin floors across pre-engineered building contracts. Scale concentration among coil processors enables premium pricing on large-volume awards while compressing margins for project-assembly contractors sourcing spot-market materials.
Pricing Analysis
After-sales service revenue from structural maintenance contracts and panel replacement programs sustains lifetime value for integrated fabricators. Project-based pricing dominates large-scale awards, with differentiation driven by SFDA certification tier and captive galvanizing capacity. Pricing pressure stems from steel coil volatility on fixed-price contracts. Residential developers show highest price sensitivity; Aramco industrial contractors accept premium positioning for turnkey accountability.
Supply Chain Analysis
Saudi Arabia and the UAE anchor regional coil processing and insulated panel manufacturing for Gulf prefabricated building demand. Domestic production draws from imported galvanized steel sheet, polyurethane rigid foam, and aluminum-zinc coating alloys. Supply chain risk centers on single-source vulnerability for rigid foam insulation from Gulf petrochemical suppliers. Distribution runs through project-based direct contracts with master developers, bypassing distributor markups on megaproject awards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's prefabricated buildings sector represents early-cycle expansion, with Vision 2030 housing mandates accelerating factory-controlled construction methods ahead of conventional labor-dependent alternatives.
For Market Incumbents: Fortify backward integration into coil galvanizing and captive engineering capability to defend margins against steel price volatility. Expand SFDA pre-certification capacity to compress mobilization timelines for Aramco camp renewal cycles. Consolidate design-fabrication-erection accountability under single-source contracts with liquidated damages clauses. For New Entrants and Emerging Players: SFDA fast-track certification for light-gauge steel fabricators opens procurement access to Eastern Province industrial zones. Target modular workforce accommodation for Red Sea Project construction logistics where relocatable unit demand outstrips established supply. Lead with BIM-integrated manufacturing capabilities to differentiate on mass customization at panelized price points. For Investors and Strategic Acquirers: Turnkey workforce accommodation specialists with established Eastern Province camp relationships represent priority acquisition targets. Long-term viability hinges on recurring infrastructure awards rather than speculative residential exposure. Watch NEOM construction zone migration patterns as inflection indicator for modular unit redeployment demand.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Fabricator Pre-Certification Investment | Compresses 4-6 month approval timelines to capture Aramco camp renewal volume. |
| Backward Integration into Coil Galvanizing | Insulates margin discipline from steel price volatility on fixed-price contracts. |
| BIM-Integrated Manufacturing Deployment | Enables mass customization of light-gauge framing at standardized panel price points. |
| Turnkey Design-Fabrication-Erection Bundling | Meets Diriyah Gate and Qiddiya master developer accountability requirements. |
| Relocatable Modular Unit Development | Aligns product architecture with NEOM construction zone migration logistics. |
Research Methodology
Cross-validation between primary interviews with Saudi fabricator operations managers, Aramco procurement leads, and Ministry of Housing project directors anchors the qualitative findings. Secondary validation draws from SASO conformity assessment documentation, Saudi Building Code amendments, customs trade data for steel coil imports, and Vision 2030 housing delivery progress reports. Bottom-up project pipeline analysis triangulates against top-down macroeconomic modeling across the analysis window.
Sensitivity analysis on steel coil price assumptions and SFDA certification timeline scenarios frames projection reliability. Segmentation modeling spans product type, construction method, end-user category, and regional demand cluster. CAGRs derive from volume-weighted average growth across segment-level forecasts. Industry-specific inputs include Aramco contractor camp renewal cycles, NEOM phased development schedules, and SASO thermal performance mandate compliance costs.
Decision-makers should treat outputs as directional under sustained Vision 2030 funding commitment and stable steel coil supply assumptions; material deviation in either would warrant model refresh. Specific risks include seismic code amendment recertification costs and rigid foam import dependency disruptions. Recalibration cycles align with material shifts in Saudi Building Code enforcement and giga-project construction logistics patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Vietnam Construction Market
Building Construction
Precast Construction Market
Building Construction
Russia Prefabricated Buildings Market
Building Construction
United Arab Emirates Infrastructure Market
Building Construction
Modular and Prefabricated Construction Market
Building Construction
Poland Construction Market
Building Construction
Dominican Republic Construction Market
Building Construction
Vertical Garden Construction Market
Building Construction
Europe 3D Printing Construction Market
Building Construction
Japan Construction Market
Building Construction
Africa Construction Market
Building Construction
China Prefabricated Buildings Market
Building Construction
Australia Construction Market
Building Construction
North America Construction Market
Building Construction
Saudi Arabia Infrastructure Sector Market
Building Construction
US Prefabricated Buildings Market