
 France Architectural Coatings Market | 2026-2036
France Architectural Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
France Architectural Coatings Market Foresight
Water-based resin systems is pivoting toward bio-based alkyd and acrylic emulsions as manufacturers respond to tightening solvent restrictions. AkzoNobel N.V. leverages its decorative coatings portfolio to dominate premium interior segments across French retail channels. Jotun competes through marine-derived durability technologies adapted for coastal Mediterranean applications. PPG Industries Inc. anchors its position via specialized color-matching services and professional contractor loyalty programs.
Architectural coatings constitute liquid or powder films applied to building substrates for protection, decoration, and functional performance, typically formulated with binders, pigments, extenders, and additives at solids contents ranging from thirty to sixty percent by volume. Water-based paint leads volume sales through residential repainting cycles, while powder coatings represent the fastest-expanding structural category driven by metal facade specifications in commercial complexes. Interior walls command the largest application share, though exterior wall systems carry superior margin pools due to weathering-performance requirements and longer recoating intervals.
ANSM monitors chemical safety in consumer-grade formulations, while the EU Green Deal and RE2020 framework mandate progressive carbon-content reductions and VOC thresholds in new building products. REACH registration requirements constrain imported raw material sourcing, shaping domestic supply chain configurations. Stakeholders must track evolving biobased-content mandates and anticipate reformulation costs before the next regulatory tightening cycle.
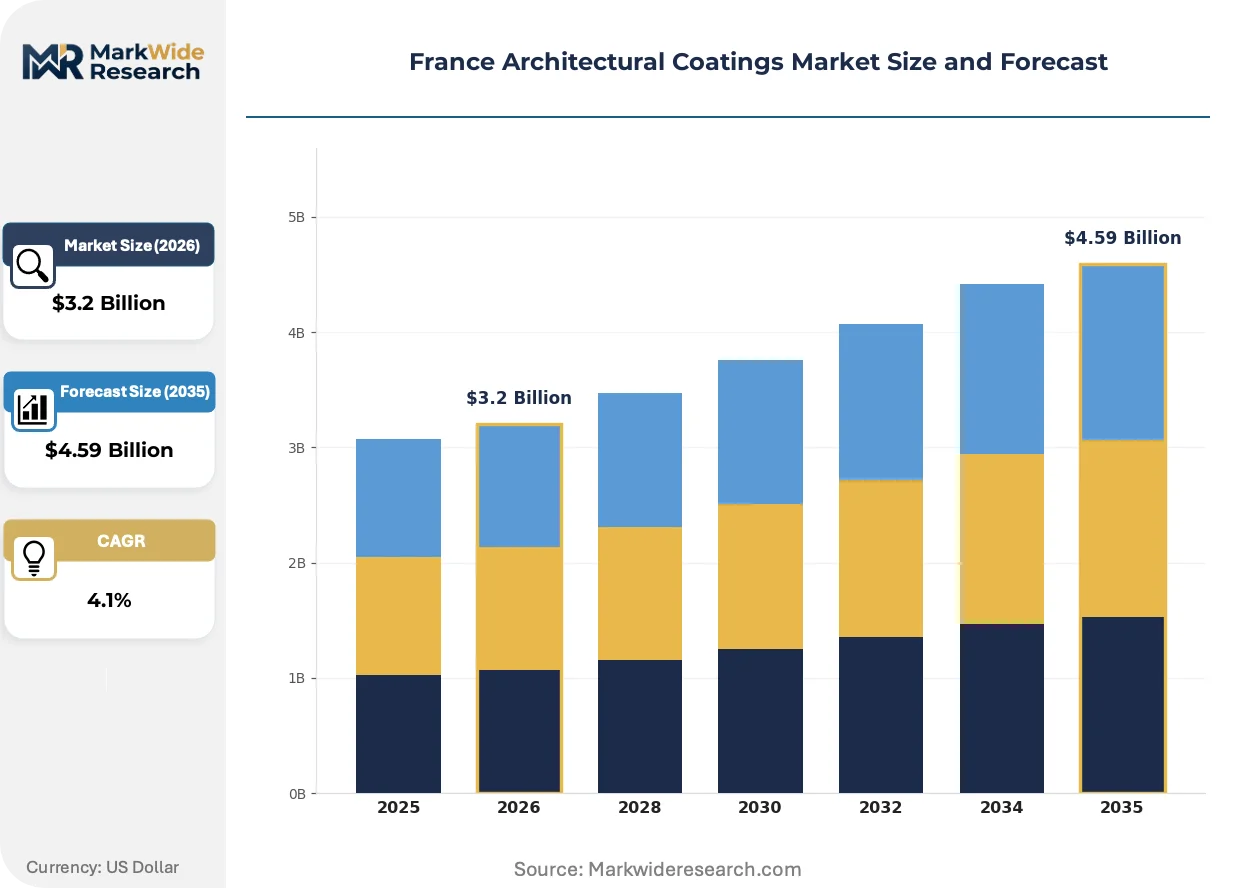
Market Dynamics
France's RE2020 environmental regulation is compressing formulation cycles as manufacturers race to reformulate solvent-based systems into compliant water-borne alternatives before mandatory carbon-content thresholds tighten further.
Growth Catalysts
- Residential renovation waves:Aging housing stock across Ile-de-France and Provence-Alpes-Côte d'Azur is generating repaint demand at fifteen-year cycle compression. Property owners prioritize aesthetic upgrades over structural repairs.
- RE2020 VOC mandates:The French government's progressive volatile organic compound limits are forcing specification shifts toward low-emission interior systems in new construction tenders.
- Bio-based resin advances:Alkyd and acrylic emulsions derived from renewable feedstocks are achieving parity with petroleum-derived binders on drying time and durability metrics.
Market Restraints
- Titanium dioxide volatility:Pigment input costs swing with Chinese export quotas and sulfate process capacity constraints, squeezing margin predictability for mid-tier producers.
- Import dependency for specialty additives:REACH registration burdens concentrate European supply among German and Dutch chemical distributors, limiting formulation flexibility.
- Performance gaps in exterior durability:Water-based systems still underperform solvent-borne alkyds on chalking resistance and substrate adhesion in Mediterranean UV exposure zones.
Strategic Opportunities
- Coastal corrosion protection:Marine-grade durability specifications from Côte d'Azur yacht maintenance yards are migrating to residential exterior applications with salt-air exposure.
- Professional contractor channel digitization:Color-matching software and just-in-time delivery platforms are capturing loyalty among Paris metropolitan area painting crews.
- Circular economy mandates:Extended producer responsibility frameworks under EU Green Deal implementation will reward take-back and recycling infrastructure investments.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in bio-based polymer synthesis and VOC-compliant additive packages concentrates among retiring cohorts at legacy French paint manufacturers.
- Multi-standard certification timelines:Simultaneous ANSM safety reviews, EU Ecolabel applications, and NF environment mark approvals extend product launch windows by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Architectural Coatings Market |
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $4.59 Billion |
| CAGR (2026 – 2036) | 4.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-based Paint, Solvent-based Paint, Powder Coatings, Emulsion Paint, Alkyd Paint Application: Exterior Walls, Interior Walls, Ceilings, Wood Surfaces, Metal Surfaces End User: Residential Buildings, Commercial Complexes, Public Infrastructure, Educational Institutions Packaging Type: Metal Cans, Plastic Buckets, Aerosol Cans, Pails |
| Companies Covered | Nippon Paint Holdings Co., Ltd., Jotun, CIN S.A., Beckers Group, Sacal International Group, AkzoNobel N.V., DAW SE, Meffert AG Farbwerke, PPG Industries Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Architectural Coatings Market Shifts & Advancements
Formulation science is pivoting toward carbon-accounted raw materials as regulatory pressure fuses with contractor demand for simplified compliance documentation.
Photocatalytic titanium dioxide coatings is electrifying the self-cleaning facade segment by decomposing atmospheric pollutants under UV exposure. Commercial developers in Lyon and Marseille are specifying these systems for high-visibility curtain wall projects. The technology is compressing maintenance contract values while premiumizing specification fees for applicators certified in nano-surface preparation.
REACH authorization procedures are constraining chromate-based corrosion inhibitor availability for metal primers. French importers are pivoting toward silane-zirconium hybrid pretreatments approved under ECHA's sunset date extensions. Powder coating applicators serving airport and stadium infrastructure projects face the steepest formulation retooling costs.
Specification authority is migrating from general contractors to facade engineering consultants armed with whole-life carbon calculators. These advisors now disqualify solvent-borne systems from Paris region commercial tenders regardless of upfront cost advantages. The shift is fragmenting legacy distribution relationships and elevating technical service capabilities over volume rebates in supplier selection.
France Architectural Coatings Market Segmentation
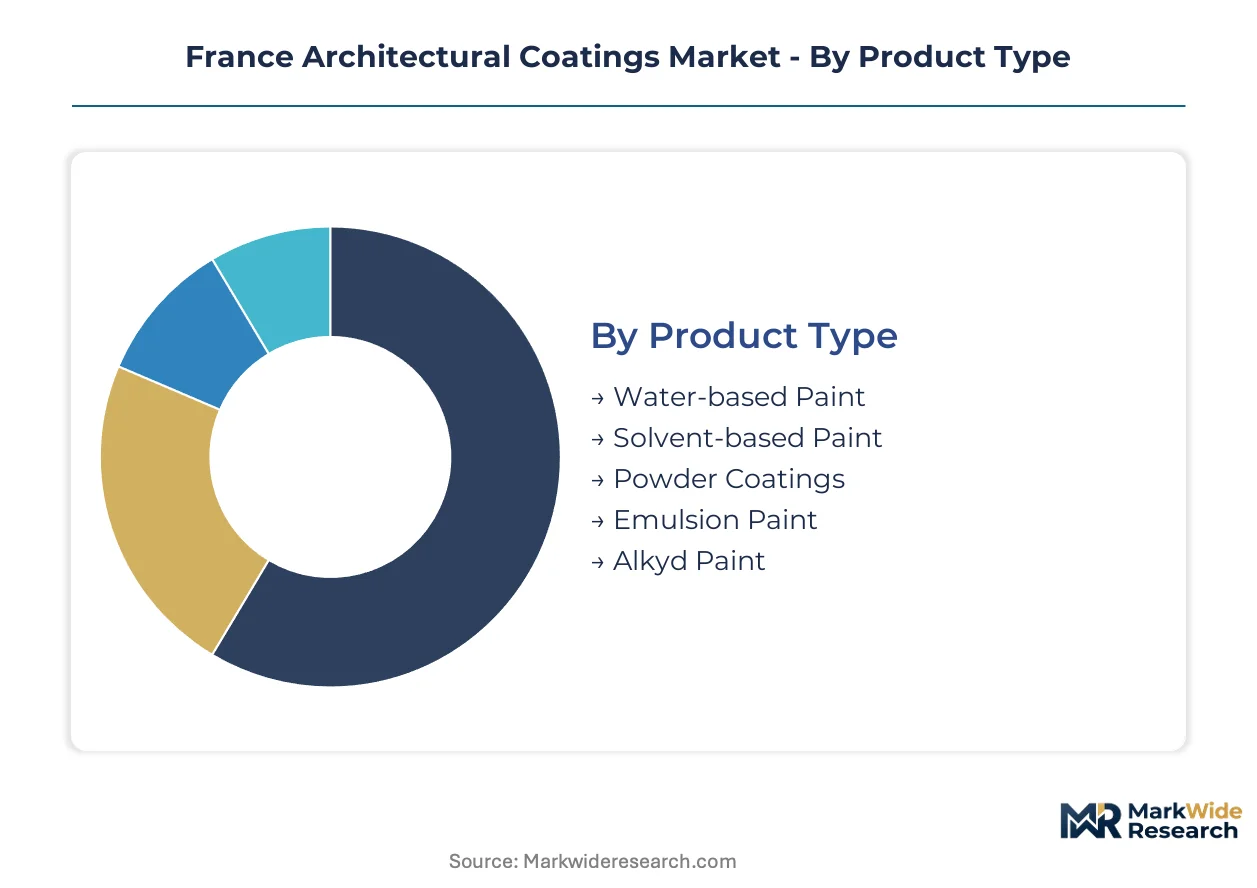
Architectural coatings demand fragments across formulation chemistry, substrate requirements, and project scale. Each dimension carries distinct margin structures and regulatory exposure under France's tightening environmental framework.
Product Type:
Volume sales concentrate in water-borne systems, while premium pricing pools around specialized solvent and powder technologies serving durability-critical specifications.
- Water-based Paint:Acrylic and vinyl-acrylic emulsions dominate residential repaint cycles through low-VOC compliance with RE2020 thresholds. Paris metropolitan area contractors specify these systems for interior apartment renovations where tenant occupancy limits drying time and fume exposure.
- Solvent-based Paint:Traditional alkyd and urethane formulations retain specification in exterior metal protection and historical monument restoration where substrate penetration and weathering resistance outweigh emission concerns. Marseille coastal applications still specify these for salt-air corrosion resistance despite regulatory pressure.
- Powder Coatings:Thermoset polyester and epoxy powders are expanding fastest in commercial facade metalwork, driven by zero-VOC profiles and single-coat efficiency on aluminum curtain wall systems.
- Emulsion Paint:Vinyl and styrene-acrylic copolymer emulsions serve mass-market interior segments through big-box retail channels, competing primarily on tinting system breadth and coverage claims.
- Alkyd Paint:Oil-modified polyester resins, increasingly bio-based, persist in professional contractor preferences for wood trim and joinery where gloss retention and block resistance matter.
Today's leader: Water-based Paint. Tomorrow's challenger: Powder Coatings.
Application:
Exterior specifications command technical service investment, while interior volumes drive manufacturing scale economics.
- Exterior Walls:Elastomeric acrylics and silicone-modified systems protect against freeze-thaw cycling and UV degradation. Ile-de-France commercial developers specify these for building envelope longevity in energy retrofit projects.
- Interior Walls:Matte and eggshell latex emulsions constitute the volume base, with scrub resistance and stain blocking differentiating professional-grade from retail offerings. Provence-Alpes-Côte d'Azur residential renovation sustains repaint frequency above national averages.
- Ceilings:Flat white formulations with high hiding power and spatter resistance target speed-oriented professional applicators. Acoustic texture coatings represent a specialized sub-segment in commercial office fit-outs.
- Wood Surfaces:Transparent stains, opaque solids, and varnish systems protect exterior joinery and decking. Breton coastal properties drive marine-grade durability specifications.
- Metal Surfaces:Primers, direct-to-metal coatings, and finish coats address corrosion protection for structural steel, railings, and architectural metalwork. Powder coating conversion is accelerating in this application.
Exterior Walls extract the highest margin per liter. Interior Walls move the highest literage.
End User:
Residential decision-making fragments across DIY homeowners and professional crews, while institutional buyers consolidate purchasing through framework agreements.
- Residential Buildings:Single-family and multi-family housing drives repaint demand on fifteen-year cycles, with aesthetic refresh prioritization over structural repair. Color-matching services and weekend project sizing dominate retail channel configuration.
- Commercial Complexes:Office, retail, and hospitality properties specify high-durability systems with extended maintenance intervals. Facility managers in Lyon and Marseille commercial districts increasingly require whole-life carbon documentation.
- Public Infrastructure:Transportation hubs, utilities, and government buildings operate under public procurement rules favoring EU Ecolabel-certified products. ANSM safety reviews add compliance layers to specification.
- Educational Institutions:Schools and universities combine high-traffic durability needs with strict indoor air quality mandates for occupied renovation. Summer vacation windows compress application schedules.
Residential Buildings anchor volume. Commercial Complexes anchor value.
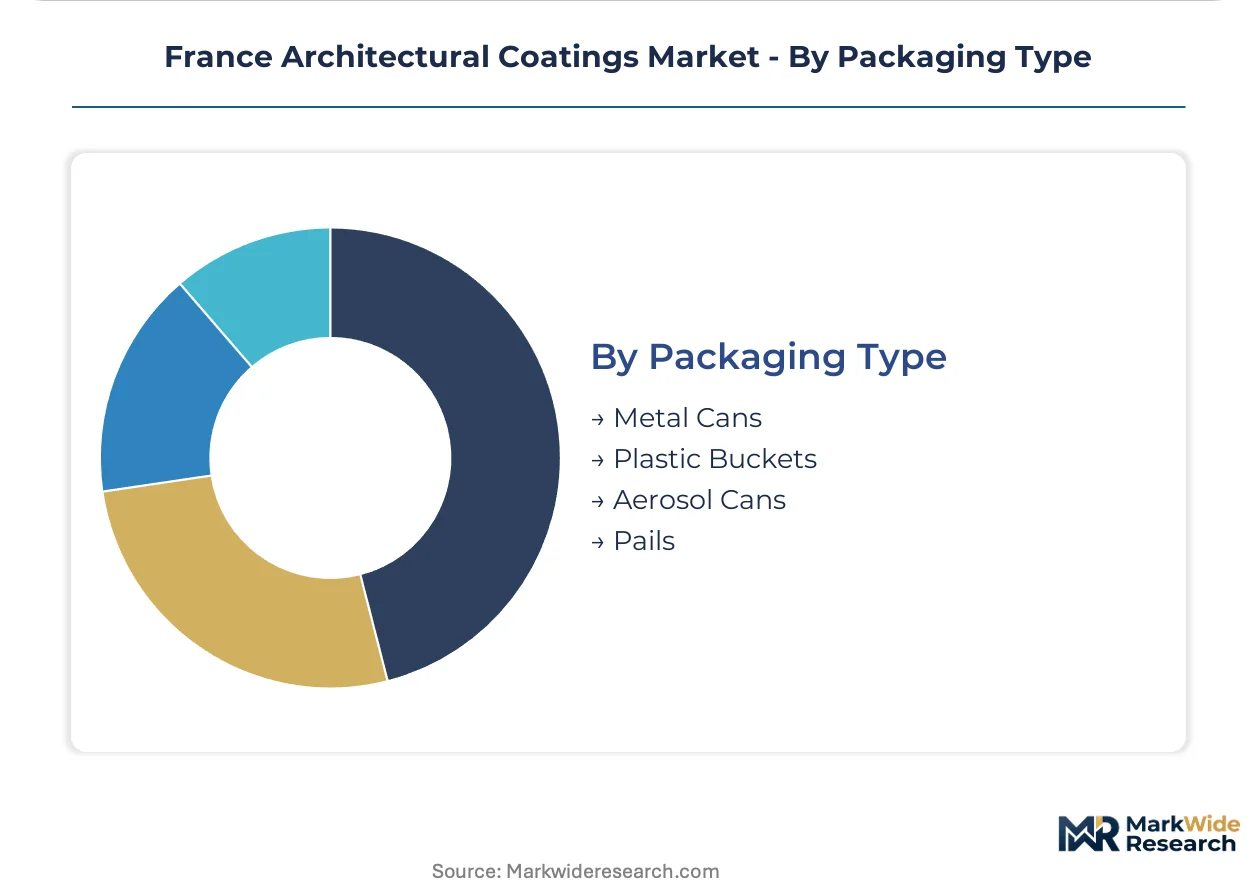
Packaging Type:
Professional contractor preference for handling efficiency shapes large-format demand, while retail accessibility sustains smaller units.
- Metal Cans:Traditional tinplate and aluminum cans serve solvent-based and specialty coatings where chemical compatibility and shelf stability matter. Historical supply chain infrastructure supports continued specification.
- Plastic Buckets:Polypropylene pails with integrated handles and pour spouts dominate water-based paint distribution. Stackability and retail shelf presence drive five-liter and fifteen-liter standardization.
- Aerosol Cans:Spray packaging addresses touch-up, small project, and hard-to-brush applications. Professional crews in Paris metropolitan area maintenance services rely on these for rapid repair work.
- Pails:Industrial-grade plastic and steel pails serve bulk professional purchasing, particularly for commercial project scale and color-matched batch consistency.
Plastic Buckets own the present. Aerosol Cans are gaining professional acceptance fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Île-de-France anchors French architectural coatings demand through Paris metropolitan renovation cycles and commercial facade specifications. Regional differentiation concentrates along climate exposure, regulatory enforcement intensity, and contractor channel maturity.
Île-de-France
Paris metropolitan area contractors drive water-based interior specifications where tenant occupancy limits drying windows. ANSM safety reviews add compliance layers to educational institution renovations in Val-de-Marne and Seine-Saint-Denis. La Défense business district commercial developers increasingly require whole-life carbon documentation for curtain wall projects.
Provence-Alpes-Côte d'Azur
Mediterranean UV exposure and salt-air corrosion sustain solvent-based alkyd specifications for coastal residential exteriors despite RE2020 pressure. Marseille commercial port infrastructure and yacht maintenance yards generate marine-grade durability demand. Nice and Cannes hospitality renovation cycles compress repaint intervals below national averages.
Auvergne-Rhône-Alpes
Lyon commercial developers specify photocatalytic titanium dioxide coatings for high-visibility facade projects targeting air quality credentials. RE2020 enforcement tightest in Rhône department new construction tenders. Grenoble alpine climate conditions test elastomeric acrylic performance on thermal retrofit building envelopes.
Hauts-de-France
Industrial heritage building restoration in Lille metropolitan area sustains traditional alkyd and urethane formulations for substrate compatibility. REACH registration burdens concentrate raw material sourcing through Belgian and Dutch chemical distributors serving the region. Dunkirk port logistics infrastructure supports powder coating import flows for commercial metalwork.
Nouvelle-Aquitaine
Bordeaux wine country tourism properties drive aesthetic refresh cycles on shorter intervals than structural repair timelines. Atlantic coastal exposure in Arcachon and Biarritz generates marine-grade specification migration from yacht maintenance standards. Limoges ceramic industry heritage shapes regional contractor preferences for specialized substrate preparation.
France Architectural Coatings Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers balance water-based volume expansion against solvent-based specialty retention. The vendor base fragments across three tiers: multinational chemical conglomerates with decorative coatings divisions, mid-cap European specialists with regional formulation expertise, and domestic French producers serving contractor loyalty networks. Strategic archetypes include premium interior specialists leveraging retail channel presence, coastal durability innovators adapting marine technologies, and industrial-scale powder coating applicators. M&A activity concentrates on bio-based resin technology acquisitions, while capacity expansion focuses on water-borne emulsion plants near Paris logistics corridors.
Among Netherlands-based multinationals, AkzoNobel N.V. anchors the premium interior segment through retail channel density. Norwegian specialist Jotun occupies a position exemplifying coastal durability migration from marine to residential applications. Pittsburgh-based PPG Industries Inc. represents the professional contractor loyalty archetype through color-matching infrastructure investment. These three entities illustrate competitive positioning vectors without exhausting the participant universe.
| Leading Market Players |
|---|
| Nippon Paint Holdings Co., Ltd. |
| Jotun |
| CIN S.A. |
| Beckers Group |
| Sacal International Group |
| AkzoNobel N.V. |
| DAW SE |
| Meffert AG Farbwerke |
| PPG Industries Inc. |
| Others |
Supply & Pricing Matrix
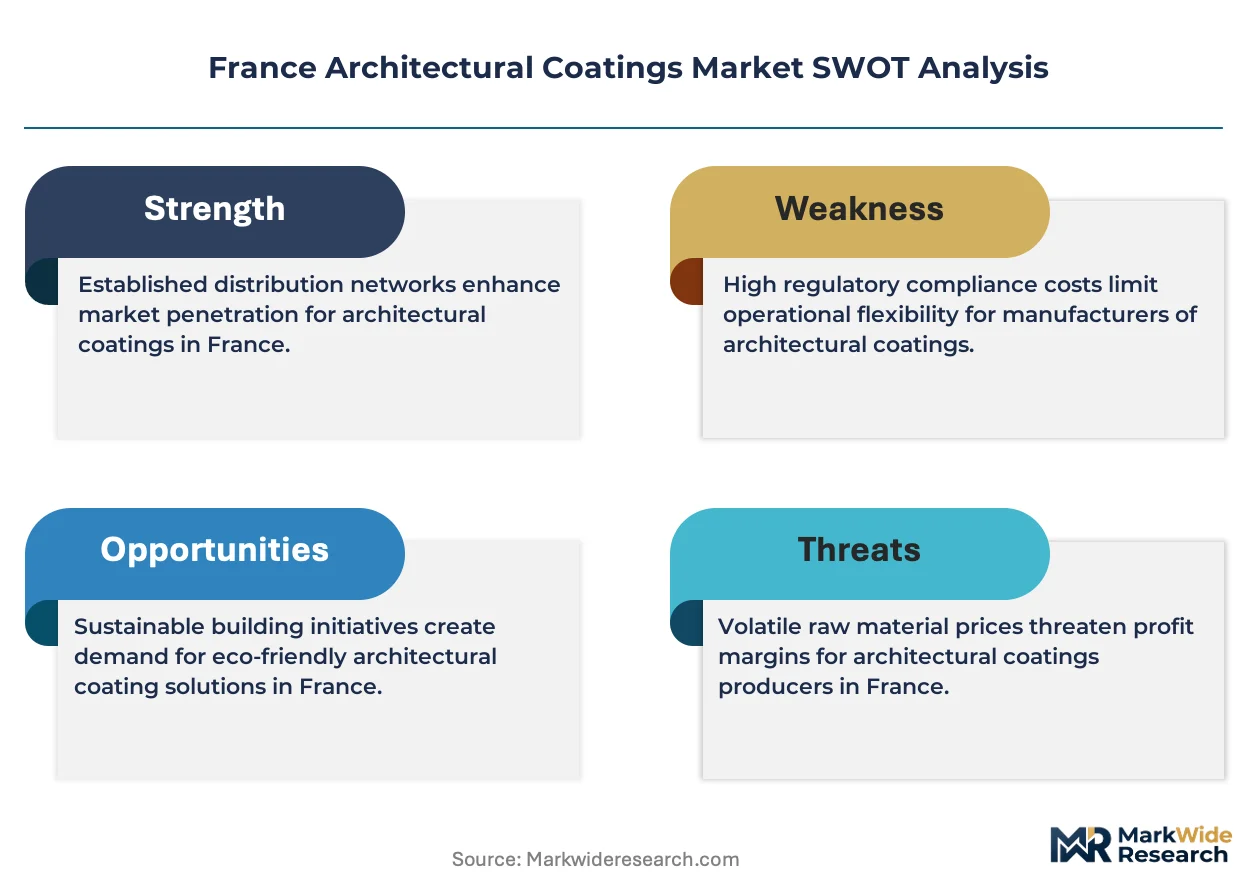
Titanium dioxide benchmark pricing cascades through French architectural coatings supply chains, compressing margin pools at mid-tier producers while concentrating pricing power among integrated resin manufacturers serving Paris metropolitan contractors. RE2020 compliance costs layer onto raw material volatility, forcing specification-grade suppliers to absorb carbon-accounting expenses or pass through to commercial tender bids.
Pricing Analysis
Input-cost pass-through operates asymmetrically across the value chain, with pigment and bio-based resin surcharges flowing faster to professional contractors than retail DIY channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by Ecolabel certification tier and volume commitment scale. Pricing pressure stems from titanium dioxide quota volatility and REACH-registered additive scarcity. DIY homeowners exhibit highest price sensitivity; facade engineering consultants demonstrate lowest sensitivity due to whole-life carbon accounting mandates.
Supply Chain Analysis
Dual-sourcing requirements for titanium dioxide and specialty alkyd resins compel French formulators to qualify both German and Dutch chemical distributors alongside domestic suppliers. Raw material dependencies center on Chinese-processed TiO2, German epoxy intermediates, and Scandinavian bio-based feedstocks. Supply chain risk concentrates in REACH authorization timelines for corrosion inhibitor alternatives. Distribution runs through big-box retail for residential volumes and direct-to-contractor platforms for professional specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's architectural coatings market represents a late-cycle quality story as RE2020 enforcement and whole-life carbon documentation shift specification authority toward premium, certified systems. Demand is migrating from volume-driven retail repaint toward durability-critical commercial facade applications.
For Market Incumbents: Extend technical service capabilities into whole-life carbon consulting to capture specification authority from facade engineering consultants. Deepen captive supply of bio-based alkyd resins before REACH authorization deadlines constrain imported alternatives. Consolidate contractor loyalty through color-matching software integration and just-in-time delivery platforms serving Ile-de-France painting crews. For New Entrants and Emerging Players: Specialty distributors serving Breton and Mediterranean coastal markets offer the most penetrable channel entry point, as marine-grade durability specifications migrate from yacht maintenance to residential exterior applications. Target photocatalytic titanium dioxide facade projects in Lyon and Marseille commercial districts where air quality credentials command premium positioning. Pursue Ecolabel certification as the primary go-to-market credential for public infrastructure tenders. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap European specialists possessing regional formulation expertise and established ANSM regulatory relationships. Long-term viability hinges on bio-based resin technology integration and circular economy infrastructure readiness. Acquisition candidates should demonstrate proven RE2020 compliance pathways and coastal durability IP. The signal to watch is tightening VOC thresholds in educational institution renovations, which would accelerate premium system conversion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Resins | Captures margin from German chemical distributors while securing RE2020-compliant feedstock supply. |
| Photocatalytic Coating Certification Program | Positions applicators for Lyon and Marseille commercial facade specifications targeting air quality credentials. |
| Contractor Platform Digitization | Locks in Paris metropolitan professional crews through color-matching software and just-in-time delivery. |
| Take-Back Infrastructure Investment | Aligns with EU Green Deal extended producer responsibility frameworks rewarding circular economy compliance. |
| Coastal Durability Technology Licensing | Monetizes marine-grade IP from Côte d'Azur yacht maintenance for salt-air residential applications. |
Research Methodology
Coverage spans Ile-de-France, Provence-Alpes-Côte d'Azur, Auvergne-Rhône-Alpes, and Hauts-de-France, with primary inputs from each region's contractor networks and distribution channels. Formulation chemists at legacy French manufacturers, procurement leads at commercial developers, retail category managers, and facade engineering consultants provided qualitative intelligence. Secondary validation drew from ANSM safety filings, EU Ecolabel product registries, REACH authorization databases, and French customs trade records. Bottom-up project pipeline analysis triangulated against top-down sector spending estimates.
Granularity-level modeling captured product type, application substrate, end-user segment, and packaging format dimensions at the regional department level. CAGRs were derived from segment-level volume and value trajectories across the projection horizon, with bio-based resin adoption curves and RE2020 compliance timelines as key forecast inputs. Price elasticity assumptions reflected differential sensitivity between DIY retail and professional contractor channels.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to RE2020 threshold tightening schedules and titanium dioxide export quota volatility. Deviation in ANSM review timelines or ECHA sunset date extensions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
US Contract Glazing Market
Building Materials
Zinc Polycarboxylate Cement Market
Building Materials
Fly Ash Bricks Market
Building Materials
Asia-Pacific Facade Market
Building Materials
North America Dry-Mix Mortar Market
Building Materials
Basalt Rock Market
Building Materials
Refractory Cement Market
Building Materials
North America Architectural Coatings Market
Building Materials
Cribbing Blocks Market
Building Materials
Engineered Wood Product Market
Building Materials
India Construction Ornamental Stone Market
Building Materials
ASEAN Dry Mix Mortar Market
Building Materials
Steel Products Market
Building Materials
North America Spray Polyurethane Foam for Building and Construction Market
Building Materials
Europe Fireproof Cladding Market
Building Materials
Acoustic Damping Tiles Market