
 Asia-Pacific White Cement Market | 2026-2036
Asia-Pacific White Cement Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific White Cement Market Outlook
Low-carbon clinker substitution is tilting production economics across the Asia-Pacific white cement industry. J.K. Cement Ltd leverages captive limestone reserves in Rajasthan to sustain cost-advantaged output of high-grade Portland white. UltraTech Cement Ltd anchors its position through integrated grinding capacity spanning Gujarat and Maharashtra. SCG International Corporation competes on Thai-sourced kaolin clay formulations that differentiate brightness performance.
White cement is a specialized hydraulic binder manufactured from iron-free raw materials, typically achieving reflectance values above 80 percent on the Hunter scale through controlled kiln atmosphere and raw meal chemistry. Its primary purpose is architectural finishing where color consistency and surface aesthetics override structural load-bearing requirements. Portland White occupies the dominant share of regional volume, though Calcium Aluminate commands premium pricing in precast applications requiring rapid strength gain and chemical resistance. Infrastructure and Commercial applications together concentrate the largest margin pools, driven by government monument restoration programs and premium retail facade specifications across Southeast Asian capitals.
India's BIS mandates minimum whiteness indices and compressive strength thresholds that filter substandard imports from neighboring supply bases. Thailand's Industrial Standards Institute and Japan's JIS frameworks impose parallel constraints on heavy metal content and sulfate resistance, shaping cross-border trade patterns. China's GB standards for decorative cement products add a third compliance layer for exporters targeting municipal beautification contracts. Stakeholders must monitor how tightening embodied carbon regulations across these jurisdictions reshape kiln fuel choices and clinker factor requirements.
Market Dynamics
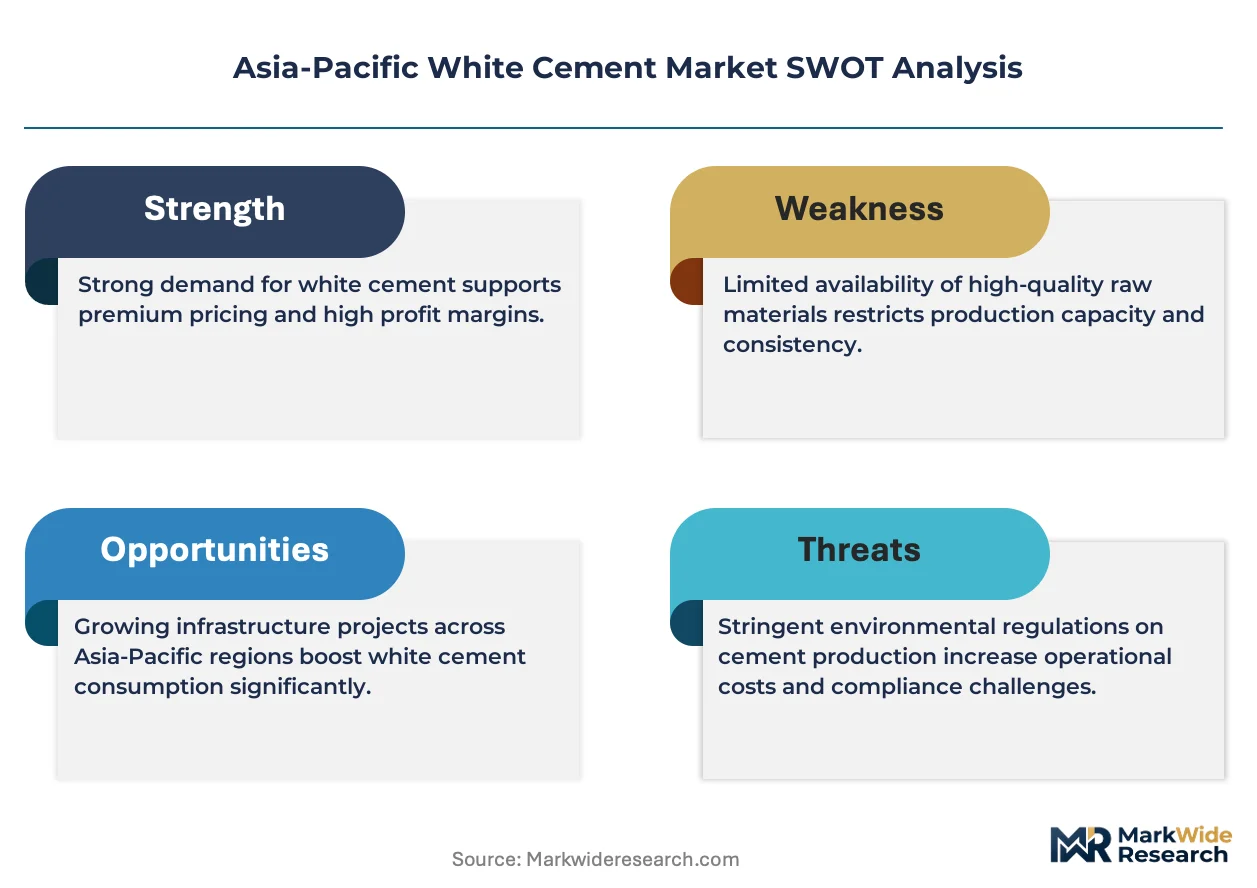
Low-carbon clinker substitution is compressing production economics across Asia-Pacific white cement manufacturing, forcing kiln operators to reconfigure fuel mixes and raw meal chemistry while preserving brightness specifications.
Growth Catalysts
- India's BIS Certification Mandates:Tightening whiteness index and compressive strength requirements are filtering substandard imports and consolidating domestic production quality tiers.
- Decorative Concrete in Luxury Residential:Premium facade specifications in Southeast Asian capitals are pulling volume upward through monument restoration and retail exterior programs.
- Kaolin Clay Formulation Advances:Thai-sourced high-purity clay inputs are enabling brightness performance differentiation in precast architectural applications.
Market Restraints
- Iron-Free Limestone Scarcity:Captive reserves concentrate in Rajasthan and Gujarat, creating input cost volatility for non-integrated producers.
- Energy-Intensive Kiln Operations:Alternative fuel adoption remains technically constrained by whiteness consistency requirements in controlled atmosphere firing.
- Calcium Aluminate Substitution:Rapid-strength precast segments increasingly specify aluminate cements for chemical resistance, displacing Portland white in premium niche applications.
Strategic Opportunities
- Vietnam Infrastructure Corridors:Northern and central province mega-projects present underpenetrated demand for standardized decorative concrete specifications.
- Japan's JIS Heavy Metal Limits:Stricter sulfate resistance and contamination thresholds create compliance-based export openings for certified regional producers.
- Digitized Supply Chain Integration:Real-time brightness monitoring and logistics coordination are converging to reduce specification variance in cross-border bulk shipments.
Industry Challenges
- Kiln Process Engineering Talent:Specialized expertise in controlled-atmosphere firing and raw meal chemistry is concentrated among retiring technical cohorts in established production bases.
- Dual Certification Timelines:Simultaneous BIS, JIS, and GB standard compliance for multi-jurisdiction project bids extends qualification cycles by twelve to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific White Cement Market |
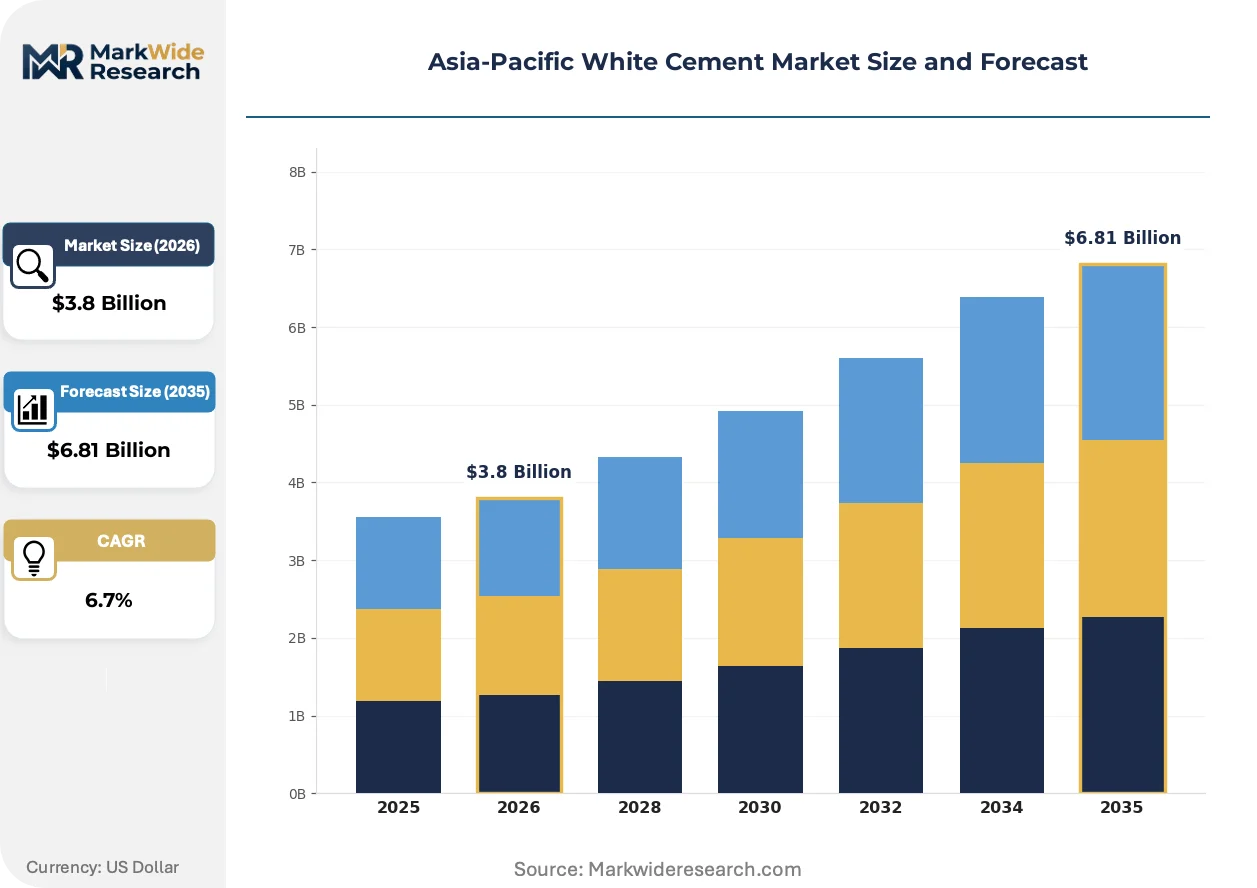
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portland White, Calcium Aluminate, White Masonry, Others Application: Residential, Commercial, Infrastructure, Precast Products End User: Contractors, Manufacturers, Architects, Developers Distribution Channel: Online, Direct Sales, Distributors, Retail |
| Companies Covered | J.K. Cement Ltd, Ambuja Cement (Adani Group), Cementir Holding NV, SCG International Corporation, India Cements Ltd, UltraTech Cement Ltd, CIMSA, SUMITOMO OSAKA CEMENT Co., Ltd., HOLCIM, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific White Cement Market Strategic Shifts
Automation and real-time quality control systems are penetrating white cement production workflows, compressing variance in brightness consistency while enabling predictive maintenance in high-temperature kiln environments.
Spectral analysis instrumentation is digitizing raw meal blending operations across integrated grinding facilities. Commercial monument restoration contractors in Bangkok and Ho Chi Minh City are adopting brightness-verified batch documentation. The technology is digitizing quality assurance workflows that previously relied on post-production laboratory testing, shortening specification confirmation cycles.
China's GB standards for decorative cement products are tightening embodied carbon disclosure requirements for municipal beautification contract eligibility. Exporters targeting state-funded infrastructure must document clinker factor and alternative fuel percentages in technical bids. Southeast Asian producers with biomass co-processing capabilities are capturing preferential supplier status in cross-border procurement frameworks.
Buyer consolidation among luxury residential developers is compressing switching cycles for white cement procurement. Single-source specifications now dominate premium tower projects in Mumbai and Bengaluru, displacing multi-vendor qualification protocols. The pattern is most visible in western and southern Indian states where real estate clusters overlap with infrastructure corridor development.
Asia-Pacific White Cement Market Segmentation
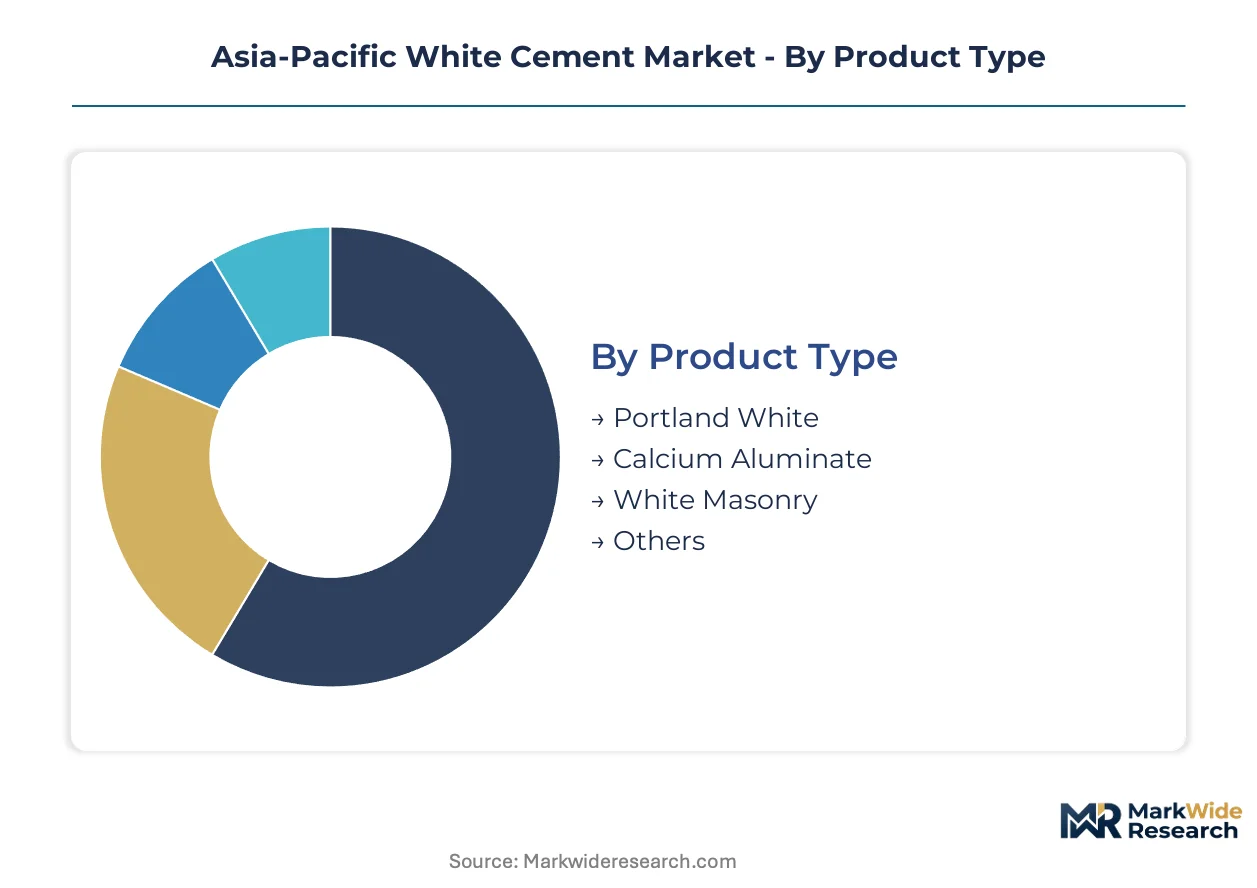
White cement procurement cycles vary dramatically across product grades and end-use specifications, with architectural finish materials turning over faster than structural precast formulations. Understanding these velocity differentials helps suppliers align inventory positioning with project timelines across India's western corridor and Southeast Asian capitals.
Product Type:
Portland White commands the shortest replenishment cycles due to standardized specifications, while Calcium Aluminate extends project timelines through custom blending requirements.
- Portland White:Manufactured from iron-free limestone and controlled kiln atmosphere to achieve Hunter scale reflectance above 80 percent. Demand concentrates in India's western states where Rajasthan's captive reserves feed integrated grinding capacity serving Mumbai and Bengaluru luxury residential towers.
- Calcium Aluminate:High-alumina clinker formulation delivering rapid strength gain and sulfate resistance for chemical exposure environments. Thai producers leverage kaolin clay inputs to capture premium pricing in Bangkok monument restoration and Ho Chi Minh City retail facade specifications.
- White Masonry:Finely ground hydraulic binder blended for mortar consistency in decorative brickwork and tile adhesion across Southeast Asian commercial interiors.
- Others:Specialty formulations including decorative plasters and terrazzo binders serving niche architectural finishing segments.
Portland White anchors the volume base while Calcium Aluminate gains share at the steepest rate.
Application:
Margin profiles diverge sharply between visible architectural surfaces and buried structural elements, with aesthetic specifications commanding premium positioning.
- Residential:Premium facade treatments and decorative concrete in luxury towers across Mumbai, Bengaluru, and Jakarta drive specification intensity. Developer consolidation toward single-source procurement compresses vendor qualification cycles.
- Commercial:Retail exterior programs and corporate campus finishes concentrate in Bangkok, Ho Chi Minh City, and Singapore where brightness-verified batch documentation is becoming standard.
- Infrastructure:Government monument restoration and municipal beautification projects across India and Vietnam require compliance with tightening embodied carbon disclosure requirements.
- Precast Products:Architectural cladding and decorative panels demand consistent color matching across production batches.
Infrastructure absorbs the largest project scale while Residential delivers the highest margin per ton.
End User:
Technical sophistication determines procurement authority, with architects specifying grades that contractors then source through qualified channels.
- Contractors:Execute project-level procurement for volume applications, prioritizing logistics reliability and brightness consistency verification.
- Manufacturers:Precast producers and ready-mix operators demand batch documentation for quality assurance in cross-border supply arrangements.
- Architects:Specify whiteness indices and performance grades in design documentation, influencing downstream vendor selection for premium projects.
- Developers:Consolidated luxury residential players in western and southern India now mandate single-source specifications to reduce variance risk.
Contractors handle the transaction volume while Architects control specification authority.
Distribution Channel:
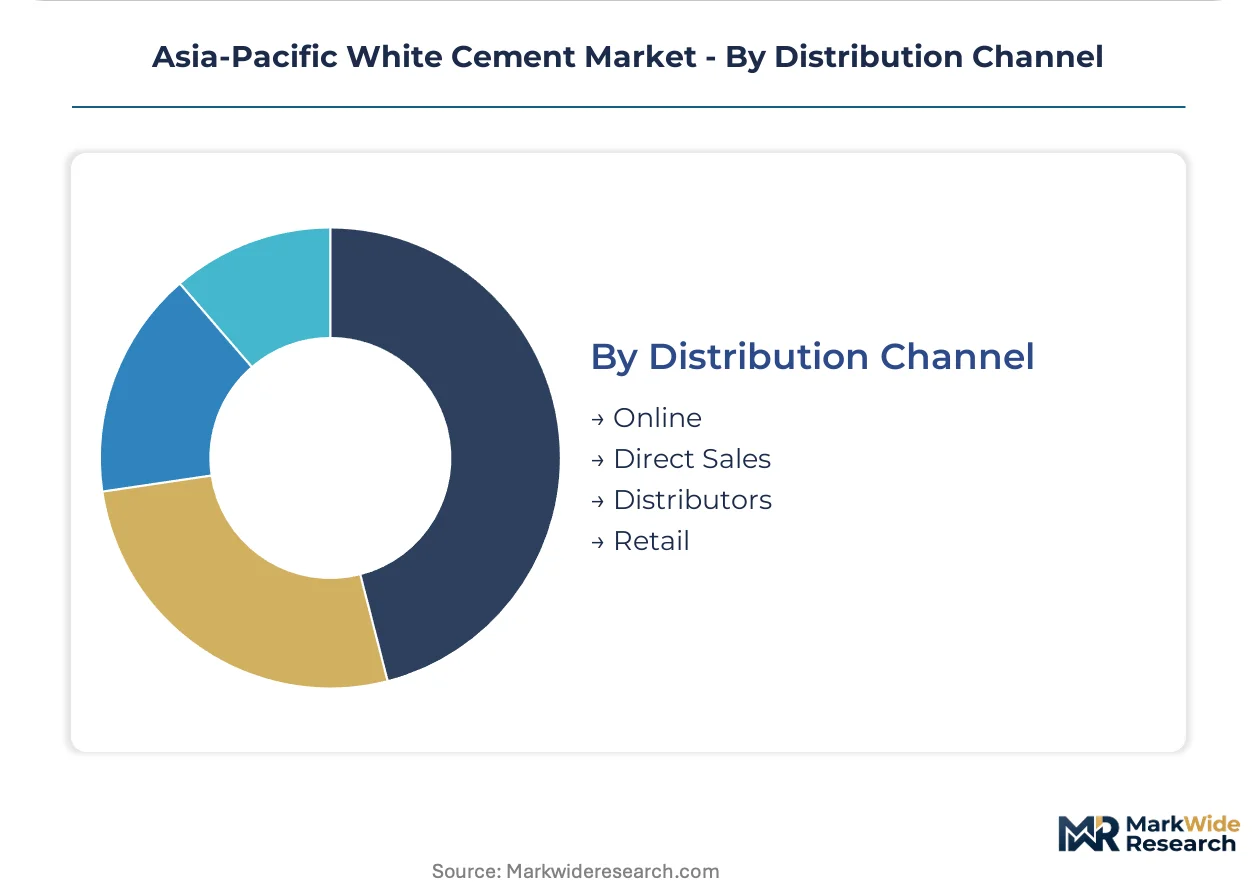
Channel selection tracks project scale and urgency, with bulk direct arrangements dominating infrastructure while retail serves repair and maintenance segments.
- Direct Sales:Integrated producers leverage captive grinding capacity to serve large developers and precast manufacturers with scheduled bulk delivery.
- Distributors:Regional stockists bridge supply gaps for mid-scale contractors across India's infrastructure corridors and Vietnam's northern provinces.
- Online:Digital procurement platforms are penetrating specification-grade materials with real-time brightness monitoring and logistics coordination.
- Retail:Hardware channels serve maintenance, repair, and small-scale decorative applications with bagged product formats.
Direct Sales captures the largest contract value while Online is expanding most quickly through digitized quality verification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thai producers export kaolin-clay-formulated white cement to Vietnam's northern infrastructure corridors, while Indian integrated mills supply western and southern state real estate clusters through captive Rajasthan limestone reserves.
India
Luxury residential towers in Mumbai and Bengaluru drive specification intensity for Portland White grades. BIS mandates minimum whiteness indices and compressive strength thresholds that filter substandard imports from neighboring supply bases. Rajasthan's captive limestone reserves feed integrated grinding capacity serving western and southern state infrastructure corridors.
Thailand
Bangkok monument restoration and retail facade programs pull volume for brightness-differentiated formulations. The Industrial Standards Institute imposes parallel constraints on heavy metal content and sulfate resistance that shape cross-border trade patterns. SCG International Corporation leverages domestic kaolin clay inputs to capture premium positioning in precast architectural applications.
Vietnam
Northern and central province mega-projects present underpenetrated demand for standardized decorative concrete specifications. Municipal beautification contracts require compliance with tightening embodied carbon disclosure requirements for state-funded infrastructure. Ho Chi Minh City commercial developers are adopting brightness-verified batch documentation for retail exterior programs.
Japan
JIS frameworks enforce stricter sulfate resistance and contamination thresholds that create compliance-based export openings for certified regional producers. METI guidelines on alternative fuel adoption constrain kiln fuel choices while preserving whiteness consistency requirements. The Kanto region concentrates technical expertise in controlled-atmosphere firing among established production bases.
China
GB standards for decorative cement products add a compliance layer for exporters targeting municipal beautification contracts. Dual carbon goals reshape clinker factor requirements and alternative fuel percentages in technical bids. Yangtze River Delta producers with biomass co-processing capabilities capture preferential supplier status in cross-border procurement frameworks.
Asia-Pacific White Cement Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered supply arrangements. The vendor base clusters around integrated producers with captive raw material reserves, regional grinding specialists, and import-dependent traders serving niche specification segments. Three archetypes dominate: backward-integrated limestone owners, kaolin-clay formulators, and multi-jurisdiction compliance specialists. Capacity expansion and strategic partnerships represent the dominant competitive moves as producers secure fuel-switching capabilities ahead of tightening embodied carbon regulations.
Among Indian integrated producers, J.K. Cement Ltd and UltraTech Cement Ltd exemplify the backward-integrated archetype through captive Rajasthan limestone positions. SCG International Corporation represents the kaolin-clay formulation specialist tier originating from Thai production bases. Cementir Holding NV and SUMITOMO OSAKA CEMENT Co., Ltd. occupy positions as multi-jurisdiction compliance specialists navigating simultaneous BIS, JIS, and GB standard requirements.
| Leading Market Players |
|---|
| J.K. Cement Ltd |
| Ambuja Cement (Adani Group) |
| Cementir Holding NV |
| SCG International Corporation |
| India Cements Ltd |
| UltraTech Cement Ltd |
| CIMSA |
| SUMITOMO OSAKA CEMENT Co., Ltd. |
| HOLCIM |
| Others |
Value Chain & Pricing Dynamics
Rajasthan's captive iron-free limestone reserves concentrate upstream supply power among integrated Indian producers, directing margin capture toward western and southern state real estate corridors where luxury residential developers consolidate procurement authority.
Pricing Analysis
Grade-generation pricing gaps separate high-purity Portland White from standard masonry formulations and premium Calcium Aluminate blends. Three-tier pricing structure across premium, standard, and economy levels tracks BIS certification tiers, volume scale, and brightness consistency verification. Cost compression in standard grades is intensifying because non-integrated producers face raw material volatility without captive reserves. Mid-scale contractors across India's infrastructure corridors exhibit highest price sensitivity, while monument restoration programs in Bangkok and Ho Chi Minh City accept premium positioning for verified batch documentation.
Supply Chain Analysis
Iron-free limestone feedstock draws from Rajasthan and Gujarat in India, with Thai kaolin clay deposits anchoring brightness-differentiated formulations. High-purity clay inputs, controlled-atmosphere kiln capacity, and cross-border grinding infrastructure form critical dependencies. Single-source vulnerability concentrates in specialized kiln engineering expertise among retiring technical cohorts. Distribution runs through integrated direct sales for large developers, regional distributors for mid-scale contractors, and emerging digital platforms with real-time quality verification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calcium Aluminate cements are reshaping competitive positioning as rapid-strength precast applications displace Portland White in premium niche segments, forcing incumbents to defend specification authority through certification depth and captive raw material control.
For Market Incumbents: Harden specification control through simultaneous BIS, JIS, and GB certification investment to extend dual-qualification timelines as a competitive moat. Deepen backward integration into Rajasthan limestone reserves to isolate input cost volatility from non-integrated competitors. Prioritize biomass co-processing capabilities ahead of tightening embodied carbon disclosure requirements for municipal beautification contracts.
For New Entrants and Emerging Players: Vietnam's northern and central province mega-projects represent the most penetrable entry point for standardized decorative concrete specifications with underpenetrated demand. Ho Chi Minh City commercial developers adopting brightness-verified batch documentation offer a compliance-based wedge. Target digitized supply chain integration with real-time quality monitoring to differentiate against established distributor networks.
For Investors and Strategic Acquirers: Capital is best deployed toward multi-jurisdiction compliance specialists navigating simultaneous BIS, JIS, and GB standard requirements with twelve-to-eighteen-month qualification cycles as barriers to replication. Long-term viability centers on fuel-switching capabilities ahead of tightening embodied carbon regulations across India, Thailand, and China. Monitor alternative fuel adoption rates in controlled-atmosphere kiln operations as the critical inflection signal for production cost trajectories. Cross-checking against IEA cement sector decarbonization benchmarks is advised before commitment-grade decisions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Limestone Reserves | Rajasthan-based reserves isolate J.K. Cement and UltraTech from iron-free limestone scarcity affecting non-integrated competitors. |
| Biomass Co-processing Capability Investment | Southeast Asian producers with alternative fuel adoption capture preferential supplier status in China's GB-compliant municipal procurement. |
| Multi-Jurisdiction Certification Depth | Simultaneous BIS, JIS, and GB compliance extends qualification timelines and filters substandard imports from neighboring supply bases. |
| Digitized Supply Chain Integration | Real-time brightness monitoring and logistics coordination reduce specification variance in cross-border bulk shipments to Vietnam corridors. |
| Kaolin Clay Formulation Specialization | Thai-sourced high-purity clay inputs enable SCG International to differentiate brightness performance in Bangkok monument restoration. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with kiln operations directors, procurement leads at luxury residential developers, BIS certification officers, and monument restoration contractors; and secondary validation through India BIS filings, Thailand Industrial Standards Institute documentation, China GB standard disclosures, Japan METI alternative fuel guidelines, and customs trade data. Bottom-up project pipeline enumeration across Mumbai, Bengaluru, Bangkok, Ho Chi Minh City, and Jakarta was triangulated against top-down capacity utilization estimates from integrated grinding facilities.
Forecast inputs considered product grade tier, end-use application intensity, regional regulatory cluster, and clinker factor trajectory across the analysis window. Segmentation dimensions modeled include Portland White versus Calcium Aluminate formulation splits, residential-commercial-infrastructure application mix, and direct-distributor-digital channel evolution. CAGRs were derived from elasticity-adjusted demand curves reflecting BIS certification mandate timing and embodied carbon disclosure phase-in schedules.
Practitioners should monitor kiln fuel switching feasibility under whiteness consistency constraints and Calcium Aluminate substitution rates in rapid-strength precast segments for early signals of forecast revision. Cross-checking against World Cement Association production cost surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Construction Materials Market
Building Materials
Concrete Blocks and Bricks Market
Building Materials
Concrete Admixtures Market
Building Materials
Roof Cover Boards Market
Building Materials
ASEAN Dry Mix Mortar Market
Building Materials
Plaster Accelerator Market
Building Materials
Cellular Concrete Market
Building Materials
Global Building Panels Market
Building Materials
Precast Concrete Retaining Walls Market
Building Materials
Europe Dry-Mix Mortar Market
Building Materials
Southeast Asia Concrete Admixtures Market
Building Materials
Mexico Architectural Coatings Market
Building Materials
Italy Architectural Coatings Market
Building Materials
Europe Acrylic Resin Dispersion Based Primers in Construction Market
Building Materials
Steel Sleepers Market
Building Materials
Polymer-Modified Cementitious Mortar Market