
 Steep Slope Roofing Materials Market | 2026-2036
Steep Slope Roofing Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Steep Slope Roofing Materials Market Outlook
Multi-source procurement among specialty contractors is expanding as builders seek supply resilience against raw material volatility. GAF leverages its integrated manufacturing network to sustain national distribution coverage. Owens Corning anchors its position through fiberglass mat technology leadership. CertainTeed differentiates via color and texture breadth across premium architectural shingle lines.
Steep slope roofing materials are engineered systems designed for roof pitches exceeding 25 percent, comprising overlapping units that shed water through gravity-driven drainage while providing structural protection and thermal insulation. Asphalt shingles dominate volume due to cost efficiency and installer familiarity, though metal roofing captures disproportionate margin pools from commercial and high-wind applications. Residential construction absorbs the majority of product flow, while institutional projects increasingly specify slate and copper for lifecycle durability.
FEMA building codes, ICC hurricane resistance standards, and EPA stormwater regulations collectively elevate product testing requirements and documentation burdens for manufacturers. The EPA's ENERGY STAR roof certification program shapes reflectivity specifications that directly influence material formulation decisions. Stakeholders must monitor code adoption timing across municipal jurisdictions and calibrate inventory to regional wind-speed design requirements.
Market Dynamics
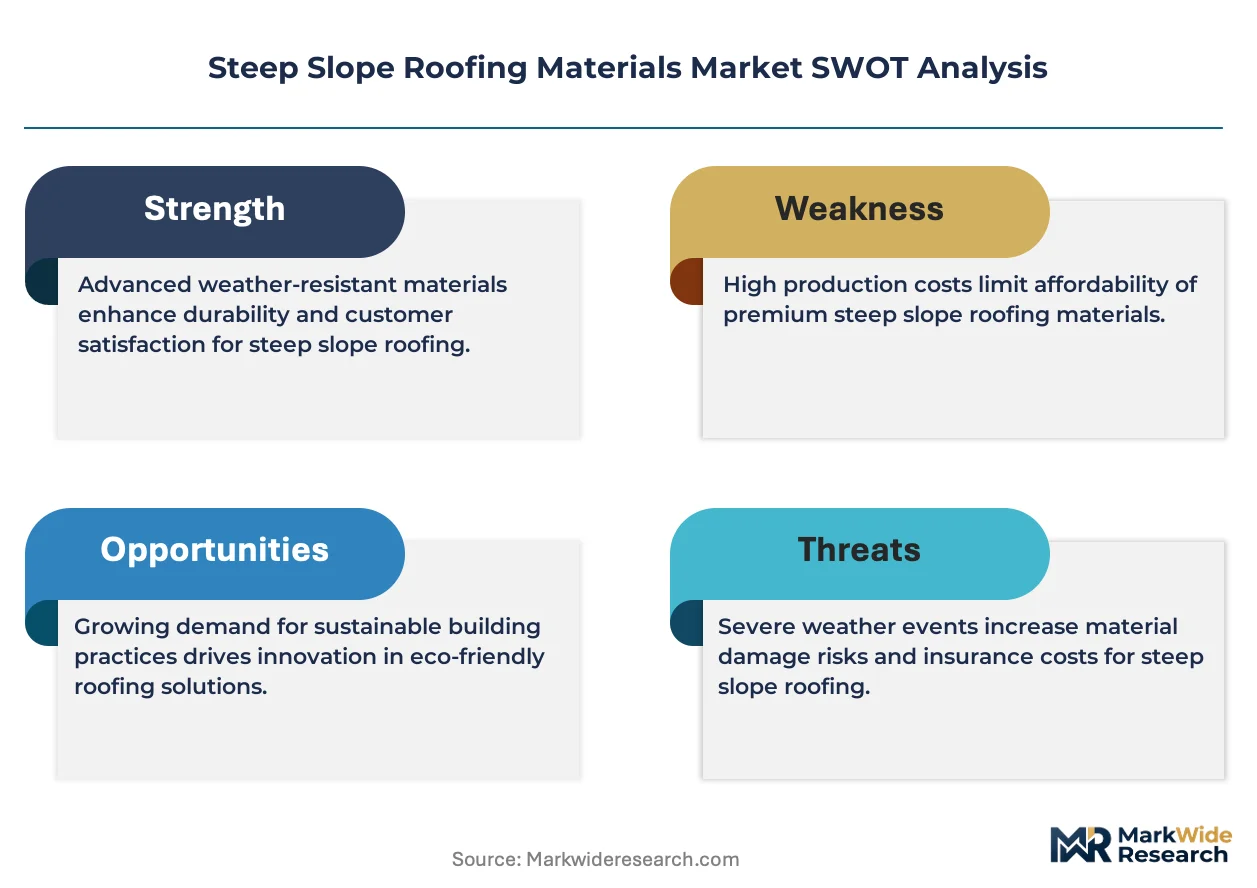
Residential housing developers across the United States are accelerating specification of impact-rated asphalt shingles as FEMA building codes and ICC hurricane resistance standards tighten product performance thresholds in high-wind regions.
Growth Catalysts
- EPA Stormwater Management Rules:The EPA's stormwater regulations elevate runoff control requirements, forcing builders toward permeable underlayment systems and advanced drainage configurations in new construction.
- Metal Roofing Technology:Standing seam metal systems capture disproportionate margin pools from commercial and high-wind applications as lifecycle cost advantages compound against asphalt in institutional projects.
- Southeastern United States Demand Concentration:Hurricane-resistant roofing codes in Florida, Georgia, and the Carolinas compress replacement cycles and sustain above-average reroofing velocity.
Market Restraints
- Bitumen and Fiberglass Mat Volatility:Crude oil price swings directly transmit to shingle manufacturing costs, compressing margins when asphalt feedstock spikes occur.
- Supply Concentration in Gulf Coast Petrochemical Corridor:Three integrated manufacturers control national distribution coverage, creating vulnerability to regional weather disruptions and logistics bottlenecks.
- Slate and Clay Tile Weight Limitations:Structural load requirements restrict specification in wood-framed residential construction, capping addressable market penetration.
Strategic Opportunities
- Cool Roof Mandates in California:Title 24 energy codes drive reflectivity specifications that favor granular-coated metal and specialized asphalt formulations with elevated solar reflectance index values.
- Solar-Integrated Roofing Convergence:Building-integrated photovoltaics embedded in standing seam metal panels create dual-function systems capturing roofing and energy generation budgets simultaneously.
- Direct-to-Contractor Digital Platforms:E-procurement channels bypass traditional distributor markups, enabling specialty contractors to source engineered systems with compressed lead times.
Industry Challenges
- Certified Installer Scarcity:Manufacturer-specific warranty programs require trained applicators, and the pipeline of qualified roofing mechanics constrains volume expansion in high-growth metropolitan areas.
- Multi-Jurisdictional Code Adoption Lag:Municipal building departments adopt ICC and FEMA standards on staggered timelines, fragmenting inventory requirements and complicating regional demand forecasting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steep Slope Roofing Materials Market |
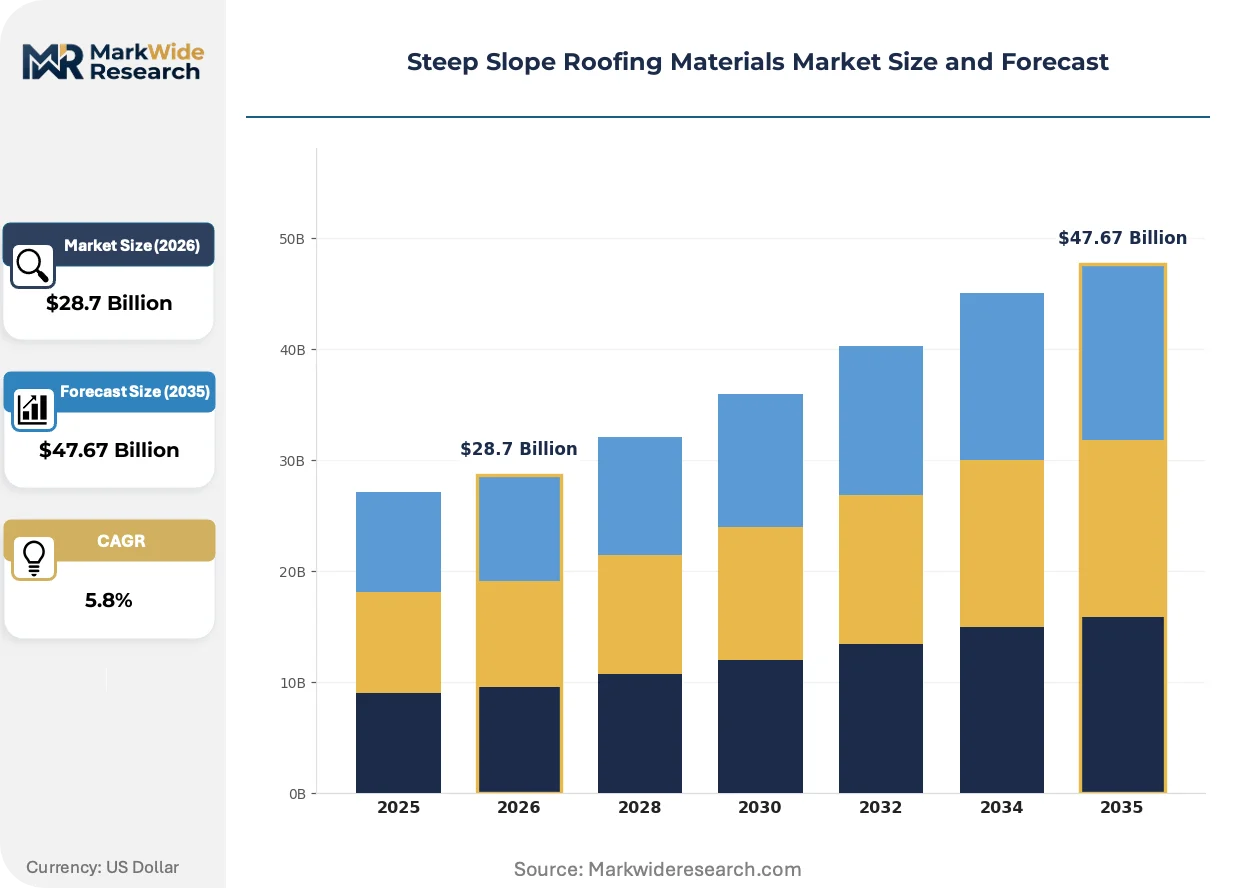
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $47.67 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Asphalt Shingles, Metal Roofing, Slate, Wood Shakes Application: Residential, Commercial, Institutional, Industrial Material: Fiberglass, Organic Felt, Steel, Copper Installation Method: Mechanically Fastened, Fully Adhered, Ballasted, Self-Adhered |
| Companies Covered | Atlas Roofing Corporation, Malarkey Roofing Products, GAF, Kingspan, SOPREMA, CertainTeed, TAMKO Building Products, Diversified Roofing Corp, Owens Corning, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steep Slope Roofing Materials Market Strategic Shifts
Synthetic underlayment materials and advanced granule adhesion chemistries are compressing traditional installation practices while ENERGY STAR certification requirements reshape material formulation priorities across residential and commercial segments.
Laminated architectural shingles with enhanced wind resistance ratings are overtaking three-tab strip shingles in new residential construction specifications. Homebuilders in high-velocity hurricane zones specify these systems to meet ICC 500 storm shelter standards and reduce callback exposure. The shift compresses volume share for entry-grade products while elevating average selling prices.
The EPA's ENERGY STAR roof certification program now mandates minimum solar reflectance thresholds that vary by climate zone. Manufacturers reformulate dark granule coatings with infrared-reflective pigments to maintain aesthetic range while achieving compliance. Cool roof specifications concentrate in California, Texas, and Florida where cooling-degree-day loads justify premium positioning.
Specialty contractors now consolidate material procurement through multi-source agreements rather than single-brand loyalty. Builders seek supply resilience against raw material volatility and regional production disruptions. This pattern concentrates in the southeastern United States where hurricane season compresses installation windows and inventory flexibility determines project completion rates.
Steep Slope Roofing Materials Market Segmentation
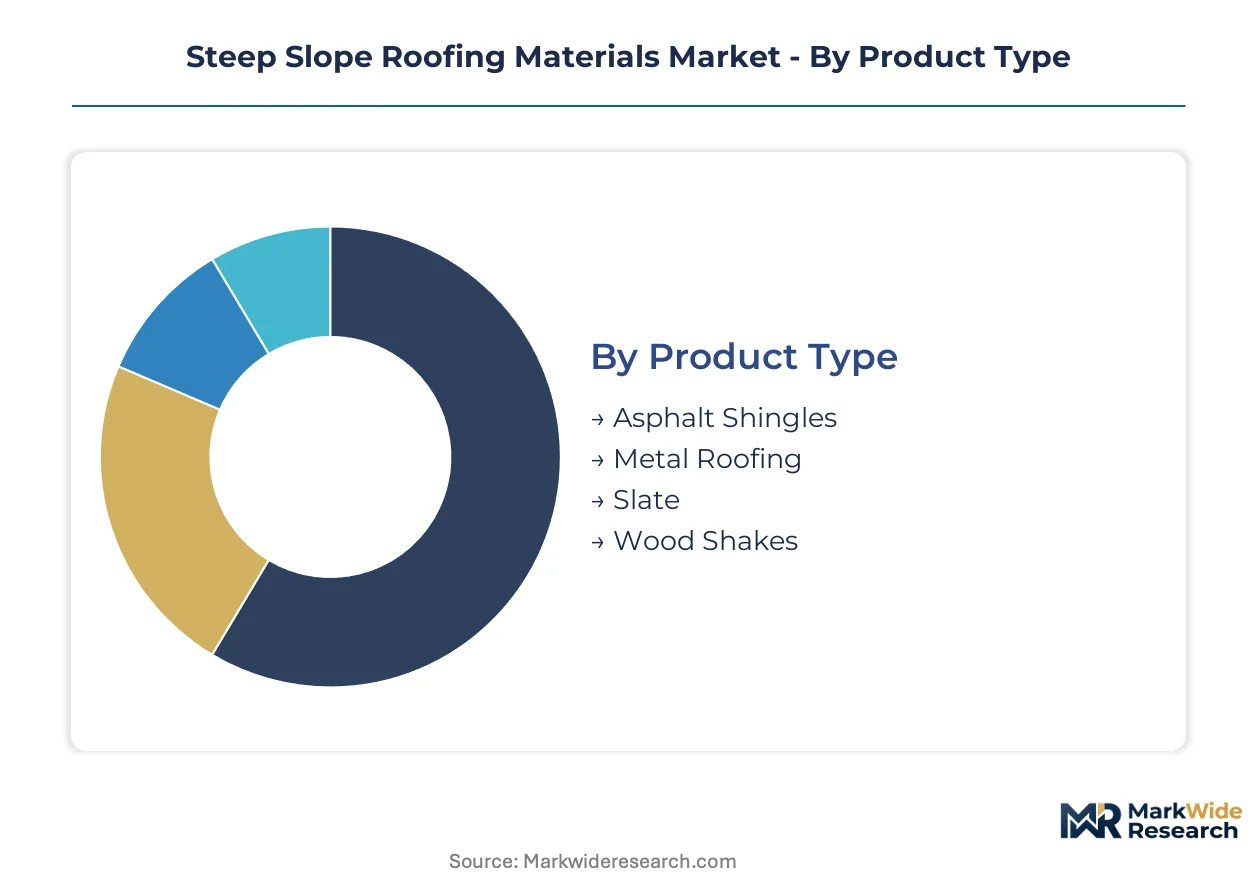
Steep slope roofing materials fragment across performance tiers, installation complexity, and lifecycle cost profiles. Specification decisions hinge on wind-speed ratings, thermal performance mandates, and structural load constraints rather than aesthetics alone.
Product Type:
Customization spans from commodity asphalt systems to bespoke copper assemblies, with standardization concentrated in impact-rated shingle platforms.
- Asphalt Shingles:Fiberglass-reinforced mats saturated with modified bitumen and surfaced with mineral granules provide cost-efficient weather protection. Demand concentrates in southeastern United States residential reroofing cycles driven by ICC hurricane resistance standards and compressed replacement intervals after storm events.
- Metal Roofing:Standing seam and modular panel systems in steel, aluminum, and copper deliver 40-70 year service lives with minimal maintenance. Commercial and institutional projects in high-wind coastal zones specify these systems for lifecycle cost advantages against asphalt alternatives.
- Slate:Natural stone quarried in Vermont and Pennsylvania offers century-scale durability with structural weight requirements limiting wood-framed residential applications.
- Wood Shakes:Cedar and redwood shingles treated with fire-retardant preservatives serve heritage restoration and premium aesthetic specifications in California and Pacific Northwest markets.
Most installed capacity flows through Asphalt Shingles. Expansion is steepest in Metal Roofing.
Application:
Volume gravitates toward single-family construction while margin pools concentrate in institutional projects demanding extended warranties and certified installer networks.
- Residential:Single-family and multifamily housing absorbs the majority of asphalt shingle volume, with laminated architectural products displacing three-tab strip shingles in new construction specifications.
- Commercial:Retail, office, and hospitality properties specify metal standing seam systems for energy reflectivity and reduced maintenance disruption to tenant operations.
- Institutional:Schools, hospitals, and government facilities prioritize slate and copper for lifecycle durability despite premium first costs, with FEMA building codes driving storm-resistant specifications.
- Industrial:Manufacturing and warehouse facilities deploy mechanically fastened metal panels for rapid installation and resistance to chemical exposure.
Residential channels dominate unit volume. Institutional projects yield the highest per-square margins.
Material:
Supply concentration in Gulf Coast petrochemical corridors shapes cost structures for organic-based systems versus distributed metal sourcing.
- Fiberglass:Non-woven glass mat substrates provide dimensional stability and fire resistance as the dominant reinforcement for asphalt shingles, with Owens Corning and Johns Manville controlling North American mat supply.
- Organic Felt:Cellulose fiber mats saturated with asphalt serve heritage replacement markets and specialized low-slope transition applications where flexibility trumps fire rating.
- Steel:Galvalume-coated cold-rolled steel dominates metal roofing volume through coil coating lines in Indiana and Ohio, with pricing indexed to scrap and hot-rolled coil futures.
- Copper:Architectural sheet and standing seam systems from domestic mills and European imports serve historic preservation and premium residential segments with supply constrained by mining output and tariff exposure.
Fiberglass substrates anchor mass-market production. Copper commands the widest price spreads and longest lead times.
Installation Method:
Mechanical fastening dominates steep slope applications while adhesive systems expand in low-slope transitions and high-wind zones requiring enhanced uplift resistance.
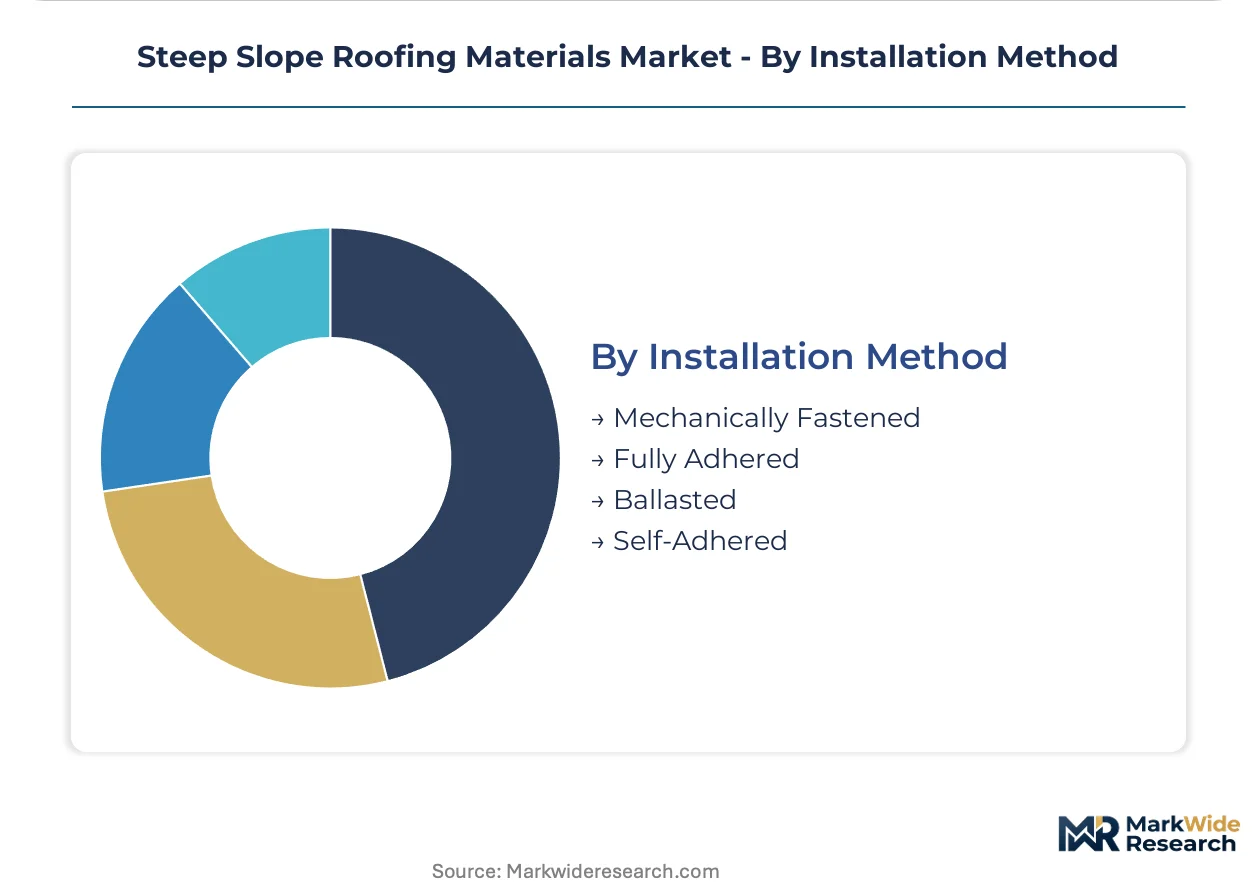
- Mechanically Fastened:Nails, screws, and concealed clips secure shingles and metal panels through substrate penetration, with Florida and coastal Carolina codes mandating enhanced fastener patterns and ring-shank nail specifications.
- Fully Adhered:Cold-applied or heat-welded membranes bond to substrate for seamless waterproofing in low-slope to steep-slope transitions on commercial buildings.
- Ballasted:Loose-laid membrane systems secured by paver or stone ballast serve limited steep slope applications where structural load capacity permits and membrane protection is prioritized.
- Self-Adhered:Pressure-sensitive adhesive backing on underlayment and ice-and-water barrier membranes accelerates installation in temperature-variable conditions without torch or solvent activation.
Mechanically Fastened methods handle the majority of steep slope volume. Self-Adhered systems are gaining share fastest in residential underlayment replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The southeastern United States concentrates steep slope roofing demand through hurricane-resistant code adoption and compressed replacement cycles following storm damage.
United States
Residential developers in Florida, Georgia, and the Carolinas specify impact-rated asphalt shingles to meet ICC 500 storm shelter standards and FEMA building codes. The EPA's ENERGY STAR roof certification program mandates climate-zone-specific solar reflectance thresholds that reshape material formulations. Dallas-Fort Worth and Houston metro areas drive metal roofing adoption for commercial projects seeking lifecycle cost advantages against traditional systems.
Canada
Wood shake demand persists in British Columbia and Pacific Northwest heritage restoration markets despite fire-retardant treatment requirements. Health Canada's PMRA regulates preservative chemistries for cedar and redwood applications. Toronto and Vancouver construction markets increasingly specify synthetic underlayment systems for moisture management in variable temperature conditions.
Germany
Natural slate quarried in North Rhine-Westphalia serves century-scale durability specifications for institutional and premium residential projects. The EU Green Deal and national building energy codes elevate thermal performance requirements for roofing assemblies. Munich and Stuttgart metropolitan areas concentrate specification activity for copper standing seam systems in historic preservation and commercial construction.
China
Urban renewal programs in Yangtze River Delta and Pearl River Delta cities accelerate reroofing velocity for aging residential stock. MIIT building material standards and GB codes govern fire resistance and structural load specifications. Shanghai and Shenzhen construction markets show rising specification of metal roofing for commercial and industrial facilities seeking rapid installation timelines.
Australia
Metal roofing dominates new residential construction in Queensland and New South Wales due to bushfire resistance ratings and thermal performance advantages. The country's national building regulator enforces wind uplift standards that vary by cyclonic and non-cyclonic regions. Sydney and Melbourne metropolitan areas concentrate demand for color-coated steel systems with elevated solar reflectance index values.
Steep Slope Roofing Materials Market Competitive Environment
Global majors compete with regional champions across manufacturing scale and distribution coverage in a market structured around three integrated manufacturers controlling national supply networks. Specialty contractors consolidate procurement through multi-source agreements rather than single-brand loyalty, fragmenting volume concentration despite manufacturing consolidation. Three archetypes dominate: integrated petrochemical-to-shingle manufacturers, metal coil coating specialists with standing seam fabrication capability, and regional slate quarries with heritage restoration expertise. Competitive moves center on backward integration into fiberglass mat supply and geographic expansion of certified installer networks.
Within the integrated manufacturing tier, GAF, Owens Corning, and CertainTeed exemplify scale-driven positions anchored in Gulf Coast petrochemical corridor production. GAF occupies a position representing captive distribution coverage across North American markets. Owens Corning exemplifies technology leadership through fiberglass mat substrate control. CertainTeed sits within the premium architectural segment through color and texture breadth. Atlas Roofing Corporation and Malarkey Roofing Products represent regional champions competing on installer relationships and specialized high-wind product formulations. TAMKO Building Products anchors a position in mid-market residential specification through regional manufacturing presence.
| Leading Market Players |
|---|
| Atlas Roofing Corporation |
| Malarkey Roofing Products |
| GAF |
| Kingspan |
| SOPREMA |
| CertainTeed |
| TAMKO Building Products |
| Diversified Roofing Corp |
| Owens Corning |
| Others |
Value Chain & Pricing Dynamics
ENERGY STAR roof certification thresholds gate qualified supply and premium-tier pricing access, as manufacturers reformulating granule coatings with infrared-reflective pigments absorb elevated raw material costs that transmit through to certified product lines. This regulatory filter concentrates margin capture among integrated producers capable of captive formulation, while uncertified competitors face pricing compression in standard-grade segments.
Pricing Analysis
Crude oil price volatility transmits directly through asphalt feedstock costs, forcing contract-based long-term offtake structures for volume buyers. Pricing stratifies across impact-rated architectural, standard laminate, and three-tab economy tiers, with wind-speed certification and ENERGY STAR compliance as primary differentiation drivers. Cost compression in entry-grade shingles is intensifying because Gulf Coast petrochemical supply concentration limits alternative sourcing. Residential reroofing contractors exhibit highest price sensitivity, while institutional project owners prioritize lifecycle durability over first cost.
Supply Chain Analysis
Storm-damaged shingle returns and regional inventory redistribution flows reveal reverse-logistics infrastructure gaps that lengthen replacement cycle completion. Production concentrates in United States Gulf Coast, Canada, and Mexico, drawing from bitumen, fiberglass mat, and mineral granule inputs. Single-source vulnerability in fiberglass mat supply—controlled by Owens Corning and Johns Manville—creates bottleneck risk during demand spikes. Distribution runs through national distributor networks with direct-to-contractor digital platforms gaining share fastest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: hurricane-resistant code adoption in Florida compresses replacement cycles and sustains premium pricing, while California cool-roof mandates create parallel certification requirements that elevate qualified-supply scarcity.
For Market Incumbents: Acquire certified installer network capacity to defend warranty-program exclusivity against emerging metal roofing convergence threats. Backward integration into granule coating formulation secures ENERGY STAR compliance cost advantages. Regional manufacturing footprint expansion in Carolinas and Texas reduces logistics exposure to Gulf Coast weather disruptions. For New Entrants and Emerging Players: Direct-to-contractor digital procurement channels bypass incumbent distributor markups and compress customer acquisition costs in fragmented southeastern specialty contractor markets. Target synthetic underlayment segments where brand loyalty remains undeveloped and specification decisions hinge on installer convenience rather than manufacturer heritage. For Investors and Strategic Acquirers: Roll-up economics work for regional metal roofing fabricators because standing seam installation certification scarcity creates local market moats. Five-to-ten year viability hinges on solar-integrated roofing convergence capturing dual budget streams. Monitor ICC code adoption timing across municipal jurisdictions as inflection indicator for inventory positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiberglass Mat Supply | Owens Corning and Johns Manville mat control creates captive supply advantages for integrated shingle manufacturers. |
| Solar-Integrated Roofing Product Development | Building-integrated photovoltaics in standing seam panels capture combined roofing and energy generation capital budgets. |
| Certified Installer Network Expansion | Manufacturer warranty programs require trained applicators, constraining volume growth in high-velocity metropolitan markets. |
| Synthetic Underlayment Formulation Investment | Self-adhered membrane systems accelerate installation in temperature-variable conditions without torch activation. |
| Direct-to-Contractor Digital Platform Launch | E-procurement channels bypass traditional distributor markups and compress lead times for specialty contractors. |
Study Parameters
Multiple input streams — specialty contractor interviews, distributor procurement data, municipal building permit records, and manufacturer production disclosures — were reconciled to construct demand estimates. Primary fieldwork engaged roofing contractor operations managers, regional distribution branch managers, building code officials in hurricane-prone jurisdictions, and institutional facilities procurement directors. Secondary validation drew from EPA ENERGY STAR certification databases, ICC code adoption tracking, FEMA building guideline publications, and state-level construction permit aggregations. Bottom-up square-footage estimates triangulated against top-down manufacturer shipment data.
Data-stream reconciliation anchored volume projections across the analysis window, with segmentation modeling across product type, application, material substrate, and installation method dimensions. CAGRs derived from historical replacement cycle velocity, code-driven specification shifts, and regional construction permit trajectories. Forecast inputs incorporated hurricane frequency assumptions, crude oil price trajectory sensitivity, and ENERGY STAR adoption rate thresholds by climate zone.
The model assumes a particular technology adoption path; alternative pathways for solar-integrated metal roofing would alter the outlook if building-integrated photovoltaics cost curves steepen faster than projected. Forecasts reflect material formulation cost assumptions and certified installer pipeline constraints. Practitioners should monitor ICC code adoption timing, ENERGY STAR threshold revisions, and Gulf Coast petrochemical corridor disruption events for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Tar Paper Market
Building & Construction Materials
SBS Waterproofing Membrane Market
Building & Construction Materials
Air Barrier Market
Building & Construction Materials
Fiberglass Doors Market
Building & Construction Materials
Saudi Arabia Sanitaryware Market
Building & Construction Materials
United Kingdom Prefab Wood Buildings Market
Building & Construction Materials
Europe I-Joist Market
Building & Construction Materials
Japan Concrete Conditioner Market
Building & Construction Materials
Pipe Hanger Market
Building & Construction Materials
North America Residential Water Heater Market
Building & Construction Materials
Clay Roof Tiles Market
Building & Construction Materials
Architectural Window Films Market
Building & Construction Materials
Europe Faucet Market
Building & Construction Materials
Global Floor and Wall Glazed Tiles Market
Building & Construction Materials
Global Hydraulic Door Closer Market
Building & Construction Materials
Middle-East and Africa Construction Adhesives Market