
 Choke and Kill Manifold Market | 2026-2036
Choke and Kill Manifold Market Size, Share, and Industry Trends Forecast 2026-2036
Choke and Kill Manifold Market Analysis
Digital wellbore monitoring and real-time pressure telemetry is reshaping choke and kill manifold architecture, forcing redesigns of legacy hydraulic control systems. Baker Hughes leverages integrated sensor networks to sustain technology leadership in intelligent pressure management. Schlumberger anchors its position through deep vertical integration into forged component supply chains. National Oilwell Varco dominates subsea manifold fabrication with proprietary alloy welding protocols that extend equipment fatigue life.
A choke and kill manifold is a high-pressure flow-control assembly installed on drilling rigs and wellheads to regulate fluid discharge and manage kicks during drilling and completion operations. These systems typically handle rated working pressures from 5,000 to 20,000 psi, incorporating multiple choke valves, kill lines, and pressure sensors to enable controlled circulation of drilling mud or formation fluids. Valves and flanges represent the most technically demanding product categories, where margin pools concentrate in API 16C-certified forged alloy components that withstand sour gas corrosion. Offshore operations command premium positioning due to subsea installation complexity and longer replacement cycles, while modular installation formats are gaining traction among drilling contractors seeking rapid rig-up flexibility across pad drilling programs.
API standards, the US Bureau of Safety and Environmental Enforcement, and Norway's Petroleum Safety Authority shape product certification, well control mandates, and offshore equipment qualification pathways that determine market access for manufacturers. Compliance with API 16C and NORSOK U-001 forces continuous metallurgical upgrades and third-party validation investments that filter out lower-tier suppliers. Stakeholders must monitor how evolving well depth ratings and sour service specifications in frontier basins will recalibrate procurement criteria and qualification timelines.
Market Dynamics
Deepwater drilling contractors in the Gulf of Mexico and offshore Brazil are expanding procurement of high-pressure rated systems, forcing manufacturers to redesign legacy hydraulic architectures around real-time telemetry integration and API 16C certification requirements.
Growth Catalysts
- API 16C Certification Mandates:Tightened well control standards in US federal waters and Norwegian North Sea fields are filtering out uncertified suppliers and concentrating demand among qualified forged alloy component producers.
- Sour Gas Corrosion Resistance:Advances in forged alloy metallurgy enable extended fatigue life in hydrogen sulfide environments, opening procurement from Middle Eastern offshore operators managing high-complexity wells.
- Pad Drilling Modularity:US shale basin contractors are specifying rapid rig-up manifold formats to minimize non-productive time across multi-well pad programs in the Permian and Eagle Ford.
Market Restraints
- Specialized Forging Capacity Concentration:Limited qualified suppliers of API 16C-certified large-bore flanges in North America and Europe create bottlenecks during demand surges.
- Alloy Input Cost Volatility:Nickel and chromium price swings directly compress margin pools on high-pressure rated systems where material costs dominate bill-of-materials.
- Extended Qualification Timelines:Third-party validation requirements under NORSOK U-001 and BSEE well control mandates stretch new product introduction cycles to 18-24 months.
Strategic Opportunities
- Subsea Installation Complexity Premium:Brazil's pre-salt fields and West African deepwater blocks reward suppliers with proprietary alloy welding protocols that extend equipment replacement cycles.
- Integrated Sensor Network Convergence:Combining pressure telemetry with predictive maintenance algorithms creates differentiated positioning for intelligent choke manifold offerings.
- US Inflation Reduction Act Domestic Content:Enhanced procurement preferences for domestically manufactured well control equipment strengthen positioning of US-based forging and fabrication facilities.
Industry Challenges
- Weld Inspector Certification Scarcity:Qualified ASME Section IX welders and ultrasonic testing technicians command premium wages, constraining throughput at fabrication facilities.
- Legacy Hydraulic Control Integration:Retrofitting digital monitoring architectures onto existing rig fleets without disrupting drilling schedules requires specialized field engineering capabilities.
- Dual Certification Pathway Complexity:Simultaneous pursuit of API 16C and NORSOK U-001 approvals demands parallel documentation and testing investments that strain mid-tier engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Choke and Kill Manifold Market |
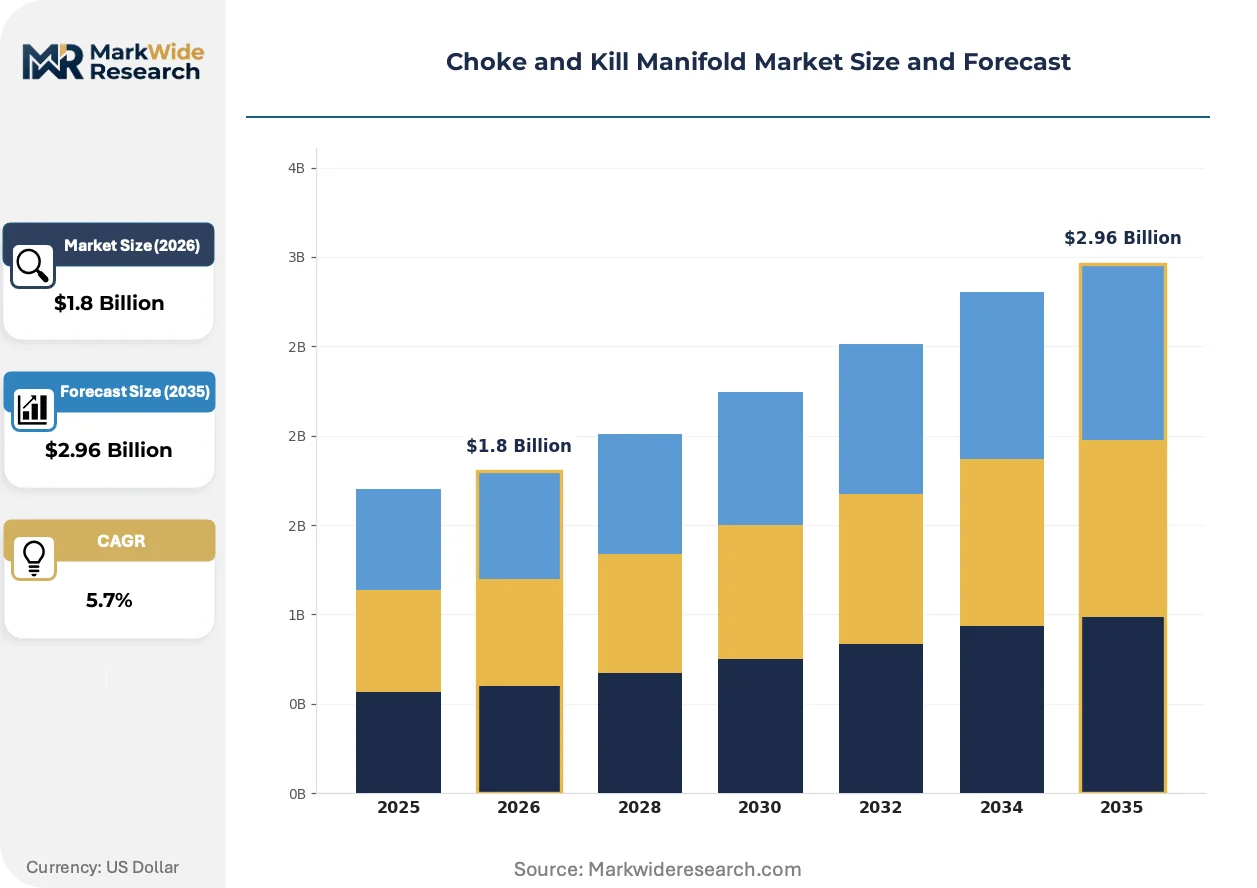
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Valves, Fittings, Flanges, Hoses Application: Onshore Operations, Offshore Operations, Emergency Shutdown, Pressure Control End User: Oil & Gas Operators, Drilling Contractors, Service Providers, Equipment Manufacturers Installation Type: Fixed, Portable, Modular, Custom Built |
| Companies Covered | Baker Hughes, Worldwide Oilfield Machine, Schlumberger, AXON Pressure Products, Jereh Group, National Oilwell Varco, Halliburton, Probe Oil Tools, TechnipFMC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Choke and Kill Manifold Market Emerging Trajectories
Digital wellbore monitoring architectures are compressing traditional equipment replacement cycles while regulatory mandates in multiple jurisdictions accelerate metallurgical upgrade requirements across the supplier base.
Real-time pressure telemetry systems are digitizing choke manifold control architectures by embedding distributed sensor networks directly into forged valve bodies. Deepwater drilling contractors in Brazil and the Gulf of Mexico are specifying these configurations on newbuild rigs to enable predictive maintenance and reduce unplanned downtime. The technology is digitizing legacy hydraulic control hierarchies, forcing established suppliers to re-engineer product lines around data-centric operating models.
Norway's Petroleum Safety Authority has tightened subsea equipment qualification pathways under updated NORSOK U-001 interpretations, requiring enhanced documentation of fatigue performance in sour service conditions. This regulatory shift is compressing the qualified supplier base as validation costs filter out smaller forging operations. Offshore manifold fabricators serving North Sea fields are responding by deepening captive control over heat treatment and non-destructive testing processes.
Drilling contractors are unbundling after-sales service contracts from initial equipment procurement, creating discrete revenue pools for predictive maintenance and spare parts logistics. This purchasing pattern shift is disrupting traditional bundled pricing models and compressing margin capture on initial hardware sales. The behavior is most visible among US shale operators running large pad drilling fleets where equipment utilization tracking enables outcome-based service fee structures.
Choke and Kill Manifold Market Segmentation
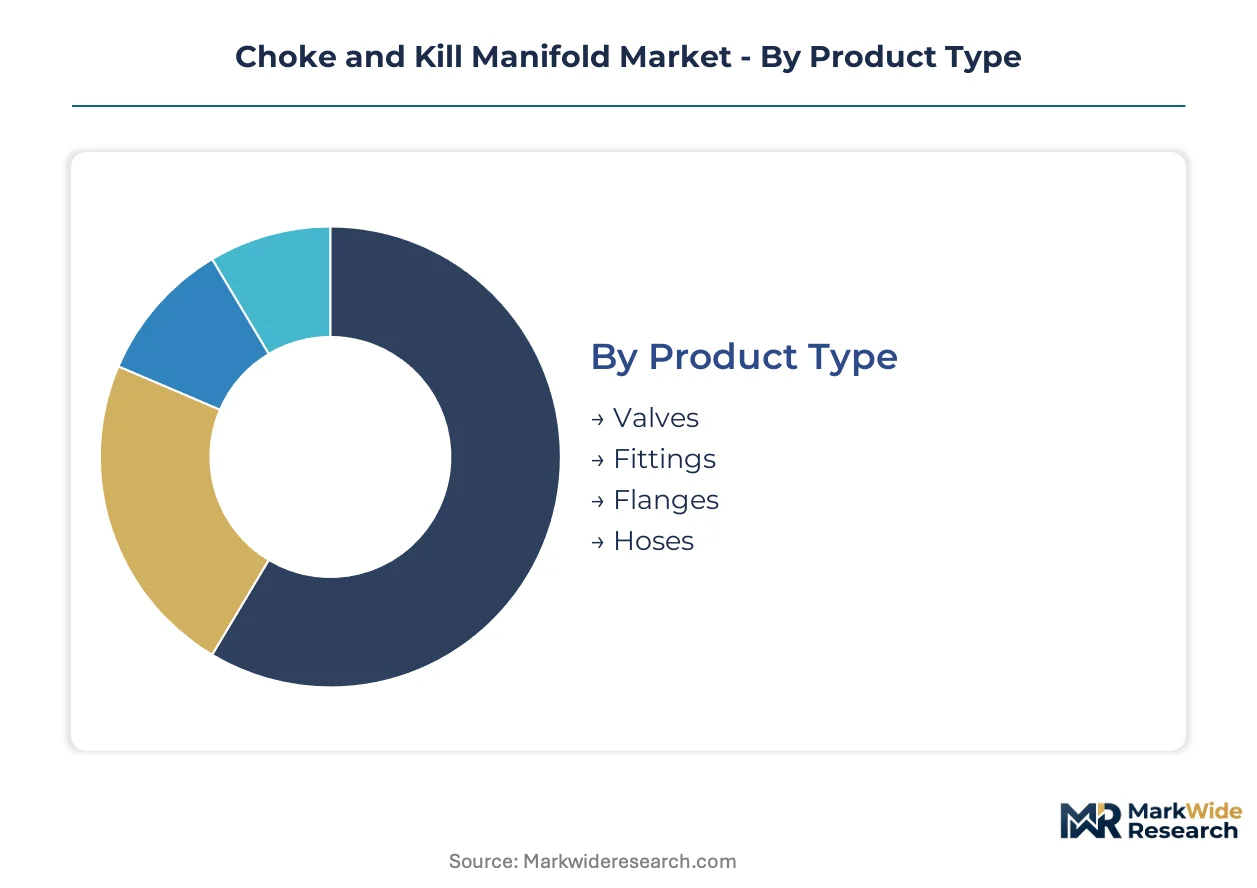
Choke and kill manifold procurement patterns fragment sharply across product categories and operational contexts. After-sales service intensity varies dramatically by segment, with subsea installations commanding multi-year maintenance contracts while onshore modular formats shift toward outcome-based fee structures.
Product Type:
After-sales service intensity concentrates in valve and flange categories where API 16C recertification cycles create recurring revenue pools for qualified suppliers.
- Valves:Forged alloy choke valves rated to 20,000 psi working pressure dominate material cost structures. Deepwater drilling contractors in the Gulf of Mexico specify these for pre-salt and high-pressure formations where sour gas corrosion accelerates replacement cycles.
- Flanges:Large-bore API 16C-certified forged flanges represent the most supply-constrained component category. Limited qualified forging capacity in North America and Europe creates procurement bottlenecks during demand surges in US shale basins.
- Fittings:Standardized connection hardware bridges manifold assemblies.
- Hoses:High-pressure flexible lines enable rapid rig-up configurations.
By volume, valves lead. By growth pace, flanges are ahead.
Application:
Cost tier differentiation separates offshore emergency shutdown systems from routine onshore pressure control configurations.
- Offshore Operations:Subsea manifold installations demand proprietary alloy welding protocols and extended fatigue life specifications. Brazil's pre-salt fields and West African deepwater blocks reward suppliers with NORSOK U-001 dual certification capabilities.
- Pressure Control:Real-time telemetry integration is digitizing legacy hydraulic architectures. Integrated sensor networks embedded directly into forged valve bodies enable predictive maintenance algorithms that reduce unplanned downtime.
- Onshore Operations:Pad drilling programs in Permian and Eagle Ford basins specify rapid rig-up formats.
- Emergency Shutdown:Regulatory mandates from the US Bureau of Safety and Environmental Enforcement drive specification upgrades.
Offshore operations capture premium pricing tiers. Pressure control applications are expanding most quickly.
End User:
Customer type determines procurement authority and contract structure across the value chain.
- Drilling Contractors:Fleet operators unbundle after-sales service from initial equipment procurement, creating discrete revenue pools for predictive maintenance. US shale operators running large pad drilling fleets enable outcome-based service fee structures through equipment utilization tracking.
- Oil & Gas Operators:Supermajors and national oil companies set metallurgical specifications for frontier basins.
- Service Providers:Rental and maintenance firms intermediate between fabricators and end-users.
- Equipment Manufacturers:System integrators source certified components for bundled well control packages.
Drilling contractors drive volume procurement. Oil & gas operators set technical standards.
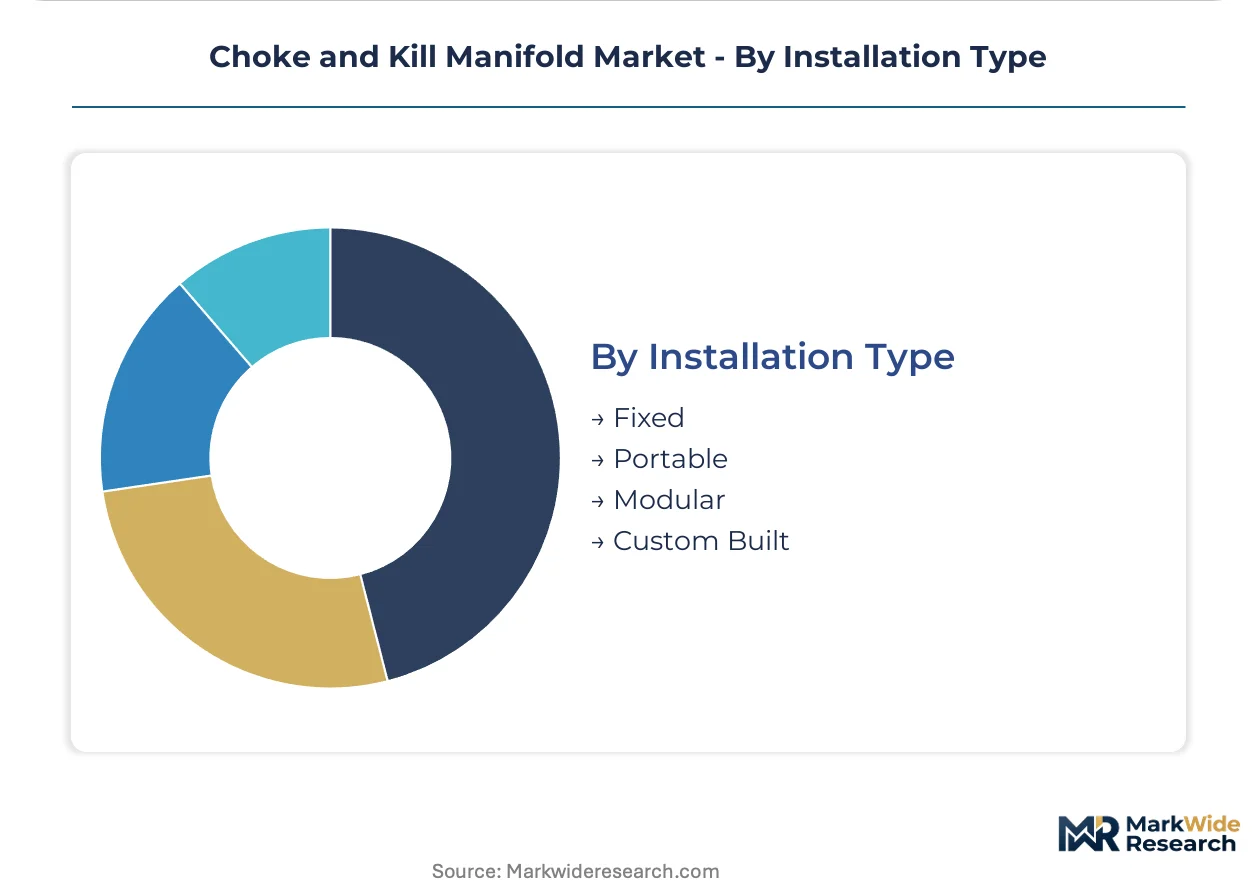
Installation Type:
Volume scale separates standardized modular formats from engineered custom builds.
- Modular:Rapid rig-up configurations minimize non-productive time across multi-well pad programs. US shale basin contractors specify these formats to accelerate deployment cycles between well sites.
- Custom Built:Engineered-to-order systems address extreme pressure ratings and sour service conditions. Deepwater projects in the Gulf of Mexico and offshore Brazil require project-specific metallurgical validation and extended qualification timelines.
- Fixed:Permanent installations on production platforms.
- Portable:Skid-mounted units for workover and intervention operations.
Modular formats lead by unit volume. Custom built configurations command highest per-unit value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deepwater drilling contractors and shale basin operators concentrate procurement authority across five national markets where high-pressure rated systems face divergent regulatory and geological requirements.
United States
The Gulf of Mexico pre-salt formations and Permian Basin pad drilling programs drive specification of 20,000 psi rated systems. The US Bureau of Safety and Environmental Enforcement mandates API 16C certification for federal offshore leases. Houston anchors domestic fabrication capacity where contractors source rapid rig-up modular formats.
Brazil
Pre-salt deepwater fields in the Santos Basin require proprietary alloy welding protocols for extended fatigue life. The national petroleum regulator ANP enforces stringent well control equipment qualification timelines. Macaé and Rio de Janeiro host subsea manifold fabrication clusters serving Petrobras-led development programs.
Norway
North Sea high-pressure sour service conditions accelerate replacement cycles for forged alloy components. The Petroleum Safety Authority's updated NORSOK U-001 interpretations compress the qualified supplier base through enhanced fatigue documentation requirements. Stavanger concentrates engineering validation and heat treatment capabilities.
China
South China Sea deepwater exploration and domestic shale development expand demand for intelligent pressure management systems. The Ministry of Emergency Management and national GB standards shape well control equipment certification pathways. Shanghai and Tianjin house forging operations supplying both domestic contractors and export markets.
Saudi Arabia
Offshore Arabian Gulf fields with hydrogen sulfide exposure prioritize sour gas corrosion resistance in procurement criteria. The national regulator SFDA oversees equipment qualification alongside Saudi Aramco technical specifications. Dhahran and Jubail Industrial City anchor high-pressure component fabrication serving frontier basin development.
Choke and Kill Manifold Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where API 16C certification filters out lower-tier suppliers. The qualified vendor base concentrates among forged alloy component producers with captive heat treatment and non-destructive testing capabilities. Three archetypes dominate: integrated oilfield service conglomerates with backward control over metallurgical supply chains; specialized manifold fabricators with proprietary welding protocols; and regional forging operations serving domestic shale basins. Competitive moves center on capacity expansion in large-bore flange categories and strategic partnerships for digital telemetry integration.
Among US-based oilfield service providers, Baker Hughes, Schlumberger, and National Oilwell Varco occupy positions across the premium-tier vector. Baker Hughes exemplifies the integrated sensor network archetype through its positioning in intelligent pressure management. Schlumberger represents deep backward integration into forged component supply chains. National Oilwell Varco anchors subsea manifold fabrication capabilities with extended equipment fatigue life specifications. These three entities collectively illustrate how certification depth and metallurgical control separate tier-one positioning from mid-tier competition.
| Leading Market Players |
|---|
| Baker Hughes |
| Worldwide Oilfield Machine |
| Schlumberger |
| AXON Pressure Products |
| Jereh Group |
| National Oilwell Varco |
| Halliburton |
| Probe Oil Tools |
| TechnipFMC |
| Others |
Supply Flow & Price Mechanics
Undercapacity in North American large-bore flange forging compresses supplier negotiation leverage while amplifying cost-pass-through power for qualified API 16C-certified producers serving Gulf of Mexico deepwater contractors.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange nickel and chromium benchmarks dominate high-pressure system procurement. Three-tier pricing structure across API 16C-certified premium, standard-grade, and non-certified economy levels separates offshore operators from shale basin contractors. Cost compression in standard-grade tiers is intensifying because drilling contractors unbundle after-sales service from initial hardware sales. US shale operators running pad drilling fleets exhibit highest price sensitivity; Brazilian pre-salt contractors show lowest sensitivity due to extended qualification timelines.
Supply Chain Analysis
Contract manufacturing concentrates among Houston-based forging operations, Stavanger heat treatment specialists, and Shanghai fabrication clusters serving domestic and export markets. The supply chain draws from nickel-chromium-molybdenum alloy feedstock, large-bore forging presses, and ASME-certified welding capacity. Single-source vulnerability in qualified ultrasonic testing technician pools constrains throughput during demand surges. Distribution runs through equipment manufacturers bundling well control packages and direct procurement by drilling contractors specifying modular formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Intelligent pressure management platforms are redefining competitive boundaries as sensor-telemetry interoperability forces ecosystem choices among drilling contractors and equipment suppliers.
For Market Incumbents: Pre-empt digital-native entrants by embedding predictive maintenance algorithms into forged valve bodies before telemetry standards consolidate. Deepen backward integration into heat treatment capabilities to defend margin position against nickel price volatility. Capture API 16C-NORSOK dual certification capacity before Norwegian Petroleum Safety Authority interpretations tighten further.
For New Entrants and Emerging Players: Build out rapid rig-up modular formats for Permian Basin pad drilling programs where incumbent service bundling creates white-space. Target outcome-based service fee structures enabled by equipment utilization tracking. Partner with established forging operations to bypass 18-24 month qualification timelines.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across subsea manifold fabrication as proprietary alloy welding protocols become mandatory for Brazil pre-salt and West African deepwater awards. Five-to-ten year viability favors suppliers with captive non-destructive testing capabilities. Monitor Petrobras procurement specification shifts as inflection indicator for premium-tier demand.
| Strategic Initiative | Industry Significance |
|---|---|
| API 16C Certification Investment | Filters out uncertified competitors in US federal waters and Norwegian North Sea fields. |
| Integrated Sensor Network Deployment | Enables predictive maintenance algorithms that reduce unplanned downtime for deepwater contractors. |
| Large-Bore Flange Capacity Expansion | Alleviates procurement bottlenecks during demand surges in US shale basins. |
| Dual Certification Pathway Pursuit | Opens access to Brazil pre-salt and North Sea sour service replacement cycles. |
| After-Sales Service Unbundling | Creates discrete revenue pools for predictive maintenance among pad drilling fleet operators. |
Methodological Framework
Cross-validation between drilling contractor procurement directors and forging facility engineering managers anchors the qualitative findings. Primary interviews with well control specialists, API certification auditors, subsea project engineers, and aftermarket service heads combined with secondary validation through BSEE enforcement data, NORSOK U-001 documentation, ANP qualification records, and SEC filings from oilfield service providers. Bottom-up project pipeline assessment and top-down equipment spend analysis triangulate market sizing.
Calibration against historical replacement cycle data and announced deepwater rig construction programs shapes the projection framework. Segmentation dimensions modeled include product type, application context, end-user category, and installation format across the analysis window. CAGRs derive from equipment unit economics and pressure rating tier trajectories. Forecast inputs incorporate metallurgical specification shifts and regulatory mandate timelines without year-specific assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by digital-native sensor platform entrants or accelerated NORSOK interpretation updates would shift outcomes. Quarterly review of Petrobras procurement specifications, BSEE enforcement action frequency, and nickel-chromium price spreads is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Electrohydraulic Servo Valves (Ehsvs) Market
Valves
Europe Vacuum Insulated Pipe Market
Valves
Manual Control Valve Market
Valves
Air Jet Ejectors Market
Valves
Pneumatic Positioner Market
Valves
Rising Stem Ball Valve Market
Valves
Tubing Heads Market
Valves
Pigging Valves Market
Valves
Chemical Injection Skid Market
Valves
Aerospace Valves Market
Valves
Fin Tube Market
Valves
Industrial Safety Valves Market
Valves
Pipeline Equipment Market
Valves
Leak Detection Market
Valves
Valve Driver Market
Valves
Fluid Transfer Solutions Market