
 Petroleum Benzine Market | 2026-2036
Petroleum Benzine Market Size, Share, and Industry Trends Forecast 2026-2036
Petroleum Benzine Market Analytics
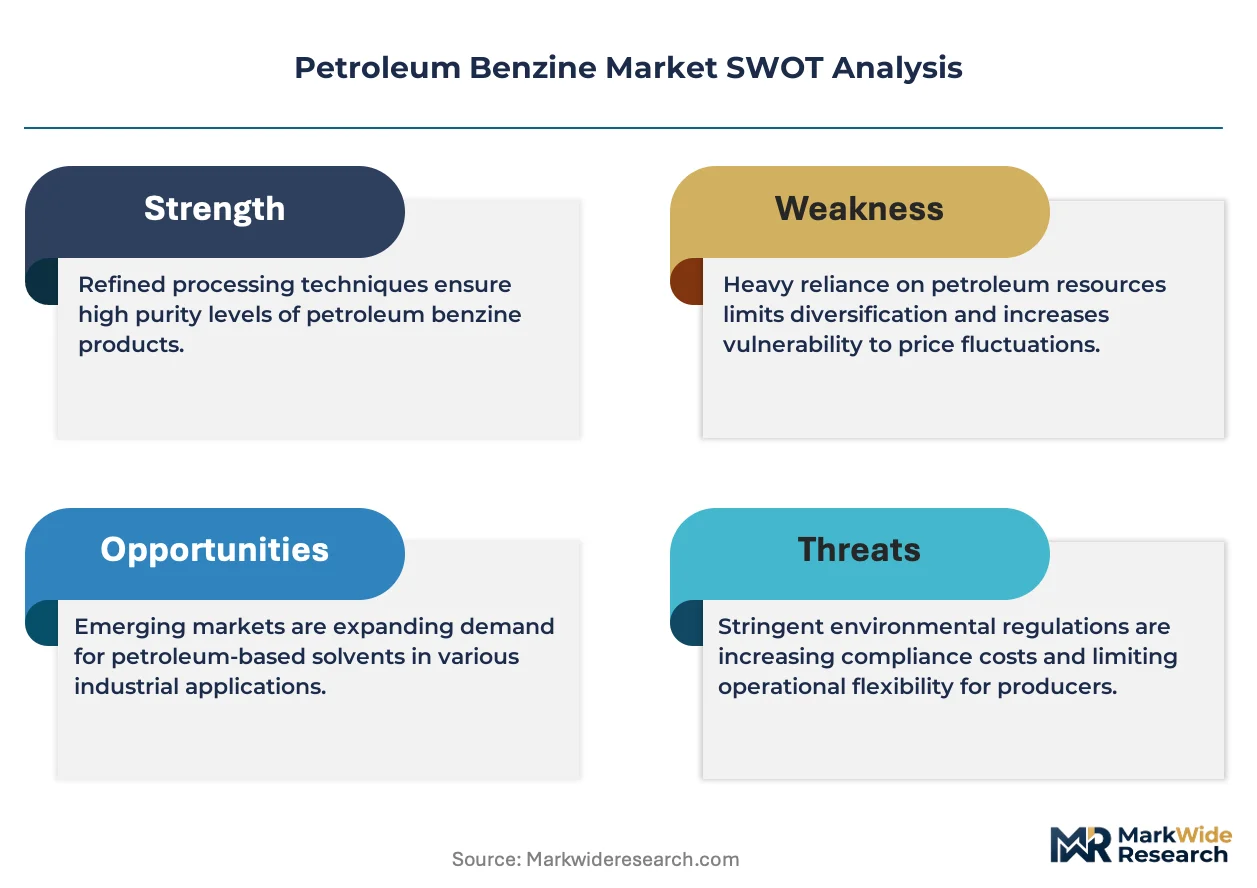
REACH is restructuring the cost-of-entry calculus for European petroleum benzine suppliers by mandating comprehensive substance registration and hazard communication protocols. ExxonMobil leverages its integrated refining-petrochemical footprint to absorb compliance costs across multiple product lines. SABIC anchors its competitive position through captive feedstock access at Saudi Aramco-affiliated complexes. INEOS Group specializes in high-purity aromatic benzine streams tailored to pharmaceutical and agrochemical solvent specifications.
Petroleum benzine denotes a volatile hydrocarbon mixture distilled from crude oil, typically boiling between 60°C and 140°C and comprising aliphatic and aromatic fractions including hexane, heptane, and toluene derivatives. Manufacturers refine it through catalytic reforming and fractional distillation to achieve specified solvent power and evaporation rates for industrial applications. The Fuel application segment dominates volume throughput due to widespread blending into gasoline pools across automotive supply chains. The Chemical Intermediate application represents the fastest-expanding category as Asian petrochemical complexes convert benzine-derived naphtha into olefins and aromatics for polymer production. The Solvent application remains mature in Western markets where water-based alternatives are displacing hydrocarbon cleaners in surface coating operations.
EPA regulations in the United States limit benzene content in petroleum benzine to protect occupational and environmental health, while China's MEE enforces emissions controls at refining facilities that constrain regional supply elasticity. The EU ECHA administers REACH registration deadlines that determine which benzine grades qualify for continued import and formulation use across member states. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions that could redirect solvent demand toward petroleum benzine alternatives in precision cleaning applications.
Market Dynamics
REACH registration deadlines are forcing European petroleum benzine suppliers to consolidate formulation portfolios and exit marginal aromatic grades, redistributing supply authority toward integrated refiners with captive testing infrastructure.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on fluorinated solvents in precision cleaning applications redirect industrial buyers toward high-purity petroleum benzine alternatives for electronics and aerospace component degreasing.
- Polymer feedstock demand:Asian petrochemical complexes expand naphtha cracking capacity, pulling additional aromatic-rich benzine streams into olefin and aromatics production chains.
- Catalytic reforming advances:Improved platinum-rhenium catalyst systems raise benzine yield rates from heavy naphtha feeds, lowering unit production costs for complex operators.
Market Restraints
- Crude oil price volatility:Feedstock cost swings compress margin predictability for independent blenders lacking long-term offtake agreements with integrated producers.
- Substitution by bio-based solvents:Agricultural-derived terpenes and esters capture surface coating applications in Western European automotive finishing operations.
- MEE emissions enforcement:China's Ministry of Ecology and Environment constrains refinery run rates during air quality campaigns, limiting regional supply elasticity during demand spikes.
Strategic Opportunities
- Pharmaceutical-grade specialization:Ultra-low sulfur aromatic benzine for active pharmaceutical ingredient synthesis commands price premiums in Indian and Chinese generic drug manufacturing clusters.
- Hydrogenation technology convergence:Combination of selective hydrogenation with molecular sieve separation enables custom benzine blends for agrochemical solvent specifications.
- Carbon border adjustment positioning:EU CBAM implementation creates first-mover advantage for Middle Eastern producers with lower-carbon intensity refining configurations.
Industry Challenges
- REACH registration timeline compression:Data gap analysis and substance sameness justification require specialized toxicology contracting that smaller blenders struggle to resource.
- Analyzer technician scarcity:Gas chromatography-mass spectrometry operation for benzine specification verification faces talent shortages in Central European industrial zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Petroleum Benzine Market |
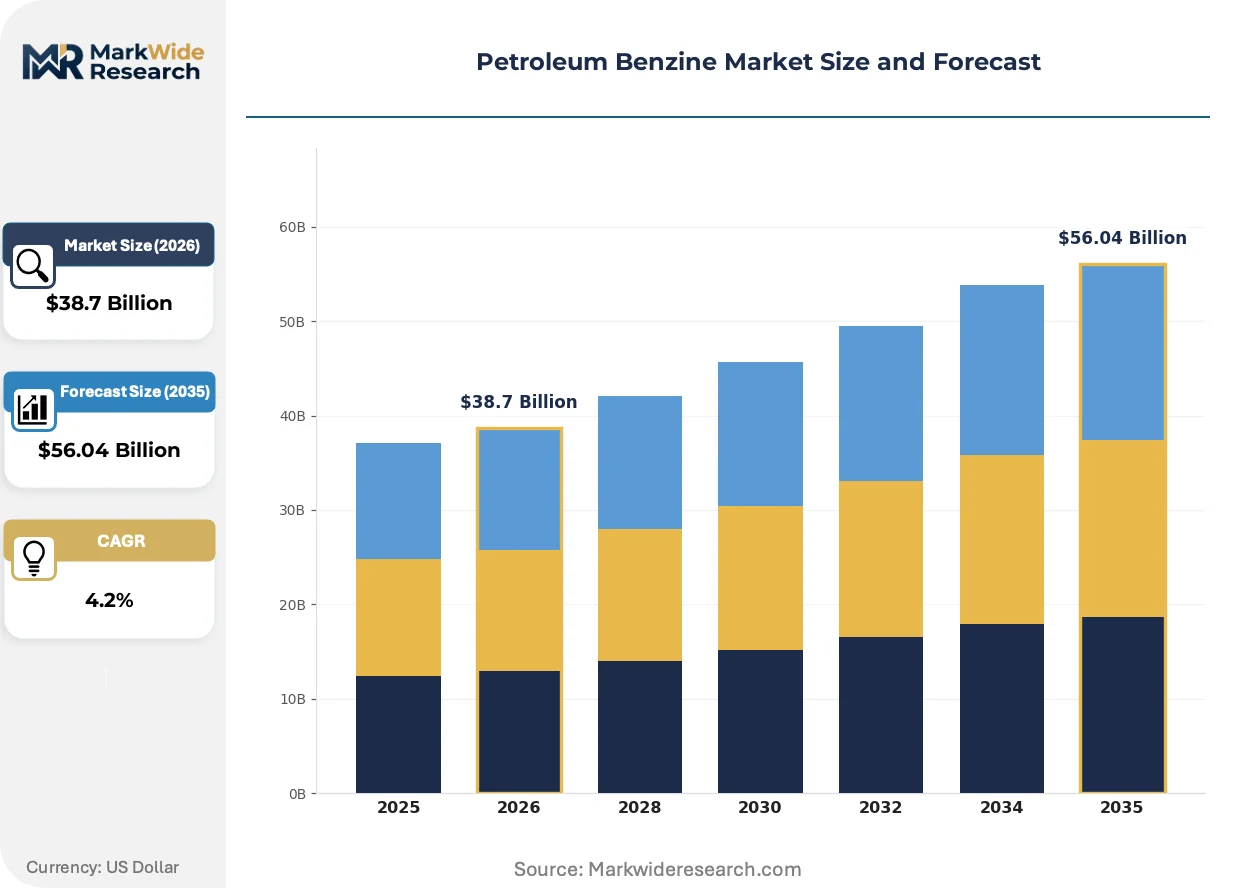
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $56.04 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular Benzine, Premium Benzine, Synthetic Benzine, Aromatic Benzine Application: Fuel, Solvent, Chemical Intermediate, Additive End User: Automotive Industry, Chemical Manufacturing, Oil & Gas Industry, Aerospace Sector Distribution Channel: Direct Sales, Wholesalers, Online Retail, Fuel Stations |
| Companies Covered | ExxonMobil Corporation, BASF SE, China Petrochemical Corporation, SABIC, Reliance Industries Limited, China National Petroleum Corporation, Shell, Dow, INEOS Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Petroleum Benzine Market Evolving Landscape
Process intensification and regulatory chemistry are restructuring how petroleum benzine gets specified, tested, and delivered across industrial solvent and chemical intermediate applications.
Advanced process control systems using real-time near-infrared spectroscopy are automating cut-point optimization in benzine fractionation units. Complex operators in Rotterdam and Singapore deploy these systems to tighten boiling range specifications without laboratory confirmation delays. This automation compresses quality deviation windows and reduces off-spec tankage requirements.
REACH authorization listings for polycyclic aromatic hydrocarbons are restricting certain high-aromatic benzine grades from consumer product formulations. The European Chemicals Agency's sunset date enforcement pushes formulators toward hydrogenated alternatives or alternative hydrocarbon solvents. German and French industrial coating manufacturers accelerate qualification programs for substitute grades ahead of 2026 deadlines.
Integrated refinery-petrochemical buyers consolidate solvent procurement under centralized chemical management contracts. Third-party distributors lose volume share as Aramco-affiliated complexes and ExxonMobil systems houses offer bundled benzine-aromatics-solvent packages. This concentration is most visible in Gulf Coast and East China chemical manufacturing corridors where site-wide chemical management agreements displace spot purchasing.
Petroleum Benzine Market Segmentation
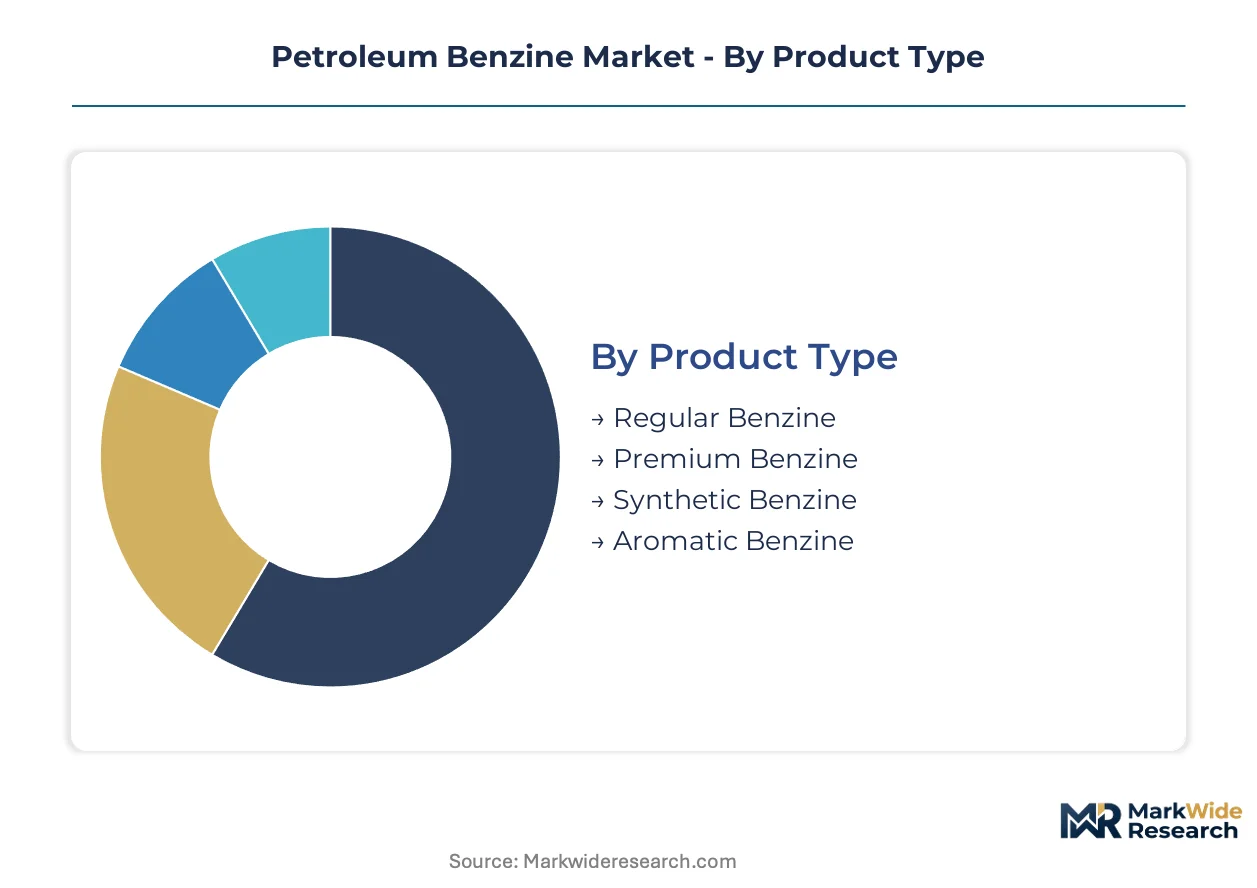
Petroleum benzine specifications diverge sharply across end-use requirements, with fuel blending tolerating wider boiling ranges while pharmaceutical and electronics solvents demand sub-ppm sulfur thresholds. Distinct formulation tiers command price multiples that reshape procurement patterns among integrated refiners versus independent blenders.
Product Type:
Upgrade cycles in solvent applications are shortening as REACH deadlines force reformulation toward lower-aromatic grades, compressing the commercial lifespan of legacy benzine specifications.
- Regular Benzine:Standard aliphatic fraction with 60-140°C boiling range serves gasoline blending and general industrial cleaning where specification tolerance permits higher aromatic content. Chinese state refiners in Shandong province dominate volume output for domestic fuel pooling.
- Premium Benzine:Tighter distillation cuts and enhanced desulfurization yield sub-50 ppm sulfur content for precision electronics cleaning and pharmaceutical extraction. South Korean display panel manufacturers in Gumi cluster are expanding offtake for OLED fabrication solvent systems.
- Synthetic Benzine:Manufactured via Fischer-Tropsch or methanol-to-gasoline routes offering consistent paraffinic composition independent of crude source.
- Aromatic Benzine:Elevated toluene and xylene fractions tailored for agrochemical dissolution and polymer feedstock preparation.
Volume placements concentrate in Regular Benzine; the faster expansion belongs to Premium Benzine.
Application:
Cost tiering separates commodity fuel blending from specification-grade solvent sales, with the latter capturing margin premiums through certification overhead.
- Fuel:Blending into gasoline pools accounts for the dominant throughput volume across refining complexes worldwide. Indian Oil Corporation's Mathura refinery processes substantial benzine streams for domestic transportation fuel compliance.
- Solvent:Surface coating, degreasing, and extraction applications require defined evaporation rates and Kauri-butanol values. German automotive finishing operations in Wolfsburg area are qualifying bio-based alternatives under EU Green Deal pressure.
- Chemical Intermediate:Naphtha cracking feedstock for olefin and aromatics production.
- Additive:Blending component for lubricant and fuel additive packages.
Margin capture is strongest in Solvent applications; Chemical Intermediate is climbing the fastest on Asian petrochemical capacity additions.
End User:
Customer type determines specification stringency, with aerospace and pharmaceutical buyers imposing lot-traceability requirements that exclude merchant market sourcing.
- Automotive Industry:Fuel blending and parts cleaning operations consume standardized benzine grades with minimal certification burden. Toyota's Nagoya manufacturing complex maintains long-term supply agreements with Idemitsu Kosan for consistent solvent quality.
- Chemical Manufacturing:Aromatic-rich benzine streams feed into BTX extraction and polymer precursor synthesis. SABIC's Jubail complex leverages captive supply from Saudi Aramco refining integration.
- Oil & Gas Industry:Drilling fluid formulations and pipeline maintenance solvents.
- Aerospace Sector:Precision cleaning of turbine components and avionics assemblies demands ultra-low residue specifications.
Procurement scale favors Chemical Manufacturing; Aerospace Sector shows steepest specification escalation.
Distribution Channel:
Supply concentration in integrated refinery-petrochemical corridors is marginalizing arm's-length distribution for volume benzine grades.
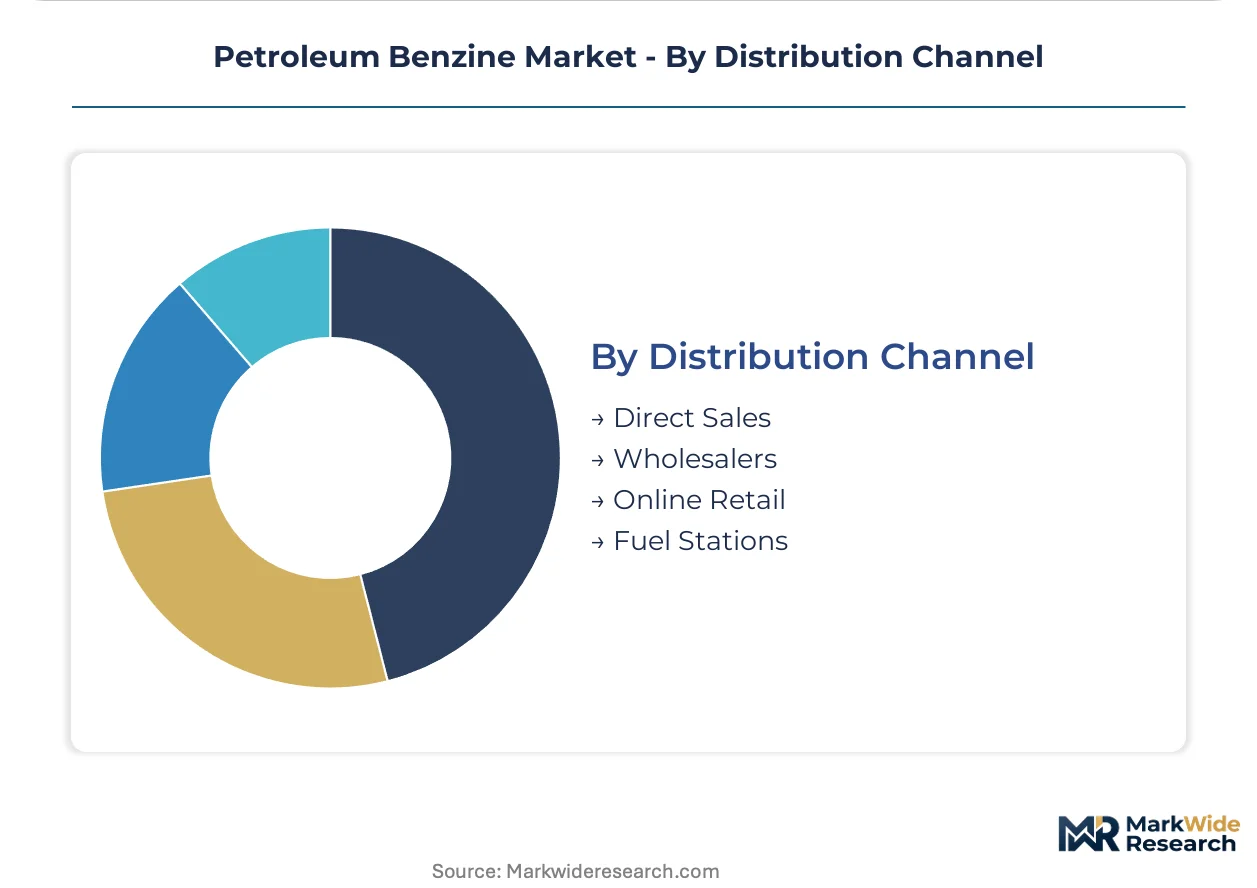
- Direct Sales:Refiner-to-manufacturer contracts dominate large-volume solvent and chemical intermediate procurement. ExxonMobil's Rotterdam refinery ships direct to BASF Antwerp under multi-year benzine-aromatics bundled agreements.
- Wholesalers:Independent distributors serve fragmented coating and cleaning operations lacking tankage infrastructure.
- Online Retail:Small-package solvent sales for laboratory and maintenance applications.
- Fuel Stations:Limited retail benzine availability for specialty small-engine applications.
Contract volume concentrates in Direct Sales; Online Retail is gaining share fastest among specialty grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong Province's petrochemical industrial zones concentrate domestic benzine refining capacity for chemical processing feedstock. State-owned refiners leverage integrated complexes to scale high-purity output. The regional pattern shows supply authority concentrating where crude import infrastructure meets downstream chemical demand.
China
Shandong and Jiangsu provinces host the dominant benzine fractionation complexes serving Asian polymer feedstock demand. MEE emissions enforcement during air quality campaigns constrains refinery run rates and limits supply elasticity. The Yangtze River Delta chemical manufacturing corridor pulls substantial aromatic-rich benzine streams into olefin production chains.
United States
Gulf Coast refining complexes process benzine streams for domestic fuel blending and chemical intermediate applications. EPA benzene content limits shape formulation standards for occupational and environmental health protection. The Houston Ship Channel petrochemical corridor maintains integrated benzine-aromatics production for polymer precursor synthesis.
Germany
Rhineland and Bavarian industrial zones consume specification-grade benzine for automotive finishing and pharmaceutical solvent applications. ECHA REACH registration deadlines force consolidation of aromatic benzine portfolios and exit from marginal grades. The BASF Ludwigshafen complex sources benzine streams under multi-year direct supply agreements with Rotterdam refiners.
Saudi Arabia
Jubail industrial city anchors benzine production for regional chemical manufacturing and export positioning. SAMR technical regulations align product specifications with Gulf standardization requirements. SABIC's captive feedstock access at Saudi Aramco-affiliated complexes secures cost-advantaged supply for BTX extraction operations.
India
Gujarat and Maharashtra industrial zones drive benzine demand for pharmaceutical extraction and agrochemical solvent applications. BIS certification requirements impose quality verification protocols on imported benzine grades. The Reliance Industries Jamnagar complex processes substantial benzine volumes for domestic fuel pooling and chemical intermediate production.
Petroleum Benzine Market Competitive Landscape
Middle Eastern producers anchor one tier through captive crude access and integrated petrochemical complexes; European and Asian specialists hold differentiated positions through specification-grade solvent capabilities. The market structure shows consolidation around state-affiliated energy majors and fragmentation among regional blenders serving niche solvent applications. Two strategic archetypes dominate: integrated refiners leveraging backward control over feedstock, and specialty chemical houses focusing on ultra-low sulfur pharmaceutical grades. Capacity expansion and portfolio diversification toward hydrogenated alternatives represent the prevailing competitive moves.
Within the integrated refiner archetype, ExxonMobil Corporation and SABIC exemplify geographic and structural differentiation. ExxonMobil occupies a position spanning Americas and European refining corridors with integrated petrochemical systems. SABIC anchors the Middle Eastern configuration through Aramco-affiliated complex integration. INEOS Group sits within the specialty tier, representing European high-purity solvent specialization without upstream crude ownership. These three entities demonstrate how feedstock access, geographic positioning, and specification focus segment competitive authority.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| BASF SE |
| China Petrochemical Corporation |
| SABIC |
| Reliance Industries Limited |
| China National Petroleum Corporation |
| Shell |
| Dow |
| INEOS Group |
| Others |
Value Network & Pricing Analysis
EU REACH authorization deadlines for polycyclic aromatic hydrocarbons gate qualified supply and premium-tier pricing access, forcing formulators to pay certification premiums for hydrogenated benzine alternatives or absorb reformulation costs to maintain market position.
Pricing Analysis
Short lead-time premiums dominate spot procurement, with pharmaceutical and electronics buyers paying substantial markups for just-in-time delivery of sub-50 ppm sulfur grades while fuel blenders capture volume discounts through multi-year offtake contracts. Price differentiation hinges on sulfur certification tier and geographic delivery cost, with Rotterdam-sourced premium benzine commanding substantial premia over Shandong regular grades. Pricing pressure stems from bio-based solvent substitution in Western European automotive finishing. Chemical manufacturers show least price sensitivity due to captive integration, while independent coating operators face acute margin compression.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Houston anchor hub-and-spoke patterns, with bulk tanker shipments feeding satellite blending facilities near downstream chemical corridors. Supply concentrates in China, Saudi Arabia, and the United States, where integrated refineries control aromatic-rich fractionation output. Raw material dependencies include heavy naphtha feedstock, platinum-rhenium catalyst systems, and molecular sieve separation media. Single-source vulnerability from Middle Eastern crude access concentration poses structural risk. Distribution runs through direct refiner-to-manufacturer contracts for volume grades, with arm's-length wholesalers serving fragmented specialty solvent demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The petroleum benzine market functions as a vertical-integration race, with players pursuing captive feedstock control to neutralize crude price volatility and secure margin stability across reforming and fractionation operations.
For Market Incumbents: Hedge aromatic benzine exposure by accelerating hydrogenation technology deployment ahead of REACH sunset enforcement, while consolidating testing infrastructure to absorb registration cost burdens that marginalize independent blenders. SABIC and ExxonMobil demonstrate how backward integration into refining complexes insulates against feedstock volatility. Defensive priority: secure pharmaceutical-grade certification pipelines in Indian and Chinese generic drug clusters before specialty competitors entrench. For New Entrants and Emerging Players: EU F-Gas Regulation in Europe opens a window for high-purity petroleum benzine positioning against displaced fluorinated solvents in precision electronics cleaning. White-space targets include ultra-low sulfur grades for OLED fabrication solvent systems in South Korean display panel manufacturing, and hydrogenated alternatives for German automotive finishing operations under Green Deal pressure. Go-to-market angle: qualification partnerships with agrochemical formulators seeking custom benzine blends for active ingredient dissolution. For Investors and Strategic Acquirers: Sustained MEE emissions enforcement constraining Shandong refinery run rates is the leading indicator that regional supply elasticity compression will persist, favoring integrated operators with multi-source feedstock flexibility. Long-term viability over the next decade rests on hydrogenation technology convergence and carbon border adjustment positioning. Acquisition target archetype: Central European specialty blenders with REACH-compliant testing infrastructure and established pharmaceutical customer relationships. Signal to watch: gas chromatography-mass spectrometry technician wage inflation as specification verification bottlenecks intensify.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heavy Naphtha Supply | Captive feedstock access at Saudi Aramco-affiliated complexes neutralizes crude price volatility for SABIC. |
| Hydrogenation Technology Deployment | Selective hydrogenation with molecular sieve separation enables custom benzine blends for agrochemical specifications at INEOS. |
| Pharmaceutical-Grade Certification Investment | Ultra-low sulfur aromatic benzine commands price premiums in Indian generic drug manufacturing clusters. |
| Long-term Direct Supply Agreements | ExxonMobil's Rotterdam refinery ships direct to BASF Antwerp under multi-year benzine-aromatics bundled contracts. |
| Carbon Border Adjustment Positioning | EU CBAM implementation creates first-mover advantage for Middle Eastern producers with lower-carbon intensity refining configurations. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews involving refinery operations managers, chemical procurement leads at downstream polymer producers, specialty solvent distributors, and ECHA regulatory affairs specialists. Secondary validation drew from SEC 10-K disclosures, Cefic chemical industry reports, and EU customs trade databases. Bottom-up benzine grade volume estimates and top-down petrochemical feedstock demand projections were triangulated to constrain forecast variance.
Data-stream reconciliation across supply-side capacity announcements, demand-side offtake contracts, and regulatory deadline calendars shaped the analytical framework. Segmentation dimensions modeled include benzine grade tier, end-use application intensity, and regional production hub configuration. CAGRs were derived from least-squares fitting of annual volume trajectories across the projection horizon, with catalytic reforming yield assumptions and REACH compliance cost pass-through rates serving as key industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for hydrogenation technology convergence would alter the outlook if breakthrough selective catalyst systems displace conventional reforming economics. Forecasts reflect documented assumptions around MEE enforcement intensity and EU CBAM implementation scope. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Crude Oil Flow Improvers Market
Petroleum Products
Performance Oil Sales Market
Petroleum Products
Uganda Petroleum Products Market
Petroleum Products
Petroleum Liquid Feedstock Naphtha and Gas Oil Sales Market
Petroleum Products
Marine Minerals Market
Petroleum Products
Europe Refined Petroleum Products Market
Petroleum Products
Very Low Sulphur Fuel Oil (VLSFO) Market
Petroleum Products
Gasoline-Naphtha-Crude-MTBE Market
Petroleum Products
Petcoke Market
Petroleum Products
Alkylate Gasoline Market
Petroleum Products
Liquefied Petroleum Gas Market
Petroleum Products
Natural Gas Liquid Market
Petroleum Products
Floating Roof Tank Market
Petroleum Products
Petroleum Liquid Feedstock Market
Petroleum Products
Spiral Submerged Arc Welded (SSAW) Steel Pipe Market
Petroleum Products
Crude Tall Oil Market