
 Chemical Injection Skid Market | 2026-2036
Chemical Injection Skid Market Size, Share, and Industry Trends Forecast 2026-2036
Chemical Injection Skid Market Analysis
REACH compliance is rebalancing the cost-of-entry calculus for European suppliers of chemical injection skids, forcing material upgrades and documentation burdens that favor established manufacturers. Lewa GmbH leverages its precision pump engineering heritage to sustain premium positioning in high-pressure applications. IDEX Corporation anchors its portfolio through Milton Roy's diaphragm pump technology, while SPX FLOW competes across modular system configurations for water treatment and hydrocarbon processing.
Chemical injection skids are self-contained packages integrating pumps, tanks, piping, and controls to meter precise chemical doses into process streams, typically operating at pressures from 100 to 10,000 psi depending on application severity. Their primary purpose spans corrosion inhibition, hydrate suppression, scale prevention, and pH adjustment in continuous industrial operations. Modular systems lead the product type landscape due to flexible configuration for brownfield retrofits, while pneumatic technology dominates offshore installations where electrical spark risks constrain equipment selection. The oil and gas application segment occupies the deepest margin pools, though water treatment utilities represent the fastest-growing demand channel.
The EPA regulates chemical handling and emissions disclosure for US installations, while REACH and the EU Green Deal shape material composition and lifecycle accountability for European deployments. API standards for corrosion management and NACE guidelines for sour service compatibility further constrain product design choices across jurisdictions. Stakeholders must monitor how evolving methane detection mandates and carbon intensity disclosures reshape specification requirements for next-generation skid packages.
Market Dynamics
Automated chemical dosing systems are compressing procurement cycles as Saudi Aramco and ADNOC mandate real-time flow monitoring and remote diagnostics across brownfield retrofits. This shift from manual intervention to closed-loop control is redrawing vendor qualification criteria and service revenue models.
Growth Catalysts
- EPA methane detection mandates:Offshore operators in the Gulf of Mexico must install continuous emission monitoring systems, driving replacement demand for instrumented skid packages with integrated sensors.
- Hydrate suppression chemistry:Deepwater gas developments in Mozambique and Tanzania require high-pressure injection infrastructure for thermodynamic inhibitors at subsea wellheads.
- API 6D valve automation standards:Upstream facilities are retrofitting existing skids with motorized actuators to enable remote shutdown capabilities and reduce platform manning.
Market Restraints
- Specialized alloy supply concentration:Duplex stainless steel for sour service pumps concentrates among Scandinavian and Japanese metallurgical suppliers, exposing lead times to geopolitical friction.
- REACH documentation burdens:European material compliance requires full substance-of-very-high-concern tracing for elastomer seals, extending quotation cycles by four to eight weeks.
- Electrochemical sensor drift:pH and corrosion probe calibration requirements in high-H2S environments limit unmanned operation intervals to ninety days maximum.
Strategic Opportunities
- Carbon capture injection skids:Post-combustion amine circulation systems require precise solvent dosing packages at power stations and cement plants.
- Desalination chemical trains:Saudi Arabia's Ras Al-Khair and UAE's Taweelah facilities are expanding antiscalant and biocide injection capacity for membrane protection.
- Digital twin integration:Predictive maintenance algorithms overlaid on skid telemetry enable condition-based overhaul scheduling and spare parts pre-positioning.
Industry Challenges
- Cross-disciplinary commissioning teams:Integrated packages demand simultaneous expertise in process engineering, PLC programming, and hazardous area electrical certification.
- Legacy DCS protocol fragmentation:Brownfield sites operate on proprietary communication architectures that resist seamless integration with modern skid-mounted PLCs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemical Injection Skid Market |
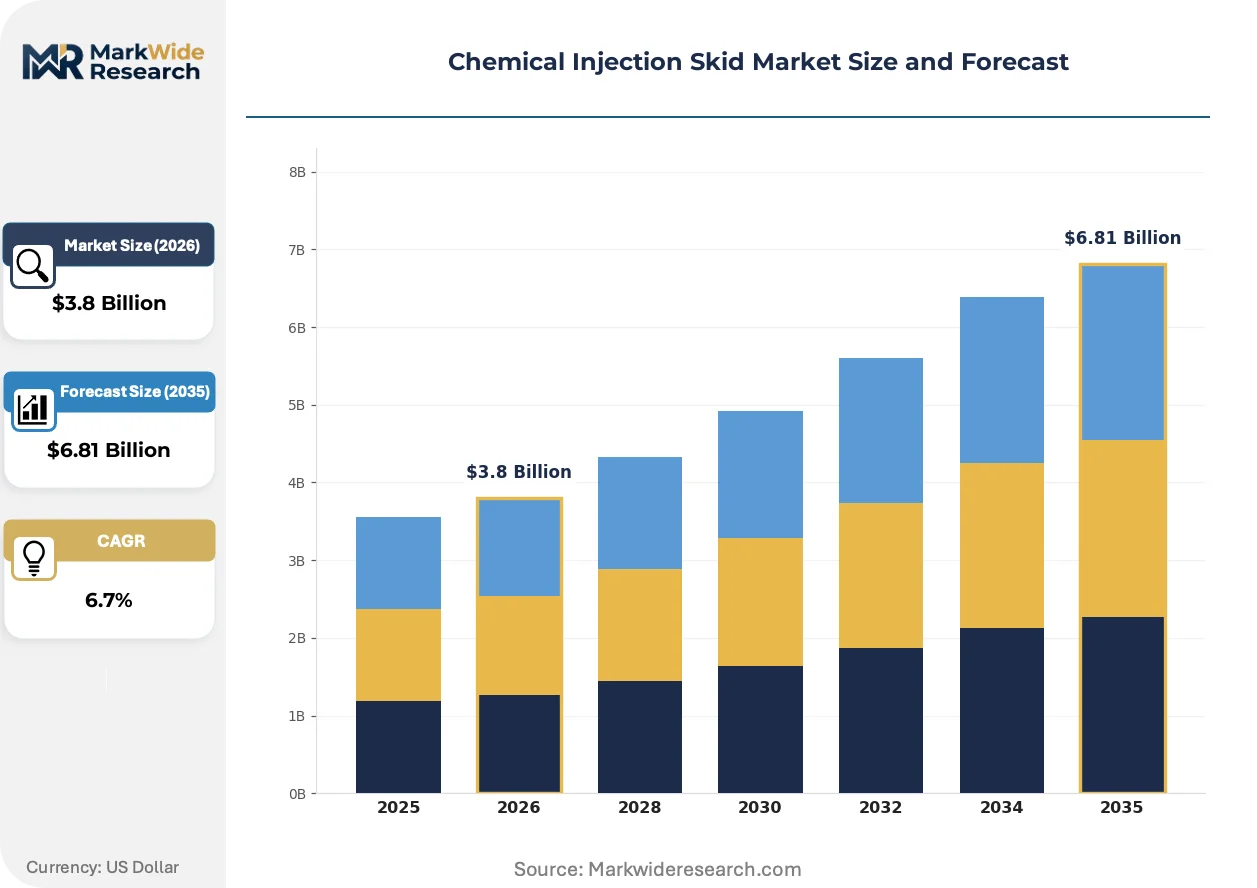
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Skids, Modular Systems, Truck-mounted Units, Portable Skids Application: Oil & Gas, Water Treatment, Chemical Processing, Food & Beverage Technology: Pneumatic, Hydraulic, Electric, Mechanical End User: OEMs, Contractors, Utilities, Service Providers |
| Companies Covered | Lewa GmbH, IDEX Corporation, SPX FLOW, Milton Roy, Proserv Group, AES Arabia Ltd., Petronash, INTECH Process Automation, Carotek, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemical Injection Skid Market Emerging Trajectories
Electrification of subsea chemical distribution is compressing topside footprint requirements while expanding intervention reach. Vendors are reconfiguring pump architectures and power transmission methods to serve wells at depths exceeding three thousand meters.
Magnetically driven sealless pumps is overtaking conventional packed plunger designs in methanol and corrosion inhibitor service. Deepwater operators in Brazil and West Africa are specifying these units for subsea distribution modules to eliminate atmospheric emissions and reduce maintenance intervals. The technology is overtaking legacy reciprocating pumps in applications above five thousand psi, compressing the addressable market for mechanical seal manufacturers.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing elastomer specification changes for O-rings and diaphragms in European deployments. Compound suppliers are accelerating validation of hydrogenated nitrile and thermoplastic alternatives for chemical resistance equivalence. Water treatment utilities in Germany and the Netherlands are absorbing extended qualification timelines as they await third-party certification of replacement materials.
Integrated service contracts bundling chemical supply, equipment lease, and performance guarantees are displacing capital purchase models in North Sea operations. Major operators are transferring dosage optimization risk to chemical vendors, who now specify and maintain skid packages against corrosion rate targets. This shift is most visible in UK continental shelf assets where mature field economics favor opex flexibility over upfront capex commitment.
Chemical Injection Skid Market Segmentation
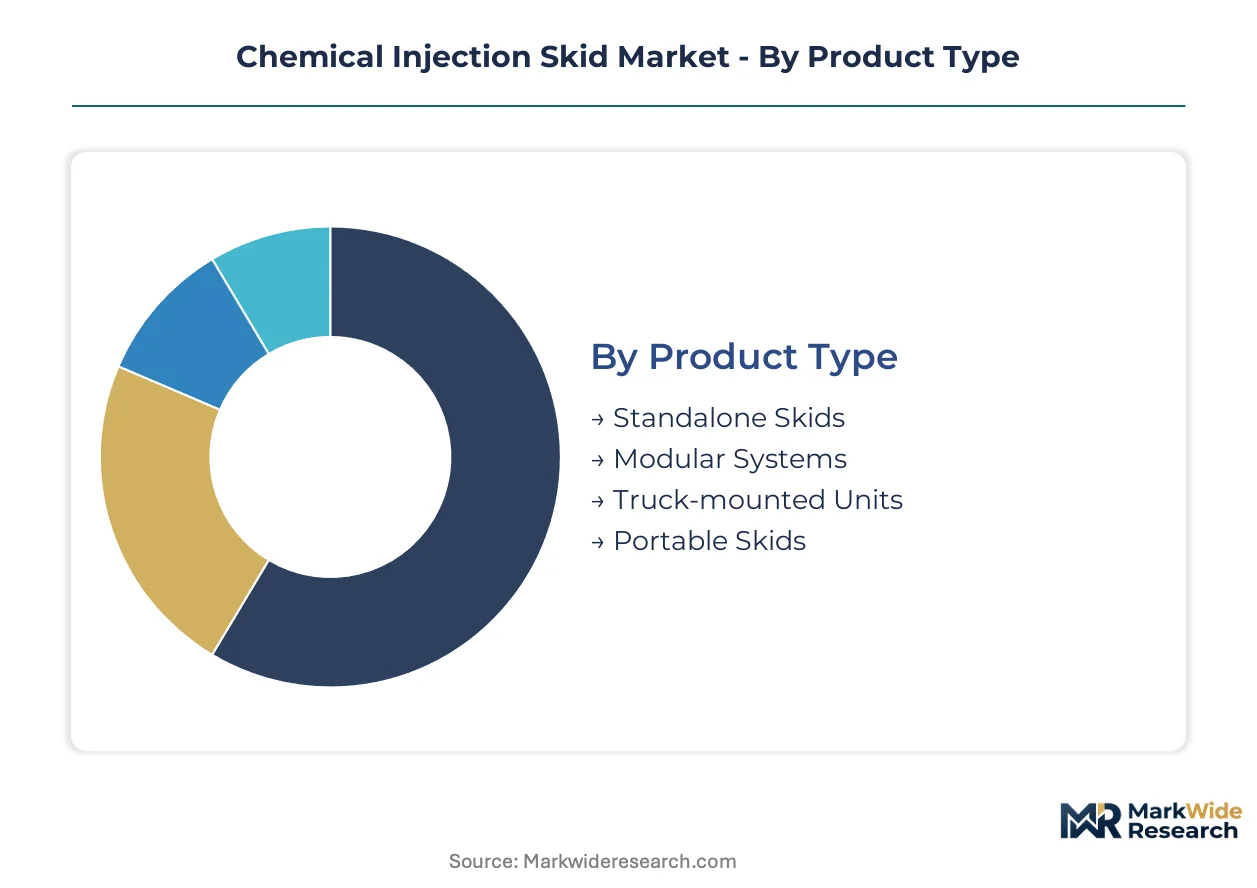
Chemical injection skids serve heterogeneous operational environments, from offshore platforms requiring explosion-proof pneumatic systems to municipal utilities demanding compact electric packages. Segmentation reveals how specification requirements diverge across pressure ratings, automation levels, and hazardous area classifications.
Product Type:
Volume concentration favors configurable architectures that minimize field engineering hours, while premium positioning attaches to integrated packages with pre-validated control loops.
- Modular Systems:Interchangeable pump, tank, and manifold assemblies enable rapid reconfiguration for brownfield retrofits without process shutdown. Saudi Aramco and ADNOC procurement specifications now mandate modular architectures for field chemical distribution upgrades across aging wellheads.
- Standalone Skids:Self-contained single-purpose units with dedicated power and control enclosures serve isolated injection points. Gulf of Mexico operators deploy these for remote wellhead methanol injection where platform space constraints preclude centralized chemical distribution.
- Truck-mounted Units:Mobile deployment packages for temporary well stimulation and pipeline commissioning operations.
- Portable Skids:Compact lightweight configurations for maintenance dosing and pilot testing applications.
Mature deployment sits with Standalone Skids. Newer deployment is concentrated in Modular Systems.
Application:
Margin pools deepen where process failure carries catastrophic cost—subsea corrosion inhibition commands specification premiums that water treatment biocide dosing cannot sustain.
- Oil & Gas:High-pressure hydrate suppression and sour service corrosion management operate at 5,000–10,000 psi with NACE MR0175 material requirements. Deepwater developments offshore Mozambique and Tanzania drive demand for subsea-rated injection distribution.
- Water Treatment:Membrane protection through antiscalant and biocide dosing at municipal desalination facilities. Ras Al-Khair and Taweelah expansion programs in Saudi Arabia and the UAE represent the steepest expansion trajectory for utility-scale installations.
- Chemical Processing:Continuous reactor feed and pH neutralization in specialty chemical manufacturing.
- Food & Beverage:Sanitary-grade injection for CIP systems and additive dosing with FDA compliance documentation.
Installed base concentration remains with Oil & Gas. Capacity expansion is accelerating fastest in Water Treatment.
Technology:
Power transmission method selection trades precision against hazardous area certification constraints, with offshore electrical spark risks preserving pneumatic dominance despite efficiency penalties.
- Pneumatic:Compressed air-driven diaphragm and piston pumps eliminate ignition sources in Zone 1 hazardous areas. North Sea and Gulf of Mexico platform specifications maintain this as default for methanol and corrosion inhibitor service.
- Electric:Variable frequency drive control enables precise flow modulation and SCADA integration. Onshore shale facilities in the Permian Basin specify electric skids for remote unattended operation with cellular telemetry.
- Hydraulic:High-force power transmission for ultra-high-pressure applications exceeding 15,000 psi in well stimulation.
- Mechanical:Simple cam-driven or spring-return mechanisms for basic dosing without external power.
Established specification dominance belongs to Pneumatic. Specification momentum is shifting toward Electric.
End User:
Procurement authority fragmentation shapes vendor engagement models—national oil companies centralize technical standards while contractor fleets prioritize lease flexibility.
- Service Providers:Integrated chemical supply and equipment lease contracts transfer dosage optimization risk from operator to vendor. UK continental shelf assets now predominantly specify performance-based corrosion rate guarantees rather than capital purchase.
- OEMs:Original equipment manufacturers bundle skid packages into larger process system deliveries for greenfield construction.
- Utilities:Municipal water and power generation entities with standardized technical specifications and public procurement cycles.
- Contractors:Temporary equipment users for drilling, completion, and maintenance campaigns requiring short-term lease structures.
Contractual innovation is emerging through Service Providers. Equipment ownership concentration persists with OEMs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jubail Industrial City and Ras Al-Khair Economic Zone concentrate chemical injection skid fabrication capacity through integrated supply chains serving Aramco and SABIC procurement programs. These Saudi special economic zones offer customs exemptions and streamlined licensing that attract European pump manufacturers seeking regional assembly presence.
Saudi Arabia
Aramco's brownfield modernization program mandates automated chemical dosing across 12,000+ wellheads, driving specification demand for modular skid architectures. The kingdom's SFDA and SASO standards now require full material traceability for sour service applications. Eastern Province clusters around Jubail and Dammam host fabrication yards supplying offshore platforms in the Arabian Gulf.
United Arab Emirates
ADNOC's offshore expansion at Upper Zakum and sour gas development at Shah field require high-pressure injection systems rated above 7,000 psi. MOHAP and ADNOC technical standards increasingly specify real-time monitoring capabilities for unmanned platform operations. Dubai and Abu Dhabi engineering offices coordinate procurement for projects spanning the emirates' offshore concessions.
United States
Gulf of Mexico operators face EPA methane detection mandates requiring instrumented skid packages with integrated emission sensors. The Bureau of Safety and Environmental Enforcement enforces API 6D valve automation standards for platform safety systems. Houston and Lake Charles fabrication centers supply brownfield retrofits across the Gulf Coast shelf and deepwater developments.
Norway
Equinor's Johan Sverdrup and Northern Lights carbon capture projects specify subsea chemical distribution modules for hydrate suppression and solvent injection. The Norwegian Environment Agency enforces strict emissions disclosure for offshore chemical handling. Stavanger and Bergen engineering clusters drive specification innovation for North Sea electrification and unmanned platform designs.
Brazil
Petrobras' Búzios and Mero pre-salt developments demand subsea chemical injection trees operating at depths exceeding 2,000 meters. ANP regulatory frameworks require corrosion management documentation for ultra-deepwater infrastructure. Rio de Janeiro and Macaé service bases coordinate vessel-based installation campaigns for floating production units.
Chemical Injection Skid Market Vendor Landscape
German and Swiss producers anchor the precision-engineering tier; Gulf-based fabricators hold the regional service and rapid-delivery tier. Market structure concentrates around three to five integrated pump-system houses with full in-house metallurgy and control capabilities, alongside a fragmented base of regional skid assemblers sourcing pumps and instrumentation externally. Two strategic archetypes dominate: heritage precision-pump specialists leveraging decades of high-pressure engineering, and integrated flow-control conglomerates bundling chemical injection into broader process equipment portfolios. Competitive moves center on performance-based service contracts transferring dosage optimization risk to vendors, and backward integration into specialized alloy supply chains to secure sour-service pump lead times.
Among heritage German engineering houses, Lewa GmbH exemplifies the precision-pump archetype through its longstanding concentration on high-pressure diaphragm technology. IDEX Corporation occupies a position as a diversified flow-control conglomerate, anchoring its portfolio through the Milton Roy subsidiary. SPX FLOW represents the modular-system integrator archetype, competing across configurable packages for water treatment and hydrocarbon processing applications. These three entities illustrate how competitive positioning diverges between technology specialization and portfolio breadth.
| Leading Market Players |
|---|
| Lewa GmbH |
| IDEX Corporation |
| SPX FLOW |
| Milton Roy |
| Proserv Group |
| AES Arabia Ltd. |
| Petronash |
| INTECH Process Automation |
| Carotek, Inc. |
| Others |
Supply Flow & Price Mechanics
Duplex stainless steel ingots from Scandinavian and Japanese metallurgical suppliers cascade through three distinct pricing tiers before reaching offshore platform operators, with material traceability documentation under REACH and API NACE MR0175 standards compressing margins at each conversion stage.
Pricing Analysis
Lead-time premiums of fifteen to twenty percent attach to sour-service pump packages delivering inside twelve-week windows, while spot inventory of standard carbon-steel skids trades at discounts to contract rates. Three-tier pricing structure across premium, standard, and economy levels separates NACE-certified high-pressure systems from modular electric configurations and basic pneumatic units. Pricing pressure stems from Saudi Aramco and ADNOC procurement teams consolidating supplier panels and demanding performance guarantees. Water treatment utilities exhibit highest price sensitivity due to municipal budget cycles, whereas deepwater operators prioritize reliability over unit cost.
Supply Chain Analysis
Regional distribution centers in Jubail Industrial City, Houston, and Stavanger anchor hub-and-spoke patterns serving fabrication yards within forty-eight-hour logistics radii. Manufacturing concentration centers on Germany, Switzerland, and Saudi Arabia for precision pump engineering, with China and India supplying instrumentation and control enclosures. Raw material dependencies include duplex stainless steel for sour service, hydrogenated nitrile elastomers for REACH-compliant seals, and specialized ceramics for plunger coatings. Single-source vulnerability concentrates in Scandinavian super-duplex forging capacity. Distribution runs through OEM-direct channels for greenfield projects and integrated service providers for brownfield retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH Annex XVII substance restrictions and EPA methane detection mandates erect compliance moats that favor established manufacturers with dedicated regulatory affairs infrastructure and pre-validated material traceability systems.
For Market Incumbents: Lock in sour-service alloy supply through backward integration into Scandinavian forging partnerships or long-term offtake agreements with Japanese metallurgical suppliers. Secure NACE MR0175 certification maintenance as a barrier against Asian pump assemblers lacking in-house metallurgy capabilities. Threat substitution from magnetically driven sealless pumps demands accelerated R&D in sealless architectures for applications above five thousand psi. For New Entrants and Emerging Players: Digital twin integration for predictive maintenance algorithms offers a technology-first wedge into the UK continental shelf service provider segment, where integrated chemical lease contracts displace capital purchase models. Target carbon capture injection skids at power stations and cement plants as the most penetrable application, with amine solvent dosing expertise as the go-to-market angle. White-space exists in truck-mounted portable units for temporary well stimulation campaigns in Mozambique and Tanzania. For Investors and Strategic Acquirers: ADNOC's unmanned platform specifications mandating real-time monitoring capabilities is the leading indicator that control-systems integration depth determines acquisition premiums across the analysis window. Long-term viability favors targets with captive PLC programming expertise and hazardous area electrical certification capabilities. Signal to watch: Saudi Aramco modular architecture mandates spreading to UAE and Kuwait national oil companies.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sour-Service Alloy Supply | Secures NACE MR0175 pump lead times against Scandinavian supply concentration. |
| Digital Twin Platform Development | Enables predictive maintenance contracts with ADNOC unmanned platform specifications. |
| REACH-Compliant Elastomer Validation | Accelerates European qualification timelines for hydrogenated nitrile seal alternatives. |
| Carbon Capture Skid Product Line | Captures amine solvent dosing demand at power stations and cement plants. |
| Integrated Service Contract Bundling | Transfers dosage optimization risk from operators to vendors in North Sea markets. |
Methodological Framework
Document review covered API standards documentation, EPA regulatory filings, REACH Annex XVII substance restrictions, and national oil company procurement specifications, complemented by interviews with maintenance directors at offshore platforms, pump system procurement leads at Aramco and ADNOC, fabrication yard operations managers in Jubail and Houston, and aftermarket service heads at integrated chemical supply vendors. Secondary sources included customs trade data for duplex stainless steel flows, SEC 10-K filings from listed flow-control conglomerates, and project development databases for deepwater installations in Mozambique and Tanzania. Bottom-up unit economics triangulated against top-down market sizing from national oil company capex disclosures.
Historical capacity utilization rates at German and Swiss precision pump manufacturers were cross-referenced against panel input from procurement executives regarding specification momentum shifts from pneumatic to electric technologies. The analytical framework modeled volume and value trajectories across product type, application severity, technology architecture, and end-user procurement authority over the projection horizon. CAGRs were derived from segment-level demand build-ups incorporating brownfield retrofit cycles, greenfield development timelines, and regulatory compliance deadlines. Industry-specific forecast inputs included subsea electrification depth records and desalination membrane protection chemical intensity per thousand cubic meters.
Several conditions sit outside the modeled scope, including unannounced national oil company procurement specification changes, breakthroughs in non-amine carbon capture solvents, and geopolitical disruptions to Scandinavian metallurgical supply. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and material substitution timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Gas Equipment Market
Valves
Bend Restrictors and Stiffeners Market
Valves
Global Control Valves Market
Valves
Christmas Tree Valves Market
Valves
Safety Valve Market
Valves
Portable Valve Actuator Market
Valves
North America Industrial Valves Market
Valves
3-Way Pilot Operated Directional Control Valves Market
Valves
Pipeline Integrity Management (PIM) Market
Valves
Valve Manifold Box (VMB) Market
Valves
Pressure Gauge Market
Valves
Carbon Seal Rings Market
Valves
Global Marine Actuators and Valves Market
Valves
Railway Emergency Valves Market
Valves
Global Industrial Thermostatic Control Valves Market
Valves
Butterfly Valves Market