
 Electrohydraulic Servo Valves (Ehsvs) Market | 2026-2036
Electrohydraulic Servo Valves (Ehsvs) Market Size, Share, and Industry Trends Forecast 2026-2036
Electrohydraulic Servo Valves (Ehsvs) Market Foresight
Military-grade qualification tiers is collapsing the addressable supply base for mission-critical applications. Moog Inc. dominates aerospace flight control actuation with proprietary torque motor designs that sustain decades-long platform contracts. Parker Hannifin leverages integrated hydraulic system architectures to anchor industrial automation demand across European manufacturing clusters. Bosch Rexroth specializes in compact servo valve formats for embedded robotics applications where space constraints dictate form factor.
An electrohydraulic servo valve is a precision fluid control device that converts low-power electrical signals into proportional hydraulic flow output, typically achieving frequency response above 100 Hz with spool positioning accuracy within micrometers. Its primary purpose is enabling closed-loop control of position, velocity, or force in systems requiring rapid, repeatable actuation under variable load conditions. Proportional control valves lead product type demand in industrial automation for their balance of precision and cost, while smart valves represent the fastest-growing technology segment as embedded diagnostics reduce unplanned downtime. Aerospace end users command the highest margin pools due to extended qualification cycles and sole-source dependencies on flight-critical hardware.
The U.S. FAA and EASA impose stringent qualification protocols on electrohydraulic servo valves deployed in primary flight control systems, mandating fault-tolerant architectures that elevate engineering barriers for new entrants. ISO 4406 cleanliness standards and REACH material compliance further constrain supplier flexibility in fluid compatibility and sealing material selection. Stakeholders must monitor the divergence between analog legacy fleet support requirements and digital smart valve adoption timelines across defense and commercial aerospace programs.
Market Dynamics
Military-grade qualification requirements are compressing the supplier base for flight-critical electrohydraulic servo valves, while embedded diagnostics capabilities create divergent investment priorities between legacy fleet support and next-generation smart valve architectures.
Growth Catalysts
- FAA Airworthiness Directives:The U.S. FAA's redundant flight control mandates for commercial aircraft sustain demand for fault-tolerant valve architectures with extended qualification cycles that lock in sole-source relationships.
- Machine Tool Automation:Germany's industrial automation corridor drives specification of high-response servo valves for multi-axis positioning systems in precision manufacturing equipment.
- Embedded Sensor Integration:Smart valve technologies with real-time diagnostics are reducing unplanned downtime in continuous-process industries, accelerating replacement cycles in predictive maintenance programs.
Market Restraints
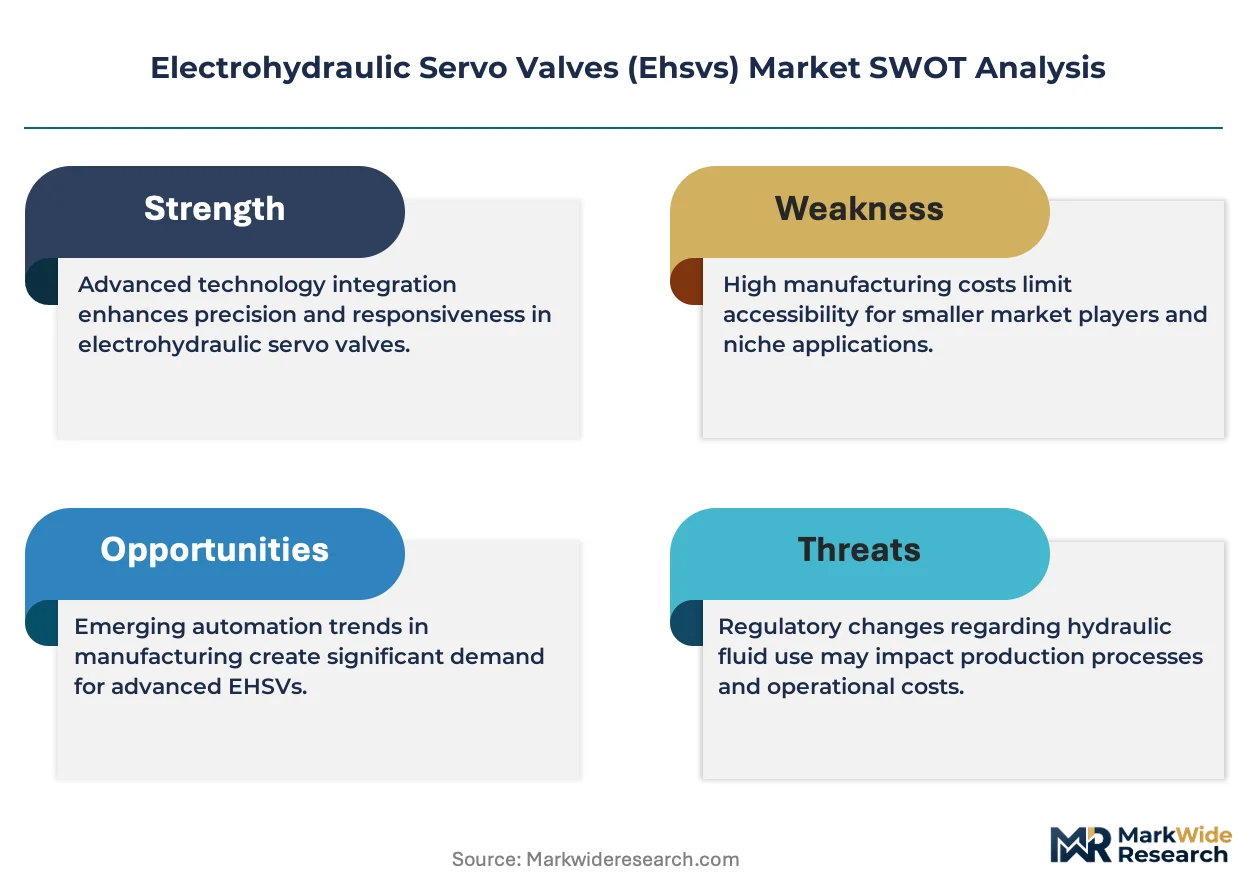
- Specialized Alloy Costs:High-performance magnetic materials and corrosion-resistant alloys expose margins to commodity volatility in torque motor and spool manufacturing.
- Qualification Timeline Compression:EASA and FAA certification protocols for primary flight control systems extend development cycles beyond typical industrial product lifecycles, constraining R&D portfolio flexibility.
- Electromechanical Substitution:All-electric actuation systems in lower-force aerospace applications displace hydraulic architectures in secondary flight control surfaces and landing gear systems.
Strategic Opportunities
- Urban Air Mobility:Electric vertical take-off and landing platforms require compact, high-bandwidth actuation for distributed flight control surfaces in space-constrained airframe designs.
- Industrial IoT Convergence:Integration of servo valve health monitoring with cloud-based analytics platforms enables subscription-based service models for hydraulic system uptime guarantees.
- India Manufacturing Expansion:Production-linked incentive schemes for aerospace and defense manufacturing localize procurement requirements for precision hydraulic components in emerging domestic supply chains.
Industry Challenges
- Torque Motor Expertise Scarcity:Specialized electromechanical design capabilities for high-frequency response valves concentrate among legacy engineering teams with decades of platform-specific experience.
- Legacy-Digital Integration:Analog valve architectures in existing aerospace fleets require sustained technical support while suppliers reallocate engineering resources to digital smart valve development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrohydraulic Servo Valves (Ehsvs) Market |
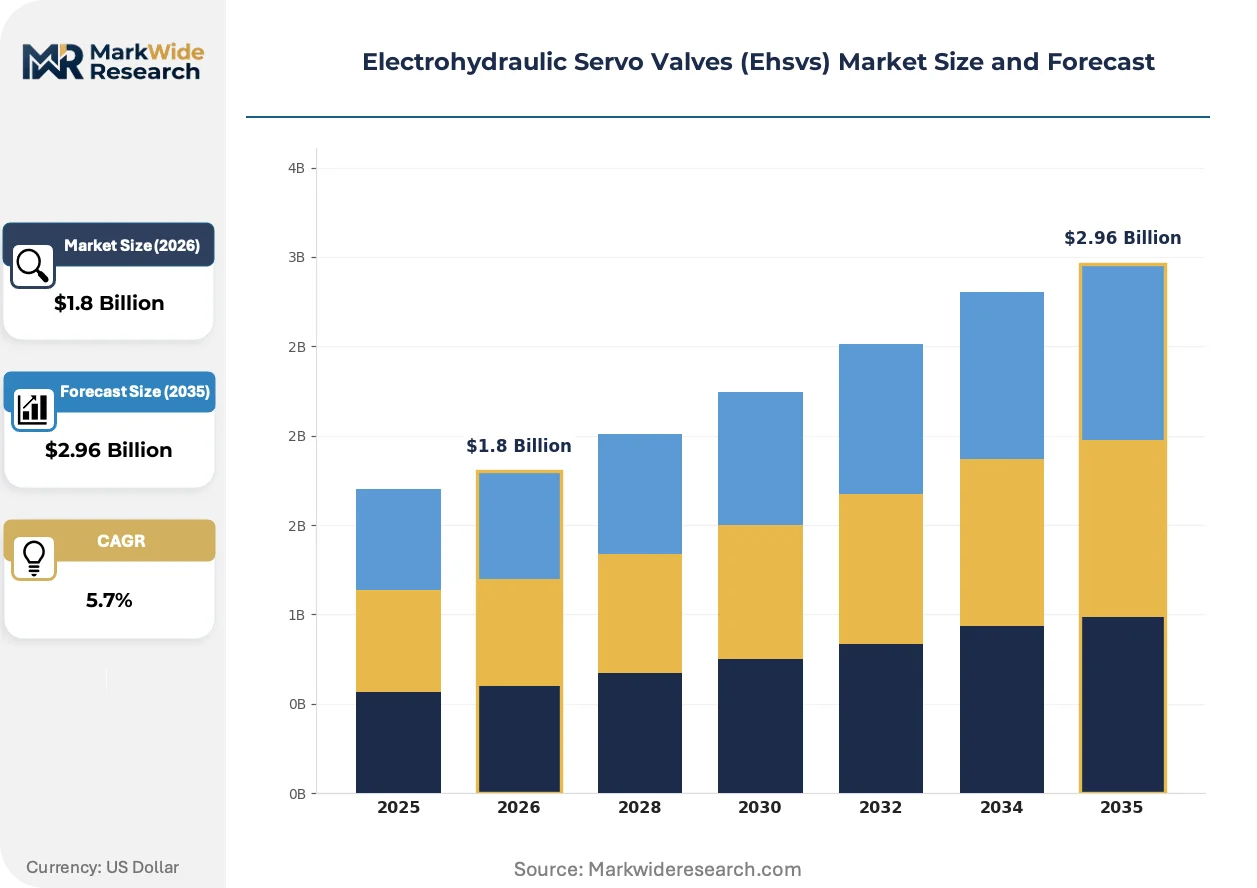
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Directional Control Valves, Proportional Control Valves, Flow Control Valves, Pressure Control Valves End User: Aerospace, Marine, Industrial Automation, Robotics Installation: Inline, Circuit Board Mounted, Panel Mounted, Portable Technology: Analog, Digital, Smart Valves, Pressure Compensated |
| Companies Covered | Moog Inc., Parker Hannifin, Bosch Rexroth, Eaton Corporation, Honeywell International, Woodward Inc., HAWE Hydraulik SE, Voith GmbH & Co. KGaA, Atos SpA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrohydraulic Servo Valves (Ehsvs) Market Shifts & Advancements
Electrohydraulic servo valve architectures are bifurcating between miniaturized embedded formats for robotics and distributed aerospace systems, and hardened redundant designs for primary flight control, with diagnostic intelligence becoming the primary differentiation vector.
Compact servo valve formats are miniaturizing spool and torque motor assemblies to enable direct integration into robotic joints and aerospace control surfaces where volume constraints previously precluded hydraulic actuation. Collaborative robot manufacturers in precision assembly applications are adopting these reduced-form-factor valves at accelerating rates. This dimensional compression is miniaturizing the boundary between centralized hydraulic power units and localized electromechanical alternatives.
REACH material compliance and EU F-Gas Regulation are constraining sealing material selection and hydraulic fluid compatibility in European industrial automation deployments. Manufacturers must reformulate elastomer compounds and validate alternative fluid chemistries to maintain certification continuity. Aerospace suppliers serving European OEMs face the most acute reformulation timelines as existing material qualifications expire.
After-sales service unbundling is fragmenting traditional bundled maintenance contracts into discrete diagnostics subscriptions and component-level replacement programs. Industrial buyers in automotive manufacturing are preferring valve-health monitoring services over capital-intensive spare inventory holdings. This behavioral shift is most pronounced in German and Japanese precision manufacturing clusters where total cost of ownership modeling dominates procurement evaluation.
Electrohydraulic Servo Valves (Ehsvs) Market Segmentation
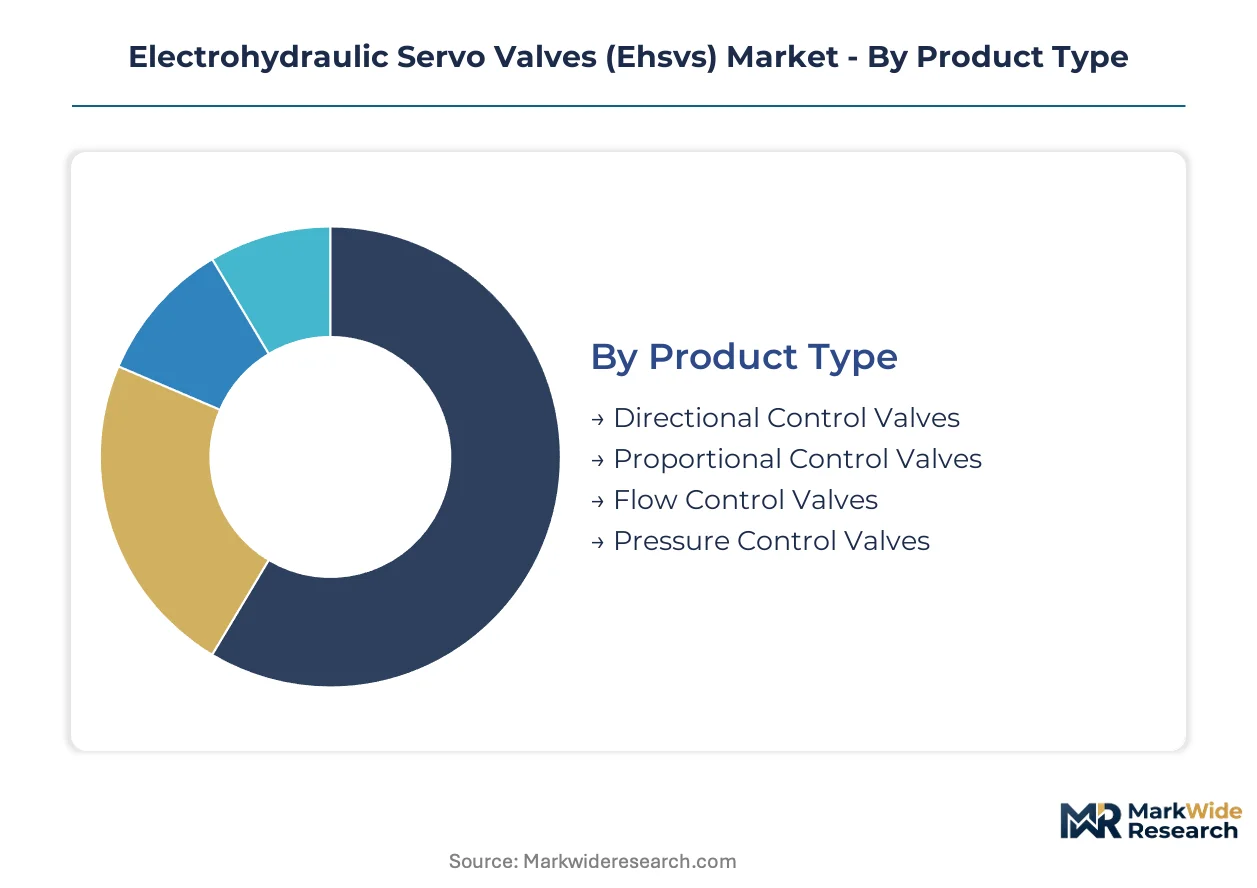
Electrohydraulic servo valve procurement patterns diverge sharply across product architectures and end-use environments. Technical specifications for aerospace flight control systems bear little resemblance to industrial automation requirements, creating distinct qualification barriers and supplier ecosystems within each segment cluster.
Product Type:
Directional control and proportional control valves anchor domestic production in Germany and the United States, while flow and pressure variants flow primarily through export channels serving Asian manufacturing clusters.
- Directional Control Valves:These devices manage hydraulic fluid path selection through spool-positioning mechanisms achieving switching times below 10 milliseconds. German machine tool builders in Stuttgart and Munich specify high-cycle variants for multi-axis positioning systems where rapid directional changes determine throughput. Specialized alloy requirements for spool manufacturing concentrate supply among torque motor specialists with decades of platform experience.
- Proportional Control Valves:Continuous-position spool architectures deliver graduated flow control for force and velocity modulation in closed-loop systems. Industrial automation demand across the German industrial corridor favors these valves for their precision-cost equilibrium in automotive manufacturing equipment. The segment balances performance specifications against qualification burden for mid-tier OEM procurement.
- Flow Control Valves:Metering orifices regulate volumetric delivery independent of load-induced pressure variations. Marine propulsion systems and heavy industrial hydraulics deploy these for constant-speed actuator regulation.
- Pressure Control Valves:Relief and reducing architectures maintain circuit pressure boundaries against pump output fluctuations. Press applications and clamping systems specify these for force-limited operation.
Proportional control valves hold the largest share; momentum sits with smart valve architectures displacing analog legacy in predictive maintenance programs.
End User:
Margin structures stratify across end-use categories, with aerospace commanding qualification premiums and industrial automation driving volume scale through standardized specifications.
- Aerospace:Primary flight control actuation demands fault-tolerant architectures with redundant torque motor paths and debris-tolerant spool designs. FAA airworthiness directives mandate extended qualification cycles that cement sole-source relationships with incumbent suppliers. The U.S. commercial aviation fleet and defense programs sustain decades-long platform contracts with specialized engineering support requirements.
- Industrial Automation:Machine tool and factory automation applications prioritize response bandwidth and positioning repeatability over extreme environmental hardening. German automotive manufacturing clusters specify high-response valves for robotic welding and assembly systems where cycle time determines capital productivity.
- Marine:Subsea and surface vessel hydraulics require corrosion-resistant sealing and pressure-balanced spool architectures for saltwater immersion. Offshore oil and gas infrastructure drives specification for deep-rated actuation systems.
- Robotics:Collaborative and industrial robot joints demand miniaturized valve formats with reduced mass and envelope dimensions. Embedded integration into articulated joint architectures favors compact servo valve derivatives.
Aerospace generates the highest margins; industrial automation delivers the steepest volume expansion trajectory.
Installation:
Physical mounting configurations determine fluid routing complexity and maintenance accessibility across distributed versus centralized hydraulic architectures.
- Inline:Straight-through porting enables direct integration into rigid tubing runs with minimal pressure drop. Mobile equipment and process machinery favor this format for service accessibility.
- Circuit Board Mounted:Miniaturized valve bodies solder or socket onto electronic control boards for integrated electrohydraulic subsystems. Robotics and aerospace distributed actuation specify these for reduced wiring complexity.
- Panel Mounted:Subplate or manifold mounting consolidates multiple valve functions into compact hydraulic power units. Machine tool builders specify these for centralized hydraulic distribution.
- Portable:Self-contained valve-power unit combinations enable field-deployable actuation for maintenance and emergency response. Marine and heavy equipment service applications drive limited demand.
Panel mounted installations dominate stationary industrial equipment; circuit board mounting is climbing fastest in embedded robotics.
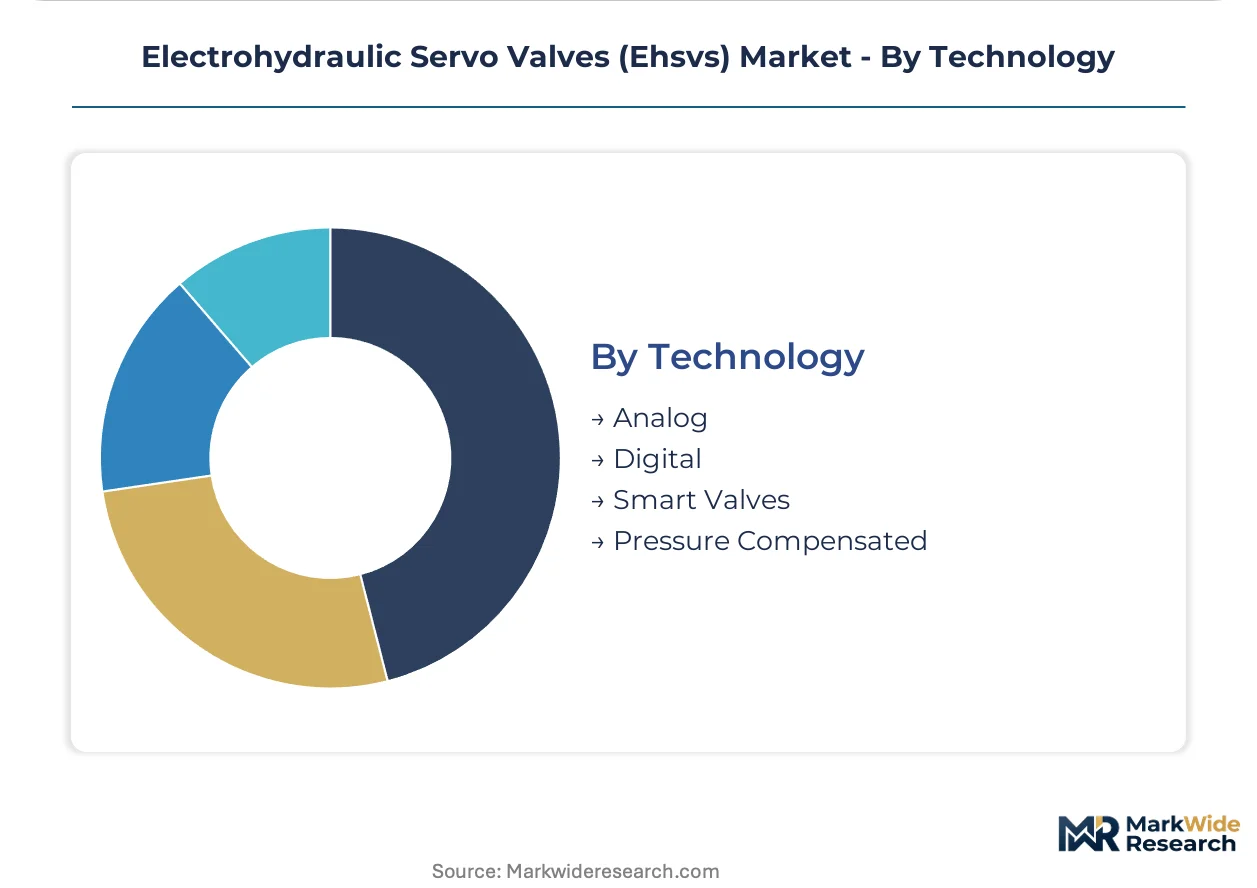
Technology:
Signal processing architectures bifurcate between legacy analog fleets requiring sustained support and digital smart valves enabling predictive diagnostics.
- Analog:Continuous electrical signal conversion through torque motor windings without digital signal processing. Existing aerospace fleets and mature industrial installations sustain replacement demand.
- Digital:Microprocessor-based signal conditioning enables programmable response characteristics and network integration. Industrial automation retrofits specify these for Industry 4.0 compatibility.
- Smart Valves:Embedded pressure, temperature, and position sensors feed edge-computing diagnostics for real-time health monitoring. Continuous-process industries in Germany and Japan are accelerating replacement cycles to capture unplanned downtime reduction.
- Pressure Compensated:Internal load-sensing mechanisms maintain constant flow delivery against varying downstream resistance. Mobile equipment and variable-load industrial applications specify these for consistent actuator velocity.
Analog architectures retain the installed base majority; smart valves are gaining share fastest through subscription-based diagnostics service models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in precision hydraulic components favor established manufacturing clusters with embedded aerospace and automation supply chains. The United States and Germany maintain structural trade surpluses in high-specification servo valves, while Asian markets absorb volume through industrial automation expansion. Regulatory harmonization pressures are reshaping procurement geography as REACH and FAA standards diverge on material qualifications.
United States
Defense aerospace programs and commercial aviation OEMs sustain demand for fault-tolerant valve architectures with redundant torque motor paths. FAA airworthiness directives mandate extended qualification cycles that cement sole-source relationships with incumbent suppliers. The Seattle-Tacoma aerospace cluster and Wichita defense manufacturing corridor concentrate engineering expertise for flight-critical actuation systems.
Germany
Machine tool builders and automotive manufacturing equipment suppliers drive specification of high-response proportional valves for multi-axis positioning systems. EU F-Gas Regulation and REACH material compliance constrain sealing material selection and hydraulic fluid compatibility, forcing reformulation timelines. The Stuttgart-Munich industrial automation corridor anchors domestic procurement for precision manufacturing applications.
China
Domestic aerospace programs and industrial robot manufacturing are localizing procurement requirements for compact servo valve formats. MIIT standards and GB certification protocols for hydraulic components are tightening import substitution pressures. The Yangtze River Delta manufacturing belt is consolidating assembly capacity for mid-tier industrial automation applications.
Japan
Collaborative robot manufacturers and precision assembly equipment builders specify miniaturized valve formats with embedded sensor integration. METI industrial policy supports predictive maintenance technology adoption in continuous-process industries. The Nagoya-Tokyo manufacturing corridor concentrates demand for smart valve architectures with real-time health monitoring capabilities.
India
Production-linked incentive schemes for aerospace and defense manufacturing are localizing procurement requirements for precision hydraulic components. BIS certification protocols for hydraulic equipment are aligning with international qualification standards to enable export competitiveness. The Bangalore-Hyderabad aerospace corridor and Pune industrial automation cluster are emerging as domestic supply chain nodes.
Electrohydraulic Servo Valves (Ehsvs) Market Competitive Landscape
Concentration sits with integrated hydraulic system architects and specialized torque motor designers that sustain decades-long platform relationships. The supplier base compresses around three strategic archetypes: aerospace-qualified incumbents with proprietary electromechanical expertise, diversified industrial automation suppliers leveraging system integration capabilities, and compact-format specialists serving embedded robotics applications. Competitive moves center on diagnostic intelligence integration and geographic expansion through localized certification support.
Among diversified industrial suppliers, Parker Hannifin exemplifies the system-architecture archetype with integrated hydraulic portfolios, while Bosch Rexroth occupies a position in compact-format specialization for space-constrained applications. Moog Inc. anchors the aerospace-qualified tier with torque motor design heritage. Eaton Corporation and Honeywell International sit within diversified technology conglomerates that leverage cross-divisional qualification capabilities. Woodward Inc., HAWE Hydraulik SE, Voith GmbH & Co. KGaA, and Atos SpA represent regional specialists with concentrated expertise in specific end-use verticals or geographic markets.
| Leading Market Players |
|---|
| Moog Inc. |
| Parker Hannifin |
| Bosch Rexroth |
| Eaton Corporation |
| Honeywell International |
| Woodward Inc. |
| HAWE Hydraulik SE |
| Voith GmbH & Co. KGaA |
| Atos SpA |
| Others |
Supply & Pricing Matrix
Scale economies in torque motor winding and spool precision grinding concentrate production among incumbent suppliers with dedicated aerospace qualification facilities, compressing price competition at the premium tier while volume-tier pricing faces input cost volatility from specialized magnetic alloys.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Aerospace-qualified valves with FAA/EASA certification command substantial premiums over industrial automation variants due to extended qualification cycles and sole-source dependencies. Pricing pressure stems from electromechanical substitution in secondary flight control applications, eroding mid-tier hydraulic demand. Machine tool builders in Germany exhibit highest price sensitivity, while defense aerospace programs demonstrate minimal elasticity given mission-critical specifications.
Supply Chain Analysis
The United States and Germany anchor high-specification servo valve production, with China consolidating assembly capacity for mid-tier industrial variants. Torque motor laminations, corrosion-resistant spool alloys, and precision elastomer seals draw from specialized metallurgical and chemical suppliers. Single-source vulnerability concentrates in aerospace-grade magnetic material feedstocks. Distribution runs through authorized distributor networks for industrial automation, with direct OEM supply agreements dominating aerospace procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat environment where FAA/EASA certification entrenchment creates switching costs that lock out unqualified competitors for decades-long platform cycles.
For Market Incumbents: Secure torque motor engineering expertise through targeted retention programs and captive training pipelines, as specialized electromechanical design capabilities concentrate among aging legacy teams. Deepen backward integration into precision alloy supply to insulate margins from commodity volatility in magnetic materials. Electromechanical substitution in lower-force aerospace applications represents the primary displacement threat requiring active monitoring. For New Entrants and Emerging Players: EASA fast-track certification for industrial automation applications offers the most penetrable entry vector, bypassing the decade-long aerospace qualification barriers that protect incumbents. Target collaborative robot manufacturers specifying miniaturized embedded valve formats where space constraints favor compact derivatives over established aerospace-qualified architectures. Cloud-based predictive maintenance service bundling provides differentiation against analog legacy suppliers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors acquisition targets with established torque motor design heritage and active aerospace platform contracts, as smart valve R&D transitions strain uncommitted capital. Long-term viability hinges on balancing legacy fleet support revenue against digital architecture development timelines. Watch for divergence between analog replacement demand peaks and smart valve adoption inflection in German and Japanese precision manufacturing clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Valve Diagnostic Integration | Embedded sensor architectures enable subscription-based uptime guarantees for continuous-process industries in Germany. |
| Aerospace Qualification Expansion | FAA redundant flight control mandates cement sole-source relationships with torque motor specialists possessing platform heritage. |
| Compact Format Miniaturization | Reduced envelope dimensions unlock robotic joint integration previously precluded by hydraulic actuation constraints. |
| Sealing Material Reformulation | REACH compliance timelines force elastomer compound validation for European industrial automation procurement continuity. |
| Predictive Maintenance Service Unbundling | Discrete diagnostics subscriptions fragment traditional bundled contracts in automotive manufacturing clusters favoring total cost of ownership models. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, incorporating flight control system engineers at aerospace OEMs, procurement leads at German machine tool builders, maintenance directors at continuous-process facilities, and aftermarket service heads at hydraulic system distributors. Secondary validation drew from FAA airworthiness directive filings, EASA certification databases, EU REACH compliance registries, and customs trade data for precision hydraulic components. Bottom-up segment sizing triangulated against top-down industry expenditure estimates.
Across the projection horizon, the analytical framework modeled demand by product architecture, end-use environment, installation configuration, and signal processing technology. CAGRs derived from segment-level growth rate synthesis weighted by base-year value shares. Forecast inputs incorporated platform contract renewal timelines at major aerospace programs and replacement cycle acceleration rates for smart valve adoption in predictive maintenance programs.
Underlying assumptions cover sustained FAA/EASA regulatory stringency, stable alloy commodity pricing bands, and gradual electromechanical substitution limited to secondary flight control surfaces, with deviation risk concentrated in REACH material compliance timeline acceleration or abrupt defense procurement reallocation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Valve Driver Market
Valves
Valve Manifold Box (VMB) Market
Valves
Liner Regulators Market
Valves
Pneumatic Slide Gates Market
Valves
Water Draw Off Valves Market
Valves
Global Valves Market
Valves
Angle Opening Ball Locator Market
Valves
Gate Impellers Market
Valves
Air Vent Heads Market
Valves
HVAC Valves Market
Valves
Valve Sack Market
Valves
Pipeline Integrity Management (PIM) Market
Valves
Diaphragm Valve Market
Valves
Fluid Power Cylinder Market
Valves
Fluid Handling Systems Market
Valves
Global Globe Valve Market