
 US Air Filter Market | 2026-2036
US Air Filter Market Size, Share, and Industry Trends Forecast 2026-2036
US Air Filter Market Insights
EPA Clean Air Act enforcement is shifting procurement priorities across commercial real estate portfolios. MANN+HUMMEL leverages its automotive filtration heritage to cross-sell into industrial HVAC retrofits. Donaldson Company anchors its position in heavy-duty engine intake systems while extending into cleanroom applications for semiconductor fabs. Cummins competes aggressively on diesel engine filtration, sustaining aftermarket revenue through dealer network density.
Air filters are porous media assemblies engineered to remove particulate matter, biological contaminants, and gaseous pollutants from airstreams, with MERV ratings and HEPA certification defining capture efficiency thresholds down to 0.3 microns. Their primary purpose spans occupant health protection, equipment longevity, and process contamination control across enclosed environments. HEPA and activated carbon product types dominate hospital and wildfire-smoke applications respectively, while HVAC Systems application volume outpaces cleanroom demand on unit economics despite lower per-unit pricing. Nanotechnology filtration remains nascent but occupies the highest margin tier as manufacturers position hybrid passive-active systems for premium residential and commercial segments.
ASHRAE Standard 62.1, EPA National Ambient Air Quality Standards, and OSHA workplace exposure limits collectively mandate minimum filtration performance across commercial, industrial, and institutional buildings. The Department of Energy enforces efficiency requirements that filter pressure-drop specifications must satisfy to qualify for federal building retrofit funding. Stakeholders must monitor state-level wildfire smoke emergency declarations and corresponding temporary filtration upgrades, as these events create surge demand that strains distributor inventory and manufacturing capacity.
Market Dynamics
ASHRAE Standard 62.1 revisions and EPA indoor air quality enforcement are compressing replacement cycles across commercial building portfolios while concentrating specification authority in MEP engineering firms.
Growth Catalysts
- Hospital HVAC Retrofit Mandates:CMS facility guidelines and Joint Commission accreditation standards require MERV-14 minimum filtration in acute care settings, forcing capital deployment across Midwest and Southeast health systems.
- Wildfire Smoke Emergency Protocols:State-level emergency declarations in California, Oregon, and Washington trigger temporary filtration upgrades in schools and municipal buildings, creating surge demand for activated carbon and HEPA configurations.
- Semiconductor Fab Construction:CHIPS Act subsidies accelerate cleanroom buildouts in Arizona, Texas, and New York, pulling ultra-low particulate filtration into multi-year supply contracts.
Market Restraints
- Glass Microfiber Supply Concentration:Three domestic manufacturers control borosilicate media production, exposing filter assemblers to price volatility and allocation risk during capacity constraints.
- Pressure-Drop Energy Penalty:Higher MERV ratings increase fan energy consumption, creating tension with Department of Energy efficiency mandates for federal building retrofits.
- Electrostatic Precipitator Competition:Washable electronic filtration systems capture share in industrial metalworking and welding applications where particulate loading is continuous and labor costs favor reusable media.
Strategic Opportunities
- Texas Gulf Coast Petrochemical Corridor:New ethylene and derivative capacity under construction requires corrosion-resistant filtration for coastal humidity and chemical vapor exposure, a specification gap for incumbent HVAC-focused suppliers.
- IRA-Eligible Residential Upgrades:Inflation Reduction Act tax credits for energy-efficient home improvements subsidize smart filter subscriptions with IoT pressure-drop monitoring, opening direct-to-consumer channels.
- Pharmaceutical Continuous Manufacturing:FDA guidance on real-time release testing creates demand for in-line particle monitoring integrated with filtration systems, converging sensor and media technologies.
Industry Challenges
- ASHRAE 52.2 Test Method Variability:Laboratory-to-laboratory MERV rating inconsistencies create specification disputes between manufacturers and MEP engineers, delaying project approvals.
- Legacy Building Infrastructure Compatibility:Aging air handlers in public school districts and municipal buildings lack static pressure capacity for high-efficiency retrofits, requiring costly fan upgrades or bypass compromises.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Air Filter Market |
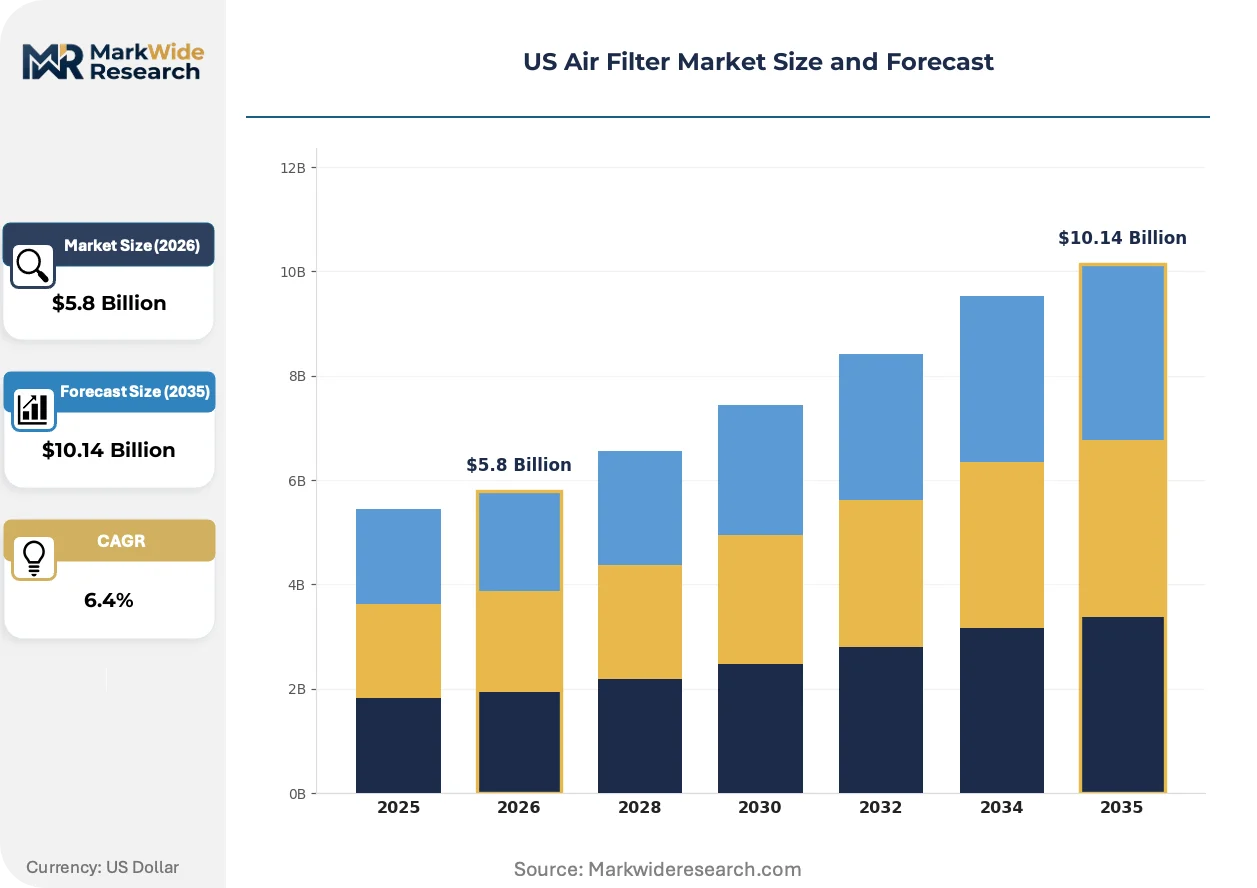
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HEPA, Activated Carbon, Electrostatic, Ultraviolet End User: Residential, Commercial, Industrial, Automotive Technology: Passive, Active, Hybrid, Nanotechnology Application: Air Purification, HVAC Systems, Respiratory Protection, Clean Rooms |
| Companies Covered | MANN+HUMMEL, Daikin Industries, Ltd., 3M Company, American Air Filter Company, Inc., Camfil, Donaldson Company, Inc., Cummins Inc., Freudenberg Filtration Technologies, Parker Hannifin Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Air Filter Market Trends and Innovations
Active filtration systems with embedded sensors and predictive maintenance algorithms are displacing passive replacement schedules in premium commercial segments. Material science advances and regulatory stringency are compressing the viable lifecycle of conventional media.
Nanofiber surface-loading technology is absorbing sub-micron particulate capture demand from glass microfiber depth-loading media in healthcare and semiconductor applications. Hospital infection control committees and fab process engineers specify nanofiber layers for extended service intervals and reduced pressure-drop degradation. This absorption is compressing commodity fiberglass market share in high-specification segments while creating tiered pricing architecture around performance durability.
EPA enforcement of the Clean Air Act's residual risk provisions tightens permissible emissions from industrial coating and solvent operations, mandating activated carbon filtration with specified minimum empty bed contact times. Paint and adhesive manufacturers in California, Texas, and Ohio face compliance deadlines that require carbon replacement tracking and documentation. Metal fabrication and automotive refinishing shops absorb the capital burden while filter service providers capture recurring media changeout revenue.
Engineering-procurement-construction firms consolidate specification authority through design-build contracts and long-term facility management agreements, disintermediating traditional distributor relationships. Large commercial real estate owners in Florida, Arizona, and Nevada negotiate enterprise filter supply agreements with national service providers. This concentration shifts margin capture from product manufacturing toward installation labor and predictive maintenance software subscriptions.
US Air Filter Market Segmentation
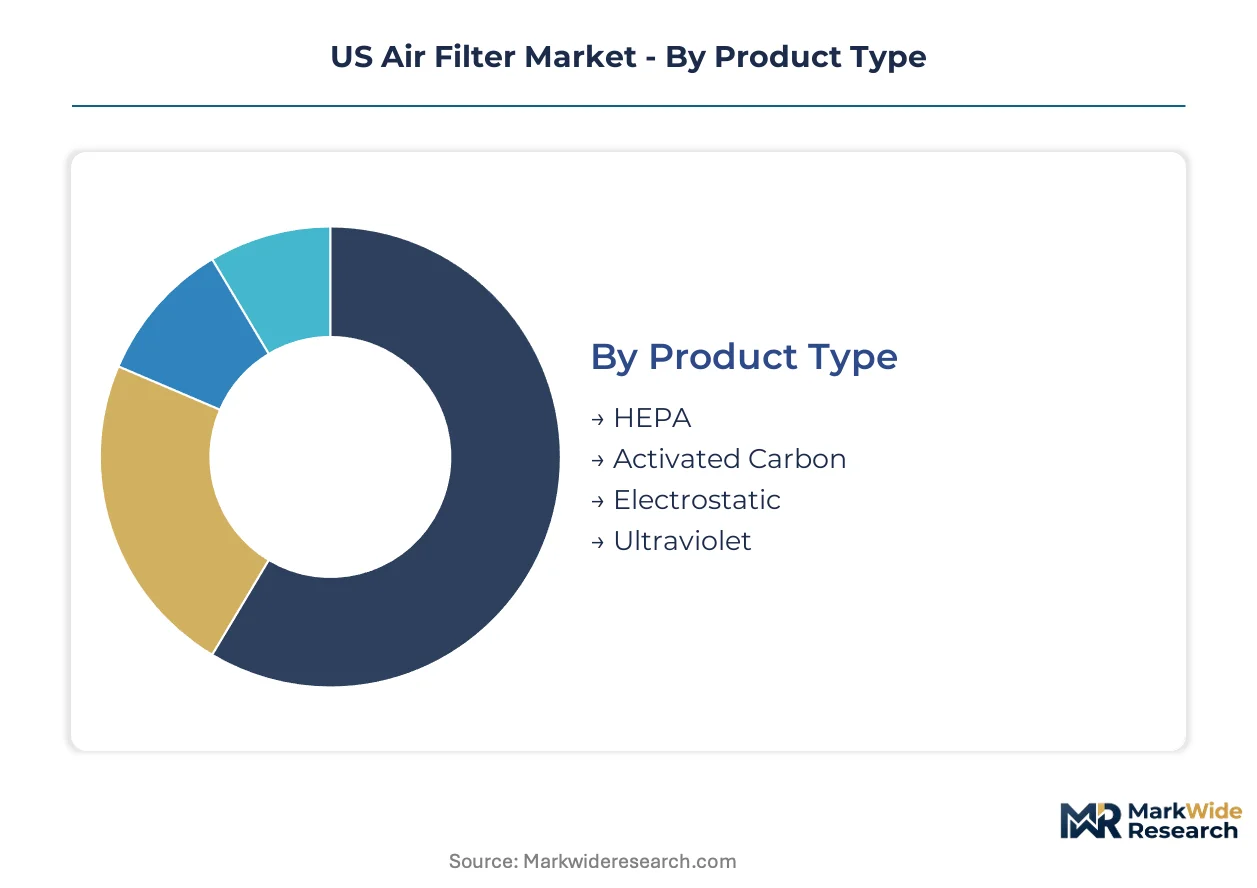
Filter specification authority concentrates in distinct buyer archetypes across the US market. Product certification requirements, end-use liability exposure, and application-specific pressure-drop constraints fragment procurement behavior into non-interchangeable segments.
Product Type:
Buyers differentiate primarily by capture efficiency thresholds and media replacement economics rather than upfront unit cost.
- HEPA:Borosilicate microfiber assemblies certified to 99.97% efficiency at 0.3 microns. Hospital infection control committees in the Midwest and Southeast specify MERV-17+ configurations for operating suites, driven by Joint Commission accreditation deadlines.
- Activated Carbon:Impregnated granular or bonded fiber media engineered for molecular adsorption of VOCs and ozone. Wildfire emergency protocols in California, Oregon, and Washington trigger surge procurement for municipal building upgrades when AQI exceeds 150.
- Electrostatic:Charged synthetic fibers that enhance particulate capture without dense media packing. Metal fabrication shops in Ohio and Michigan favor washable configurations for welding fume extraction where labor rates justify cleaning cycles.
- Ultraviolet:UV-C lamp arrays integrated downstream of particulate stages for biological inactivation. Texas healthcare construction projects specify these for ambulatory surgical centers facing CMS facility guideline updates.
HVAC Systems leads volumes today; HEPA is gaining share fastest.
End User:
Procurement sophistication scales with regulatory exposure and portfolio standardization pressure.
- Commercial:Property management firms and EPC contractors negotiate enterprise supply agreements spanning multi-state portfolios. Florida, Arizona, and Nevada commercial real estate owners centralize specification authority through design-build contracts that disintermediate traditional distributors.
- Industrial:Continuous-process manufacturers specify corrosion-resistant configurations for chemical vapor exposure. Ethylene derivative capacity under construction along the Texas Gulf Coast requires coastal humidity-rated media not addressed by incumbent HVAC suppliers.
- Residential:IRA tax credits subsidize smart filter subscriptions with IoT pressure-drop monitoring, opening direct-to-consumer channels for premium replacement cycles.
- Automotive:Cabin air filtration follows vehicle platform refresh schedules with aftermarket capture through dealer network density.
Commercial dominates absolute unit volume; residential subscription models are climbing the fastest.
Technology:
Capital deployment intensity separates buyers pursuing predictive maintenance integration from those optimizing first-cost procurement.
- Passive:Conventional depth-loading media with fixed replacement intervals. Public school districts in legacy buildings rely on these where aging air handlers lack static pressure capacity for higher-efficiency alternatives.
- Active:Sensor-embedded systems with predictive algorithms displacing calendar-based changeouts. Premium commercial segments in Manhattan and Chicago adopt these for facility management labor cost reduction.
- Hybrid:Combined passive-active architectures balancing capture efficiency with energy penalty mitigation. Semiconductor fabs in Arizona and Texas specify these for multi-year supply contract security.
- Nanotechnology:Surface-loading nanofiber layers capturing sub-micron particulate with extended service intervals. Hospital infection control committees and fab process engineers absorb these despite 40-60% price premiums over glass microfiber.
Passive retains installed base dominance; nanotechnology shows the steepest expansion trajectory.
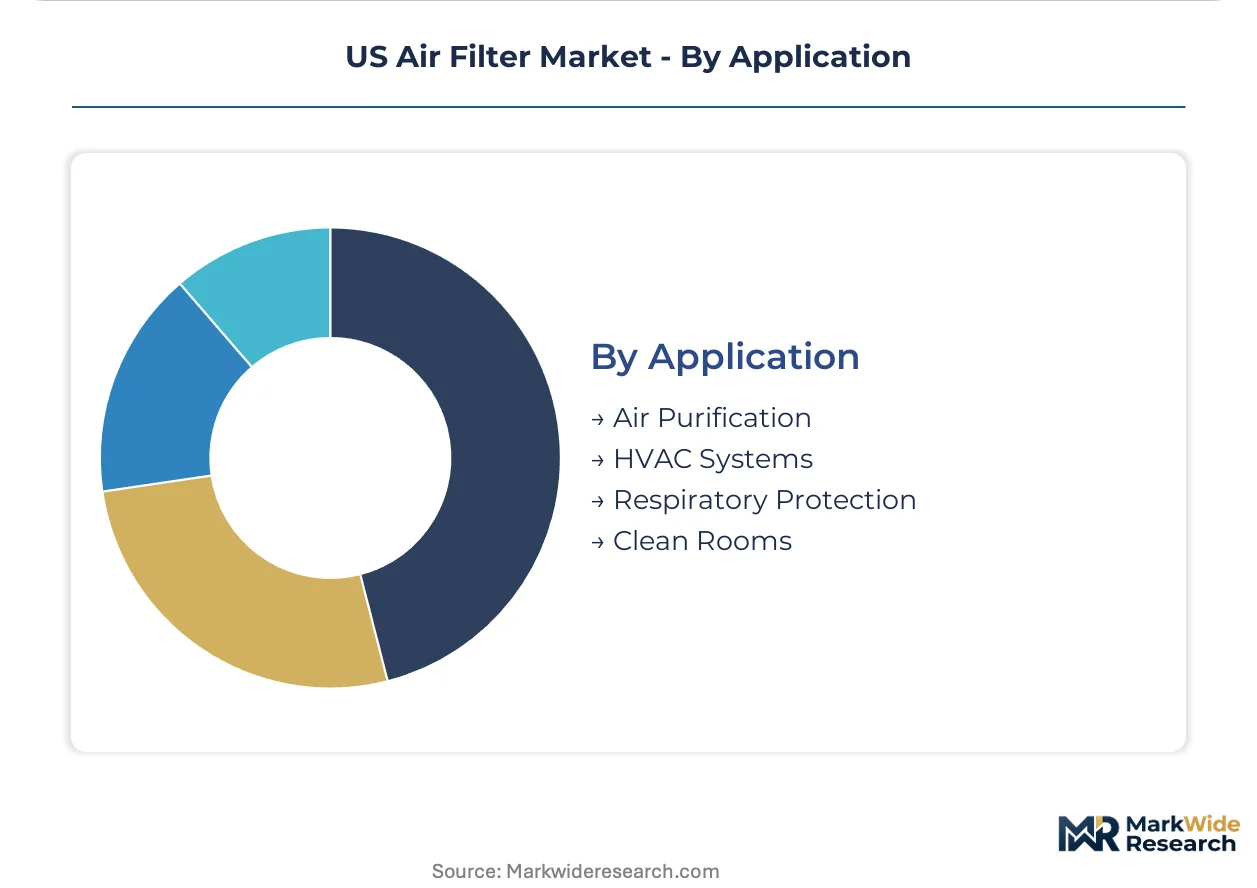
Application:
Specification authority concentrates where contamination control carries liability or process yield consequences.
- HVAC Systems:Building-integrated filtration for occupant health and equipment protection. ASHRAE Standard 62.1 revisions compress replacement cycles across commercial portfolios while concentrating authority in MEP engineering firms.
- Clean Rooms:Ultra-low particulate environments for semiconductor and pharmaceutical manufacturing. CHIPS Act subsidies pull Arizona, Texas, and New York fabs into multi-year filtration supply contracts with specified minimum efficiency guarantees.
- Air Purification:Standalone portable and fixed installations for residential and light commercial spaces. Wildfire smoke emergency declarations create inventory strain that distributors address through regional safety stock positioning.
- Respiratory Protection:Personal and fixed-source capture for occupational exposure control. OSHA workplace exposure limits mandate minimum performance in metalworking and coating operations.
HVAC Systems anchors current revenue; cleanroom applications command the highest per-unit margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Air filtration manufacturing first achieved industrial scale in the United States during the mid-20th century, when defense and aerospace applications demanded particulate control standards that later transferred to commercial HVAC and healthcare sectors. The industry's geographic footprint now concentrates where regulatory stringency, construction activity, and semiconductor investment intersect.
Texas
Petrochemical expansion along the Gulf Coast drives demand for corrosion-resistant filtration media in ethylene derivative facilities. EPA residual risk enforcement tightens emissions controls for coating and solvent operations statewide. CHIPS Act subsidies pull semiconductor cleanroom construction into Arizona and Texas border zones, with Dallas-Fort Worth fabs specifying multi-year supply contracts.
California
Wildfire smoke emergency protocols trigger surge procurement for activated carbon and HEPA configurations when AQI exceeds 150. The state's Air Resources Board mandates increasingly stringent indoor air quality thresholds for public buildings. Bay Area semiconductor fabs and Los Angeles commercial real estate portfolios centralize specification authority through design-build contracts.
Florida
Commercial construction and healthcare facility expansion concentrate filtration demand in Miami-Dade and Orange County corridors. ASHRAE Standard 62.1 revisions compress replacement cycles across hospital HVAC systems seeking Joint Commission accreditation. Large property management firms negotiate enterprise supply agreements that disintermediate traditional distributor channels.
Midwest
Hospital HVAC retrofit mandates across Illinois, Michigan, and Ohio force capital deployment for MERV-14 minimum filtration in acute care settings. Aging public school infrastructure struggles with static pressure capacity for high-efficiency retrofits. Cleveland and Detroit metal fabrication shops favor washable electrostatic configurations for welding fume extraction.
Pacific Northwest
Oregon and Washington state-level emergency declarations create inventory strain for municipal building filtration upgrades during wildfire season. Seattle and Portland commercial real estate owners adopt sensor-embedded active systems for facility management labor cost reduction. The region's semiconductor equipment suppliers specify nanofiber surface-loading technology for extended service intervals.
US Air Filter Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across distinct specification tiers. The market structure consolidates around diversified industrial conglomerates with captive distribution networks, while specialized filtration pure-plays occupy premium niches. Three strategic archetypes dominate: automotive-heritage suppliers cross-selling into HVAC retrofits, heavy-duty engine filtration specialists extending into cleanroom applications, and diversified industrial conglomerates leveraging scale for national service contracts. Competitive moves concentrate on strategic partnerships with engineering-procurement-construction firms and portfolio diversification into predictive maintenance software subscriptions.
Among German-heritage filtration specialists, MANN+HUMMEL and Freudenberg Filtration Technologies occupy positions that exemplify cross-sector technology transfer from automotive into industrial HVAC. Donaldson Company anchors the heavy-duty engine filtration archetype while representing extension strategies into contamination-controlled environments. These three entities sit within the tier characterized by manufacturing depth and established specification relationships with MEP engineering firms.
| Leading Market Players |
|---|
| MANN+HUMMEL |
| Daikin Industries, Ltd. |
| 3M Company |
| American Air Filter Company, Inc. |
| Camfil |
| Donaldson Company, Inc. |
| Cummins Inc. |
| Freudenberg Filtration Technologies |
| Parker Hannifin Corporation |
| Others |
Pricing and Supply Chain Analysis
Borosilicate glass microfiber pricing indices cascade through three distinct procurement tiers, compressing margins for commodity HVAC assemblers while amplifying returns for nanofiber-certified suppliers serving semiconductor fabs and hospital infection control committees.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates nanofiber-enhanced HEPA configurations from commodity fiberglass depth-loading media and washable electrostatic alternatives. Certification grade under ASHRAE 52.2 and MERV rating precision create the primary price differentiation, with volume scale secondary for national service contract negotiations. Cost compression in standard-grade fiberglass is intensifying because glass microfiber supply concentration exposes assemblers to allocation risk during capacity constraints. Public school districts and legacy municipal buildings exhibit the highest price sensitivity, while semiconductor fabs and acute care hospitals absorb 40-60% premiums for extended service interval guarantees.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from semiconductor fabs and hospital systems, while regional distributors serve fragmented commercial real estate portfolios and municipal accounts. Manufacturing draws from domestic borosilicate microfiber production concentrated in Ohio, Pennsylvania, and South Carolina, with activated carbon media sourcing from coconut shell suppliers in Sri Lanka, Indonesia, and the Philippines. Single-source vulnerability in pharmaceutical-grade HEPA certification creates supply chain risk for cleanroom construction timelines. Distribution runs through engineering-procurement-construction firms consolidating specification authority in Florida, Arizona, and Nevada commercial portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on nanofiber technology absorption compressing commodity fiberglass share, with IRA-subsidized smart filter subscriptions opening premium recurring revenue channels.
For Market Incumbents: Acquire predictive maintenance software platforms to capture facility management labor cost reduction budgets in Manhattan and Chicago commercial portfolios. Consolidate specification authority through design-build contract partnerships with EPC firms, defending against electrostatic precipitator competition in metalworking applications by embedding IoT pressure-drop monitoring into hybrid passive-active system offerings. For New Entrants and Emerging Players: Engineering-procurement-construction firms represent the most penetrable channel partner type for bypassing entrenched distributor relationships. Target Texas Gulf Coast petrochemical corridor greenfield construction for corrosion-resistant filtration specifications unaddressed by incumbent HVAC-focused suppliers, leveraging CHIPS Act cleanroom demand in Arizona and Texas for multi-year supply contract entry. For Investors and Strategic Acquirers: Asymmetric upside sits with nanofiber surface-loading technology specialists serving hospital infection control and semiconductor fab process engineering segments. Long-term viability over a multi-year horizon favors acquisition targets with captive borosilicate microfiber supply relationships or backward integration into pharmaceutical-grade HEPA certification capabilities. Watch for state-level wildfire smoke emergency declaration frequency as inflection indicator for activated carbon surge demand capacity investments.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Acquisition | Captures facility management software budgets displacing calendar-based filter replacement schedules. |
| CHIPS Act Cleanroom Supply Contract | Locks in multi-year revenue with Arizona and Texas semiconductor fabs requiring ultra-low particulate guarantees. |
| IRA-Eligible Smart Filter Subscription Launch | Opens direct-to-consumer channels subsidized by federal energy-efficient home improvement tax credits. |
| Nanofiber Surface-Loading R&D Investment | Absorbs sub-micron particulate demand from glass microfiber in healthcare and semiconductor applications. |
| Texas Gulf Coast Petrochemical Specification | Addresses corrosion-resistant media gap for coastal humidity and chemical vapor exposure in ethylene derivative facilities. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with MEP engineering firm specification leads, hospital infection control committee directors, semiconductor fab process engineers, commercial real estate portfolio managers, and activated carbon distributor inventory planners. Secondary validation drew from EPA enforcement action databases, ASHRAE standard revision documentation, CHIPS Act subsidy award filings, and state-level wildfire emergency declaration records. Bottom-up unit economics modeling and top-down market sizing triangulated across product type, end user, technology, and application segmentation dimensions.
Segment-weighting approaches applied differential growth assumptions across the projection horizon based on regulatory enforcement intensity, construction activity concentration, and technology substitution elasticities. HVAC Systems, cleanroom, air purification, and respiratory protection applications each carried distinct margin and replacement cycle parameters. CAGRs were derived from installed base turnover rates, new construction filtration content per square foot, and emergency procurement surge patterns. Wildfire smoke emergency protocol frequency and CMS facility guideline revision timelines served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to glass microfiber supply allocation disruptions, ASHRAE 52.2 test method standardization delays, and electrostatic precipitator technology cost-performance improvements. Forecasts reflect assumptions around IRA tax credit continuity, CHIPS Act fab construction timelines, and EPA residual risk enforcement pacing. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Global Electric Power Substation Automation Market
Electrical Power Equipment
Magneto Optic Current Transformer Market
Electrical Power Equipment
AC-DC Controller Market
Electrical Power Equipment
SF6 Gas Circuit Breaker Market
Electrical Power Equipment
Packaged Substation Market
Electrical Power Equipment
North America Power Inverter Market
Electrical Power Equipment
North America Surge Arresters Market
Electrical Power Equipment
Hollow Core Insulator Market
Electrical Power Equipment
AC Residential Switchgear Market
Electrical Power Equipment
Magnetic Ballast Market
Electrical Power Equipment
Industrial Power Supply Market
Electrical Power Equipment
Low Voltage Protection Control Market
Electrical Power Equipment
Unitary Heaters Market
Electrical Power Equipment
Frameless Brushless DC Motors Market
Electrical Power Equipment
MV Protection Relay Market
Electrical Power Equipment
South America Air Insulated Switchgear Market