

Supply Stop Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Supply Stop Valves Market Insights
Commercial building HVAC retrofit activity is pivoting toward higher-specification supply stop valves as energy efficiency mandates tighten across developed economies. Emerson Electric leverages its automation portfolio to integrate smart valve actuation into building management systems. Honeywell International sustains channel dominance through spec-grade brass and stainless steel product lines. Siemens competes on digital twin compatibility, positioning its valve offerings within predictive maintenance architectures.
Supply stop valves are mechanical flow control devices that completely halt fluid passage through a piping system, typically rated for pressures from 150 to 600 psi and temperatures spanning -20°F to 450°F depending on seal elastomer and body material selection. Ball valve configurations dominate residential and light commercial installations due to quarter-turn operation reliability and compact form factors, while globe valves retain structural preference in chemical processing where precise throttling accompanies shutoff duty. Stainless steel material grades command premium positioning in corrosive service environments, whereas brass maintains volume leadership in potable water applications subject to lead-content restrictions.
EPA Lead and Copper Rule provisions, EU Drinking Water Directive revisions, and ISO 5752 face-to-face dimension standards collectively dictate material eligibility, testing protocols, and dimensional interchangeability for cross-border project supply. Municipal procurement departments in Germany and the United States increasingly require third-party NSF/ANSI 61 certification and CE marking documentation as baseline qualification thresholds. Stakeholders must monitor evolving lead-content thresholds and corresponding alloy reformulation timelines to avoid inventory obsolescence in regulated jurisdictions.
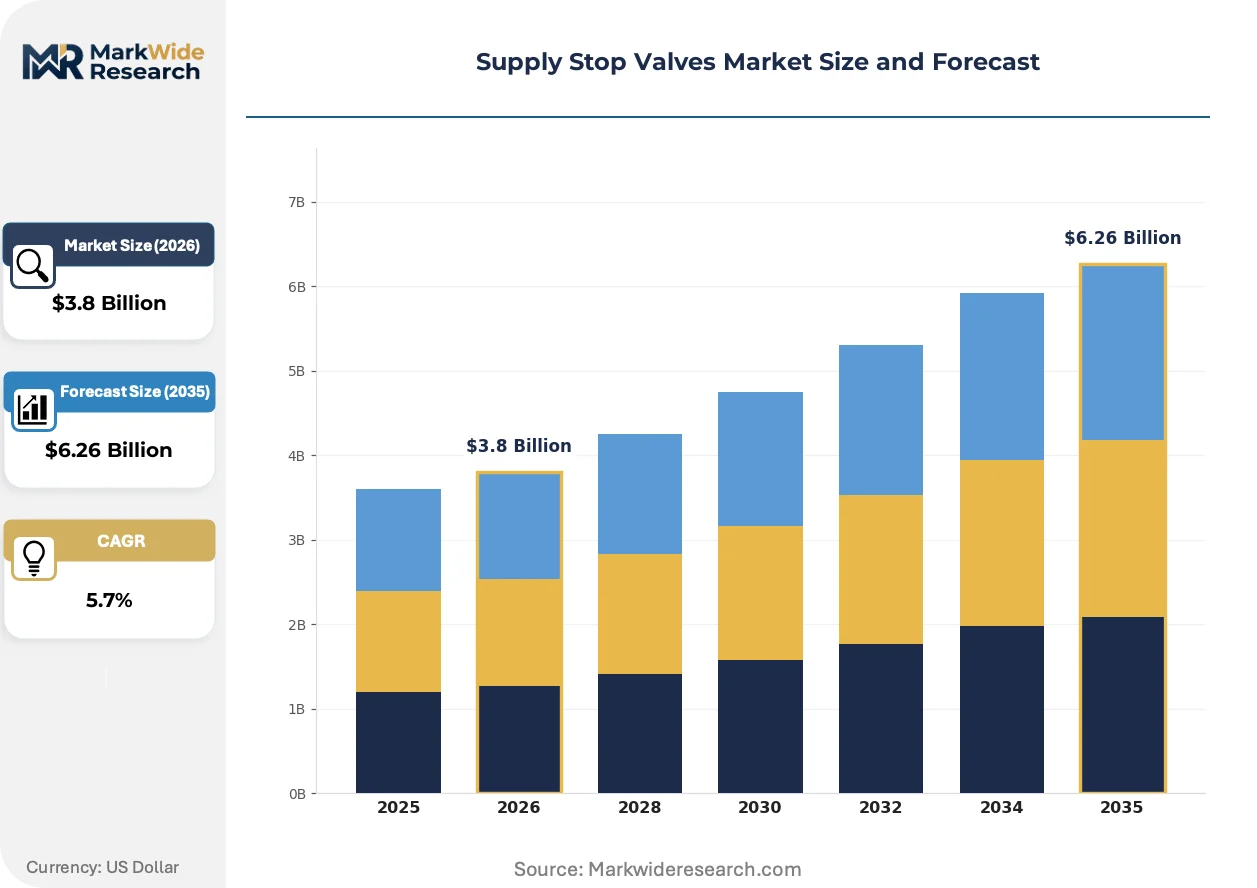
Market Dynamics
Material compliance mandates are compressing product lifecycles across the Supply Stop Valves Market as EPA Lead and Copper Rule revisions and EU Drinking Water Directive updates force alloy reformulation investments. Brass suppliers face immediate recertification deadlines while stainless steel producers capture specification upgrades in corrosive service segments.
Growth Catalysts
- EPA Lead and Copper Rule:Revised lead-content thresholds in the United States are accelerating replacement cycles in municipal water infrastructure and residential plumbing systems.
- HVAC retrofit mandates:Germany's building energy efficiency regulations are sustaining above-average valve replacement rates in commercial heating and cooling networks.
- Stainless steel corrosion resistance:Chemical processing capacity expansions in industrial corridors are specifying super-austenitic grades for aggressive fluid handling.
Market Restraints
- Copper and zinc price volatility:Brass body production faces margin pressure from London Metal Exchange commodity swings and concentrate supply disruptions.
- Foundry concentration in China:Casting capacity geographic clustering creates tariff exposure and logistics vulnerability for North American and European valve assemblers.
- Polymer composite substitution:PEX manifold systems with integrated shutoff functions are displacing discrete valve installations in residential new construction.
Strategic Opportunities
- Smart building integration:IoT-enabled valve position monitoring converges with building management system architectures in commercial real estate.
- India municipal water programs:AMRUT scheme funding is opening specification-grade procurement channels for brass and ductile iron variants.
- CE marking harmonization:Unified EU conformity assessment is reducing cross-border certification duplication for valve exporters.
Industry Challenges
- NSF/ANSI 61 certification timelines:Third-party testing backlogs extend product launch schedules by six to twelve months in regulated potable water markets.
- Legacy system integration:Digital twin compatibility requirements demand protocol adaptation for predictive maintenance deployment in brownfield industrial sites.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Supply Stop Valves Market Trends and Innovations
Valve architecture is pivoting toward connected functionality as building automation and industrial IoT architectures demand real-time flow state visibility. Material science advances and regulatory chemistry restrictions are simultaneously reshaping body and seal specifications.
Smart actuation is absorbing position feedback and remote shutoff capabilities into supply stop valve designs. Facility managers in commercial real estate portfolios are specifying networked valves at accelerating rates. This convergence is absorbing traditional mechanical valve margins into building automation system contracts and service agreements.
REACH substance restrictions are eliminating certain elastomer compounds from potable water contact applications. ECHA candidate list updates are forcing seal manufacturers toward hydrogenated nitrile and perfluoroelastomer alternatives. German municipal procurement departments are now requiring full material disclosure documentation as baseline bid qualification.
Maintenance cycle compression is shortening planned replacement intervals in critical infrastructure. Water utilities in the United States are moving from reactive repair to predictive replacement schedules based on installation age records. This behavioral shift is concentrating demand into specialized contractors with asset database integration capabilities.
Supply Stop Valves Market Segmentation
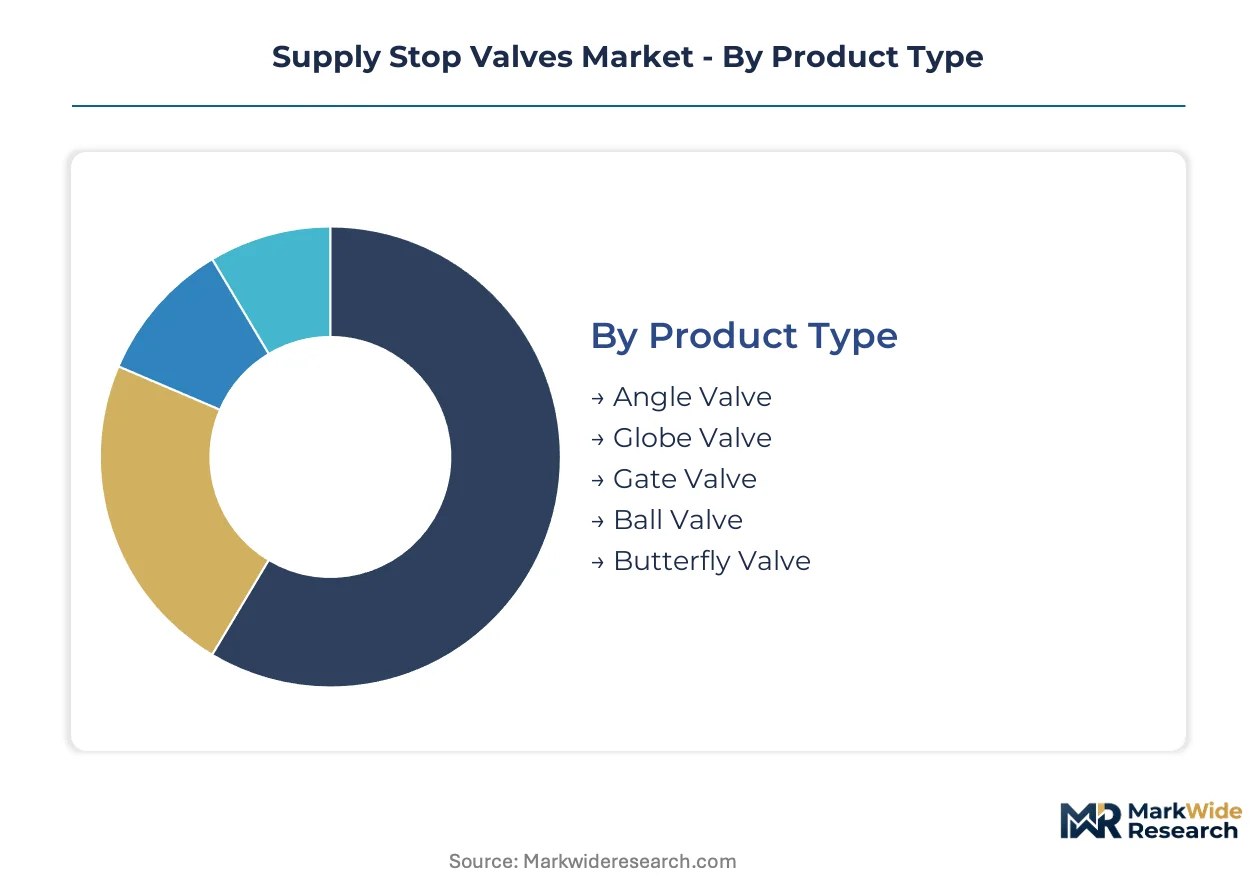
Supply stop valve procurement follows distinct technical and commercial logics across product architectures, material grades, and end-use environments. Specification engineers weight pressure ratings, corrosion resistance, and regulatory compliance differently depending on installation context.
Product Type:
Quarter-turn operation reliability dominates buyer specifications in residential and light commercial channels, while throttling precision commands premium positioning in industrial process applications.
- Ball Valve:Quarter-turn shutoff mechanism delivers fail-safe sealing across 150-600 psi pressure ranges. Municipal water infrastructure upgrades in Germany and the United States specify brass and stainless steel ball valve configurations to meet EPA Lead and Copper Rule and EU Drinking Water Directive material thresholds.
- Globe Valve:Linear stem motion enables precise flow modulation alongside positive shutoff duty. Chemical processing capacity expansions in Germany's industrial corridor sustain above-average replacement rates for globe valve architectures in aggressive fluid handling service.
- Gate Valve:Full-bore straight-through design minimizes pressure drop in high-flow water transmission mains.
- Angle Valve:90-degree port configuration suits confined installation spaces in residential plumbing risers.
- Butterfly Valve:Compact wafer body format addresses large-diameter HVAC and irrigation applications with weight-sensitive specifications.
Ball valve configurations lead on installation scale across residential and commercial building stock; globe valve specifications lead on replacement momentum in chemical processing and refining infrastructure.
Material:
Regulatory chemistry restrictions and corrosion service requirements are compressing viable material options, with lead-content mandates forcing alloy reformulation investments across foundry networks.
- Brass:Copper-zinc alloys maintain volume leadership in potable water applications subject to lead-content restrictions. EPA Lead and Copper Rule revisions in the United States and EU Drinking Water Directive updates are compelling brass suppliers toward immediate recertification deadlines and low-lead alloy transitions.
- Stainless Steel:Austenitic and super-austenitic grades deliver corrosion resistance in aggressive chemical and marine environments. Chemical processing capacity expansions specify stainless steel for chloride-bearing and acidic fluid handling where brass degradation risks accelerate failure modes.
- Bronze:Legacy copper-tin compositions face procurement phase-out as lead-content thresholds tighten across North American and European jurisdictions.
- Cast Iron:Ductile iron variants address cost-sensitive municipal water and fire protection infrastructure at pressure ratings below 250 psi.
- PVC:Thermoplastic construction serves irrigation and non-potable drainage applications with low-pressure, low-temperature specifications.
Brass maintains the broadest installed base; stainless steel is climbing the fastest as specification upgrades accelerate in corrosive service segments.
Application:
Energy efficiency mandates and infrastructure replacement cycles are diverting procurement volumes toward HVAC retrofit and municipal water upgrade channels.
- Water Supply:Municipal distribution networks and residential plumbing systems require lead-compliant shutoff devices at service entry points and branch take-offs. EPA Lead and Copper Rule enforcement is accelerating replacement cycles in legacy bronze valve installations across United States water utilities.
- HVAC Systems:Commercial building heating and cooling networks demand specification-grade valves for hydronic balancing and isolation duty. Germany's building energy efficiency regulations sustain above-average valve replacement rates as retrofit contractors upgrade circulation loop controls.
- Chemical Processing:Aggressive fluid handling specifies corrosion-resistant alloys and specialized seal elastomers.
- Fire Protection:Standpipe and sprinkler system codes mandate reliable shutoff capability with tamper-evident features.
- Irrigation:Agricultural and landscape water distribution prioritizes cost-efficient thermoplastic and cast iron configurations.
Water supply applications command the largest replacement volume; HVAC systems are gaining share fastest as energy efficiency mandates tighten across developed economies.
End User:
Procurement sophistication varies sharply across customer types, with municipal buyers enforcing third-party certification requirements that residential channels often bypass.
- Municipal Facilities:Water utilities and wastewater treatment authorities require NSF/ANSI 61 certification and CE marking documentation as baseline qualification thresholds. United States and German municipal procurement departments are moving from reactive repair to predictive replacement schedules based on installation age records.
- Commercial Buildings:Facility managers in real estate portfolios are specifying networked valves with IoT-enabled position monitoring at accelerating rates. Building automation system integration is absorbing traditional mechanical valve margins into service contracts.
- Residential Complexes:Multi-family construction and renovation drives volume demand for ball valve and angle valve configurations in plumbing riser and unit isolation applications.
- Manufacturing Plants:Process industry maintenance departments specify corrosion-resistant materials for chemical, pharmaceutical, and food processing line isolation.
Municipal facilities anchor procurement scale through infrastructure replacement programs; commercial buildings are expanding most quickly as smart building integration requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as foundry capacity migrates toward jurisdictions with lower compliance-cost burdens for lead-free alloy reformulation.
United States
EPA Lead and Copper Rule enforcement is accelerating municipal water infrastructure replacement cycles across legacy bronze valve installations. Water utilities in California, Texas, and the Great Lakes region are shifting procurement toward NSF/ANSI 61 certified brass and stainless steel variants. The Rust Belt manufacturing corridor retains foundry concentration for ductile iron fire protection valves serving North American distribution networks.
Germany
Building energy efficiency regulations under the EU Green Deal are sustaining above-average HVAC retrofit activity in commercial heating and cooling networks. ECHA REACH substance restrictions are eliminating certain elastomer compounds from potable water contact specifications. The industrial corridor spanning North Rhine-Westphalia and Baden-Württemberg anchors chemical processing capacity expansions specifying super-austenitic stainless steel for aggressive fluid handling.
China
GB standards alignment with ISO face-to-face dimension specifications is expanding export qualification for valve assemblers serving Belt and Road infrastructure projects. NMPA and MEE oversight of drinking water contact materials is tightening domestic market entry requirements. The Yangtze River Delta and Pearl River Delta clusters concentrate casting capacity for brass and bronze body production serving global supply chains.
India
AMRUT scheme funding is opening specification-grade procurement channels for brass and ductile iron variants in municipal water distribution upgrades. BIS certification requirements for potable water contact materials are compressing product launch timelines for imported valve assemblies. Maharashtra and Gujarat industrial zones are attracting foundry investments targeting domestic replacement demand and Middle East export markets.
Japan
METI building energy efficiency standards are driving HVAC system modernization in Tokyo and Osaka commercial real estate portfolios. JIS standards alignment with ISO dimensional specifications facilitates cross-border project supply for regional contractors. The Kanto and Kansai manufacturing belts maintain precision machining capabilities for high-specification process industry valve applications.
Supply Stop Valves Market Competitive Landscape
Capacity expansion dominates the current landscape as brass suppliers race to recertify low-lead alloy formulations ahead of EPA and EU enforcement deadlines. The vendor base stratifies across three tiers: multinational automation conglomerates with building management system integration capabilities; mid-scale regional specialists with foundry-to-assembly vertical control; and commodity assemblers dependent on Chinese casting supply. Strategic archetypes include smart building enablers, corrosion-resistant material specialists, and municipal certification-focused fabricators. M&A activity and geographic diversification of casting supply are the dominant competitive moves as tariff exposure and logistics vulnerability reshape sourcing strategies.
Among automation-integrated conglomerates, Emerson Electric, Honeywell International, and Siemens exemplify the convergence of mechanical valve portfolios with digital building infrastructure. These entities occupy positions where traditional component margins are absorbed into system-level contracts and predictive maintenance service agreements. Their archetype represents the premium tier where IoT-enabled position monitoring and building management system compatibility command specification preference in commercial real estate and industrial facility deployments.
| Leading Market Players |
|---|
| Emerson Electric |
| Honeywell International |
| Siemens |
| Schneider Electric |
| Danfoss |
| BELIMO Holding |
| Bray International |
| AVK Holding |
| Oventrop |
| Others |
Pricing and Supply Chain Analysis
EPA Lead and Copper Rule enforcement gates qualified supply for potable water valve tiers while reserving premium pricing access to NSF/ANSI 61 certified fabricators with recertified low-lead alloy portfolios. Municipal procurement departments in the United States and Germany enforce third-party certification thresholds that compress viable supplier pools and sustain margin premiums for compliant incumbents.
Pricing Analysis
Distributor margin layers absorb roughly one-third of final delivered cost for specification-grade brass and stainless steel variants sold through mechanical contractor channels. Three-tier pricing structure across premium, standard, and economy levels separates smart-actuated building automation valves from spec-grade mechanical configurations and commodity residential ball valves. Price differentiation hinges on NSF/ANSI 61 certification tier and volume scale, with certified premium grades commanding substantial premiums over uncertified imports. Cost compression in economy brass tiers is intensifying because foundry concentration in China exposes assemblers to tariff exposure and zinc price volatility. Residential plumbing contractors exhibit highest price sensitivity, while municipal water utilities prioritize certification compliance over unit cost.
Supply Chain Analysis
Freight cost inflation from Yangtze River Delta and Pearl River Delta clusters to North American distribution hubs has compressed assembler margins and accelerated geographic diversification efforts. Foundry capacity concentrates in China, India, and Germany, with brass and bronze casting drawing from copper concentrate feedstocks anchored in Chile and Peru. Raw material dependencies rest on London Metal Exchange copper and zinc contracts, super-austenitic stainless steel from Japanese and European mills, and specialized seal elastomers subject to REACH substance restrictions. Single-source vulnerability pervades Chinese casting supply for North American valve assemblers. Distribution runs through authorized distributor networks serving mechanical contractors, with direct municipal procurement gaining share in infrastructure replacement programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through alloy reformulation cost-down curves as low-lead brass production scales and premium-tier specification upgrades accelerate in corrosive service segments.
For Market Incumbents: Hedge against polymer composite substitution in residential new construction by deepening captive brass foundry capacity in India and Southeast Asia. Prioritize NSF/ANSI 61 certification backlog clearance to defend specification-grade positioning in United States municipal procurement. Smart building integration capabilities represent the priority lever for margin absorption into building automation system contracts. For New Entrants and Emerging Players: The price-point gap between premium smart-actuated valves and economy brass configurations creates entry space for mid-tier spec-grade specialists. Target India's AMRUT-funded municipal water programs where BIS certification requirements compress import competition and open specification-grade channels. Pursue foundry-to-assembly vertical control as the go-to-market anchor for cost-competitive brass variants. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale regional specialists with foundry-to-assembly vertical control and dormant CE marking documentation. Long-term viability favors fabricators with certified low-lead alloy portfolios and predictive maintenance architecture compatibility. The signal to watch is municipal procurement department migration from reactive repair to predictive replacement scheduling based on installation age databases.| Strategic Initiative | Industry Significance |
|---|---|
| Low-Lead Alloy Recertification | EPA enforcement deadlines compress product launch timelines for brass suppliers serving United States municipal water utilities. |
| Smart Actuation Integration | IoT-enabled position monitoring converges with Emerson Electric and Honeywell International building management system architectures. |
| Foundry Geographic Diversification | Capacity additions in India and Vietnam reduce tariff exposure and logistics vulnerability from Chinese casting concentration. |
| NSF/ANSI 61 Certification Investment | Third-party testing documentation serves as baseline bid qualification threshold for German and United States municipal procurement. |
| Digital Twin Compatibility Development | Predictive maintenance protocol adaptation unlocks brownfield industrial site replacement cycles in Germany's chemical processing corridor. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to capture supply stop valve procurement patterns across municipal, commercial, and industrial channels. Primary interviews engaged valve manufacturer product managers, municipal water utility procurement officers, mechanical contractor purchasing leads, and building automation system integrators. Secondary validation drew from EPA enforcement guidance documents, EU Drinking Water Directive revision drafts, NSF/ANSI 61 certification databases, and London Metal Exchange copper and zinc price series. Bottom-up demand modeling triangulated against top-down market sizing across material grades and end-use applications.
Segment-weighting approaches allocated volume and value projections across ball, globe, gate, angle, and butterfly valve configurations; brass, stainless steel, bronze, cast iron, and PVC material grades; and water supply, HVAC, chemical processing, fire protection, and irrigation applications. CAGRs were derived from replacement cycle analysis, infrastructure funding program disbursement schedules, and regulatory enforcement timeline assumptions. Forecast inputs incorporated EPA Lead and Copper Rule implementation pacing, EU Green Deal building energy efficiency mandate adoption curves, and AMRUT scheme funding allocation trajectories.
Caveats apply where NSF/ANSI 61 testing backlog extensions, copper and zinc commodity price spikes, or polymer composite substitution acceleration in residential construction could materially shift the outlook. Forecasts reflect modeling assumptions that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.