
 Choke Valves Market | 2026-2036
Choke Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Choke Valves Market Outlook
Specialized petroleum engineering talent is rotating toward digital choke valve integration, tightening the labor pool for conventional hydraulic design. Schlumberger Limited leverages its subsea technology leadership to anchor deepwater project portfolios. Baker Hughes Holdings LLC sustains manufacturing scale across North American pressure control supply chains. Mokveld Valves BV dominates axial choke valve engineering for high-capacity gas transmission networks.
A choke valve is a flow control device engineered to regulate fluid pressure and flow rate through a restricted orifice, typically constructed from chromium-molybdenum steel or Inconel alloys to withstand corrosive sour gas environments at pressures exceeding 15,000 psi. Its primary industrial purpose is to protect downstream equipment from pressure surges while maintaining production throughput in oil and gas extraction systems. Automatic choke systems lead the product type category due to their integration with SCADA-enabled wellhead automation, while digital choke technology represents the fastest-growing segment as operators pursue remote monitoring capabilities. The oil and gas end user segment commands the largest share of installed base volume, though power generation applications are expanding with supercritical CO2 cycle adoption.
API 6A and ISO 10423 wellhead equipment standards govern material qualification and pressure testing protocols, while NACE MR0175 defines sulfide stress cracking resistance thresholds that dictate alloy selection for sour service applications. The EPA's methane emissions regulations and the EU Green Deal's fugitive gas reduction targets are accelerating demand for low-leakage choke valve sealing technologies. Stakeholders must monitor how digital twin integration and predictive maintenance contracts reshape procurement criteria across operator supply chains.
Market Dynamics
Upstream operators are consolidating wellhead automation architectures around digital choke valve integration, compressing specification cycles and forcing suppliers to recertify legacy hydraulic portfolios against API 6A 21st Edition testing protocols.
Growth Catalysts
- Permian Basin tight-gas development:High-density pad drilling in Texas and New Mexico requires choke valve arrays rated for 15,000 psi sour service. Operators specify NACE MR0175-compliant Inconel trim to withstand hydrogen sulfide corrosion.
- EU Green Deal methane abatement mandates:Fugitive emission reduction targets are accelerating procurement of low-leakage metal-to-metal sealing technologies across North Sea offshore platforms. Regulators enforce quarterly LDAR inspection cycles.
- Digital twin integration:SCADA-enabled choke systems with real-time pressure telemetry are displacing manual hydraulic actuation in Saudi Aramco's onshore gas fields. Remote monitoring contracts now bundle predictive maintenance clauses.
Market Restraints
- Chromium-molybdenum steel price volatility:Alloy input costs fluctuate with nickel and molybdenum commodity indices, compressing fabrication margins for forged valve bodies. Foundries in Houston and Aberdeen face working capital strain.
- API 6A certification bottlenecks:Third-party witnessed testing queues at Lloyd's Register and DNV extend lead times by fourteen weeks for new choke valve designs. Small fabricators lack capital to maintain redundant certification pathways.
- Subsea choke valve supply concentration:Deepwater project procurement clusters around Norwegian and Singaporean assembly yards, creating single-source vulnerability for operators in Brazil's pre-salt basins.
Strategic Opportunities
- Supercritical CO2 power cycles:Choke valve applications in dense-phase CO2 transport networks for carbon capture projects represent nascent demand. NETL research facilities in West Virginia pilot 4,000 psi injection systems.
- India's city gas distribution expansion:PNGRB pipeline authorization rounds mandate high-pressure regulation skids for CNG mother stations. Domestic valve fabricators lack axial choke engineering expertise, creating import substitution openings.
- Predictive maintenance contract bundling:Operators in the North Sea are unbundling valve overhaul schedules from OEM service agreements. Independent service companies capture recurring revenue through condition-based intervention models.
Industry Challenges
- SCADA-legacy hydraulic integration:Brownfield wellhead retrofits require protocol bridging between analog choke positioners and digital control systems. System integrators face commissioning delays in mature Gulf of Mexico assets.
- API 6A 21st Edition recertification timelines:Existing valve portfolios require witnessed pressure testing against updated temperature derating curves. Engineering departments allocate eighteen-month windows for documentation overhaul.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Choke Valves Market |
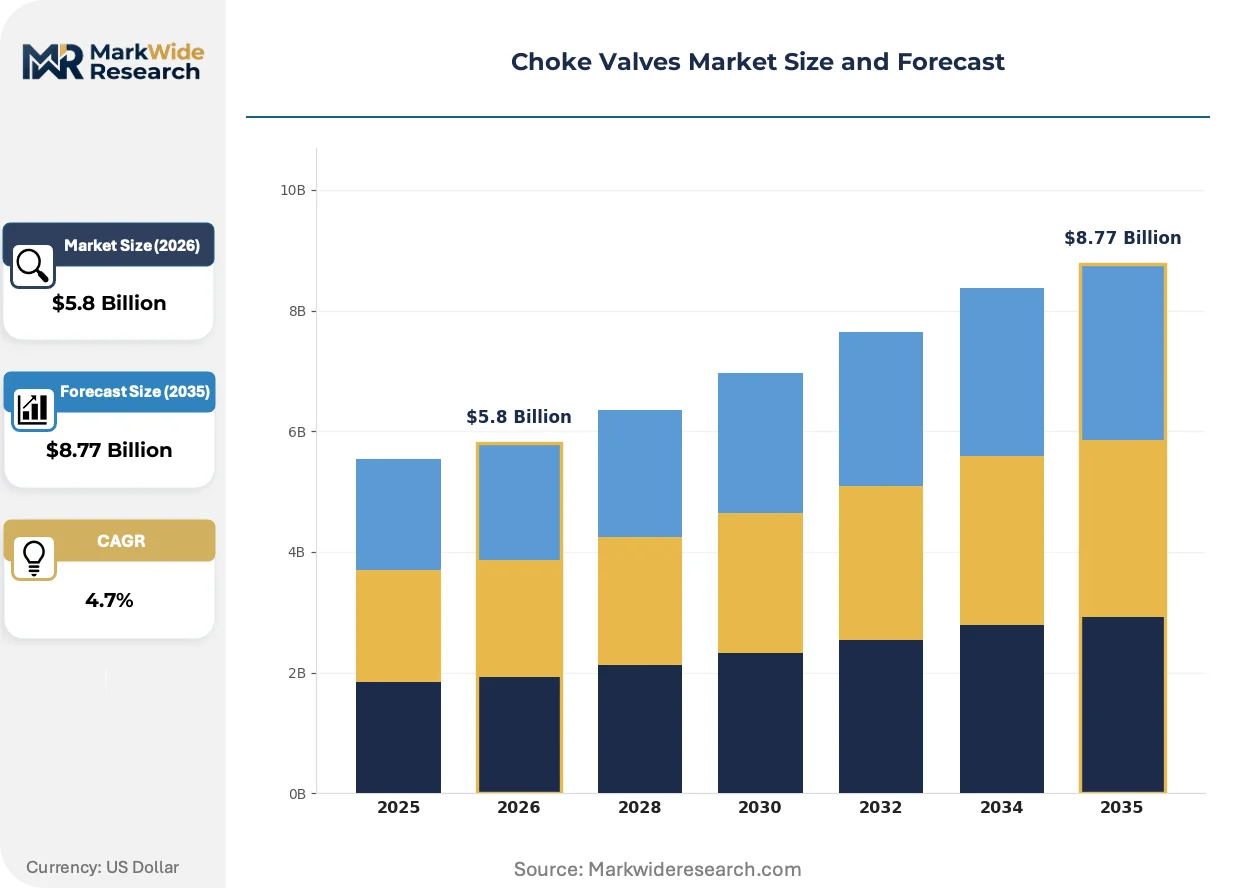
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.77 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Choke, Automatic Choke, Digital Choke, Pneumatic Choke End User: Oil & Gas, Water Treatment, Chemical Processing, Power Generation Technology: Hydraulic Control, Electric Control, Pneumatic Control, Electronic Control Installation: Onshore, Offshore, Above Ground, Below Ground |
| Companies Covered | The Weir Group PLC, Mokveld Valves BV, Schlumberger Limited, TechnipFMC plc, Master Flo Valve Inc., Baker Hughes Holdings LLC, IMI plc, Flowserve Corporation, Emerson Electric Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Choke Valves Market Strategic Shifts
Digitalization is compressing choke valve specification cycles while material science advances enable thinner-walled pressure containment. Regulatory methane enforcement and operator procurement model evolution are reshaping competitive requirements simultaneously.
Smart positioner technology with embedded pressure-temperature sensors is miniaturizing actuator footprints while maintaining 0.1% flow control accuracy. Permian Basin operators specify these integrated packages for space-constrained multi-well pads. The technology is miniaturizing skid dimensions, reducing wellsite civil works by thirty percent in high-density developments.
EPA methane emissions regulations finalized under the Inflation Reduction Act impose facility-wide leak detection thresholds. Choke valve packing systems must demonstrate sub-500 ppm fugitive rates under quarterly optical gas imaging inspection. Offshore Gulf of Mexico operators are retrofitting metal-to-metal stem seals ahead of 2026 compliance deadlines.
Integrated service contracting now bundles choke valve supply with predictive analytics subscriptions. Majors in the North Sea disaggregate capital procurement from lifecycle maintenance, awarding ten-year performance contracts to valve OEMs with embedded digital monitoring. Norway's Equinor pioneered this structure in Johan Sverdrup phase two developments.
Choke Valves Market Segmentation
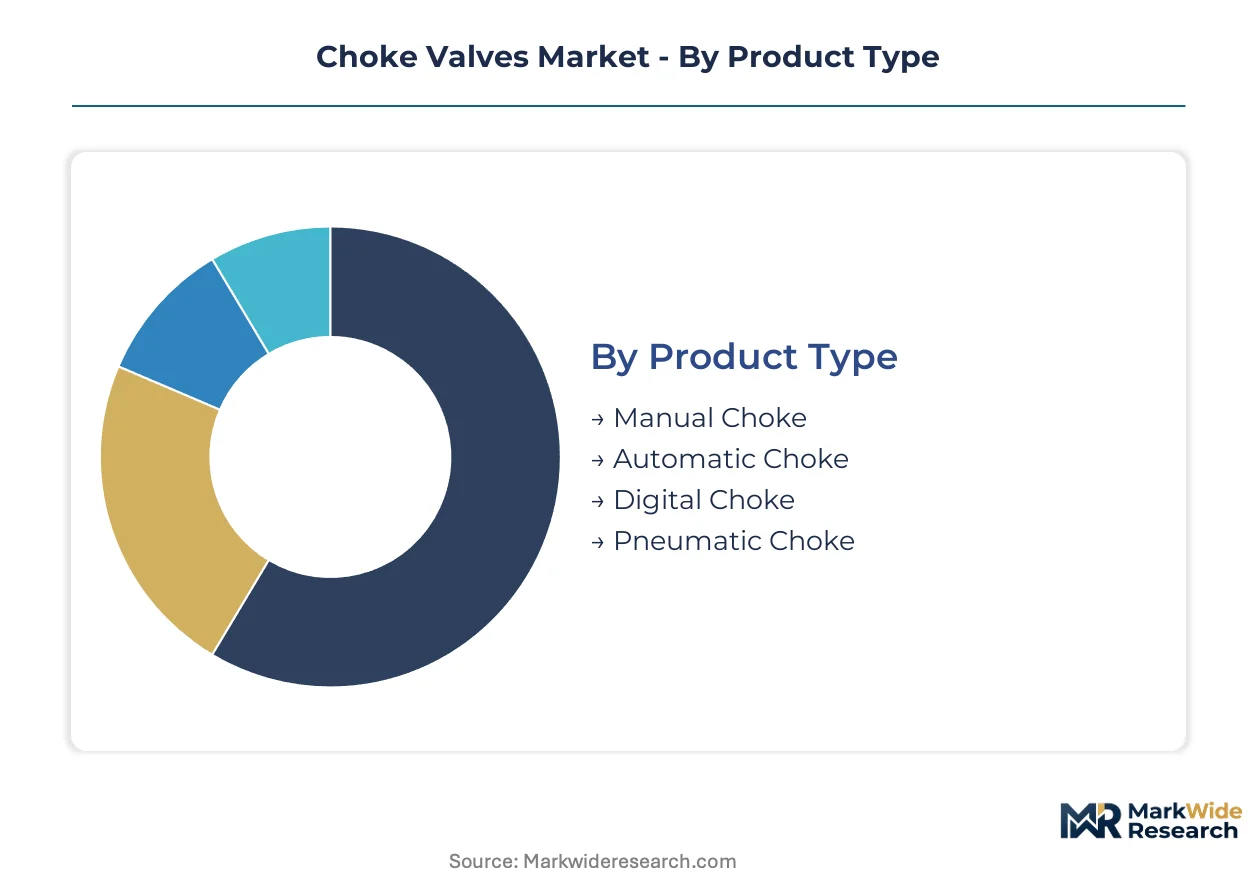
Choke valve procurement channels diverge sharply across product tiers, with automated systems flowing through OEM-direct contracts while manual configurations distribute through regional valve stockists. Specification complexity and certification requirements determine whether buyers engage fabricators directly or rely on distributor inventories.
Product Type:
Channel strategy bifurcates between specification-intensive automated systems and commodity manual replacements, with digital variants commanding premium direct sales while pneumatic units move through energy-sector distributors.
- Automatic Choke:These systems integrate SCADA-enabled actuation with real-time pressure feedback loops, typically specified for Permian Basin multi-well pads where remote operation reduces crew exposure. Operators in Texas and New Mexico procure these through OEM-direct contracts bundling installation and commissioning services.
- Digital Choke:Embedded sensor arrays enable predictive maintenance algorithms and digital twin integration. Saudi Aramco's onshore gas fields are standardizing on these for centralized control room operation, with procurement flowing through multi-year performance contracts rather than spot purchasing.
- Manual Choke:Mechanical handwheel actuation dominates replacement demand in mature North Sea assets where brownfield budgets constrain automation investment.
- Pneumatic Choke:Compressed air actuation serves offshore platforms with reliable instrument air infrastructure, particularly in Norwegian North Sea developments.
By volume, Manual Choke leads. By growth pace, Digital Choke is expanding most quickly.
End User:
Application requirements dictate material specification tiers, with sour service oil and gas commanding superalloy trim while water treatment accepts standard carbon steel bodies.
- Oil & Gas:Upstream operators specify NACE MR0175-compliant Inconel trim for hydrogen sulfide corrosion resistance at pressures exceeding 15,000 psi. Permian tight-gas development and Saudi onshore expansion concentrate procurement volume for API 6A certified units.
- Power Generation:Supercritical CO2 cycle pilot plants at NETL West Virginia facilities are piloting dense-phase choke applications, creating nascent demand for 4,000 psi rated designs in carbon capture injection networks.
- Chemical Processing:Corrosive fluid handling requires Hastelloy or titanium trim variants, with procurement clustering around Texas Gulf Coast petrochemical complexes.
- Water Treatment:Municipal and industrial pressure regulation operates at substantially lower specification thresholds, with ductile iron bodies and standard elastomer seals sufficient for most applications.
By installed base, Oil & Gas dominates. By application expansion rate, Power Generation is gaining share fastest.
Technology:
Control architecture selection tracks field infrastructure maturity, with hydraulic systems entrenched in legacy assets and electric actuation displacing them in greenfield developments.
- Hydraulic Control:Fluid power actuation remains standard in subsea completions where electric penetrations face reliability challenges at depth. Norwegian and Singaporean assembly yards concentrate supply for Brazil's pre-salt developments.
- Electric Control:Servo motor precision enables sub-one-percent flow accuracy for tight-gas wellhead automation. Permian Basin operators specify these for space-constrained pad layouts where hydraulic power units prove impractical.
- Pneumatic Control:Instrument air systems dominate offshore Gulf of Mexico platforms with established compressor infrastructure and explosion-proofing requirements.
- Electronic Control:Integrated positioners with embedded diagnostics bridge analog legacy systems to digital control networks in brownfield retrofit applications.
By deployment volume, Hydraulic Control retains the largest footprint. By displacement rate, Electric Control shows the steepest expansion trajectory.
Installation:
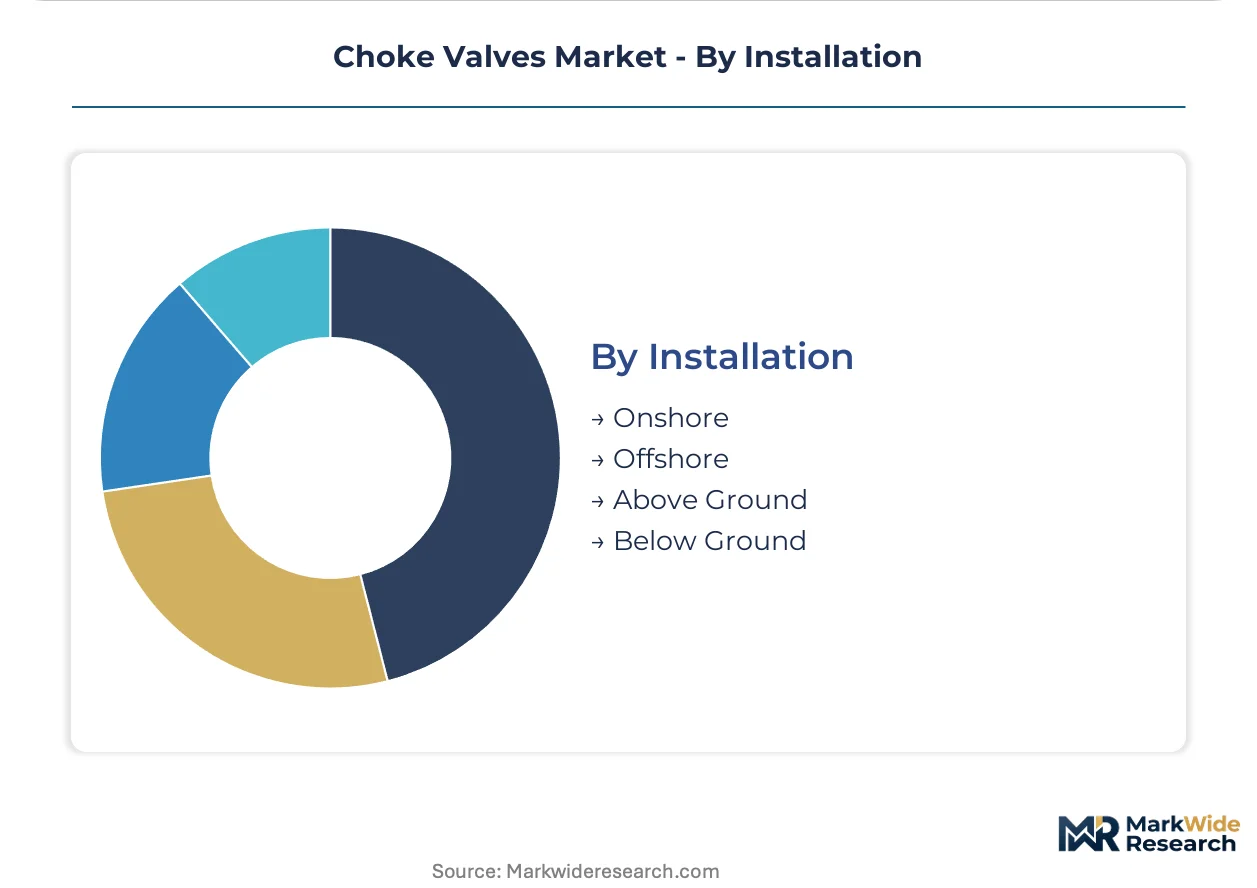
Physical siting determines environmental protection requirements and accessibility for maintenance, with below-ground installations commanding specialized corrosion allowances and offshore units requiring marine-grade coatings.
- Onshore:Surface wellhead and pipeline applications constitute the procurement volume base, with standard weatherproofing sufficient for most North American and Middle Eastern climates.
- Offshore:Platform and subsea installations require API 6A 21st Edition certification against updated temperature derating curves, with witnessed testing queues extending lead times.
- Above Ground:Skid-mounted production facilities and compressor stations favor this configuration for accessibility and simplified civil works.
- Below Ground:Buried pipeline regulation stations in European gas distribution networks require cathodic protection integration and specialized external coatings.
By unit shipments, Onshore leads. By project value concentration, Offshore commands premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Upstream operators in the United States deploy choke valves for 15,000 psi sour service in tight-gas formations, while Saudi Arabia concentrates procurement for onshore gas field automation and Norway dominates subsea high-pressure specifications.
United States
Permian Basin pad drilling in Texas and New Mexico drives specification-intensive procurement for NACE MR0175-compliant Inconel trim systems. EPA methane regulations under the Inflation Reduction Act enforce quarterly LDAR inspection cycles for fugitive emissions. Houston-area foundries face working capital strain from chromium-molybdenum price volatility.
Saudi Arabia
Saudi Aramco's onshore gas field expansion standardizes digital choke systems for centralized control room operation. The country's national oil company bundles multi-year performance contracts with predictive maintenance clauses. Eastern Province assembly yards concentrate high-capacity axial choke fabrication for domestic pipeline networks.
Norway
Equinor's Johan Sverdrup development pioneered integrated service contracting that unbundles valve supply from lifecycle maintenance. EU Green Deal methane abatement mandates accelerate low-leakage metal-to-metal sealing retrofits across North Sea platforms. Stavanger-based engineering clusters dominate subsea choke valve specification for deepwater projects.
China
Sinopec and CNOOC expand procurement for high-pressure wellhead systems in offshore Bohai Bay developments. The Ministry of Ecology and Environment enforces fugitive emission standards that mirror EPA thresholds for valve packing integrity. Shanghai and Tianjin fabrication yards scale API 6A certification capacity for domestic upstream operators.
Brazil
Petrobras pre-salt basin development concentrates demand for subsea choke systems rated to 3,000 meter water depths. ANP regulatory frameworks require witnessed pressure testing against ISO 10423 protocols for wellhead equipment. Rio de Janeiro assembly yards depend on Norwegian and Singaporean supply chains for critical subsea components.
Choke Valves Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding direct procurement relationships with national oil companies and the lower tier competing through regional distributor networks. The market structure reflects consolidation around subsea technology portfolios and fragmentation across onshore fabrication capacity. Three archetypes dominate: integrated energy service conglomerates with full wellhead portfolios, axial choke engineering specialists focused on high-capacity gas transmission, and diversified industrial valve manufacturers with energy-sector divisions. Competitive moves center on predictive maintenance contract bundling and API 6A 21st Edition recertification races.
Among European specialists, Mokveld Valves BV occupies a position exemplifying axial choke engineering concentration for pipeline applications. Schlumberger Limited and Baker Hughes Holdings LLC anchor the integrated service tier, representing the archetype of energy technology conglomerates with subsea and surface wellhead capabilities. These three entities illustrate the competitive spectrum from specialized component engineering to full lifecycle service integration.
| Leading Market Players |
|---|
| The Weir Group PLC |
| Mokveld Valves BV |
| Schlumberger Limited |
| TechnipFMC plc |
| Master Flo Valve Inc. |
| Baker Hughes Holdings LLC |
| IMI plc |
| Flowserve Corporation |
| Emerson Electric Co. |
| Others |
Value Chain & Pricing Dynamics
Inconel alloy substitution for chromium-molybdenum trim in sour service specifications is redrawing procurement geography toward Singaporean and Norwegian forging capacity while compressing margin structures for Houston-based fabricators unable to pass through nickel price volatility.
Pricing Analysis
Long-term performance contracts with bundled predictive maintenance clauses dominate premium tier procurement, separating digital choke systems with SCADA integration from spot-market manual valve replacements. Price differentiation hinges on API 6A 21st Edition certification status and NACE MR0175 compliance tier, with superalloy trim commanding substantial premiums over standard carbon steel configurations. Cost compression in mid-tier pneumatic actuation is intensifying because Brazilian pre-salt operators are consolidating procurement around Norwegian subsea specialists. Independent upstream operators in mature North Sea assets exhibit highest price sensitivity, while Saudi Aramco's national oil company structure tolerates premium positioning for centralized automation.
Supply Chain Analysis
Witnessed pressure testing queues at Lloyd's Register and DNV have extended inventory lead times for new choke valve designs, straining working capital across Houston and Aberdeen foundries. Manufacturing gravity centers on the United States, Norway, and Singapore, with forging capacity for high-pressure bodies drawing from Japanese and German specialty steel mills. Raw material dependencies rest on nickel-molybdenum alloy indices, Inconel billet supply, and chromium-molybdenum steel plate. Single-source vulnerability concentrates in subsea choke valve assembly for Brazil's pre-salt developments. Distribution runs through OEM-direct channels for automated systems and regional energy-sector distributors for manual replacement units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance contract bundling is expanding faster than hardware shipments as operators disaggregate capital procurement from lifecycle service, creating recurring revenue pools that reshape competitive economics.
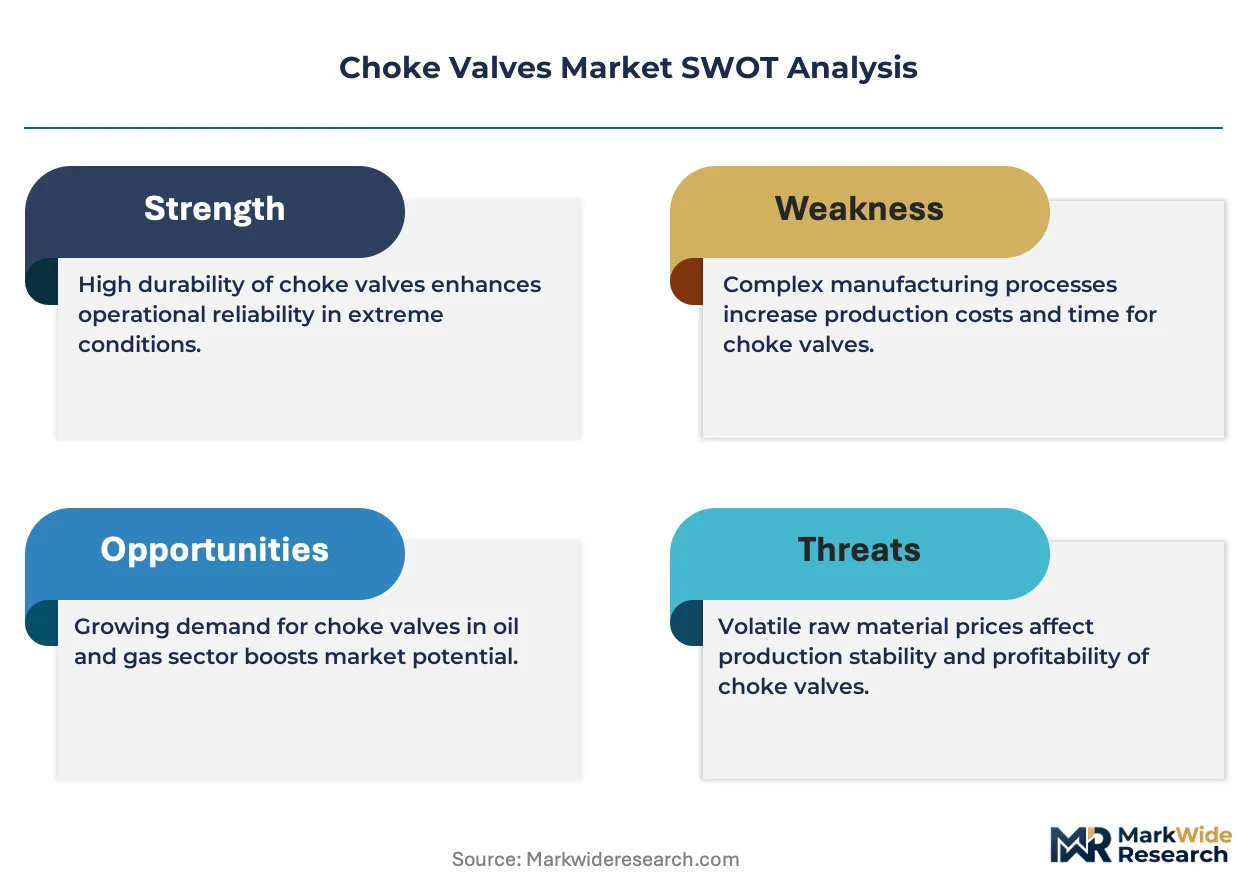
For Market Incumbents: Shield installed base relationships by embedding digital monitoring capabilities ahead of API 6A 21st Edition recertification deadlines, while consolidating backward integration into Inconel forging capacity to neutralize alloy price volatility threats from commodity indices. For New Entrants and Emerging Players: Anchor in India's city gas distribution expansion where PNGRB pipeline mandates outpace domestic axial choke engineering expertise, targeting CNG mother station regulation skids through technology licensing partnerships with established European specialists. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors predictive maintenance platform providers over pure hardware fabricators; prioritize assets with embedded SCADA software stacks and ten-year performance contract backlogs, watching for inflection when quarterly LDAR inspection cycles tighten methane emission thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| API 6A 21st Edition Recertification Investment | Third-party witnessed testing at Lloyd's Register unlocks Saudi Aramco and Equinor procurement eligibility. |
| Predictive Maintenance Platform Development | Embedded digital twin integration captures ten-year performance contracts displacing spot hardware sales. |
| Superalloy Forging Capacity Expansion | In-house Inconel billet processing insulates margins from nickel commodity index volatility. |
| India Market Entry Partnership | Technology licensing to domestic fabricators addresses PNGRB pipeline authorization requirements. |
| Subsea Assembly Yard Diversification | Singaporean capacity addition reduces Brazilian pre-salt project single-source vulnerability. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with upstream procurement managers, wellhead engineering directors, aftermarket service heads, and API certification auditors; and secondary validation against EPA methane regulation filings, ISO 10423 documentation, Lloyd's Register certification records, and customs trade data for alloy steel valve imports. Bottom-up segmentation triangulation against top-down energy sector capex projections anchored volume estimates.
Across the analysis window, the forecasting framework modeled product type, end-use application, control technology architecture, and installation environment dimensions. CAGRs derived from segment-level demand elasticity coefficients applied to operator wellhead automation spending patterns, with supercritical CO2 cycle pilot data from NETL West Virginia facilities informing power generation expansion assumptions.
Decision-makers should treat outputs as directional under sustained oil price bands and regulatory enforcement intensity assumptions; material deviation in alloy commodity indices or API certification timeline shifts would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Valve Seat Inserts Market
Valves
Explosion Isolation Valves Market
Valves
Subsea Control System Market
Valves
Industrial Hydraulic Filters Market
Valves
Backflow Preventers Market
Valves
Large Bore Vacuum Insulated Pipe Market
Valves
Valve Cover Gasket Market
Valves
Tubing Heads Market
Valves
Fluid Power Cylinder Market
Valves
Angle Opening Ball Locator Market
Valves
Railway Emergency Valves Market
Valves
HVAC Valves Market
Valves
Global Solenoid Valves Market
Valves
Deluge Valve Market
Valves
Global Valves Market
Valves
Pneumatic Slide Gates Market