
 Logging While Drilling (LWD) Market | 2026-2036
Logging While Drilling (LWD) Market Size, Share, and Industry Trends Forecast 2026-2036
Logging While Drilling (LWD) Market Intelligence
Exploration companies are gaining procurement share as the LWD market is bifurcating between integrated oil majors and specialized independents chasing unconventional reservoirs. Schlumberger dominates deepwater measurement-while-drilling integration through its reservoir characterization platforms. Baker Hughes differentiates via electromagnetic telemetry systems that penetrate high-loss formations where mud pulse fails. Halliburton sustains North American shale market presence through dense regional service infrastructure.
Logging While Drilling refers to downhole measurement systems that acquire formation petrophysical data during the drilling process, typically operating at bottom-hole pressures exceeding 20,000 psi and temperatures above 175°C to deliver gamma ray, resistivity, and density logs without tripping pipe. Resistivity tools anchor the product mix as the primary revenue pool since azimuthal deep-reading capabilities command premium pricing in geosteering applications. Real-time data transmission via wired drill pipe represents the fastest-growing technology segment, displacing conventional mud pulse in high-value wells where latency costs exceed telemetry investment.
BSEE well control rules and NORSOK D-010 drilling standards shape tool reliability specifications, while China's GB/T petroleum equipment standards constrain market access for non-certified suppliers. EPA methane monitoring requirements and EU methane emissions regulations are extending LWD demand into emissions verification workflows. Stakeholders must weigh telemetry architecture bets against the pace of electrified rig adoption and associated power constraints.
Market Dynamics
Real-time telemetry architecture decisions now dominate capital allocation as operators weigh wired drill pipe deployment against legacy mud pulse systems in high-dayrate offshore environments.
Growth Catalysts
- Ultradeepwater expansion:Brazil's pre-salt formations require azimuthal resistivity tools for geosteering in salt-layered reservoirs where conventional logging fails.
- BSEE well control mandates:Tighter blowout preventer integration standards force telemetry upgrades that embed formation evaluation into safety-critical workflows.
- Electromagnetic telemetry:High-loss carbonate formations in Middle Eastern gas fields reward through-the-earth signal transmission where mud pulse attenuates.
Market Restraints
- Raw material concentration:Specialty electronics-grade ceramics for high-temperature sensors source primarily from Japanese suppliers, creating single-point fragility.
- Regulatory fragmentation:China's GB/T petroleum equipment certification requirements block non-compliant tool vendors from national oil company tenders.
- Technical ceiling:Current battery chemistry limits downhole power density at sustained temperatures above 200°C, constraining sensor complexity in ultradeep wells.
Strategic Opportunities
- Emissions verification workflows:EPA methane monitoring rules and EU methane emissions regulations extend LWD demand into leak detection and quantification services.
- Geothermal crossover:High-temperature tool platforms developed for oil and gas adapt to volcanic reservoir characterization in Indonesia and Kenya.
- Carbon capture site screening:Resistivity and sonic logging while drilling enables real-time caprock integrity assessment for sequestration projects.
Industry Challenges
- Downhole electronics reliability:Mean-time-between-failure targets under BSEE and NORSOK D-010 strain quality assurance systems and field service density.
- Cross-functional talent scarcity:Engineers combining petrophysics, signal processing, and drilling mechanics command premium compensation and limit deployment scaling.
- Legacy system integration:Wired drill pipe retrofits on existing rig fleets require mechanical and software interfaces that delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Logging While Drilling (LWD) Market |
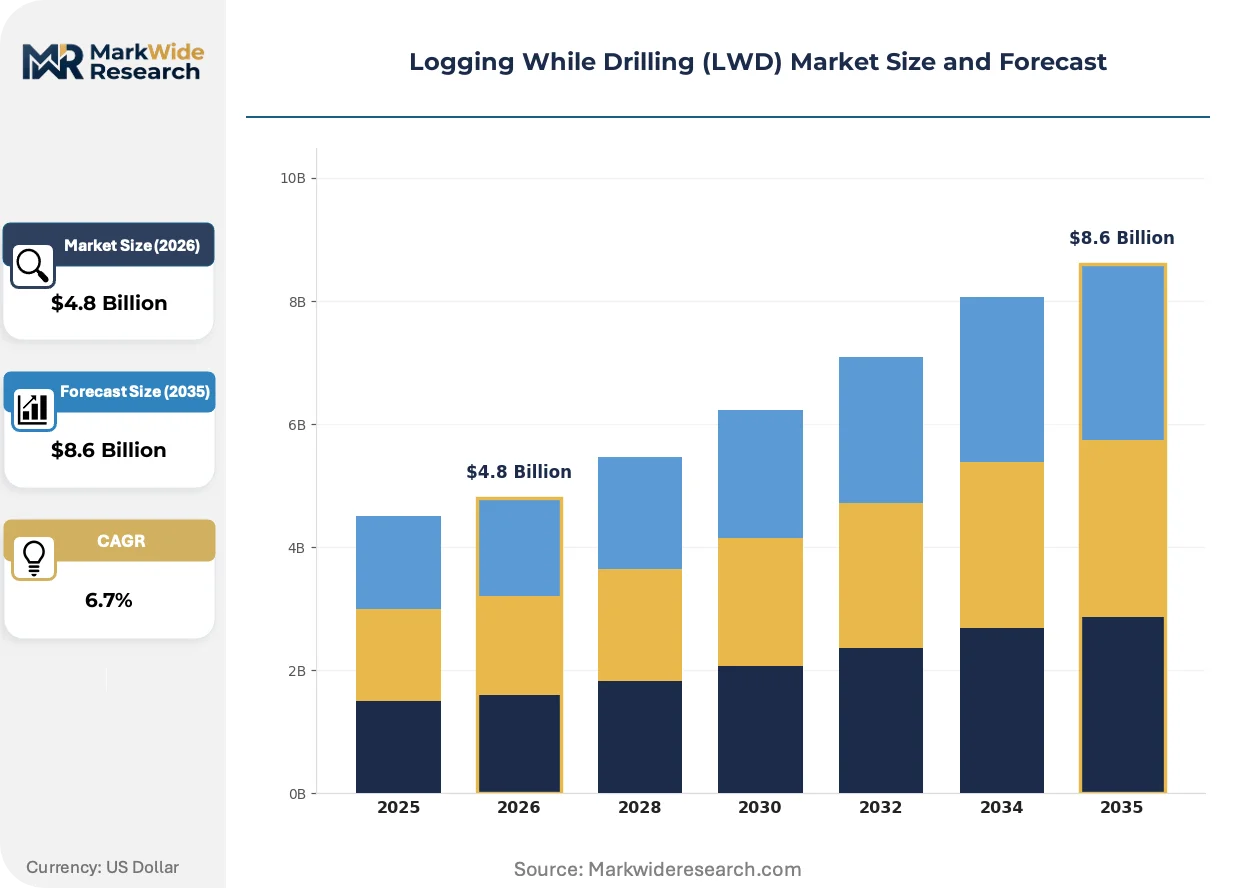
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gamma Ray Tools, Resistivity Tools, Neutron Density Tools, Sonic Tools, Caliper Tools Technology: Measurement While Drilling, Real-Time Data Transmission, Mud Pulse Telemetry, Electromagnetic Telemetry, Wired Drill Pipe Application: Hydrocarbon Exploration, Unconventional Reservoirs, Reservoir Characterization, Formation Evaluation, Wellbore Stability End User: Oilfield Services, Drilling Contractors, Exploration Companies, Oil & Gas Operators, Well Logging Firms |
| Companies Covered | Weatherford International, Scientific Drilling, Schlumberger, China Oilfield Services, Nabors Industries, Halliburton, National Oilwell Varco, APS Technology, Baker Hughes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Logging While Drilling (LWD) Market Strategic Shifts & Innovations
Telemetry modality selection now determines competitive position as latency-sensitive applications reward real-time formation evaluation over post-drilling wireline alternatives.
Wired drill pipe telemetry is fragmenting the high-value well segment by eliminating surface-to-bit signal delay. National oil companies in Brazil and Norway mandate this architecture for pre-salt and Arctic developments where geosteering decisions carry million-dollar daily consequences. The technology is fragmenting service company revenue models away from per-foot logging charges toward integrated drilling-performance contracts.
EU methane emissions regulations and EPA methane monitoring requirements are embedding continuous emissions verification into drilling workflows. These rules force tool vendors to integrate gas detection sensors with standard gamma ray and resistivity suites. Offshore operators in the North Sea and Gulf of Mexico now specify this capability in tender documents, compressing procurement cycles for compliant suppliers.
Integrated drilling contracts are compressing vendor selection criteria around full-telemetry performance guarantees rather than discrete tool specifications. Independent exploration companies in US shale plays now bundle LWD with rotary steerable systems under single-provider accountability. This consolidation is most visible in the Permian Basin, where pad drilling density rewards standardized tool configurations across multi-well programs.
Logging While Drilling (LWD) Market Segmentation

LWD segmentation reflects competing telemetry architectures and tool specifications that operators balance against well economics. Substitution pressures vary sharply across categories—mud pulse systems face displacement from wired drill pipe in premium offshore markets, while resistivity tools resist replacement due to irreplaceable geosteering value.
Product Type:
Resistivity and gamma ray tools face the strongest substitution threat from wireline alternatives in onshore shale, whereas azimuthal deep-reading capabilities defend pricing in complex geologies.
- Resistivity Tools:Azimuthal deep-reading sensors measure formation conductivity at multiple depths of investigation for geosteering in salt-layered reservoirs. Brazil's pre-salt operators specify these tools for million-dollar daily consequence decisions where wellbore placement accuracy determines field economics.
- Gamma Ray Tools:Natural gamma radiation detectors identify shale content and stratigraphic correlation in real time. North American shale drillers deploy these as baseline formation evaluation tools where low unit cost supports pad drilling standardization across multi-well programs.
- Neutron Density Tools:Compensated neutron and bulk density measurements quantify porosity and lithology in carbonate formations.
- Sonic Tools:Acoustic velocity sensors capture compressional and shear slowness for mechanical properties and pore pressure prediction.
- Caliper Tools:Mechanical or ultrasonic borehole diameter measurements assess washout and cement volume requirements.
Resistivity tools anchor the volume base while wired-telemetry-compatible gamma ray configurations gain share at the steepest rate.
Technology:
Cost tier stratification separates commodity mud pulse deployments from premium wired drill pipe installations where dayrate economics justify capital intensity.
- Wired Drill Pipe:Conductor-embedded drill string eliminates surface-to-bit signal delay for continuous high-bandwidth data transmission. Norway's Arctic developments and Brazil's pre-salt fields mandate this architecture where geosteering latency carries extreme financial exposure.
- Electromagnetic Telemetry:Through-the-earth signal transmission penetrates high-loss formations where mud pulse attenuates completely. Middle Eastern gas operators in carbonate formations reward this capability with contracted deployment premiums.
- Mud Pulse Telemetry:Pressure wave modulation through drilling fluid remains the default offshore and onshore standard.
- Measurement While Drilling:Directional and inclination sensors integrated with logging suites for trajectory control.
- Real-Time Data Transmission:Surface processing and visualization systems enabling immediate operational response.
Mud pulse telemetry retains the widest installed base while wired drill pipe climbs the fastest in contracted revenue per well.
Application:
Application maturity spreads from standardized hydrocarbon exploration workflows to emerging carbon capture site screening where tool specifications remain unsettled.
- Hydrocarbon Exploration:Conventional oil and gas prospect evaluation using standard gamma ray-resistivity-density triple combo configurations. Deepwater operators in the Gulf of Mexico specify BSEE-compliant telemetry integration for well control assurance.
- Unconventional Reservoirs:Horizontal shale well geosteering and landing zone identification in low-permeability formations. Permian Basin pad drilling rewards standardized tool strings that minimize non-productive time between wells.
- Reservoir Characterization:Detailed petrophysical property mapping for field development planning.
- Formation Evaluation:Real-time lithology and fluid identification during drilling.
- Wellbore Stability:Mechanical earth model calibration for safe mud weight window maintenance.
Hydrocarbon exploration commands the largest revenue pool while unconventional reservoir applications expand most quickly in unit deployment volume.
End User:
Customer type concentration favors integrated oil and gas operators with capital discipline to specify full-telemetry performance guarantees over discrete tool rentals.
- Oil & Gas Operators:Asset-owning companies specifying integrated drilling contracts with single-provider accountability. National oil companies in Brazil and Norway drive wired drill pipe adoption through tender mandates.
- Oilfield Services:Technology-owning service companies deploying owned equipment under performance-based contracts. These firms capture margin through reservoir characterization platform integration and real-time optimization services.
- Drilling Contractors:Rig-owning companies coordinating third-party tool integration on contracted wells.
- Exploration Companies:Independent upstream firms prioritizing capital efficiency in unconventional resource plays.
- Well Logging Firms:Specialized wireline and LWD service providers operating on rental or per-foot models.
Oil and gas operators dominate procurement value while oilfield services capture the steepest margin expansion through integrated performance contracts.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tool exports from Houston service centers supply pre-salt drilling campaigns in Brazil and North Sea developments in Norway. Equipment flows concentrate on high-specification resistivity and telemetry systems demanded by national oil company tenders.
United States
Gulf of Mexico ultradeepwater drilling and Permian Basin shale pad development drive tool deployment intensity. BSEE well control rules mandate telemetry integration with blowout preventer systems. Houston hosts the densest concentration of service company engineering centers and field logistics operations.
Brazil
Pre-salt carbonate formations require azimuthal deep-reading resistivity tools for geosteering through salt-layered reservoirs. Petrobras tender specifications mandate wired drill pipe architecture for million-dollar dayrate environments. Santos Basin development clusters anchor the highest-value LWD contract awards in Latin America.
Norway
Arctic and sub-Arctic drilling programs specify high-reliability telemetry systems under NORSOK D-010 standards. Electromagnetic signal transmission penetrates high-loss formations where conventional mud pulse attenuates. Stavanger and Bergen service bases support North Sea and Barents Sea exploration campaigns.
China
National oil company offshore expansion in the South China Sea rewards high-temperature tool platforms. GB/T petroleum equipment certification requirements constrain market access for non-compliant suppliers. Tianjin and Shenzhen manufacturing clusters produce regionally certified sensor assemblies.
Saudi Arabia
Gas field development in high-loss carbonate formations rewards electromagnetic telemetry capabilities. Aramco drilling contracts specify integrated formation evaluation and wellbore stability workflows. Dhahran-based research centers collaborate on high-temperature sensor reliability programs.
Logging While Drilling (LWD) Market Key Industry Players
Player mix skews toward integrated oilfield services conglomerates with reservoir characterization platforms. Market structure concentrates around three dominant technology owners with complementary telemetry specializations. Strategic archetypes include full-service drilling performance contractors, electromagnetic telemetry specialists, and regional infrastructure-heavy service providers. Competitive moves center on integrated contract bundling and high-temperature sensor platform development.
Within the integrated services tier, Schlumberger, Baker Hughes, and Halliburton occupy positions defined by telemetry architecture differentiation. Schlumberger exemplifies the reservoir characterization platform archetype through measurement-while-drilling integration. Baker Hughes anchors electromagnetic system capabilities for high-loss formation penetration. Halliburton represents infrastructure-scale service density in North American unconventional plays.
| Leading Market Players |
|---|
| Weatherford International |
| Scientific Drilling |
| Schlumberger |
| China Oilfield Services |
| Nabors Industries |
| Halliburton |
| National Oilwell Varco |
| APS Technology |
| Baker Hughes |
| Others |
Cost & Logistics Intelligence
Integrated drilling-performance contracts lock in multi-year telemetry deployments and freeze price visibility for operators committing capital to Brazil's pre-salt and Norway's Arctic developments. These arrangements tether service company margins to uptime guarantees while insulating buyers from spot-rate volatility in high-dayrate environments.
Pricing Analysis
Next-generation wired drill pipe systems command 40-60% premiums over mud pulse telemetry, while legacy electromagnetic platforms face price erosion as battery chemistry constraints limit their addressable market. Three-tier pricing structure across premium, standard, and economy levels separates BSEE-mandated safety-integrated packages from basic gamma ray configurations. Cost compression in standard-tier resistivity tools stems from pad drilling standardization in North American shale. Independent exploration companies exhibit highest price sensitivity, whereas Petrobras and Equinor absorb premium telemetry costs without procurement friction.
Supply Chain Analysis
Extended lead times for electronics-grade ceramics stretch sensor assembly schedules, with Japanese suppliers dominating high-temperature substrate production. Manufacturing concentrates in the United States, China, and Norway, with Houston engineering centers feeding Brazil's pre-salt campaigns and Tianjin plants serving regional certification requirements. Downhole battery packs draw from South Korean cell producers, creating single-source vulnerability for 200°C-rated power systems. Distribution runs through Stavanger, Houston, and Singapore service hubs that coordinate rig-site logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-functional engineers combining petrophysics, signal processing, and drilling mechanics represent the scarcest capability layer, constraining deployment scaling for integrated contract winners. Tool vendors must secure this talent base before capacity expansion.
For Market Incumbents: Secure exclusive offtake agreements with Japanese ceramics suppliers to lock in high-temperature sensor capacity before competitors replicate Schlumberger's reservoir characterization platform. Defend against electromagnetic telemetry specialists by embedding formation evaluation into BSEE-mandated well control workflows, converting regulatory compliance into switching costs. For New Entrants and Emerging Players: Lead with geothermal crossover applications in Indonesia and Kenya, where oil and gas tool platforms adapt to volcanic reservoir characterization with minimal R&D adaptation. Target carbon capture site screening workflows where caprock integrity specifications remain unsettled and incumbent tool configurations carry legacy hydrocarbon bias. Pursue direct contracting with national oil company research centers rather than competing for integrated drilling tenders. For Investors and Strategic Acquirers: Capital is best deployed toward electromagnetic telemetry specialists with proven high-loss formation penetration and contracted deployment premiums from Middle Eastern gas operators. Long-term viability hinges on electrified rig adoption curves and associated power constraint relief. Watch for inflection when BSEE or NORSOK mandates wired drill pipe as default architecture rather than premium option.| Strategic Initiative | Industry Significance |
|---|---|
| High-Temperature Sensor Platform Development | Unlocks ultradeep geothermal and pre-salt carbonate markets where 200°C batteries currently fail. |
| Integrated Drilling-Performance Contracting | Shifts revenue from per-foot logging to uptime guarantees, locking in multi-year operator relationships. |
| Electromagnetic Telemetry Specialization | Penetrates Saudi Arabian and Norwegian carbonate formations where mud pulse signal attenuates completely. |
| Emissions Verification Sensor Integration | Captures EPA and EU methane monitoring mandates extending LWD demand into leak detection services. |
| Regional Certification Investment | GB/T compliance unlocks China National Offshore Oil Corporation tenders blocking non-certified vendors. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with drilling engineers, petrophysicists, procurement managers at national oil companies, and telemetry systems architects; and secondary validation through BSEE regulatory filings, NORSOK D-010 standard documentation, Petrobras tender specifications, and SEC disclosures from oilfield services conglomerates. Bottom-up well-count and dayrate assumptions triangulated against top-down market size estimates from customs records and service company revenue segmentations.
Across the analysis window, the forecasting framework modeled revenue trajectories by telemetry architecture, tool specification tier, and end-user contract type, with particular weighting on integrated drilling-performance guarantees versus discrete tool rentals. CAGRs derived from weighted average of historical deployment growth, tender pipeline visibility, and regulatory mandate implementation schedules. Inputs included rig fleet electrification curves and ceramics supply capacity expansion plans.
The analysis sits within stated boundaries; outcomes outside sustained ultradeepwater capital commitment or accelerated BSEE mandate enforcement would require recalibration. Forecasts reflect documented assumptions about battery chemistry advancement and national oil company procurement centralization. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil and Gas Field Services Market
Oil & Gas
Coal Mining Market
Oil & Gas
Asia-Pacific Small-Scale LNG Market
Oil & Gas
Oilfield Air Drilling Market
Oil & Gas
Well Completion Equipment Service Market
Oil & Gas
Casing and Cementation Hardware Market
Oil & Gas
Blockchain in Oil and Gas Market
Oil & Gas
Liner Hanger System Market
Oil & Gas
Romania Oil and Gas Upstream Market
Oil & Gas
Distributed Fiber Optic Sensor in Oil & Gas Market
Oil & Gas
South America Intelligent Pigging Market
Oil & Gas
Smart Well Market
Oil & Gas
Asia-Pacific Underground Coal Gasification Market
Oil & Gas
Wellhead System Market
Oil & Gas
Workover Rigs Market
Oil & Gas
United Kingdom Oil and Gas Midstream Market