
 Aerospace Valves Market | 2026-2036
Aerospace Valves Market Size, Share, and Industry Trends Forecast 2026-2036
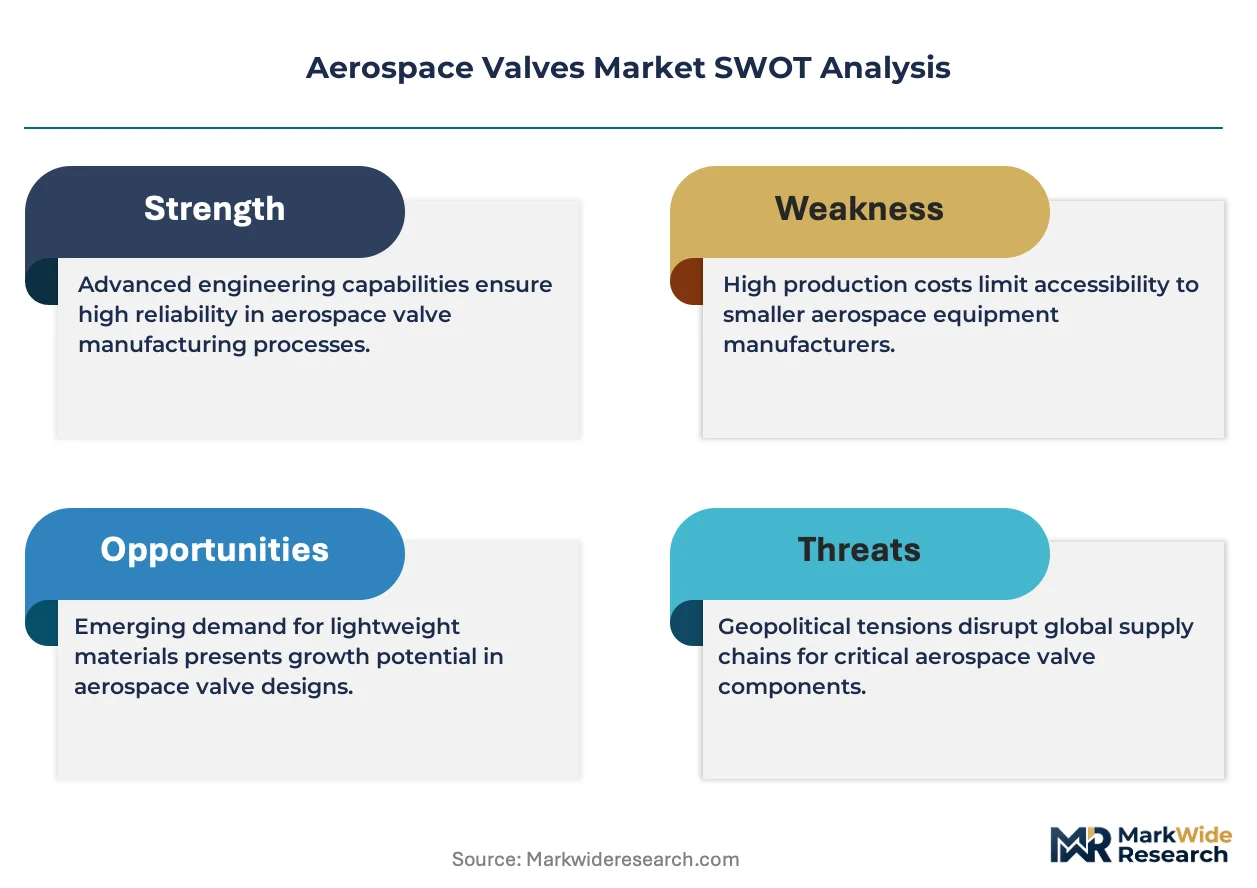
Aerospace Valves Market Analysis
North American precision machining capacity is recalibrating after pandemic-era disruptions, with specialty forgers and additive manufacturers restoring throughput for flight-critical components. Eaton Corporation leverages captive titanium casting operations to secure upstream supply for fuel valve housings. Parker Hannifin Corporation anchors its position through electromechanical actuator integration that reduces hydraulic complexity in next-generation narrow-body platforms. Honeywell International Inc. competes on sensor-embedded valve architectures that enable predictive maintenance protocols for commercial operators.
Aerospace valves are precision-engineered flow control devices manufactured from titanium alloys, stainless steel, or nickel-based superalloys, designed to regulate fluid and gas distribution across propulsion, environmental control, and landing systems under extreme pressure differentials and temperature cycles. Fuel valves incorporate burst-disk safety mechanisms and fire-resistant sealing compliant with FAR 25.963 burnthrough requirements, while hydraulic valves manage actuation forces exceeding 3000 psi in primary flight control circuits. Pneumatic valves dominate engine bleed-air management applications where weight reduction drives titanium adoption over legacy steel configurations. Electromechanical control mechanisms are displacing purely hydraulic architectures in commercial aviation as OEMs pursue more-electric aircraft designs that simplify maintenance intervals and reduce fluid leakage points.
FAA airworthiness directives and EASA CS-25 certification standards mandate redundant shutoff capabilities and fire-containment testing that extend development cycles but elevate technical barriers for new entrants. The EPA's NESHAP regulations for chromium electroplating constrain surface treatment options for corrosion-resistant valve components, pushing suppliers toward plasma-sprayed ceramic alternatives. Stakeholders must monitor evolving FAA propulsion certification timelines for hydrogen-fueled aircraft architectures, as cryogenic valve specifications will reshape material selection and sealing technologies across the supplier base.
Market Dynamics
Electromechanical actuation architectures are compressing hydraulic system complexity across next-generation narrow-body and wide-body platforms, forcing incumbent suppliers to reconfigure manufacturing footprints and certification pipelines for more-electric aircraft designs.
Growth Catalysts
- FAA propulsion certification timelines for hydrogen-fueled aircraft:Cryogenic valve specifications are stimulating R&D investment in nickel-based superalloy sealing technologies and thermal expansion management systems.
- NASA's Artemis program procurement:Sustained demand for high-reliability propellant valves is expanding addressable market scope beyond commercial aviation into crewed spaceflight systems.
- EASA CS-25 fire-containment mandates:Redundant shutoff capability requirements are elevating technical barriers and consolidating procurement toward certified incumbents with established airworthiness track records.
Market Restraints
- Titanium alloy input volatility:Sponge titanium price swings and Russian-origin supply disruptions are compressing margin buffers for precision casters serving fuel valve housing production.
- EPA NESHAP chromium electroplating constraints:Surface treatment restrictions are forcing costly process migrations to plasma-sprayed ceramic alternatives with unproven field longevity.
- Supply concentration in US specialty forging:Pandemic-era capacity attrition has left limited qualified sources for flight-critical titanium valve bodies, creating single-source vulnerability.
Strategic Opportunities
- Predictive maintenance sensor integration:Valve-embedded health monitoring architectures are opening recurring revenue streams through data-enabled service contracts with commercial operators.
- India's defense aerospace modernization:Indigenous fighter and transport programs are creating import substitution openings for valve suppliers establishing local certification partnerships.
- Additive manufacturing qualification pathways:FAA acceptance of laser powder bed fusion for titanium valve components is compressing lead times for complex internal flow geometries.
Industry Challenges
- Cryogenic sealing expertise scarcity:Qualified polymer chemists and metallurgists capable of validating hydrogen-compatible elastomer and metal-to-metal seals remain concentrated within legacy space propulsion suppliers.
- Dual certification burden:Simultaneous FAA and EASA validation timelines for modified valve designs are extending program development cycles and freezing engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Valves Market |
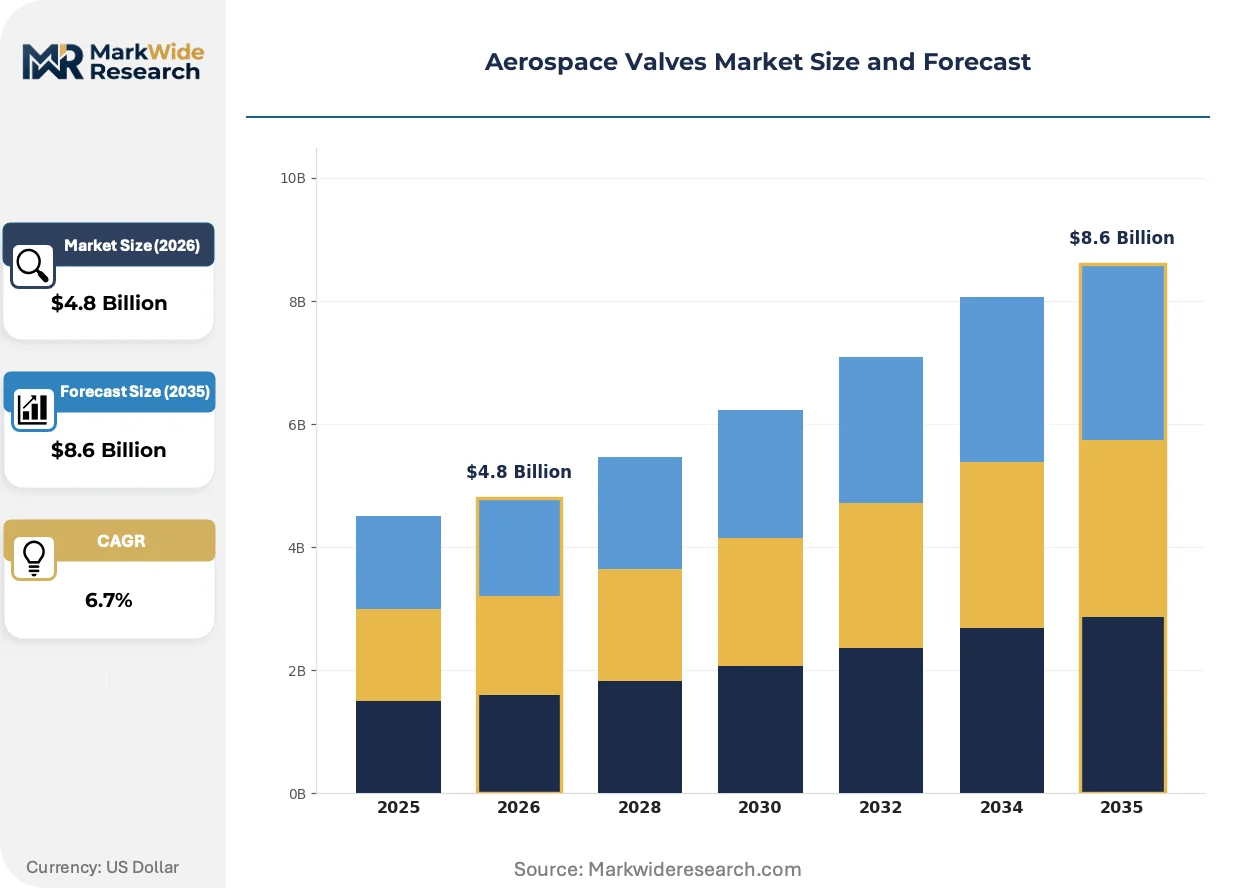
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Fuel Valves, Hydraulic Valves, Pneumatic Valves, Check Valves Application: Commercial Aviation, Military Aviation, Unmanned Aerial Vehicles, Spacecraft Material: Aluminum, Stainless Steel, Titanium, Composite Materials Control Mechanism: Manual, Electromechanical, Hydraulic, Pneumatic |
| Companies Covered | Eaton Corporation, Safran, Woodward Inc., Parker Hannifin Corporation, Honeywell International Inc., Triumph Group, Moog Inc., Meggitt PLC, Liebherr, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Valves Market Emerging Trajectories
Distributed electromechanical control systems are displacing centralized hydraulic manifolds across propulsion and flight control applications, compressing component counts while elevating power electronics integration requirements.
Additive manufacturing of titanium valve housings is consolidating complex multi-piece assemblies into single printed components with internal lattice structures for weight reduction. Tier-one suppliers are adopting laser powder bed fusion for prototype iterations and limited production runs. This consolidation is compressing supplier tiers and forcing machine shops to reposition toward post-processing and inspection services.
EASA's evolving CS-25 certification interpretations for more-electric aircraft architectures are tightening electromagnetic interference and fault-containment requirements for valve actuation electronics. Manufacturers must now validate control electronics to DO-178C software assurance levels previously reserved for flight computers. European narrow-body programs are experiencing the most pronounced certification timeline extensions as a result.
Airline technical procurement teams are unbundling valve maintenance from original equipment manufacturer captive service agreements, instead contracting independent MRO providers with proprietary test cell capabilities. This fragmentation is redirecting aftermarket revenue toward specialized repair stations in Singapore and the United Arab Emirates. Low-cost carriers with narrow-body fleets are driving this disintermediation most aggressively.
Aerospace Valves Market Segmentation
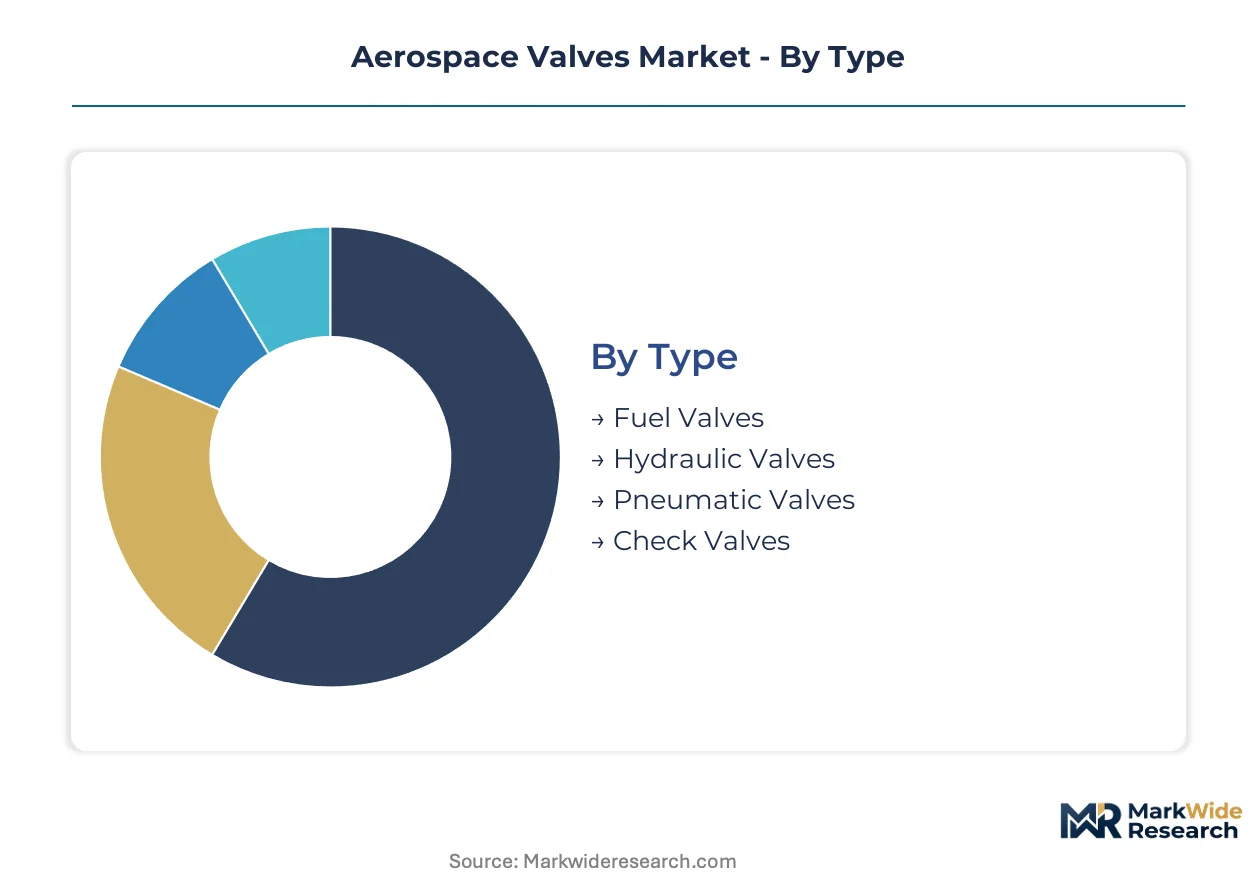
Valve segmentation in aerospace reflects divergent certification intensities and material science thresholds. Each category maps to distinct FAA and EASA approval pathways that shape supplier qualification timelines and manufacturing economics.
Type:
FAA fuel system integrity mandates impose the heaviest certification burden on fuel valve architectures, while hydraulic and pneumatic variants face differentiated pressure-testing protocols under EASA CS-25.
- Fuel Valves:Burst-disk safety mechanisms and fire-resistant sealing compliant with FAR 25.963 burnthrough requirements define these titanium-alloy components. Commercial aviation narrow-body and wide-body platforms concentrate procurement in the United States, where Boeing's supply chain sustains qualified supplier volumes amid sponge titanium price volatility.
- Hydraulic Valves:These stainless steel or nickel-based superalloy devices manage actuation forces exceeding 3000 psi in primary flight control circuits. Military aviation programs in India and indigenous fighter procurement are expanding addressable scope beyond commercial fleets, though dual FAA-EASA validation timelines freeze engineering resources for modified designs.
- Pneumatic Valves:Engine bleed-air management applications favor titanium over legacy steel for weight reduction, with NASA's Artemis program sustaining additional demand for high-reliability propellant variants.
- Check Valves:Unidirectional flow prevention components with simplified actuation requirements, these see concentrated demand in environmental control systems across unmanned aerial vehicle platforms.
Leading the category by volume: Fuel Valves. Expanding most quickly: Hydraulic Valves.
Application:
End-use segmentation tracks divergent procurement patterns across defense budgets, commercial fleet modernization cycles, and civil space investment trajectories.
- Commercial Aviation:Airlines modernizing narrow-body and wide-body platforms drive procurement concentration, with electromechanical actuation architectures displacing hydraulic complexity. Unbundling of valve maintenance from OEM captive service agreements is redirecting aftermarket revenue toward Singapore and UAE repair stations.
- Military Aviation:India's defense aerospace modernization creates import substitution openings for suppliers establishing local certification partnerships with indigenous fighter and transport programs.
- Unmanned Aerial Vehicles:Reduced weight and electromagnetic interference tolerance requirements favor compact electromechanical designs with DO-178C software assurance validation.
- Spacecraft:NASA's Artemis program sustains demand for cryogenic-compatible propellant valves, though qualified polymer chemists and metallurgists for hydrogen sealing remain concentrated within legacy space propulsion suppliers.
Procurement concentrates in: Commercial Aviation. Steepest expansion trajectory: Spacecraft.
Material:
Material selection directly determines forging complexity, thermal expansion management, and surface treatment regulatory exposure under EPA NESHAP constraints.
- Aluminum:Lower-pressure pneumatic applications and non-flight-critical environmental control systems favor these cost-efficient castings, though limited penetration in fuel or primary hydraulic circuits.
- Stainless Steel:Corrosion-resistant grades dominate hydraulic valve bodies where 3000 psi ratings exceed aluminum capabilities, with plasma-sprayed ceramic alternatives displacing chromium electroplating under environmental constraints.
- Titanium:Sponge titanium price swings and Russian-origin supply disruptions compress margin buffers for precision casters serving fuel valve housing production, while additive manufacturing qualification pathways compress lead times for complex internal geometries.
- Composite Materials:Emerging polymer-matrix configurations target unmanned aerial vehicle weight reduction, though FAA acceptance timelines lag metallic alternatives.
Volume leadership: Titanium. Gaining share fastest: Composite Materials.
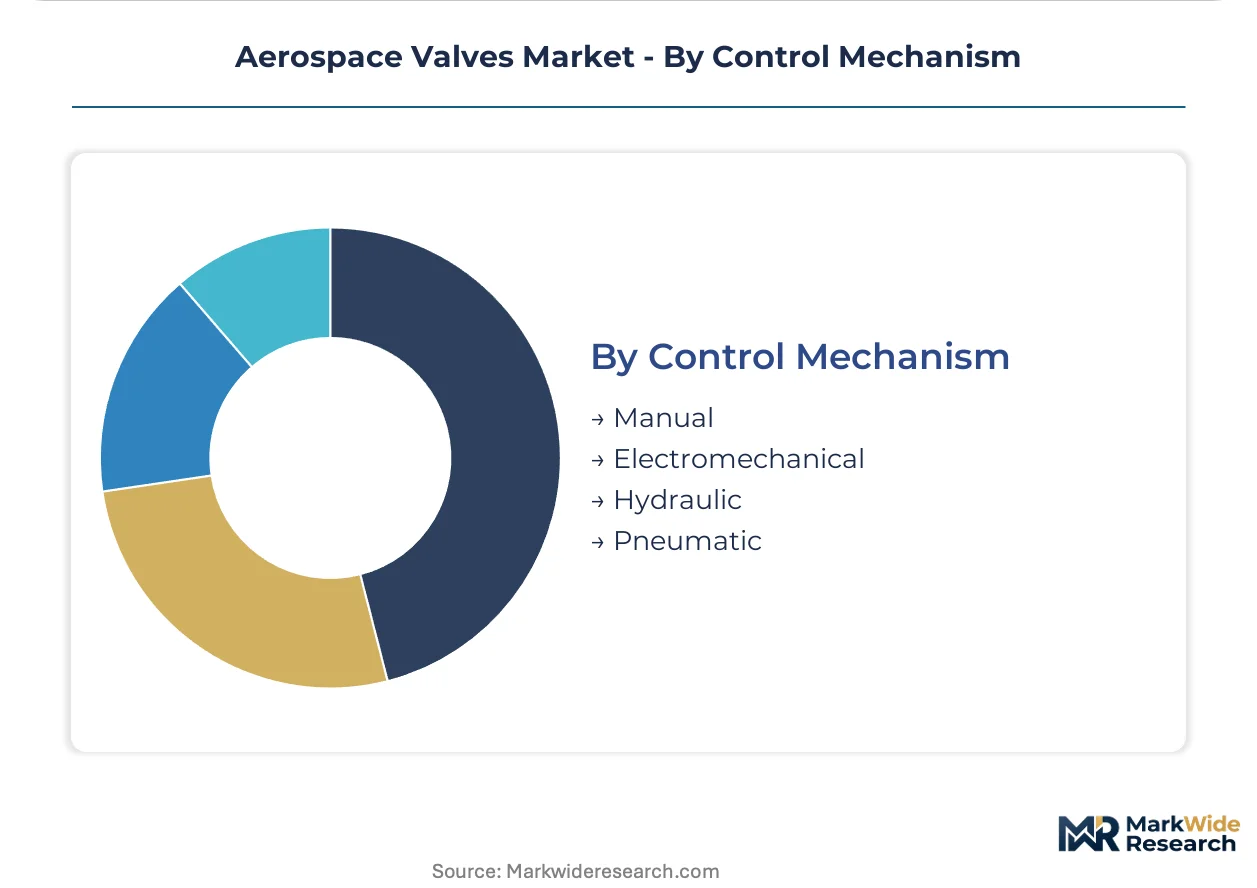
Control Mechanism:
Actuation architecture segmentation tracks the industry transition toward more-electric aircraft designs and associated power electronics integration requirements.
- Manual:Backup and emergency override functions in legacy platforms, with declining procurement share as automated systems achieve certification maturity.
- Electromechanical:Sensor-embedded architectures enable predictive maintenance protocols and recurring revenue through data-enabled service contracts, though EASA's evolving electromagnetic interference requirements extend certification timelines for European narrow-body programs.
- Hydraulic:Centralized manifold configurations face displacement as distributed electromechanical systems compress component counts across propulsion and flight control applications.
- Pneumatic:Engine bleed-air management retains pneumatic preference where thermal cycling tolerance exceeds electromechanical reliability thresholds.
Technology maturity favors: Hydraulic. Climbing the fastest: Electromechanical.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sponge titanium production in the United States and Russia has historically anchored aerospace valve manufacturing geography, though supply chain recalibration is redistributing forging capacity toward alternative sources.
United States
Boeing's commercial narrow-body and wide-body supply chain sustains qualified fuel valve procurement volumes, while NASA's Artemis program drives demand for cryogenic propellant valves. FAA airworthiness directives for fuel system integrity tighten certification standards. Wichita, Kansas and Everett, Washington host precision machining clusters where specialty forgers restore pandemic-disrupted throughput for flight-critical titanium castings.
Germany
EASA CS-25 certification interpretations for more-electric aircraft architectures extend electromagnetic interference validation timelines for European narrow-body programs. The country's national aerospace regulator enforces redundant shutoff capability mandates that elevate technical barriers for valve suppliers. Hamburg and Munich industrial corridors concentrate electromechanical actuator integration expertise for distributed flight control systems.
France
Airbus procurement patterns for next-generation single-aisle platforms compress hydraulic system complexity through electromechanical displacement. The national aviation safety authority applies fire-containment testing protocols that freeze engineering resources for modified valve designs. Toulouse and Nantes manufacturing basins anchor titanium valve housing production for engine bleed-air management applications.
Japan
Domestic defense aerospace modernization and space propulsion investments stimulate demand for high-reliability hydraulic valves exceeding 3000 psi ratings. METI industrial policy supports additive manufacturing qualification pathways for complex internal flow geometries. Nagoya and Tokyo industrial districts host precision forgers developing laser powder bed fusion capabilities for titanium components.
India
Indigenous fighter and transport programs create import substitution openings for valve suppliers establishing local certification partnerships. The country's national standards body and defense procurement frameworks require domestic manufacturing footprints for critical flight systems. Bangalore and Hyderabad aerospace clusters attract foreign suppliers seeking offset arrangements and joint venture structures.
Aerospace Valves Market Vendor Landscape
Global majors compete with regional champions across certification pipelines and captive titanium casting capacity. The supplier base consolidates around tier-one system integrators with established FAA-EASA dual validation track records, while mid-scale specialists occupy niche positions in unmanned aerial vehicle and space propulsion segments. Three archetypes dominate: diversified industrial conglomerates with upstream material control, focused electromechanical specialists with sensor-embedded architectures, and legacy hydraulic component suppliers retooling for more-electric transitions. Competitive positioning hinges on backward integration into titanium forging and strategic partnerships with additive manufacturing qualification bodies.
Among diversified industrial conglomerates, Eaton Corporation and Parker Hannifin Corporation exemplify the integrated-systems archetype with captive supply chain control, while Honeywell International Inc. represents the sensor-embedded predictive maintenance tier. These three occupy positions spanning fuel valve housing production, electromechanical actuator integration, and health-monitoring architectures that enable recurring revenue through data-enabled service contracts with commercial operators.
| Leading Market Players |
|---|
| Eaton Corporation |
| Safran |
| Woodward Inc. |
| Parker Hannifin Corporation |
| Honeywell International Inc. |
| Triumph Group |
| Moog Inc. |
| Meggitt PLC |
| Liebherr |
| Others |
Supply Flow & Price Mechanics
FAA airworthiness directives for fuel system integrity are forcing suppliers to absorb certification cost inflation while commercial airlines unbundle maintenance contracts from OEM captive agreements. This procurement shift compresses margin buffers for precision casters and redirects aftermarket revenue toward independent MRO providers with proprietary test cell capabilities.
Pricing Analysis
Warranty and predictive maintenance service bundling now separates tier-one suppliers from commodity valve producers, with sensor-embedded architectures commanding premium positioning through data-enabled recurring revenue streams. Price differentiation hinges on dual FAA-EASA certification status and captive titanium casting capacity, with certified incumbents extracting margin premiums from narrow-body platform procurement. Cost compression in hydraulic valve tiers is intensifying as electromechanical displacement accelerates, while low-cost carriers with unbundled maintenance strategies exhibit the highest price sensitivity and NASA Artemis contractors the lowest.
Supply Chain Analysis
Regional distribution centers in Wichita, Kansas and Everett, Washington anchor hub-and-spoke patterns for flight-critical titanium valve bodies, with secondary nodes in Hamburg and Toulouse serving European narrow-body programs. Sponge titanium draws from United States and Russian-origin feedstock, while nickel-based superalloy sealing technologies and laser powder bed fusion equipment rest on Japanese and German precision engineering. Single-source vulnerability concentrates in pandemic-depleted US specialty forging capacity, with distribution running through Boeing's tiered supplier pyramid and Airbus's consolidated procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electromechanical actuation architectures are displacing centralized hydraulic systems across commercial aviation, creating asymmetric consolidation opportunities for suppliers with power electronics integration capabilities and dual certification track records.
For Market Incumbents: Anchor market position through backward integration into titanium forging capacity in Wichita or Nagoya industrial districts, insulating against sponge titanium price volatility and Russian-origin supply disruptions. Defend against emerging additive manufacturing specialists by accelerating FAA qualification pathways for laser powder bed fusion propellant valve housings, locking in certification timelines that freeze engineering resources for challengers.
For New Entrants and Emerging Players: India's defense aerospace modernization programs represent the most penetrable buyer archetype, with indigenous fighter and transport procurement creating import substitution openings for valve suppliers establishing local certification partnerships with Bangalore and Hyderabad aerospace clusters. Target unmanned aerial vehicle environmental control systems with compact electromechanical check valve designs, leveraging simplified DO-178C software assurance requirements relative to commercial aviation fuel valve mandates.
For Investors and Strategic Acquirers: The window for entry favors mid-scale specialists with cryogenic sealing expertise and established NASA propulsion supplier relationships, as hydrogen-fueled aircraft certification timelines compress qualified polymer chemist and metallurgist scarcity into acquisition premiums. Monitor FAA propulsion certification timeline announcements for hydrogen architectures as the critical inflection signal, with qualified nickel-based superalloy sealing capabilities becoming the dominant valuation driver across the analysis window.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Titanium Casting Investment | Eaton Corporation's in-house fuel valve housing production secures upstream supply against sponge titanium volatility. |
| Electromechanical Actuator Integration | Parker Hannifin Corporation's distributed flight control architectures reduce hydraulic complexity for Boeing narrow-body platforms. |
| Predictive Maintenance Sensor Embedding | Honeywell International Inc.'s health-monitoring architectures enable recurring revenue through data-enabled commercial operator contracts. |
| Additive Manufacturing Qualification | FAA acceptance of laser powder bed fusion compresses lead times for complex titanium valve internal geometries. |
| Local Certification Partnership | Foreign suppliers establishing joint ventures in Bangalore gain access to India's indigenous fighter procurement frameworks. |
Methodological Framework
Multi-period observation of FAA airworthiness directive issuance patterns, EASA CS-25 certification timeline extensions, and NASA Artemis procurement schedules anchored the trend analysis, supplemented by interviews with valve engineering directors at tier-one system integrators, procurement leads at Boeing and Airbus supply chain divisions, precision forging plant managers in Wichita and Nagoya, and MRO test cell operators in Singapore and Dubai. Secondary validation drew from FAA type certificate databases, EASA certification management system filings, SEC 10-K supply chain disclosures, and USGS mineral commodity summaries for sponge titanium production. Bottom-up segmentation modeling triangulated against top-down aerospace OEM production forecasts.
Input-output matrices mapped titanium alloy input costs, certification engineering hours, and electromechanical component content per valve across type, application, material, and control mechanism dimensions throughout the forecast period. CAGRs were derived from regression analysis of historical procurement volumes against fleet modernization cycles and propulsion technology transition curves. Industry-specific forecast inputs incorporated hydrogen-fueled aircraft certification timeline scenarios and additive manufacturing qualification pathway acceleration assumptions.
Revisions become necessary when FAA propulsion certification timelines for hydrogen architectures materially shift, EASA electromagnetic interference requirements for more-electric aircraft extend beyond modeled scenarios, or Russian-origin titanium sponge supply disruptions exceed pandemic-era attrition baselines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Europe Industrial Valves Market
Valves
Valve Driver Market
Valves
Flow Computer Market
Valves
Flare Stack Monitoring Systems Market
Valves
Valve Interlocks Market
Valves
Steel Cylinder Market
Valves
Global Flow Control Market
Valves
North America Valves Market
Valves
Backflow Preventers Market
Valves
Curb Valves Market
Valves
Electronic Expansion Valves Market
Valves
Naval Actuators and Valves Market
Valves
Valve Grinder Market
Valves
Gate Impellers Market
Valves
Europe Vacuum Insulated Pipe Market
Valves
Dense Phase Vessels Market