
 Leak Detection Market | 2026-2036
Leak Detection Market Size, Share, and Industry Trends Forecast 2026-2036
Leak Detection Market Intelligence
The US Environmental Protection Agency's updated methane emission rules for the oil and gas sector is hardening requirements for continuous monitoring. Honeywell International Inc. leverages its portfolio of fixed gas detectors to serve industrial facilities. Siemens AG competes on integrated software and sensor solutions for utility networks. Emerson Electric Co. specializes in ultrasonic and acoustic technologies for process industries, providing solutions for complex operational environments.
Leak detection comprises systems and methods that identify the unintended escape of fluids or gases from sealed infrastructure. These systems often operate on principles like acoustic wave analysis, detecting specific sound frequencies to pinpoint pipeline failures. The primary purpose is to ensure operational safety, prevent environmental contamination, and minimize product loss. Thermal imaging and acoustic sensors are gaining traction for pipeline monitoring, while fixed leak detection systems constitute a mature product category.
Regulatory frameworks such as the EU's F-Gas Regulation and mandates from the US EPA directly influence system specifications and adoption rates. In China, the Ministry of Ecology and Environment imposes strict standards on industrial emissions, compelling facilities to install compliant monitoring equipment. Vendor selection will increasingly hinge on the ability to provide certified systems that integrate seamlessly with existing digital asset management platforms.
Market Dynamics
Regulatory mandates for emissions reduction and infrastructure safety are the central force shaping the leak detection market. Stricter rules from bodies like the US EPA and frameworks like the EU Green Deal compel asset owners to invest in continuous monitoring, moving the market from periodic inspection to real-time surveillance.
Growth Catalysts
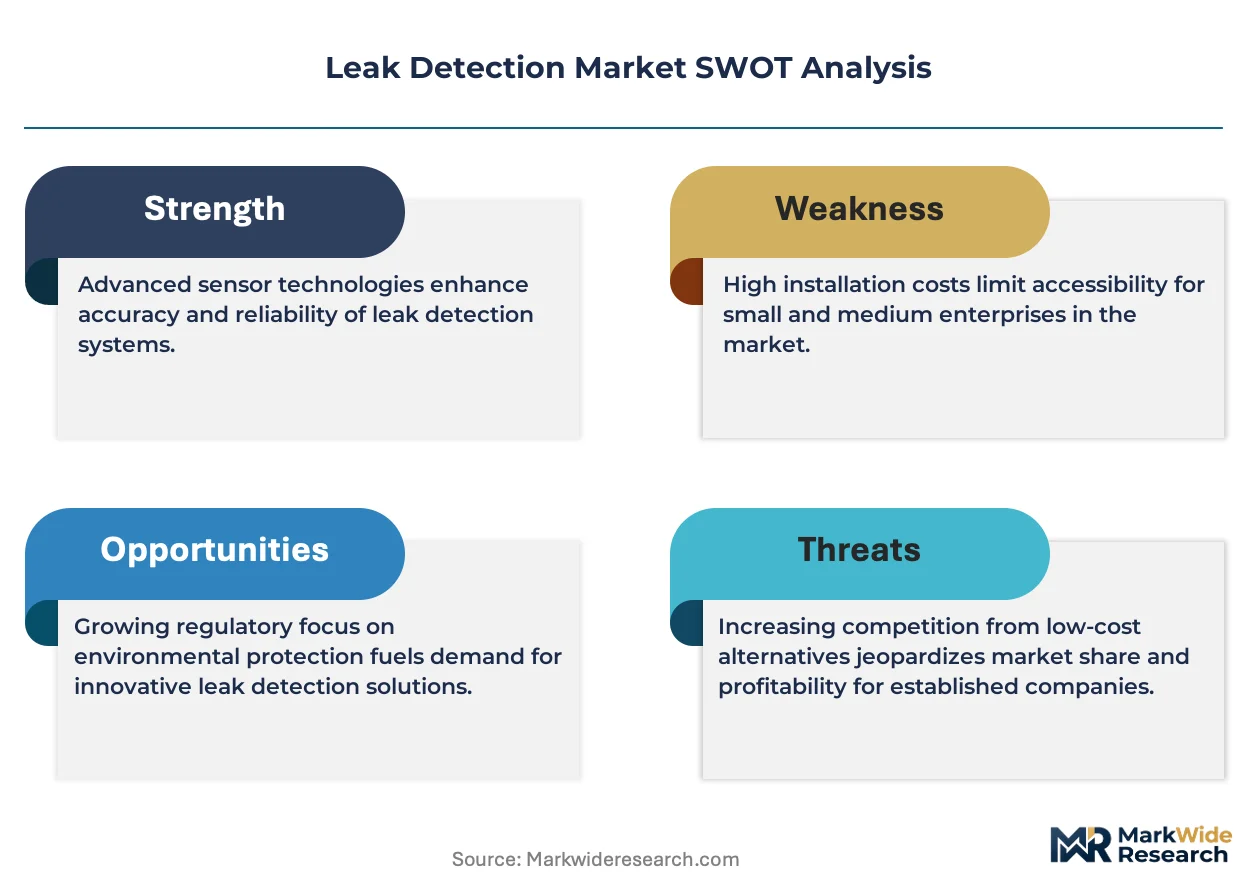
- Stringent Regulations:The EU's F-Gas Regulation and similar mandates in other jurisdictions create a non-discretionary need for certified leak detection systems in the HVAC-R and industrial sectors to control greenhouse gas emissions.
- Oil and Gas Infrastructure:The oil and gas industry's focus on pipeline integrity to prevent product loss and environmental damage drives sustained demand for acoustic and fiber optic monitoring systems.
- Technological Advancement:The increasing accuracy and decreasing cost of sensor technologies, such as thermal imaging and ultrasonic detectors, make advanced monitoring economically viable for a wider range of applications.
Market Restraints
- High Initial Investment:The significant capital expenditure required for deploying comprehensive, network-wide leak detection systems, particularly fiber optic-based solutions, can be a barrier for smaller operators or municipalities.
- Integration Complexity:Integrating new, advanced leak detection sensors with disparate and often outdated legacy SCADA and industrial control systems presents significant technical and financial hurdles for asset owners.
- False Alarm Rates:In acoustically noisy environments like processing plants, traditional acoustic sensors can generate high rates of false positives, which reduces operator trust and system effectiveness without advanced signal processing.
Strategic Opportunities
- Water Utility Modernization:Addressing non-revenue water loss in aging municipal water networks represents a substantial opportunity, particularly in North America and Europe, where infrastructure upgrades are a priority.
- Predictive Analytics Services:The convergence of IoT sensors with AI and machine learning algorithms creates an opportunity for vendors to offer subscription-based predictive maintenance and data analytics services.
- Hydrogen Infrastructure:The development of a global hydrogen economy will require specialized leak detection solutions capable of safely and reliably identifying leaks of this small, highly flammable molecule.
Industry Challenges
- Data Interpretation Skills Gap:A shortage of technicians and engineers qualified to install, maintain, and accurately interpret the complex data generated by advanced sensor systems like acoustic and infrared cameras impedes adoption.
- Lack of Data Standardization:The absence of universal communication protocols and data formats across different vendors' equipment complicates the creation of integrated, multi-vendor monitoring networks for large-scale assets.
- Retrofitting Aging Assets:Modifying existing pipelines, storage tanks, and industrial facilities that were not designed for modern monitoring is often more complex and costly than installing systems in new-build projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leak Detection Market |
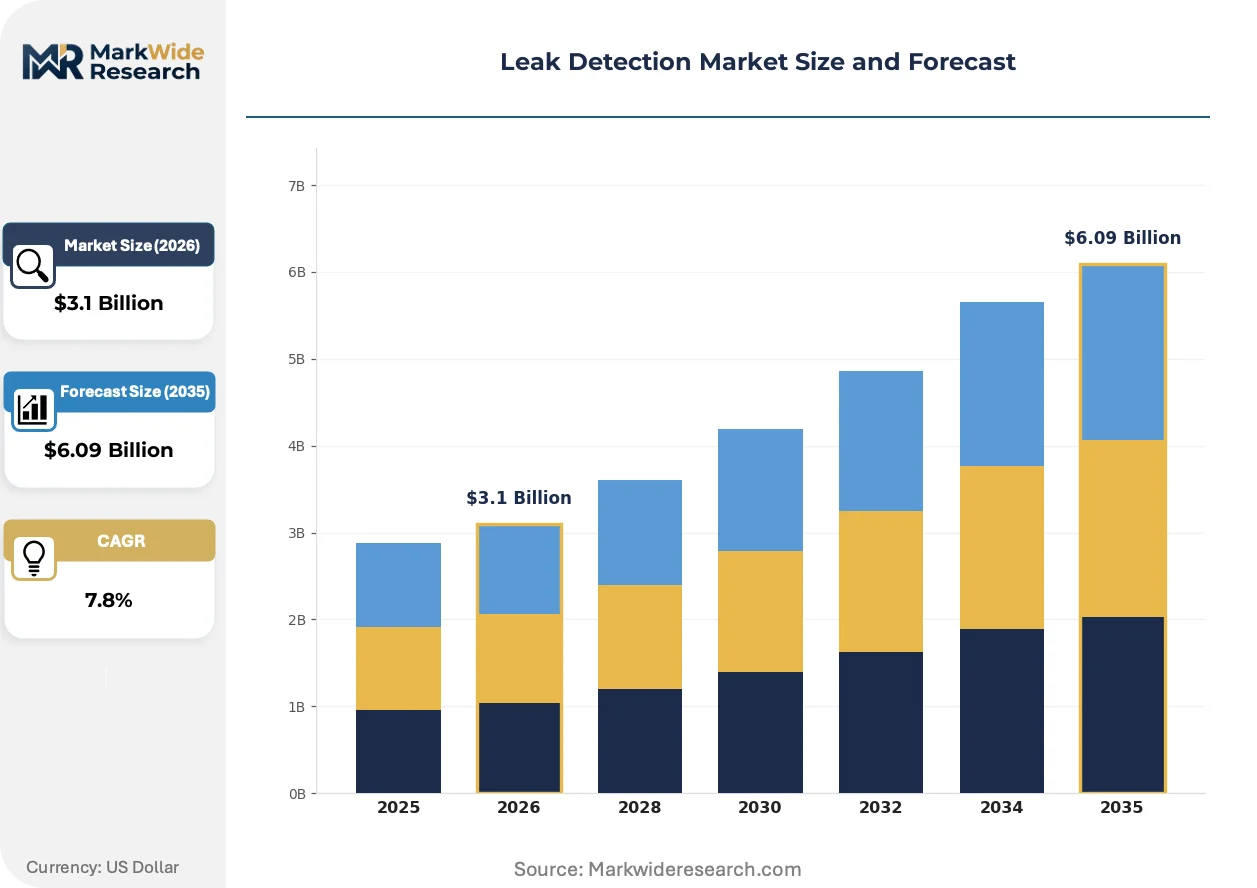
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $6.09 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Acoustic Sensors, Ultrasonic Testing, Thermal Imaging, Pressure Monitoring, Optical Sensors, Electromagnetic Sensors Application: Pipeline Monitoring, HVAC Systems, Water Supply Networks, Fire Protection Systems, Chemical Processing, Gas Distribution End User: Oil & Gas Operators, Utilities Providers, Chemical Manufacturers, Facility Managers, Fire Safety Experts, Municipal Water Authorities Product Type: Portable Leak Detectors, Fixed Leak Detection Systems, Software Solutions, Inspection Cameras, Pressure Sensors, Data Loggers |
| Companies Covered | Honeywell International Inc., Siemens AG, ABB Ltd., Schneider Electric SE, Emerson Electric Co., Aeris Technologies, Inc., Bridger Photonics, TTK, Aquilar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leak Detection Market Strategic Shifts & Innovations
A convergence of sensor technology and data analytics is transforming leak detection from a reactive, alarm-based function into a proactive, predictive maintenance discipline. The market is shifting toward integrated systems that provide a holistic view of asset integrity rather than isolated data points.
AI-powered software platforms process and correlate inputs from diverse sensor types, including acoustic, thermal, and vapor sensors. Oil and gas operators and water utilities are the primary adopters of these advanced analytical tools. This software-centric approach is unifying previously siloed data streams, enabling a single, comprehensive operational view that can predict failures before they occur.
China's Ministry of Ecology and Environment (MEE) has implemented stringent standards for industrial emissions, particularly targeting volatile organic compounds. This forces petrochemical and manufacturing facilities to deploy continuous monitoring systems to comply with Leak Detection and Repair (LDAR) programs. The fixed gas detector segment is directly impacted, requiring vendors to secure MEE certification for market access.
A shift from one-time capital equipment sales to recurring revenue models like Leak-Detection-as-a-Service (LDaaS) is gaining momentum. This model disrupts the traditional equipment distributor channel, as vendors build direct relationships with end-users to offer ongoing monitoring and data analysis. This service-based approach is most visible in North American oil and gas, where operators seek to convert capital expenditures into predictable operational costs.
Leak Detection Market Segmentation
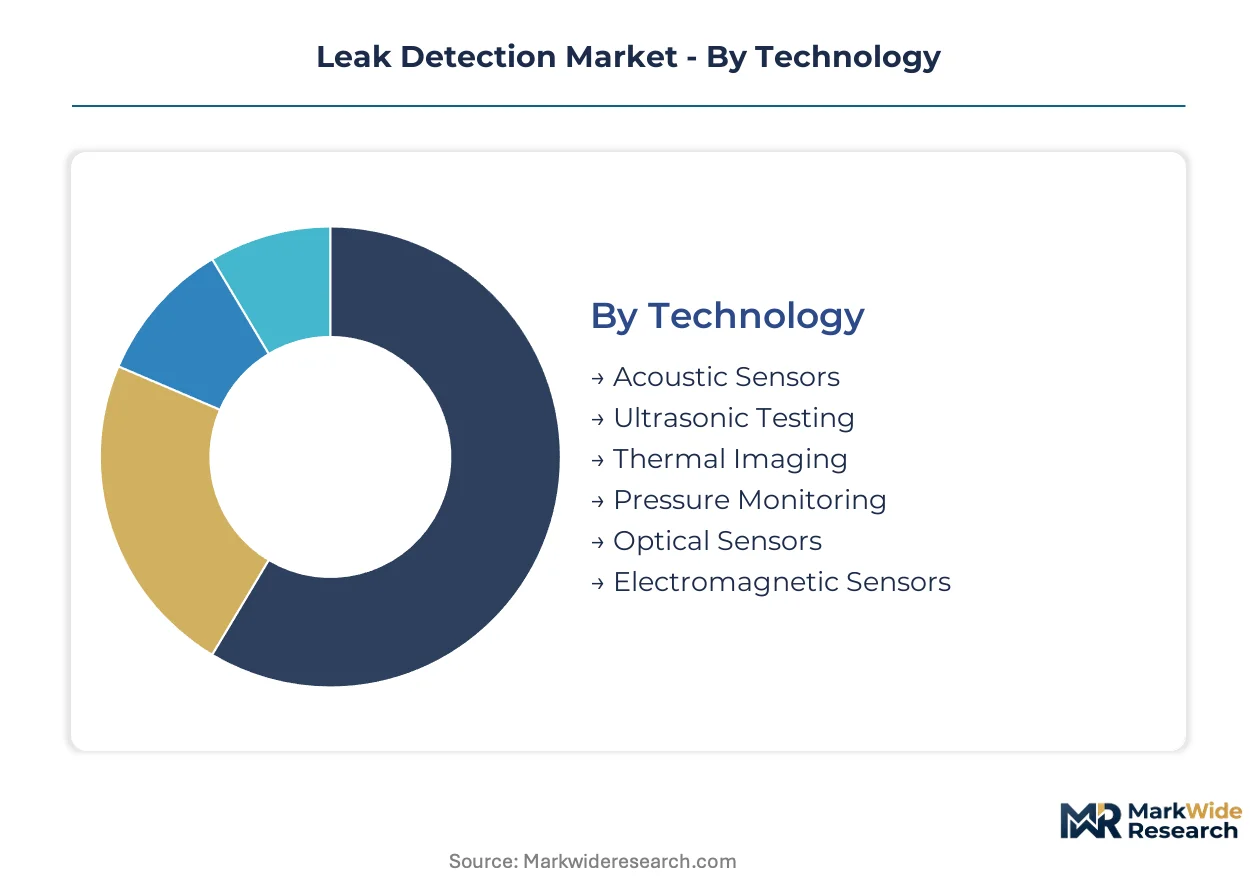
The leak detection market segments across diverse technologies, applications, end-users, and product types, reflecting the varied operational demands for fluid and gas containment. Understanding these distinctions is critical for vendors to tailor solutions for specific industry challenges and regulatory compliance requirements. Each segment addresses unique operational environments and safety mandates.
Technology:
The technology segment reveals a spectrum from standardized sensor components to bespoke integrated systems, reflecting varying customization for leak detection scenarios.
- Acoustic Sensors:These devices identify leaks by detecting specific sound frequencies from escaping fluids or gases, often deployed in pipelines. Demand concentrates in the United States oil and gas sector for continuous pipeline integrity monitoring.
- Thermal Imaging:Infrared cameras visualize temperature differences caused by escaping substances, effective for identifying gas leaks or thermal anomalies. European industrial facilities adopt thermal imaging for methane emission compliance.
- Ultrasonic Testing:High-frequency sound waves detect internal and external flaws in materials, used for non-destructive testing of pressure vessels.
- Pressure Monitoring:Systems track pressure drops within sealed infrastructure, indicating potential leaks in pipelines or storage tanks.
- Optical Sensors:These sensors utilize light absorption to identify specific gas molecules, suitable for detecting hazardous or flammable gases.
- Electromagnetic Sensors:Employing electromagnetic fields to detect changes, these sensors are used for underground pipeline mapping and leak localization.
Most installed capacity flows through Acoustic Sensors. Expansion is steepest in Thermal Imaging, driven by enhanced regulatory scrutiny.
Application:
The application segment highlights diverse operational environments where leak detection is critical, from large infrastructure networks to enclosed industrial spaces.
- Pipeline Monitoring:This application involves continuous surveillance of extensive pipeline networks for oil, gas, and water to prevent environmental damage. The oil and gas sector drives significant demand, particularly in North America.
- Water Supply Networks:Focused on reducing non-revenue water loss, these systems identify leaks in municipal distribution networks. Modernization efforts in aging European water networks are gaining share fastest.
- HVAC Systems:Leak detection for HVAC systems ensures efficient operation and compliance with F-Gas regulations regarding refrigerant emissions.
- Fire Protection Systems:These applications monitor sprinkler systems and fire suppression infrastructure for leaks to maintain readiness.
- Chemical Processing:Leak detection in chemical plants prevents hazardous substance escape, ensuring worker safety and environmental protection.
- Gas Distribution:This application detects leaks in natural gas distribution networks, crucial for safety and minimizing greenhouse gas emissions.
Pipeline Monitoring applications currently command the largest share. Water Supply Networks are gaining share fastest due to global infrastructure modernization initiatives.
End User:
The end-user segment differentiates customers by operational scale and specific regulatory compliance needs, influencing system complexity and integration requirements.
- Oil & Gas Operators:These entities manage vast infrastructure, requiring robust leak detection for safety, environmental protection, and product integrity. Operators in the United States see significant investment.
- Municipal Water Authorities:Responsible for public water supply, these authorities seek solutions to minimize non-revenue water loss and ensure public health. European municipal water authorities see significant investment.
- Utilities Providers:This category includes electricity, gas, and telecommunications utilities requiring leak detection for infrastructure like underground cables.
- Chemical Manufacturers:These facilities handle hazardous materials, necessitating precise leak detection to prevent spills and comply with regulations.
- Facility Managers:Responsible for commercial and industrial buildings, facility managers use leak detection to protect assets and manage utility costs.
- Fire Safety Experts:Professionals in fire safety utilize specialized leak detection to ensure the integrity of fire suppression systems and prevent false alarms.
Oil & Gas Operators represent the largest end-user segment. Municipal Water Authorities are seeing the most significant investment for infrastructure upgrades.
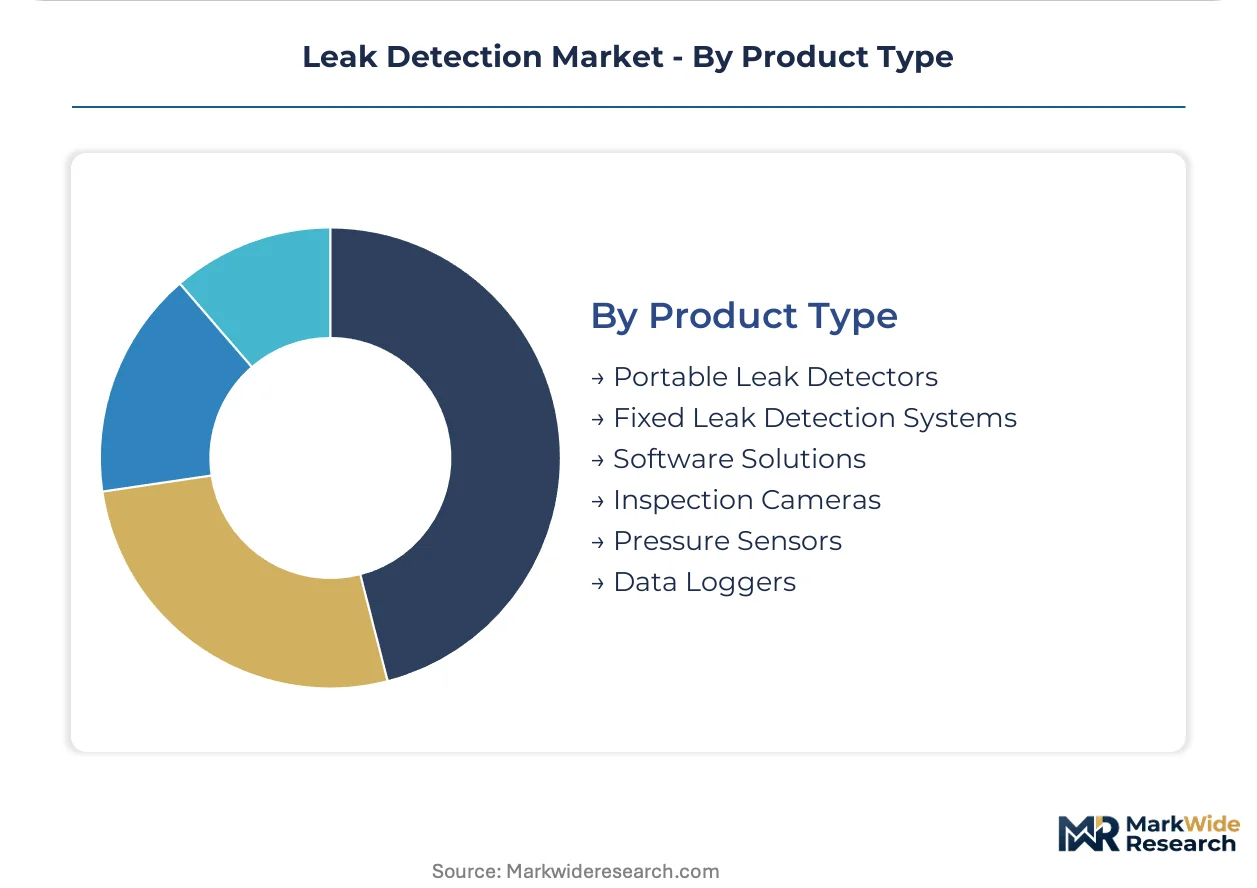
Product Type:
The product type segment spans from mature, standalone devices to sophisticated, integrated software platforms, reflecting diverse technical maturity and system integration.
- Fixed Leak Detection Systems:These permanently installed systems offer continuous, real-time monitoring in critical areas like industrial plants, providing automated alerts. The oil and gas sector drives deployment for continuous monitoring mandates.
- Software Solutions:These platforms integrate data from multiple sensors, providing advanced analytics, predictive capabilities, and centralized management. Utilities providers increasingly adopt software for comprehensive data interpretation.
- Portable Leak Detectors:Handheld devices offer flexibility for spot-checking and rapid fault localization, commonly used by field technicians in various environments.
- Inspection Cameras:Specialized cameras, including thermal and acoustic models, visually identify leaks in hard-to-reach areas for detailed diagnostics.
- Pressure Sensors:Devices that measure pressure changes are fundamental components within larger leak detection systems, indicating potential breaches.
- Data Loggers:These instruments record and store sensor data over time, enabling trend analysis and historical tracking of leak events.
Fixed Leak Detection Systems maintain the largest market share. Software Solutions demonstrate the strongest growth in deployment, driven by advanced analytics demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled technical workforces in industrial hubs globally drive the adoption of advanced leak detection solutions. These workforces are critical for implementing and maintaining the complex systems required by evolving regulatory frameworks and infrastructure demands. Regional market dynamics reflect specific economic development, existing infrastructure, and environmental priorities.
United States
Aging oil and gas infrastructure in the United States necessitates continuous surveillance to prevent environmental incidents and product loss. The US Environmental Protection Agency's updated methane emission rules harden requirements for continuous monitoring. Texas's Permian Basin, a major oil and gas producing region, sees significant investment in pipeline integrity technologies.
Germany
European industrial facilities, particularly in Germany, demand advanced leak detection for methane emission compliance and HVAC-R sector efficiency. The EU Green Deal's stringent methane emission targets compel investment in certified systems. The Rhine-Ruhr region, with its dense concentration of chemical and industrial plants, actively deploys thermal imaging for environmental monitoring.
China
China's industrial sector faces strict standards for volatile organic compounds and other emissions, driving demand for compliant leak detection. The Ministry of Ecology and Environment (MEE) imposes mandates for continuous monitoring under Leak Detection and Repair (LDAR) programs. The Yangtze River Delta, a major manufacturing and petrochemical hub, is a focal point for fixed gas detector deployments.
Canada
Canada's extensive oil and gas pipeline networks require robust leak detection for environmental protection and infrastructure safety. Federal and provincial environmental regulations for hydrocarbon emissions ensure continuous monitoring system adoption. Alberta's oil sands region implements advanced acoustic and fiber optic systems for pipeline integrity management.
Leak Detection Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the leak detection market. The industry exhibits a tiered structure, with established industrial giants offering integrated hardware and software solutions alongside specialized technology firms. Strategic archetypes include diversified industrial conglomerates, niche sensor developers, and software-centric analytics providers. These players increasingly focus on integrating IoT sensors with AI and machine learning algorithms. Companies primarily engage in strategic partnerships for technology integration and portfolio diversification to capture new application areas.
Within the diversified industrial solutions segment, companies such as Honeywell International Inc. and Siemens AG exemplify broad portfolio strategies. These entities leverage extensive engineering capabilities to offer integrated hardware and software platforms across multiple industrial applications. Emerson Electric Co. further anchors the market by providing specialized detection technologies, representing a focus on specific operational environments within process industries. These companies primarily serve large-scale infrastructure owners and utility networks.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Siemens AG |
| ABB Ltd. |
| Schneider Electric SE |
| Emerson Electric Co. |
| Aeris Technologies, Inc. |
| Bridger Photonics |
| TTK |
| Aquilar |
| Others |
Cost & Logistics Intelligence
A clear performance gap between mature fixed systems and advanced software solutions drives a bifurcated pricing structure, which in turn influences component sourcing and supply chain partnerships. This divergence reflects varying technological complexity and integration requirements across the leak detection market.
Pricing Analysis
The bundled-versus-unbundled service split significantly impacts pricing, with comprehensive Leak-Detection-as-a-Service (LDaaS) models offering recurring revenue streams. Project-based pricing dominates for large-scale infrastructure deployments, while transactional per-unit sales characterize portable detectors. Price differentiation stems from certification level, such as MEE compliance, and the extent of customization for integrated systems. Pricing pressure on hardware intensifies due to increasing demand for software integration capabilities. Municipal Water Authorities and smaller operators demonstrate higher price sensitivity, whereas Oil & Gas Operators prioritize system reliability over cost for critical applications.
Supply Chain Analysis
Dual-sourcing requirements for critical components are increasingly mandated by buyers to mitigate supply chain risks. The supply chain for advanced leak detection draws from specialized sensor manufacturing in China and precision engineering expertise in Germany. Raw material dependencies include specialized acoustic, thermal, and optical sensors, alongside advanced microcontrollers for data processing. Single-source vulnerability for highly specialized sensor components presents a structural risk. Distribution runs through direct sales channels for major industrial end-users and utilities, with specialized equipment distributors serving a broader client base.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The leak detection market presents a margin-expansion story, driven by the increasing shift towards software-centric solutions and advanced data analytics that command premium pricing.
For Market Incumbents: Anchor existing client relationships by offering comprehensive, integrated solutions that combine hardware with advanced analytics platforms. Acquire niche software firms specializing in AI-driven data interpretation to counter emerging software-centric players. Invest in certification for new technologies, particularly those addressing methane emissions under stringent EPA and EU Green Deal mandates. Deep integration with enterprise digital asset management platforms will secure long-term contracts.
For New Entrants and Emerging Players: Begin with targeting underpenetrated segments such as the nascent hydrogen infrastructure market, which requires specialized detection capabilities for highly flammable molecules. Focus on developing subscription-based LDaaS models for municipal water authorities to address non-revenue water loss, offering predictable operational costs. A go-to-market angle emphasizing ease of integration and actionable insights for asset integrity will differentiate offerings.
For Investors and Strategic Acquirers: Consolidation pressure builds where specialized software capabilities meet hardware commoditization, creating opportunities for strategic acquisitions. The long-term viability of this market remains strong due to persistent regulatory mandates and aging global infrastructure. Identify acquisition targets among specialized AI/ML analytics firms or sensor technology developers with unique intellectual property for emerging applications. A key signal to watch is the adoption rate of comprehensive LDaaS models by large industrial operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquire AI/ML Analytics Firms | Integrating advanced software enhances predictive maintenance capabilities for end-users. |
| Invest in Hydrogen Detection R&D | Developing specialized solutions addresses critical safety needs for future energy infrastructure. |
| Expand LDaaS Offerings | Shifting to subscription models creates predictable recurring revenue streams for vendors. |
| Secure Regulatory Certifications | Compliance with EPA and EU Green Deal mandates unlocks market access and builds trust. |
| Deepen Digital Asset Integration | Seamless integration with existing platforms simplifies data management for operators. |
Research Approach
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this report. Primary interviews with plant managers, utility engineers, regulatory compliance officers, and sensor R&D leads provided crucial qualitative and quantitative insights. Secondary validation drew from EPA reports, EU F-Gas Regulation documents, company financial filings, and industry association publications, ensuring data integrity.
Historical trendline analysis established foundational market dynamics across the analysis window. The forecast framework integrated various segmentation dimensions, including technology, application, end-user, product type, and regional regulatory environments. Compound annual growth rates were derived through rigorous regression analysis and expert consensus, informed by industry-specific forecast inputs such as regulatory compliance deadlines and infrastructure investment cycles.
Several conditions sit outside the modeled scope, including unforeseen geopolitical events and rapid shifts in global energy policy. Forecasts reflect assumptions regarding consistent regulatory enforcement and the pace of technological innovation. Deviation in major economic downturns or disruptive sensor breakthroughs would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Portable Valve Actuator Market
Valves
Magnetic Coupler Market
Valves
Expansion Valves Market
Valves
Valve Sack Market
Valves
Pressure Gauge Market
Valves
Fin Tube Market
Valves
Pipeline Equipment Market
Valves
Pressure Reducing Valve Market
Valves
Mobile Hydraulic Valves Market
Valves
Blow - Off Valves Market
Valves
Global Valves in Oil and Gas Industry Market
Valves
Battery Pack Cooling Valve Actuator Systems Market
Valves
North America Irrigation Valves Market
Valves
Middle East and Africa Machined Seals Market
Valves
Emergency Shut Down Valves (ESDV) Market
Valves
Europe Valves Market