
 Fin Tube Market | 2026-2036
Fin Tube Market Size, Share, and Industry Trends Forecast 2026-2036
Fin Tube Market Analytics
Project finance for large-scale heat recovery installations is rewriting competitive dynamics in the fin tube supply base. Alfa Laval AB leverages its captive engineering services to bundle financing with equipment procurement. Kelvion Holding GmbH anchors its position through backward integration into fin-forming tooling. Modine Manufacturing Company competes by specializing in lightweight aluminum configurations for transportation HVAC.
Fin tubes are extended-surface heat transfer elements manufactured by helically wrapping or extruding fins onto a base tube, typically achieving surface-area multiplication of tenfold to twentyfold over bare tubing. Their primary purpose is to enhance thermal efficiency in gas-to-liquid or gas-to-gas heat exchange where the gas-side film coefficient limits performance. Aluminum fin tubes dominate volume in air-cooled applications where corrosion resistance and cost efficiency matter most. Titanium fin tubes occupy premium niches in offshore and chemical processing environments where seawater exposure mandates material immunity. Welded fin technology sustains margin pools in high-pressure hydrocarbon service where mechanical bond integrity is non-negotiable.
ASME Boiler and Pressure Vessel Code compliance shapes product qualification timelines for North American power and petrochemical buyers. China's GB/T 151 standard for heat exchangers and the EU Pressure Equipment Directive collectively determine which manufacturers can bid on cross-border infrastructure tenders. Stakeholders must monitor how carbon-border adjustment mechanisms reweight material sourcing decisions between domestic and import supply channels.
Market Dynamics
Power utilities retrofitting aging coal and gas-fired plants with heat recovery systems are compressing procurement cycles and favoring suppliers with bundled engineering services over pure component vendors.
Growth Catalysts
- US EPA Clean Air Act enforcement:Tightening emissions standards for industrial boilers force boiler operators to install economizers and air preheaters, directly expanding fin tube replacement demand.
- China's district heating network expansion:State-backed energy infrastructure programs in northern provinces are specifying high-efficiency finned heat exchangers for centralized thermal distribution.
- Helically wound fin forming:Automated high-speed winding equipment reduces labor content and improves bond consistency, lowering unit costs for carbon steel configurations.
Market Restraints
- Aluminum ingot price volatility:Raw material swings of 15-30% within single quarters compress fabrication margins and deter long-term contracting.
- Welded fin qualification bottlenecks:ASME Section IX welding procedure qualifications require 6-12 month validation timelines, freezing out new entrants from high-pressure hydrocarbon service.
- Compact plate heat exchanger substitution:Swappable plate configurations are capturing maintenance-intensive applications in food processing and pharmaceutical HVAC.
Strategic Opportunities
- India's petrochemical capacity buildout:Reliance Industries and Indian Oil Corporation expansions along the Gujarat coast require corrosion-resistant titanium fin bundles for coastal cooling duty.
- Carbon border adjustment mechanisms:EU CBAM implementation is incentivizing European buyers to source from domestic or low-carbon-intensity suppliers, reshaping import competitiveness.
- Additive manufacturing convergence:3D-printed turbulators integrated with conventional fin tubes are enabling customized flow patterns for geothermal binary cycle plants.
Industry Challenges
- ASME BPVC certification backlog:Third-party inspection agency capacity constraints stretch qualification timelines for North American power sector bids.
- Legacy boiler integration complexity:Retrofit projects require custom header configurations and structural modifications, extending project engineering phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fin Tube Market |
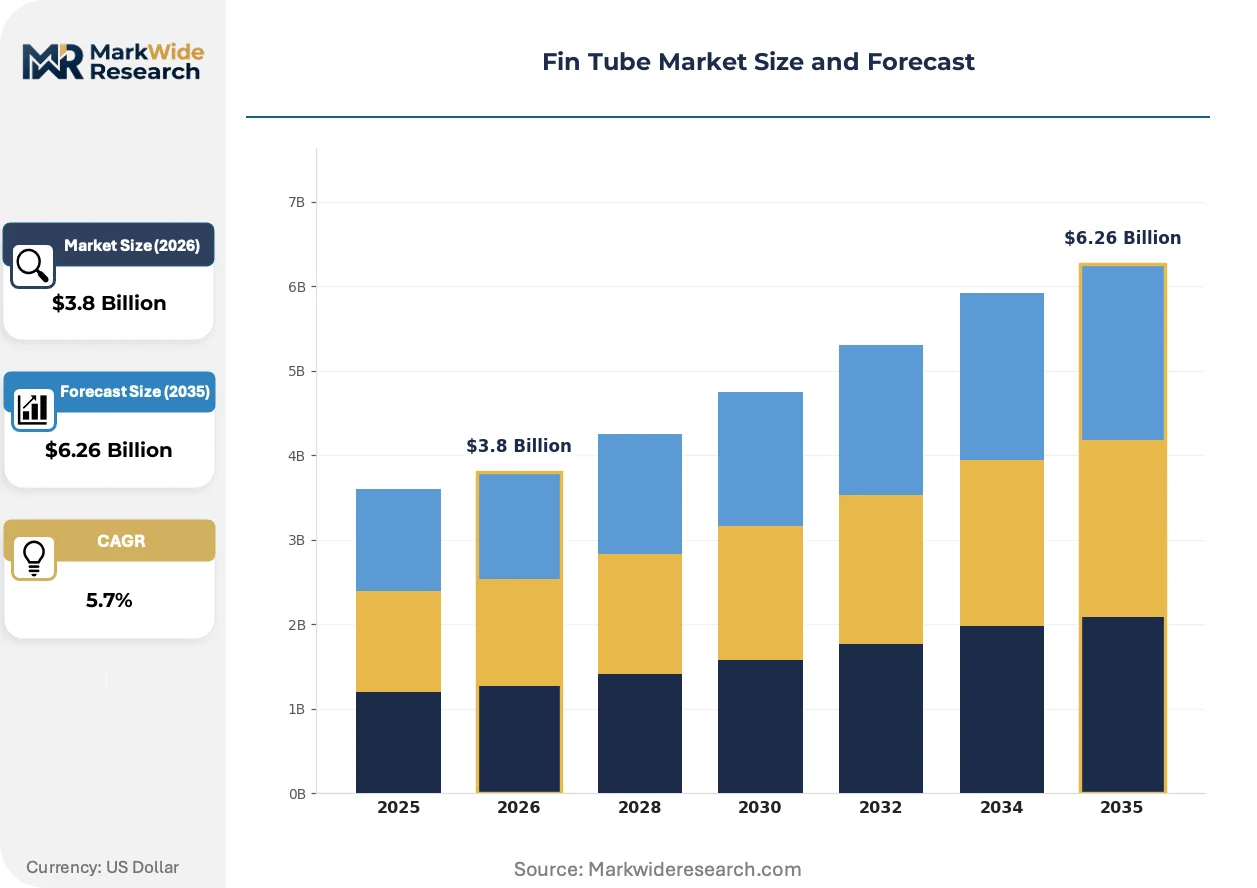
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Fin Tubes, Copper Fin Tubes, Aluminum Fin Tubes, Titanium Fin Tubes Technology: Welded, Extruded, Brazed, Fabricated Application: Heat Exchangers, HVAC Systems, Oil & Gas, Power Generation End User: Construction, Manufacturing, Energy, Marine |
| Companies Covered | Alfa Laval AB, Kelvion Holding GmbH, Modine Manufacturing Company, Danfoss A/S, Fin Tube Products, Inc., Vulcan Finned Tubes, L.P., Wieland Thermal Solutions, Boyd Corporation, PROFINS LIMITED, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fin Tube Market Evolving Landscape
Thermal performance optimization is shifting from incremental fin geometry refinement toward integrated system-level redesign, with material science advances and digital engineering tools compressing development cycles.
Micro-channel aluminum extrusions are collapsing the surface-area-to-weight ratio in automotive HVAC condensers. Tier 1 suppliers to electric vehicle manufacturers are specifying these configurations to extend thermal management range without adding chassis load. The technology is collapsing the addressable market for traditional round-tube-and-plate designs in passenger vehicle climate systems.
The EU F-Gas Regulation phase-down is mandating lower-global-warming-potential refrigerants with reduced thermodynamic capacity. Industrial refrigeration OEMs are responding by specifying enhanced-surface copper tubes with internally grooved profiles to compensate for refrigerant performance degradation. Cold storage warehouse operators in Germany and the Netherlands are driving specification changes fastest.
Asset operators are unbundling after-sales service contracts from original equipment procurement. District heating utilities in Denmark and Sweden now contract finned coil cleaning and retubing through independent service providers rather than captive manufacturer networks. This channel fragmentation is compressing spare parts margins while expanding the addressable market for third-party refurbishment specialists.
Fin Tube Market Segmentation
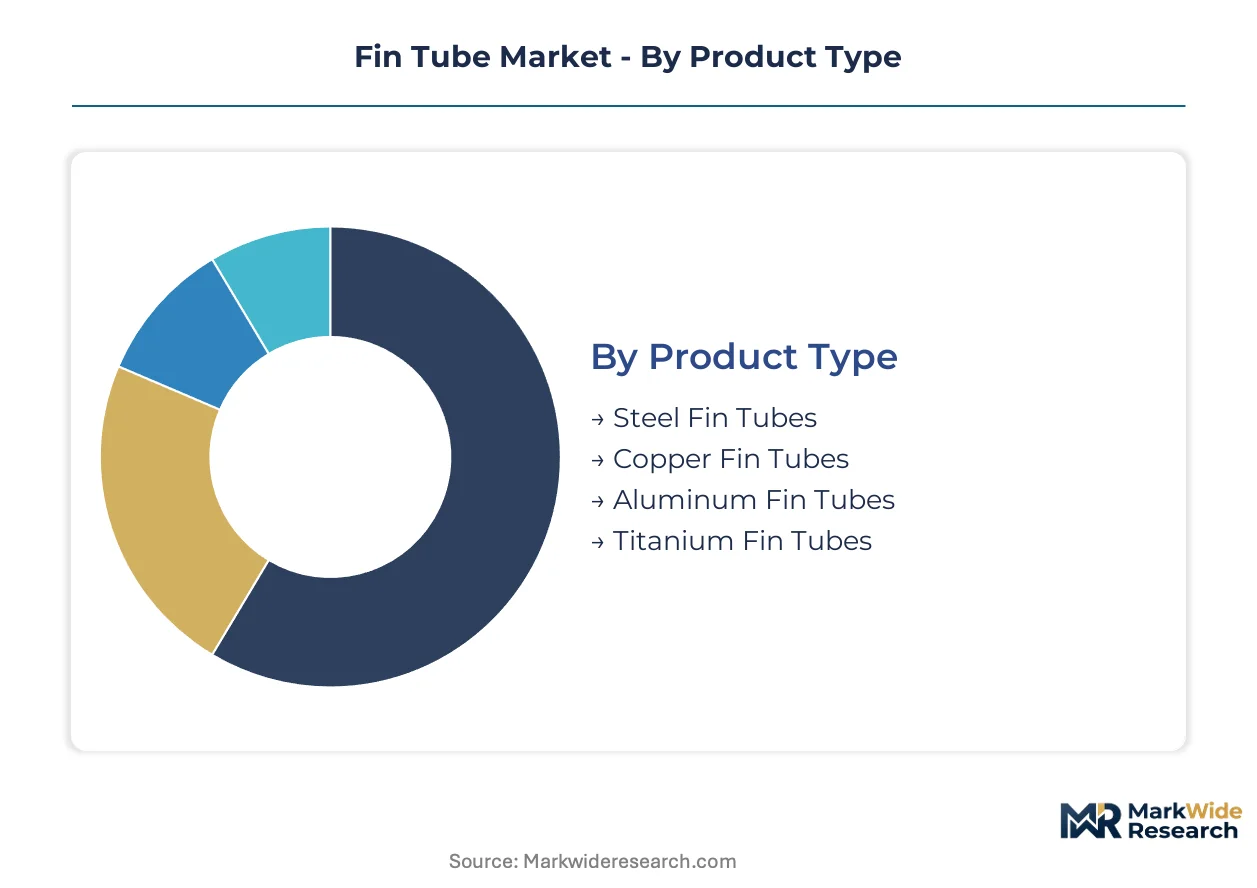
Fin tube specifications vary dramatically across thermal duty cycles, pressure ratings, and corrosion environments. Material selection and bonding technology determine lifecycle economics in ways that reshape procurement patterns by end-use sector.
Product Type:
End-use severity spans from benign air-cooling to aggressive chemical exposure, driving material selection trade-offs between first cost and corrosion immunity.
- Aluminum Fin Tubes:Lightweight extruded or wound aluminum fins on carbon steel or aluminum base tubes deliver the lowest unit cost per square meter of heat transfer surface. District heating utilities in northern China specify these configurations for air-cooled condensers where ambient corrosion remains moderate and weight savings reduce structural steel requirements.
- Steel Fin Tubes:Carbon steel fins helically wound onto steel base tubes withstand thermal cycling in coal-fired boiler economizers where aluminum would soften. US power plant retrofits under EPA Clean Air Act enforcement concentrate procurement here for high-temperature flue gas recovery duty.
- Copper Fin Tubes:Copper's superior thermal conductivity suits HVAC refrigeration circuits where compact coil geometry matters most.
- Titanium Fin Tubes:Seawater immunity commands premium positioning in desalination and offshore platform cooling loops.
The dominant share belongs to Aluminum Fin Tubes, while Titanium Fin Tubes is closing the gap fastest on coastal infrastructure spending.
Technology:
Manufacturing method locks in mechanical bond integrity, thermal performance, and qualification timeline for pressure equipment codes.
- Welded:Resistance welding or laser welding creates metallurgical bonds between fin and tube capable of withstanding thermal shock and high-pressure hydrocarbon service. ASME Section IX qualification requirements stretch procurement cycles, freezing out uncertified suppliers from petrochemical tenders.
- Extruded:Bimetallic extrusion collapses fin-to-tube thermal resistance to near-zero for premium HVAC and refrigeration applications. European cold storage operators driving EU F-Gas Regulation compliance specify extruded copper-aluminum configurations to maximize efficiency with lower-GWP refrigerants.
- Brazed:Furnace brazing achieves uniform bond coverage for complex coil geometries in automotive climate systems.
- Fabricated:Mechanical attachment methods serve lowest-cost replacement markets where bond longevity is secondary to immediate availability.
Welded technology commands premium pricing in hydrocarbon service, while Extruded configurations are expanding most quickly in refrigeration efficiency upgrades.
Application:
Thermal duty characteristics—temperature range, pressure level, fouling tendency—determine specification intensity and replacement frequency.
- Heat Exchangers:Shell-and-tube and air-cooled exchangers in refineries, petrochemical plants, and power stations represent the core installed base. India's Gujarat coast petrochemical expansions require corrosion-resistant bundles for cooling tower duty.
- HVAC Systems:Commercial building climate control and industrial process cooling drive volume demand with shorter replacement cycles. Micro-channel aluminum extrusions are displacing round-tube designs in electric vehicle thermal management.
- Oil & Gas:Upstream production and downstream processing impose sour gas, high-pressure, and subsea exposure requirements.
- Power Generation:Coal, gas, and nuclear plants specify fin tubes for feedwater heating, condensing, and flue gas heat recovery.
Heat Exchangers holds the largest installed base, while HVAC Systems is gaining share fastest on building efficiency mandates and electric vehicle thermal management growth.
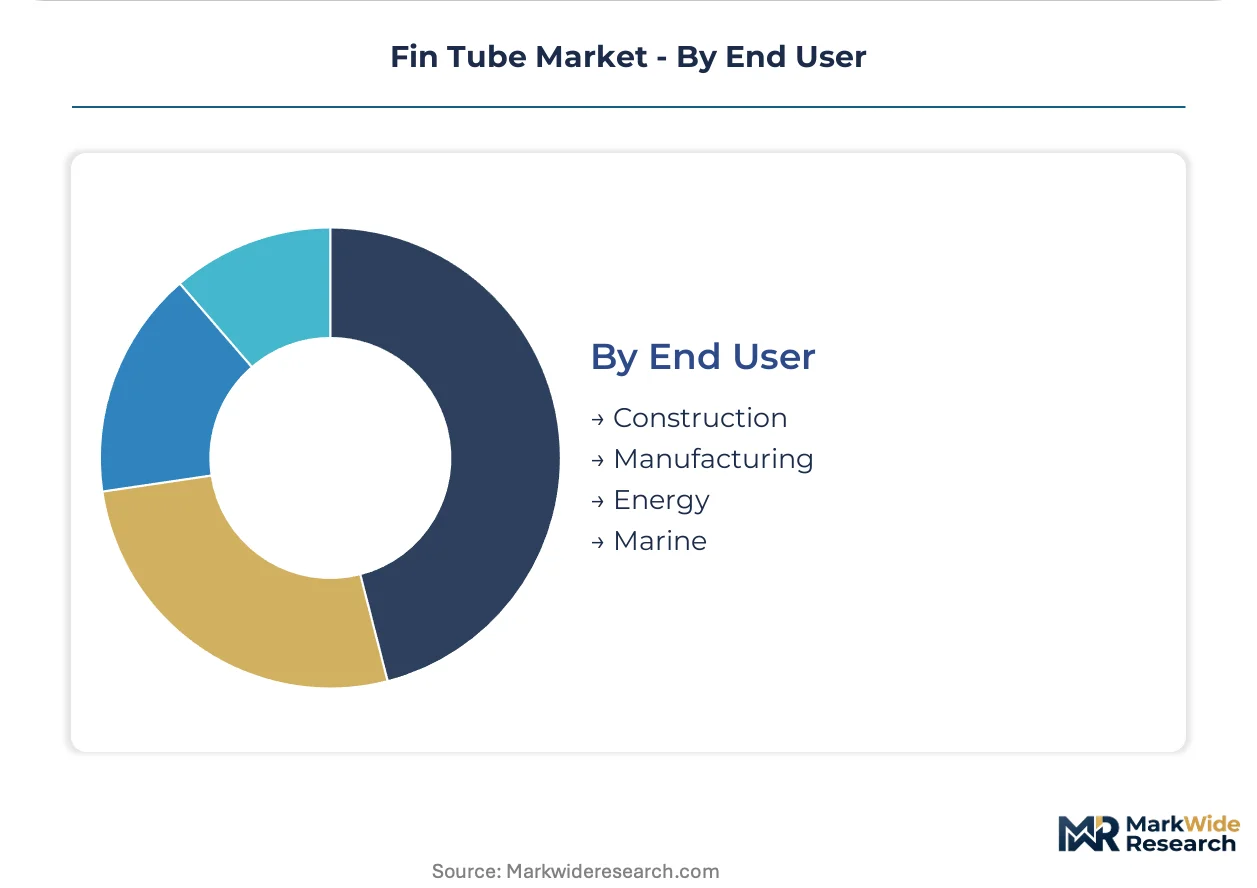
End User:
Capital intensity and operating philosophy diverge sharply between project-driven infrastructure and maintenance-heavy industrial operations.
- Energy:Power utilities and district heating operators run the longest duty cycles and most demanding thermal profiles. China's state-backed northern heating network expansions specify high-efficiency configurations for centralized distribution.
- Manufacturing:Process industries balance thermal performance against production continuity, favoring standardized designs with rapid spare parts availability. Food and pharmaceutical processors increasingly specify swappable plate alternatives for maintenance access.
- Construction:Commercial building HVAC contractors prioritize first cost and installation speed over lifecycle efficiency.
- Marine:Saltwater exposure mandates titanium or cupronickel alloys for seawater cooling circuits.
Energy sector procurement dominates by project value, while Manufacturing end-use is climbing the fastest on process heat recovery retrofits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US EPA's Clean Air Act enforcement is accelerating utility retrofits across multiple jurisdictions. China's state-backed district heating programs are specifying high-efficiency configurations. India's coastal petrochemical expansions are driving corrosion-resistant demand.
United States
Power utilities retrofitting aging coal and gas-fired plants are compressing procurement cycles for economizers and air preheaters. The EPA's emissions standards enforcement under the Clean Air Act mandates boiler upgrades. Industrial clusters in Texas and Louisiana are driving welded fin tube demand for high-pressure hydrocarbon service.
China
State-backed energy infrastructure programs in northern provinces are expanding centralized thermal distribution networks. The country's GB/T 151 standard for heat exchangers shapes procurement specifications for cross-border tenders. Manufacturing concentration in Shandong and Jiangsu provinces supplies domestic district heating retrofits.
Germany
Cold storage warehouse operators are driving specification changes for enhanced-surface copper tubes under EU F-Gas Regulation compliance. The EU Pressure Equipment Directive determines qualification timelines for industrial refrigeration OEMs. Industrial zones in Bavaria and North Rhine-Westphalia anchor refrigeration equipment manufacturing.
India
Reliance Industries and Indian Oil Corporation expansions along the Gujarat coast require corrosion-resistant titanium fin bundles. The country's Bureau of Indian Standards regulates heat exchanger safety for coastal cooling duty. The Gujarat Industrial Development Corporation zone concentrates petrochemical processing capacity.
Japan
Electric vehicle manufacturers are specifying micro-channel aluminum extrusions for thermal management range extension. METI's energy efficiency mandates accelerate HVAC component lightweighting. Automotive supplier clusters in Aichi Prefecture and the Kanto region prototype next-generation climate systems.
Fin Tube Market Competitive Landscape
On the supply side, the industry is tiered between integrated thermal engineering groups and specialized component fabricators. Large-scale project finance capabilities separate bundled-service providers from pure equipment vendors. Strategic archetypes include captive engineering integrators, backward-integrated tooling specialists, and lightweight configuration specialists. Dominant competitive moves encompass geographic expansion into coastal petrochemical corridors and portfolio diversification across refrigerant-transition product lines.
Among European-integrated engineering groups, Alfa Laval AB and Kelvion Holding GmbH represent bundled-service archetypes combining equipment procurement with project financing. Modine Manufacturing Company occupies a position among North American specialists focused on transportation thermal management. These three anchors exemplify how scale, geographic origin, and sector focus stratify competitive positioning across power generation, petrochemical, and automotive end-uses.
| Leading Market Players |
|---|
| Alfa Laval AB |
| Kelvion Holding GmbH |
| Modine Manufacturing Company |
| Danfoss A/S |
| Fin Tube Products, Inc. |
| Vulcan Finned Tubes, L.P. |
| Wieland Thermal Solutions |
| Boyd Corporation |
| PROFINS LIMITED |
| Others |
Value Network & Pricing Analysis
Shanghai-to-Rotterdam container freight corridors transmit aluminum ingot cost volatility directly into European fin tube landed costs, compressing margins for distributors while amplifying price spreads between ASME-certified and uncertified suppliers.
Pricing Analysis
Certification level (ASME Section IX/CE PED/GB-T 151-grade) creates the primary spread between premium welded configurations and economy fabricated alternatives. Project-based long-term contracting dominates energy sector procurement, while spot transactional pricing serves replacement HVAC markets. Price differentiation stems from welding qualification timelines and after-sales service bundling. Cost compression in aluminum extruded tiers is intensifying because of LME price swings, with district heating utilities in China exhibiting highest price sensitivity and offshore petrochemical operators in India showing least.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk calculus for carbon steel base tube sourcing. Manufacturing concentrates in China, Germany, and the United States. Raw material feeds draw from aluminum smelters in Shandong, carbon steel mills in the Ruhr basin, and titanium sponge producers in Japan. Single-source vulnerability persists for high-purity titanium fin stock. Distribution runs through EPC contractor networks for power sector projects and independent HVAC wholesalers for commercial replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fin tube market is in cyclical recovery mode as EPA enforcement and China's district heating buildout drive replacement waves through aging thermal infrastructure.
For Market Incumbents: Build certification moats around ASME Section IX welding procedures to freeze out uncertified competitors from high-pressure hydrocarbon tenders. Deepen backward integration into fin-forming tooling to capture margin pools currently leaking to specialized equipment vendors. Compact plate heat exchanger substitution in food processing threatens traditional coil demand; respond with bundled engineering services that plate alternatives cannot replicate. For New Entrants and Emerging Players: Build out independent aftermarket service capabilities for district heating retubing contracts in Denmark and Sweden, where asset operators are unbundling maintenance from OEM procurement. India's Gujarat coast petrochemical corridor offers the most penetrable geography for corrosion-resistant titanium bundles. Lead with 3D-printed turbulator integration for geothermal binary cycle applications as a differentiated entry wedge. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors tooling-integrated fabricators over pure component vendors as automated helical winding equipment reshapes cost structures. Long-term viability rests on exposure to refrigerant transition cycles and carbon border adjustment mechanics. Watch for EU CBAM implementation intensity as the inflection signal determining import competitiveness reweighting.| Strategic Initiative | Industry Significance |
|---|---|
| ASME Certification Investment | Unlocks bidding eligibility for EPA-mandated utility retrofits in Texas and Louisiana industrial clusters. |
| Backward Integration into Fin-Forming Tooling | Kelvion's captive tooling production anchors margin control against aluminum price volatility. |
| Micro-Channel Aluminum Extrusion Scale-Up | Captures electric vehicle thermal management specifications from Aichi Prefecture automotive suppliers. |
| Independent Aftermarket Service Buildout | Denmark's district heating unbundling creates addressable market for third-party coil refurbishment. |
| Corrosion-Resistant Titanium Bundle Development | Reliance Industries' Gujarat expansions require seawater-immune configurations for coastal cooling duty. |
Research Methodology
Initial hypotheses were tested against primary input from thermal engineering directors, EPC procurement managers, district heating utility maintenance heads, and refrigeration OEM specification engineers and refined through secondary validation against customs trade data, ASME certification registries, EPA enforcement action databases, and GB/T 151 standard revision notices. Bottom-up triangulation across plant-level capacity assessments and top-down demand modeling from end-use sector buildouts converged on volume estimates.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompass material grade, bonding technology, thermal duty intensity, and regional regulatory cluster. CAGRs were derived from installation base depreciation curves and replacement cycle compression observed in utility retrofit programs. Industry-specific forecast inputs included EPA Clean Air Act enforcement timelines and China's northern heating network capital deployment patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by additive manufacturing specialists or compact heat exchanger vendors would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Valve Cover Gasket Market
Valves
Middle East and Africa Machined Seals Market
Valves
Bend Restrictors and Stiffeners Market
Valves
Angle Opening Ball Locator Market
Valves
Industrial Valves and Actuators Market
Valves
Pressure Gauge Market
Valves
Electronic Expansion Valves Market
Valves
Hybrid Valve Market
Valves
Naval Actuators and Valves Market
Valves
Directional Control Valves Market
Valves
Global Level Gauge Market
Valves
Sanitary Valves Market
Valves
North America Butterfly Valve Market
Valves
Compressor Valves Market
Valves
Stainless Steel Valve Tag Market
Valves
Axial and Radial Seals Market