
 Chile Extracorporeal Shock Wave Lithotripsy Market | 2026-2036
Chile Extracorporeal Shock Wave Lithotripsy Market Size, Share, and Industry Trends Forecast 2026-2036
Chile Extracorporeal Shock Wave Lithotripsy Market Intelligence
Ambulatory surgical centers is rebalancing the end-user mix as Chile's healthcare system pushes same-day procedures to reduce hospital bed occupancy. Siemens Healthineers AG leverages its imaging-integrated lithotripsy platforms to dominate the premium hospital segment. STORZ Medical AG sustains competitive positioning through specialized electromagnetic technology leadership in focused ESWL systems. Dornier MedTech GmbH anchors its presence via deep channel control across Chile's largest private clinic chains.
Extracorporeal shock wave lithotripsy employs focused acoustic pulses generated through electrohydraulic, electromagnetic, or piezoelectric mechanisms to fragment urinary calculi without percutaneous incision, typically operating at focal pressures of 10-100 MPa and pulse frequencies between 0.5-2.0 Hz. The technology's primary purpose is non-invasive stone disintegration in the kidney, ureter, and bladder, preserving renal tissue integrity while eliminating surgical recovery periods. Focused ESWL occupies the dominant revenue position due to established clinical efficacy in kidney stone applications, while portable ESWL systems represent the fastest-expanding category as point-of-care deployment extends to mid-sized clinics outside Santiago. Electromagnetic technology leads the installed base for new purchases given its reproducible energy output and lower maintenance burden compared to electrohydraulic alternatives.
Chile's national pharmaceutical regulator, the Instituto de Salud Pública, enforces medical device registration under Decreto Supremo 825 that mandates clinical evidence submissions for ESWL systems entering the market. The Ministry of Health's explicit coverage of lithotripsy under the AUGE/GES guaranteed care plan shapes demand by mandating timely access to stone treatment for insured populations. ISO 13485 quality management certification serves as a de facto market access requirement that filters out non-compliant suppliers. Stakeholders must monitor how Chile's ongoing healthcare decentralization affects equipment procurement autonomy in regional hospital networks versus centralized Ministry purchasing.
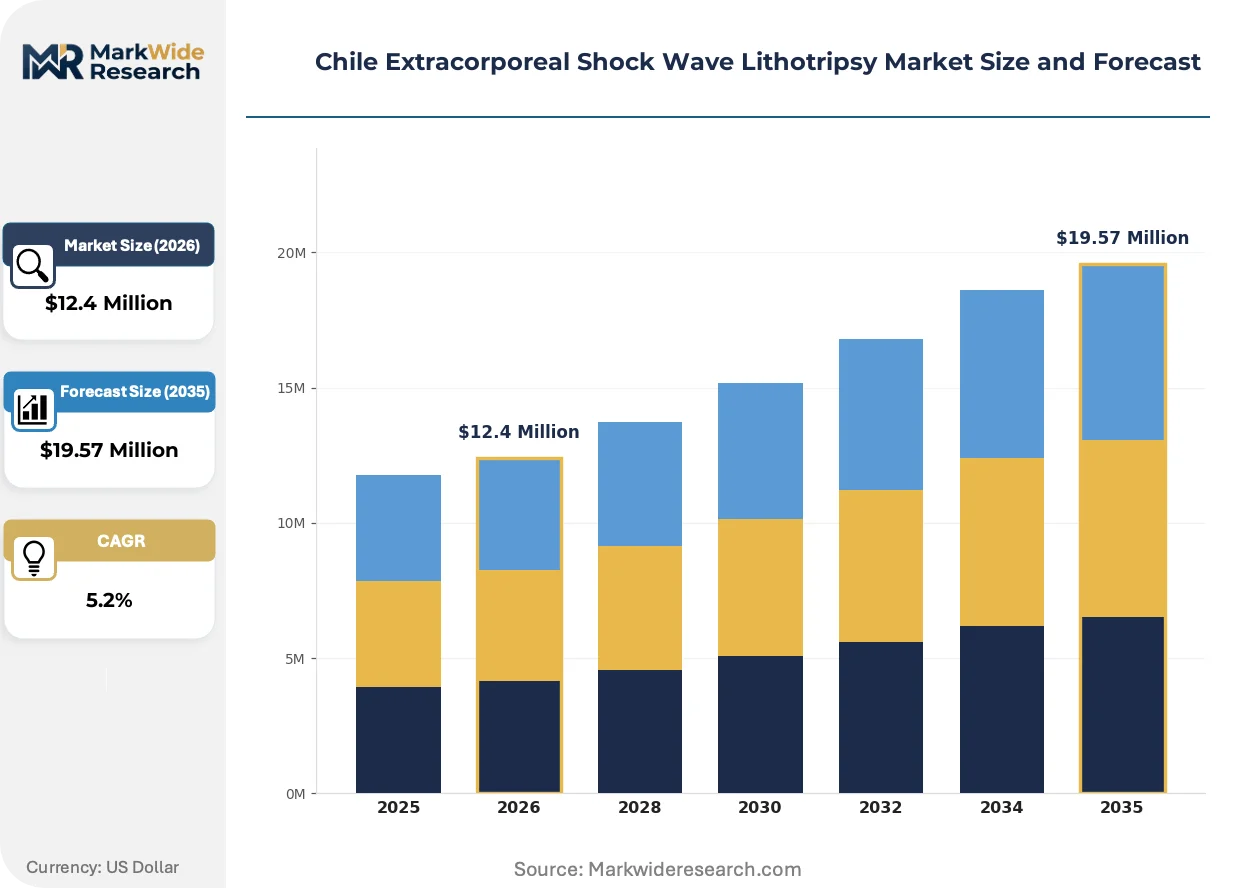
Market Dynamics
Chile's healthcare decentralization is fragmenting procurement authority, shifting equipment purchasing decisions from centralized Ministry of Health control to autonomous regional hospital networks with diverging technical specifications and budget timelines.
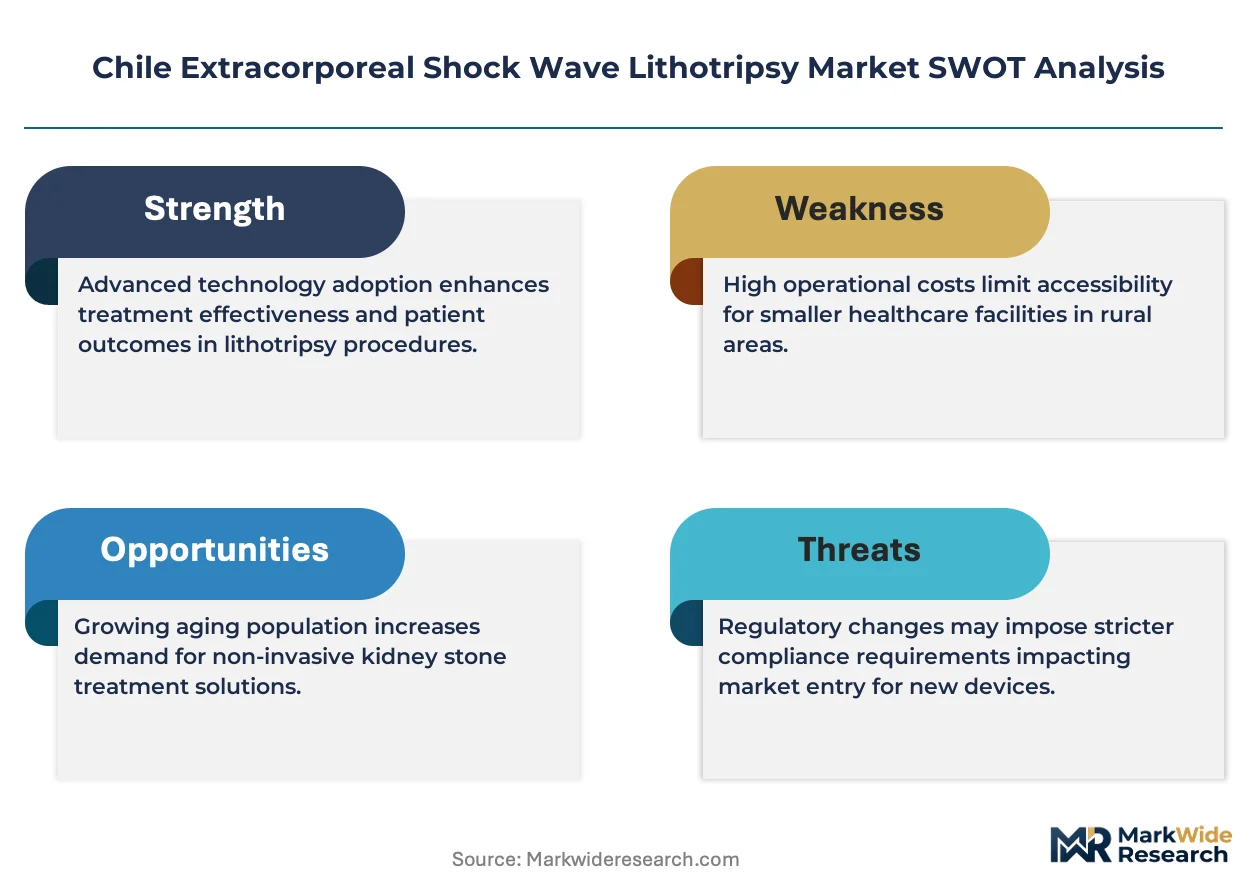
Growth Catalysts
- AUGE/GES Guaranteed Care Plan:The Ministry of Health's mandated coverage of lithotripsy procedures guarantees timely stone treatment access for insured populations, creating steady procedure volume demand across public and private providers.
- Metropolitan Santiago Infrastructure:Concentration of tertiary care facilities and specialist urologist density in the capital region generates procedure clustering that justifies dedicated ESWL capital investments.
- Electromagnetic Technology Maturation:Reproducible energy output and reduced maintenance requirements compared to electrohydraulic systems are accelerating replacement cycles in hospital procurement plans.
Market Restraints
- Decreto Supremo 825 Compliance Burden:Instituto de Salud Pública clinical evidence requirements extend import registration timelines, delaying market entry for new equipment suppliers.
- Electrohydraulic Component Supply:Dependence on specialized electrode suppliers outside South America creates spare parts vulnerability and maintenance cost unpredictability for installed base systems.
- Minimally Invasive Surgical Alternatives:Ureteroscopy and percutaneous nephrolithotomy technique improvements are capturing complex stone cases from ESWL referral pathways.
Strategic Opportunities
- Regional Hospital Networks:Healthcare decentralization in Valparaíso, Biobío, and Araucanía regions is creating procurement autonomy that enables direct supplier relationships outside Santiago's centralized purchasing.
- Portable System Deployment:Point-of-care lithotripsy platforms are opening mid-sized clinic penetration in secondary cities where fixed installation capital constraints previously blocked access.
- ISO 13485 Certification Premium:Quality management certification is becoming a de facto filtering mechanism that rewards compliant suppliers with preferred vendor status in competitive tenders.
Industry Challenges
- Biomedical Technician Specialization:Electromagnetic and piezoelectric system maintenance requires training pipelines that regional hospital networks outside Santiago struggle to staff.
- Legacy Electrohydraulic Integration:Mixed technology fleets complicate service contract standardization and spare parts inventory management for multi-site healthcare operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chile Extracorporeal Shock Wave Lithotripsy Market |
| Market Size in 2026 | $12.4 Million |
| Market Size in 2035 | $19.57 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cylindrical ESWL, Focused ESWL, Burst Wave ESWL, Portable ESWL Application: Kidney Stones, Ureteral Stones, Bladder Stones, Gallstones End User: Hospitals, Clinics, Ambulatory Surgical Centers, Research Facilities Technology: Electrohydraulic, Electromagnetic, Piezoelectric, Laser |
| Companies Covered | Boston Scientific Corporation, Becton, Dickinson and Company, Cook Medical, Siemens Healthineers AG, STORZ Medical AG, Dornier MedTech GmbH, Olympus Corporation, Lumenis, EDAP TMS S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chile Extracorporeal Shock Wave Lithotripsy Market Strategic Shifts & Innovations
Imaging-integrated lithotripsy platforms are compressing procedure times and reshaping competitive differentiation, while regulatory compliance automation and ambulatory care migration are restructuring how equipment reaches end-users.
Dual-source electromagnetic generators with real-time focal zone tracking are rewriting stone targeting precision standards. Metropolitan Santiago's tertiary hospitals are adopting these platforms for complex renal calculi cases within 18-month replacement windows. The technology is rewriting maintenance economics by eliminating electrode replacement cycles and reducing annual service contract costs.
Instituto de Salud Pública electronic submission pathways for Decreto Supremo 825 compliance are compressing registration review periods for established suppliers with prior dossier history. New market entrants face extended clinical evidence requirements that favor incumbents with existing Chilean validation studies. Regional hospital networks are responding by consolidating procurement around pre-registered equipment platforms to avoid procurement delays.
Service unbundling is separating equipment purchase from maintenance contracts in private clinic procurement. Specialist urology chains in Santiago are negotiating direct technical training arrangements with manufacturers, bypassing traditional distributor service markups. This pattern is most visible in Providencia and Las Condes clinic clusters where procedure volumes justify captive technical staffing.
Chile Extracorporeal Shock Wave Lithotripsy Market Segmentation
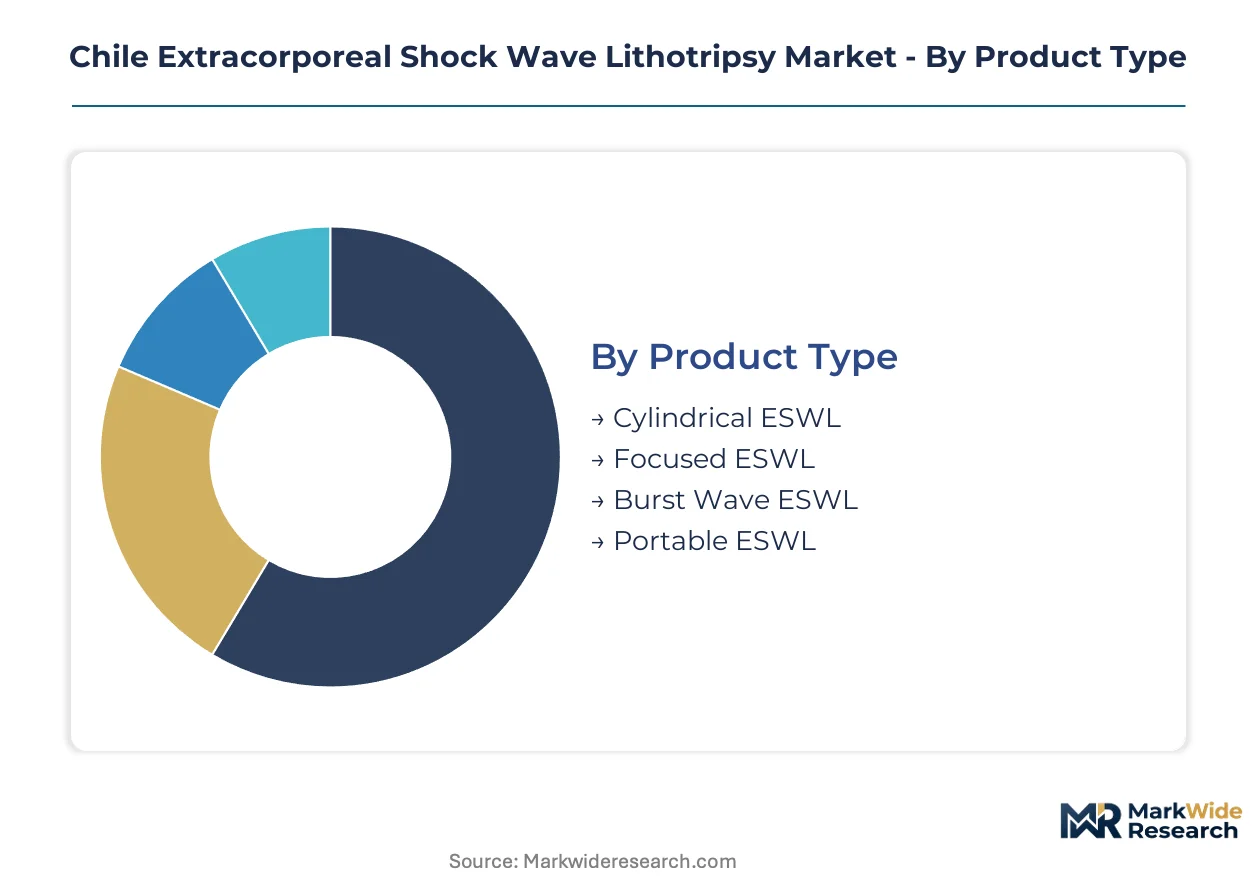
ESWL market segmentation in Chile reveals how technology integration depth, procedure setting, and clinical application shape procurement patterns across public and private healthcare networks. Understanding these dimensions clarifies why certain configurations dominate Santiago's tertiary hospitals while alternative formats penetrate regional markets.
Product Type:
Standalone lithotripsy systems operate as dedicated capital installations with fixed imaging integration, while portable configurations embed shock wave generation into mobile platforms for flexible deployment across multiple clinical sites.
- Focused ESWL:Acoustic pulse concentration at a precise focal point enables kidney stone fragmentation at pressures of 10-100 MPa without tissue penetration. Metropolitan Santiago's tertiary hospitals concentrate demand for these systems due to complex renal calculi referral volumes and specialist urologist density.
- Portable ESWL:Compact electromagnetic or piezoelectric generators mounted on mobile carts permit point-of-care relocation between procedure rooms. Mid-sized clinics in Valparaíso and Biobío regions are adopting these platforms to circumvent fixed installation capital constraints.
- Cylindrical ESWL:Tubular shock wave applicators designed for circumferential stone targeting in specific anatomical positions.
- Burst Wave ESWL:Rapid pulse sequences delivering clustered acoustic energy for enhanced fragmentation efficiency in resistant calculi.
Volume placements concentrate in Focused ESWL; the faster expansion belongs to Portable ESWL.
Application:
Stone location determines acoustic coupling requirements, imaging integration complexity, and reimbursement pathways under Chile's AUGE/GES guaranteed care framework.
- Kidney Stones:Renal calculi treatment represents the foundational ESWL application with established clinical protocols and favorable reimbursement rates. Public hospital networks prioritize these procedures under AUGE/GES mandates, generating predictable procedure volumes.
- Ureteral Stones:Ureteric calculi fragmentation requires modified patient positioning and real-time fluoroscopic tracking. Private urology chains in Providencia and Las Condes specialize in these cases due to faster turnaround times and ambulatory care compatibility.
- Bladder Stones:Lower urinary tract calculi respond to simplified acoustic coupling without complex imaging alignment.
- Gallstones:Biliary lithotripsy occupies a niche position given competing laparoscopic cholecystectomy prevalence.
Procedure volume clusters around kidney stone applications; ureteral stone treatment is climbing the fastest as ambulatory migration accelerates.
End User:
Facility type dictates capital allocation authority, maintenance infrastructure, and patient throughput requirements that filter equipment specifications.
- Hospitals:Tertiary care institutions with dedicated urology departments deploy high-throughput electromagnetic systems integrated with fixed fluoroscopy suites. Santiago's public hospital network anchors installed base concentration.
- Ambulatory Surgical Centers:Same-day procedure facilities prioritize compact footprints and rapid patient turnover compatible with portable ESWL platforms. These centers are gaining share fastest as Chile's healthcare system pushes bed occupancy reduction.
- Clinics:Private specialist practices concentrate in metropolitan areas with selective procedure portfolios.
- Research Facilities:Academic medical centers validate emerging acoustic technologies and train regional biomedical technicians.
Capital commitment concentrates in Hospitals; Ambulatory Surgical Centers are expanding most quickly.
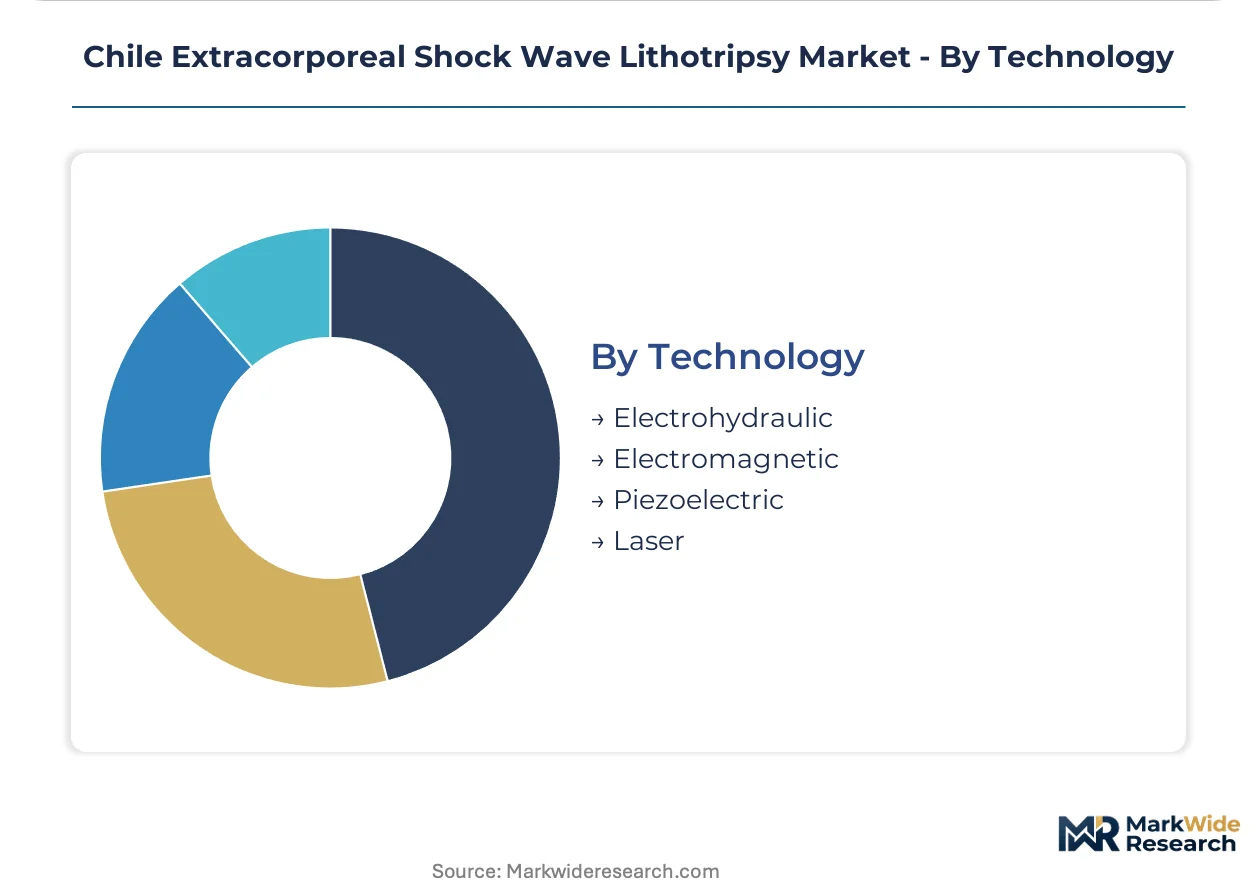
Technology:
Energy generation mechanism determines maintenance burden, pulse reproducibility, and electrode replacement economics that shape total cost of ownership calculations.
- Electromagnetic:Coil-driven membrane vibration produces consistent acoustic pulses without electrode degradation. Hospital procurement plans favor this technology for reduced annual service contract costs and predictable maintenance schedules.
- Electrohydraulic:Spark-gap electrode discharge generates high-pressure shock waves through plasma expansion. Legacy installed base persists in older facilities despite spare parts supply vulnerabilities from non-regional suppliers.
- Piezoelectric:Ceramic crystal arrays enable precise focal zone control with modular repair potential.
- Laser:Holmium and thulium fiber systems compete for ureteral stone cases through direct visual contact.
New purchase volume concentrates in Electromagnetic technology; Piezoelectric systems are gaining share fastest among precision-focused installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zona Franca de Iquique anchors northern Chile's medical device import concentration through duty-exempt warehousing that accelerates ESWL equipment customs clearance before inland distribution to Santiago and regional hospital networks.
Metropolitan Santiago
Tertiary care infrastructure density and specialist urologist concentration drive ESWL procedure clustering in Providencia, Las Condes, and Ñuñoa districts. The Ministry of Health's AUGE/GES guaranteed care mandates shape public hospital procurement calendars. Private urology chains in Santiago's eastern communes deploy imaging-integrated platforms for complex renal calculi cases.
Valparaíso Region
Port logistics connectivity and expanding regional hospital autonomy under healthcare decentralization enable direct supplier relationships outside centralized Ministry purchasing. The Instituto de Salud Pública maintains identical Decreto Supremo 825 registration requirements for imported devices. Viña del Mar and Valparaíso municipal hospitals are consolidating procurement around pre-registered electromagnetic platforms.
Biobío Region
Industrial manufacturing heritage supports biomedical technician training pipelines for electromagnetic system maintenance. Regional hospital networks in Concepción and Talcahuano exercise procurement autonomy to negotiate service unbundling contracts. Mid-sized clinics adopt portable ESWL configurations to circumvent fixed installation capital constraints.
Araucanía Region
Rural healthcare access priorities under AUGE/GES expansion create demand for point-of-care lithotripsy deployment in Temuco and surrounding provincial centers. The regional health service's equipment replacement cycles lag Santiago by 24-36 months. Portable system penetration accelerates as ambulatory surgical center licensing expands beyond metropolitan cores.
Chile Extracorporeal Shock Wave Lithotripsy Market Key Industry Players
Top-tier vendors anchor the premium hospital segment, while mid-tier specialists and regional distributors occupy procurement channels outside Santiago's tertiary centers. Siemens Healthineers AG leverages imaging integration to dominate fixed-installation electromagnetic platforms. STORZ Medical AG sustains positioning through focused ESWL technology specialization. Dornier MedTech GmbH maintains channel control across private clinic chains. Competitive moves concentrate on service contract unbundling and direct technical training arrangements that bypass traditional distributor markups.
Among Germany-based manufacturers, Siemens Healthineers AG, STORZ Medical AG, and Dornier MedTech GmbH exemplify the tiered structure shaping Chile's procurement landscape. These entities occupy positions aligned with distinct end-user segments—tertiary hospitals, specialized urology chains, and regional networks respectively. Their collective presence filters market access through ISO 13485 certification requirements and Decreto Supremo 825 registration histories that disadvantage new entrants lacking prior Chilean clinical validation studies. The archetype distribution rewards established suppliers with preferred vendor status in competitive tenders while compressing margins for distributors dependent on service markups.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Becton, Dickinson and Company |
| Cook Medical |
| Siemens Healthineers AG |
| STORZ Medical AG |
| Dornier MedTech GmbH |
| Olympus Corporation |
| Lumenis |
| EDAP TMS S.A. |
| Others |
Cost & Logistics Intelligence
Biomedical technician concentration in Metropolitan Santiago generates labor-cost spreads that stratify equipment pricing across premium electromagnetic platforms and economy-tier electrohydraulic alternatives. Regional hospital networks outside the capital absorb higher service contract premiums due to scarce qualified maintenance staff, compressing margins on mid-tier offerings.
Pricing Analysis
Short lead-time premiums command substantial markups as regional hospital networks bypass centralized Ministry procurement to secure immediate electromagnetic system availability. Pricing stratifies across premium, standard, and economy tiers based on ISO 13485 certification grade and bundled after-sales service depth. Cost compression in the economy tier is intensifying as private clinic chains negotiate direct technical training arrangements that eliminate distributor service markups. Public hospital procurement committees demonstrate highest price sensitivity due to fixed AUGE/GES reimbursement ceilings, while private urology chains in Providencia and Las Condes prioritize imaging integration over unit cost.
Supply Chain Analysis
Dual-sourcing requirements for electromagnetic coil assemblies and imaging sensor modules compel manufacturers to qualify suppliers across Germany, Japan, and the United States. Component sourcing draws from specialized electrode suppliers outside South America, ceramic crystal arrays from Japanese manufacturers, and fluoroscopy integration subsystems from German imaging specialists. Single-source vulnerability in electrohydraulic electrode supply creates maintenance cost unpredictability for installed base systems. Distribution runs through Zona Franca de Iquique duty-exempt warehousing before inland deployment to Santiago and regional networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified biomedical technician scarcity props pricing power for suppliers capable of delivering captive training pipelines alongside equipment sales.
For Market Incumbents: Anticipate ureteroscopy and percutaneous nephrolithotomy technique improvements capturing complex stone referrals by deepening electromagnetic technology leadership and accelerating real-time focal zone tracking adoption. Channel control through direct technical training arrangements with specialist urology chains defends margin position against service unbundling pressure from procurement-sophisticated buyers. For New Entrants and Emerging Players: Launch via portable ESWL platform distribution to ambulatory surgical centers in Valparaíso, Biobío, and Araucanía regions where fixed installation capital constraints previously blocked market access. Point-of-care deployment in secondary cities outside Santiago represents the most penetrable white space, with service contract bundling as the critical go-to-market angle against incumbent premium positioning. For Investors and Strategic Acquirers: Re-rating potential sits with electromagnetic technology specialists possessing established Instituto de Salud Pública registration histories given Decreto Supremo 825 compliance barriers that disadvantage unvalidated newcomers. Long-term viability hinges on procurement autonomy expansion under healthcare decentralization. Monitor regional hospital network service unbundling adoption as the inflection signal for distributor-dependent margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Quality management certification filters non-compliant suppliers from competitive tenders. |
| Regional Hospital Network Partnership | Direct supplier relationships in Valparaíso and Biobío bypass centralized Ministry purchasing. |
| Portable System Development | Compact electromagnetic platforms penetrate mid-sized clinics with capital constraints. |
| Technical Training Pipeline Establishment | Captive biomedical technician programs address workforce scarcity outside Metropolitan Santiago. |
| Imaging Integration Advancement | Real-time focal zone tracking compresses procedure times in tertiary hospital settings. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs that were cross-referenced against primary interviews with hospital procurement managers, biomedical engineers, urology department heads, and GPO contracts managers. Instituto de Salud Pública device registration databases, Ministry of Health AUGE/GES procedure volume reports, and Zona Franca de Iquique import manifests supplied quantitative foundations. Bottom-up equipment placement tallies reconciled with top-down healthcare expenditure estimates across the analysis window.
Data-stream reconciliation between procedure volume projections and capital equipment replacement cycles generated segmentation-specific growth trajectories. The model disaggregated revenue by product type, technology mechanism, application setting, and end-user facility class. CAGRs were derived from installed base turnover analysis and procurement calendar alignment with AUGE/GES mandate expansion. Electromagnetic technology maturation curves and regional hospital autonomy indices informed scenario-weighted outputs.
The model assumes a particular technology adoption path; alternative pathways for piezoelectric system penetration would alter the outlook if focal zone precision gains accelerate beyond current electromagnetic benchmarks. Deviation in healthcare decentralization implementation pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Coatings Market
Medical Devices
Global Cerebrospinal Fluid Management Devices Market
Medical Devices
Global Transcatheter Embolization and Occlusion Devices Market
Medical Devices
General Surgical Devices Market
Medical Devices
Europe Otoscope Market
Medical Devices
Intraoperative Sensor Market
Medical Devices
Medical Devices Reimbursement Market
Medical Devices
Transcutaneous Oximetry Systems Market
Medical Devices
Europe Minimally Invasive Surgery Devices Market
Medical Devices
Global Augmentative and Alternative Communication (AAC) Devices Market
Medical Devices
General Surgery Devices Market
Medical Devices
Electrocardiograph (ECG) Market
Medical Devices
Global Surgical Visualization Systems Market
Medical Devices
Active Implantable Devices Market
Medical Devices
Blood Warmers Market
Medical Devices
Non-Magnetic Wheelchair Market