
 Latin America Dental Devices Market | 2026-2036
Latin America Dental Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Dental Devices Market Foresight
Brazil's industrial base for precision-machined titanium abutments is fragmenting as regional assemblers enter the supply chain. Dentsply Sirona leverages its integrated CAD/CAM workflow platforms to dominate chairside restoration systems across São Paulo and Rio de Janeiro. Straumann Group anchors premium implantology through its tissue-level and bone-level portfolio, while Envista Holdings Corporation competes on instrument breadth across the mid-tier clinic segment.
Dental devices encompass instruments, equipment, and consumables engineered from biocompatible alloys, zirconia, and resin composites for oral diagnosis, treatment, and rehabilitation. Titanium alloy implants typically achieve osseointegration thresholds of 35 Ncm insertion torque, with surface modifications such as SLA etching enhancing bone-to-implant contact ratios. Orthodontic devices and dental implants command the deepest margin pools due to recurring consumables and high replacement cadence, while CAD/CAM technology displaces conventional impression workflows fastest among dental laboratories seeking same-day crown throughput.
ANVISA governs medical device registration and Good Manufacturing Practice compliance for imports into Brazil, while Mexico's COFEPRIS enforces equivalent premarket authorization for dental materials crossing its border. Argentina's ANMAT maintains parallel vigilance requirements that lengthen entry timelines for unfamiliar manufacturers. Stakeholders must monitor regulatory harmonization progress under MERCOSUR's proposed unified device framework to preempt distribution restructuring.
Market Dynamics
Digital dentistry workflows are compressing turnaround times for crown and bridge restorations across Brazil's private clinic network, forcing equipment suppliers to bundle chairside milling with intraoral scanning subscriptions rather than sell discrete hardware.
Growth Catalysts
- ANVISA pathway streamlining:Brazil's medical device regulator has consolidated technical documentation requirements for Class III dental implants, reducing registration timelines for European and North American manufacturers seeking southeastern state market entry.
- Metropolitan corridor density:São Paulo's concentrated population of private-pay patients sustains specialist clinic clusters that amortize CAD/CAM capital across high daily patient throughput.
- Titanium surface engineering:SLA and SLActive etching protocols now dominate premium implantology, with modified topography accelerating osseointegration timelines and supporting immediate loading protocols in select bone quality categories.
Market Restraints
- Import dependency concentration:Precision-machined titanium abutments rely heavily on Swiss and German milling centers, exposing Brazilian assemblers to euro-denominated input volatility and extended ocean freight windows through Santos port.
- ANMAT procedural friction:Argentina's national pharmaceutical and medical technology regulator maintains non-harmonized vigilance reporting that duplicates Brazil's ANVISA requirements, lengthening entry timelines for unfamiliar manufacturers.
- Zirconia substitution pressure:Monolithic zirconia crowns are capturing posterior restoration volume from layered porcelain-fused-to-metal, compressing margin pools for laboratories dependent on precious metal alloy workflows.
Strategic Opportunities
- COFEPRIS digital dossier acceptance:Mexico's health regulator now permits electronic submission of biocompatibility testing data, reducing paper-based translation costs and enabling faster northern border state distribution builds.
- Orthodontic aligner convergence:Direct-to-consumer scanning apps are merging with clinic-based treatment planning software, creating hybrid service models that capture teenage patient acquisition earlier in the care lifecycle.
- Colombian Andean corridor:Bogotá and Medellín exhibit specialist dentist density ratios below São Paulo thresholds but above regional peers, presenting whitespace for mid-tier implant system launches before competitor saturation.
Industry Challenges
- CAD/CAM technician certification gaps:Brazilian dental technology schools graduate fewer operators proficient in 3Shape and exocam nesting software than clinic demand requires, forcing laboratories to train in-house or poach from competitors.
- MERCOSUR harmonization uncertainty:The proposed unified device framework lacks implementation timelines, leaving manufacturers to maintain parallel compliance infrastructures across Brazil, Argentina, Paraguay, and Uruguay without clarity on consolidation benefits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Dental Devices Market |
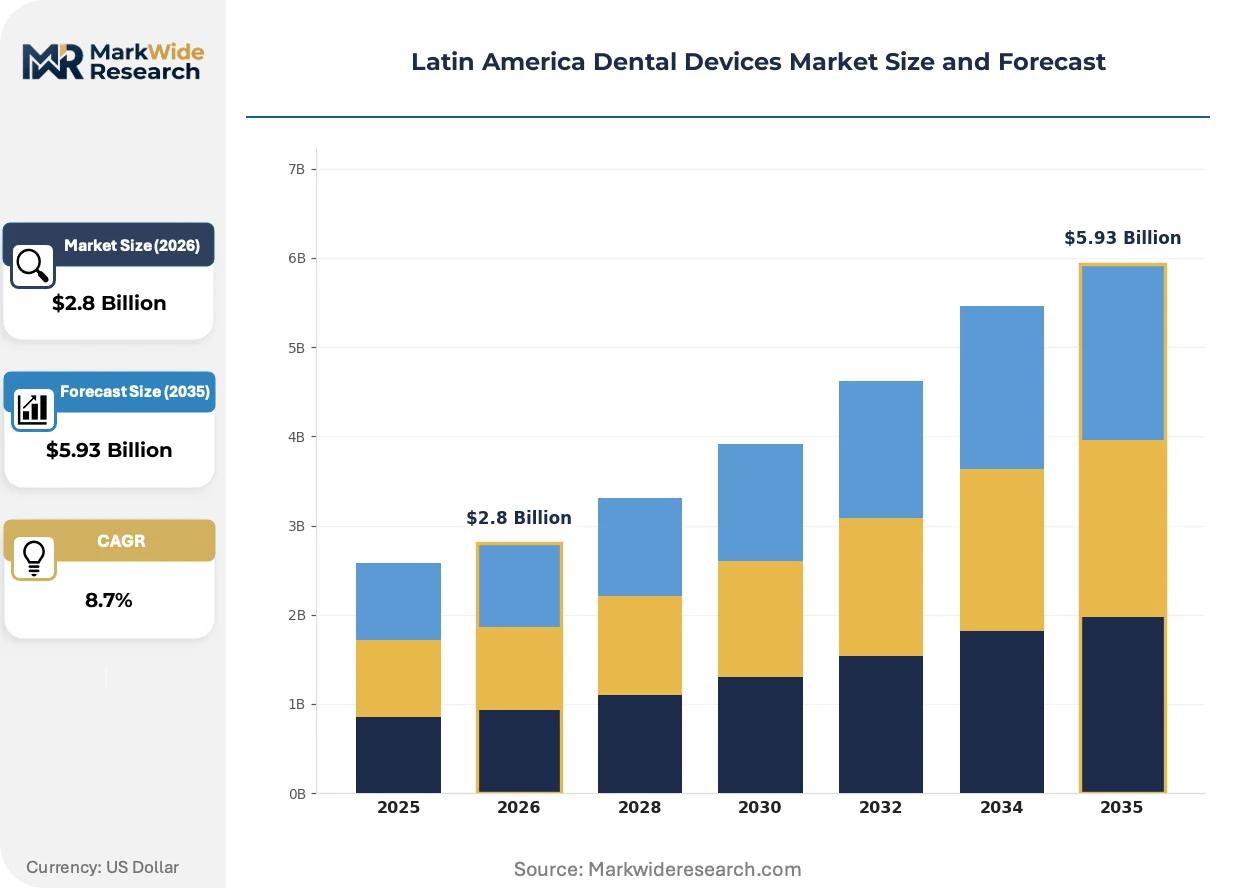
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dental Implants, Orthodontic Devices, Endodontic Devices, Restorative Materials Technology: CAD/CAM, 3D Printing, Laser Dentistry, Digital Radiography End User: Dental Clinics, Hospitals, Dental Laboratories, Academic Institutions Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Dentsply Sirona, Straumann Group, 3M, Zimmer Biomet, Dentium, Ivoclar Vivadent, Planmeca OY, Envista Holdings Corporation, Biolase Inc., Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Dental Devices Market Shifts & Advancements
Workflow digitization is collapsing the traditional separation between clinic diagnosis and laboratory fabrication, with real-time data transmission now enabling same-day restoration delivery that reshapes capital allocation across the value chain.
Intraoral scanners are migrating from standalone diagnostic tools to integrated patient acquisition platforms. São Paulo's largest private clinic chains deploy scanning hardware in hygiene operatories to capture restorative opportunities during routine cleanings. This technology is migrating from high-end prosthodontic suites to general dentistry floors, compressing the addressable market for conventional polyether and alginate impression materials.
COFEPRIS and ANVISA are converging on risk-based classification alignment for 3D-printed surgical guides, though implementation timelines diverge. Mexican premarket authorization now accepts FDA 510(k) summaries as primary evidence for Class I and II devices, reducing redundant biocompatibility testing. Argentine laboratories importing photopolymer resins face the longest adaptation curves due to ANMAT's continued insistence on local stability studies.
Clinic procurement committees now bundle consumables purchasing across implant, restoration, and orthodontic categories to secure volume discounts from distributors. Rio de Janeiro's dental cooperative purchasing organizations aggregate demand from 40-60 independent practices, displacing the traditional manufacturer-to-clinic direct sales model. This concentration is most visible in Brazil's southeastern states where cooperative density exceeds other Latin American markets.
Latin America Dental Devices Market Segmentation
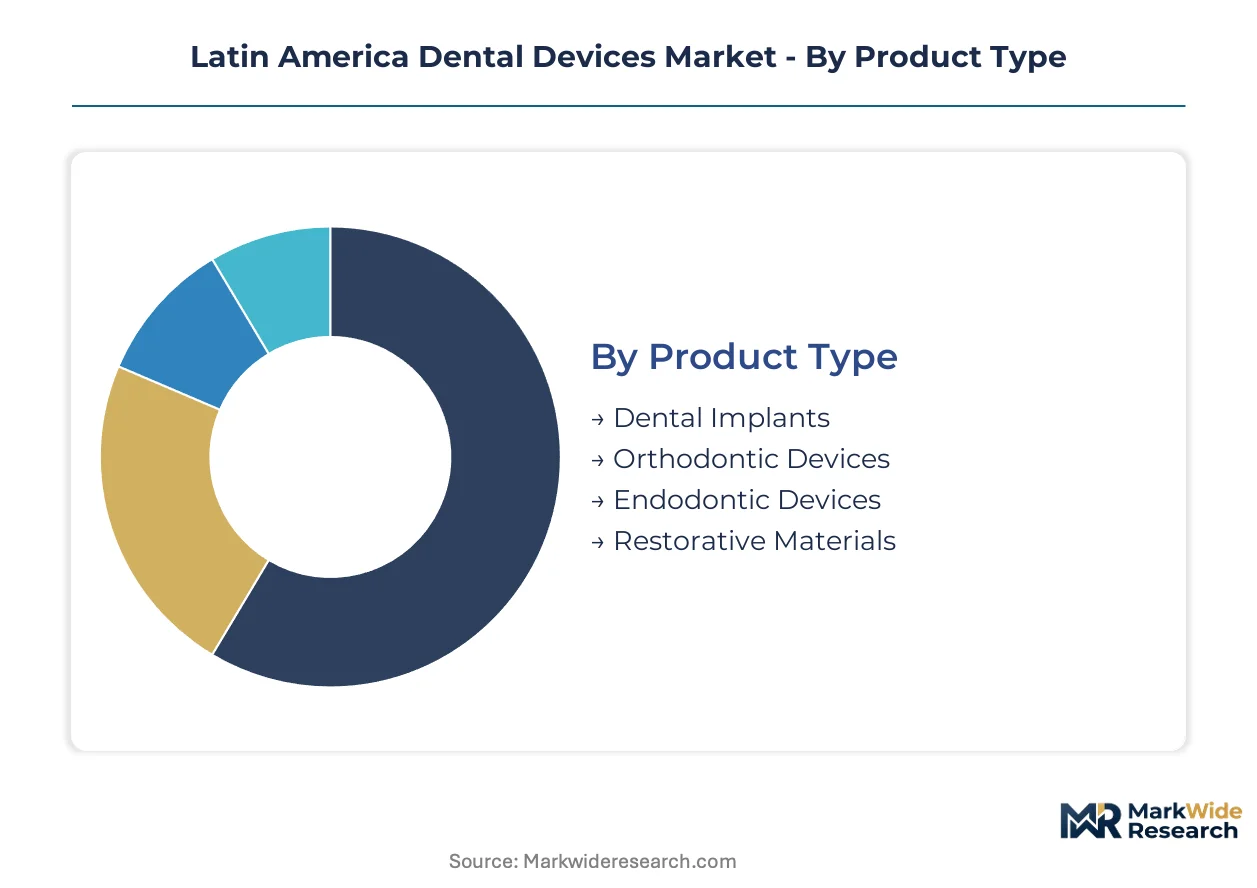
Dental device segmentation in Latin America reflects divergent technology maturities and reimbursement environments across the region's largest markets. Category boundaries blur as CAD/CAM workflows integrate formerly discrete product lines, while distribution channel selection increasingly determines which manufacturers capture volume in Brazil's cooperative purchasing networks versus Mexico's northern border states.
Product Type:
Use cases span from permanent osseointegration to removable orthodontic correction, with margin structures varying dramatically by replacement cadence and consumables attachment.
- Dental Implants:Titanium alloy fixtures with SLA-etched surfaces achieve 35 Ncm insertion torque thresholds for immediate loading protocols. São Paulo's specialist corridor absorbs premium tissue-level and bone-level systems where private-pay density amortizes surgical guide investments across high daily throughput.
- Orthodontic Devices:Clear aligner platforms and fixed bracket systems command recurring consumables revenue through treatment monitoring and wire replacement cycles. Mexico's teenage demographic concentration and direct-to-consumer scanning app penetration are accelerating hybrid clinic-digital acquisition models in Monterrey and Guadalajara.
- Endodontic Devices:Nickel-titanium rotary files and obturation systems address root canal therapy volume concentrated in Brazil's public health dental emergency networks.
- Restorative Materials:Zirconia blocks and resin composites feed chairside milling workflows displacing precious metal-ceramic layering in Rio de Janeiro's laboratory clusters.
Established volume favors Dental Implants; emerging adoption favors Orthodontic Devices.
Technology:
Capital intensity and technician certification requirements stratify technology penetration across clinic tiers, with subscription bundling now dominating hardware procurement.
- CAD/CAM:Integrated intraoral scanning and chairside milling compress crown turnaround from two weeks to same-day delivery. Dentsply Sirona's workflow platforms dominate São Paulo and Rio de Janeiro clinic chains that amortize equipment across 40-plus daily scanning events.
- 3D Printing:Photopolymer resin systems fabricate surgical guides and temporary restorations at unit economics below milling center outsourcing. Argentine laboratories face ANMAT-mandated local stability studies that extend adaptation curves versus Mexican counterparts under COFEPRIS digital dossier acceptance.
- Laser Dentistry:Soft-tissue ablation and caries detection systems concentrate in Brazil's premium private clinic segment where per-procedure fees justify hardware investment.
- Digital Radiography:CBCT and intraoral sensor upgrades displace analog film across Colombian Andean corridor clinics building implantology capabilities.
CAD/CAM claims the steepest expansion trajectory as subscription bundling erodes upfront capital barriers.
End User:
Procurement authority and patient volume concentration determine pricing leverage, with cooperative purchasing organizations reshaping vendor relationships in southeastern Brazil.
- Dental Clinics:Private practices and clinic chains generate 70-plus percent of restorative and implant device demand. Rio de Janeiro dental cooperatives aggregate 40-60 independent practices to displace direct manufacturer sales with volume-negotiated distributor contracts.
- Hospitals:Maxillofacial surgery departments and emergency dental services concentrate trauma and oncological reconstruction volume in São Paulo's metropolitan hospital networks.
- Dental Laboratories:Independent and clinic-captive fabrication centers face margin compression as chairside milling bypasses traditional crown-and-bridge outsourcing.
- Academic Institutions:Dental schools in Mexico City and Bogotá drive training-equipment procurement cycles tied to curriculum modernization grants.
Procurement concentration favors Dental Clinics; training-driven replacement favors Academic Institutions.
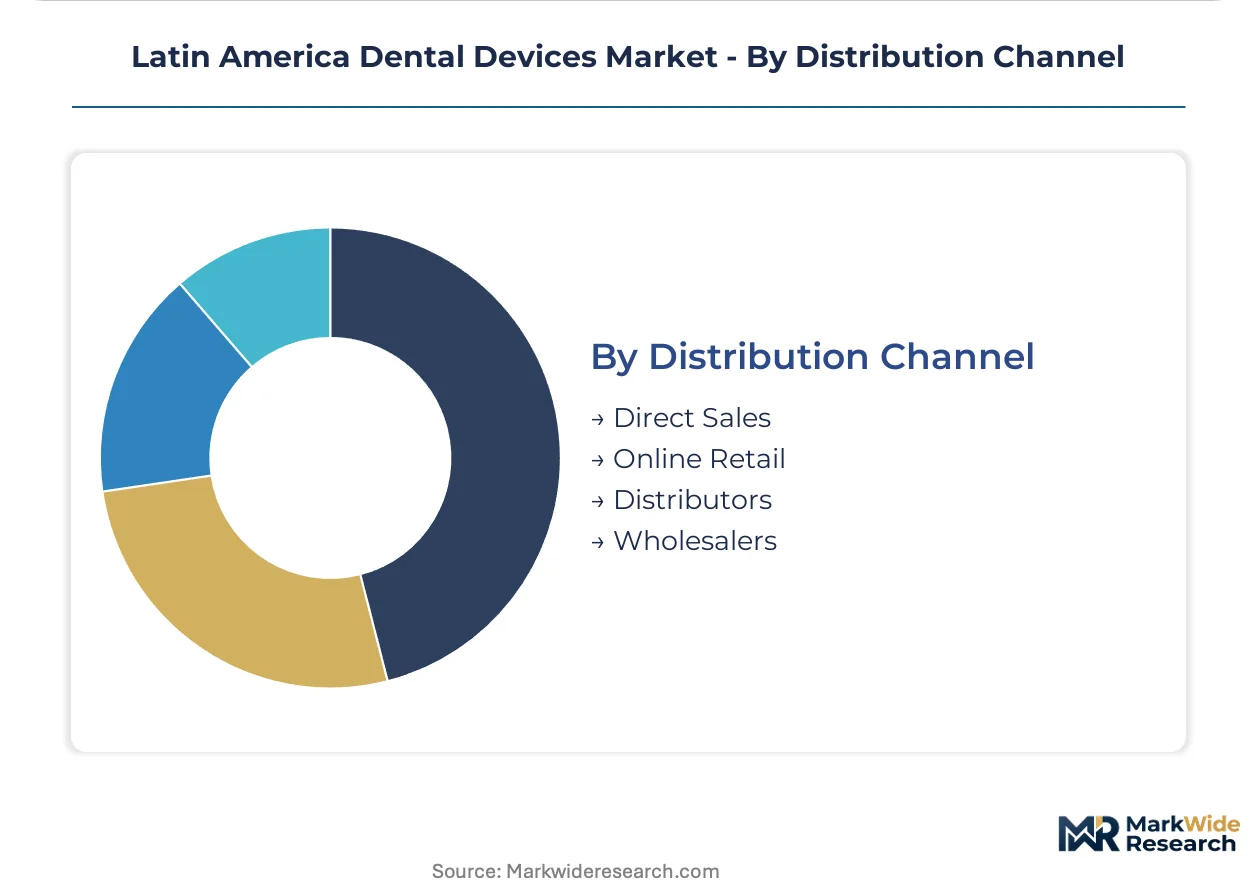
Distribution Channel:
Channel selection reflects geographic fragmentation and import regulatory complexity across ANVISA, COFEPRIS, and ANMAT jurisdictions.
- Direct Sales:Manufacturer field forces maintain relationships with Brazil's largest clinic chains and cooperative purchasing organizations. Straumann Group and Envista Holdings deploy dedicated sales engineers for implant system installation and training in São Paulo's premium corridor.
- Distributors:Regional inventory holders absorb euro-denominated titanium abutment import volatility and extended Santos port clearance windows. Brazilian assemblers depend on Swiss and German milling center relationships intermediated by distributor credit terms.
- Online Retail:Consumables and small equipment bypass traditional dental supply houses for independent practitioners in Mexico's northern border states with US shipping integration.
- Wholesalers:Bulk orthodontic supplies and endodontic files flow through cash-and-carry depots serving secondary Brazilian cities outside cooperative coverage.
Relationship depth favors Direct Sales; geographic reach favors Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
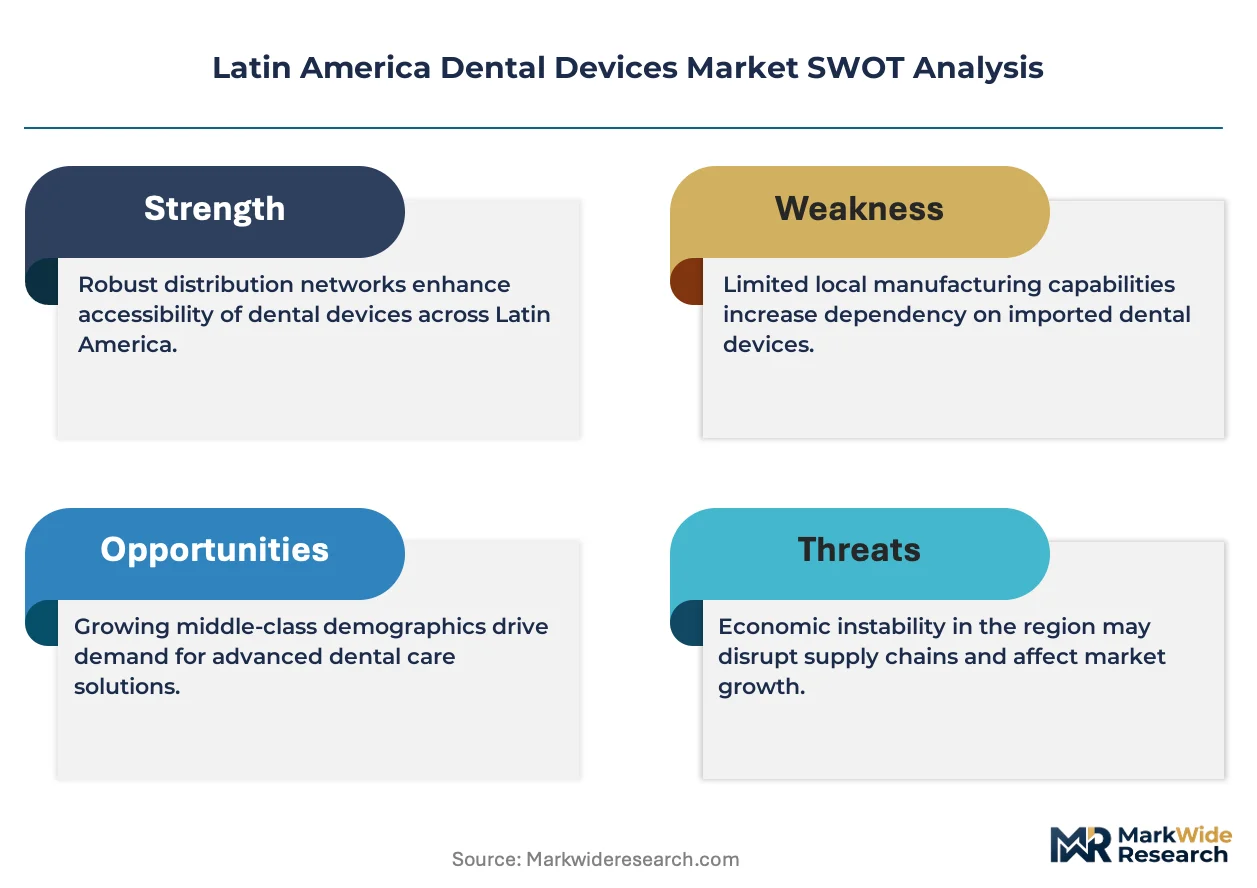
ANVISA's consolidated technical documentation requirements for Class III dental implants have reduced registration timelines, positioning Brazil as the dominant geography for market entry and southeastern state expansion.
Brazil
São Paulo's metropolitan corridor sustains specialist clinic clusters with high private-pay patient density that amortizes CAD/CAM capital investments. ANVISA's streamlined pathways for European and North American manufacturers accelerate implant system approvals. Rio de Janeiro dental cooperatives aggregate 40-60 independent practices to displace direct manufacturer sales with volume-negotiated distributor contracts.
Mexico
Monterrey and Guadalajara exhibit teenage demographic concentration accelerating hybrid clinic-digital orthodontic acquisition models. COFEPRIS now permits electronic submission of biocompatibility testing data, reducing paper-based translation costs for northern border state distribution builds. Mexico City dental schools drive training-equipment procurement cycles tied to curriculum modernization grants.
Argentina
ANMAT maintains non-harmonized vigilance reporting that duplicates Brazil's requirements, lengthening entry timelines for unfamiliar manufacturers. Buenos Aires laboratories importing photopolymer resins face mandated local stability studies extending adaptation curves. Argentine dental technology schools graduate fewer operators proficient in nesting software than clinic demand requires.
Colombia
Bogotá and Medellín specialist dentist density ratios sit below São Paulo thresholds but above regional peers, presenting whitespace for mid-tier implant system launches. CBCT and intraoral sensor upgrades displace analog film across Andean corridor clinics building implantology capabilities. Colombian laboratories face shorter regulatory adaptation curves than Argentine counterparts.
Chile
Santiago's concentrated private healthcare infrastructure supports premium implantology adoption where per-procedure fees justify surgical guide investments. The national pharmaceutical regulator enforces risk-based classification alignment for 3D-printed devices converging with COFEPRIS standards. Chilean distributors absorb euro-denominated titanium abutment import volatility through extended credit terms.
Latin America Dental Devices Market Competitive Landscape
Capability concentration sits with integrated workflow platform providers; scale advantage sits with broad instrument portfolio manufacturers. The market structures around three tiers: premium implantology specialists, mid-tier clinic segment suppliers, and regional assemblers entering precision-machined component supply. Dominant competitive moves include subscription bundling of chairside hardware with consumables and cooperative purchasing organization penetration in southeastern Brazil.
Within the integrated workflow tier, Dentsply Sirona exemplifies platform dominance through CAD/CAM system penetration. Straumann Group occupies a position anchoring premium implantology portfolios. Envista Holdings Corporation sits within the mid-tier instrument breadth segment competing on clinic coverage scale.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Straumann Group |
| 3M |
| Zimmer Biomet |
| Dentium |
| Ivoclar Vivadent |
| Planmeca OY |
| Envista Holdings Corporation |
| Biolase Inc. |
| Others |
Supply & Pricing Matrix
São Paulo's precision-machined titanium abutment assemblers command downstream pricing leverage through euro-denominated input exposure and extended Santos port clearance windows. Brazilian distributors absorb currency volatility into extended credit terms, compressing margin pools for mid-tier clinic suppliers competing against integrated workflow platforms.
Pricing Analysis
São Paulo-to-Bogotá price spreads of 15-25 percent reflect freight cost differentials and ANVISA registration amortization across volume tiers. Three-tier pricing structure across premium, standard, and economy levels separates Straumann-level tissue-level systems from regional abutment assemblers and imported Korean implant lines. Cost compression in monolithic zirconia posterior restorations is intensifying because chairside milling bypasses laboratory margin stacking. Cooperative purchasing organizations in Rio de Janeiro exhibit highest price sensitivity through aggregated volume negotiations, while São Paulo's premium corridor clinics show lowest sensitivity due to immediate-loading protocol fees.
Supply Chain Analysis
Swiss and German milling centers hold contract-manufacturing concentration for precision titanium abutments, with Straumann's in-house production and Dentsply Sirona's supplier network anchoring capacity. Brazil, Mexico, and Colombia draw from eurozone machining inputs, Chinese zirconia block supply, and Korean implant fixture sources. Single-source vulnerability concentrates in SLA-etched surface treatment protocols controlled by three European licensors. Distribution runs through Santos port customs brokers and regional dental supply houses serving cooperative purchasing organizations across southeastern Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's CAD/CAM technician certification gap—graduating fewer 3Shape and exocam operators than clinic demand requires—creates sustained capability premiums for trained labor holders. This scarcity propagates through laboratory margin structures and equipment subscription pricing power.
For Market Incumbents: Build workflow-platform moats through captive technician training academies and exclusive nesting software licensing. Consolidate position by acquiring Rio de Janeiro cooperative purchasing organization distributors before mid-tier competitors replicate Envista's clinic coverage scale. Zirconia substitution pressure threatens precious metal-ceramic dependent laboratories; vertical integration into chairside milling hardware subscriptions defends margin pools. For New Entrants and Emerging Players: Pursue Colombian Andean corridor whitespace where Bogotá and Medellín specialist dentist density sits below São Paulo thresholds but above regional peers. Target mid-tier implant system launches before competitor saturation, leveraging COFEPRIS digital dossier acceptance for faster northern Mexico distribution builds. Hybrid clinic-digital orthodontic acquisition models in Monterrey offer lowest go-to-market friction through direct-to-consumer scanning app partnerships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among CAD/CAM platform operators with consumables attachment and subscription bundling. Long-term viability across the analysis window favors integrated workflow providers over discrete hardware vendors. Acquisition target archetype: Brazilian distributors with cooperative purchasing organization relationships and euro-hedged inventory financing. ANVISA-COFEPRIS regulatory harmonization progress serves as the signal to watch for distribution restructuring inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Technician Certification Academy Launch | Captive 3Shape and exocam operator pipelines lock laboratory customers into proprietary workflows. |
| Cooperative Purchasing Organization Partnership | Rio de Janeiro and São Paulo aggregator access displaces direct sales models at 40-60 clinic scale. |
| COFEPRIS Digital Dossier Leverage | Electronic biocompatibility submission accelerates northern Mexico border state market entry timelines. |
| Zirconia Block Backward Integration | In-house ceramic supply hedges euro-denominated titanium abutment import volatility for Brazilian assemblers. |
| Hybrid Aligner Clinic-Digital Model | Monterrey and Guadalajara teenage demographic concentration supports early patient acquisition lifecycle capture. |
Research Methodology
Operator-level perspectives from CAD/CAM laboratory technicians, dental cooperative purchasing managers, ANVISA regulatory consultants, and implant system sales engineers anchored the qualitative base. Primary interviews combined with secondary validation across SEC filings of listed device manufacturers, ANVISA registration databases, COFEPRIS premarket authorization records, and Brazilian dental technology school enrollment statistics. Bottom-up equipment installation counts and top-down distributor revenue estimates were triangulated for market sizing.
Scenario-bracketing framed conservative and expansion cases across the projection horizon without year-specific milestones. Segmentation dimensions modeled include product type, technology tier, end-user procurement authority, and distribution channel concentration. CAGRs derived from equipment replacement cycles, clinic penetration curves, and consumables attachment rates. Forecast inputs incorporated ANVISA pathway streamlining implementation pace and MERCOSUR harmonization uncertainty buffers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese implant system exporters or accelerated COFEPRIS-ANVISA regulatory convergence would shift outcomes. Forecasts reflect assumptions of continued eurozone machining supply dominance and cooperative purchasing organization aggregation trends. Quarterly review of technician certification graduate counts, Santos port clearance duration indices, and zirconia block import volume is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Dental Implants and Dental Prosthetics Market
Dental Devices
United States Dental Implants Market
Dental Devices
Digital Facebow Market
Dental Devices
Middle East and Africa Dental Lab Market
Dental Devices
Americas Acrylic Teeth Market
Dental Devices
Dental Veneers Market
Dental Devices
India Dental Devices Market
Dental Devices
Dental Dam Market
Dental Devices
Dental Amalgamators Market
Dental Devices
Saudi Arabia Dental Devices Market
Dental Devices
Periodontal Scalers and Curettes Market
Dental Devices
Acrylic Teeth Market
Dental Devices
Subperiosteal Dental Implants Market
Dental Devices
Global Dental Lasers Market
Dental Devices
Europe Dental Implants Market
Dental Devices
South Korea Dental Devices Market