
 General Surgical Devices Market | 2026-2036
General Surgical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
General Surgical Devices Market Analysis
Aftermarket service revenue is rewriting profitability expectations across the general surgical devices sector. Medtronic Plc leverages its broad installed base to capture recurring maintenance contracts. Johnson & Johnson Service, Inc. anchors its position through sterile processing and reprocessing services. Stryker Corporation competes by extending warranty-linked service packages that lock in multi-year hospital commitments.
General surgical devices encompass handheld instruments, electrosurgical generators, and robotic platforms engineered from surgical-grade stainless steel, titanium alloys, and polymer composites to perform incision, dissection, cauterization, and wound closure during operative procedures. Electrosurgery and robotic surgery technologies command premium pricing as hospitals prioritize precision and reduced blood loss, while manual surgery instruments remain a high-volume, lower-margin category sustained by replacement cycles in cost-constrained settings. Scalpels and sutures represent mature product lines with stable procurement patterns, whereas robotic surgery systems attract concentrated investment from academic medical centers seeking differentiation in complex procedures.
FDA 510(k) clearance pathways and EU MDR conformity assessments shape product development timelines and market entry costs for device manufacturers worldwide. ISO 13485 quality management standards and WHO surgical safety checklists further influence design specifications and clinical validation requirements. Stakeholders must monitor evolving reimbursement policies for minimally invasive procedures and robotic-assisted operations as payors recalibrate coverage thresholds across major healthcare systems.
Market Dynamics
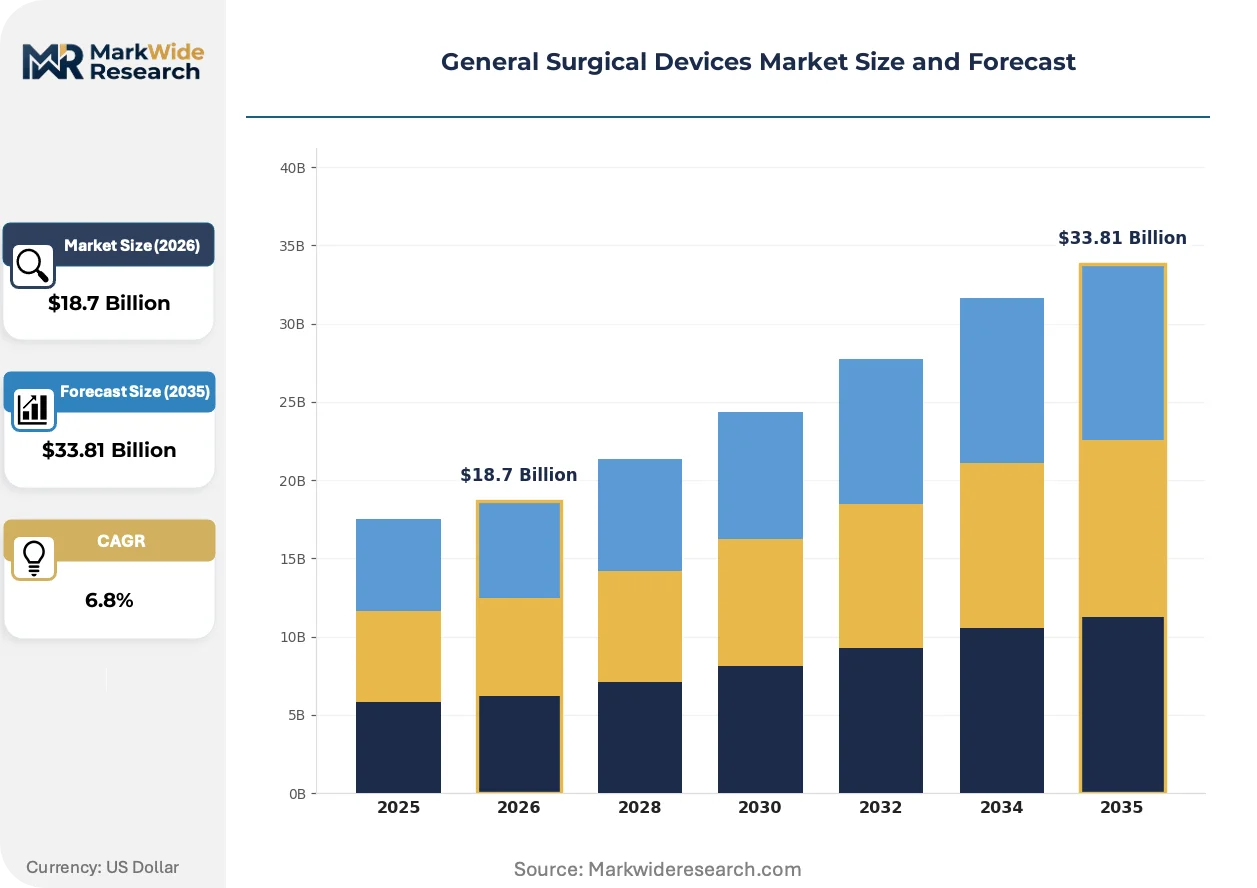
The general surgical devices market is being fundamentally restructured by the convergence of EU MDR sterilization mandates and robotic platform adoption, which together compress replacement cycles for manual instruments while elevating capital intensity for hospitals.
Growth Catalysts
- EU MDR traceability requirements:The Medical Device Regulation mandates Unique Device Identification for all surgical instruments, forcing hospital procurement departments toward certified suppliers with validated sterilization documentation.
- India healthcare infrastructure expansion:Government schemes targeting district hospital surgical capacity are generating procurement waves for electrosurgical generators and standard instrument kits.
- Polymer composite adoption:Non-conductive polymer composites in retractors and forceps reduce thermal injury risk during electrosurgical procedures, accelerating replacement of traditional stainless steel in high-frequency settings.
Market Restraints
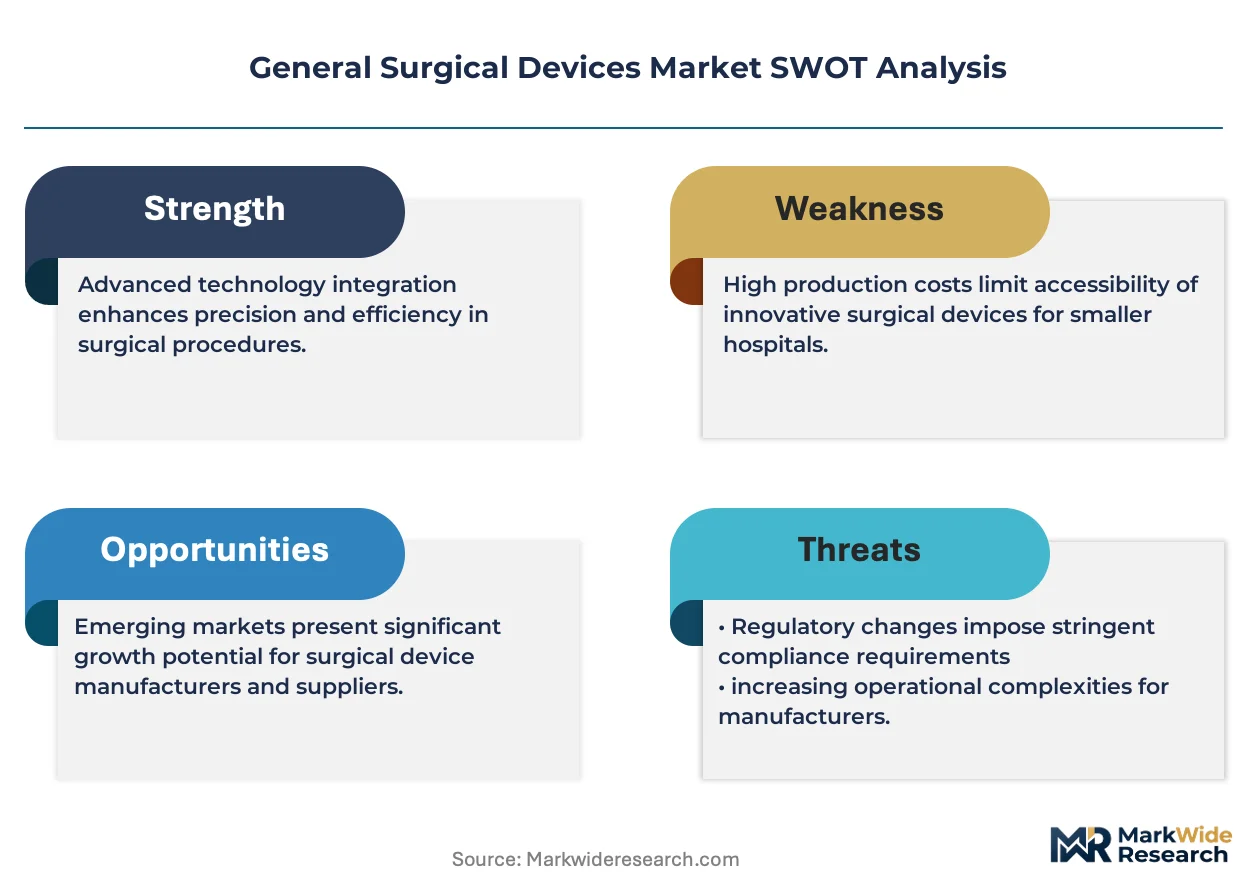
- Titanium alloy supply concentration:Surgical-grade titanium feedstock for implantable instruments concentrates among a limited supplier base, exposing device manufacturers to raw material volatility and qualification delays.
- FDA 510(k) pathway friction:Substantial equivalence determinations for electrosurgical accessories now require expanded biocompatibility data, extending premarket timelines and freezing product line extensions.
- Reprocessed single-use device substitution:Third-party reprocessors in the US are capturing share in suction and irrigation devices, compressing OEM pricing power in mature categories.
Strategic Opportunities
- China county hospital penetration:Tier-3 and county-level hospitals remain undersupplied with laparoscopic instrument sets, creating whitespace for mid-tier electrosurgical platforms with localized service networks.
- ISO 13485-certified contract manufacturing:Outsourced production partnerships allow OEMs to redirect capital toward software-enabled surgical navigation without sacrificing quality system compliance.
- WHO surgical safety checklist integration:Instrument tracking systems aligned with checklist protocols open bundled service contracts combining hardware, software, and compliance documentation.
Industry Challenges
- Robotic surgery technician scarcity:Academic medical centers face recruitment bottlenecks for da Vinci system-certified surgical technologists, constraining utilization rates of installed capital.
- Legacy sterilization workflow retrofit costs:Hospitals must reconfigure central sterile supply departments to accommodate rigid container systems and barcode verification, requiring capital outlays that compete with clinical equipment budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | General Surgical Devices Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scalpels, Forceps, Scissors, Sutures Technology: Electrosurgery, Laser Surgery, Robotic Surgery, Manual Surgery End User: Hospitals, Surgical Centers, Clinics, Ambulatory Surgical Units Application: General Surgery, Orthopedic Surgery, Cardiothoracic Surgery, Neurosurgery |
| Companies Covered | Medtronic Plc, Johnson & Johnson Service, Inc., Stryker Corporation, B. Braun Melsungen AG, Becton, Dickinson and Company, Conmed Corporation, Boston Scientific Corporation, Smith & Nephew, Olympus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
General Surgical Devices Market Emerging Trajectories
Digital integration and materials science are converging to redefine surgical instrument value propositions, with connectivity and precision engineering displacing commodity positioning across all price tiers.
Single-use polymer electrosurgical pencils with integrated smoke evacuation channels are collapsing the distinction between capital equipment and consumable categories. Ambulatory surgery centers in the US are adopting these devices to eliminate reprocessing labor and liability exposure. The shift is compressing margins for traditional reusable pencil manufacturers while expanding addressable volume.
EU MDR Article 10 post-market surveillance obligations now require systematic literature review and PMCF study design for all Class IIa surgical instruments. Manufacturers are restructuring regulatory affairs departments to maintain continuous clinical evidence generation. High-risk electrosurgical accessories face the steepest compliance cost escalation, prompting portfolio rationalization among mid-tier competitors.
Hospital buying consortia are consolidating procurement decisions for surgical devices across multi-hospital systems, displacing individual surgeon preference as the primary selection criterion. Group purchasing organizations in the US are extracting standardized pricing for laparoscopic instrument sets. Academic medical centers resist most aggressively, citing research protocol requirements that demand specific instrument geometries.
General Surgical Devices Market Segmentation
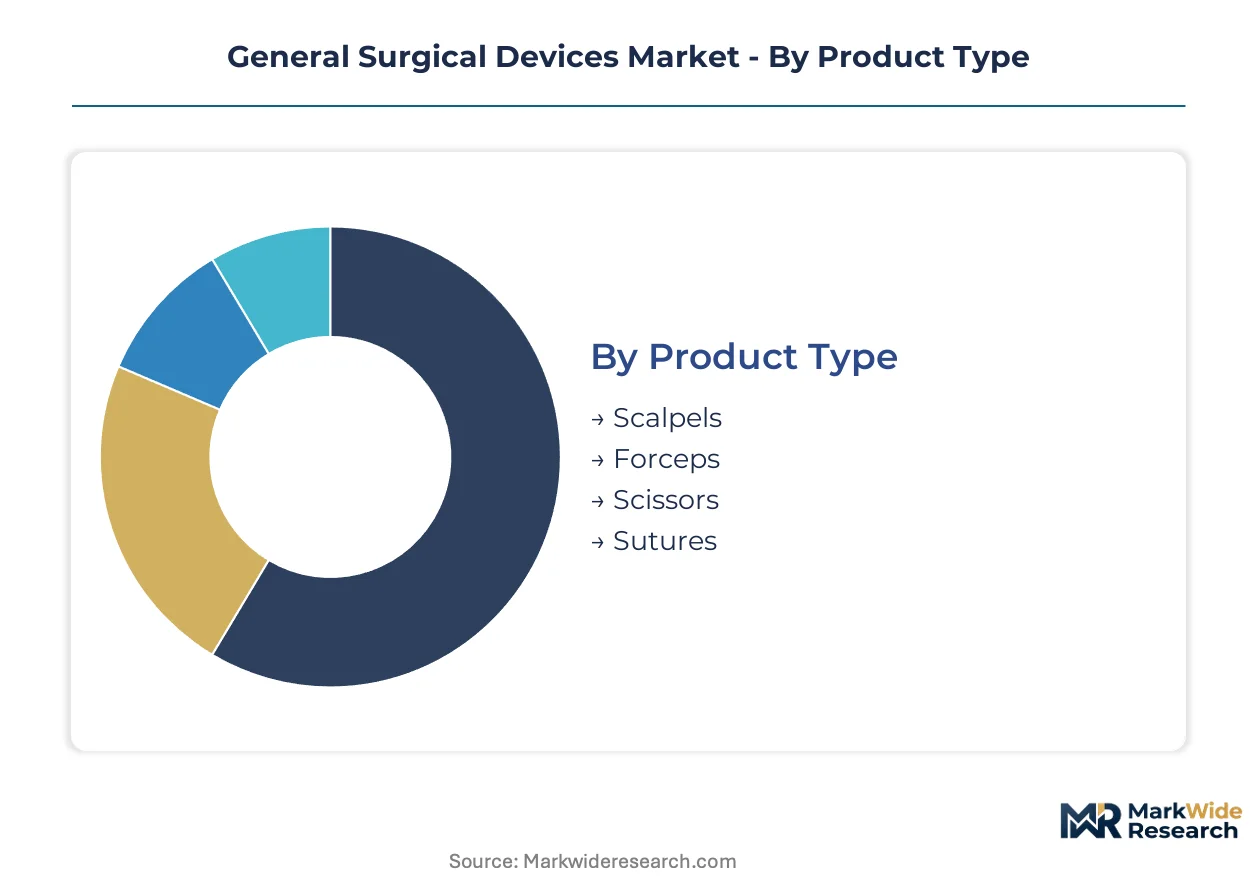
General surgical devices fragment across four intersecting dimensions that determine procurement patterns and margin structures. Product type and technology classifications shape manufacturing investment, while end-user and application segments dictate regulatory pathways and service requirements.
Product Type:
Use-case spectrum spans disposable consumables through precision-engineered reusable instruments, with material composition and sterilization compatibility driving hospital procurement workflows.
- Scalpels:Manufactured from surgical-grade stainless steel with carbon or ceramic blade variants, these instruments command highest unit volume in emergency departments across India and China where trauma caseloads concentrate. Disposable safety-engineered designs are displacing traditional reusable handles in US academic medical centers seeking needlestick liability reduction.
- Sutures:Absorbable polyglycolic acid and non-absorbable polypropylene thread configurations dominate wound closure protocols, with antimicrobial-coated variants gaining preference in cardiothoracic units managing sternal infections. Demand concentrates in surgical centers performing high-volume orthopedic and general procedures where kit standardization reduces OR turnover time.
- Forceps:Tissue grasping instruments with ratcheted locking mechanisms and atraumatic tip geometries serve specialized functions across all surgical disciplines.
- Scissors:Metzenbaum and Mayo dissecting configurations with tungsten carbide inserts maintain cutting precision through thousands of sterilization cycles.
The dominant share belongs to sutures, while scalpels are closing the gap fastest.
Technology:
Cost tier stratification separates capital-intensive platform investments from high-volume consumable categories, with reimbursement alignment determining hospital adoption sequencing.
- Manual Surgery:Handheld stainless steel and titanium instruments without energy delivery capability remain the procurement baseline for cost-constrained settings, with replacement cycles averaging three to five years in district hospitals across emerging economies.
- Electrosurgery:Radiofrequency generators and active electrode instruments enable hemostatic cutting through tissue impedance modulation, commanding premium pricing in US and European hospitals where reduced blood transfusion requirements justify capital outlay. EU MDR sterilization documentation requirements are compressing supplier pools to ISO 13485-certified manufacturers with validated reprocessing protocols.
- Laser Surgery:Carbon dioxide and Nd:YAG wavelength systems target precise tissue ablation in otolaryngology and gynecology subspecialties.
- Robotic Surgery:Computer-assisted telemanipulation platforms with haptic feedback and 3D visualization integrate capital equipment with proprietary instrument ecosystems.
Manual surgery retains volume leadership, though robotic platforms are expanding most quickly in academic medical centers.
End User:
Customer type determines service intensity expectations, with integrated delivery networks and standalone facilities pursuing divergent procurement strategies.
- Hospitals:Multi-specialty institutions with centralized sterile processing departments manage complex instrument portfolios spanning all technology tiers, with group purchasing organization contracts standardizing laparoscopic and open surgery sets across US health systems.
- Surgical Centers:Focused facilities performing same-day procedures prioritize single-use electrosurgical pencils and pre-sterilized kits to eliminate reprocessing infrastructure investment, with volume concentrated in ophthalmology and orthopedics across Germany and France.
- Clinics:Office-based settings with minor procedure capability source limited instrument sets for dermatology and wound care applications.
- Ambulatory Surgical Units:Hospital-affiliated outpatient departments balance cost efficiency with access to central sterile supply resources for reusable instrument turnaround.
Hospitals command the dominant procurement volume, while surgical centers are gaining share fastest.
Application:
Procedure complexity dictates instrument precision requirements and regulatory classification, with specialized fields commanding dedicated product development resources.
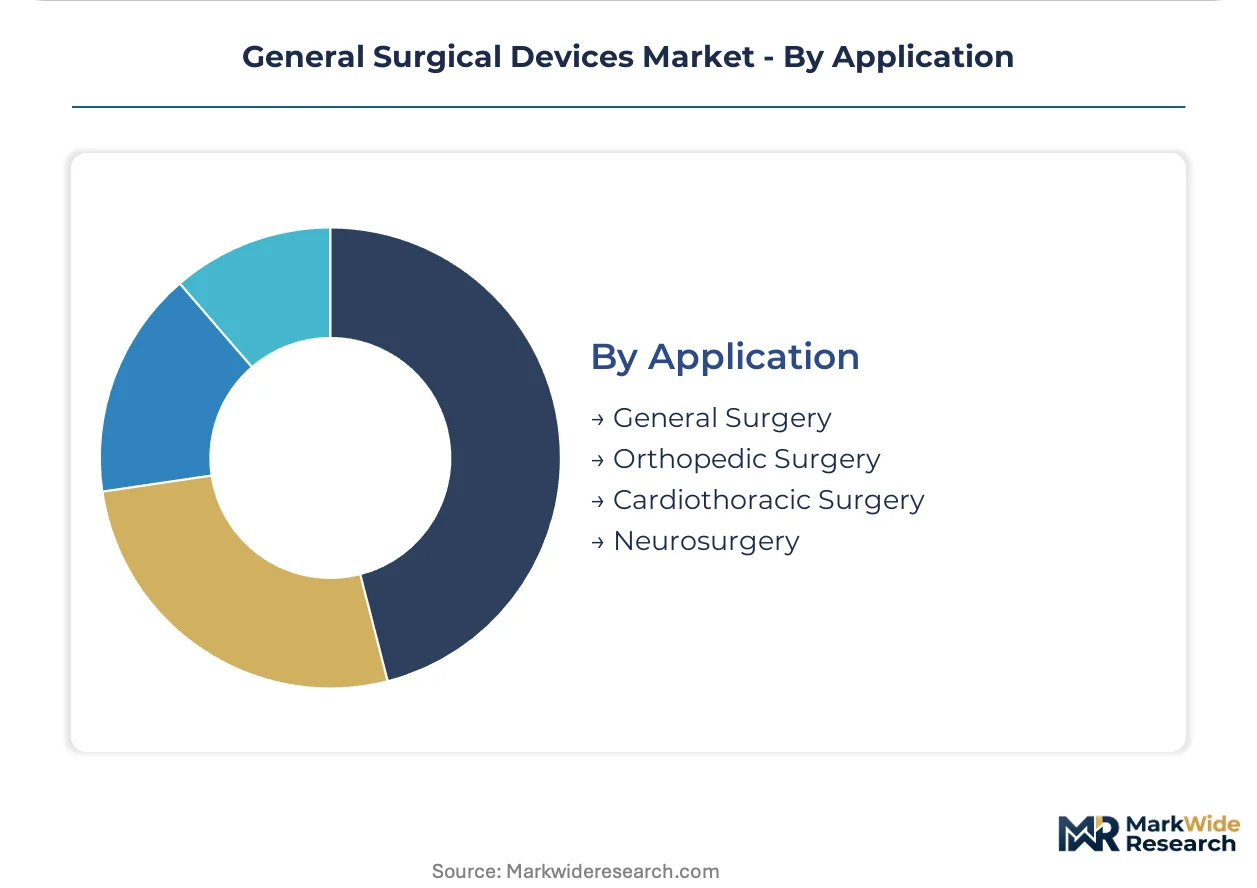
- General Surgery:Open and laparoscopic abdominal procedures utilize the broadest instrument portfolios, with cholecystectomy and hernia repair volumes driving standard kit configurations across US and Indian hospital systems where procedure standardization supports resident training protocols.
- Orthopedic Surgery:Arthroscopic and joint replacement procedures require specialized retractors, saws, and fixation instruments engineered for load-bearing applications, with demand concentrating in China's tier-3 hospitals expanding trauma and arthroplasty capacity under government infrastructure schemes.
- Cardiothoracic Surgery:Sternotomy and minimally invasive cardiac procedures demand precision-engineered instruments with atraumatic tissue handling characteristics.
- Neurosurgery:Cranial and spinal access instruments require microscopic precision and non-ferromagnetic compatibility for intraoperative imaging integration.
General surgery holds the dominant application share, while orthopedic surgery is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. Academic medical centers in the United States absorb premium robotic platforms with minimal procurement friction, while district hospitals in India and county-level facilities in China demand mid-tier electrosurgical bundles with localized service support.
United States
Academic medical centers drive capital-intensive robotic platform procurement, prioritizing precision instrumentation for complex procedures. FDA 510(k) clearance pathways shape premarket timelines for electrosurgical accessories, with expanded biocompatibility data requirements freezing product line extensions. The Boston-Cambridge corridor anchors medical device innovation clusters, with sterile processing workflow retrofits consuming capital budgets across New England health systems.
Germany
Ambulatory surgery centers prioritize single-use electrosurgical pencils to eliminate reprocessing infrastructure investment. EU MDR Article 10 post-market surveillance obligations force systematic literature review and PMCF study design for Class IIa surgical instruments. The Baden-Württemberg region concentrates precision engineering capabilities, with ISO 13485-certified contract manufacturers serving OEM software navigation partnerships.
China
Tier-3 and county-level hospitals generate whitespace demand for laparoscopic instrument sets as healthcare infrastructure scales under government schemes. NMPA regulatory pathways align with national dual carbon goals, influencing sterilization equipment energy efficiency standards. The Yangtze River Delta manufacturing corridor supplies polymer composite retractors to domestic electrosurgical device producers.
India
Government infrastructure schemes targeting district hospital surgical capacity generate procurement waves for electrosurgical generators and standard instrument kits. CDSCO medical device regulations tighten sterilization documentation requirements for imported surgical instruments. Maharashtra's Mumbai-Pune industrial belt hosts contract sterilization services supporting domestic instrument manufacturers.
Japan
PMDA quality management standards enforce rigorous clinical validation requirements for electrosurgical accessories entering the market. METI industrial policy supports precision manufacturing capabilities for microscopic surgical instruments. The Kansai region around Osaka maintains specialized titanium alloy processing clusters for implantable instrument feedstock.
General Surgical Devices Market Vendor Landscape
Capability concentration sits with diversified conglomerates possessing integrated sterile processing networks; scale advantage sits with specialized manufacturers leveraging ISO 13485-certified production partnerships. The vendor base stratifies across three archetypes: multinational platform providers with recurring service revenue models, regional mid-tier competitors with localized distribution, and contract manufacturers supplying private-label instruments to hospital buying consortia. Dominant competitive moves include strategic partnerships for software-enabled surgical navigation and geographic expansion through WHO surgical safety checklist-aligned instrument tracking systems.
Within the diversified multinational tier, Medtronic Plc, Johnson & Johnson Service, Inc., and Stryker Corporation exemplify service-anchored competitive positioning. These entities leverage broad installed bases to capture recurring maintenance contracts, sterile processing services, and warranty-linked multi-year hospital commitments. Their geographic footprints span FDA-regulated US markets, EU MDR-compliant European operations, and emerging economy expansion targeting India and China county hospital penetration.
| Leading Market Players |
|---|
| Medtronic Plc |
| Johnson & Johnson Service, Inc. |
| Stryker Corporation |
| B. Braun Melsungen AG |
| Becton, Dickinson and Company |
| Conmed Corporation |
| Boston Scientific Corporation |
| Smith & Nephew |
| Olympus Corporation |
| Others |
Supply Flow & Price Mechanics
Titanium alloy feedstock for surgical-grade instruments concentrates in Japanese and German specialty metallurgy clusters, anchoring margin capture with downstream device manufacturers who bundle sterilization services and extended warranty contracts.
Pricing Analysis
After-sales service revenue tiers—including multi-year maintenance contracts, sterile processing subscriptions, and warranty extensions—drive lifetime value realization for installed surgical platforms. Three-tier pricing structure across premium robotic systems, standard electrosurgical generators, and economy manual instrument kits reflects ISO 13485 certification grades and regional service network density. Cost compression in consumable categories intensifies as third-party reprocessors capture suction and irrigation device share. Ambulatory surgery centers exhibit highest price sensitivity, prioritizing single-use disposables that eliminate capital infrastructure, while academic medical centers absorb premium capital equipment with minimal procurement friction.
Supply Chain Analysis
Surgical-grade titanium and polymer composite feedstocks draw from Japanese Kansai region smelters, German Baden-Württemberg precision engineering clusters, and Yangtze River Delta polymer manufacturers. Device production rests on validated sterilization equipment, ISO 13485-certified contract manufacturing capacity, and electrosurgical generator electronic components. Single-source vulnerability concentrates in titanium alloy qualification pathways, where supplier change requires extended FDA and EU MDR revalidation timelines. Distribution runs through group purchasing organization contracts in US health systems, direct hospital procurement in India's district hospital expansion, and localized service partnerships in China's county-level facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital buying consortia and group purchasing organization consolidation across US multi-hospital systems have shifted procurement leverage toward standardized contracting, fragmenting individual surgeon preference as a pricing determinant.
For Market Incumbents: Pre-empt reprocessor encroachment by embedding instrument tracking software with WHO surgical safety checklist protocols, locking hospitals into bundled compliance-and-hardware contracts. Deepen backward integration into polymer composite molding capacity to secure non-conductive retractor supply chains against raw material volatility. Capture sterile processing workflow retrofit contracts as capital equipment budgets compete for hospital infrastructure investment. For New Entrants and Emerging Players: Mid-tier electrosurgical platforms with localized service networks in China's tier-3 and county-level hospitals represent the most penetrable entry point, given whitespace demand for laparoscopic instrument sets. India's district hospital surgical capacity expansion under government schemes offers secondary entry through electrosurgical generator procurement waves. ISO 13485-certified contract manufacturing partnerships enable quality system compliance without captive production investment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed mid-tier surgical instrument manufacturers lacking software-enabled navigation capabilities. Long-term viability in this market hinges on recurring revenue attachment rates rather than transactional instrument sales. Monitor EU MDR Article 10 post-market surveillance compliance cost escalation as an inflection indicator for portfolio rationalization pressure among undercapitalized competitors.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR conformity assessments compress supplier pools to validated sterilization documentation holders. |
| Hospital System Partnership | Group purchasing organization contracts standardize laparoscopic sets across US multi-hospital networks. |
| Software Companion Development | Instrument tracking systems aligned with WHO surgical safety checklists open bundled service contracts. |
| Reimbursement Strategy | Payor coverage recalibration for robotic-assisted operations determines capital equipment adoption sequencing. |
| Backward Integration | Captive polymer composite molding secures non-conductive retractor supply against feedstock volatility. |
Methodological Framework
A standing panel of hospital purchasing committee directors, biomedical engineers, GPO contracts managers, and sterile processing department heads provided ongoing calibration against market developments. Primary interviews with these stakeholders combined with secondary validation from FDA 510(k) filings, EU MDR notified body certificates, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up instrument shipment tracking and top-down healthcare capital expenditure analysis enabled triangulation across independent estimation pathways.
Scenario bracketing around regulatory enforcement intensity, robotic platform adoption curves, and hospital infrastructure investment cycles anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology tier, end-user facility category, and application specialty, with regional regulatory clusters treated as distinct adoption environments. CAGRs derived from procedure volume elasticity, replacement cycle compression, and premium technology penetration rates, with electrosurgical generator procurement waves in India and China county hospital penetration treated as demand-side inflection inputs.
Practitioners should monitor EU MDR sterilization documentation enforcement, FDA 510(k) biocompatibility data expansion, and third-party reprocessor market share capture for early signals requiring forecast reassessment. Cross-checking against hospital capital expenditure surveys and GPO contract award databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Interspinous Spacers Market
Medical Devices
Reusable Medical Battery Market
Medical Devices
3D Printed Medical Devices Market
Medical Devices
Printed Electronics in Healthcare Market
Medical Devices
Global Microelectronic Medical Implants Market
Medical Devices
Global MRI Safe Cardiac Resynchronization Therapy Device Market
Medical Devices
Syringe Filling Machine Market
Medical Devices
Brazil Ultrasound Devices Market
Medical Devices
India Medical Devices Market
Medical Devices
Acne Treatment Devices Market
Medical Devices
Latin America Biomedical Sensors Market
Medical Devices
Global Photomedicine Market
Medical Devices
Nonvascular Interventional Radiology Devices Market
Medical Devices
Neurovascular Access Catheters Market
Medical Devices
Medical Device Trays Market
Medical Devices
Nephrostomy Catheters Market