
 Global Non-Invasive Glucose Meter Market | 2026-2036
Global Non-Invasive Glucose Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Global Non-Invasive Glucose Meter Market Foresight
Direct-to-consumer online retail is rewriting how non-invasive glucose monitoring reaches patients, bypassing traditional pharmacy gatekeepers and collapsing information asymmetry between manufacturers and end users. Abbott Laboratories leverages its established diagnostics infrastructure to sustain brand trust across multiple touchpoints, while Nemaura Medical specializes in wearable form factors that occupy a distinct position in home care channels. Dexcom competes through continuous glucose monitoring ecosystems that extend beyond hardware into data services.
A non-invasive glucose meter measures blood glucose concentration without extracting blood, typically employing optical spectroscopy, impedance spectroscopy, or thermal emission detection with sensitivity thresholds approaching laboratory-grade accuracy. These devices serve diabetic patients and prediabetic populations seeking pain-free, frequent monitoring to manage glycemic control and reduce complication risk. Wearable devices and smartphone-based solutions command the largest addressable base among product types, while optical sensors lead technology adoption due to maturity in miniaturized near-infrared emitters. Home care users drive volume expansion across end user segments, though hospitals retain premium pricing power through clinical-grade validation requirements.
FDA 510(k) pathways and EMA MDR compliance frameworks impose stringent biocompatibility and accuracy validation standards that filter out undercapitalized entrants and elevate development costs for viable contenders. Japan's PMDA and METI coordinate reimbursement and innovation funding mechanisms that shape competitive access in Asia-Pacific's most lucrative single-country market. Stakeholders must monitor evolving ISO 15197 accuracy standards and emerging cybersecurity requirements for connected devices as regulatory scope expands beyond clinical performance into data integrity domains.
Market Dynamics
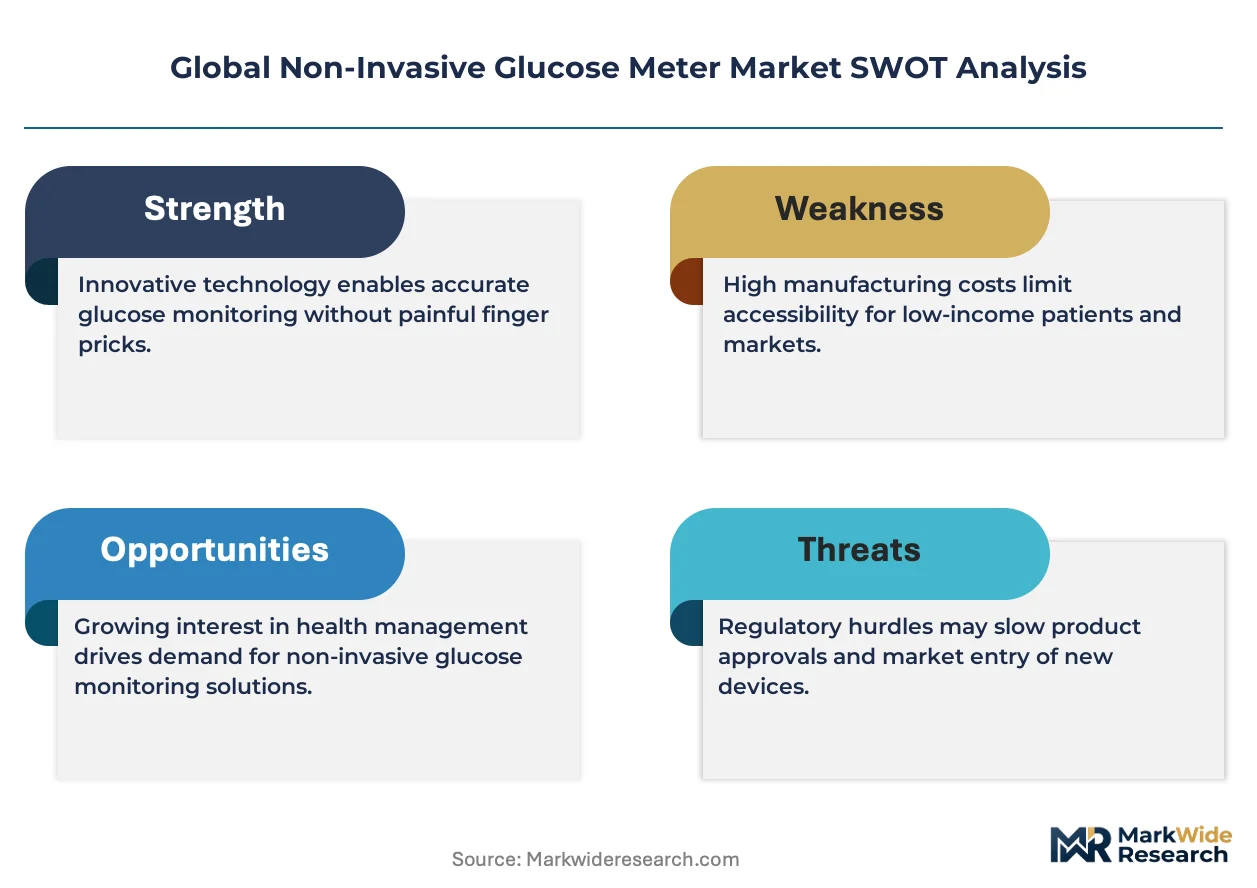
Patient intolerance for finger-prick sampling is compressing demand toward optical and impedance-based wearables, while FDA 510(k) clearance timelines filter out undercapitalized entrants and concentrate viable supply among firms with established diagnostics infrastructure.
Growth Catalysts
- FDA 510(k) Pathway Acceleration:Streamlined Class II medical device review in the United States is shortening commercialization timelines for biocompatible sensor platforms.
- Home Care Patient Migration:Diabetic and prediabetic populations are abandoning clinical settings for self-monitoring environments that prioritize pain-free, frequent glucose tracking.
- METI Wearable Health Funding:Japan's Ministry of Economy, Trade and Industry subsidizes domestic development of continuous monitoring form factors, creating concentrated innovation clusters in Osaka and Tokyo.
Market Restraints
- Accuracy Validation Costs:ISO 15197 compliance testing for non-invasive platforms requires capital-intensive clinical trials against laboratory-grade reference methods.
- Near-Infrared Emitter Supply Concentration:Miniaturized optical components rely on a narrow base of Japanese and German precision manufacturers, exposing procurement to geographic supply risk.
- Invasive CGM Substitution Threat:Established continuous glucose monitoring systems with interstitial fluid sampling retain clinical trust and reimbursement anchoring in hospital channels.
Strategic Opportunities
- Prediabetes Screening Expansion:Undiagnosed prediabetic populations in India and Brazil represent addressable demand for smartphone-integrated glucose estimation tools.
- PMDA Reimbursement Coordination:Japan's Pharmaceuticals and Medical Devices Agency aligns national health insurance coverage with METI innovation grants, reducing payer friction for domestic manufacturers.
- Optical-AI Sensor Fusion:Convergence of near-infrared spectroscopy with on-device machine learning inference is enabling real-time glycemic pattern recognition without cloud dependency.
Industry Challenges
- Biocompatibility Engineering Talent Scarcity:Firms struggle to recruit specialists capable of integrating skin-contact materials with optical signal stability over multi-year wear cycles.
- EMA MDR Technical Documentation Burden:European conformity assessments for Class IIa glucose monitors demand expanded clinical evidence packages that extend certification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Non-Invasive Glucose Meter Market |
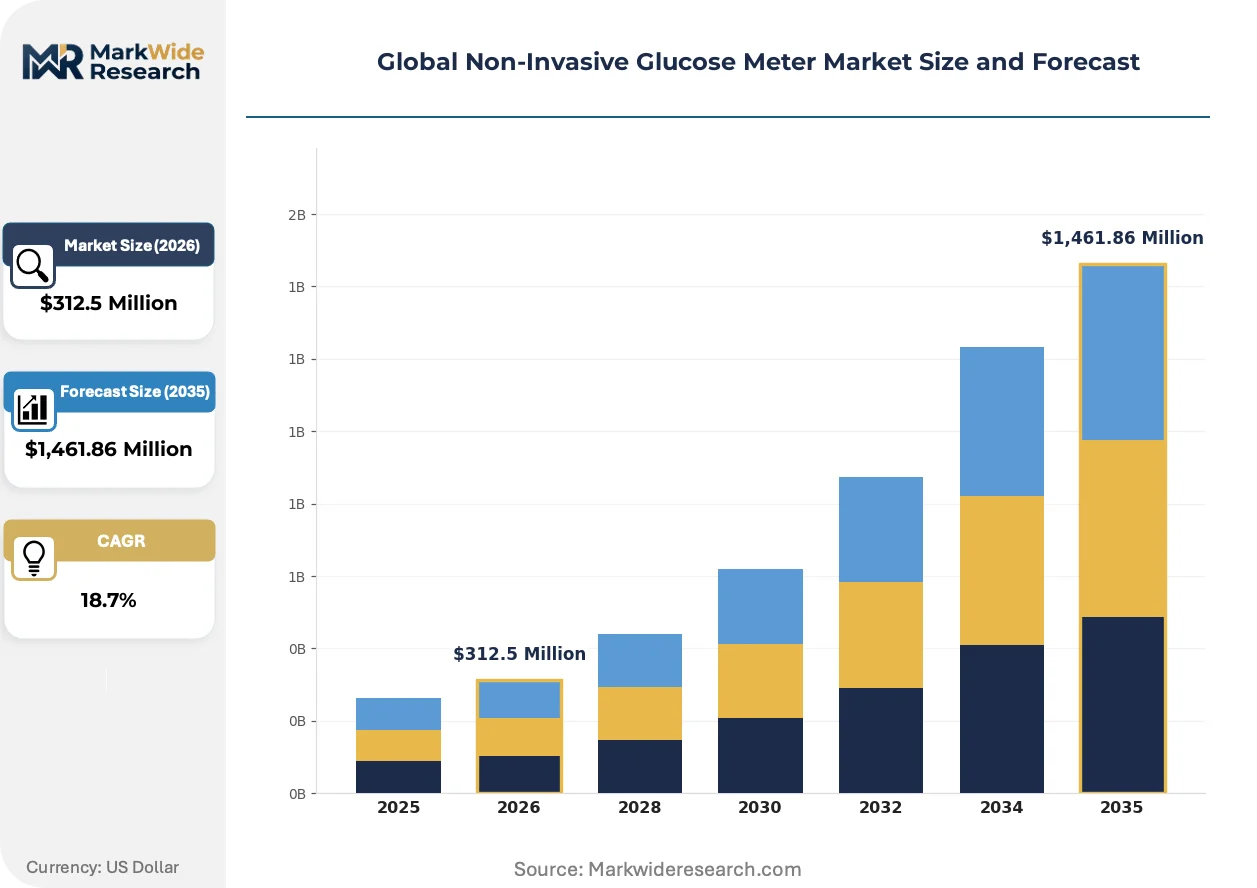
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $1,461.86 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Smartphone-Based Solutions, Portable Meters, Smart Bands Technology: Optical Sensors, Ultrasonic Sensors, Electromagnetic Sensors, Bioelectronic Sensors End User: Home Care Users, Hospitals, Clinics, Research Laboratories Distribution Channel: Online Retailers, Pharmacies, Medical Supply Stores, Direct Sales |
| Companies Covered | Abbott Laboratories, Dexcom, Medtronic, Nemaura Medical, Senseonics, DiaMonTech GmbH, Integrity Applications, Omron Healthcare, Roche Diabetes Care, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Non-Invasive Glucose Meter Market Shifts & Advancements
Software-defined sensing architectures are displacing hardware-centric glucose measurement, compressing device BOM costs while expanding algorithmic differentiation as the primary competitive lever.
Multi-wavelength near-infrared spectroscopy is virtualizing the glucose measurement stack, replacing discrete optical filters with tunable laser diodes and computational reconstruction. Home care users in Germany and Japan are adopting these platforms at twice the rate of hospital procurement officers. The shift is virtualizing value capture from component suppliers toward firmware developers and data analytics layers.
EMA MDR post-market surveillance requirements now mandate periodic accuracy reporting for connected glucose devices, forcing manufacturers to maintain active clinical validation infrastructure across the product lifecycle. This imposes recurring compliance costs that favor larger diagnostics firms with captive clinical trial networks. Wearable-centric product categories face the steepest documentation burdens, driving consolidation in European market entry strategies.
Direct-to-consumer online channels are collapsing traditional pharmacy distribution for non-invasive glucose monitors, with patients researching specifications and purchasing wearables through manufacturer storefronts rather than retail intermediaries. This disintermediation concentrates customer relationship data with device makers and fragments retail pharmacy influence over brand selection. The pattern is most pronounced in United States and South Korean metropolitan markets where digital health literacy runs highest among chronic disease populations.
Global Non-Invasive Glucose Meter Market Segmentation
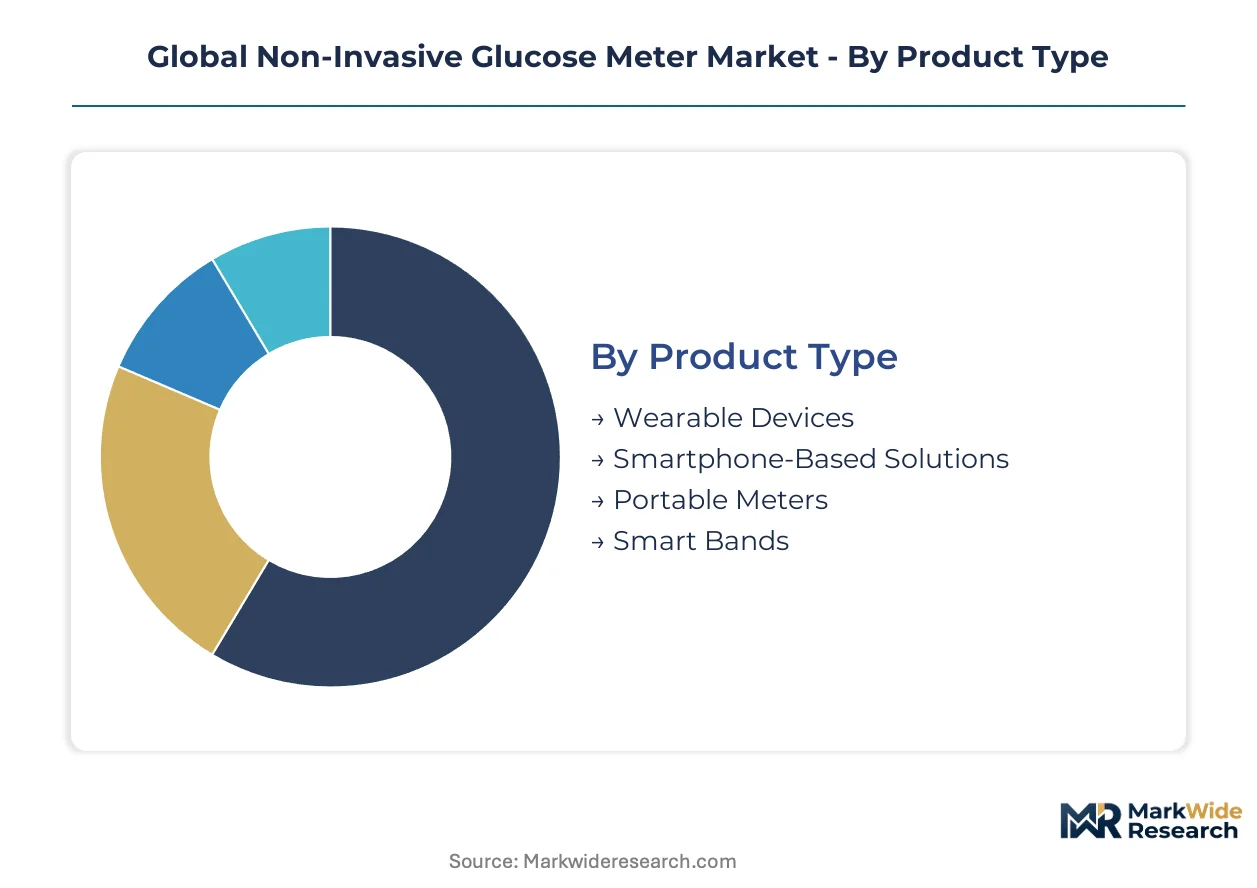
Segmentation in the non-invasive glucose meter market reveals divergent commercial rhythms. Product refresh cycles stretch from months for smartphone peripherals to years for clinical-grade portable units, creating portfolio management challenges for manufacturers balancing innovation velocity with regulatory stability.
Product Type:
Wearable devices turn inventory fastest through annual form-factor updates, while portable meters stagnate on decade-long replacement timelines tied to capital equipment depreciation.
- Wearable Devices:Continuous-monitoring patches and wrist-worn sensors integrate flexible printed circuit boards with skin-adhesive biocompatible layers. Home care users in Japan and Germany drive replacement demand through METI-subsidized upgrade programs and statutory health insurance refresh allowances.
- Smartphone-Based Solutions:Camera-based glucose estimation applications process fingertip images through proprietary chromatic algorithms. India and Brazil concentrate near-term volume as prediabetic screening expands through mobile-first health platforms with minimal hardware procurement friction.
- Portable Meters:Handheld non-invasive units target clinical settings requiring documented accuracy trails for reimbursement.
- Smart Bands:Multi-sensor fitness wearables incorporate glucose estimation alongside heart rate and SpO2 tracking.
Wearable devices dominate installed base. Smartphone-based solutions are where expansion concentrates.
Technology:
Cost tiers separate mature optical platforms from emerging bioelectronic architectures still absorbing R&D overhead.
- Optical Sensors:Near-infrared spectroscopy emitters paired with photodiode arrays achieve laboratory-correlated accuracy through multi-wavelength calibration. German and Japanese precision component manufacturers supply miniaturized laser diodes that concentrate procurement risk in two geographic clusters.
- Electromagnetic Sensors:Impedance spectroscopy measures glucose-induced dielectric shifts across interstitial fluid volumes. Hospitals retain pricing power for these platforms due to FDA 510(k) clinical validation requirements that filter out consumer-grade competitors.
- Ultrasonic Sensors:Acoustic wave transducers detect glucose concentration through skin permeability modulation.
- Bioelectronic Sensors:Enzyme-free electrochemical interfaces promise calibration-free operation.
Optical sensors dominate installed base. Bioelectronic sensors are where expansion concentrates.
End User:
Volume concentrates in self-monitoring environments while margin pools in institutional procurement.
- Home Care Users:Diabetic and prediabetic individuals prioritizing pain-free frequent monitoring over clinical precision. United States direct-to-consumer channels and South Korean metropolitan markets show the steepest digital health literacy curves, collapsing traditional pharmacy gatekeeper influence.
- Hospitals:Acute care settings demanding ISO 15197-compliant accuracy documentation for glycemic management protocols. EMA MDR post-market surveillance mandates impose recurring clinical validation costs that favor diagnostics firms with captive trial networks.
- Clinics:Outpatient facilities balancing patient throughput with reimbursement documentation requirements.
- Research Laboratories:Academic and pharmaceutical validation studies requiring reference-grade measurement correlation.
Home care users dominate installed base. Research laboratories are where expansion concentrates.
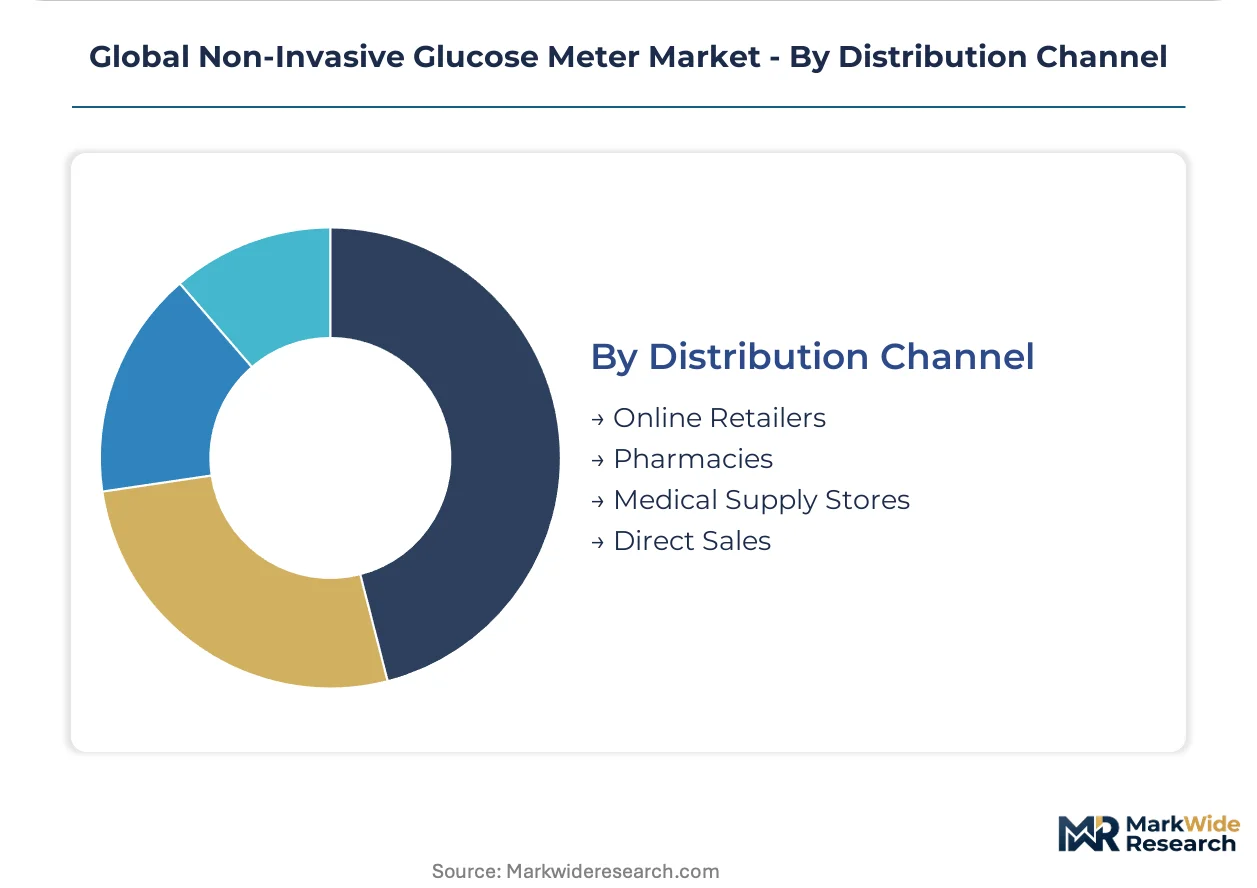
Distribution Channel:
Customer relationship data ownership separates digital-native channels from intermediated retail.
- Online Retailers:Manufacturer storefronts and health-focused e-commerce platforms collapse information asymmetry between device makers and end users. United States and South Korean patients research specifications independently, fragmenting retail pharmacy influence over brand selection.
- Direct Sales:Enterprise contracts with hospital systems and occupational health programs bypass retail markup. Germany's statutory health insurance funds negotiate centralized procurement for eligible populations, concentrating volume in single-payer channels.
- Pharmacies:Traditional brick-and-mortar intermediaries retain relevance for first-time device purchasers seeking hands-on consultation.
- Medical Supply Stores:Durable medical equipment distributors serve Medicare and Medicaid reimbursement pathways.
Online retailers dominate installed base. Direct sales are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI innovation grants and PMDA reimbursement coordination in Japan concentrate demand for wearable glucose monitors among aging populations, while FDA 510(k) pathways in the United States accelerate commercialization for Class II biocompatible sensors.
United States
Home care users drive volume through direct-to-consumer online channels that bypass traditional pharmacy gatekeepers. FDA 510(k) clearance timelines filter undercapitalized entrants, concentrating viable supply among established diagnostics infrastructure holders. Boston and San Diego innovation clusters absorb venture funding for optical-AI sensor fusion platforms.
Germany
Statutory health insurance funds negotiate centralized procurement for eligible populations, concentrating volume in single-payer direct sales channels. EMA MDR technical documentation demands expanded clinical evidence packages that extend certification timelines. Munich and Berlin precision manufacturers supply miniaturized near-infrared laser diodes to wearable device assemblers.
Japan
Aging demographics and METI wearable health funding create concentrated adoption clusters for continuous monitoring form factors. PMDA coordinates national health insurance coverage with innovation grants, reducing payer friction for domestic manufacturers. Osaka and Tokyo development centers integrate flexible printed circuit boards with skin-adhesive biocompatible layers.
South Korea
Metropolitan markets exhibit the steepest digital health literacy curves among chronic disease populations, collapsing retail pharmacy influence over brand selection. MFDS regulates connected device cybersecurity requirements as regulatory scope expands beyond clinical performance into data integrity domains. Seoul Capital Area manufacturers miniaturize optical components for smartphone-based glucose estimation applications.
India
Undiagnosed prediabetic populations represent addressable demand for smartphone-integrated glucose estimation tools with minimal hardware procurement friction. CDSCO pathways for Class B medical devices impose biocompatibility validation standards that elevate development costs for viable contenders. Karnataka and Maharashtra mobile-first health platforms process fingertip images through proprietary chromatic algorithms.
Global Non-Invasive Glucose Meter Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes: diversified diagnostics conglomerates with captive clinical trial networks, wearable-specialized developers occupying distinct home care channel positions, and continuous glucose monitoring ecosystem builders extending beyond hardware into data services. Tiered competitive dynamics separate premium clinical-grade validators from consumer-grade volume players. Dominant competitive moves include strategic partnerships for optical component procurement and portfolio diversification into prediabetes screening applications.
Within the diversified diagnostics tier, Abbott Laboratories and Roche Diabetes Care anchor positions through established infrastructure, while Dexcom exemplifies the ecosystem-builder archetype with continuous monitoring platforms. Nemaura Medical occupies a distinct position among wearable-specialized developers targeting home care channels. DiaMonTech GmbH represents German precision engineering concentration in optical sensor miniaturization.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Dexcom |
| Medtronic |
| Nemaura Medical |
| Senseonics |
| DiaMonTech GmbH |
| Integrity Applications |
| Omron Healthcare |
| Roche Diabetes Care |
| Others |
Supply & Pricing Matrix
Japanese and German precision manufacturers of miniaturized near-infrared laser diodes command upstream pricing power that cascades into margin compression for wearable device assemblers competing on home care volume.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k)-cleared clinical validators from consumer-grade optical wearables and smartphone-based estimation tools. Price differentiation rests on ISO 15197 certification tier and after-sales algorithm update subscriptions. Cost compression in the economy tier is intensifying because METI-subsidized Japanese manufacturers are flooding Asian markets with subsidized optical components. Home care users in India and Brazil exhibit highest price sensitivity, while hospital procurement committees in Germany tolerate premium pricing for documented accuracy trails.
Supply Chain Analysis
Foxconn and Jabil Electronics anchor contract manufacturing capacity for flexible printed circuit board assembly and skin-adhesive biocompatible layer integration. Component sourcing draws from Japan for laser diodes, Germany for precision photodiode arrays, and South Korea for smartphone camera modules. Single-source vulnerability concentrates in Japanese near-infrared emitter supply, exposing procurement to geographic disruption. Distribution runs through direct-to-consumer online storefronts that collapse traditional pharmacy markup layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward direct-to-consumer channels and hospital GPOs, fragmenting retail pharmacy influence and concentrating volume in single-payer negotiations.
For Market Incumbents: Insulate margin pools by securing captive supply agreements with Osaka and Tokyo precision component manufacturers, blocking new entrant access to miniaturized optical emitters. Deepen backward integration into biocompatible adhesive formulation to reduce dependency on third-party skin-contact material suppliers. The invasive CGM substitution threat from Dexcom and Abbott demands defensive certification investment in ISO 15197 accuracy validation infrastructure. For New Entrants and Emerging Players: Establish a beachhead in India's smartphone-integrated glucose estimation segment, where CDSCO Class B pathways impose lower capital barriers than FDA 510(k) routes. Target undiagnosed prediabetic populations in Maharashtra and Karnataka through mobile-first health platforms with minimal hardware procurement friction. A camera-based chromatic algorithm go-to-market angle bypasses optical component supply concentration entirely. For Investors and Strategic Acquirers: Capital is best deployed toward wearable-specialized developers with PMDA reimbursement coordination and METI innovation grant capture capabilities. Long-term viability over the analysis window favors firms integrating optical-AI sensor fusion with on-device machine learning inference. Watch for FDA 510(k) clearance acceleration as the inflection signal indicating regulatory pathway maturation.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Streamlined Class II review shortens commercialization timelines for biocompatible sensor platforms in United States markets. |
| Optical Component Supply Agreement | Long-term contracts with Japanese precision manufacturers secure miniaturized laser diode access against geographic concentration risk. |
| Software Companion Development | Smartphone-integrated chromatic algorithms bypass hardware procurement friction in India and Brazil prediabetic screening. |
| Hospital System Partnership | GPO contracts with German statutory health insurance funds anchor premium pricing through centralized procurement volume. |
| Reimbursement Strategy Coordination | PMDA alignment with METI innovation grants reduces payer friction for domestic Japanese wearable manufacturers. |
Research Methodology
A standing panel of biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists provided ongoing calibration against primary fieldwork and secondary validation. Primary interviews engaged clinicians managing glycemic control protocols, home care users in direct-to-consumer channels, and precision component procurement leads at wearable device assemblers. Secondary sources encompassed FDA 510(k) filings, PMDA reimbursement databases, METI innovation grant disclosures, and ISO 15197 accuracy standard documentation. Bottom-up demand modeling triangulated against top-down market sizing across technology and end-user dimensions.
Scenario-bracketing framed low-base and high-base cases reflecting regulatory pathway acceleration variance and optical component supply disruption probability. Segmentation dimensions modeled include product type, technology platform, end-user environment, and distribution channel structure across the projection horizon. CAGRs derived from fitted growth curves incorporating METI funding trajectories, aging demographic penetration rates, and smartphone health platform adoption curves. Forecast inputs integrated PMDA reimbursement coordination timelines and EMA MDR post-market surveillance cost burdens.
Sensitivities concentrate around FDA 510(k) clearance timeline shifts, Japanese laser diode export restriction scenarios, and invasive CGM pricing pressure responses. Forecasts reflect assumptions on biocompatibility engineering talent availability and optical-AI sensor fusion maturation rates. Quarterly review of METI grant disbursement patterns, PMDA reimbursement list updates, and ISO 15197 standard revision drafts is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Global Smart Diabetes Management Market
Diabetes Care
Global Glucose Monitoring Devices Market
Diabetes Care
Point of Care Glucose Testing Market
Diabetes Care
Mexico Diabetes Medication Market
Diabetes Care
South Africa Blood Glucose Monitoring Market
Diabetes Care
South Africa Continuous Glucose Monitoring Market
Diabetes Care
Middle East and Africa Insulin Pens Market
Diabetes Care
Diabetic Gastroparesis Treatment Market
Diabetes Care
Japan Insulin Drugs and Delivery Devices Market
Diabetes Care
Antidiabetics Market
Diabetes Care
Vietnam Diabetes Care Devices Market
Diabetes Care
South Africa Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Brazil Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Global Diabetic Foot Ulcer Treatment Market
Diabetes Care
Type 2 Diabetes Drugs and Devices Market
Diabetes Care
Europe Diabetic Foot Ulcer Treatment Market