
 Transcutaneous Oximetry Systems Market | 2026-2036
Transcutaneous Oximetry Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Transcutaneous Oximetry Systems Market Outlook
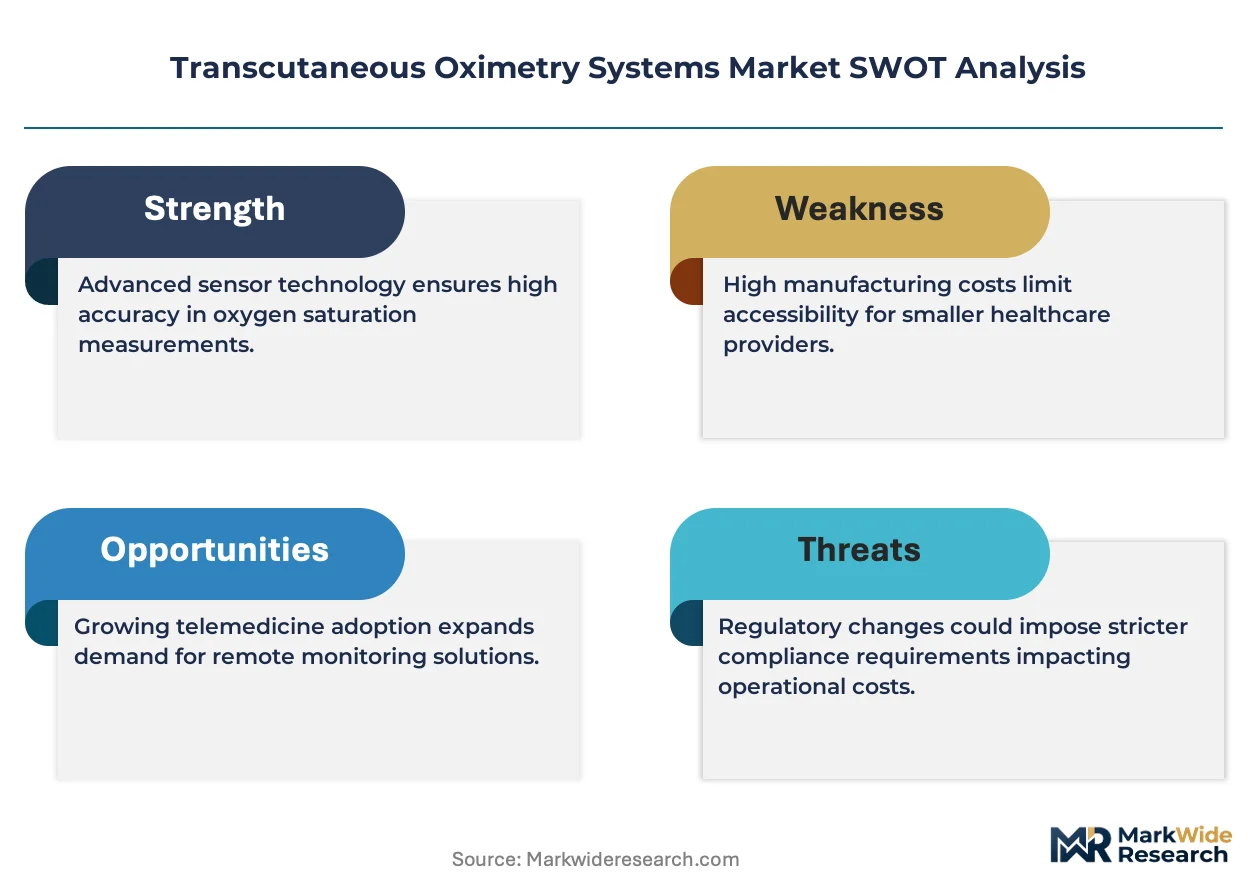
Silver-silver chloride electrode chemistry is decoupling from traditional Clark electrode designs in next-generation sensors, reducing calibration frequency and extending sensor longevity. Radiometer Medical ApS leverages its blood gas heritage to dominate hospital laboratory placements. Perimed AB specializes in microcirculation research applications, sustaining premium positioning in academic medical centers. Masimo Corporation extends its pulse oximetry brand into transcutaneous monitoring, competing through integrated multimodal platforms.
Transcutaneous oximetry systems measure oxygen tension at the skin surface via heated sensors that induce local hyperemia, typically operating at electrode temperatures between 43°C and 45°C to maximize arterialization of cutaneous blood flow. These devices serve critical functions in wound healing assessment, amputation-level determination, and hyperbaric oxygen therapy efficacy monitoring. Portable monitors represent the fastest-expanding product category as point-of-care testing migrates beyond traditional hospital settings. Electrochemical sensors anchor the installed base due to proven accuracy in hypoxic range detection, though optical sensors are gaining traction in sports medicine applications where motion artifact tolerance matters.
The FDA's 510(k) premarket notification framework governs device clearance in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for Class IIa monitoring equipment in Europe. Japan's PMDA enforces QMS conformity assessments that filter out lower-reliability entrants, preserving market quality standards. Stakeholders must weigh regulatory pathway complexity against addressable market breadth when prioritizing geographic expansion sequences.
Market Dynamics
Silver-silver chloride electrode chemistry is displacing traditional Clark electrode designs as the dominant sensing architecture, fundamentally altering calibration protocols and sensor replacement economics across clinical settings.
Growth Catalysts
- FDA 510(k) Pathway:The streamlined premarket notification framework accelerates multi-parameter monitoring device approvals, compressing product entry timelines for manufacturers targeting the United States.
- Wound Care Clinic Expansion:Non-invasive perfusion assessment protocols are replacing invasive alternatives across outpatient settings, driving installed base growth in specialized wound healing centers.
- Heated Sensor Standardization:Operating temperatures between 43°C and 45°C now dominate design specifications, enabling arterialization of cutaneous blood flow with proven hypoxic range accuracy.
Market Restraints
- Electrode Material Cost Volatility:Silver price fluctuations directly impact sensor manufacturing economics, squeezing margins for electrochemical sensor producers.
- EU MDR Clinical Evidence Burden:The Medical Device Regulation imposes stricter documentation requirements for Class IIa monitoring equipment, extending European market entry timelines.
- Optical Sensor Substitution Pressure:Photoplethysmography-based alternatives are gaining traction in sports medicine applications where motion artifact tolerance outweighs hypoxic precision requirements.
Strategic Opportunities
- Germany Laboratory Integration:Hospital laboratory placements remain underpenetrated for transcutaneous oximetry systems with blood gas analyzer connectivity, offering expansion potential for systems with automated calibration.
- Portable Monitor Channel Innovation:Point-of-care testing migration beyond traditional hospital settings creates white space for wireless-enabled monitors with cloud-based data transmission.
- Hyperbaric Oxygen Therapy Efficacy Monitoring:Emerging reimbursement protocols for chronic wound treatment are mandating objective perfusion documentation, creating regulatory tailwind for quantitative monitoring adoption.
Industry Challenges
- Biomedical Engineer Talent Scarcity:Specialized expertise in electrochemical sensor design and thermal regulation engineering remains concentrated among legacy blood gas equipment manufacturers.
- Legacy EMR Integration Complexity:Hospital information system connectivity requires HL7 FHIR compliance and proprietary middleware development, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transcutaneous Oximetry Systems Market |
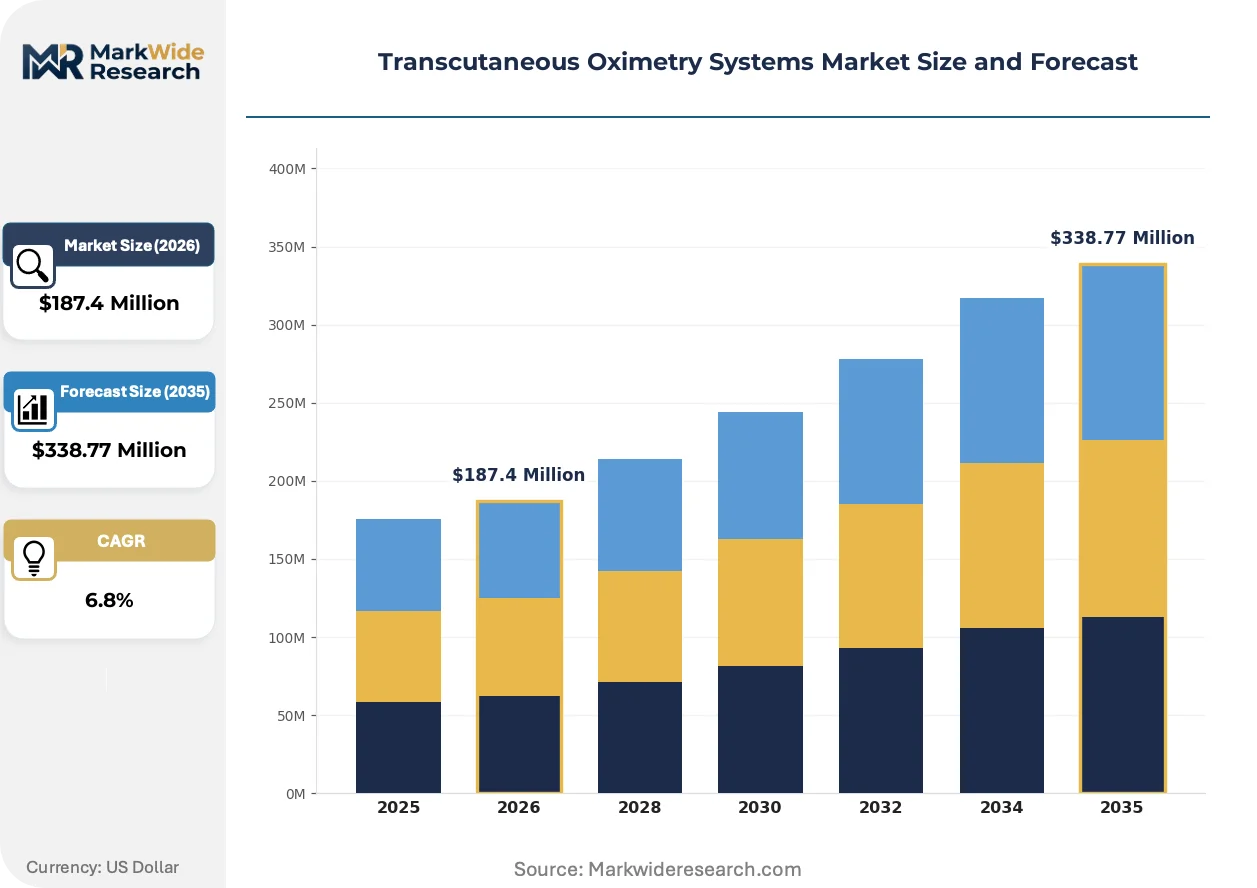
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Devices, Integrated Systems, Portable Monitors, Wireless Units End User: Hospitals, Clinics, Homecare Settings, Research Laboratories Technology: Infrared Spectroscopy, Optical Sensors, Electrochemical Sensors, Laser Doppler Application: Monitoring Hypoxia, Postoperative Care, Wound Assessment, Sports Medicine |
| Companies Covered | Radiometer Medical ApS, Perimed AB, SenTec AG, Koninklijke Philips N.V., Drägerwerk AG & Co. KGaA, GE HealthCare, Masimo Corporation, Medtronic plc, Nihon Kohden Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transcutaneous Oximetry Systems Market Strategic Shifts
Sensor miniaturization and multimodal platform integration are compressing device footprints while expanding parameter capture, reshaping competitive requirements for both laboratory and point-of-care deployment.
Wireless transcutaneous monitors are electrifying deployment flexibility across ambulatory care settings. These battery-powered units transmit oxygen tension data to centralized dashboards without tethered connections. Wound care clinics in Germany and Japan are adopting portable configurations at accelerating rates. The technology is electrifying competitive positioning for manufacturers capable of integrating pulse oximetry, temperature mapping, and perfusion indices within single handheld units.
Japan's PMDA QMS conformity assessments are filtering lower-reliability entrants from the medical device marketplace. The quality management system requirements impose rigorous design control and post-market surveillance obligations. Domestic Japanese manufacturers with established regulatory affairs infrastructure capture disproportionate share of new hospital installations. International competitors must establish in-country quality representatives or partner with local distributors possessing PMDA-certified facilities.
After-sales service unbundling is fragmenting traditional equipment procurement relationships. Hospital procurement departments now separate hardware acquisition from calibration service contracts and sensor supply agreements. Third-party biomedical service firms are capturing maintenance revenue previously retained by original equipment manufacturers. This pattern is most visible in United States academic medical centers where centralized procurement offices mandate multi-vendor service competition.
Transcutaneous Oximetry Systems Market Segmentation
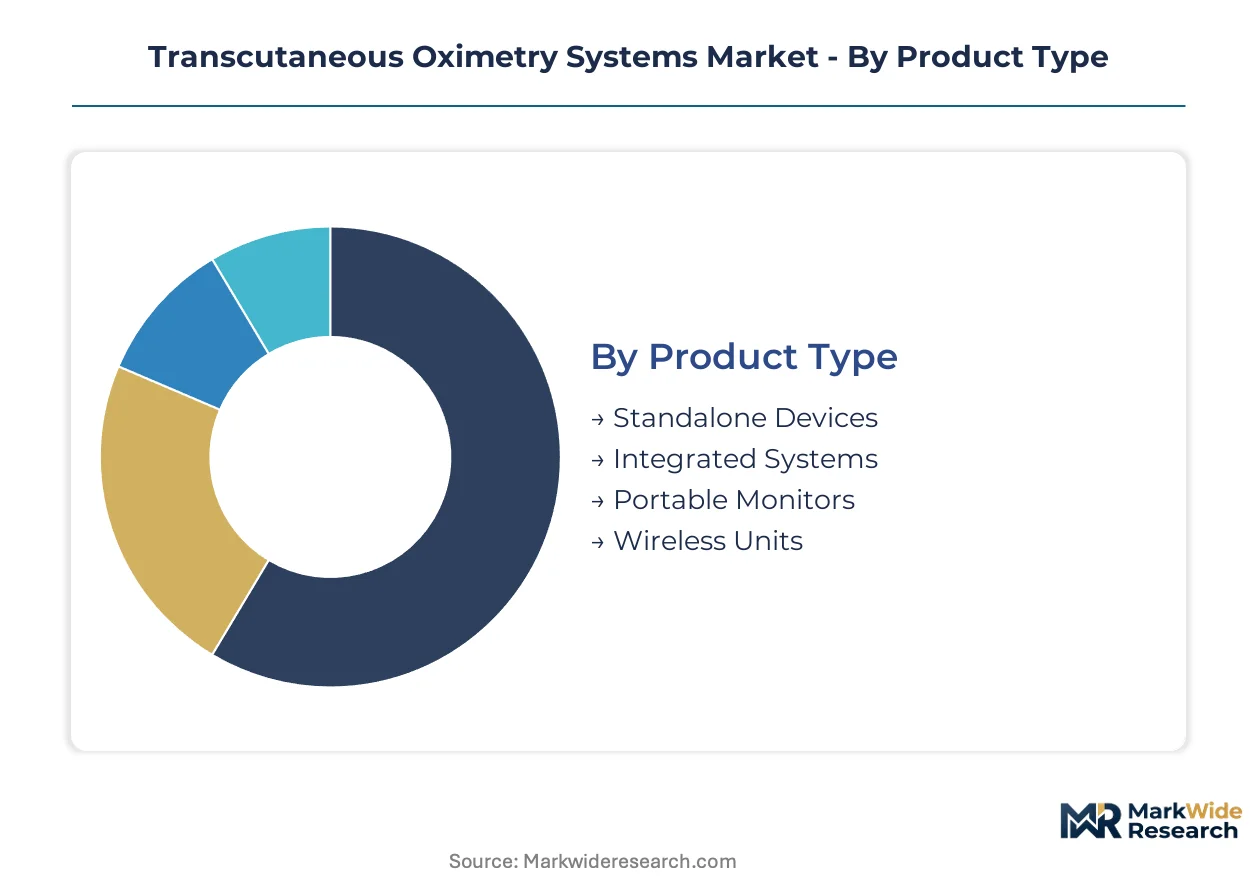
Product architecture determines calibration protocols, sensor replacement economics, and regulatory pathway complexity across clinical settings. Understanding segment boundaries clarifies where heated electrode designs compete against emerging optical alternatives.
Product Type:
Procurement departments weigh capital expenditure against per-test operational costs when selecting system configurations.
- Standalone Devices:Self-contained units with dedicated displays and internal power supplies dominate hospital laboratory installations. Demand concentrates in Germany and Japan where blood gas analyzer integration requires standardized output protocols.
- Portable Monitors:Battery-powered configurations with wireless data transmission are expanding most quickly in wound care clinics. United States outpatient facilities favor these for point-of-care testing migration beyond traditional hospital settings.
- Integrated Systems:Modular designs connect to central monitoring stations through HL7 FHIR-compliant interfaces.
- Wireless Units:Untethered sensors transmit oxygen tension data to cloud-based dashboards for ambulatory monitoring.
Standalone devices lead on scale; portable monitors lead on momentum.
End User:
Reimbursement coding variations across settings reshape equipment specification requirements and service contract structures.
- Hospitals:Acute care facilities prioritize multi-parameter platforms with EMR connectivity and automated calibration routines. United States academic medical centers drive demand for systems with third-party service compatibility.
- Clinics:Specialized wound healing centers require non-invasive perfusion assessment tools with rapid deployment protocols. Germany's outpatient network is expanding installed base for heated sensor configurations operating at 43°C to 45°C.
- Homecare Settings:Post-discharge monitoring applications favor lightweight designs with simplified user interfaces.
- Research Laboratories:Microcirculation studies demand precision instrumentation with customizable measurement parameters.
Hospitals anchor revenue concentration; clinics are climbing the fastest.
Technology:
Sensor chemistry selection trades hypoxic range precision against motion artifact tolerance and manufacturing cost stability.
- Electrochemical Sensors:Silver-silver chloride electrode designs deliver proven accuracy in low-oxygen detection scenarios. Hospital laboratories in Japan and the United States retain these for amputation-level determination protocols despite silver price volatility.
- Optical Sensors:Photoplethysmography-based alternatives tolerate patient movement during measurement. Sports medicine applications in the United States favor these where motion artifact outweighs hypoxic precision requirements.
- Infrared Spectroscopy:Non-contact measurement approaches eliminate thermal heating requirements entirely.
- Laser Doppler:Perfusion imaging capabilities support microvascular research applications.
Electrochemical sensors dominate installed base; optical alternatives gain share fastest.
Application:
Clinical indication determines sensor temperature protocols, measurement duration standards, and documentation requirements for reimbursement.
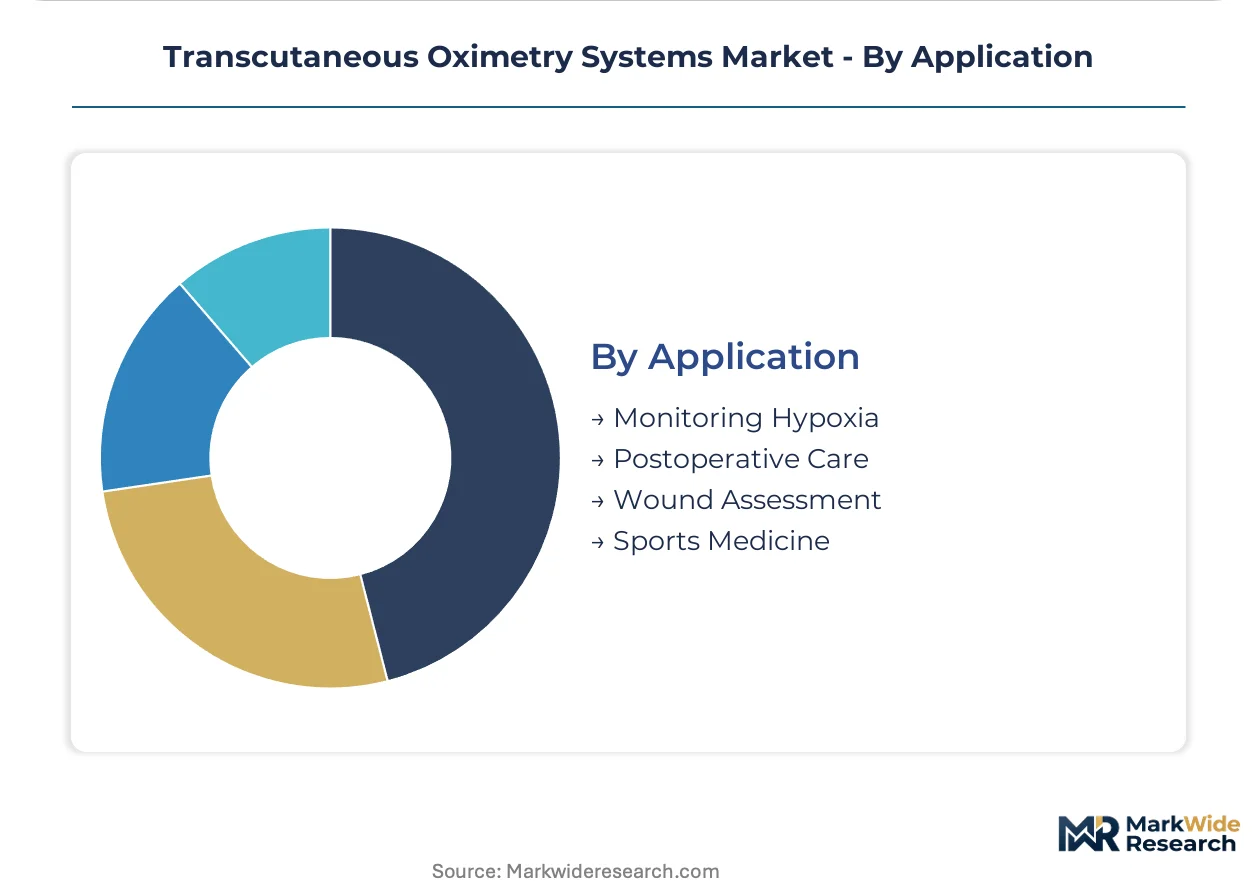
- Wound Assessment:Chronic wound protocols mandate objective perfusion documentation for hyperbaric oxygen therapy efficacy verification. United States reimbursement rules are tightening requirements for quantitative monitoring data.
- Monitoring Hypoxia:Critical care applications demand continuous oxygen tension tracking with alarm thresholds. German hospital laboratories specify these for peripheral artery disease evaluation.
- Postoperative Care:Surgical recovery units utilize intermittent monitoring to detect compromised tissue perfusion.
- Sports Medicine:Athletic performance testing emphasizes rapid assessment portability over clinical-grade precision.
Wound assessment commands premium pricing; hypoxia monitoring sustains volume leadership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's hospital laboratory network concentrates the densest installed base of electrochemical sensor systems outside Japan, with Bavaria and North Rhine-Westphalia driving procurement standardization for blood gas analyzer-integrated platforms.
United States
Wound care clinic expansion and hyperbaric oxygen therapy reimbursement mandates propel portable monitor demand. FDA 510(k) clearances accelerate multi-parameter device entry timelines. Texas and Florida outpatient networks are deploying wireless-enabled configurations for point-of-care testing migration.
Germany
Hospital laboratory placements prioritize automated calibration and HL7 FHIR connectivity for blood gas integration. EU MDR clinical evidence requirements filter lower-reliability entrants from Class IIa monitoring equipment. Bavaria's university medical centers sustain premium positioning for microcirculation research applications.
Japan
PMDA QMS conformity assessments preserve quality standards by filtering unreliable device entrants. Domestic manufacturers with established regulatory infrastructure capture disproportionate hospital installation share. Tokyo and Osaka academic centers drive demand for precision instrumentation with customizable measurement parameters.
United Kingdom
NHS procurement frameworks emphasize third-party service competition and multi-vendor maintenance contracts. Post-discharge monitoring applications favor lightweight designs with simplified user interfaces. London and Southeast England research laboratories sustain niche demand for laser Doppler perfusion imaging capabilities.
China
NMPA medical device registration requirements extend market entry timelines for international competitors. Local manufacturers leverage cost advantages in electrochemical sensor production. Yangtze River Delta hospital clusters are adopting integrated multimodal platforms for peripheral artery disease evaluation protocols.
Transcutaneous Oximetry Systems Market Competitive Environment
Strategic partnerships dominate the current landscape as manufacturers seek regulatory expertise and distribution reach without full acquisition costs. The vendor base concentrates around legacy blood gas equipment heritage, specialized microcirculation research positioning, and pulse oximetry brand extension archetypes. Three structural tiers have emerged: integrated multimodal platform providers, standalone electrochemical sensor specialists, and optical alternative innovators. Portfolio diversification and geographic expansion through distributor relationships represent the dominant competitive moves.
Within the blood gas heritage tier, Radiometer Medical ApS and Drägerwerk AG & Co. KGaA occupy positions anchored by hospital laboratory relationships and automated calibration expertise. Perimed AB exemplifies the specialized research positioning archetype, sustaining premium placement in academic medical centers requiring microcirculation precision. Masimo Corporation represents the brand extension vector, leveraging pulse oximetry recognition into transcutaneous monitoring through integrated platform architecture. These three patterns illustrate how regulatory navigation capability, clinical application focus, and existing brand equity stratify competitive positioning.
| Leading Market Players |
|---|
| Radiometer Medical ApS |
| Perimed AB |
| SenTec AG |
| Koninklijke Philips N.V. |
| Drägerwerk AG & Co. KGaA |
| GE HealthCare |
| Masimo Corporation |
| Medtronic plc |
| Nihon Kohden Corporation |
| Others |
Value Chain & Pricing Dynamics
United States academic medical centers concentrate procurement leverage for transcutaneous oximetry systems, driving three-tier pricing structure across premium, standard, and economy levels based on calibration automation and EMR connectivity depth.
Pricing Analysis
Silver electrode cost pass-through dominates sensor pricing dynamics, with manufacturers indexing replacement component tariffs to London Metal Exchange spot movements. Price differentiation hinges on FDA 510(k) clearance tier and automated calibration capability, with premium configurations commanding substantial service contract premiums. Pricing pressure stems from optical sensor substitution in sports medicine applications where motion tolerance outweighs hypoxic precision. Wound care clinics exhibit highest price sensitivity due to reimbursement compression, while Japan's academic medical centers show lowest sensitivity given PMDA quality prioritization.
Supply Chain Analysis
Biomedical engineer scarcity in Denmark and Germany constrains electrochemical sensor manufacturing expansion, forcing reliance on legacy blood gas equipment heritage firms. Raw material dependencies center on silver-silver chloride electrode chemistry, lithium polymer battery cells for portable units, and precision thermal control components. Supply chain risk concentrates in single-source vulnerability for heated sensor substrates subject to Japan's PMDA QMS conformity assessments. Distribution runs through specialized medical device distributors with in-country regulatory affairs infrastructure, particularly in Germany and Japan where hospital laboratory relationships require localized service presence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The transcutaneous oximetry systems market compounds regulatory tailwinds as FDA reimbursement mandates for hyperbaric oxygen therapy efficacy documentation harden demand for quantitative perfusion monitoring.
For Market Incumbents: Anticipate optical sensor encroachment in sports medicine by deepening automated calibration expertise and securing exclusive GPO contracts with United States wound care clinic networks. Prioritize backward integration into silver-silver chloride electrode production to buffer commodity volatility. Defend hospital laboratory placements through HL7 FHIR-compliant EMR connectivity investments that raise switching costs for Radiometer Medical ApS and Drägerwerk AG & Co. KGaA accounts. For New Entrants and Emerging Players: Capture Germany's underpenetrated outpatient wound healing network by offering wireless-enabled portable monitors with cloud-based dashboards at standard-tier pricing. Target Texas and Florida clinic clusters where point-of-care testing migration accelerates fastest. Pursue strategic partnerships with third-party biomedical service firms to bypass incumbent after-sales service bundling. For Investors and Strategic Acquirers: Pulse oximetry platform manufacturers are the most active acquirer in this space, seeking transcutaneous monitoring capabilities to complete multimodal vital signs portfolios. Five-to-ten year viability rests on regulatory navigation infrastructure rather than hardware differentiation alone. Monitor FDA 510(k) clearance velocity for multi-parameter devices as inflection indicator for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | United States CMS coding alignment for hyperbaric oxygen therapy mandates objective perfusion documentation protocols. |
| Hospital System Partnership | Bavaria university medical centers sustain premium positioning for microcirculation research instrumentation. |
| Software Companion Development | HL7 FHIR-compliant cloud dashboards enable wireless portable monitor adoption across German outpatient networks. |
| CE Marking Pathway | EU MDR clinical evidence requirements filter lower-reliability Class IIa monitoring equipment from European market entry. |
| Strategic Partnership | Third-party biomedical service firms capture maintenance revenue from United States academic medical center procurement offices. |
Study Parameters
Direct dialogue with biomedical engineers, hospital purchasing committee members, wound care clinic directors, and GPO contracts managers grounded primary intelligence, validated against FDA 510(k) clearance databases, PMDA QMS registration records, hospital procurement contract filings, and CMS reimbursement coding updates. Bottom-up installed base estimates triangulated with top-down market sizing across electrochemical and optical sensor technology segments.
Segment-level revenue projections incorporated product type differentiation between standalone laboratory devices and portable wireless monitors, end-user concentration across hospitals versus wound care clinics, and technology split between heated electrode and photoplethysmography architectures. CAGRs derived from regression analysis of historical adoption curves calibrated to regulatory milestone impacts, with wound assessment application protocols and hypoxia monitoring standards as key forecast inputs across the projection horizon.
Underlying measurement precision varies by segment; electrochemical sensor hospital laboratory placements carry tighter precision than emerging optical sports medicine applications. Forecasts assume continued FDA 510(k) pathway stability, silver price band containment, and EU MDR enforcement consistency. Practitioners should monitor PMDA QMS assessment timelines and optical sensor accuracy improvements in hypoxic ranges for early signals of competitive reordering.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
External Pacemakers Market
Medical Devices
Implantable Neurostimulators Market
Medical Devices
Inhaled Nitric Oxide (NO) Delivery Systems Market
Medical Devices
Lower Limb Prosthetics Market
Medical Devices
Global Cervical Total Disc Replacement (CTDR) Market
Medical Devices
Needle-Free Drug Delivery Devices Market
Medical Devices
Blood Irradiator Device Market
Medical Devices
Minimally Invasive Neurosurgery Devices Market
Medical Devices
Japan Medical Device Regulatory Affairs Market
Medical Devices
South America Single-Use Medical Device Reprocessing Market
Medical Devices
Global Endodontic Reparative Cement Market
Medical Devices
SPG Microstimulator System Market
Medical Devices
UK Surgical Devices Market
Medical Devices
Global Patient Warming Systems Market
Medical Devices
Ultrasonic Diathermy Market
Medical Devices
Ventilator Breathing Circuit Market