
 Medical Devices Reimbursement Market | 2026-2036
Medical Devices Reimbursement Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Devices Reimbursement Market Intelligence
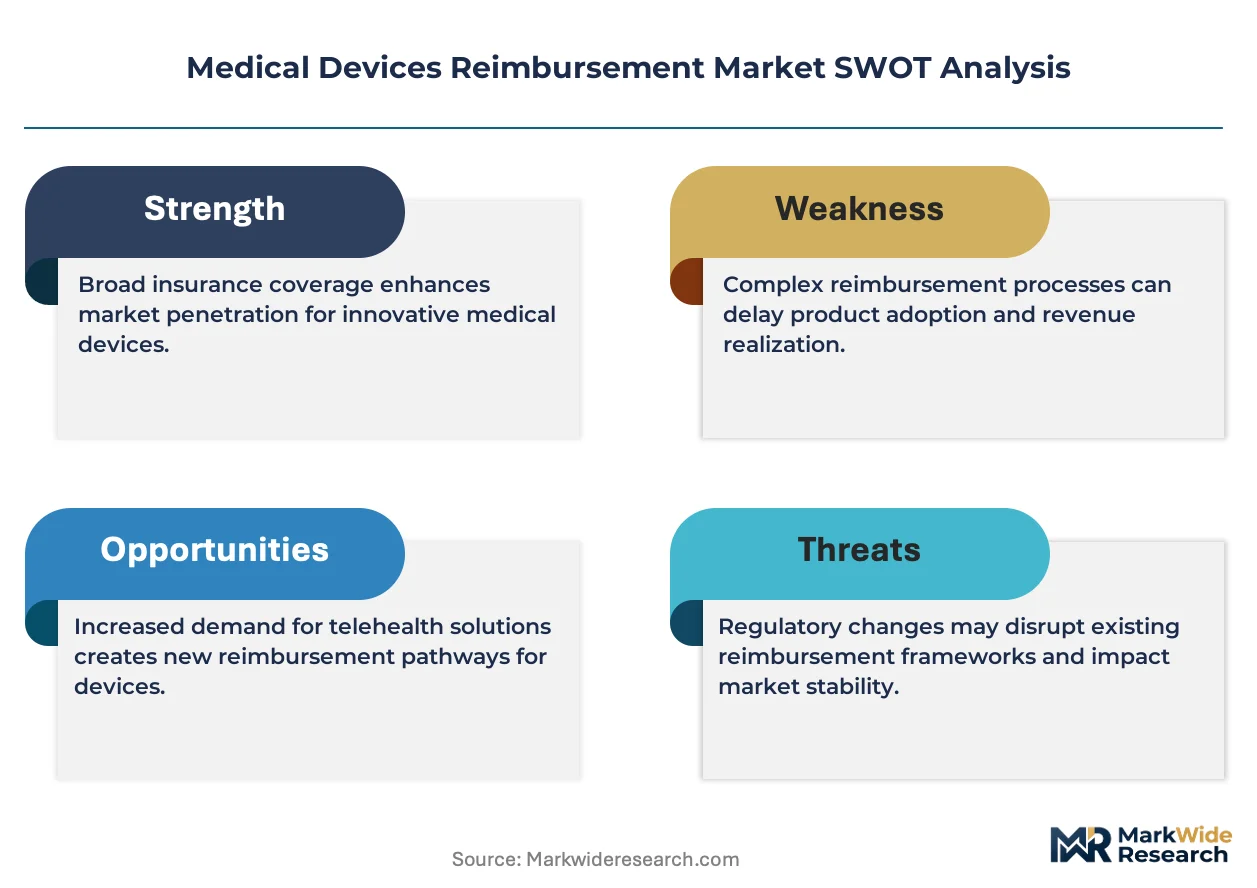
US private payers is recalibrating coverage frameworks for connected cardiac monitors and robotic surgical systems. UnitedHealth Group leverages its Optum data infrastructure to anchor value-based contracting for high-cost implantable devices. Allianz competes through specialized reimbursement products targeting European hospital networks. Cigna differentiates with bundled payment models for orthopedic procedures across its national provider footprint.
Medical devices reimbursement encompasses the financial mechanisms through which healthcare payers compensate providers for the use of regulated diagnostic, therapeutic, and monitoring equipment, typically governed by coding systems such as HCPCS and DRG classifications that establish payment thresholds based on clinical efficacy and cost-effectiveness benchmarks. Its primary commercial purpose is to align capital-intensive medical technology adoption with sustainable payer economics while ensuring patient access to innovative care. Diagnostic equipment claims processing occupies mature margin pools due to established CPT code density, while value-based care payment models represent the fastest-growing structural segment as risk-bearing entities seek to tie device utilization to outcome metrics. Monitoring devices within home care settings sustain premium reimbursement rates where remote data capture reduces acute utilization.
FDA breakthrough device designation interacts with CMS national coverage determination pathways to shape market access timelines for novel technologies. HIPAA data portability requirements and the EU MDR clinical evidence standards constrain how device manufacturers structure reimbursement submissions across jurisdictions. Stakeholders must monitor how national health technology assessment bodies recalibrate cost-effectiveness thresholds for AI-enabled diagnostic platforms.
Market Dynamics
CMS national coverage determinations for remote patient monitoring CPT codes are compressing market access timelines and forcing payers to rebuild prior authorization workflows around continuous data streams rather than episodic claims.
Growth Catalysts
- Breakthrough Device Pathway:FDA's expedited review for novel diagnostics accelerates parallel CMS coverage analysis, shrinking the gap between regulatory clearance and reimbursement eligibility for AI-enabled imaging platforms.
- Germany's DiGA Framework:The Federal Institute for Drugs and Medical Devices reimburses prescribed digital health applications through statutory health insurance, creating a template for software-based therapeutic coverage across European markets.
- Home Care Migration:Hospital-at-home programs in post-acute settings sustain premium reimbursement rates where remote physiologic monitoring reduces emergency department utilization and readmission penalties.
Market Restraints
- Health Technology Assessment Rigor:England's NICE and France's HAS demand incremental cost-effectiveness ratios below standard thresholds for novel implantable devices, forcing manufacturers to fund multi-year real-world evidence studies before coverage decisions.
- Code Density Saturation:Established CPT categories for diagnostic imaging equipment face compressed fee schedules as CMS implements annual conversion factor reductions under physician fee schedule regulations.
- Cross-Border Evidence Friction:EU MDR clinical investigation requirements diverge from FDA pivotal trial designs, compelling manufacturers to duplicate evidence generation for parallel reimbursement submissions.
Strategic Opportunities
- Brazil's ANVISA Reform:Streamlined registration pathways for software as medical device create first-mover advantage in Latin America's largest private insurance market where reimbursement frameworks remain underdeveloped.
- Japan's Sakigake Designation:PMDA's priority review for innovative devices triggers conditional early coverage under Chuikyo reimbursement listings, enabling premium pricing before full clinical data maturity.
- Value-Based Contracting Infrastructure:Payer data platforms that link device utilization to patient outcomes enable risk-sharing arrangements where reimbursement scales with demonstrated reduction in complication rates or hospital days.
Industry Challenges
- Specialized Health Economics Talent:Manufacturers face scarcity of professionals capable of structuring cost-effectiveness models that satisfy divergent HTA methodologies across US, EU, and Asia-Pacific jurisdictions.
- Legacy Claims System Integration:Payer IT infrastructure built on DRG-based inpatient classification requires expensive retrofitting to process continuous data streams from connected devices under emerging remote therapeutic monitoring codes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Devices Reimbursement Market |
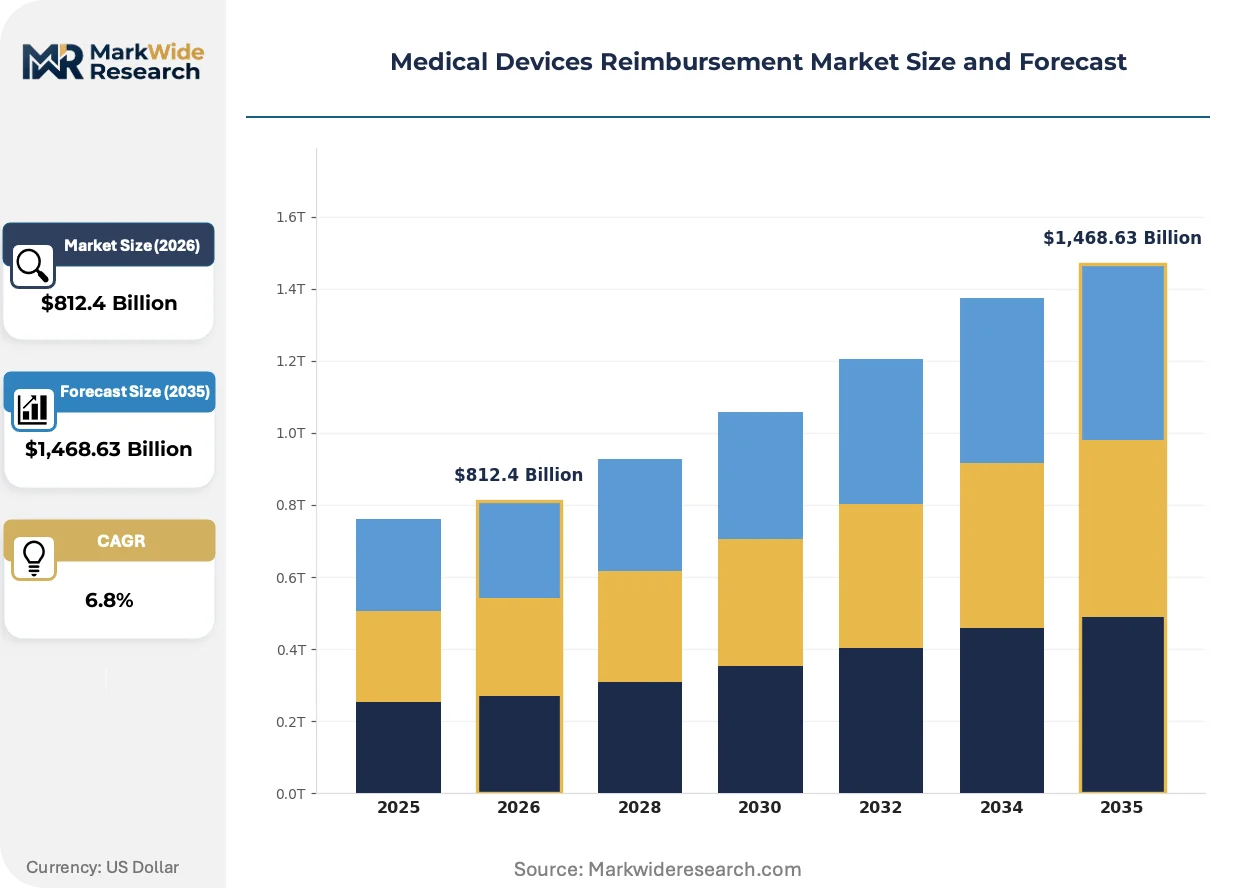
| Market Size in 2026 | $812.4 Billion |
| Market Size in 2035 | $1,468.63 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Instruments, Diagnostic Equipment, Monitoring Devices, Therapeutic Devices End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Payment Model: Fee-for-Service, Capitation, Value-Based Care, Bundled Payments Procedure Type: Invasive Surgery, Non-Invasive Procedure, Routine Check-Up, Emergency Care |
| Companies Covered | UnitedHealth Group, Allianz, Cigna, CVS Health, Humana Inc., Aetna, Anthem Insurance Companies, Inc., Aviva, BNP Paribas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Devices Reimbursement Market Strategic Shifts & Innovations
Reimbursement architecture is pivoting from procedure-based fee schedules toward episode accountability, with data infrastructure investments determining which stakeholders capture margin from outcome-linked payment models.
Artificial intelligence diagnostic algorithms are unifying imaging interpretation and clinical decision support into single reimbursement claims. Radiology groups in US hospital systems are deploying FDA-cleared AI for mammography and CT stroke detection at scale. This convergence is unifying previously separate technical and professional component billing into bundled payment structures that compress administrative overhead while elevating performance-based contracting.
EU MDR transitional provisions are forcing manufacturers to resubmit clinical evidence for legacy devices to maintain CE marking and associated reimbursement eligibility. German notified bodies face capacity constraints that delay certificate renewals. High-risk implantable device categories encounter the steepest recertification backlogs, pushing manufacturers toward early withdrawal of marginal product lines from European markets.
Hospital purchasing cooperatives are consolidating orthopedic and cardiovascular device procurement under single-source agreements that tie reimbursement rates to volume commitments and outcome guarantees. IDN-owned distribution channels displace independent distributors in US metropolitan markets. This concentration is most visible in Texas and Florida health systems where private equity-backed platform rollups command pricing leverage with commercial payers.
Medical Devices Reimbursement Market Segmentation
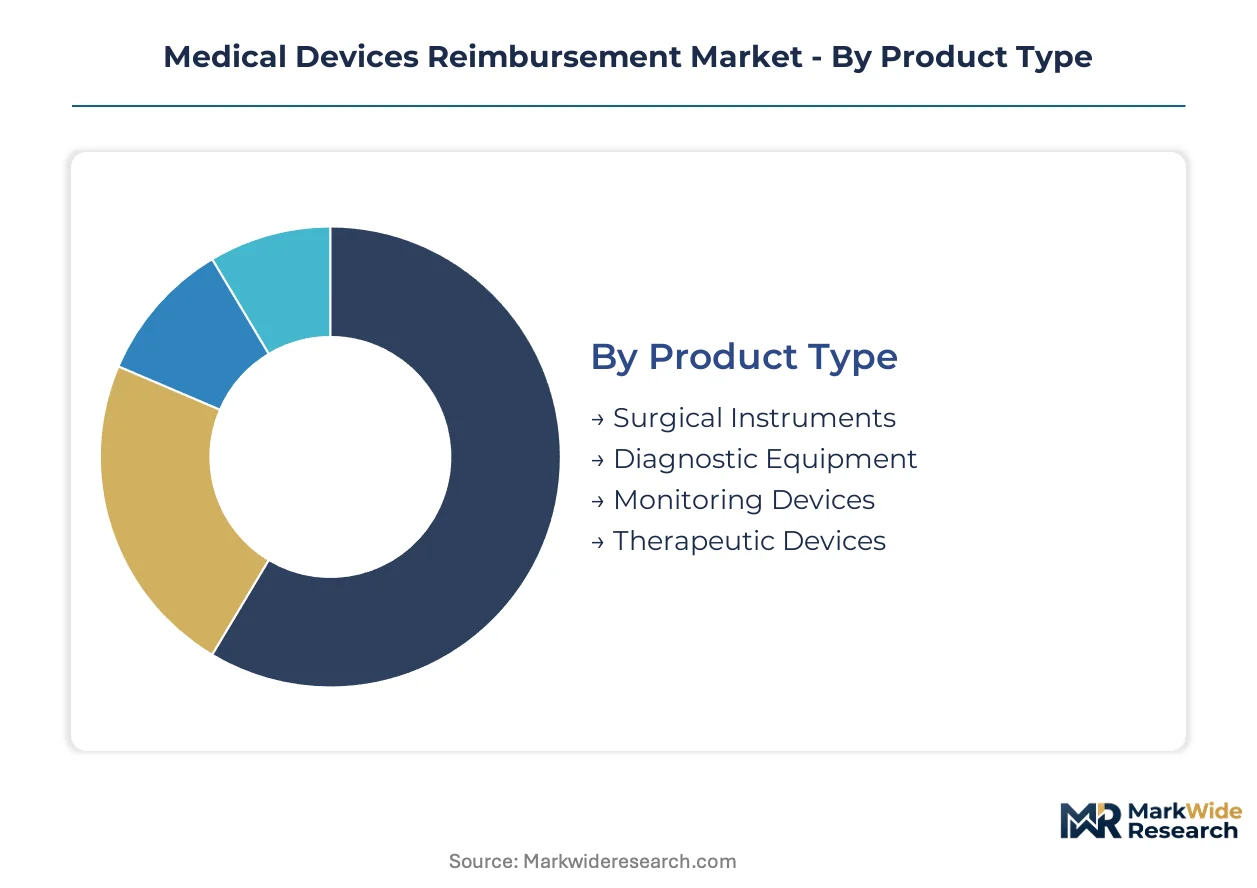
Reimbursement pathways diverge sharply across device categories, with capital intensity determining which segments attract payer investment and which face coverage compression. Payment model selection directly shapes manufacturer pricing power and provider adoption timelines.
Product Type:
Surgical instruments demand the heaviest upfront capital deployment, while diagnostic equipment spreads costs across high-volume utilization.
- Surgical Instruments:Robotic platforms and advanced laparoscopic systems carry acquisition costs exceeding several million dollars per unit. German hospital networks prioritize these investments where HTA bodies recognize operative time reductions and complication rate improvements in prostate and cardiac procedures.
- Diagnostic Equipment:MRI and CT modalities require substantial facility infrastructure but generate recurring revenue through high patient throughput. Japan's Chuikyo reimbursement listings maintain premium technical component rates for advanced imaging where PMDA clearance signals clinical utility.
- Monitoring Devices:Wearable cardiac and glucose sensors carry lower hardware costs but demand continuous data infrastructure investment from payers processing remote therapeutic monitoring codes.
- Therapeutic Devices:Implantable pumps and neurostimulation systems occupy mid-range capital requirements with long replacement cycles tied to battery longevity and device degradation.
Surgical instruments absorb the bulk of installed capacity; monitoring devices are expanding most quickly.
End User:
Site-of-care migration is redistributing reimbursement risk from acute facilities toward distributed settings with lower overhead structures.
- Hospitals:Inpatient DRG classifications still anchor the majority of high-value device reimbursement, though margin pressure intensifies as CMS compresses conversion factors for implantable categories.
- Home Care:Remote patient monitoring platforms sustain premium rates where continuous physiologic data reduces emergency department utilization. CMS national coverage determinations for CPT codes 99453-99458 are accelerating prior authorization workflow redesigns around data streams rather than episodic claims.
- Clinics:Ambulatory surgical centers capture shifting volumes for lower-acuity orthopedic and ophthalmic procedures under site-neutral payment policies.
- Rehabilitation Centers:Post-acute settings face bundled payment constraints that limit device utilization to standardized functional improvement protocols.
Hospitals retain the dominant share of high-value claims; home care is climbing the fastest as risk-bearing entities shift utilization downstream.
Payment Model:
Reimbursement architecture is pivoting from procedure-based fee schedules toward episode accountability, with data infrastructure investments determining margin capture.
- Value-Based Care:Risk-sharing arrangements tie device reimbursement to demonstrated outcome improvements, requiring manufacturers to fund real-world evidence generation that satisfies divergent HTA methodologies across jurisdictions.
- Fee-for-Service:Established CPT code density supports predictable revenue streams for diagnostic imaging, though annual conversion factor reductions compress margins under physician fee schedule regulations.
- Bundled Payments:Single-price episodes for orthopedic and cardiac procedures concentrate pricing leverage with hospital purchasing cooperatives that negotiate volume-outcome guarantees.
- Capitation:Per-member-per-month structures incentivize device selection based on total cost of care rather than unit price, favoring preventive monitoring over acute intervention.
Fee-for-service still processes the majority of claims volume; value-based care is gaining share fastest as payer data platforms mature.
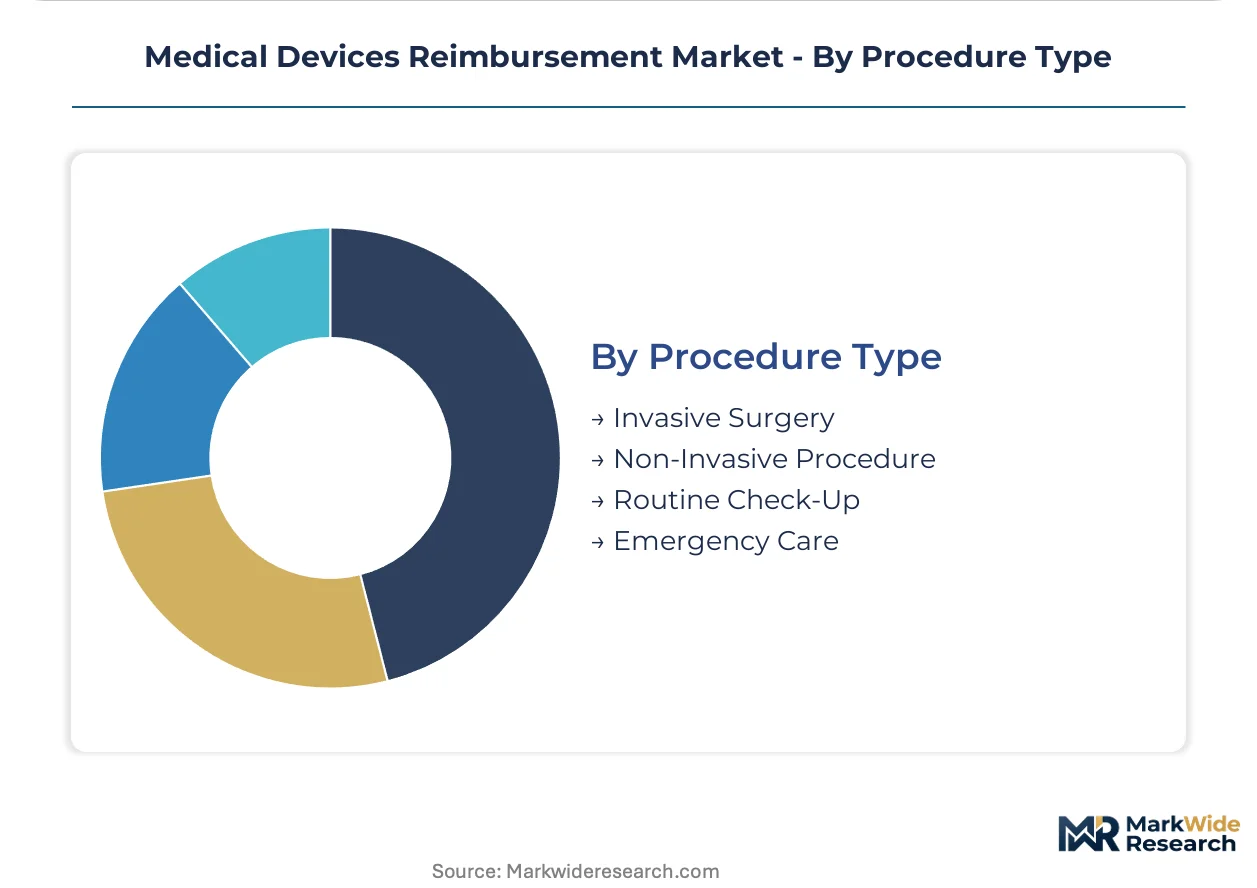
Procedure Type:
Reimbursement intensity correlates with procedural invasiveness, though remote monitoring is disrupting traditional acuity-based payment hierarchies.
- Invasive Surgery:Open and laparoscopic procedures command the highest facility and professional component rates, with robotic assistance attracting incremental technical fees where FDA breakthrough designation accelerates parallel CMS coverage analysis.
- Emergency Care:Trauma and acute intervention codes bypass prior authorization requirements, ensuring rapid device deployment regardless of payer pre-approval workflows.
- Non-Invasive Procedure:External beam radiation and focused ultrasound occupy mid-tier reimbursement with compressed margins as treatment planning software commodifies technical differentiation.
- Routine Check-Up:Preventive screening encounters face strict frequency limits and co-payment requirements that constrain device utilization to established clinical guidelines.
Invasive surgery generates the highest per-episode reimbursement; emergency care maintains the most reliable access pathway regardless of prior authorization evolution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's statutory health insurance funds anchor European reimbursement policy development, while CMS rulemaking in the United States drives remote monitoring code expansion. Japan's Chuikyo system and Brazil's ANVISA reforms complete the quartet of jurisdictions reshaping device coverage criteria.
United States
UnitedHealth Group and CVS Health deploy data infrastructure to anchor value-based contracting for high-cost implantable devices. CMS national coverage determinations for remote patient monitoring CPT codes 99453-99458 compress prior authorization workflows around continuous data streams. The Texas Medical Center cluster in Houston concentrates hospital purchasing cooperative activity where private equity-backed platform rollups negotiate volume-outcome guarantees with commercial payers.
Germany
Federal Institute for Drugs and Medical Devices reimbursement of prescribed digital health applications through statutory health insurance creates template coverage for software-based therapeutics. The DiGA framework accelerates parallel regulatory and reimbursement pathways for AI-enabled diagnostic platforms. Berlin-based hospital networks prioritize robotic surgical system investments where HTA bodies recognize operative time reductions in prostate and cardiac procedures.
Japan
PMDA's Sakigake priority review designation for innovative devices triggers conditional early coverage under Chuikyo reimbursement listings. Premium technical component rates for advanced imaging persist where clearance signals clinical utility. The Kansai region around Osaka concentrates medical device distribution channels serving hospital systems negotiating bundled payment models for orthopedic procedures.
Brazil
ANVISA streamlined registration pathways for software as medical device create first-mover positioning in Latin America's largest private insurance market. Reimbursement frameworks remain underdeveloped, favoring early entrants with established HTA submission capabilities. São Paulo's hospital networks drive demand for connected cardiac monitors as commercial payers recalibrate coverage frameworks for outpatient care delivery.
Medical Devices Reimbursement Market Key Industry Players
Global majors compete with regional champions across data infrastructure and provider network scale. The market structure tiers between integrated health systems with captive payer arms and specialized reimbursement consultancies serving mid-tier manufacturers. Three archetypes dominate: vertically integrated payers with pharmacy benefit management capabilities, European multi-line insurers with health technology assessment expertise, and regional specialists in emerging market regulatory navigation. Competitive moves center on payer-provider data platform consolidation and value-based contracting infrastructure deployment.
Among integrated health system payers, UnitedHealth Group, CVS Health, and Cigna occupy positions exemplifying the data-driven contracting archetype. UnitedHealth Group leverages its Optum infrastructure to anchor risk-sharing arrangements. CVS Health represents the pharmacy-benefit-integrated model. Cigna exemplifies bundled payment specialization across national provider footprints. European insurers Allianz and Aviva sit within the HTA-specialized tier serving hospital networks across Germany and broader European markets.
| Leading Market Players |
|---|
| UnitedHealth Group |
| Allianz |
| Cigna |
| CVS Health |
| Humana Inc. |
| Aetna |
| Anthem Insurance Companies, Inc. |
| Aviva |
| BNP Paribas |
| Others |
Cost & Logistics Intelligence
Breakthrough device designation versus standard clearance creates a stark reimbursement velocity gap that manifests in both pricing power and supply chain configuration. Manufacturers holding FDA breakthrough status command premium technical component rates while standard-clearance devices face compressed fee schedules under annual CMS conversion factor reductions.
Pricing Analysis
Warranty and real-world evidence service bundling now separates premium-tier implantable contracts from unbundled commodity procurement. Three-tier pricing structure across premium, standard, and economy levels reflects FDA breakthrough status, HTA submission depth, and outcome guarantee scope. Cost compression in diagnostic imaging runs through annual physician fee schedule reductions. Ambulatory surgical centers exhibit highest price sensitivity; integrated delivery networks with captive payer arms demonstrate lowest sensitivity due to risk-sharing cushion.
Supply Chain Analysis
Health economics talent shortages in Massachusetts, Basel, and Singapore constrain manufacturers' ability to structure parallel HTA submissions across jurisdictions. Supply chains draw from Germany for precision surgical instrumentation, Ireland for diagnostic imaging subassemblies, and Malaysia for disposable monitoring components. Single-source vulnerability concentrates in EU MDR notified body capacity for high-risk implantable recertification. Distribution runs through hospital purchasing cooperatives in Texas and Florida that displace independent distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Remote therapeutic monitoring codes are displacing legacy DRG-based inpatient reimbursement, forcing stakeholders to rebuild around continuous data infrastructure rather than episodic claims processing.
For Market Incumbents: To counter CMS national coverage determination compression timelines, UnitedHealth Group and CVS Health must deepen Optum-level data platform investments and secure exclusive GPO contracts with hospital purchasing cooperatives in Houston and Dallas. Captive real-world evidence generation capabilities anchor risk-sharing arrangements that protect margin from conversion factor erosion. For New Entrants and Emerging Players: Launch via software-as-medical-device pathways under Brazil's ANVISA reform before reimbursement frameworks mature, targeting São Paulo private insurance networks with connected cardiac monitoring solutions. White-space concentration sits in Japan's Sakigake conditional coverage window where premium pricing precedes full clinical data maturity. For Investors and Strategic Acquirers: Re-rating potential sits with health economics consultancies possessing multi-jurisdictional HTA submission capabilities given EU MDR transitional backlog demand. Long-term viability frames around five-to-ten year real-world evidence infrastructure buildout. Signal to monitor: CMS remote therapeutic monitoring code expansion velocity as inflection indicator for platform valuation.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Expedited review shrinks regulatory-to-reimbursement gap for AI-enabled diagnostics. |
| CE Marking Pathway | EU MDR recertification backlog forces portfolio rationalization toward high-margin categories. |
| Hospital System Partnership | Texas Medical Center cooperatives negotiate volume-outcome guarantees with commercial payers. |
| Software Companion Development | DiGA framework in Germany creates template for prescribed digital therapeutic coverage. |
| Reimbursement Strategy | Parallel CMS and Chuikyo submissions capture premium technical component rates in Japan. |
Research Approach
Multi-period observation of CMS national coverage determination timelines, FDA breakthrough designations, and HTA body precedent decisions anchored the trend analysis, supplemented by interviews with hospital purchasing committee chairs, GPO contracts managers, biomedical engineers, and payer access specialists. Secondary validation drew from FDA 510(k) and PMA filings, CMS Medicare claims data, hospital procurement databases, and EU MDR notified body capacity reports. Bottom-up segment sizing triangulated against top-down payer expenditure estimates.
Segment-weighting applied product type, end user site-of-care, payment model architecture, and procedure invasiveness as core dimensions across the analysis window. CAGRs derived from fitted growth curves calibrated to historical reimbursement code expansion patterns and regulatory pathway velocity. Forecast inputs incorporated remote patient monitoring CPT code density projections and health technology assessment body queue lengths.
Regulatory pathway delays, HTA body capacity constraints, and payer IT infrastructure retrofitting pace are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions regarding CMS rulemaking continuity and EU MDR transitional provision adherence. Material deviation in remote therapeutic monitoring code adoption velocity or notified body certification throughput warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Nasal Irrigation Market
Medical Devices
Radiofrequency Skin Rejuvenation Devices Market
Medical Devices
Ovulation Microscope Market
Medical Devices
UK Surgical Devices Market
Medical Devices
Canada Respiratory Devices Market
Medical Devices
Sputum Ejection Machine Market
Medical Devices
Skincare Devices Market
Medical Devices
Global Surgical Tourniquets Market
Medical Devices
Smart Syringe Pumps Market
Medical Devices
Global Extremities Market
Medical Devices
Global Intravenous Infusion Pump Market
Medical Devices
US Nurse Call Systems Market
Medical Devices
Urolithiasis Management Devices Market
Medical Devices
Lumbar Disc Replacement Device Market
Medical Devices
Computer-Aided Oral and Maxillofacial Surgery Market
Medical Devices
Middle East and Africa Hip and Knee Reconstruction Devices Market