
 Electrocardiograph (ECG) Market | 2026-2036
Electrocardiograph (ECG) Market Size, Share, and Industry Trends Forecast 2026-2036
Electrocardiograph (ECG) Market Intelligence
The EU Medical Device Regulation (MDR) is recalibrating design and clinical evidence requirements for ECG manufacturers seeking CE marking access. Nihon Kohden Corporation leverages its heritage in precision instrumentation to sustain leadership in hospital-grade diagnostic systems. Koninklijke Philips N.V. anchors its position through integrated informatics platforms that connect bedside monitors to enterprise cardiovascular workflows.
An electrocardiograph measures electrical activity of the heart through surface electrodes, typically capturing 12-lead configurations at sampling rates exceeding 500 Hz to detect arrhythmias, ischemia, and conduction abnormalities. Portable and wireless product types now command attention as healthcare delivery decentralizes from acute settings toward ambulatory and home environments. Cloud-based technology segments attract investment because subscription revenue models and continuous data streams create stickier customer relationships than capital equipment sales.
The FDA regulates ECG devices as Class II medical devices requiring 510(k) clearance, while the EU MDR demands updated technical documentation and post-market surveillance systems for continued market access. Japan's PMDA maintains distinct quality management expectations that shape product localization strategies for Asian markets. Stakeholders must monitor how interoperability mandates from the Office of the National Coordinator for Health IT affect purchasing criteria as health systems prioritize seamless data exchange across vendor platforms.
Market Dynamics
Hospital-at-home programs and Medicare reimbursement revisions in the United States are accelerating demand migration from acute care settings toward ambulatory and residential cardiac monitoring environments.
Growth Catalysts
- FDA 510(k) pathway streamlining:The FDA's evolving digital health guidance reduces clearance timelines for software-based ECG algorithms, enabling faster market entry for AI-augmented diagnostic tools.
- Home care infrastructure:Aging demographics across Germany, Japan, and the United States are expanding reimbursement eligibility for remote patient monitoring devices prescribed outside hospital walls.
- Cloud-native architectures:Subscription revenue models for continuous ECG data streaming are displacing capital equipment sales cycles, improving vendor cash flow predictability and customer retention.
Market Restraints
- Electrode material cost volatility:Silver-silver chloride electrode prices fluctuate with precious metal markets, compressing margins on disposable consumables used in Holter monitors.
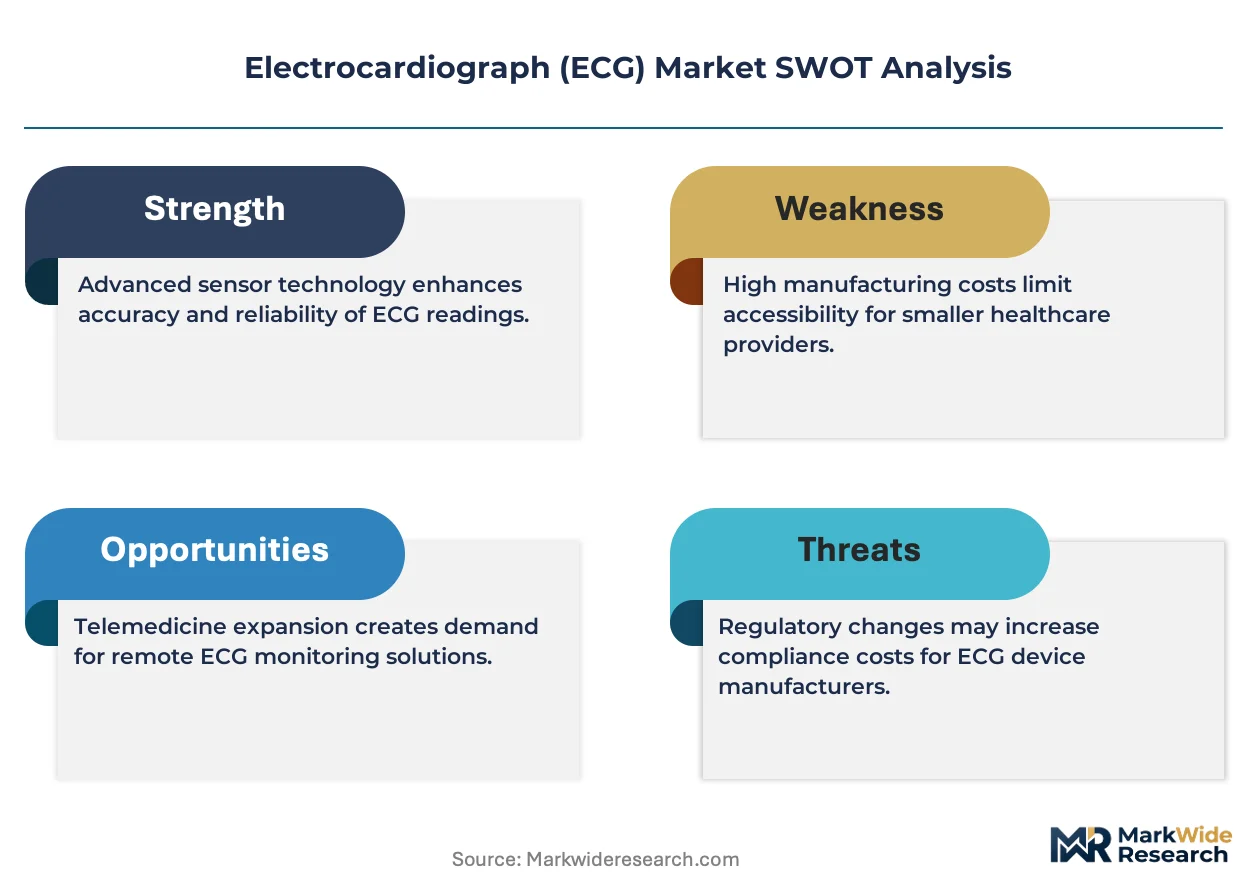
- EU MDR compliance burden:Updated technical documentation and post-market surveillance requirements for CE marking extend product launch timelines and elevate regulatory overhead for European market access.
- Signal fidelity limitations:Motion artifact and dry electrode impedance challenges in wearable form factors constrain diagnostic equivalence to traditional wet-electrode 12-lead systems.
Strategic Opportunities
- Underpenetrated rural India:Telemedicine corridors and government health digitization initiatives create first-mover advantage for low-cost, smartphone-integrated ECG devices in primary care networks.
- Sports cardiology applications:Elite athletic programs and occupational health screening for high-exertion professions represent untapped demand for ambulatory arrhythmia detection during physical stress.
- Interoperability mandates:The Office of the National Coordinator for Health IT certification requirements favor ECG platforms with native HL7 FHIR connectivity, rewarding vendors with pre-built integration capabilities.
Industry Challenges
- Biomedical engineering talent scarcity:Specialized expertise in analog signal processing and cardiac electrophysiology remains concentrated among legacy device manufacturers, constraining startup R&D velocity.
- Legacy EMR integration complexity:Health system procurement committees prioritize ECG platforms with proven Cerner and Epic interoperability, raising competitive barriers for emerging vendors lacking established interface libraries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrocardiograph (ECG) Market |
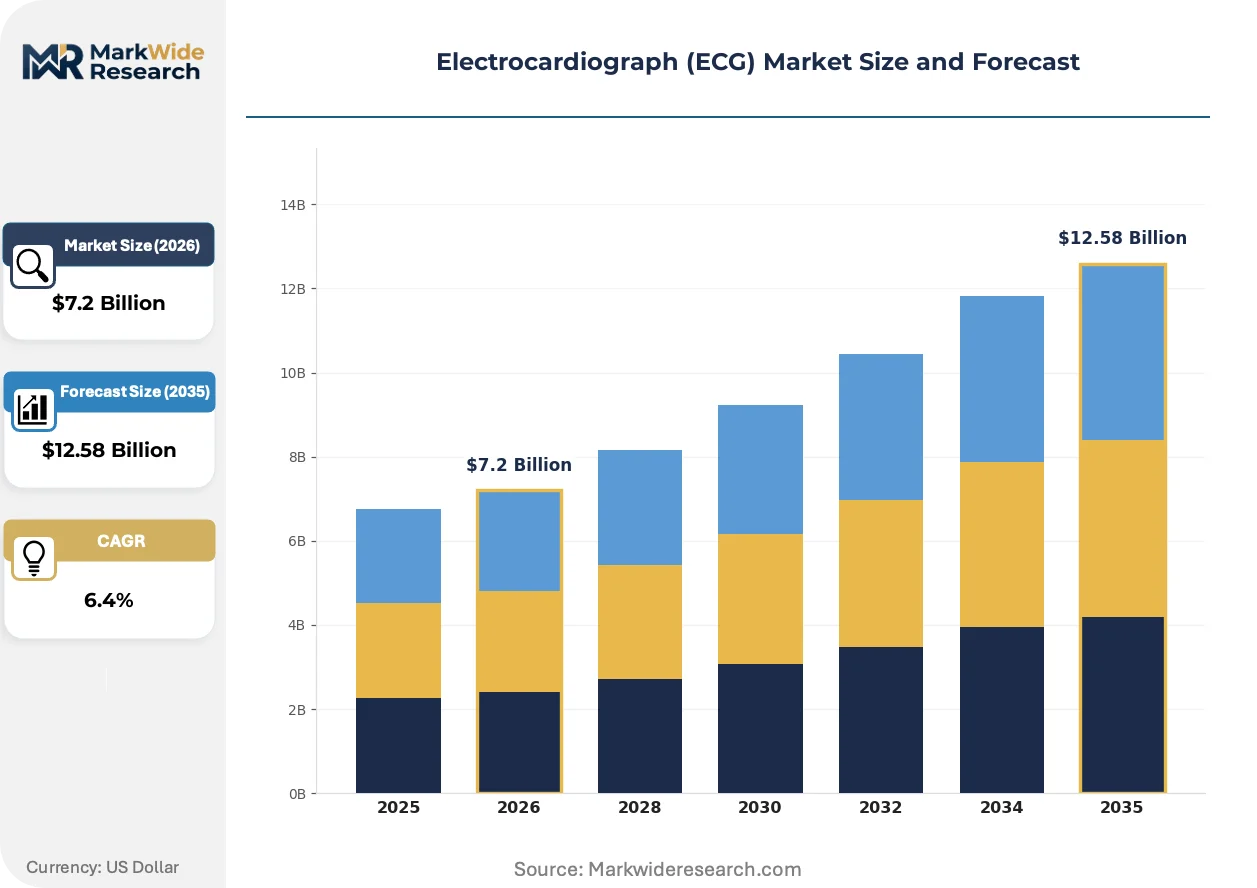
| Market Size in 2026 | $7.2 Billion |
| Market Size in 2035 | $12.58 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Wireless, Standalone, Holter Monitor End User: Hospitals, Clinics, Home Care, Diagnostic Centers Technology: Digital, Analog, Software-Based, Cloud-Based Application: Cardiology, Telemedicine, Emergency Care, Preventive Medicine |
| Companies Covered | Nihon Kohden Corporation, EDAN Instruments, Inc., GE Healthcare, Mortara Instrument, Spacelabs Healthcare, Koninklijke Philips N.V., Schiller AG, BPL Medical Technologies, Shenzhen Mindray Bio-Medical Electronics Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrocardiograph (ECG) Market Strategic Shifts & Innovations
Artificial intelligence inference at the edge is transforming how cardiac rhythm abnormalities are detected, classified, and escalated without continuous cloud connectivity.
Deep learning algorithms trained on million-scale ECG databases are converging with low-power microcontroller architectures to enable real-time arrhythmia classification directly on wearable devices. Cardiology practices in the United States and Germany are piloting these systems for post-discharge monitoring of atrial fibrillation patients. This convergence is compressing response times for critical events while reducing dependency on continuous cellular connectivity.
The EU Medical Device Regulation's clinical evidence requirements for software-as-a-medical-device are elevating validation standards for AI-enabled ECG classifiers seeking CE marking. Manufacturers must now demonstrate diagnostic performance across demographically diverse patient cohorts prior to market authorization. High-risk arrhythmia detection algorithms face the most stringent scrutiny, with notified bodies demanding prospective clinical studies rather than retrospective database validations.
Cardiovascular service line administrators are unbundling after-sales technical support from equipment procurement contracts, creating standalone subscription offerings for remote calibration and software maintenance. This shift pressures traditional vendors with embedded service margins while opening entry points for third-party technical service specialists. The transformation is most visible in United States health systems pursuing operating expense reduction through vendor consolidation and shared services models.
Electrocardiograph (ECG) Market Segmentation
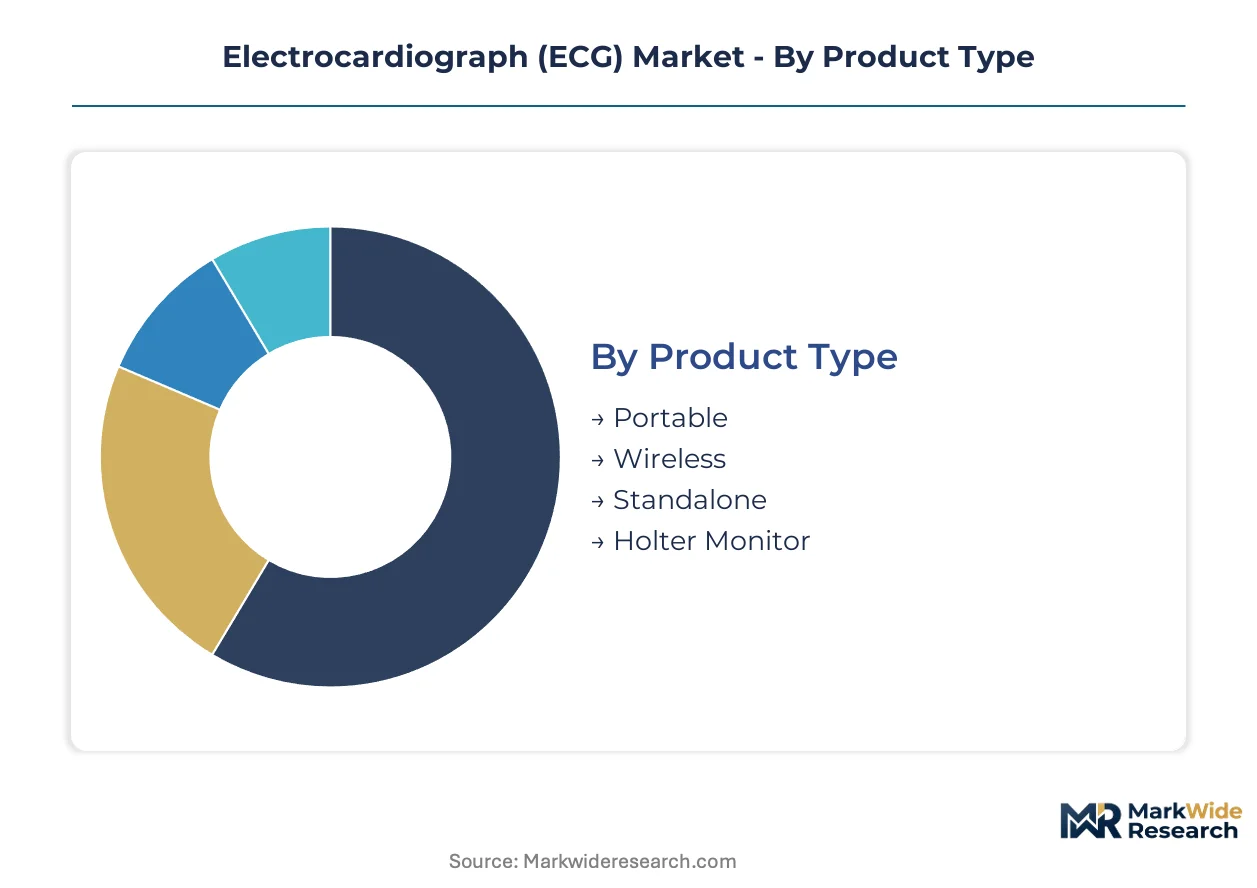
ECG market segmentation reveals divergent capital requirements and margin profiles across hardware, software, and service layers. Product architecture choices determine regulatory pathway complexity, while end-user settings dictate reimbursement eligibility and purchasing authority.
Product Type:
Capital intensity varies sharply across form factors, with hospital-grade standalone systems demanding the highest upfront manufacturing investment in precision analog front-ends and medical-grade enclosures.
- Portable:Battery-powered units with integrated displays and thermal printers serve ambulance services and rural clinics where mains power is unreliable. Demand concentrates in India's primary health centers and United States emergency medical services, driven by government procurement programs for pre-hospital cardiac assessment.
- Wireless:Bluetooth and WiFi-enabled devices stream data to smartphones or central monitoring stations without tethering patients to bedside equipment. Cardiology wards in Germany and Japan are replacing legacy hardwired systems to improve patient mobility and reduce fall risks.
- Standalone:Fixed-installation diagnostic systems with 12-lead acquisition and integrated interpretation algorithms remain the revenue anchor for hospital catheterization laboratories and cardiac stress testing suites.
- Holter Monitor:Ambulatory recorders with 24-48 hour memory capacity capture intermittent arrhythmias outside clinical settings; disposable electrode consumables generate recurring revenue streams.
Most installed capacity flows through Standalone systems. Expansion is steepest in Wireless.
End User:
Customer purchasing power and procurement sophistication separate institutional buyers from individual consumers, with hospital procurement committees wielding volume leverage absent in direct-to-patient channels.
- Hospitals:Integrated delivery networks negotiate enterprise contracts covering hundreds of bedside monitors, telemetry systems, and centralized review workstations. United States health systems prioritize FDA 510(k) clearance and Epic EMR interoperability in vendor selection.
- Clinics:Smaller patient volumes and constrained capital budgets favor portable devices with flexible financing or lease arrangements. Outpatient cardiology practices in Germany balance diagnostic capability against MDR compliance documentation costs.
- Home Care:Patients with chronic heart failure or post-ablation monitoring needs receive prescribed devices for remote rhythm surveillance. Medicare reimbursement expansion for remote patient monitoring is accelerating United States adoption among Medicare Advantage plans.
- Diagnostic Centers:High-throughput facilities performing executive health screenings and insurance-mandated cardiac evaluations prioritize rapid acquisition speed and automated measurement accuracy.
Procurement concentration sits with Hospitals. Home Care is climbing the fastest.
Technology:
Development cost structures separate mature hardware platforms from software-intensive architectures requiring continuous validation against evolving regulatory standards for algorithm-based diagnosis.
- Digital:Microcontroller-based signal acquisition with 16-bit or higher resolution ADCs has displaced analog tape recording in all new device designs, enabling software-configurable filter settings and noise reduction.
- Analog:Legacy galvanometer-based recorders persist only in extreme low-resource settings where electronic component supply chains are unreliable; replacement demand is negligible outside humanitarian aid contexts.
- Software-Based:AI-augmented interpretation algorithms running on general-purpose computing hardware require substantial clinical validation investment for FDA clearance and EU MDR conformity assessment.
- Cloud-Based:Subscription-hosted ECG databases with automated trend analysis and physician alert routing shift capital expenditure to operating expense, attracting United States accountable care organizations managing population health contracts.
Deployment volume runs through Digital architectures. Cloud-Based is gaining share fastest.
Application:
Clinical use case specificity determines performance requirements, with emergency settings demanding rapid diagnostic output and preventive applications tolerating longer analysis windows.
- Cardiology:Specialized departments require full 12-lead diagnostic fidelity, measurement precision meeting IEC 60601-2-25 standards, and integration with hemodynamic monitoring during electrophysiology procedures.
- Telemedicine:Asynchronous store-and-forward and real-time video-integrated ECG consultation platforms serve rural populations distant from cardiac specialists; India's national telemedicine guidelines specify minimum transmission quality standards.
- Emergency Care:Pre-hospital and emergency department triage protocols mandate rapid ST-elevation detection to activate catheterization laboratory teams within guideline-mandated door-to-balloon timeframes.
- Preventive Medicine:Corporate wellness programs and aging population screening initiatives in Japan employ simplified single-lead devices for atrial fibrillation case finding in asymptomatic cohorts.
Clinical workflow integration centers on Cardiology. Preventive Medicine shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Willem Einthoven invented the string galvanometer in Leiden, Netherlands in 1903, establishing the electrocardiograph's scientific foundation. German and Japanese manufacturers subsequently scaled precision instrumentation production through the twentieth century. Today's market distributes manufacturing and demand across concentrated national clusters shaped by reimbursement policy and regulatory pathway differentiation.
United States
Hospital-at-home initiatives and Medicare Advantage remote patient monitoring expansion drive ambulatory ECG procurement. FDA 510(k) clearance timelines for AI-augmented algorithms compress from 180 days toward 90 days under digital health guidance updates. The Minneapolis-St. Paul corridor hosts established cardiovascular device engineering talent pools serving integrated delivery network contracts.
Germany
Outpatient cardiology practices and diagnostic centers sustain replacement demand for 12-lead diagnostic systems. EU MDR notified bodies in Berlin and Munich impose extended clinical evidence requirements for software-as-a-medical-device classifications. The Baden-Württemberg industrial belt concentrates precision electronics manufacturing for medical-grade analog front-end components.
Japan
Aging demographics and government preventive screening programs expand Holter monitor prescriptions for asymptomatic atrial fibrillation detection. PMDA quality management system inspections enforce distinct localization protocols for Asian market entry. Tokyo and Osaka metropolitan areas concentrate cardiovascular specialist practices adopting cloud-native telemetry platforms.
India
Telemedicine corridor expansion and government health digitization initiatives create primary care network penetration opportunities for smartphone-integrated devices. CDSCO medical device rules harmonize with IMDRF guidelines for software-based diagnostics. Karnataka's Bangalore-Tumkur pharmaceutical and medical device cluster attracts contract manufacturing for export-oriented ECG hardware.
China
Domestic hospital procurement reform and tiered diagnosis-treatment systems elevate demand for portable units in county-level medical institutions. NMPA innovation pathway designations accelerate review for AI-enabled ECG classifiers meeting breakthrough criteria. The Shenzhen-Pearl River Delta electronics manufacturing ecosystem supplies microcontroller and wireless module components.
Electrocardiograph (ECG) Market Key Industry Players
Premium-margin players sit above commodity-margin players across regulatory sophistication and enterprise integration depth, with FDA-cleared algorithm portfolios commanding pricing multiples over hardware-only vendors. The vendor base stratifies into three tiers: legacy precision instrumentation houses, diversified health technology conglomerates, and emerging software-native entrants. Strategic archetypes include integrated informatics platform builders, disposable electrode consumable specialists, and AI algorithm licensing pure-plays. Dominant competitive moves encompass cloud-native architecture transitions and vertical service unbundling from equipment contracts.
Among diversified health technology conglomerates, Koninklijke Philips N.V. and GE Healthcare exemplify enterprise cardiovascular workflow integration archetypes, while Nihon Kohden Corporation occupies a position within precision instrumentation heritage specialists. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. represents scale-driven manufacturing competitiveness from China's medical device production base. These three anchors illustrate divergent strategic postures: informatics platform depth, analog signal processing legacy, and cost-optimized hardware scalability respectively.
| Leading Market Players |
|---|
| Nihon Kohden Corporation |
| EDAN Instruments, Inc. |
| GE Healthcare |
| Mortara Instrument |
| Spacelabs Healthcare |
| Koninklijke Philips N.V. |
| Schiller AG |
| BPL Medical Technologies |
| Shenzhen Mindray Bio-Medical Electronics Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Cloud-native telemetry architectures are compressing capital equipment cycles into subscription revenue streams while concentrating manufacturing leverage among microcontroller and wireless module suppliers in East Asian electronics hubs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared AI-augmented diagnostic platforms from MDR-compliant European systems and basic portable units for emerging markets. Price differentiation rests on certification tier and after-sales service bundling, with United States hospital procurement committees least sensitive to unit cost when Epic EMR interoperability is guaranteed. Cost compression in the economy tier is intensifying because smartphone-integrated devices from Indian and Chinese manufacturers bypass traditional distribution markups. Rural primary care networks in India exhibit the highest price sensitivity, while integrated delivery networks in the United States prioritize total cost of ownership over acquisition price.
Supply Chain Analysis
Biomedical engineering talent scarcity in precision analog front-end design concentrates manufacturing competency in Germany's Baden-Württemberg industrial belt, Japan's Tokyo-Osaka corridor, and China's Shenzhen-Pearl River Delta electronics ecosystem. Component sourcing draws from silver-silver chloride electrode suppliers tethered to precious metal spot markets, medical-grade microcontroller fabricators in Taiwan, and Bluetooth/WiFi module producers in South Korea. Single-source vulnerability in FDA-registered contract manufacturing organizations elevates risk for emerging vendors lacking dual-qualified production sites. Distribution runs through hospital procurement committees and group purchasing organizations in developed markets, with direct-to-patient channels expanding in Medicare Advantage remote monitoring programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ECG market offers geographic-arbitrage returns for vendors structuring operations between Germany's high-regulation, high-margin outpatient cardiology segment and India's low-cost, high-volume primary care penetration opportunity.
For Market Incumbents: Deepen backward integration into silver-silver chloride electrode production to buffer margin compression from precious metal volatility, while consolidating cloud-native telemetry platforms through acquisition of software-as-a-medical-device startups facing EU MDR clinical evidence cost barriers. FDA 510(k) clearance portfolios represent the priority defensive asset against AI-native entrants with faster algorithm iteration cycles. For New Entrants and Emerging Players: Smartphone-integrated single-lead devices offer the most penetrable wedge for India's telemedicine corridor expansion, where CDSCO harmonization with IMDRF guidelines reduces regulatory friction for software-based diagnostics. Target government procurement programs for pre-hospital cardiac assessment in United States emergency medical services and Indian primary health centers. A direct-to-patient subscription model bypasses hospital procurement committee gatekeeping. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap precision instrumentation specialists with legacy analog signal processing expertise but underdeveloped cloud-native platform strategies. Long-term viability over the coming decade hinges on successful transition from capital equipment to recurring revenue architectures. The signal to monitor is FDA digital health guidance expansion accelerating 510(k) timelines for AI-augmented algorithms, which would compress competitive moats for algorithm-only pure-plays.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Digital health guidance updates compress clearance timelines for AI-augmented arrhythmia classifiers seeking United States market entry. |
| EU MDR CE Marking Pathway Investment | Notified bodies in Berlin and Munich demand prospective clinical studies for high-risk software-as-a-medical-device classifications. |
| Hospital System Partnership Development | Integrated delivery networks prioritize Epic and Cerner interoperability in enterprise cardiovascular workflow procurement decisions. |
| Software Companion Development | Cloud-native telemetry platforms with HL7 FHIR connectivity satisfy ONC certification requirements for seamless data exchange. |
| Reimbursement Strategy Execution | Medicare remote patient monitoring expansion creates prescription eligibility for ambulatory Holter monitors in Medicare Advantage plans. |
Research Approach
Multiple input streams — structured interviews with biomedical engineers and hospital purchasing committees, GPO contract database analysis, and CMS Medicare reimbursement filings — were reconciled against secondary validation from FDA 510(k) clearance records, EU MDR notified body guidance documents, and CDSCO medical device registration data. Primary fieldwork engaged cardiology department heads, telemetry system integration specialists, and remote patient monitoring program administrators at United States health systems, German outpatient practices, and Indian primary care networks. Bottom-up demand modeling across portable, wireless, and Holter monitor form factors was cross-checked against top-down market sizing from capital equipment shipment tracking.
Historical revenue trajectories of precision instrumentation manufacturers were cross-referenced against panel input from cardiovascular service line administrators regarding procurement budget allocations across the projection horizon. Segmentation dimensions modeled include product architecture, end-user setting, technology layer, and clinical application, with particular attention to cloud-based versus hardware-centric revenue model transitions. CAGRs were derived from installed base replacement cycles, ambulatory care expansion rates, and software subscription adoption curves. Industry-specific forecast inputs incorporated FDA digital health guidance implementation pace and EU MDR notified body capacity constraints.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Medicare reimbursement policy shifts, silver price volatility affecting electrode consumable economics, and AI algorithm diagnostic performance validation standards. Forecasts reflect documented assumptions regarding hospital-at-home program expansion and interoperability mandate enforcement timelines. Material deviation in FDA clearance velocity or EU MDR clinical evidence requirements warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Bone Cement Market
Medical Devices
Internal Nasal Dilators Market
Medical Devices
Electronic Pill Market
Medical Devices
North America and Europe Group 2 Powered Mobility Devices Market
Medical Devices
Otorhinolaryngology Devices Market
Medical Devices
Japan Drug Delivery Devices Market
Medical Devices
Canada General Surgical Devices Market
Medical Devices
Germany Contraceptive Devices Market
Medical Devices
Bone Anchored Hearing Aids Market
Medical Devices
Global Digital Dose Inhaler Market
Medical Devices
Computer Assisted Surgical (CAS) Systems Market
Medical Devices
India Medical Devices Market
Medical Devices
Cough Assist Devices Market
Medical Devices
Global Cast Saw Devices Market
Medical Devices
Fluorescence-Guided Surgery Systems Market
Medical Devices
Radiotherapy Positioning Devices Market